
 Asia Pacific Sortation Systems Market | 2026-2036
Asia Pacific Sortation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Sortation Systems Market Outlook
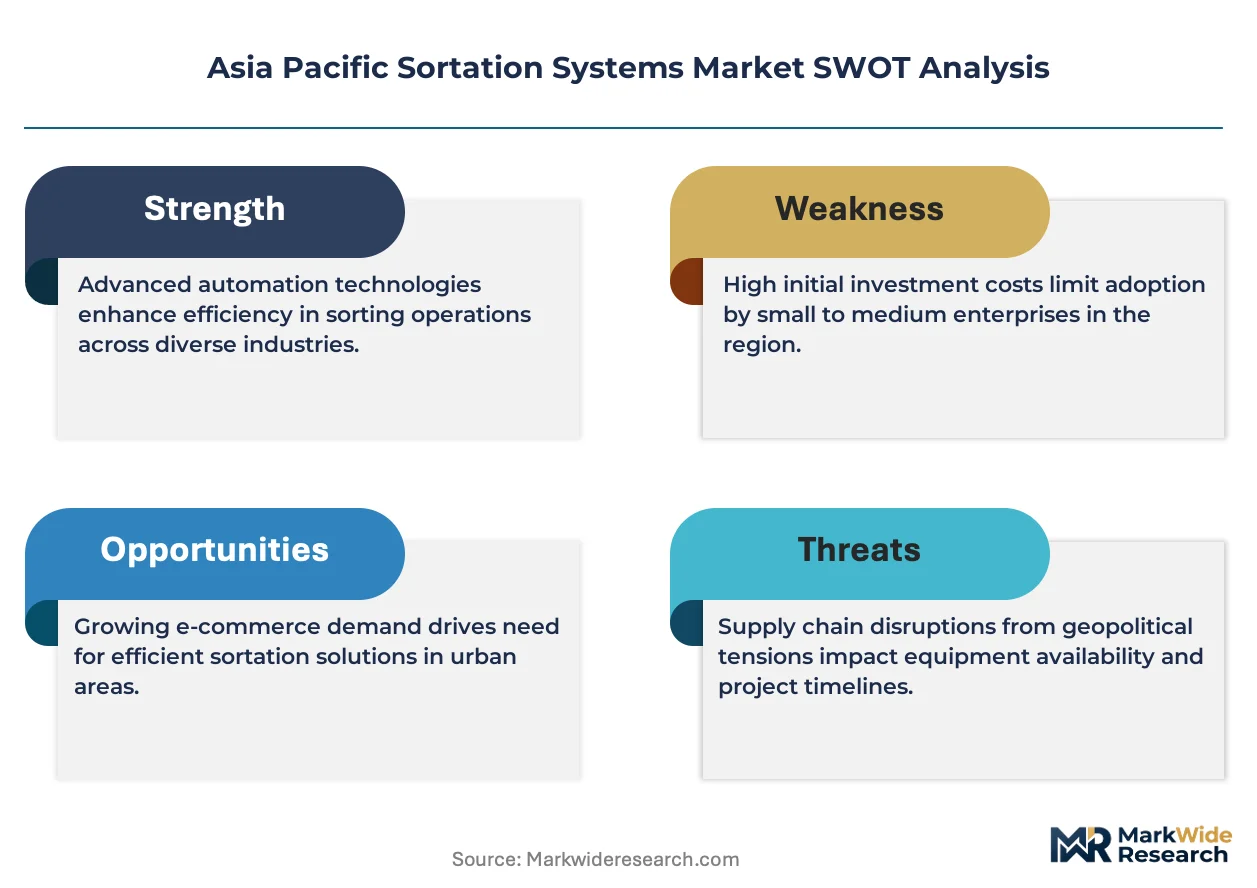
China's GB standards for warehouse automation and energy efficiency are expanding the cost-of-entry calculus for sortation system vendors across the Asia Pacific region. Daifuku Co. Ltd. anchors its regional position through deep manufacturing scale in intralogistics equipment. Vanderlande Industries B.V. competes on technology leadership in vision-guided parcel handling for high-throughput e-commerce hubs. Honeywell Intelligrated differentiates through integrated software layers that control modular sortation cells.
Asia Pacific sortation systems comprise mechanized conveyor networks, diverters, tilt-tray loops, and cross-belt sorters engineered to route parcels, cartons, and individual items to designated discharge points at throughput rates exceeding 15,000 items per hour. These systems integrate barcode scanners, RFID interrogators, and machine-vision arrays to identify, track, and direct material flows through fulfillment, distribution, and parcel-sorting operations. Automated product types dominate installed base value across the region, though hybrid configurations—blending fixed automation with mobile robotic induction—are capturing the fastest expansion in greenfield e-commerce facilities. Vision systems technology commands premium positioning where dimensional weight pricing and damage reduction justify higher capital outlays, while barcode remains the default for mid-tier logistics deployments.
China's SAMR enforces national standards on industrial equipment safety and electromagnetic compatibility that shape product certification requirements for sortation machinery sold domestically. Japan's METI promotes smart logistics infrastructure through subsidy frameworks that accelerate RFID and multi-sensor technology adoption in regional distribution networks. India's BIS mandates conformity assessment for imported electromechanical systems, creating procedural friction that favors local assembly partnerships or wholly owned manufacturing subsidiaries. Stakeholders must monitor how divergent national certification timelines affect deployment schedules and whether modular installation architectures can compress commissioning cycles across fragmented regulatory environments.
Market Dynamics
China's dual carbon goals are compressing deployment timelines for energy-efficient sortation architectures across Asia Pacific warehouse networks. E-commerce fulfillment centers now face mandatory efficiency audits that favor regenerative-drive conveyor systems and modular tilt-tray loops over legacy fixed automation.
Growth Catalysts
- Cross-border e-commerce corridors:Southeast Asian logistics hubs are retrofitting regional distribution centers with high-throughput parcel handling equipment to manage surging intra-ASEAN trade volumes.
- India's PLI scheme for logistics infrastructure:The Production Linked Incentive framework subsidizes automated material handling equipment purchases, accelerating third-party logistics provider capital expenditure cycles.
- RFID mandate penetration:Japan's METI subsidy frameworks for smart logistics infrastructure are driving multi-sensor technology adoption in pharmaceutical and electronics distribution networks.
Market Restraints
- Steel and aluminum input volatility:Conveyor frame and cross-belt module manufacturers face margin compression from fluctuating ferrous metal prices sourced primarily from Chinese mills.
- Certification timeline fragmentation:India's BIS conformity assessment for imported electromechanical systems creates procedural delays that extend commissioning cycles by four to eight months versus domestic assembly alternatives.
- Manual sortation labor arbitrage:Low-wage warehouse workforces in Vietnam, Indonesia, and Bangladesh continue to undercut automation ROI calculations for mid-volume facilities.
Strategic Opportunities
- Vietnam's northern industrial zones:Samsung and Apple supplier clusters are generating demand for precision sortation systems capable of handling fragile electronics components at sub-millimeter tolerances.
- Machine-vision and AI convergence:Integration of dimensional weight scanners with predictive maintenance algorithms creates premium positioning for vendors serving high-value pharmaceutical cold chains.
- Australia's TGA track-and-trace mandates:Pharmaceutical serialization requirements are forcing wholesale distributors to upgrade legacy conveyor networks with verified discharge tracking capabilities.
Industry Challenges
- Commissioning engineer scarcity:The specialized skill set required for vision-guided parcel handling calibration is concentrated among Japanese and German expatriate technicians, creating deployment bottlenecks.
- Legacy WMS integration friction:Brownfield facilities running decade-old warehouse management software require expensive middleware development to connect modular sortation cells with existing inventory databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Sortation Systems Market |
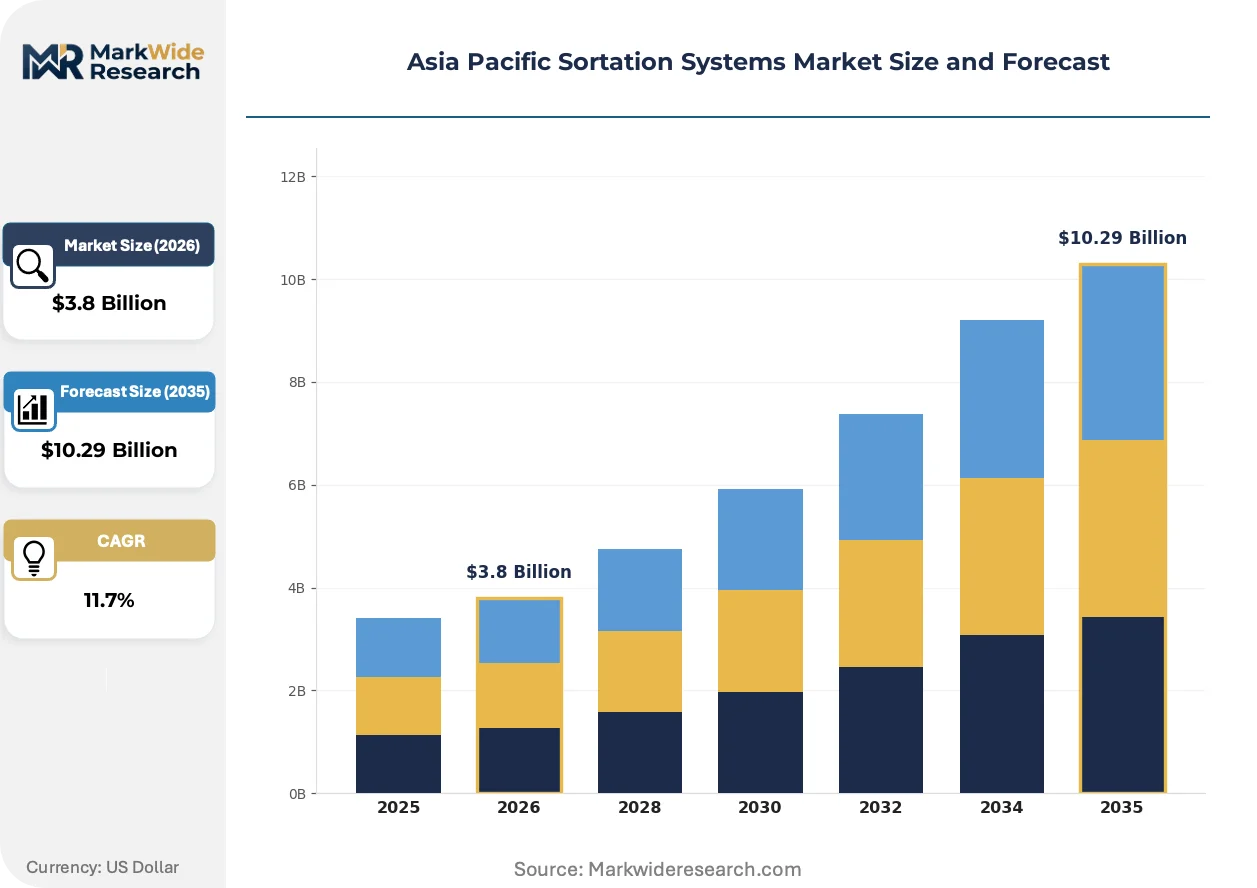
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated, Semi-Automated, Manual, Hybrid Technology: Barcode, RFID, Vision Systems, Multi-Sensor End User: E-Commerce, Retail, Food & Beverage, Logistics Installation: In-Line, Off-Line, Mobile, Modular |
| Companies Covered | Dematic Corp. (KION GROUP), Daifuku Co. Ltd., Vanderlande Industries B.V., Beumer Group GmbH, Honeywell Intelligrated, Interroll Holding AG, Bastian Solutions Inc., Murata Machinery Ltd., Fives Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Sortation Systems Market Strategic Shifts
Vision-guided parcel handling is consolidating technical leadership across Asia Pacific e-commerce fulfillment. Three interconnected developments are compressing competitive positioning and reshaping procurement priorities for automated material handling equipment.
Cross-belt sorter technology is consolidating market share in high-throughput hubs by replacing legacy tilt-tray loops for parcels under five kilograms. Chinese e-commerce operators are deploying these systems at throughput rates exceeding fifteen thousand items per hour. The technology is consolidating vendor margins by compressing mechanical complexity into standardized modular cells that reduce on-site commissioning labor.
China's GB standards for warehouse automation safety and electromagnetic compatibility are expanding certification requirements for sortation machinery sold domestically. The SAMR enforcement framework now mandates third-party testing for all imported electromechanical systems above specified voltage thresholds. Japanese and Korean manufacturers are responding by establishing wholly owned assembly subsidiaries in Jiangsu and Guangdong provinces to bypass import assessment timelines.
Third-party logistics providers are unbundling after-sales service contracts from initial equipment procurement, forcing sortation vendors to compete on lifecycle cost transparency rather than capital expenditure pricing alone. Australian and Singaporean buyers now demand predictive maintenance subscriptions with guaranteed uptime clauses. This shift is most visible in pharmaceutical distribution verticals where TGA serialization mandates require continuous operational verification.
Asia Pacific Sortation Systems Market Segmentation
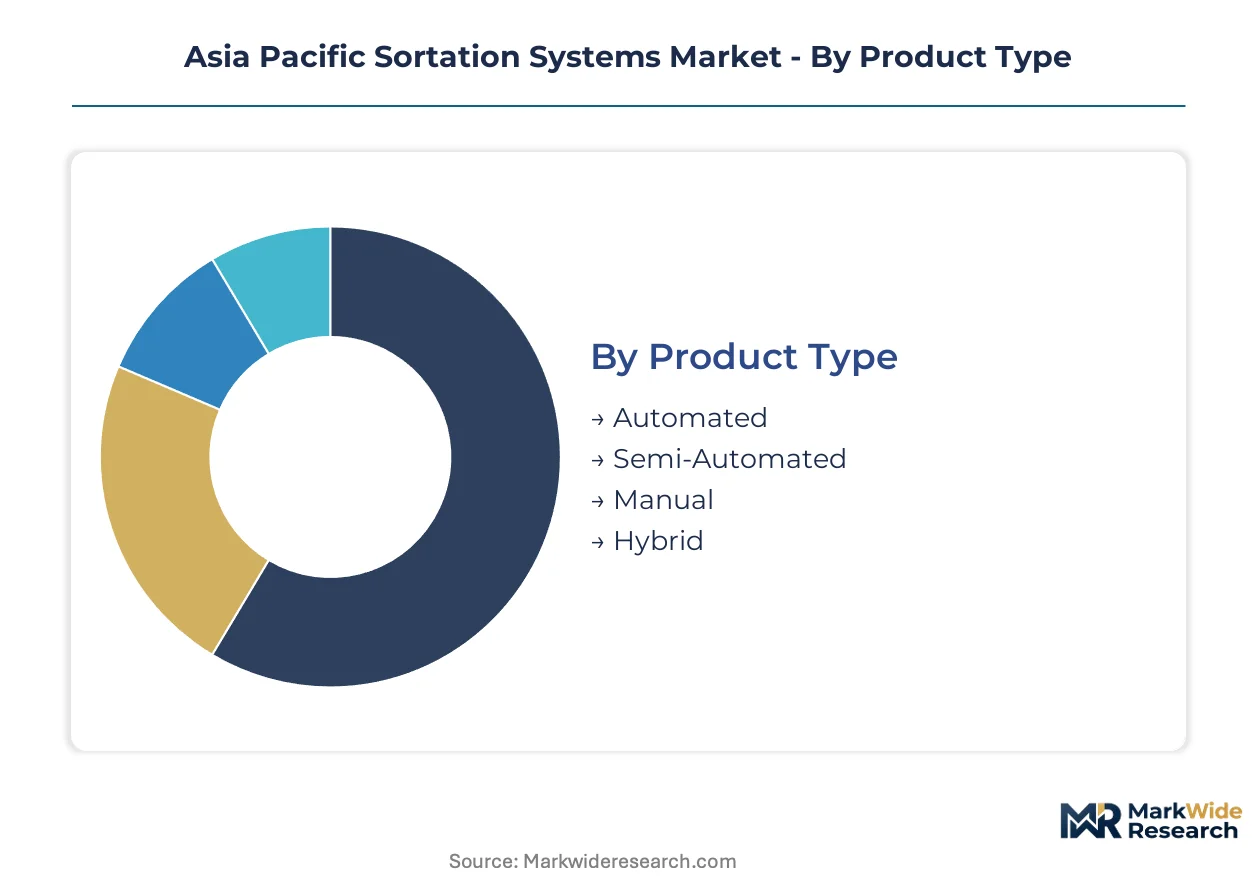
Sortation system procurement across Asia Pacific follows distinct technical and operational logics that shape vendor positioning. Product architecture, identification technology, and deployment configuration each create separate competitive arenas with divergent margin profiles and customer loyalty patterns.
Product Type:
Supply concentration tilts toward automated configurations as Chinese and Japanese manufacturers scale production of modular tilt-tray and cross-belt platforms.
- Automated:Fully mechanized conveyor networks with programmable logic controllers achieve throughput rates exceeding 15,000 items per hour in Chinese e-commerce mega-hubs. Demand concentrates in Alibaba and JD.com fulfillment centers where SAMR energy efficiency audits mandate regenerative-drive architectures.
- Semi-Automated:Hybrid configurations blending fixed automation with manual induction stations dominate India's third-party logistics retrofits. PLI scheme subsidies compress payback periods for mid-tier 3PL providers operating in Mumbai-Chennai logistics corridors.
- Manual:Gravity roller and basic belt conveyor systems persist in Bangladesh and Vietnam facilities where labor arbitrage undercuts automation ROI.
- Hybrid:Mobile robotic induction paired with fixed sortation loops captures greenfield Southeast Asian e-commerce deployments seeking operational flexibility.
Automated systems absorb the bulk of installed capacity; hybrid configurations are expanding most quickly.
Technology:
Cost tier differentiation separates premium vision-guided installations from commodity barcode deployments across regional fulfillment networks.
- Barcode:Laser scanner arrays remain the default identification method for mid-tier logistics operations throughout Indonesia and Thailand. Hardware costs below vision system equivalents by substantial margins sustain penetration in price-sensitive procurement environments.
- RFID:Ultra-high frequency tag interrogation systems penetrate Japan's pharmaceutical and electronics distribution networks under METI smart logistics subsidies. Cold chain operators in Singapore deploy RFID for serialized track-and-trace compliance.
- Vision Systems:Machine-vision arrays with dimensional weight capture command premium positioning in Australian pharmaceutical wholesale where TGA mandates require damage reduction verification.
- Multi-Sensor:Fused barcode-RFID-vision architectures serve high-value electronics handling in Vietnam's northern industrial zones where Samsung supplier clusters demand sub-millimeter placement tolerances.
Barcode technology retains the deepest installed base; vision systems are gaining share fastest among new capital commitments.
End User:
Application-specific throughput requirements and regulatory exposure create divergent vendor-customer relationships across vertical markets.
- E-Commerce:High-velocity parcel handling with sub-second induction-to-discharge cycles dominates capital allocation across Southeast Asian fulfillment networks. Cross-border corridor expansion between ASEAN member states accelerates tilt-tray loop deployment.
- Retail:Store replenishment and returns processing applications favor modular configurations adaptable to seasonal volume fluctuations in Australian and Japanese distribution networks.
- Food & Beverage:Temperature-controlled sortation with washdown-rated components serves chilled and frozen logistics operations in China's urban consumption hubs.
- Logistics:Third-party providers operating multi-tenant facilities prioritize reconfigurable architectures that accommodate diverse client SKU profiles across India's emerging logistics corridors.
E-commerce absorbs the bulk of installed capacity; logistics service providers are expanding most quickly.
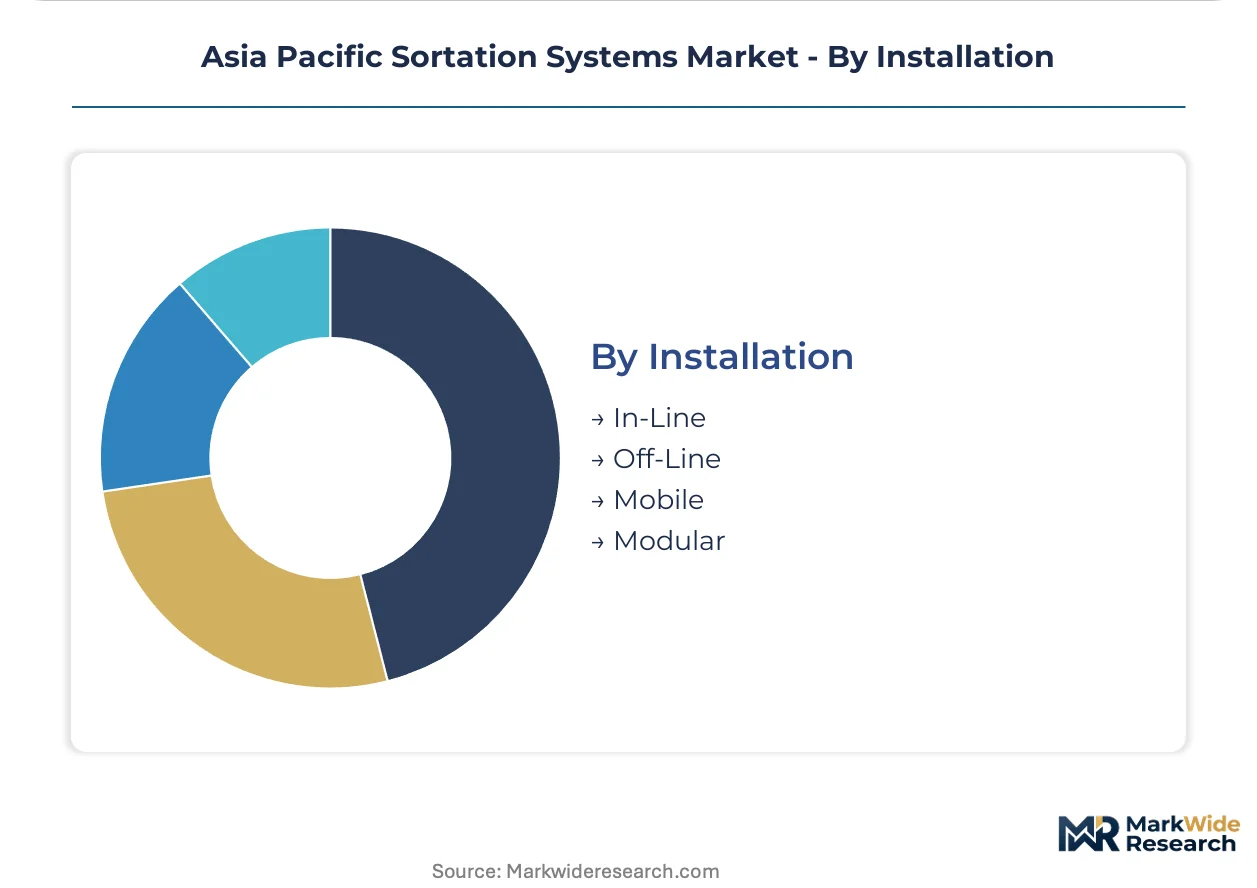
Installation:
Volume concentration in greenfield facilities favors modular architectures over fixed in-line systems that dominated prior generation warehouse design.
- In-Line:Continuous conveyor sequences integrated into building infrastructure serve high-throughput parcel hubs with predictable, sustained volume profiles in Chinese postal networks.
- Off-Line:Standalone sortation cells handling overflow or specialty flows supplement primary systems during peak e-commerce promotional periods across Southeast Asian markets.
- Mobile:Portable belt and roller configurations enable rapid deployment for temporary promotional distribution centers serving Australia's seasonal retail peaks.
- Modular:Pre-engineered cells with compressed commissioning timelines address India's BIS certification delays by enabling domestic assembly partnerships that bypass import assessment bottlenecks.
In-line systems retain the bulk of legacy infrastructure; modular installations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate automated material handling procurement, with Jiangsu and Zhejiang provincial governments offering tax rebates for energy-efficient logistics equipment.
China
Alibaba and JD.com fulfillment centers drive tilt-tray loop deployment across Jiangsu and Guangdong provinces. SAMR's GB standards mandate third-party electromagnetic compatibility testing for imported electromechanical systems above specified voltage thresholds. Zhejiang-based assembly subsidiaries bypass import assessment delays while serving domestic e-commerce mega-hubs.
India
Third-party logistics providers retrofit Mumbai-Chennai logistics corridors with semi-automated configurations under PLI scheme subsidies. BIS conformity assessment for imported systems extends commissioning cycles by four to eight months versus domestic assembly alternatives. Gujarat's emerging logistics parks attract regional distribution hub investments from multinational contract operators.
Japan
Pharmaceutical and electronics distribution networks adopt multi-sensor technology under METI smart logistics subsidy frameworks. Cold chain operators in Osaka and Tokyo deploy RFID interrogation systems for serialized track-and-trace compliance. Nagoya's automotive supplier clusters generate precision handling demand for fragile electronics components.
Vietnam
Samsung and Apple supplier clusters in northern industrial zones demand sub-millimeter placement tolerances for fragile electronics handling. Low-wage warehouse workforces in Ho Chi Minh City undercut automation ROI calculations for mid-volume facilities. Bac Ninh and Hai Phong provinces concentrate precision sortation procurement from Korean and Japanese capital equipment vendors.
Australia
TGA pharmaceutical serialization mandates force wholesale distributors to upgrade legacy conveyor networks with verified discharge tracking capabilities. Sydney and Melbourne distribution centers prioritize predictive maintenance subscriptions with guaranteed uptime clauses. Seasonal retail peaks drive temporary mobile belt deployments for promotional distribution centers.
Asia Pacific Sortation Systems Market Competitive Environment
Japanese producers anchor the premium-equipment tier; German and Dutch specialists hold technology leadership positions in vision-guided handling. The vendor base concentrates around three strategic archetypes: integrated intralogistics conglomerates with captive manufacturing scale, modular component specialists competing on commissioning speed, and software-centric integrators bundling control layers with mechanical hardware. Competitive moves center on establishing wholly owned assembly subsidiaries to bypass import certification delays, and unbundling after-sales service contracts from initial equipment procurement to compete on lifecycle cost transparency.
Within the integrated conglomerate tier, Daifuku Co. Ltd. and Vanderlande Industries B.V. exemplify divergent geographic anchoring strategies. Daifuku represents deep manufacturing scale in intralogistics equipment through its Japanese corporate structure. Vanderlande occupies a position as a Netherlands-based technology leader in high-throughput parcel handling systems. Honeywell Intelligrated sits within the software-integrated archetype, differentiating through control system layers that manage modular sortation cells. These three entities collectively illustrate how regional origin shapes competitive positioning across certification, manufacturing, and service unbundling dimensions.
| Leading Market Players |
|---|
| Dematic Corp. (KION GROUP) |
| Daifuku Co. Ltd. |
| Vanderlande Industries B.V. |
| Beumer Group GmbH |
| Honeywell Intelligrated |
| Interroll Holding AG |
| Bastian Solutions Inc. |
| Murata Machinery Ltd. |
| Fives Group |
| Others |
Value Chain & Pricing Dynamics
Commissioning engineer scarcity in Japan and Germany widens pricing spreads between premium vision-guided installations and commodity barcode systems. Labor-cost differentials between these specialized technician pools and lower-skill regional workforces create three distinct pricing tiers across Asia Pacific fulfillment networks.
Pricing Analysis
Short lead-time premiums command substantial markups as India's BIS certification delays extend commissioning cycles for imported systems. Project-based pricing stratifies across premium, standard, and economy tiers where vision-system configurations with guaranteed uptime clauses capture top-tier margins. Cost compression in mid-tier barcode installations intensifies as Chinese manufacturers scale modular cross-belt production. Third-party logistics providers in India exhibit highest price sensitivity due to PLI scheme subsidy dependency, while Australian pharmaceutical distributors prioritize lifecycle cost transparency over capital expenditure minimization.
Supply Chain Analysis
Workforce availability constraints in Jiangsu and Guangdong provinces limit assembly capacity for Japanese and Korean manufacturers establishing wholly owned subsidiaries. Steel and aluminum inputs draw primarily from Chinese mills, creating ferrous metal price volatility exposure for conveyor frame producers. Single-source vulnerability concentrates in precision sensor components sourced from Japanese optical equipment suppliers. Distribution runs through regional equipment integrators who bundle installation services with hardware procurement across Southeast Asian e-commerce corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around vendors with captive manufacturing scale as certification timeline fragmentation forces smaller players toward exit or acquisition. SAMR's expanding GB standards enforcement accelerates this pressure by raising fixed-cost barriers.
For Market Incumbents: To counter emerging modular specialists compressing commissioning timelines, Daifuku and Vanderlande should deepen backward integration into precision sensor manufacturing. Establishing captive Jiangsu assembly capacity bypasses India's BIS import assessment bottlenecks while securing electromagnetic compatibility certification speed.
For New Entrants and Emerging Players: Enter via Vietnam's northern industrial zones where Samsung and Apple supplier clusters generate unmet demand for sub-millimeter tolerance handling. Target semi-autated hybrid configurations in India's PLI-subsidized logistics corridors through domestic assembly partnerships that compress BIS compliance cycles.
For Investors and Strategic Acquirers: Re-rating potential sits with software-centric integrators bundling predictive maintenance subscriptions given Australia's TGA serialization mandate expansion. Long-term viability favors vendors with demonstrated lifecycle cost transparency rather than capital-expenditure price competition. Monitor METI subsidy framework renewal as inflection signal for Japanese pharmaceutical distribution automation demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Assembly Subsidiary Establishment | Bypasses India's BIS certification delays while serving regional 3PL retrofit demand. |
| Predictive Maintenance Subscription Launch | Captures Australian pharmaceutical distributors seeking TGA-mandated uptime guarantees. |
| Vision-Guided Handling Technology Licensing | Accelerates penetration in Vietnam's precision electronics supplier clusters. |
| Regenerative-Drive Architecture Development | Aligns with China's SAMR energy efficiency audits for e-commerce mega-hubs. |
| Multi-Sensor Fusion Platform Integration | Serves Japan's METI-subsidized pharmaceutical cold chain track-and-trace requirements. |
Study Parameters
Multi-period observation of PLI scheme disbursement patterns, BIS certification timelines, and METI subsidy uptake anchored the trend analysis, supplemented by interviews with warehouse operations directors, OEM procurement managers, aftermarket service heads, and system integration specialists. Secondary validation drew from SAMR regulatory filings, customs trade data for steel and aluminum inputs, Jiangsu provincial tax rebate disclosures, and TGA pharmaceutical serialization mandate documentation. Bottom-up installation data triangulated against top-down logistics infrastructure investment flows.
Segment-weighting applied product type, technology tier, end-use vertical, and installation configuration dimensions across the modeling period. CAGRs derived from regression analysis against e-commerce parcel volume trajectories and logistics automation capital expenditure cycles. Industry-specific inputs incorporated RFID mandate penetration rates and dual carbon goal compliance timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt BIS procedural changes or ferrous metal price spikes. Forecasts reflect documented assumptions regarding subsidy framework continuity and certification timeline stability. Material deviation in SAMR enforcement intensity or PLI scheme renewal warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Smart Warehouse System Market
Industrial Automation
Brazil Factory Automation and Industrial Controls Market
Industrial Automation
Electric Linear Actuator Market
Industrial Automation
Cold Storage AGV Market
Industrial Automation
Global Assembly Line Solutions Market
Industrial Automation
Europe Water Automation and Instrumentation Market
Industrial Automation
Europe SCADA Market
Industrial Automation
Asia-Pacific Industrial Automation Market
Industrial Automation
Internet of Things Enabled Industrial Wearables Market
Industrial Automation
Industrial Automation Software Market
Industrial Automation
Magnetic Grippers Market
Industrial Automation
Europe Automation Components Market
Industrial Automation
Connected Worker Market
Industrial Automation
Linear Actuator Market
Industrial Automation
Machine Automation Controllers Market
Industrial Automation
Industrial Automation Spares Market