
 Europe SCADA Market | 2026-2036
Europe SCADA Market Size, Share, and Industry Trends Forecast 2026-2036
Europe SCADA Market Intelligence
German industrial automation suppliers is repositioning their SCADA portfolios toward edge-native architectures. Siemens AG leverages its embedded software heritage to dominate process control deployments across chemical plants. ABB Group anchors its European presence through specialized substation automation integration. Schneider Electric SE differentiates via interoperable platform ecosystems that bridge IT and OT environments.
SCADA denotes supervisory control and data acquisition systems that aggregate real-time sensor data, execute remote command logic, and visualize operational states through human-machine interfaces using protocols such as DNP3 and IEC 61850. These systems orchestrate geographically dispersed infrastructure including power grids, pipelines, and water treatment facilities. Software and services segments capture expanding margin pools as utilities shift from perpetual licenses toward subscription-based remote monitoring. Cloud-based deployment is displacing legacy on-premises installations where latency constraints permit, though hybrid architectures retain dominance in critical national infrastructure.
The EU Green Deal, CE marking under the MDR framework for safety-critical components, and the F-Gas Regulation collectively mandate higher telemetry density and refrigerant leak detection across European industrial assets. ECHA's REACH compliance requirements further shape material selections for field instrumentation and communication hardware. Stakeholders must monitor evolving NIS2 cybersecurity directives that will impose mandatory incident reporting and supply-chain risk management on SCADA operators.
Market Dynamics
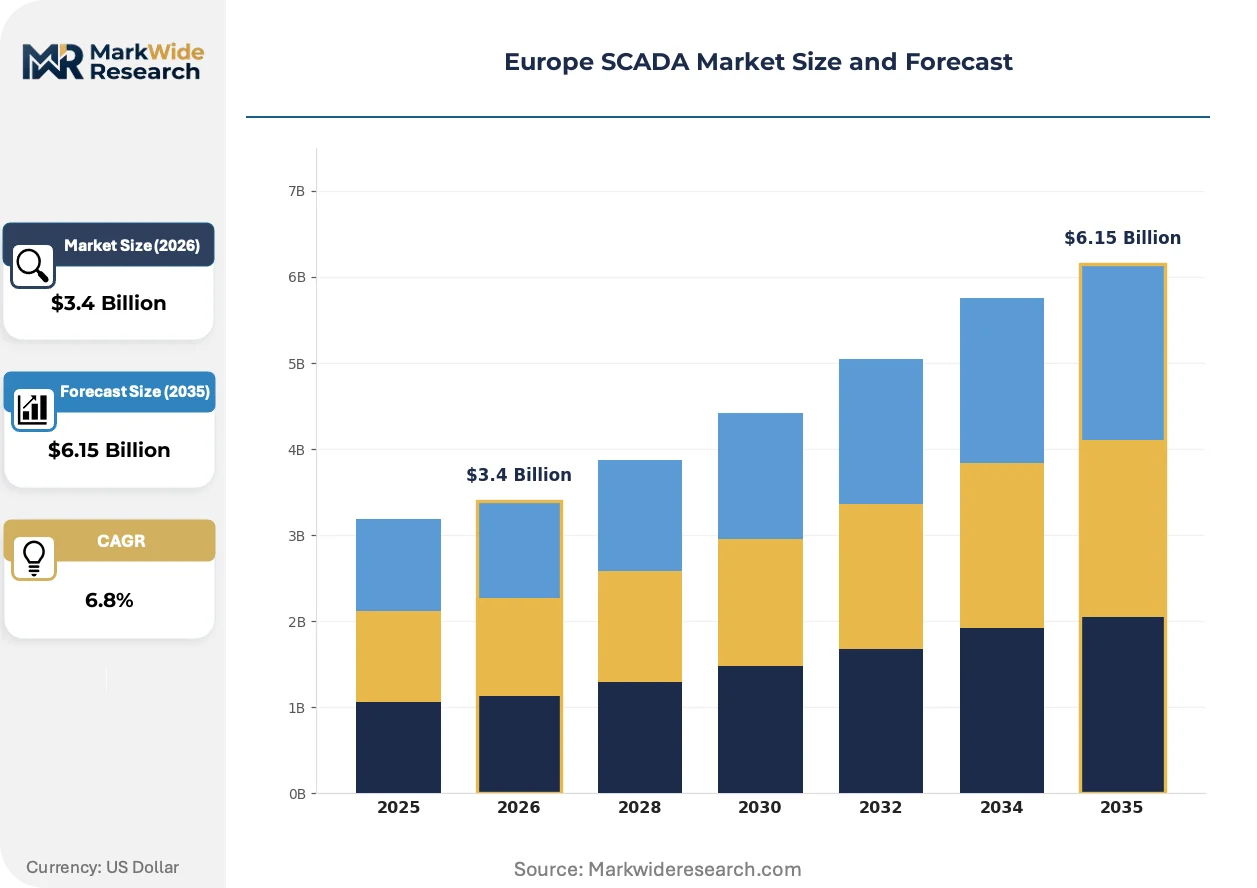
The EU Green Deal and F-Gas Regulation are forcing utilities to replace legacy control systems with telemetry-dense architectures, compressing replacement cycles from fifteen years to under seven.
Growth Catalysts
- EU Green Deal:Mandates for carbon-neutral industrial operations accelerate SCADA deployments across German chemical clusters and French power utilities.
- Edge computing architectures:Real-time processing at substation level reduces latency for grid stabilization applications in Nordic renewable integration projects.
- Italy:Industrial automation investments in Lombardy and Veneto manufacturing corridors drive demand for interoperable platform ecosystems.
Market Restraints
- Semiconductor supply concentration:Dependence on East Asian foundries for industrial-grade processors creates twelve-month lead time volatility for European system integrators.
- Cybersecurity compliance costs:NIS2 directive implementation requires mandatory incident reporting infrastructure that burdens mid-sized water treatment operators.
- Technical debt in legacy protocols:Persistent DNP3 and Modbus installations resist seamless migration to IEC 61850, fragmenting upgrade roadmaps.
Strategic Opportunities
- Poland:Underpenetrated district heating networks present greenfield SCADA deployment potential as EU cohesion funds modernize municipal infrastructure.
- Refrigerant leak detection:F-Gas Regulation phase-down mandates create specialized application demand across cold chain logistics in Spain and Portugal.
- Cloud-native subscription models:Remote monitoring services displace perpetual licenses in non-critical commercial building automation across Benelux markets.
Industry Challenges
- OT cybersecurity expertise scarcity:European utilities face recruitment gaps for IEC 62443-certified engineers capable of securing converged IT-OT environments.
- Legacy system integration complexity:Brownfield deployments require protocol gateways that introduce latency and expand attack surfaces for critical national infrastructure operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe SCADA Market |
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $6.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Services, Integrated Solutions Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing End User: Utilities, Manufacturing, Transportation, Oil & Gas Application: Monitoring, Control, Data Acquisition, Asset Management |
| Companies Covered | Rockwell Automation, Inc., Honeywell International, Inc., Siemens AG, Yokogawa Electric Corporation, General Electric Company, Schneider Electric SE, Emerson Electric Co., Omron Corporation, ABB Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe SCADA Market Strategic Shifts & Innovations
SCADA architectures are pivoting from centralized control rooms toward distributed edge intelligence, driven by renewable intermittency and cybersecurity mandates.
Digital twin technology is automating predictive maintenance workflows across transmission and distribution networks. German grid operators deploy virtual substation replicas to simulate fault scenarios before physical intervention. This capability is automating outage response coordination, compressing restoration timelines from hours to minutes.
The F-Gas Regulation and its refrigerant phase-down schedules are mandating continuous emissions monitoring across industrial refrigeration assets. Chemical plants in the Netherlands and Belgium retrofit ammonia detection loops with higher sensor density. Process control vendors respond with pre-certified hardware bundles that accelerate compliance timelines.
Subscription-based remote monitoring is displacing perpetual license procurement in commercial and light industrial segments. Facility managers in France and Italy now purchase SCADA-as-a-service through energy performance contractors rather than capitalizing software directly. This shift concentrates vendor relationships with integrated service providers and fragments direct OEM contact.
Europe SCADA Market Segmentation
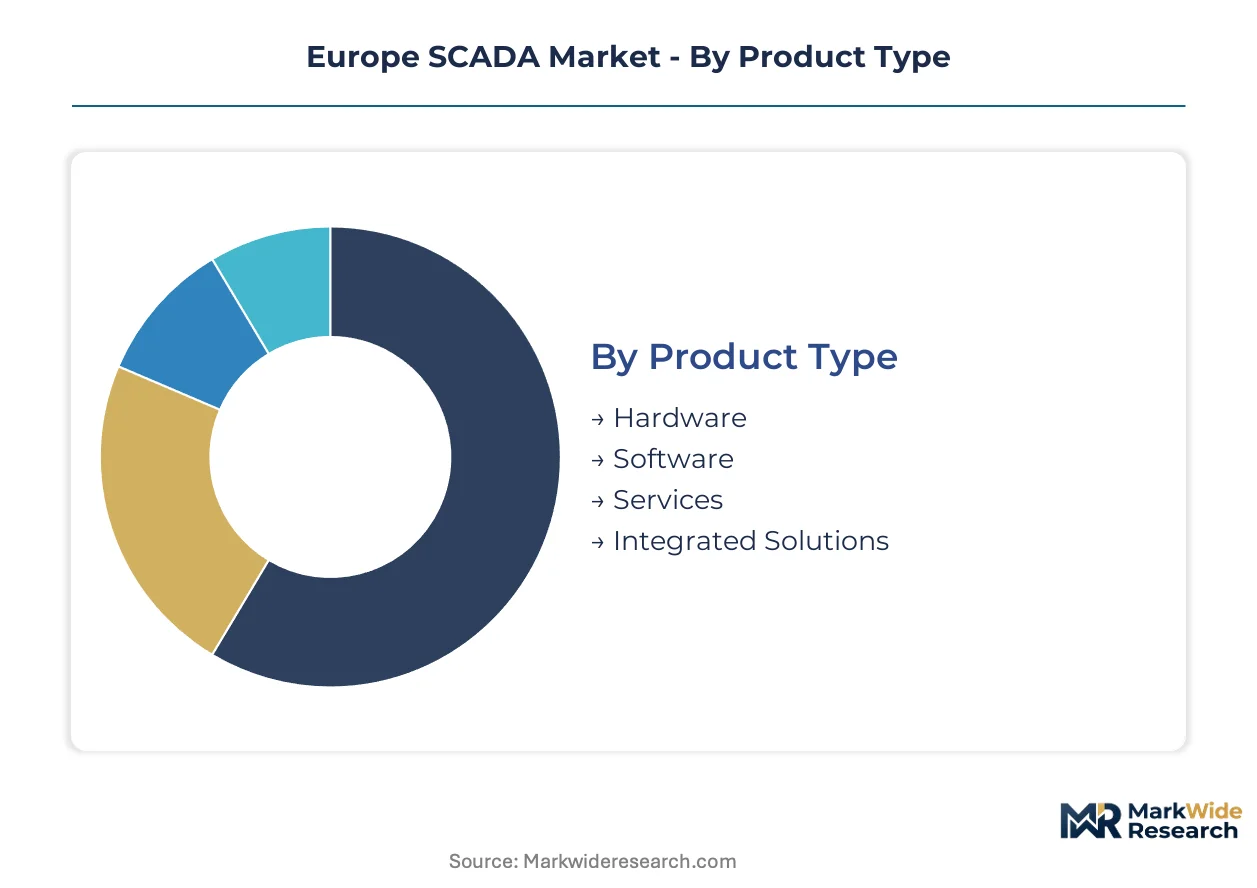
SCADA market segmentation reveals how replacement cycles, cybersecurity mandates, and cloud migration reshape procurement patterns across European industrial infrastructure. Understanding these dimensions exposes where margin pools concentrate and which deployment architectures capture upgrade budgets.
Product Type:
Legacy replacement cycles compress from fifteen years to under seven as EU Green Deal and NIS2 directives force control system modernization across critical infrastructure operators.
- Hardware:Field instrumentation, RTUs, PLCs, and communication gateways form the physical telemetry layer. German chemical clusters and French TSOs drive demand for IEC 61850-compliant substation controllers as they retire DNP3-era equipment.
- Software:HMI platforms, historian databases, and alarm management systems execute visualization and control logic. Nordic renewable integrators prioritize edge-native licenses that reduce dependency on centralized control rooms for grid stabilization.
- Services:System integration, cybersecurity hardening, and lifecycle support contracts capture expanding share as mid-sized water utilities outsource IEC 62443 compliance to specialized vendors.
- Integrated Solutions:Pre-engineered bundles combining hardware, software, and managed services accelerate deployment timelines for F-Gas Regulation compliance projects in Benelux cold chain logistics.
Hardware sits at the top of the volume ranking, with Software climbing the fastest as subscription models displace perpetual licenses.
Deployment:
Latency tolerance and criticality classification determine architecture selection, with hybrid configurations dominating where national security designations restrict pure cloud adoption.
- On-Premises:Air-gapped installations persist in nuclear and defense-adjacent facilities where NIS2 mandates physical segmentation. Italian and Spanish CNI operators retain capital-intensive control rooms despite higher TCO.
- Cloud-Based:SaaS SCADA platforms enable remote monitoring for commercial building automation and light industrial applications. French energy performance contractors deploy multi-tenant dashboards across distributed retail portfolios.
- Hybrid:Local edge processing with cloud analytics aggregation balances latency and scalability. German DSOs favor this architecture for renewable intermittency management while maintaining OT isolation.
- Edge Computing:Substation-level intelligence processes PMU data for real-time grid stabilization. Polish and Romanian grid modernization projects embed compute nodes directly within switchgear to reduce backhaul dependency.
Hybrid deployments command the largest installed base, with Edge Computing gaining share fastest among new TSO tenders.
End User:
Regulatory exposure and asset criticality create divergent procurement patterns, with cybersecurity-burdened sectors prioritizing managed service relationships over direct OEM engagement.
- Utilities:Power, water, and gas distribution operators face mandatory NIS2 incident reporting and supply-chain risk management. German and French utilities consolidate vendor relationships to reduce audit complexity.
- Manufacturing:Discrete and process industries deploy SCADA for OEE optimization and predictive maintenance. Lombardy and Veneto automotive suppliers drive demand for IT-OT bridge platforms.
- Transportation:Rail electrification and tunnel ventilation systems require SIL-rated control architectures. Alpine corridor projects in Switzerland and Austria specify redundant telemetry for avalanche-prone sections.
- Oil & Gas:Pipeline compression stations and LNG terminals retrofit leak detection loops for F-Gas Regulation compliance. North Sea operators phase out refrigerant-dependent cooling systems.
Utilities represent the deepest vertical, with Manufacturing expanding most quickly as Industry 4.0 investments accelerate.
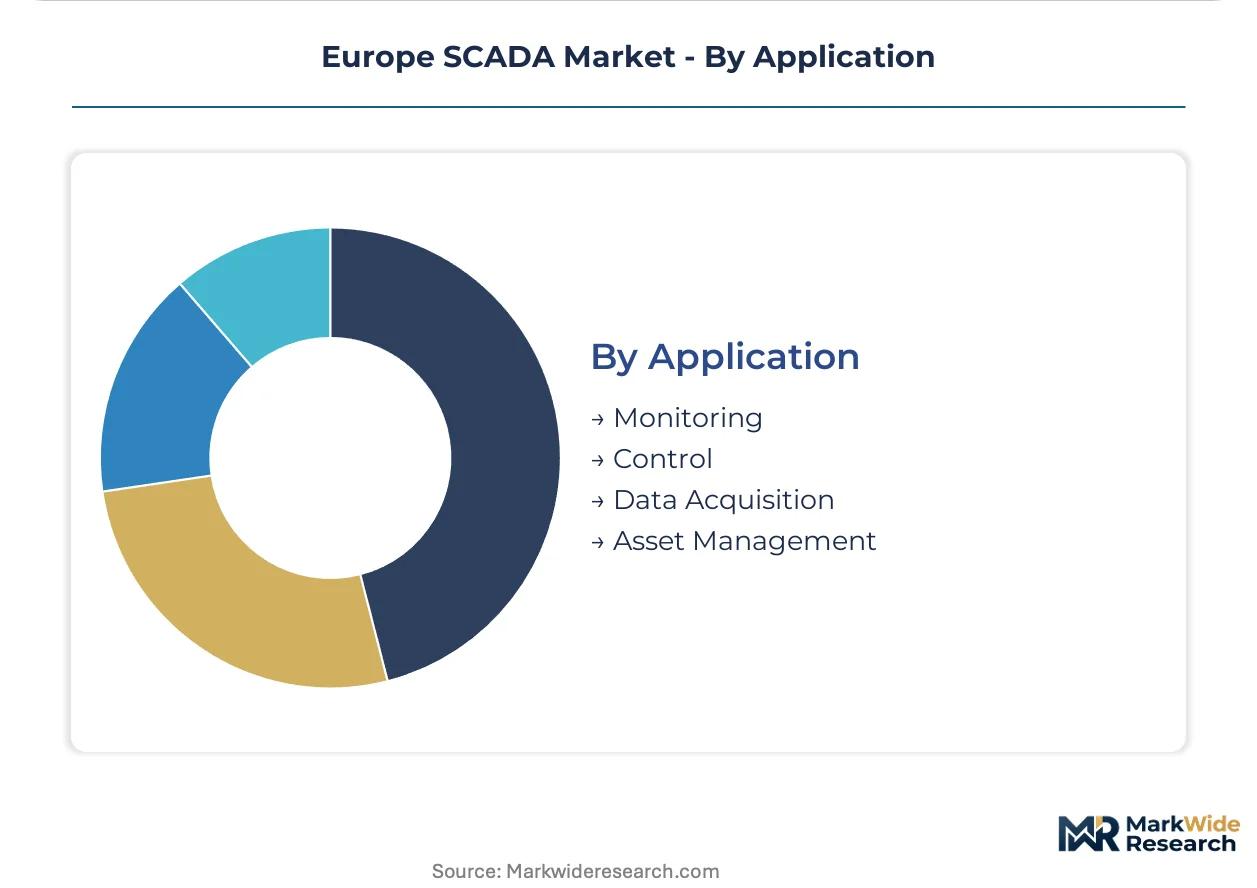
Application:
Functional requirements evolve from reactive alarm management toward predictive orchestration as digital twin technology matures for European transmission networks.
- Monitoring:Real-time visualization of geographically dispersed assets through centralized HMI dashboards. Dutch chemical plants deploy higher sensor density for REACH-mandated emissions tracking.
- Control:Remote command execution for circuit breakers, valves, and protection relays. Nordic TSOs prioritize sub-100ms latency for synthetic inertia provision from inverter-based resources.
- Data Acquisition:Time-series historian functions supporting forensic analysis and regulatory reporting. CE marking under MDR frameworks shapes validation requirements for safety-critical data loggers.
- Asset Management:Condition-based maintenance and lifecycle optimization through predictive analytics. German grid operators simulate virtual substation replicas to compress fault restoration timelines.
Monitoring retains the largest functional footprint, with Asset Management climbing fastest as digital twin adoption penetrates transmission infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping SCADA deployment patterns as utilities migrate modernization budgets toward jurisdictions offering faster permitting and cohesion fund access. The EU Green Deal's uniform carbon mandates mask significant national variance in implementation speed and subsidy intensity.
Germany
Grid operators TenneT and 50Hertz accelerate substation automation upgrades to manage renewable intermittency from North Sea wind clusters. The NIS2 directive forces municipal utilities to consolidate vendor relationships for audit simplicity. Bavarian chemical plants in Ludwigshafen and Leverkusen deploy edge-native architectures for real-time process control.
France
RTE and Enedis prioritize digital twin deployment across transmission corridors to compress fault restoration timelines. The MDR framework's CE marking requirements shape validation protocols for safety-critical data loggers. Auvergne-Rhône-Alpes manufacturing clusters drive demand for IT-OT bridge platforms in automotive supply chains.
Italy
Terna SpA embeds PMU processing nodes directly within switchgear for synthetic inertia provision. The F-Gas Regulation mandates refrigerant leak detection retrofits across Lombardy cold chain logistics. Veneto industrial automation investments in Vicenza and Verona prioritize interoperable platform ecosystems.
Poland
PSE and regional DSOs leverage EU cohesion funds to modernize district heating networks with greenfield SCADA architectures. REACH compliance requirements from ECHA shape material selections for field instrumentation procurement. Silesian industrial corridors retrofit legacy DNP3 installations with IEC 61850-compliant substation controllers.
Netherlands
TenneT Netherlands deploys hybrid edge-cloud architectures for North Sea offshore grid integration. The F-Gas Regulation's phase-down schedules drive ammonia detection loop upgrades at Rotterdam chemical terminals. Brabant manufacturing clusters adopt subscription-based remote monitoring through energy performance contractors.
Europe SCADA Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized compliance applications and edge-native software licensing. The vendor base concentrates around three strategic archetypes: diversified industrial conglomerates with embedded software heritage, pure-play automation specialists with substation integration expertise, and platform-centric integrators bridging IT-OT convergence. Dominant competitive moves include vertical integration into field instrumentation manufacturing and strategic partnerships with cloud hyperscalers for hybrid deployment architectures.
Among diversified industrial conglomerates, Siemens AG and ABB Group exemplify the scale-driven archetype through their embedded control system legacies. Schneider Electric SE occupies a distinct position within the platform-centric tier, emphasizing interoperable ecosystems. Rockwell Automation, Inc. represents the specialist vector with concentrated presence in discrete manufacturing automation. These anchors reflect broader structural patterns: German and Swiss-based conglomerates leverage process control heritage, while French and US-origin players prioritize software platformization and subscription revenue models.
| Leading Market Players |
|---|
| Rockwell Automation, Inc. |
| Honeywell International, Inc. |
| Siemens AG |
| Yokogawa Electric Corporation |
| General Electric Company |
| Schneider Electric SE |
| Emerson Electric Co. |
| Omron Corporation |
| ABB Group |
| Others |
Cost & Logistics Intelligence
Industrial-grade processor procurement from East Asian foundries cascades through three distinct pricing tiers as European system integrators absorb twelve-month lead time volatility into project quotations.
Pricing Analysis
Distributor margins compress most acutely at the hardware tier where semiconductor shortages persist. Three-tier pricing structure across premium, standard, and economy levels separates IEC 61850-certified substation controllers from legacy DNP3-compatible units and unbranded gateway hardware. Pricing pressure stems from NIS2 compliance investments that force mid-sized utilities toward bundled service contracts. Municipal water operators exhibit highest price sensitivity, while German TSOs prioritize latency performance over unit cost.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific semiconductor hubs to Rotterdam and Hamburg shapes inventory holding strategies across German automation distributors. Supply concentrates in Taiwan, South Korea, and Japan for industrial processors, with field instrumentation sourcing from China and Mexico. Raw material dependencies span silicon wafers, copper cabling, and rare earth magnetics for actuator motors. Single-source vulnerability in advanced node fabrication creates procurement risk. Distribution runs through authorized system integrators with direct OEM relationships for critical infrastructure projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe SCADA market functions as a stable compounder where regulatory replacement mandates compress hardware cycles and expand recurring software revenue pools.
For Market Incumbents: Hedge semiconductor exposure through multi-source qualification programs for industrial processors. Prioritize captive software subscription platforms to offset hardware margin erosion from East Asian supply constraints. Defend against edge-native entrants by embedding predictive analytics within existing HMI deployments at German chemical clusters. For New Entrants and Emerging Players: Launch via energy performance contractor channels in France and Italy where facility managers outsource capital decisions. Target Poland's district heating modernization funded by EU cohesion allocations. Exploit F-Gas refrigerant detection as a compliance-driven wedge application with faster procurement cycles than grid infrastructure. For Investors and Strategic Acquirers: Consolidation pressure builds where NIS2 audit burdens fragment mid-sized water utility vendor relationships. Five-to-ten year viability favors platform-centric integrators with recurring revenue depth over hardware-dependent system houses. Monitor IEC 62443 certification velocity among Polish and Romanian engineering firms as inflection signal for M&A timing.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Native Platform Development | Reduces latency for German TSO renewable integration below 100ms thresholds. |
| Backward Integration into Field Instrumentation | Captures REACH-compliant sensor margins for Benelux chemical terminal retrofits. |
| Subscription Service Conversion | Transforms French energy contractor relationships into recurring revenue streams. |
| Strategic Partnership with Cloud Hyperscalers | Enables hybrid deployments for Dutch offshore grid operators. |
| Acquisition of Cybersecurity Specialist | Addresses IEC 62443 talent scarcity burdening mid-sized European utilities. |
Research Approach
Multiple input streams — structured interviews with utility planning officers, automation vendor account directors, and system integration project leads; secondary validation against EU regulatory filings, ECHA REACH substance databases, and national grid operator procurement disclosures; plus customs trade data for industrial control equipment — were reconciled through bottom-up deployment tracking and top-down market sizing triangulation.
Data-stream reconciliation anchored volume projections to modeled segmentation across hardware-software-services product tiers, on-premises-cloud-hybrid-edge deployment architectures, and utility-manufacturing-transportation-oil & gas end-use verticals. CAGRs were derived from replacement cycle compression analysis and regulatory mandate implementation timelines, incorporating North Sea offshore wind capacity expansion and F-Gas phase-down schedules as demand drivers.
Forecast precision tightens around the base case; tail outcomes carry wider variance under NIS2 enforcement intensity variations and semiconductor supply normalization scenarios. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Robot Gearboxes Market
Industrial Automation
Brazil Factory Automation and Industrial Controls Market
Industrial Automation
Predictive Maintenance for Manufacturing Market
Industrial Automation
North America Machine Control System Market
Industrial Automation
Distribution Feeder Automation Market
Industrial Automation
Middle East and Africa Medical Automation Market
Industrial Automation
Smart Sorting Machine Market
Industrial Automation
Global PC Based Automation Market
Industrial Automation
Palletizing Systems Market
Industrial Automation
Industrial Automation Software Market
Industrial Automation
Sortation Systems Market
Industrial Automation
Europe Water Automation and Instrumentation Market
Industrial Automation
Asia Pacific Process Automation Market
Industrial Automation
Industrial Automation Products Market
Industrial Automation
GMC Based Motion Controller Market
Industrial Automation
Mining Automation Solutions Market