
 Magnetic Grippers Market | 2026-2036
Magnetic Grippers Market Size, Share, and Industry Trends Forecast 2026-2036
Magnetic Grippers Market Analytics
Buyer concentration among tier-one automotive OEMs is restructuring procurement patterns for magnetic gripper suppliers. Schunk leverages its modular gripper architecture to serve high-volume robotic integration contracts across European assembly plants. Goudsmit Magnetics anchors its position through deep specialization in permanent magnet assemblies for ferrous material handling. Schmalz competes by extending its vacuum and magnetic hybrid systems into collaborative robot installations.
Magnetic grippers are electromechanical end-effectors that generate holding force through either electrically activated coils or permanent rare-earth magnet arrays, typically achieving clamping forces from fifty to over one thousand newtons depending on pole geometry and surface contact area. These devices serve primarily to manipulate ferrous workpieces in automated manufacturing environments where pneumatic or vacuum alternatives risk contamination or slippage. Electromagnetic grippers dominate high-cycling robotic applications where precise on-off control prevents accidental part release during transfer motions. Permanent magnetic grippers sustain margin pools in heavy material handling segments where continuous power draw would penalize operating economics. Smart technology integration across sensor-based gripper variants is expanding fastest as machine vision and force-feedback systems converge on adaptive grasping protocols.
The EU Machinery Directive and ISO 10218 collaborative robot safety standards shape product design requirements for magnetic gripper manufacturers serving European automation integrators. OSHA lockout-tagout regulations in the United States and China's GB standards for industrial robot safety create parallel compliance obligations for suppliers with transnational footprints. Stakeholders must monitor how evolving energy-efficiency mandates and rare-earth material sourcing disclosures reshape total cost-of-ownership calculations for permanent versus electromagnetic gripper architectures.
Market Dynamics
Automotive electrification is forcing magnetic gripper suppliers to redesign pole geometries for lighter, non-ferrous vehicle architectures while maintaining clamping integrity on remaining steel chassis components.
Growth Catalysts
- ISO 10218 compliance mandates:Collaborative robot installations across European automotive plants require certified magnetic grippers with force-feedback safety systems, expanding replacement demand.
- Rare-earth magnet performance gains:Neodymium-iron-boron arrays now achieve holding forces exceeding 1000 newtons in compact footprints, enabling deployment in precision electronics assembly.
- Yangtze River Delta automation:Electronics contract manufacturers in this Chinese manufacturing corridor are retrofitting SMT lines with electromagnetic grippers to eliminate vacuum contamination risks.
Market Restraints
- Neodymium price volatility:Permanent magnet architectures face margin compression when Chinese rare-earth export quotas tighten, as seen in 2021 supply disruptions.
- Single-source magnet supply:Over 60% of processed rare-earth magnet material originates from Chinese separation facilities, creating geographic concentration risk.
- Non-ferrous material substitution:Automotive body-in-white aluminum adoption above 50% by weight in premium electric vehicle platforms eliminates gripper applicability on major subassemblies.
Strategic Opportunities
- India PLI scheme automation:Electronics and automotive component manufacturing incentives are creating first-mover advantage for gripper suppliers establishing local integration partnerships.
- GB standard harmonization:China's evolving industrial robot safety framework is opening certification pathways for European-designed collaborative gripper systems.
- Machine vision convergence:Adaptive grasping protocols combining force feedback with real-time surface detection are enabling deployment in unstructured bin-picking environments.
Industry Challenges
- Mechatronics engineering scarcity:Gripper OEMs struggle to hire specialists capable of integrating magnetic flux simulation with robotic kinematic modeling.
- CE-MDR dual certification timelines:European integrators face 14-18 month approval cycles when combining machinery directive compliance with medical device gripper applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnetic Grippers Market |
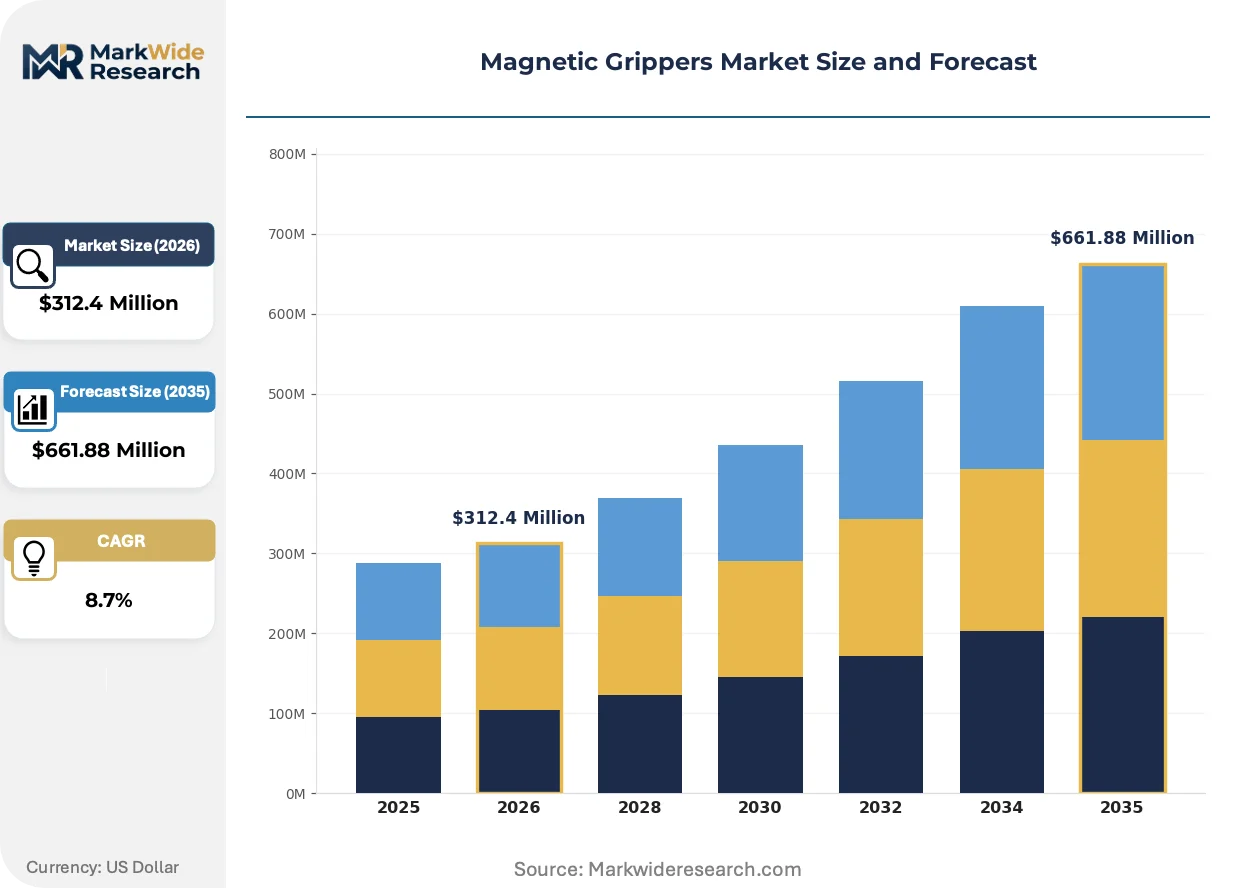
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromagnetic Grippers, Permanent Magnetic Grippers, Customized Grippers, Vacuum Assist Grippers Application: Robotics, Material Handling, Assembly Automation, Pick and Place Operations End User: Manufacturing, Automotive Industry, Electronics, Packaging Technology: Sensor-Based, Pneumatic Control, Manual Control, Smart Technology |
| Companies Covered | Goudsmit Magnetics, Schmalz, Schunk, PHD, FIPA, SMC, Zimmer, SAS Automation, Master Magnetics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnetic Grippers Market Evolving Landscape
Sensor fusion architectures are displacing simple on-off magnetic control, enabling real-time grip force modulation that adapts to surface irregularities without pneumatic backup systems.
Permanent magnet arrays with electrically switchable polarity are integrating Hall-effect position sensors to provide closed-loop verification of workpiece contact before robot motion initiation. Tier-one automotive OEMs in Germany and Japan are specifying these verified-grip systems for unattended night-shift operations. The technology is integrating predictive maintenance algorithms that flag demagnetization trends before clamping failures occur.
REACH substance restrictions on hexavalent chromium surface treatments are forcing suppliers to migrate from traditional electroplated pole shoes to nickel-copper-nickel coating stacks. The regulation is compressing supplier qualification timelines as integrators demand material disclosure documentation spanning full supply chains. Electromagnetic gripper manufacturers serving European medical device automation are experiencing the most acute compliance pressure.
Consolidated procurement through robotic system integrators is displacing direct OEM sales, compressing available margin for component suppliers. Automotive buyers in Stuttgart and Nagoya now mandate single-source accountability for full end-effector performance, forcing gripper specialists to partner with sensor and cable management providers. This channel consolidation is most advanced in battery tray handling applications where Tesla and BYD specify integrated gripper-vision-force packages.
Magnetic Grippers Market Segmentation
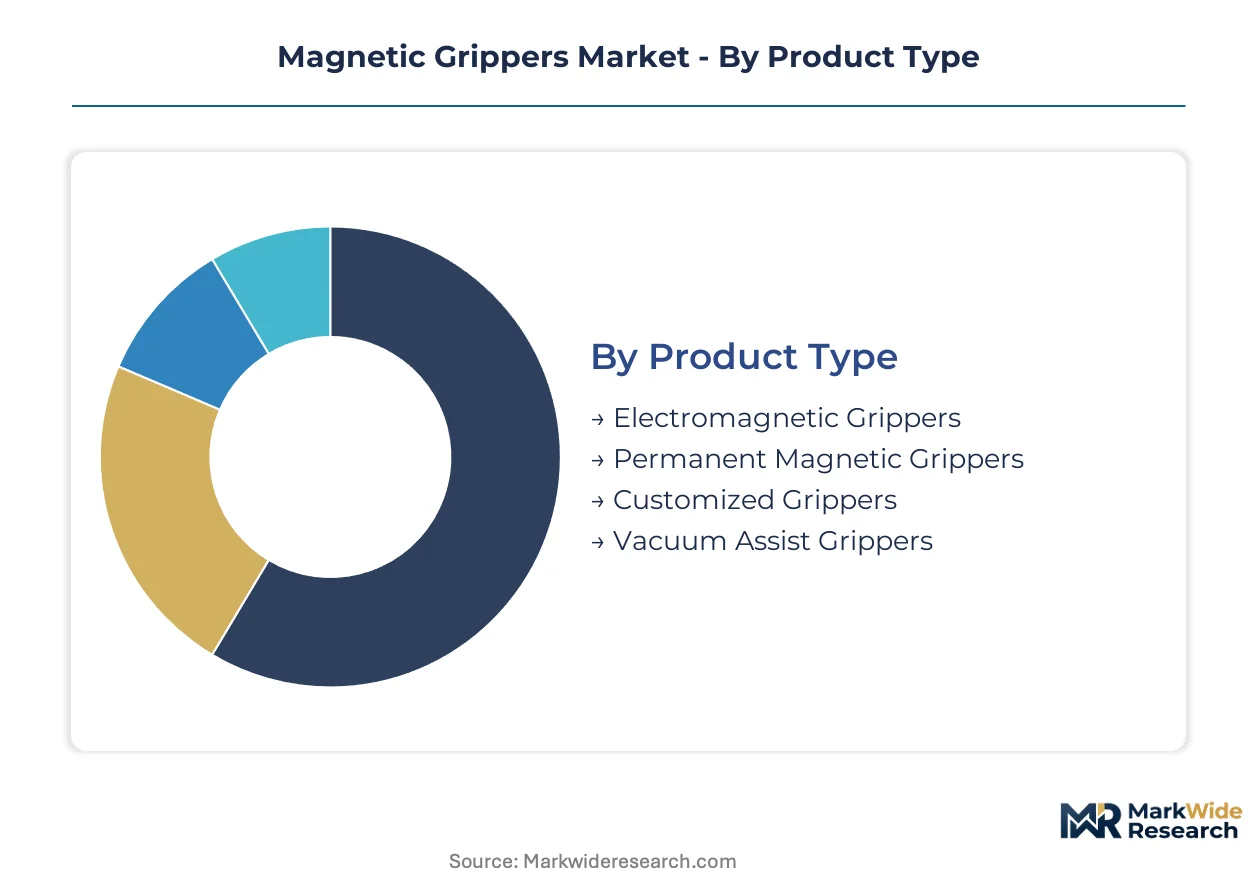
Magnetic gripper segmentation reveals distinct integration architectures across manufacturing environments. Standalone electromagnetic systems dominate high-cycling robotic cells, while embedded permanent magnet arrays serve cost-sensitive material handling operations. Understanding these deployment patterns enables suppliers to align R&D investment with actual procurement workflows rather than theoretical demand curves.
Product Type:
Integration depth varies sharply across product architectures, with standalone electromagnetic systems commanding premium positioning in robotic OEM channels while embedded permanent magnet modules penetrate through distributor networks serving retrofit applications.
- Electromagnetic Grippers:These systems generate variable holding force through electrically activated copper coils wound around ferromagnetic cores, enabling precise on-off control via PLC signals. Automotive assembly plants in Germany and Japan specify these for robotic welding lines where accidental part release during transfer motions carries catastrophic liability. ISO 10218 force-feedback safety mandates are accelerating replacement demand across European collaborative robot installations.
- Permanent Magnetic Grippers:Rare-earth neodymium-iron-boron arrays deliver continuous clamping force without electrical input, eliminating power-failure risk in heavy material handling. Yangtze River Delta electronics contract manufacturers favor these for ferrous component placement where vacuum alternatives risk electrostatic contamination. Neodymium price volatility from Chinese export quota fluctuations compresses margin pools during supply disruptions.
- Customized Grippers:Application-specific pole geometries and flux patterns designed for unique workpiece contours in aerospace and medical device automation.
- Vacuum Assist Grippers:Hybrid architectures combining magnetic holding with pneumatic vacuum backup for non-ferrous surface handling in mixed-material assembly environments.
Electromagnetic grippers lead volumes today; permanent magnetic variants are gaining share fastest in heavy material handling segments seeking energy independence.
Application:
Cost tier stratification separates precision robotics commanding system-integrator pricing from commoditized material handling sold through industrial distributors.
- Robotics:End-effector integration with six-axis industrial and collaborative robots demands certified force-feedback systems with real-time grip verification. Tier-one automotive OEMs in Stuttgart and Nagoya mandate these for unattended night-shift operations where human intervention is economically prohibitive. Predictive maintenance algorithms flagging demagnetization trends before clamping failures command substantial pricing premiums.
- Material Handling:Overhead crane and conveyor-mounted magnetic systems for raw steel, scrap metal, and finished ferrous goods prioritize holding force reliability over precision control. Steel service centers and foundries in India's PLI scheme corridors represent emerging demand concentration as local automation partnerships mature.
- Assembly Automation:Fixed-station magnetic fixtures for welding, riveting, and adhesive bonding operations in automotive body-in-white construction.
- Pick and Place Operations:High-speed bin-picking and sorting applications combining machine vision with adaptive magnetic grasping protocols.
Material handling leads volumes today; robotics applications are climbing the fastest as collaborative robot deployments expand.
End User:
Customer type concentration creates divergent procurement patterns, with automotive OEMs demanding single-source accountability while packaging buyers prioritize distributor availability and rapid spare parts fulfillment.
- Automotive Industry:Body-in-white welding, battery tray handling, and powertrain assembly operations specify integrated gripper-vision-force packages from qualified system integrators. Tesla and BYD procurement mandates for single-source end-effector performance are compressing available margin for component specialists. Electrification trends forcing redesign for lighter non-ferrous architectures while maintaining steel chassis clamping integrity.
- Electronics:Surface-mount technology lines and semiconductor packaging operations require contamination-free ferrous component handling in cleanroom environments. REACH substance restrictions on hexavalent chromium surface treatments are compressing supplier qualification timelines as integrators demand full supply chain material disclosure documentation.
- Manufacturing:General industrial automation spanning metal fabrication, appliance production, and machinery assembly with standardized gripper specifications.
- Packaging:End-of-line palletizing and depalletizing operations for canned goods and ferrous container handling in food and beverage facilities.
Automotive leads volumes today; electronics is expanding most quickly as contract manufacturers automate component placement.
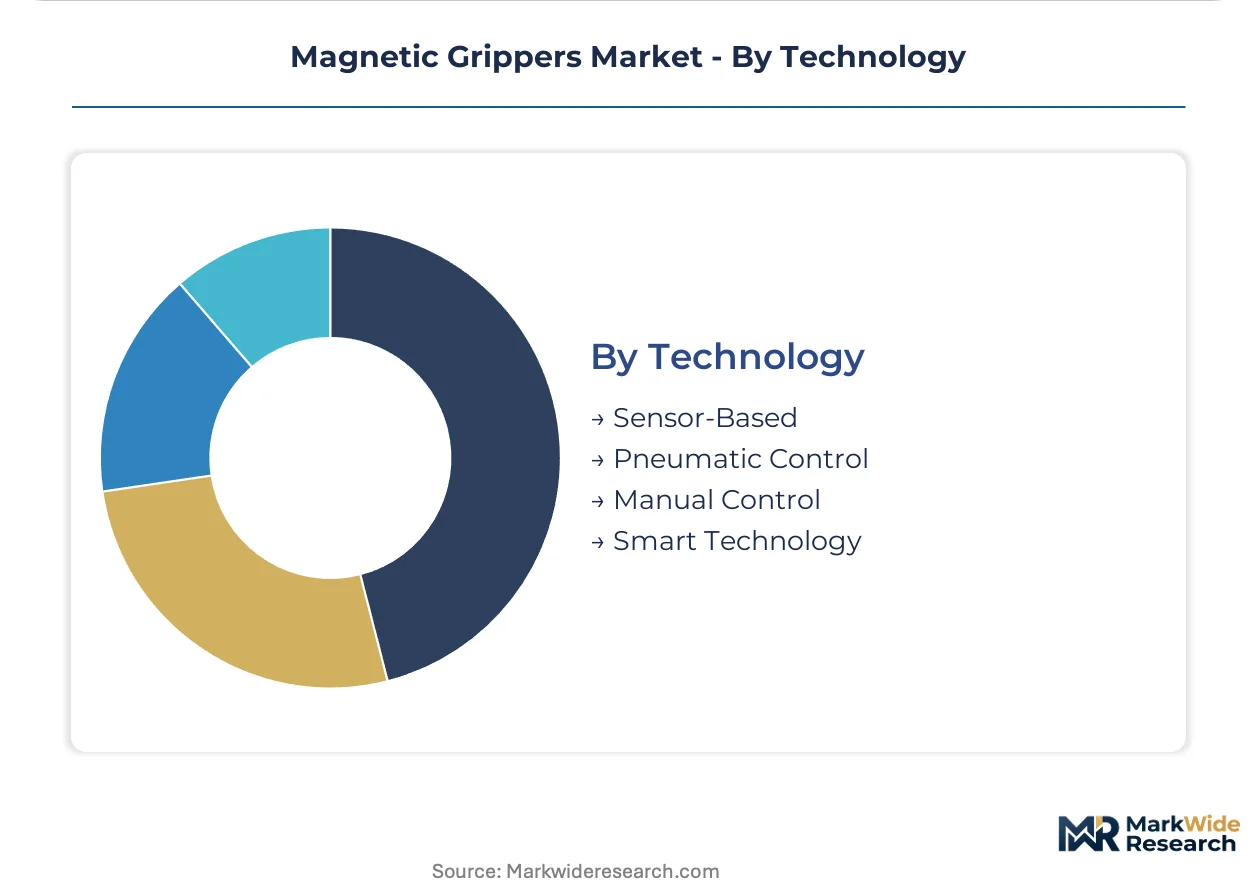
Technology:
Technology maturity curves separate established pneumatic and manual control architectures from emerging smart systems integrating sensor fusion and adaptive grasping protocols.
- Smart Technology:Sensor fusion architectures displacing simple on-off magnetic control enable real-time grip force modulation adapting to surface irregularities without pneumatic backup. Hall-effect position sensors providing closed-loop workpiece contact verification before robot motion initiation. Tier-one automotive OEMs specifying these verified-grip systems for liability-sensitive unattended operations.
- Sensor-Based:Discrete force, proximity, and temperature sensors monitoring gripper health and workpiece presence in basic feedback configurations. Machine vision convergence enabling deployment in unstructured bin-picking environments where workpiece orientation varies.
- Pneumatic Control:Compressed air actuation of magnetic release mechanisms in legacy industrial automation installations.
- Manual Control:Hand-operated magnetic switches and mechanical release levers in non-automated material handling and maintenance applications.
Sensor-based systems lead volumes today; smart technology is gaining share fastest as adaptive grasping protocols mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive automation density contrasts with China's electronics manufacturing scale, while Japan maintains precision robotics leadership. These three markets anchor magnetic gripper procurement patterns, with India and the United States completing the demand map through divergent industrial incentives.
Germany
Automotive OEMs in Stuttgart and Wolfsburg specify electromagnetic grippers for body-in-white welding lines and battery tray handling. The EU Machinery Directive and ISO 10218 safety mandates force gripper suppliers into 14-18 month certification cycles for collaborative robot installations. Bavarian system integrators now demand single-source accountability for full end-effector performance, compressing margins for component specialists.
China
Electronics contract manufacturers in the Yangtze River Delta retrofit SMT lines with electromagnetic grippers to eliminate vacuum contamination risks. GB standards for industrial robot safety are harmonizing with European frameworks, opening certification pathways for foreign-designed collaborative systems. Shanghai and Suzhou automation clusters concentrate procurement power as local integrators consolidate supplier relationships.
Japan
Precision robotics OEMs in Nagoya and Tokyo specify verified-grip magnetic systems with Hall-effect sensors for unattended night-shift operations. METI industrial automation incentives support domestic gripper production for export markets. Kansai-region automotive plants are expanding electromagnetic gripper deployment in hybrid vehicle assembly where steel chassis components persist.
India
PLI scheme incentives for electronics and automotive component manufacturing are creating first-mover opportunities for gripper suppliers establishing local integration partnerships. BIS industrial safety standards are evolving toward ISO alignment, shortening foreign equipment qualification timelines. Tamil Nadu and Gujarat manufacturing corridors represent emerging demand concentration as automation partnerships mature.
United States
OSHA lockout-tagout regulations shape gripper design requirements for automotive and general manufacturing automation. The Southeast automotive corridor and Texas electronics assembly plants drive replacement demand for legacy pneumatic systems. Midwest metal fabrication centers prioritize permanent magnet grippers for energy-independent heavy material handling operations.
Magnetic Grippers Market Competitive Landscape
German producers anchor the premium tier through integrated system supply; Japanese and Chinese specialists hold positions in precision and cost-optimized segments respectively. The vendor base concentrates around three strategic archetypes: modular architecture suppliers serving high-volume robotic integration, permanent magnet specialists dominating heavy material handling, and hybrid system providers extending into collaborative installations. Competitive moves center on backward integration into rare-earth magnet supply and geographic expansion through local integration partnerships in India and Southeast Asia.
Within the European modular architecture tier, Schunk and Goudsmit Magnetics occupy positions reflecting divergent specialization paths. Schunk leverages its German engineering base to serve automotive OEM consolidation trends. Goudsmit Magnetics anchors the permanent magnet assembly segment through Dutch technical heritage in ferrous material handling. Schmalz represents the hybrid system archetype, extending vacuum-magnetic combinations into collaborative robot channels where ISO 10218 certification creates barriers for pure-play competitors.
| Leading Market Players |
|---|
| Goudsmit Magnetics |
| Schmalz |
| Schunk |
| PHD |
| FIPA |
| SMC |
| Zimmer |
| SAS Automation |
| Master Magnetics |
| Others |
Value Network & Pricing Analysis
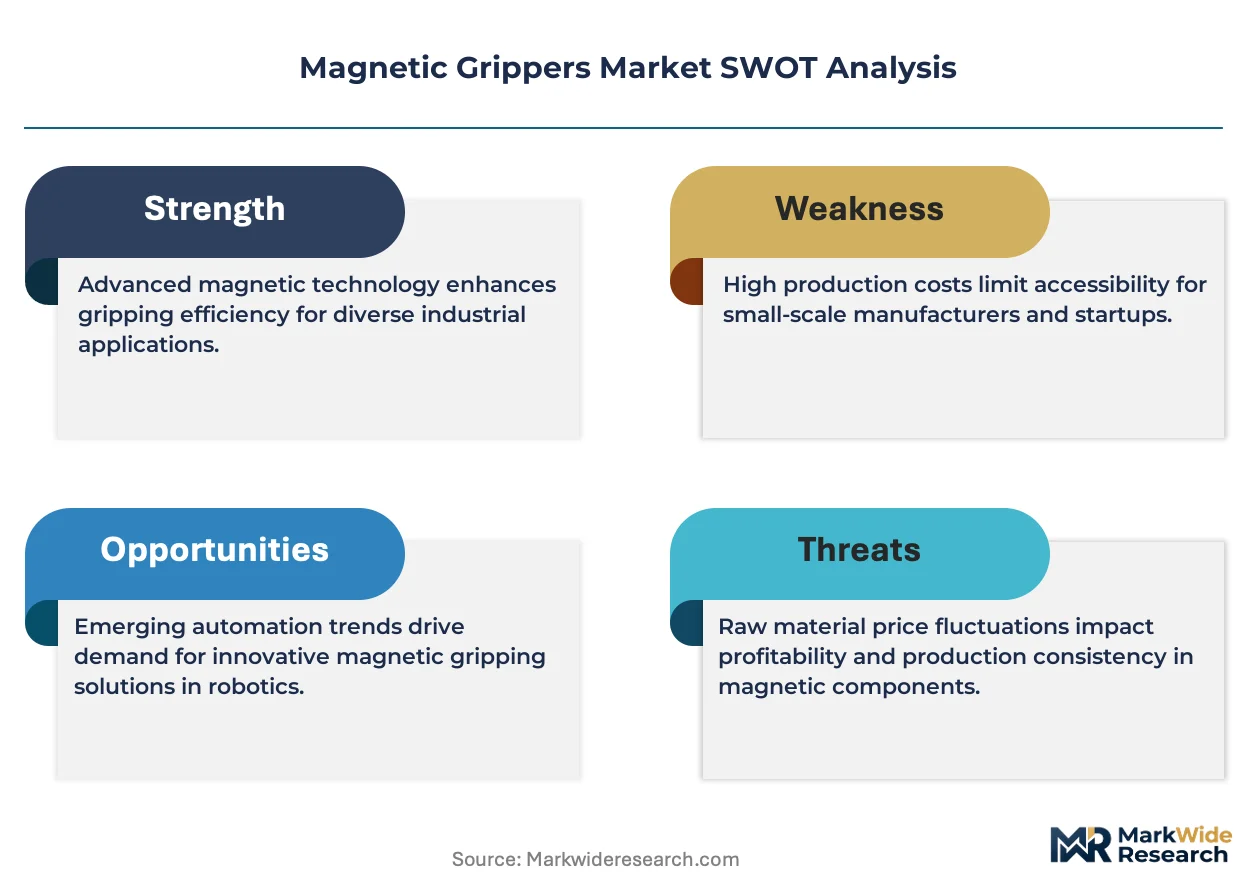
Neodymium export quota volatility from Chinese separation facilities cascades through magnetic gripper manufacturing, compressing margin pools for permanent magnet architectures while amplifying pricing power for electromagnetic system suppliers serving automotive OEM consolidation.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for standard electromagnetic grippers sold through distributor channels. Three-tier pricing structure across premium, standard, and economy levels separates ISO 10218-certified collaborative systems from legacy pneumatic-replacement units. Cost compression in the economy tier is intensifying because contract manufacturers prioritize rapid spare parts availability over predictive maintenance capabilities. Electronics contract manufacturers exhibit highest price sensitivity; tier-one automotive OEMs in Stuttgart and Nagoya accept substantial premiums for verified-grip Hall-effect sensor integration.
Supply Chain Analysis
CE marking and ISO 10218 certification gates create 14-18 month qualification timelines that filter supplier participation in European collaborative robot channels. Magnet raw material processing concentrates in China, with secondary winding and assembly operations in Germany and Japan. Copper coil supply draws from Chilean mining operations and Chinese smelters, while rare-earth magnet feedstock rests on Mongolian and Australian ore extraction. Single-source vulnerability in Chinese rare-earth separation facilities exposes permanent magnet architectures to quota-driven disruption. Distribution runs through robotic system integrators consolidating procurement power in battery tray handling applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in smart technology tiers where sensor fusion architectures command pricing premiums, while neodymium cost volatility creates arbitrage potential for electromagnetic gripper specialists.
For Market Incumbents: Acquire Hall-effect sensor and machine vision software capabilities to defend integrated gripper-vision-force package positioning against pure-play magnetic component suppliers. Backward integration into rare-earth magnet recycling or alternative magnetic material R&D hedges Chinese export quota exposure. Prioritize certification investment in India's BIS alignment pathway to capture PLI scheme automation demand before local partnerships mature. For New Entrants and Emerging Players: Capture electronics contract manufacturer retrofit demand in India's Tamil Nadu and Gujarat corridors where automation partnerships remain underdeveloped. Target vacuum-magnetic hybrid architectures for mixed-material assembly environments where aluminum adoption in automotive body-in-white eliminates pure magnetic applicability. Pursue distributor channel relationships rather than direct OEM sales to bypass incumbent system integrator consolidation. For Investors and Strategic Acquirers: Asymmetric upside sits with smart technology specialists possessing closed-loop force feedback and predictive maintenance algorithms. Five-to-ten year viability favors suppliers with demonstrated ISO 10218 certification velocity and established relationships with tier-one automotive OEM procurement committees. Monitor neodymium price index stabilization as inflection indicator for permanent magnet architecture margin recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Magnet Supply | Captures margin pools exposed to Chinese export quota volatility. |
| ISO 10218 Certification Acceleration | Unlocks European collaborative robot replacement demand cycles. |
| Machine Vision Partnership Development | Enables verified-grip systems for unattended night-shift operations. |
| India PLI Scheme Localization | Establishes first-mover positioning in emerging electronics automation corridors. |
| REACH-Compliant Surface Treatment Migration | Preserves European medical device automation market access. |
Research Methodology
Multiple input streams — procurement director interviews at tier-one automotive OEMs, technical consultations with robotic system integrators, and regulatory affairs discussions with CE marking specialists — were reconciled against customs trade data, EU Machinery Directive enforcement records, and SEC filings from automation component suppliers. Bottom-up demand modeling from SMT line retrofit projects and top-down market sizing from robotic end-effector shipment aggregates were cross-validated.
Historical shipment trajectories were cross-referenced against panel input from plant engineers and maintenance directors to establish baseline penetration rates across the projection horizon. Segmentation dimensions modeled include gripper architecture type, application intensity tier, end-user industry vertical, and regional regulatory cluster. CAGRs were derived from installed base growth and replacement cycle dynamics, with specific weighting for collaborative robot safety mandate compliance timelines and rare-earth material cost pass-through elasticity.
Neodymium supply disruption recurrence, automotive electrification pace affecting steel chassis share, and GB standard harmonization velocity are the dominant revision risks to modeled outputs. A model refresh is warranted upon material change in Chinese rare-earth export quota policy or ISO 10218 enforcement intensity across European automotive plants.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
US and Europe Warehouse Automation Market
Industrial Automation
Factory Automation Platform As a Service Market
Industrial Automation
Industrial Automation Services Market
Industrial Automation
Global Distribution Feeder Automation System Market
Industrial Automation
Asia-Pacific Industrial Automation Market
Industrial Automation
US Smart Manufacturing Market
Industrial Automation
Global Industrial Automation and Control Systems Market
Industrial Automation
Embedded Automation Computers Market
Industrial Automation
Internet of Things Enabled Industrial Wearables Market
Industrial Automation
Robotic Paint Booth Market
Industrial Automation
Europe Retail Automation Market
Industrial Automation
Global PC Based Automation Market
Industrial Automation
North America Industrial Automation Market
Industrial Automation
Middle East and Africa Industrial Automation Market
Industrial Automation
Europe Water Automation and Instrumentation Market
Industrial Automation
Middle East Programmable Logic Controller (PLC) Market