
 Asia-Pacific Industrial Automation Market | 2026-2036
Asia-Pacific Industrial Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Industrial Automation Market Insights
Copper winding materials in servo motors is realigning cost structures across precision motion systems. ABB leverages its robotics heritage to dominate automotive welding applications. Siemens sustains technology leadership through its digital twin software stack for factory floors. Yaskawa Electric Corporation anchors Japanese supply chains with specialized AC servo and motion controller production.
Asia-Pacific industrial automation encompasses electromechanical systems, programmable logic controllers, sensor networks, and robotic platforms engineered for precise, repeatable manufacturing operations with response times measured in milliseconds. The primary purpose centers on reducing human intervention in hazardous, high-throughput, or quality-critical production environments. Robotics and control systems capture the dominant share of equipment spending as manufacturers prioritize flexible production lines. Machine learning and AI technology within the automation software layer represent the fastest-expanding margin pool, though sensors remain the most mature segment with compressed pricing.
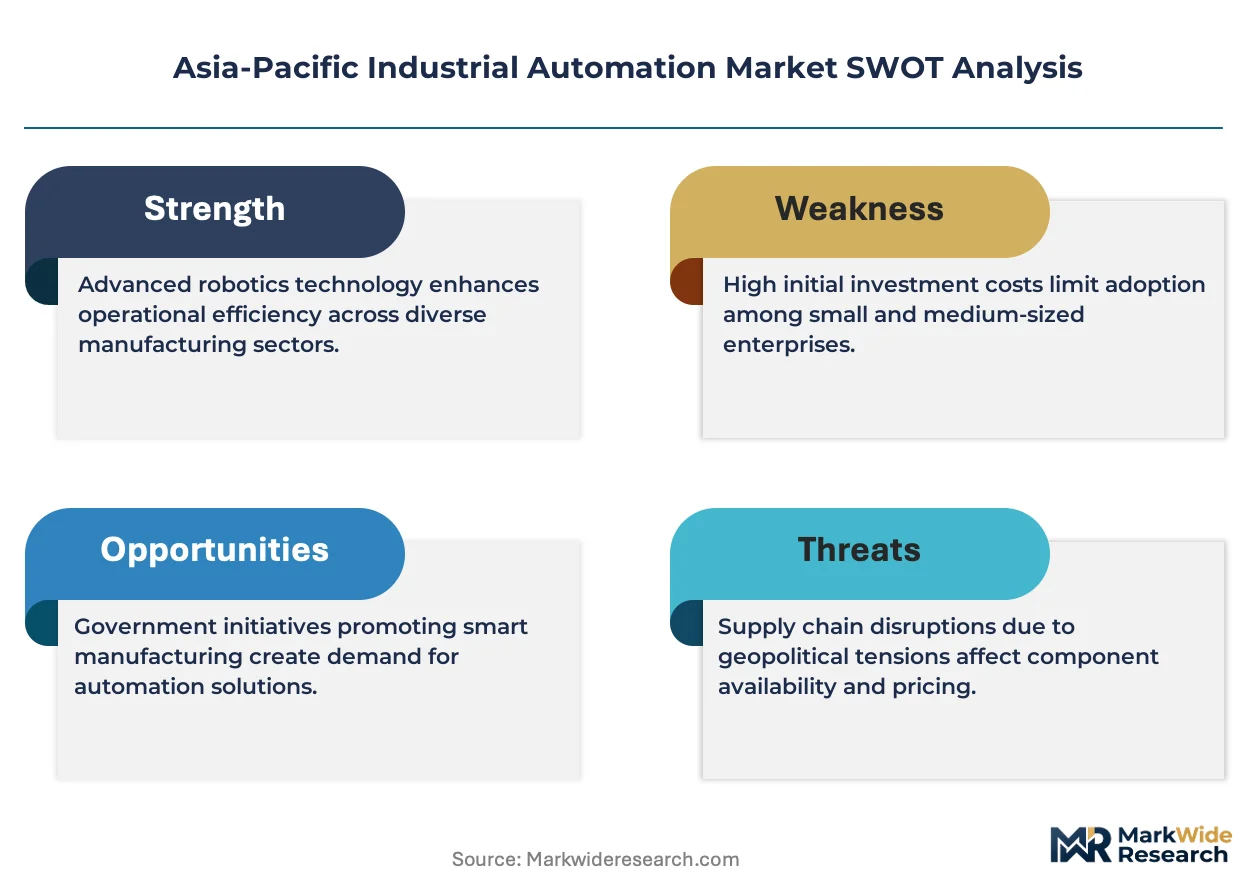
China's MIIT enforces GB standards for industrial robot safety and interoperability, while Japan's METI promotes JIS-certified smart factory architectures through its Society 5.0 framework. These regulatory frameworks compel vendors to localize certification and adapt product portfolios to national conformance requirements. Stakeholders must weigh the cost of multi-standard compliance against the volume premium available in each national market.
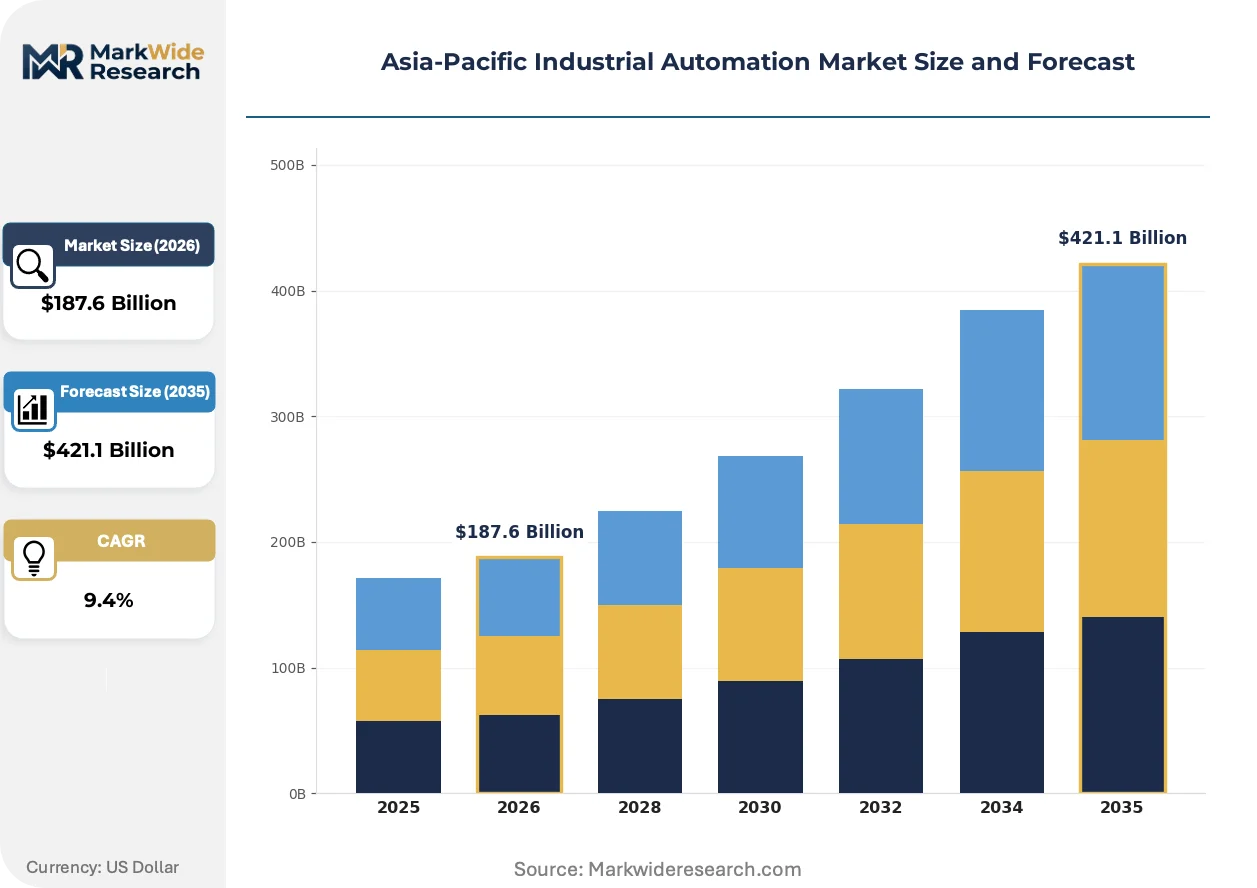
Market Dynamics
China's MIIT mandates for domestic servo motor production are forcing foreign vendors to localize supply chains or surrender market position to indigenous competitors with state-backed scale advantages.
Growth Catalysts
- Semiconductor cleanroom robotics:South Korean fabrication facilities are expanding robot deployment for wafer handling and contamination-sensitive operations, pulling precision motion control demand.
- Japan's Society 5.0 framework:METI-certified smart factory architectures subsidize IoT sensor integration and predictive maintenance software adoption across automotive supplier networks.
- Copper winding substitution:Rare-earth magnet supply volatility accelerates development of ferrite-based servo motors with comparable torque density for mid-precision applications.
Market Restraints
- Input cost volatility:Neodymium and dysprosium price swings from Chinese export quotas compress margin stability for permanent magnet motor producers.
- Supply concentration risk:Precision harmonic drive gearheads depend on Japanese and German suppliers with limited second-source alternatives.
- Technical limitation:Millisecond-level synchronization across heterogeneous vendor control systems remains unresolved without proprietary middleware lock-in.
Strategic Opportunities
- Vietnam and Indonesia manufacturing bases:Greenfield automotive and electronics assembly plants lack legacy automation infrastructure, enabling direct deployment of collaborative robot platforms.
- Digital twin convergence:Physics simulation software is converging with real-time edge analytics to enable virtual commissioning of production lines before physical installation.
- Australia's critical minerals processing:Lithium hydroxide and rare-earth refining facilities require explosion-proof automation systems with limited incumbent vendor presence.
Industry Challenges
- Multi-standard certification timelines:Vendors must secure separate GB, JIS, and KCS approvals for cross-border deployment, extending product launch cycles by 8-14 months.
- Legacy PLC integration friction:Brownfield facilities running 1990s-era ladder logic controllers resist retrofit with modern Ethernet-based motion networks without complete control architecture replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Industrial Automation Market |
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $421.1 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Control Systems, Sensors, Robotics, Deployable Units Application: Manufacturing, Process Automation, Warehouse Management, Smart Grids End User: Manufacturers, Supply Chain, Oil & Gas, Mining Technology: IoT, Machine Learning, AI, Automation Software |
| Companies Covered | Mitsubishi Electric Corporation, Rockwell Automation, ABB, Schneider Electric, OMRON Corporation, Siemens, Yaskawa Electric Corporation, Emerson Electric, FANUC Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Industrial Automation Market Trends and Innovations
Edge-native AI inference is displacing cloud-dependent quality inspection, compressing defect response latency from seconds to milliseconds while reducing bandwidth costs for high-resolution machine vision.
Time-sensitive networking over standard Ethernet is converging with deterministic motion control protocols to unify factory floor communication on a single physical layer. Automotive tier-one suppliers in Japan and South Korea are piloting TSN-enabled servo drives for mixed-criticality traffic. This convergence is collapsing the historical separation between information technology and operational technology infrastructure procurement.
China's GB/T industrial robot safety standards mandate functional safety certifications equivalent to ISO 10218, compelling foreign vendors to establish in-country testing facilities. The regulation compresses product registration timelines for compliant manufacturers while erecting documentation barriers for uncertified imports. European robotics vendors are responding by acquiring Chinese certification bodies to accelerate market access.
After-sales service unbundling is fragmenting traditional equipment-plus-maintenance contracts into separate hardware, software license, and remote support subscriptions. Japanese automotive component manufacturers now procure predictive analytics as standalone SaaS rather than bundled with motion controller hardware. This shift is most pronounced in South Korea, where Hyundai and Kia supplier networks negotiate software renewals independently from capital equipment procurement.
Asia-Pacific Industrial Automation Market Segmentation
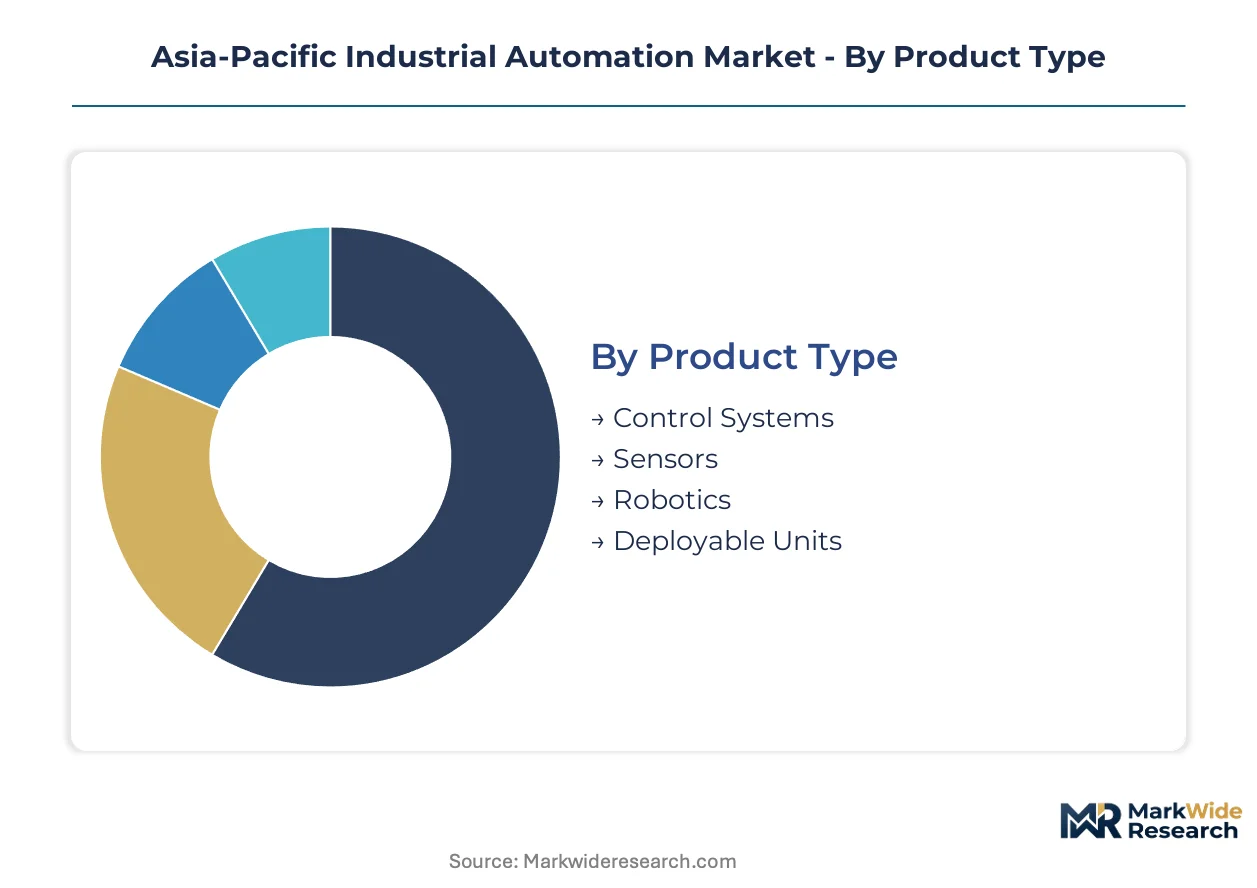
Industrial automation procurement in Asia-Pacific fragments across four analytical dimensions. Product type determines capital allocation cycles, while technology selection locks in decade-long vendor relationships. Application context dictates regulatory compliance burdens and integration complexity.
Product Type:
Volume concentrates in mature electromechanical equipment, while premium margins accrue to software-integrated platforms with predictive capabilities.
- Control Systems:Programmable logic controllers and distributed control systems orchestrate factory floor operations with millisecond response guarantees. China's automotive stamping plants and Japan's semiconductor backend facilities anchor demand as both geographies push for higher line speeds.
- Robotics:Articulated arms, SCARA units, and collaborative platforms execute precise, repeatable motion sequences. South Korean cleanroom deployments for wafer handling and Chinese EV battery assembly lines are pulling six-axis precision systems fastest.
- Sensors:Photoelectric, inductive, and vision-based detection devices feed real-time process data upstream. These units face compressed pricing from domestic Chinese producers.
- Deployable Units:Pre-integrated skid-mounted automation packages reduce field commissioning time for greenfield facilities. Australia's lithium processing plants and Indonesian nickel smelters are specifying explosion-rated variants.
Today's leader: Control Systems. Tomorrow's challenger: Robotics.
Application:
Customer procurement maturity separates brownfield retrofit opportunities from greenfield platform decisions.
- Manufacturing:Discrete assembly operations demand flexible reconfiguration for model changeovers. Japan's automotive supplier networks and China's consumer electronics contract manufacturers are converging on modular cell architectures.
- Process Automation:Continuous flow operations in chemicals, pharmaceuticals, and food processing require batch consistency validation. Australia's rare-earth refining facilities and South Korean petrochemical complexes are specifying IEC 61511-compliant safety instrumented systems.
- Warehouse Management:Automated storage and retrieval systems with autonomous mobile robots compress fulfillment latency. Southeast Asian e-commerce fulfillment centers are expanding fastest.
- Smart Grids:Distribution automation and substation control integrate renewable intermittency. China's State Grid deployments and Australia's NEM-connected microgrids are driving substation retrofit cycles.
Manufacturing commands current spend share. Warehouse Management is climbing the fastest as logistics automation penetrates tier-two cities.
End User:
Capital intensity and safety criticality stratify buyer sophistication and contract values.
- Manufacturers:Discrete and process producers across automotive, electronics, and consumer goods represent the foundational demand base. Japanese precision component makers and Chinese EV original equipment manufacturers are specifying digital twin-integrated lines.
- Supply Chain:Third-party logistics providers and distribution operators prioritize asset utilization metrics over absolute throughput. South Korean port automation and Vietnamese cross-border fulfillment hubs are deploying autonomous yard tractors.
- Oil & Gas:Upstream and downstream operators require explosion-proof certification and SIL-rated safety systems. Australia's LNG trains and Malaysia's offshore platforms are sustaining demand for harsh-environment actuators.
- Mining:Surface and underground extraction operations automate haulage and processing to reduce labor exposure. Indonesia's nickel laterite operations and Western Australia's iron ore Pilbara region are deploying autonomous haul trucks at scale.
Manufacturers retain volume leadership. Mining is gaining share fastest as autonomous haulage economics improve.
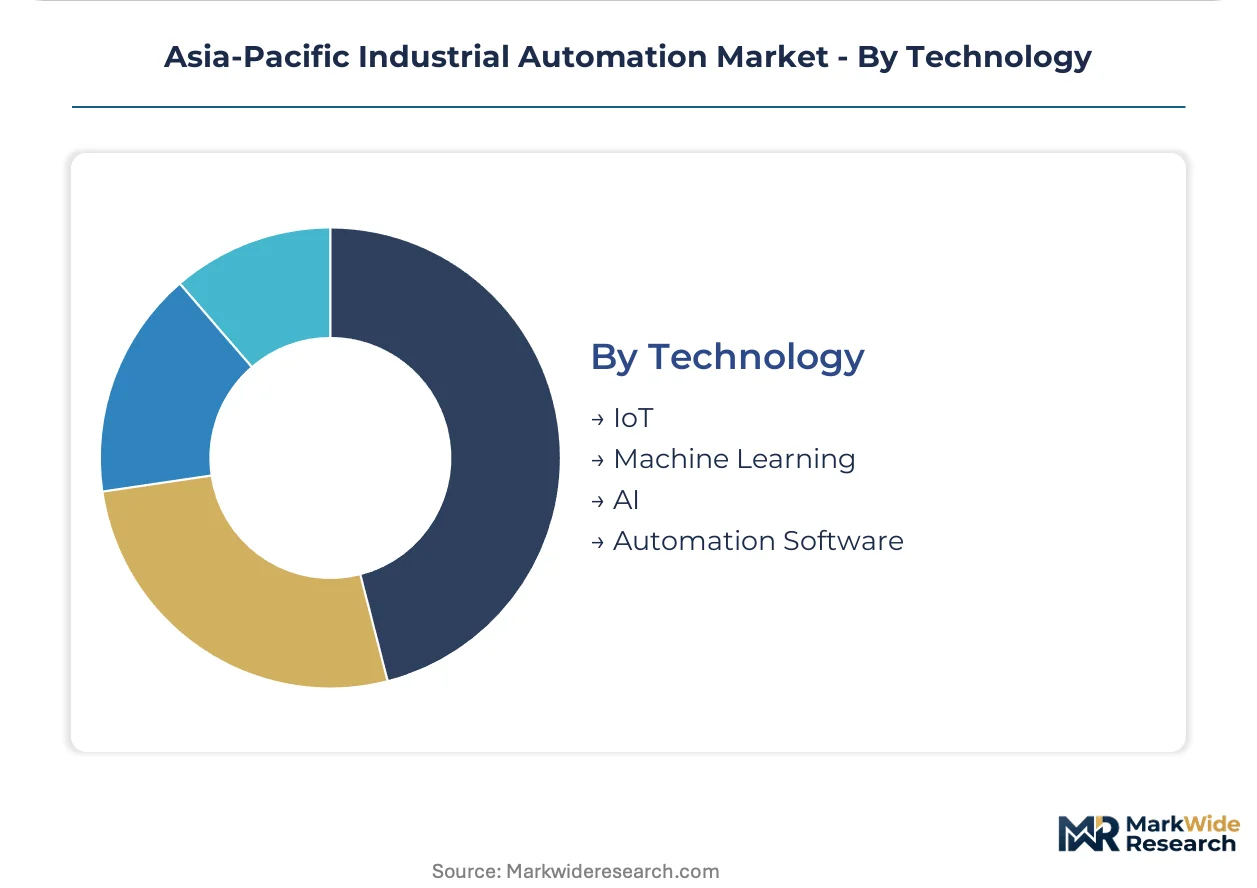
Technology:
Stack position determines margin capture—edge hardware commoditizes while platform software concentrates value.
- IoT:Sensor-to-cloud connectivity infrastructure enables remote monitoring and over-the-air updates. China's MIIT-mandated industrial internet platforms are accelerating domestic gateway deployment.
- Machine Learning:Predictive models trained on operational data forecast equipment degradation and quality drift. Japanese automotive suppliers are subscribing to anomaly detection as standalone SaaS.
- AI:Generative and computer vision systems automate programming and inspection tasks. South Korean semiconductor fabs are piloting vision-guided robotic wafer handling.
- Automation Software:SCADA, MES, and digital twin platforms unify operational data for enterprise visibility. METI's Society 5.0 subsidies are accelerating Japanese smart factory software adoption.
Automation Software anchors current revenue. AI represents the steepest expansion trajectory as inference moves to the edge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong Province anchors automation procurement across the Asia-Pacific, with Shenzhen and Dongguan manufacturing clusters driving servo motor and robotic arm demand for consumer electronics assembly.
China
MIIT mandates for domestic servo motor production are forcing supply chain localization decisions among foreign vendors. GB standards for industrial robot safety require in-country testing facilities, compressing registration timelines for compliant manufacturers while erecting documentation barriers for imports. Yangtze River Delta automotive stamping plants specify digital twin-integrated lines for EV battery assembly.
Japan
METI-certified smart factory architectures subsidize IoT sensor integration across automotive supplier networks. JIS standards for motion control equipment lock in decade-long vendor relationships among precision component makers. Nagoya's Chubu region semiconductor backend facilities anchor demand for millisecond-response programmable logic controllers.
South Korea
Semiconductor fabrication facilities in Pyeongtaek and Hwaseong expand cleanroom robotics deployment for wafer handling operations. KCS certification requirements for industrial safety systems extend product launch cycles for cross-border equipment vendors. Busan-Ulsan petrochemical complexes specify IEC 61511-compliant safety instrumented systems for continuous flow operations.
Australia
Lithium hydroxide and rare-earth refining facilities in Western Australia's Pilbara region require explosion-proof automation systems with limited incumbent vendor presence. NEM-connected microgrids drive substation retrofit cycles for distribution automation equipment. Queensland nickel processing plants specify skid-mounted automation packages with hazardous area ratings.
Vietnam
Greenfield automotive and electronics assembly plants in Bac Ninh and Hai Phong lack legacy automation infrastructure, enabling direct deployment of collaborative robot platforms. Cross-border fulfillment hubs negotiate software renewals independently from capital equipment procurement. Northern industrial zones prioritize asset utilization metrics over absolute throughput for logistics automation.
Asia-Pacific Industrial Automation Market Competitive Landscape
Global majors compete with regional champions across control systems and robotics portfolios, producing a tiered structure where European conglomerates hold premium software positions while Asian specialists dominate precision motion hardware. Siemens and ABB exemplify the integrated platform archetype, bundling digital twin software with hardware sales. Japanese specialists occupy the component-deep archetype, focusing on servo motors and harmonic drives with narrow but defensible technical moats. Competitive moves center on acquiring in-country certification bodies to accelerate market access and unbundling after-sales service into standalone software subscriptions.
Within the integrated platform tier, ABB and Siemens represent the European conglomerate archetype, anchoring premium positioning through bundled hardware-software offerings. Yaskawa Electric Corporation exemplifies the Japanese component specialist archetype, occupying a defensible position in AC servo and motion controller production for automotive supply chains.
| Leading Market Players |
|---|
| Mitsubishi Electric Corporation |
| Rockwell Automation |
| ABB |
| Schneider Electric |
| OMRON Corporation |
| Siemens |
| Yaskawa Electric Corporation |
| Emerson Electric |
| FANUC Corporation |
| Others |
Pricing and Supply Chain Analysis
Japanese automotive component manufacturers anchor premium pricing through long-term service contracts bundled with precision motion hardware, while Chinese EV OEMs drive transactional spot purchasing for servo motors. This buyer-archetype concentration splits the market between value-based partnership models and cost-optimized procurement tiers.
Pricing Analysis
Neodymium and dysprosium price volatility passes through to permanent magnet motor producers, compressing margins for uncaptured supply chain exposure. Pricing stratifies across JIS-certified premium tiers, GB-compliant domestic alternatives, and unbranded economy imports from Southeast Asian assembly plants. Cost compression in mid-precision servo applications is intensifying because ferrite-based substitutes erode rare-earth dependency premiums. Chinese EV battery suppliers exhibit highest price sensitivity, while Japanese semiconductor backend facilities prioritize torque density over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Yangtze River Delta automotive clusters, while distributor networks serve fragmented Indonesian and Vietnamese greenfield projects. Precision harmonic drive gearheads draw from Japanese and German suppliers with limited second-source alternatives. Copper winding materials and rare-earth magnets rest on Chinese processing dominance, creating tariff exposure from export quota policies. Distribution runs through certified system integrators who bundle installation with hardware procurement across METI-subsidized Japanese smart factory deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific industrial automation has entered a late-cycle quality phase where buyers prioritize predictive maintenance integration over standalone equipment specs. South Korean semiconductor fabs now mandate edge-native AI inference as a baseline procurement requirement.
For Market Incumbents:Lock in decade-long vendor relationships with Japanese automotive suppliers through JIS-certified motion controller upgrades and captive harmonic drive production. Rare-earth magnet supply volatility threatens margin stability for non-integrated producers. Backward integration into ferrite-based motor architectures defends position against Chinese state-backed competitors with domestic magnet supply.
For New Entrants and Emerging Players:Enter via Australia's lithium hydroxide and rare-earth refining facilities, where explosion-proof automation demand outpaces incumbent vendor presence. Vietnam's Bac Ninh electronics assembly corridor offers the most penetrable greenfield collaborative robot deployment. Target unbundled software subscriptions as a standalone SaaS entry point, mirroring South Korean supplier network procurement patterns.
For Investors and Strategic Acquirers:European industrial conglomerates are the most active acquirer in this space, consolidating Chinese certification bodies to compress GB standard registration timelines. Five-to-ten year viability hinges on digital twin software platform ownership rather than discrete hardware production. Watch for MIIT mandates expanding beyond servo motors to harmonic drive gearheads as the inflection signal for forced localization acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Body Acquisition | European vendors acquire Chinese testing facilities to accelerate GB standard compliance for industrial robot safety. |
| Ferrite Motor Architecture Pivot | Mid-precision servo producers reduce rare-earth dependency as neodymium price volatility compresses margin stability. |
| Edge-Native AI Integration | South Korean semiconductor fabs mandate millisecond-latency defect detection replacing cloud-dependent vision systems. |
| Service Contract Unbundling | Japanese automotive suppliers subscribe to predictive analytics SaaS separately from motion controller hardware procurement. |
| Greenfield Collaborative Deployment | Vietnamese electronics assembly plants specify collaborative robot platforms without legacy PLC retrofit friction. |
Research Methodology
Direct dialogue with plant engineers at Japanese automotive component suppliers, procurement leads at Chinese EV OEMs, aftermarket service heads at South Korean semiconductor fabs, and maintenance directors at Australian lithium processing facilities grounded qualitative insights. Secondary validation drew from MIIT GB standard filings, METI Society 5.0 subsidy disclosures, KCS certification registries, and customs data on servo motor trade flows. Bottom-up equipment shipment tallies and top-down industrial capex forecasts were triangulated to anchor projections.
Segment-level outputs across the analysis window reflect modeled trajectories for control systems, robotics, sensors, and deployable units by application context and technology stack. The framework incorporated product type substitution elasticities, regulatory compliance cost burdens, and end-user capital intensity differentials. CAGRs were derived from regression against industrial production indices and automation penetration benchmarks.
Inputs from METI subsidy disbursement records and MIIT domestic production mandates were available through the study window; gaps in real-time rare-earth magnet inventory data introduce uncertainty bands around ferrite substitution timing assumptions. Forecasts reflect documented expectations for regulatory enforcement intensity and supply chain localization pressures. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Europe ICS Market
Industrial Automation
Europe Sortation Systems Market
Industrial Automation
Global Distribution Feeder Automation System Market
Industrial Automation
Global Smart Manufacturing Platform Market
Industrial Automation
Predictive Maintenance for Manufacturing Market
Industrial Automation
UV Curing System Market
Industrial Automation
Europe Factory Automation and Industrial Controls Market
Industrial Automation
Safety Programmable Controller Market
Industrial Automation
AI-driven Predictive Maintenance Market
Industrial Automation
France Factory Automation and Industrial Controls Market
Industrial Automation
Latin America Factory Automation and Industrial Controls Market
Industrial Automation
Europe Intralogistics Automation Market
Industrial Automation
Drilling Automation Market
Industrial Automation
Forklift-Mounted Computers Market
Industrial Automation
Industrial Fieldbus Solution Market
Industrial Automation
Hardware in the Loop Market