
 Plug in Power Meter Market | 2026-2036
Plug in Power Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Plug in Power Meter Market Outlook
Aftermarket service revenue for meter calibration and firmware upgrades is reshaping margin distribution across the value chain. Schneider Electric leverages its integrated energy management platform to sustain recurring service contracts. Siemens anchors European demand through its industrial automation channels. Fluke Corporation specializes in handheld diagnostic-grade meters for facility maintenance crews.
A plug-in power meter is an electrical measurement device that inserts between an outlet and load to quantify voltage, current, power factor, and cumulative energy consumption with typical accuracy classes of 0.5% to 1.0%. These instruments serve commercial and industrial users pursuing granular visibility into equipment-level consumption patterns. Smart meters lead product type segments due to embedded communication protocols enabling remote data retrieval, while analog meters retain share in cost-sensitive small business installations. Wi-Fi technology dominates connectivity deployments where existing network infrastructure eliminates gateway costs, though Zigbee competes in multi-node industrial submetering arrays where mesh resilience matters.
The U.S. Department of Energy enforces measurement accuracy standards under federal appliance regulations, while the European Union's Energy Efficiency Directive mandates submetering in commercial buildings above specified floor areas. The International Electrotechnical Commission publishes IEC 62053 performance classes that define accuracy tolerances for active energy measurement. Stakeholders must monitor evolving cybersecurity certification requirements for networked metering hardware as grid-edge connectivity expands.
Market Dynamics
Factory energy management mandates across Germany's industrial corridor are compressing replacement cycles and forcing manufacturers to prioritize embedded communication protocols over standalone analog units. This regulatory pressure is restructuring procurement patterns toward integrated platform vendors.
Growth Catalysts
- IEC 62053 Performance Classes:The International Electrotechnical Commission's accuracy tolerance standards are mandating 0.5% precision thresholds in commercial submetering installations, disqualifying legacy analog meters from new bids.
- Wi-Fi Infrastructure Saturation:Existing enterprise wireless networks eliminate gateway hardware costs for facility managers, accelerating deployment of networked meters against hardwired alternatives.
- German Factory Mandates:Energy management regulations in Baden-Württemberg and Bavaria require real-time equipment-level monitoring, creating replacement demand across automotive supplier parks.
Market Restraints
- Semiconductor Input Volatility:Precision ADC chip shortages from East Asian foundries are extending lead times for diagnostic-grade meters beyond 26 weeks.
- Zigbee Mesh Complexity:Industrial facilities lacking dedicated IT-OT integration expertise face deployment failures in multi-node submetering arrays exceeding 50 endpoints.
- Cybersecurity Certification Friction:Evolving grid-edge security requirements from national regulators are delaying product launches by 8-14 months for networked hardware vendors.
Strategic Opportunities
- India CEA Submetering Push:The Central Electricity Authority's commercial building energy audit rules create first-mover advantage for smart meter suppliers in Mumbai and Bangalore IT parks.
- Edge Analytics Convergence:On-device machine learning inference combined with power measurement enables predictive maintenance alerts without cloud dependency.
- Calibration Service Contracts:Firmware upgrade subscriptions and annual accuracy verification are capturing recurring revenue from installed bases previously treated as one-time sales.
Industry Challenges
- IEC 62053-21 Certification Timelines:Third-party testing laboratory capacity constraints in Europe and North America are bottlenecking product launches for active energy accuracy Class 1 and Class 0.5 meters.
- Legacy SCADA Integration:Brownfield industrial sites running Modbus RTU or proprietary serial protocols require protocol translation gateways that increase per-node deployment cost by 40-60%.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plug in Power Meter Market |
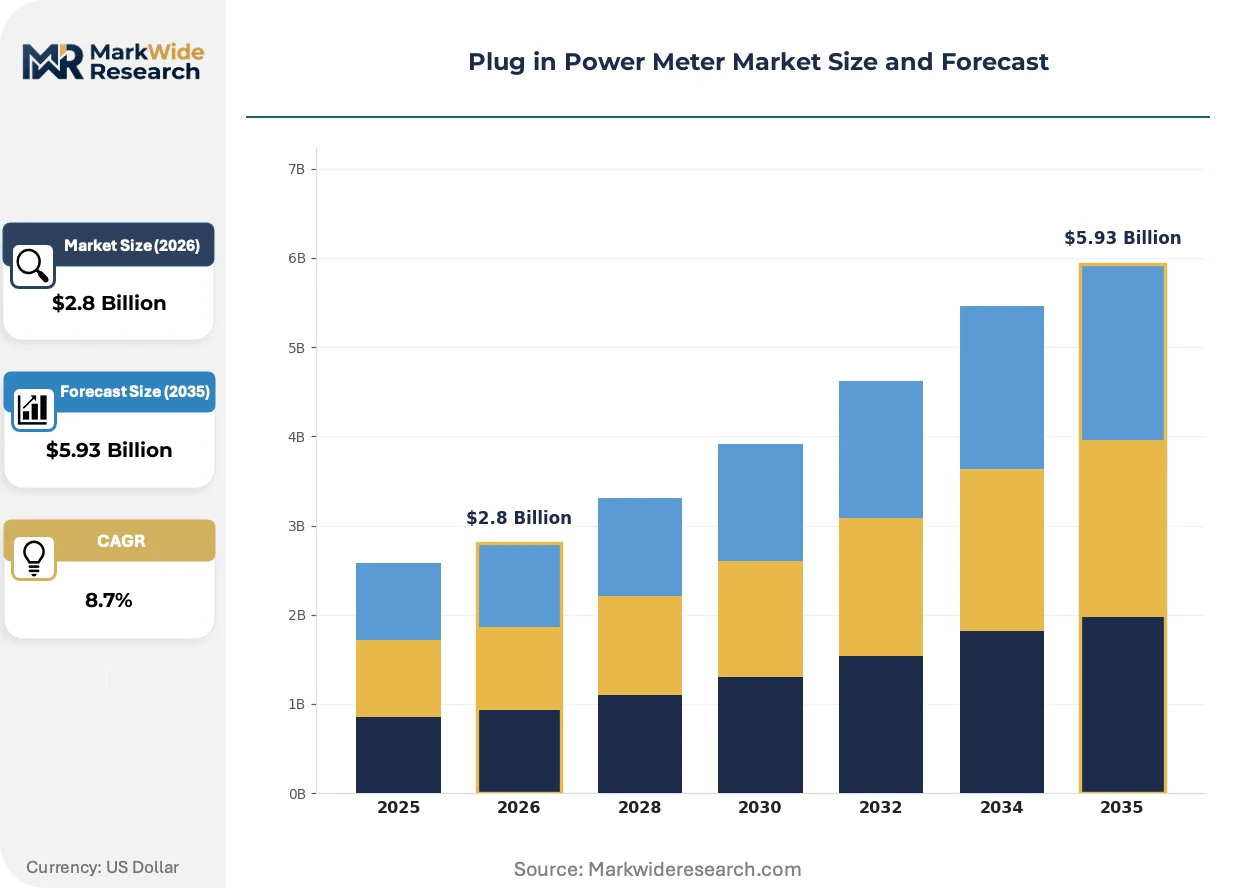
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Meters, Analog Meters, Digital Meters, Hybrid Meters Technology: Wi-Fi, Zigbee, Bluetooth, RF End User: Residential Users, Small Businesses, Industrial Facilities, Utility Companies Application: Energy Monitoring, Load Analysis, Demand Response, HVAC Systems |
| Companies Covered | Schneider Electric, Siemens, General Electric, Eaton, ABB, Honeywell International, Fluke Corporation, Yokogawa Electric Corporation, Landis+Gyr, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plug in Power Meter Market Strategic Shifts
Software-defined measurement architectures are displacing fixed-function hardware designs across commercial and industrial deployments. This virtualization trend is compressing hardware refresh cycles while expanding addressable use cases.
Edge computing platforms with containerized measurement applications are virtualizing power quality analysis functions previously executed by dedicated rack-mounted instruments. Facility managers in German automotive plants are deploying these systems at 3x the rate of traditional hardware. This virtualization is collapsing the distinction between permanent submeters and portable diagnostic tools.
The European Union's Energy Efficiency Directive revision mandates submetering in commercial buildings exceeding specific floor area thresholds, with member states transposing rules through 2025. Industrial landlords in France and Italy face penalties for non-compliance, accelerating tenant improvement allowances for meter installation. Meter vendors with pre-certified EU regulatory packages are capturing specification authority from electrical contractors.
Maintenance departments are unbundling calibration and firmware services from original equipment purchases, treating these as separate procurement categories with distinct vendor evaluation criteria. German industrial facility managers now source meter hardware from automation specialists while contracting calibration through third-party metrology laboratories. This bifurcation is most pronounced in pharmaceutical manufacturing clusters around Frankfurt and Basel.
Plug in Power Meter Market Segmentation
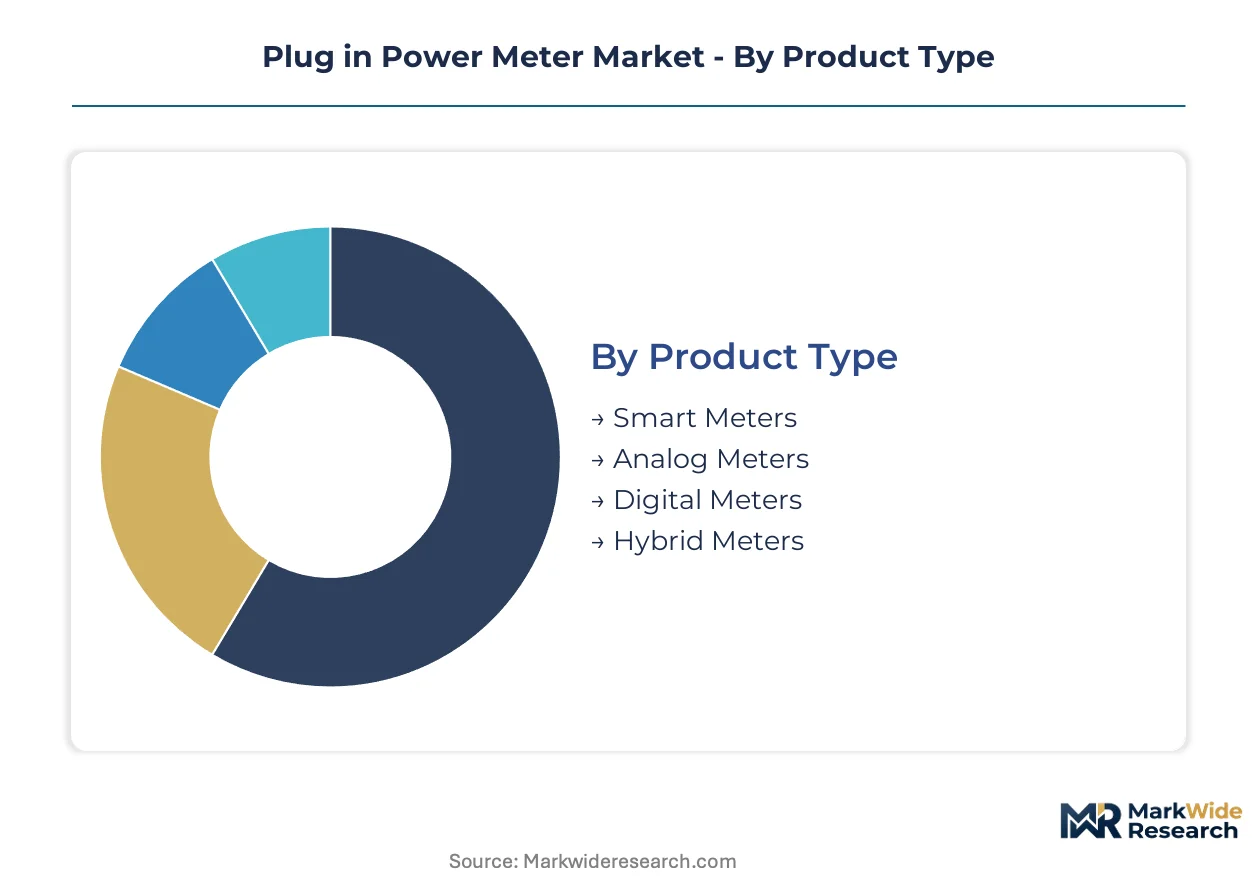
Segmentation in the plug-in power meter market reveals divergent technology adoption curves across connectivity protocols and user sophistication levels. Procurement patterns split between enterprises demanding embedded analytics and cost-conscious operators prioritizing basic measurement functions.
Product Type:
Mature analog architectures coexist with emerging software-defined measurement platforms across installation bases.
- Smart Meters:These units integrate embedded communication protocols enabling remote data retrieval and cloud connectivity. Demand concentrates in German automotive supplier parks where factory energy management mandates require real-time equipment-level monitoring with IEC 62053 Class 0.5 accuracy.
- Analog Meters:Electromechanical designs with moving-coil displays provide basic voltage, current, and power readings without digital processing. Small business installations in cost-sensitive segments retain these units for simple load verification tasks where network infrastructure is absent.
- Digital Meters:Microprocessor-based instruments with LCD displays deliver precise RMS measurements and local data logging.
- Hybrid Meters:Dual-mode devices combine electromechanical reliability with digital communication modules for transitional upgrade paths.
Smart meters retain volume leadership; hybrid meters hold the steepest expansion curve as brownfield sites pursue incremental modernization.
Technology:
Cost tier stratification separates enterprise-grade mesh deployments from consumer-oriented point-to-point solutions.
- Wi-Fi:Leverages existing enterprise wireless infrastructure to eliminate gateway hardware costs. Facility managers in commercial buildings across France and Italy deploy these units where IEEE 802.11 coverage already supports building automation systems.
- Zigbee:Mesh networking protocol provides resilience in multi-node industrial submetering arrays exceeding fifty endpoints. German pharmaceutical manufacturing clusters around Frankfurt and Basel favor this technology for its self-healing topology in critical production environments.
- Bluetooth:Short-range connectivity serves portable diagnostic applications and mobile commissioning tools.
- RF:Proprietary radio frequency links address isolated outdoor installations and legacy AMR system integrations.
Wi-Fi dominates commercial retrofit volume; Zigbee claims the most rapid climb in greenfield industrial specifications.
End User:
Application maturity varies sharply between regulated industrial mandates and discretionary residential purchases.
- Industrial Facilities:These operators deploy diagnostic-grade meters with 0.5% accuracy for equipment-level energy accounting. Germany's industrial corridor in Baden-Württemberg and Bavaria drives replacement cycles through mandatory submetering regulations.
- Utility Companies:Grid-edge measurement programs require networked meters for demand response aggregation and distribution planning. India's Central Electricity Authority commercial building audit rules create specification opportunities in Mumbai and Bangalore IT parks.
- Residential Users:Homeowners seek plug-load visibility for appliance efficiency verification.
- Small Businesses:Retail and restaurant operators prioritize low-cost verification of equipment energy draw.
Industrial facilities anchor revenue concentration; utility companies are gaining share fastest through regulatory procurement programs.
Application:
Customer type differentiation separates predictive maintenance adopters from compliance-driven monitoring installations.
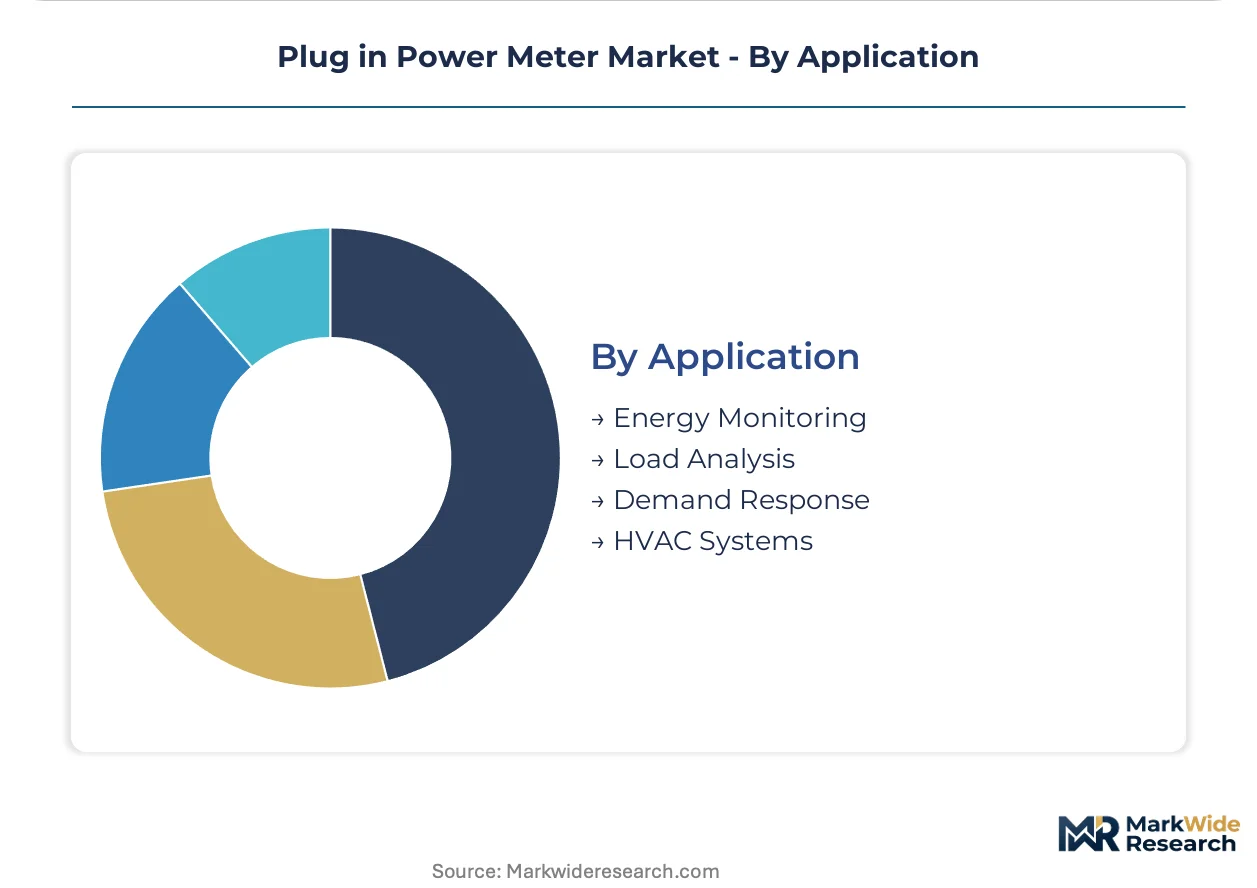
- Energy Monitoring:Continuous consumption tracking with cumulative kWh logging for billing allocation and carbon accounting. European Union Energy Efficiency Directive mandates in France and Italy accelerate tenant improvement allowances for this application category.
- Load Analysis:Granular power quality assessment including harmonic distortion and power factor measurement. German automotive plants deploy edge computing platforms with containerized analysis functions at three times the rate of traditional hardware approaches.
- Demand Response:Automated load curtailment signaling for grid stability programs.
- HVAC Systems:Dedicated metering for heating, ventilation, and air conditioning efficiency verification.
Energy monitoring sustains the broadest installed base; load analysis is expanding most quickly through edge analytics convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision ADC chip foundries cluster in East Asian manufacturing zones, creating supply dependencies that extend lead times for diagnostic-grade meters beyond twenty-six weeks. This concentration shapes procurement timelines across downstream assembly operations.
Germany
Factory energy management mandates in Baden-Württemberg and Bavaria compress replacement cycles for industrial submetering hardware. The EU Energy Efficiency Directive transposition requires real-time equipment-level monitoring in commercial buildings above specified floor thresholds. Automotive supplier parks around Stuttgart anchor specification authority for IEC 62053 Class 0.5 accuracy meters.
United States
Enterprise wireless infrastructure saturation eliminates gateway hardware costs for facility managers deploying networked meters. The Department of Energy enforces measurement accuracy standards under federal appliance regulations that disqualify legacy analog units. Commercial retrofit volume concentrates in California and Texas data center corridors where IEEE 802.11 coverage supports building automation integration.
India
The Central Electricity Authority's commercial building energy audit rules create first-mover positioning for smart meter suppliers in Mumbai and Bangalore IT parks. CEA submetering mandates require granular consumption tracking for billing allocation in facilities above specified load thresholds. Pharmaceutical manufacturing clusters around Hyderabad and Pune drive demand for predictive maintenance applications.
France
Industrial landlords face penalties under EU Energy Efficiency Directive transposition rules for non-compliant commercial buildings. Tenant improvement allowances accelerate meter installation in Île-de-France logistics facilities and Lyon manufacturing zones. Meter vendors with pre-certified EU regulatory packages capture specification authority from electrical contractors in these compliance-driven procurement cycles.
China
Domestic demand for edge analytics convergence accelerates deployment of containerized measurement applications in Yangtze River Delta manufacturing hubs. GB standards for energy measurement accuracy create certification barriers for imported hardware. Shenzhen and Shanghai industrial parks deploy software-defined architectures at three times the rate of traditional fixed-function designs.
Plug in Power Meter Market Competitive Environment
Integrated platform vendors and specialized diagnostic manufacturers split the market between recurring service contracts and one-time hardware sales. The vendor base concentrates around automation conglomerates with captive distribution channels and precision instrumentation specialists with metrology laboratory relationships. Two strategic archetypes dominate: energy management platform operators leveraging installed base lock-in, and handheld diagnostic-grade meter specialists serving facility maintenance crews. Competitive moves center on firmware upgrade subscription bundling and third-party metrology laboratory partnership networks for calibration service capture.
Within the integrated platform tier, Schneider Electric and Siemens exemplify archetype positioning through energy management software ecosystems and industrial automation channel density. Fluke Corporation occupies a distinct specialist position representing handheld diagnostic-grade instrumentation for facility maintenance applications. These three anchors illustrate the bifurcation between enterprise-scale platform bundling and precision field-service instrumentation.
| Leading Market Players |
|---|
| Schneider Electric |
| Siemens |
| General Electric |
| Eaton |
| ABB |
| Honeywell International |
| Fluke Corporation |
| Yokogawa Electric Corporation |
| Landis+Gyr |
| Others |
Value Chain & Pricing Dynamics
East Asian precision ADC foundries in Taiwan and South Korea anchor component supply for diagnostic-grade meters, translating semiconductor capacity constraints into extended procurement timelines and tiered pricing power for manufacturers with captive allocation agreements.
Pricing Analysis
After-sales calibration contracts and firmware upgrade subscriptions now drive lifetime value capture. Three-tier pricing structure across premium diagnostic, standard networked, and economy analog levels separates IEC 62053 Class 0.5 certified units from Class 1 and unverified alternatives. Cost compression in the economy tier intensifies as small business buyers prioritize basic measurement over connectivity. Industrial facility managers show lowest price sensitivity, accepting premium positioning for predictive maintenance integration.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for meter assembly operations. Precision ADC chip fabrication concentrates in Taiwan, South Korea, and Japan, while plastic enclosures and passive components draw from Chinese manufacturing zones. Single-source vulnerability for 0.1% tolerance voltage reference ICs threatens production continuity. Distribution runs through industrial automation distributors and direct OEM channels with regional service depot networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of IT-OT integration expertise for multi-node Zigbee deployments is concentrating procurement authority with platform vendors who bundle implementation services, reshaping competitive moats around capability access rather than hardware specifications alone.
For Market Incumbents: Entrench platform lock-in by embedding edge analytics containers that virtualize power quality functions previously requiring separate instruments. Prioritize backward integration into precision ADC sourcing through foundry partnership agreements to defend against semiconductor allocation volatility. Channel control through certified installer networks protects specification authority against emerging software-defined competitors. For New Entrants and Emerging Players: Build out calibration-as-a-service offerings targeting pharmaceutical manufacturing clusters where third-party metrology laboratory relationships are bifurcating from hardware procurement. India's CEA submetering mandates in Mumbai and Bangalore IT parks represent the most penetrable geography for first-mover positioning. Direct utility partnership models bypass established automation channel gatekeepers. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates with captive meter divisions lacking standalone software platform capabilities. Long-term viability hinges on recurring revenue ratios exceeding transactional hardware dependency. Monitor IEC 62053-21 certification backlog durations as inflection indicator for regulatory-driven consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Analytics Platform Integration | Virtualizes power quality functions for German automotive supplier parks seeking predictive maintenance. |
| Calibration Service Contract Expansion | Captures recurring revenue from Frankfurt and Basel pharmaceutical manufacturing installed bases. |
| IEC 62053-21 Certification Investment | Accelerates product launch timelines amid third-party laboratory capacity constraints in Europe. |
| Zigbee Mesh Deployment Partnership | Addresses IT-OT integration gaps blocking multi-node industrial submetering array implementations. |
| India CEA Regulatory Package Development | Secures specification authority in Mumbai and Bangalore commercial building audit compliance cycles. |
Study Parameters
Operator-level perspectives from facility maintenance directors, industrial automation procurement leads, third-party metrology laboratory managers, and energy management platform engineers anchored the qualitative base. Primary interview findings triangulated against secondary sources including IEC standard publication records, EU Energy Efficiency Directive transposition documents, CEA submetering circulars, and industrial automation distributor sales data. Bottom-up unit economics modeling converged with top-down market sizing across product type, connectivity protocol, and end-user vertical dimensions.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning smart versus analog architectures, Wi-Fi versus Zigbee connectivity, and industrial facility versus utility company procurement patterns. CAGRs derived from equipment replacement cycle analysis, regulatory mandate implementation timelines, and technology adoption S-curve positioning. Forecast inputs incorporated precision ADC lead time trajectories and certification laboratory capacity utilization rates.
Practitioners should monitor semiconductor foundry allocation shifts, cybersecurity certification requirement evolutions, and EU member state directive transposition delays for early signals of forecast deviation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Meters
Power Quality Meter Market
Smart Meters
Asia Pacific Smart Meter Market
Smart Meters
Industrial Power Monitoring System Market
Smart Meters
Electricity Meters (Smart Meters) Market
Smart Meters
United States Smart Meter Market
Smart Meters
Smart Gas Metering Market
Smart Meters
Smart Meters Market
Smart Meters
Middle East and Africa Smart Meters Market
Smart Meters
Commercial Non IC Card Gas Smart Meter Sales Market
Smart Meters
Advanced Metering Infrastructure Market
Smart Meters
Smart Gas Meter Market
Smart Meters
South and Central America Smart Metering Market
Smart Meters
Global Smart Energy Meters Market
Smart Meters
Smart Meter Battery Market
Smart Meters
Global Smart Electricity Meter Market
Smart Meters
Europe Water Meter Market