
 Battery Tray Market | 2026-2036
Battery Tray Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Tray Market Insights
OEM direct sourcing is tilting away from multi-tier distributor networks toward contracted mill relationships. Novelis Inc. leverages captive aluminum rolling capacity to secure long-term supply agreements with battery pack integrators. Nemak S.A.B. de C.V. anchors its position through high-pressure die-casting expertise tailored to large-format tray geometries. Gestamp Automoción S.A. competes on modular platform architectures that reduce tooling changeover across vehicle programs.
A battery tray is a structural enclosure that houses, protects, and thermally manages electrochemical cells within a battery pack, typically fabricated from 5000 or 6000 series aluminum alloys with wall thicknesses between 1.5 mm and 3.0 mm to achieve crashworthiness and weight targets. The component serves as both a load-bearing chassis element and a sealed barrier against intrusion, coolant leakage, and electromagnetic interference in electric vehicle and stationary storage applications. Metal material trays, particularly aluminum extrusions and stampings, command the dominant share of value given their strength-to-weight ratio and recyclability credentials, while composite trays represent the fastest-growing niche as fiber-reinforced thermoplastics advance toward automotive qualification cycles. Customized trays capture premium margin pools where pack-specific integration demands bespoke thermal interface designs, whereas standard trays face commoditization pressure from Chinese producers with scale advantages.
FDA guidelines for medical device battery enclosures and EPA lifecycle assessment protocols for automotive materials create dual compliance burdens for cross-industry suppliers, while China's MIIT enforces GB/T standards that mandate tray-level abuse testing for new energy vehicle certification. The EU's REACH restrictions on hexavalent chromium surface treatments are forcing conversion to trivalent passivation or plasma electrolytic oxidation across European-bound production. Stakeholders must monitor how battery passport traceability requirements under the EU Green Deal reshape material sourcing documentation and supplier qualification timelines.
Market Dynamics
Electric vehicle OEMs are consolidating supplier tiers around aluminum mills with captive rolling capacity, compressing procurement cycles from multi-year qualification to 18-month direct contracting windows.
Growth Catalysts
- GB/T 31467.3 abuse testing mandates:China's MIIT protocols require tray-level thermal runaway containment, forcing design upgrades that favor structurally integrated aluminum extrusions over bolted assemblies.
- Cell-to-pack architecture migration:Large-format prismatic and blade cells eliminate modular subframes, expanding single-piece tray footprints and increasing aluminum tonnage per vehicle.
- Germany's Zwickau-Dresden manufacturing corridor:Concentrated EV platform production creates localized demand density that justifies dedicated aluminum casting investments by Tier 1 suppliers.
Market Restraints
- Primary aluminum price volatility:LME aluminum contract swings above 15% annually compress extrusion margins and complicate long-term OEM pricing agreements.
- Chinese producer scale concentration:State-backed aluminum fabricators in Shandong and Henan provinces control 40% of global extrusion capacity, creating sourcing risk for European and North American pack integrators.
- Composite material substitution ceiling:Fiber-reinforced thermoplastic trays face crashworthiness validation gaps at tray lengths exceeding 1.8 meters, limiting penetration in full-size SUV and commercial vehicle platforms.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cell manufacturing:Subsidized gigafactory construction in Gujarat and Tamil Nadu creates first-mover tray supply contracts for aluminum processors establishing local extrusion capacity.
- Second-life stationary storage retrofit:Decommissioned EV trays require structural recertification for grid-scale battery enclosures, opening refurbishment service revenue streams.
- EU battery passport traceability requirements:Material provenance documentation mandates under the Green Deal favor suppliers with integrated recycling and primary metal sourcing transparency.
Industry Challenges
- High-pressure die-casting tooling lead times:28-week mold fabrication cycles for large-format tray geometries mismatch 12-week OEM program acceleration demands.
- Multi-jurisdiction surface treatment compliance:REACH hexavalent chromium restrictions, China's GB/T corrosion standards, and EPA lifecycle protocols require parallel process qualification tracks.
- Thermal interface material integration complexity:Gap filler dispensing and cure-cycle compatibility with aluminum surface preparation adds 15-20 process steps to tray assembly lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Tray Market |
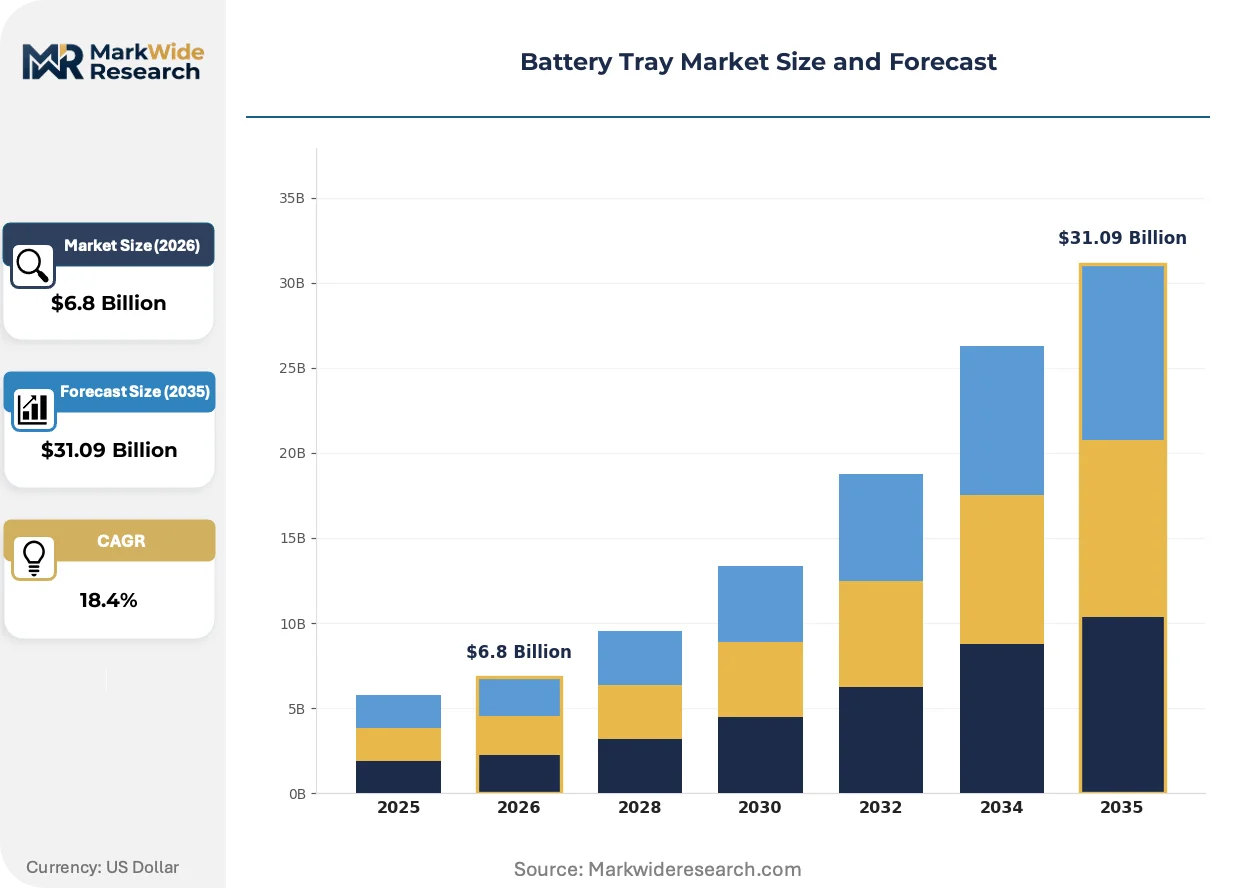
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.09 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Trays, Customized Trays, Modular Trays, Stackable Trays Material: Plastic, Metal, Composite, Rubber Application: Automotive, Renewable Energy, Consumer Electronics, Industrial Equipment End User: Manufacturers, Distributors, Retailers, End Consumers |
| Companies Covered | Novelis Inc., Nemak S.A.B. de C.V., Gestamp Automoción S.A., Magna International Inc., Guangdong Hoshion Aluminium Co., Ltd., Benteler International, Minth Group Co., Ltd., SGL Carbon, Constellium, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Tray Market Trends and Innovations
Digital twin workflows are compressing tray development cycles from 36 months to 18 months while enabling real-time structural optimization against crash and thermal loads.
Generative design software coupled with topology optimization algorithms is virtualizing traditional stiffener rib patterns, replacing uniform wall thicknesses with variable-density lattice structures that reduce aluminum mass by 12-18% without sacrificing torsional rigidity. BMW and Hyundai pack engineering teams have deployed these tools for 2026 platform trays. The technology is virtualizing legacy stamping-die economics by collapsing multiple forming operations into single continuous extrusion profiles with machined feature integration.
REACH Annex XVII restrictions on hexavalent chromium conversion coatings are forcing European-bound production lines to convert plasma electrolytic oxidation or trivalent passivation processes by 2026. The industrial consequence is a 8-12% surface treatment cost increase and 6-month supplier requalification timelines. High-volume aluminum extruders in Spain and Italy are most affected, with several facilities suspending European automotive contracts rather than absorbing capex for compliant coating lines.
Direct mill contracting is displacing distributor-mediated aluminum sourcing for battery tray programs above 50,000 units annually. Novelis and Constellium now maintain dedicated technical sales teams for pack integrators, bypassing traditional metal service centers. This channel compression is most visible in Germany's automotive manufacturing corridor, where OEMs including Volkswagen and Mercedes-Benz have eliminated two-tier procurement structures for structural aluminum components.
Battery Tray Market Segmentation
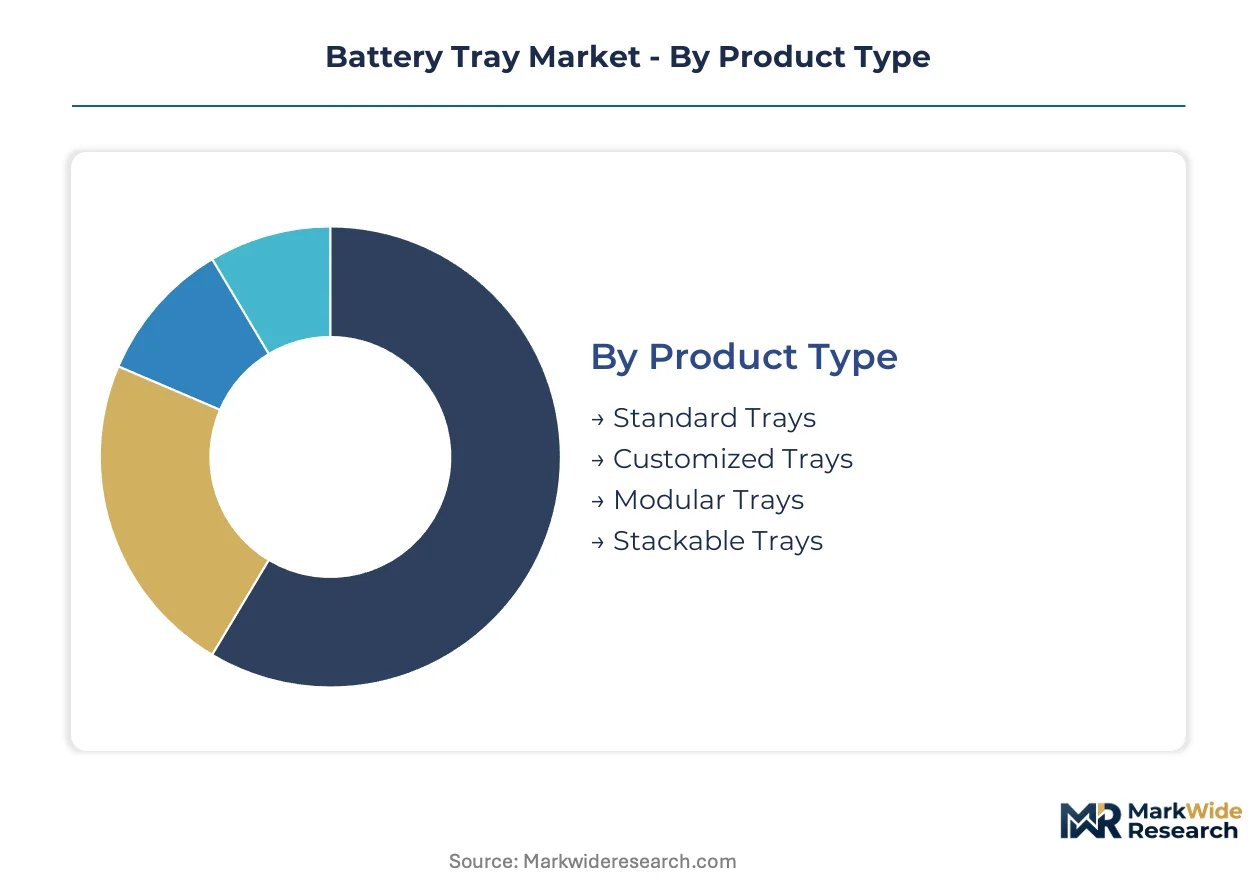
Battery tray procurement patterns diverge sharply across product architectures and material specifications. OEMs structure supplier contracts around these divisions, with each segment demanding distinct qualification timelines and technical service commitments.
Product Type:
After-sales service intensity escalates dramatically from standardized commodity trays to engineered custom solutions, with field engineering support becoming a contract retention mechanism.
- Standard Trays:Mass-produced aluminum stampings with fixed dimensional tolerances serve high-volume EV platforms where interchangeability reduces spare parts complexity. Procurement concentrates in China's Shandong province extrusion clusters, where state-backed fabricators leverage scale to compress unit economics below European cost floors.
- Customized Trays:Bespoke thermal interface geometries and pack-specific mounting patterns require dedicated tooling investments and on-site engineering liaison. Germany's Zwickau-Dresden corridor anchors demand as Volkswagen and Mercedes-Benz specify tray-integrated cooling circuits that demand supplier resident engineers.
- Modular Trays:Sub-assemblies enable platform flexibility across multiple vehicle programs.
- Stackable Trays:Designed for stationary storage density optimization in containerized deployments.
Standard trays hold the largest share; momentum sits with customized trays.
Material:
Material selection governs crashworthiness validation burden and recycling credential transparency under emerging EU battery passport requirements.
- Metal:5000 and 6000 series aluminum alloys deliver the strength-to-weight ratio mandatory for automotive crash structures, with wall thicknesses between 1.5 mm and 3.0 mm. Novelis and Constellium capture premium positioning through captive rolling capacity and closed-loop recycling documentation that satisfies Green Deal traceability mandates.
- Composite:Fiber-reinforced thermoplastics are climbing the fastest as SABIC and Lanxess advance automotive qualification cycles, though crashworthiness gaps persist at tray lengths exceeding 1.8 meters for full-size SUV platforms.
- Plastic:Polypropylene and ABS variants dominate consumer electronics and low-voltage auxiliary applications.
- Rubber:Vibration isolation and sealing gaskets in hybrid material assemblies.
Metal dominates value capture; composites are expanding most quickly.
Application:
Application context determines thermal management intensity and regulatory exposure, with automotive facing the most severe abuse-testing mandates.
- Automotive:Cell-to-pack architectures eliminate modular subframes, expanding single-piece tray footprints and aluminum tonnage per vehicle. China's MIIT enforces GB/T 31467.3 tray-level thermal runaway containment, forcing structural integration of aluminum extrusions over bolted assemblies.
- Renewable Energy:Grid-scale battery enclosures demand corrosion resistance for decades-long outdoor deployment.
- Consumer Electronics:Miniaturization drives thin-gauge metal stampings and precision plastic molding.
- Industrial Equipment:Forklift and material handling applications prioritize impact resistance over weight optimization.
Automotive commands the steepest expansion trajectory; stationary storage offers refurbishment service potential.
End User:
End-user type structures pricing power and inventory risk allocation across the value chain.
- Manufacturers:Tier 1 pack integrators and EV OEMs negotiate direct mill contracts, compressing procurement cycles from multi-year qualification to 18-month windows. High-pressure die-casting tooling lead times of 28 weeks still mismatch 12-week program acceleration demands.
- Distributors:Metal service centers face channel compression as Novelis and Constellium deploy dedicated technical sales teams.
- Retailers:Aftermarket replacement trays for legacy vehicle fleets.
- End Consumers:DIY and small-scale stationary storage builders.
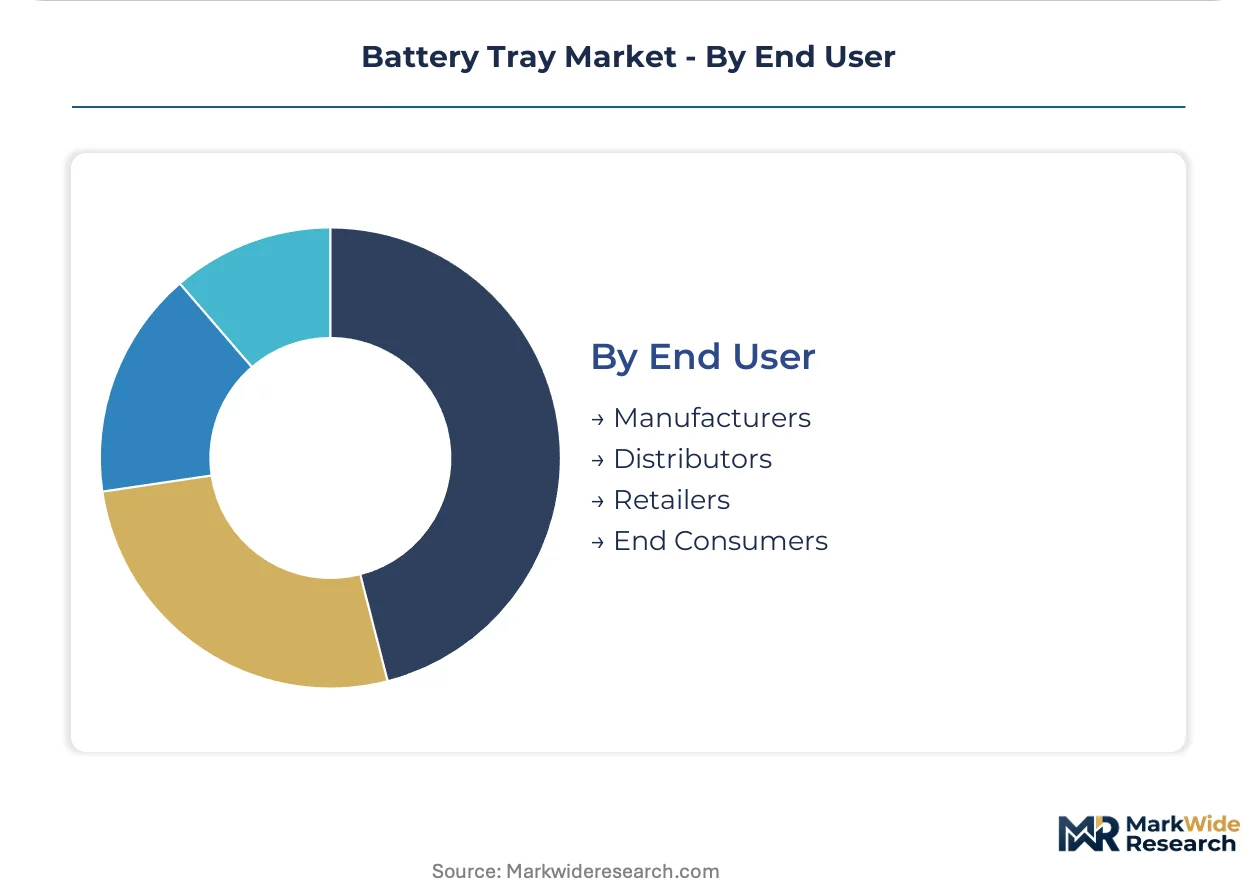
Direct manufacturer procurement holds the largest share; distributor mediation is contracting fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT subsidy restructuring and India's PLI scheme for advanced chemistry cells are redirecting aluminum extrusion investments toward battery tray fabrication capacity. Germany's Zwickau-Dresden corridor anchors European demand density, while the United States IRA domestic content bonuses reshape North American sourcing patterns.
China
Shandong and Henan province extrusion clusters control 40% of global aluminum fabrication capacity for battery enclosures. MIIT enforces GB/T 31467.3 tray-level abuse testing mandates that structurally integrate aluminum extrusions over bolted assemblies. State-backed fabricators in Zhengzhou and Jinan leverage scale advantages to compress unit economics below European cost floors.
Germany
Volkswagen and Mercedes-Benz cell-to-pack architectures expand single-piece tray footprints and aluminum tonnage per vehicle. ECHA REACH Annex XVII restrictions on hexavalent chromium force conversion to plasma electrolytic oxidation by 2026. The Zwickau-Dresden manufacturing corridor concentrates EV platform production that justifies dedicated aluminum casting investments by Tier 1 suppliers.
United States
IRA domestic content bonuses accelerate OEM direct contracting with aluminum mills possessing captive rolling capacity. EPA lifecycle assessment protocols for automotive materials create compliance documentation burdens for cross-industry suppliers. Michigan and Ohio automotive manufacturing clusters anchor demand for structural aluminum components serving Detroit Three EV programs.
India
PLI scheme subsidies for advanced chemistry cell manufacturing in Gujarat and Tamil Nadu create first-mover tray supply contracts for aluminum processors. BIS standards for new energy vehicle safety are tightening structural requirements for battery enclosures. The Gujarat International Finance Tec-City and Sriperumbudur industrial corridors attract extrusion capacity investments from domestic and multinational fabricators.
Japan
METI carbon neutrality roadmaps prioritize closed-loop aluminum recycling documentation for battery passport compliance. JIS standards govern crashworthiness validation for large-format tray geometries in premium EV platforms. The Nagoya-Toyota industrial corridor maintains specialized high-pressure die-casting expertise for structurally integrated battery enclosures.
Battery Tray Market Competitive Landscape
On the supply side, the industry is consolidating around aluminum mills with captive rolling capacity and Tier 1 automotive suppliers with high-pressure die-casting expertise. The vendor base stratifies into three archetypes: integrated aluminum producers controlling upstream smelting and rolling, automotive Tier 1 suppliers leveraging vehicle platform relationships, and regional extrusion specialists serving aftermarket and industrial applications. Dominant competitive moves include direct mill contracting that bypasses traditional metal service centers, and strategic partnerships between pack integrators and aluminum processors for co-developed thermal interface designs.
Among North American integrated aluminum producers, Novelis Inc. and Constellium exemplify the captive capacity archetype that secures long-term OEM supply agreements through closed-loop recycling documentation. Mexican automotive Tier 1 supplier Nemak S.A.B. de C.V. occupies a position within the high-pressure die-casting specialization tier, serving large-format tray geometries for European and North American EV platforms. These three companies represent distinct competitive positioning vectors—upstream metal control, automotive systems integration, and geographic proximity to major manufacturing corridors—that define the current market structure.
| Leading Market Players |
|---|
| Novelis Inc. |
| Nemak S.A.B. de C.V. |
| Gestamp Automoción S.A. |
| Magna International Inc. |
| Guangdong Hoshion Aluminium Co., Ltd. |
| Benteler International |
| Minth Group Co., Ltd. |
| SGL Carbon |
| Constellium |
| Others |
Pricing and Supply Chain Analysis
The Shanghai-Rotterdam maritime corridor's container rate volatility cascades through aluminum ingot landed costs, amplifying price spreads between Chinese state-backed extruders and European rolling mills while forcing OEM procurement teams into longer-term contract structures that trade flexibility for cost predictability.
Pricing Analysis
Certification level creates the primary spread across battery tray procurement, with GB/T 31467.3-validated suppliers commanding substantial premiums over non-certified alternatives. Contract-based long-term offtake agreements dominate high-volume automotive programs, while spot-market transactions persist for aftermarket and industrial applications. Price differentiation hinges on thermal runaway containment validation and closed-loop recycling documentation under EU battery passport requirements. Cost compression in standard aluminum stampings is intensifying because Chinese producers with captive smelting capacity are exporting at marginal production economics. Tier 1 automotive OEMs exhibit lowest price sensitivity, prioritizing qualification speed and technical integration support over unit cost.
Supply Chain Analysis
Extended payment terms from European OEMs now stretch to 120 days, forcing Tier 1 suppliers into supply-chain finance facilities that erode margins before production begins. Primary aluminum smelting concentrates in China, Russia, and Canada, while precision extrusion and high-pressure die-casting capacity clusters in Germany, Mexico, and Japan. The supply chain draws from bauxite refining, primary aluminum ingot, and 6000-series alloying elements including magnesium and silicon. Single-source vulnerability around Chinese extrusion capacity creates exposure for European pack integrators. Distribution runs through direct mill contracting that eliminates traditional metal service centers for programs above fifty thousand units annually.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery tray demand sits at early-cycle expansion as cell-to-pack architectures proliferate across EV platforms, with aluminum tonnage per vehicle doubling as modular subframes disappear from pack designs.
For Market Incumbents: Harden qualification pipelines against composite material substitution by accelerating plasma electrolytic oxidation capacity investments ahead of REACH Annex XVII enforcement. Lock in backward integration into captive aluminum rolling through long-term bauxite supply agreements that insulate against LME volatility. Defensive positioning requires resident engineering deployments at Volkswagen and Mercedes-Benz platform teams to entrench custom tray specifications. For New Entrants and Emerging Players: Build out regional extrusion capacity in Gujarat and Tamil Nadu to capture PLI-linked gigafactory demand before incumbent aluminum mills establish local presence. Stationary storage refurbishment services for decommissioned EV trays offer penetrable white-space with minimal qualification burden. Go-to-market execution should emphasize BIS certification acquisition and technical sales teams co-located with emerging Indian cell manufacturers. For Investors and Strategic Acquirers: EU battery passport traceability requirements reshape the acquisition landscape by privileging targets with integrated recycling documentation and primary metal sourcing transparency. Five-to-ten-year viability favors processors with captive smelting or rolling capacity rather than pure-play fabricators exposed to input cost volatility. Monitor GB/T standard revision timelines as inflection indicators for Chinese export competitiveness and European qualification cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Direct Mill Contracting | Novelis and Constellium technical sales teams bypass metal service centers for high-volume programs. |
| Plasma Electrolytic Oxidation Conversion | REACH Annex XVII compliance investments separate qualified European suppliers from suspended competitors. |
| Resident Engineering Deployment | Supplier personnel embedded at Volkswagen and Mercedes-Benz platform teams secure custom tray specifications. |
| Closed-Loop Recycling Documentation | Green Deal battery passport mandates favor processors with integrated primary metal sourcing transparency. |
| Generative Design Adoption | BMW and Hyundai pack engineering teams deploy topology optimization to reduce aluminum mass by twelve to eighteen percent. |
Research Methodology
Desk research of customs trade databases, aluminum industry association reports, and vehicle production registries preceded structured interviews with OEM platform engineers, Tier 1 supplier procurement directors, aluminum mill technical sales managers, and MIIT certification auditors. Primary fieldwork combined telephone and video interviews with secondary validation against SEC filings, ECHA regulatory notices, and MIIT new energy vehicle approval announcements. Bottom-up volume estimates from pack-level aluminum content assumptions triangulated against top-down market sizing from extrusion capacity utilization data.
Forecast assumptions held fixed the current regulatory trajectory for GB/T, REACH, and IRA domestic content requirements while varying EV penetration rates and cell-to-pack adoption curves across the projection horizon. Segmentation modeling incorporated product architecture, material specification, application intensity, and end-user procurement structure. CAGRs derived from aluminum tonnage-per-vehicle coefficients applied to regional vehicle production forecasts, with cross-checks against extruder capacity expansion announcements and tooling investment disclosures.
Practitioners should monitor MIIT subsidy restructuring, LME aluminum contract volatility, and composite material crashworthiness validation milestones for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Infrastructure
Lithium-Ion Battery Housing Cases Market
Battery Infrastructure
Europe Lithium Foil Market
Battery Infrastructure
Battery Enclosure Market
Battery Infrastructure
Germany Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
United Kingdom Electric Vehicle Battery Separator Market
Battery Infrastructure
Battery Production Machine Market
Battery Infrastructure
South America Electric Vehicle Battery Separator Market
Battery Infrastructure
ASEAN Countries Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
ASEAN Countries Electric Vehicle Battery Separator Market
Battery Infrastructure
Carbon Battery Bank Market
Battery Infrastructure
Canada Electric Vehicle Battery Separator Market
Battery Infrastructure
Battery Maintenance Service Market
Battery Infrastructure
North America Electric Vehicle Battery Manufacturing Equipment Market
Battery Infrastructure
Battery Raw Materials Market
Battery Infrastructure
France Electric Vehicle Battery Materials Market
Battery Infrastructure
EV Battery Sealant Market