
 Hybrid Valve Market | 2026-2036
Hybrid Valve Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid Valve Market Outlook
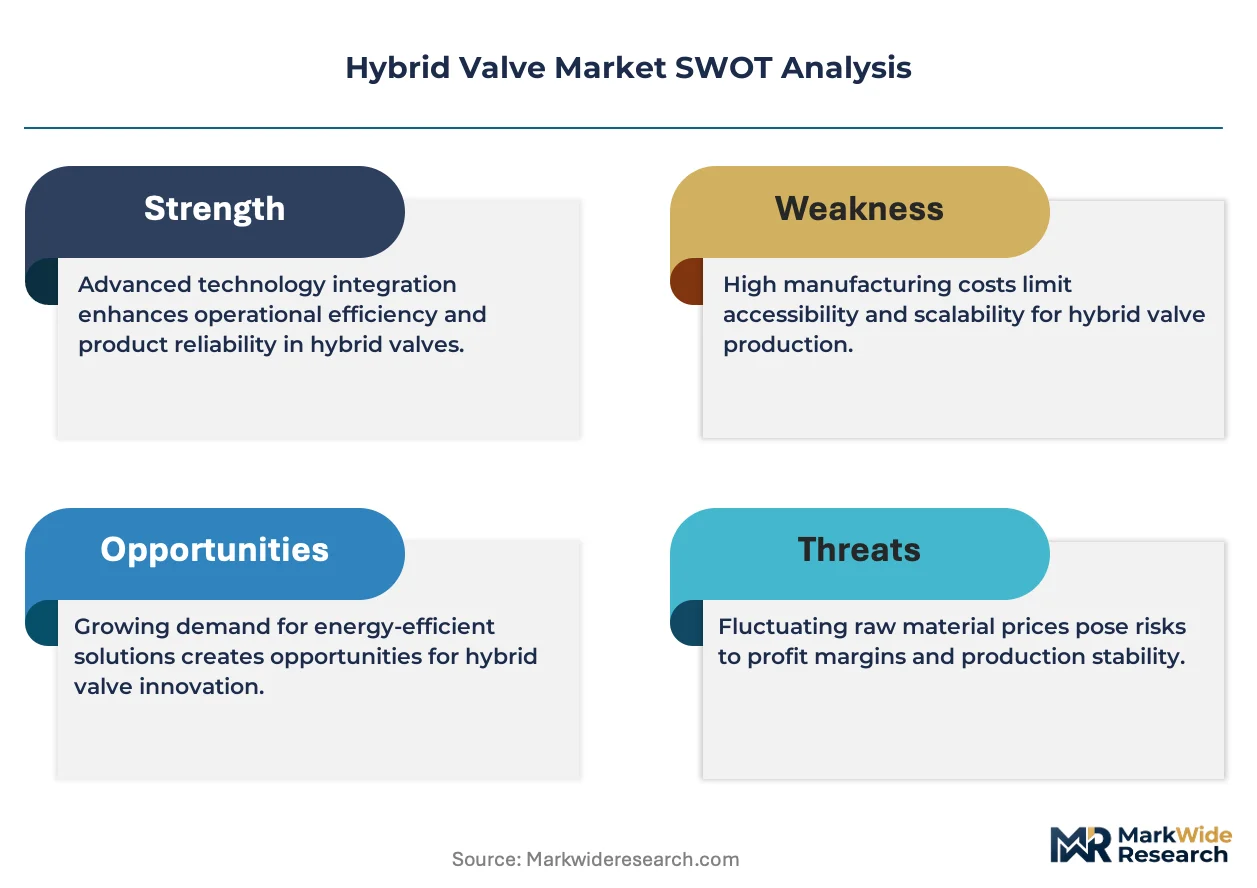
The EU Green Deal is realigning procurement criteria across European process industries, forcing capital equipment buyers to prioritize energy-efficient fluid control systems. Emerson Electric Co. leverages its automation platform to integrate smart diagnostics into hybrid valve architectures. Flowserve Corporation anchors its position through aftermarket service density in refining and petrochemical corridors. IMI plc differentiates via specialized alloy formulations that extend operational life in corrosive process streams.
A hybrid valve combines actuation technologies—typically electric, pneumatic, or hydraulic—with advanced sealing systems and position feedback to enable precise flow modulation under variable pressure and temperature conditions, commonly specified for ANSI Class 150 through 2500 service ratings. Butterfly valves lead volume deployment in HVAC and water treatment due to lower installed cost and compact face-to-face dimensions, while ball valves command premium positioning in oil and gas isolation service where zero-leak tolerance governs specification. Stainless steel dominates material selection in chemical processing and power generation, whereas brass and PVC occupy cost-sensitive commercial plumbing and light industrial fluid control segments.
The EPA enforces emissions limits under the Clean Air Act that compel fugitive emission monitoring and sealed bonnet designs in U.S. process facilities. REACH and the EU F-Gas Regulation restrict fluoropolymer seal chemistries and mandate material traceability across European supply chains. ISO 15848 certification for fugitive emissions has become a de facto market access threshold for suppliers serving international energy projects. Stakeholders must weigh the trade-off between smart actuator integration costs and the operational savings from predictive maintenance capabilities as facility digitalization accelerates.
Market Dynamics
The EU F-Gas Regulation is forcing wholesale replacement of conventional sealing systems across European process plants, compressing procurement cycles and elevating certified hybrid valve architectures to mandatory status in fluid handling specifications.
Growth Catalysts
- Water treatment digitization:Smart distribution networks in municipal utilities are specifying position-feedback hybrid valves for real-time pressure modulation and leak detection.
- REACH compliance mandates:Material traceability requirements across European chemical processing are disqualifying legacy valve suppliers lacking certified alloy documentation.
- Germany's chemical corridor retrofit cycle:Process automation investments in Ludwigshafen and Leverkusen clusters are accelerating displacement of pneumatic-only actuation systems.
Market Restraints
- Nickel alloy price volatility:Super duplex and Inconel input costs swing unpredictably, compressing margins on ANSI Class 600+ specifications.
- Specialized foundry concentration:Precision casting capacity for complex valve bodies concentrates in northern Italy and western Germany, creating single-source vulnerability.
- Fluoropolymer seal restrictions:REACH Annex XVII limitations on PTFE compounds force reformulation cycles that extend qualification timelines.
Strategic Opportunities
- Hydrogen infrastructure buildout:High-pressure isolation requirements in Germany and Netherlands hydrogen hubs favor metal-seated ball valve configurations.
- ISO 15848 certification arbitrage:Suppliers achieving TA-Luft compliance in German markets can leverage equivalent testing for Middle Eastern petrochemical tenders.
- Predictive maintenance convergence:Edge computing integration with electric actuators enables condition-based servicing contracts displacing scheduled replacement programs.
Industry Challenges
- Mechatronics skill scarcity:Field technicians capable of diagnosing integrated actuator-positioner faults command premium wages, constraining service network expansion.
- Legacy DCS integration friction:Retrofitting smart valve positioners into proprietary control architectures requires custom gateway development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid Valve Market |
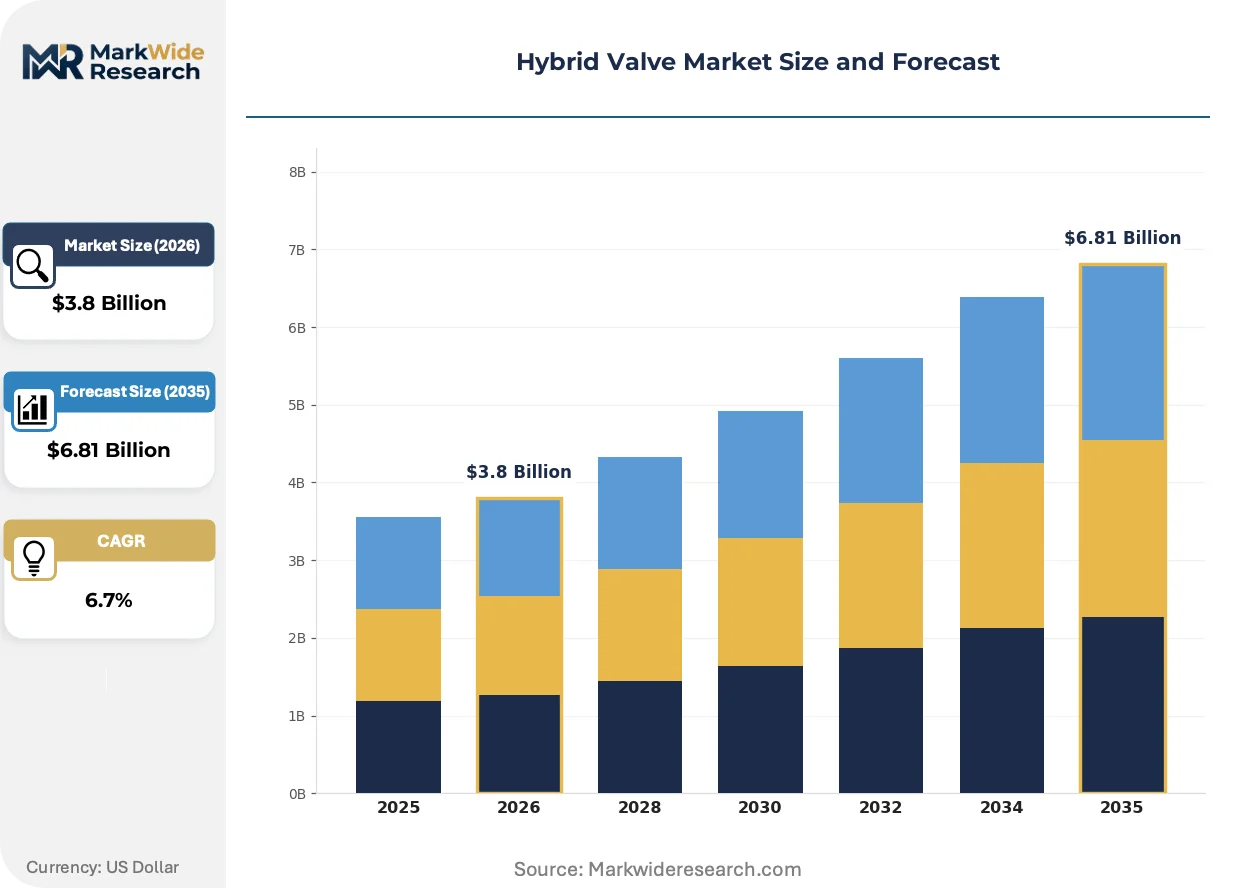
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ball Valves, Gate Valves, Butterfly Valves, Check Valves Material: Stainless Steel, Brass, PVC, Cast Iron End User: Oil & Gas, Water Treatment, Power Generation, Chemical Processing Application: Industrial Automation, HVAC Systems, Pipeline Transport, Fluid Control |
| Companies Covered | Emerson Electric Co., IMI plc, Flowserve Corporation, Trillium Flow Technologies, CIRCOR International Inc., Dymet Alloys, L&T Valves Limited, Wuxi Smart Auto-Control Engineering Co., Carter Process Control GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid Valve Market Strategic Shifts
Fluid control architectures are pivoting from mechanical reliability to data-generating assets, with specification criteria now weighting diagnostic bandwidth equally with pressure containment performance.
Electric actuation with integrated variable frequency drives is overtaking pneumatic systems in modulating service applications. Water treatment utilities and pharmaceutical processors specify all-electric packages to eliminate compressed air infrastructure and enable sub-percent positioning accuracy. This transition compresses aftermarket revenue from pneumatic component replacement while shifting value capture toward firmware and sensor ecosystems.
The EU F-Gas Regulation's tightening leak-rate thresholds are mandating sealed bonnet designs and live-loaded packing systems across chemical processing corridors. German and Belgian plant operators now require ISO 15848-1 BH certification as a gate condition for vendor qualification. This regulatory compression favors suppliers with in-house fugitive emissions testing laboratories over those reliant on third-party certification.
Buyer consolidation among European EPC contractors is compressing specification autonomy at the project level. Engineering firms in the Netherlands and France now mandate pre-approved vendor lists that privilege integrated automation packages over standalone valve procurement. This channel concentration disadvantages specialized valve manufacturers lacking alliances with major actuator suppliers.
Hybrid Valve Market Segmentation
Hybrid valve specification diverges sharply between standalone retrofit installations and embedded smart infrastructure builds. Procurement patterns in water treatment digitization favor integrated position-feedback architectures, while oil and gas isolation service maintains demand for conventional actuation with sealed bonnet upgrades.
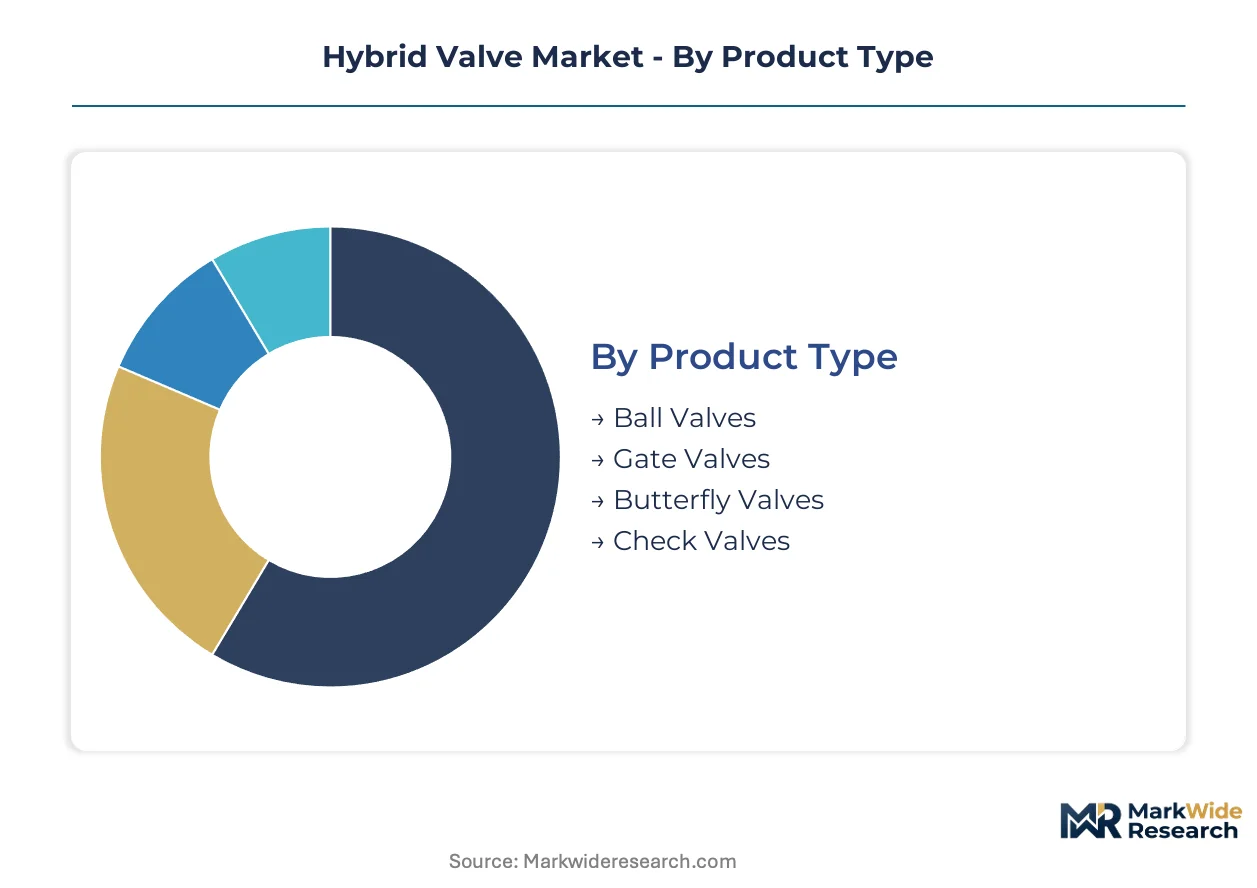
Product Type:
Ball valves and butterfly valves anchor distinct integration depths—ball configurations dominate high-pressure isolation as standalone critical assets, while butterfly designs embed densely into HVAC and water distribution networks as flow modulation elements.
- Ball Valves:Metal-seated configurations achieve ANSI Class 2500 ratings with zero-leak tolerance for hydrogen infrastructure and petrochemical isolation. German hydrogen hub specifications in Hamburg and Rotterdam favor these for high-pressure containment.
- Butterfly Valves:Compact face-to-face dimensions and lower installed cost drive volume deployment across municipal smart distribution networks. Water treatment utilities in Leverkusen and Ludwigshen clusters specify position-feedback variants for real-time pressure modulation.
- Gate Valves:Linear shutoff design suits pipeline transport isolation with minimal pressure drop.
- Check Valves:Passive backflow prevention integrates into fluid control systems without external actuation.
Butterfly valves lead volumes today; ball valves are gaining share fastest in hydrogen and chemical processing corridors.
Material:
Material selection stratifies across corrosion resistance requirements and cost sensitivity, with super duplex and Inconel commanding premium positioning in severe service while brass and PVC serve commercial infrastructure.
- Stainless Steel:Austenitic and duplex grades dominate chemical processing and power generation for corrosion resistance and REACH-compliant traceability. Belgian and German plant operators mandate certified alloy documentation under material transparency rules.
- Brass:Lead-free formulations satisfy commercial plumbing codes with lower capital outlay than alloy steel alternatives.
- PVC:Thermoplastic construction serves light industrial fluid control and cost-sensitive HVAC applications.
- Cast Iron:Ductile iron bodies with epoxy coating anchor water treatment distribution mains for pressure ratings through ANSI Class 250.
Stainless steel dominates revenue today; brass is expanding most quickly in municipal retrofit programs.
End User:
End-use concentration reflects regulatory pressure intensity—EU F-Gas Regulation compliance compresses procurement cycles in chemical processing while water treatment digitization drives specification toward smart actuator integration.
- Oil & Gas:Fugitive emissions monitoring under EPA Clean Air Act and ISO 15848 certification requirements govern specification for upstream isolation and pipeline block valves.
- Water Treatment:Smart distribution network investments specify hybrid valves with edge computing integration for leak detection and predictive maintenance contracts.
- Power Generation:Combined cycle and nuclear plants require stainless steel construction for steam and feedwater service.
- Chemical Processing:REACH Annex XVII restrictions on fluoropolymer seals force reformulation cycles and live-loaded packing system upgrades across German and Belgian corridors.
Water treatment leads procurement volumes today; chemical processing is climbing the fastest on regulatory replacement cycles.
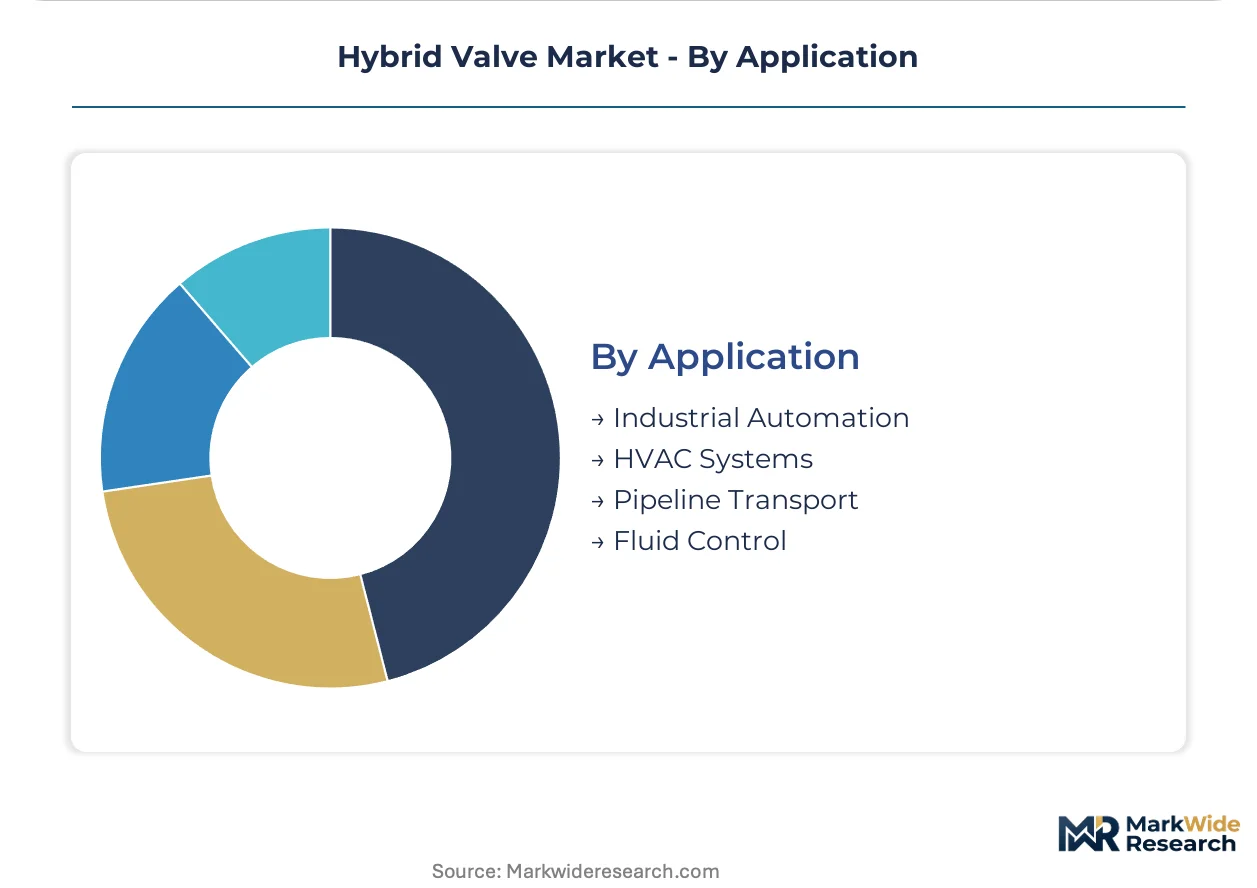
Application:
Application scope spans discrete automation cells through continuous process infrastructure, with integration complexity determining actuator specification and diagnostic bandwidth requirements.
- Industrial Automation:Discrete manufacturing cells specify electric actuation with sub-percent positioning accuracy for batch process control.
- HVAC Systems:Commercial building automation favors butterfly valve configurations with BACnet integration for energy-efficient thermal distribution.
- Pipeline Transport:Long-distance oil and gas transmission requires full-bore ball valves with emergency shutdown actuation.
- Fluid Control:General process service encompasses modulating and isolation functions across chemical and pharmaceutical batch operations.
HVAC systems lead installed base today; industrial automation is expanding most quickly on facility digitalization investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision casting specialists cluster in northern Italy and western Germany, creating regional chokepoints for complex valve body supply. Chemical processing engineers concentrate along Germany's Rhine corridor, driving specification authority for high-performance fluid control systems.
Germany
Ludwigshafen and Leverkusen chemical clusters anchor European demand for REACH-compliant hybrid valves with certified alloy traceability. The EU F-Gas Regulation forces live-loaded packing upgrades across BASF and Covestro facilities. Process automation investments in North Rhine-Westphalia displace pneumatic-only actuation systems with electric alternatives.
United States
Gulf Coast petrochemical complexes specify ISO 15848-certified valves for fugitive emissions compliance under EPA Clean Air Act enforcement. The Permian Basin drives demand for metal-seated ball valves in high-pressure isolation service. Houston-based engineering procurement contractors consolidate vendor lists toward integrated automation packages.
China
Yangtze River Delta chemical processors import super duplex valve specifications for corrosion-resistant service. Provincial environmental bureaus tighten leak detection mandates in Shanghai and Ningbo industrial zones. Domestic foundries in Jiangsu province expand capacity for ANSI Class 600+ valve body casting.
Netherlands
Rotterdam hydrogen hub specifications favor metal-seated ball valves for high-pressure containment in import terminal infrastructure. The Port of Amsterdam drives smart distribution network investments with position-feedback valve requirements. Dutch EPC contractors mandate pre-approved vendor lists privileging integrated automation systems.
Belgium
Antwerp chemical corridor operators require ISO 15848-1 BH certification as mandatory vendor qualification criteria. REACH Annex XVII restrictions force fluoropolymer seal reformulation cycles across Solvay and INEOS facilities. Flemish process plants accelerate retrofit timelines to meet tightening EU F-Gas Regulation leak-rate thresholds.
Hybrid Valve Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the hybrid valve supply base. Integrated automation conglomerates with captive foundry capacity face pressure from specialized valve manufacturers outsourcing precision casting. The market structures around three archetypes: full-platform automation suppliers, standalone valve specialists with alloy formulation expertise, and regional fabricators serving municipal infrastructure. Dominant competitive moves include vertical integration into precision casting capacity and strategic alliances between valve manufacturers and electric actuator suppliers.
Among diversified industrial conglomerates, Emerson Electric Co. and Flowserve Corporation exemplify the integrated automation archetype, anchoring positions through control platform integration and aftermarket service density. IMI plc occupies a position within the specialized alloy tier, representing manufacturers differentiating via corrosion-resistant material formulations. Regional specialists including L&T Valves Limited and Wuxi Smart Auto-Control Engineering Co. exemplify the geographic fabricator archetype, serving infrastructure and utility procurement with cost-optimized configurations.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| IMI plc |
| Flowserve Corporation |
| Trillium Flow Technologies |
| CIRCOR International Inc. |
| Dymet Alloys |
| L&T Valves Limited |
| Wuxi Smart Auto-Control Engineering Co. |
| Carter Process Control GmbH |
| Others |
Value Chain & Pricing Dynamics
Nickel alloy input costs cascade through three distinct pricing tiers as super duplex and Inconel specifications concentrate procurement authority among German chemical processors and Gulf Coast petrochemical operators. Buyers with captive foundry relationships capture margin insulation against spot market volatility, while spot purchasers absorb swing exposure through indexed contract structures.
Pricing Analysis
Bundled aftermarket service contracts versus unbundled valve-only procurement splits the market into divergent value capture models. Three-tier pricing structure across ISO 15848-certified premium, REACH-compliant standard, and economy municipal tiers reflects certification investment recovery and alloy grade differentiation. Price erosion runs through the economy tier as Chinese foundries expand ANSI Class 150-300 capacity. Municipal water utilities exhibit highest price sensitivity; hydrogen infrastructure developers show lowest, prioritizing metal-seated containment over capital outlay.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Houston, and Singapore anchor hub-and-spoke patterns for emergency replacement inventory. Precision casting capacity concentrates in northern Italy, western Germany, and Jiangsu province, with complex valve body supply resting on single-source vulnerability at specialty foundries. Raw material flows draw from Indonesian nickel laterite, South African chromium, and Australian titanium sponge. Tariff exposure on alloy steel semis from third-country routing threatens margin stability. Distribution runs through authorized distributor networks with certified technician attachment for actuator-integrated packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through predictive maintenance contract attachment and premium-tier shift toward hydrogen-certified metal-seated configurations. Electric actuator firmware ecosystems displace commoditized pneumatic component revenue.
For Market Incumbents: Anticipate channel consolidation among Dutch and French EPC contractors by securing pre-approved vendor list status through integrated automation packaging. Defensive consolidation moves center on captive precision casting capacity in Germany or Italy, and TA-Luft emissions laboratory accreditation ahead of EU F-Gas Regulation tightening. Threat substitution from all-electric actuator specialists without valve heritage demands firmware-platform response. Certification investment in ISO 15848-1 BH compliance anchors lever priority. For New Entrants and Emerging Players: Engineering procurement contractors in the Netherlands represent the most penetrable channel partner type for pre-approved vendor list insertion. White-space targets concentrate on hydrogen hub metal-seated ball valve specifications in Hamburg and Rotterdam, and edge-computing-enabled position-feedback variants for water treatment digitization. Go-to-market execution through actuator OEM co-development agreements bypasses standalone valve qualification barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where specialized alloy formulation expertise concentrates in sub-scale European manufacturers without automation platform alliances. Long-term viability frames around captive emissions testing infrastructure and predictive maintenance contract recurring revenue attachment. Acquisition target archetype: mid-tier valve specialists with TA-Luft certification and unfilled foundry capacity. Signal to watch: hydrogen infrastructure tender awards accelerating metal-seated specification displacement of soft-seated legacy stock.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Casting | Captive super duplex capacity insulates margin from Indonesian nickel volatility. |
| ISO 15848-1 BH Certification Investment | TA-Luft compliance unlocks German chemical corridor and Middle Eastern petrochemical access. |
| Electric Actuator Firmware Platform Development | Sub-percent positioning accuracy displaces pneumatic infrastructure in water treatment procurement. |
| Predictive Maintenance Contract Attachment | Condition-based servicing contracts convert capital equipment sales into recurring revenue streams. |
| Hydrogen Infrastructure Specification Alignment | Metal-seated ball valve configurations capture high-pressure containment demand in Rotterdam and Hamburg hubs. |
Study Parameters
Bottom-up end-use modeling reconciled against top-down foundry capacity tracking forms the analytical core of this study. Primary interviews with plant engineers at German chemical processors, procurement leads at Dutch EPC contractors, maintenance directors at water treatment utilities, and aftermarket service heads at valve distributors combined with secondary validation from SEC 10-K filings, Cefic chemical industry reports, customs trade data for alloy steel valve imports, and EPA Clean Air Act enforcement disclosures. Triangulation across supply-side capacity announcements and demand-side procurement pipeline visibility ensures segment-level accuracy.
Historical trendline analysis of retrofit cycle timing and regulatory compliance deadlines informs projection construction across the analysis window. Segmentation dimensions modeled include valve type, material grade tier, end-use industry, actuation architecture, and regional regulatory cluster. CAGRs derive from weighted average of replacement cycle velocity and new infrastructure buildout assumptions. Industry-specific forecast inputs incorporate EU F-Gas Regulation phase-in schedules and hydrogen hub project development timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to nickel alloy price volatility and foundry capacity expansion timing. Outputs reflect documented assumptions around regulatory enforcement intensity and electric actuation substitution rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Global Plug Valve Market
Valves
Compressor Valves Market
Valves
Choke and Kill Manifold Market
Valves
Explosion Vents Market
Valves
Safety Valve Market
Valves
Middle East and Africa Industrial Valves Market
Valves
Industrial Valves and Actuators Market
Valves
Sand Control System Market
Valves
Global Fluid Management Systems Market
Valves
Global Pressure Relief Valves Market
Valves
Construction Valve Seat Insert Market
Valves
Orifice Reducers Market
Valves
Aerospace Valves Market
Valves
Ball Valves Market
Valves
Middle East and Africa Electro Hydraulic Servo Valve Market
Valves
HVAC Valves Market