
 Lithium Thionyl Chloride Battery Market | 2026-2036
Lithium Thionyl Chloride Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Thionyl Chloride Battery Market Foresight
Long-term performance contracts and predictive maintenance subscriptions is restructuring how battery suppliers monetize reliability. Saft leverages its aerospace heritage to dominate high-altitude and defense contracts. Maxell, Ltd. anchors the Asian supply base through precision manufacturing scale in Japan. Ultralife Corporation specializes in medical-grade power systems that sustain FDA-validated device lifecycles.
Lithium thionyl chloride batteries are primary electrochemical cells using a lithium metal anode and thionyl chloride catholyte, delivering nominal voltages near 3.6 volts with exceptionally low self-discharge rates suited for decade-long deployments in inaccessible locations. Cylindrical formats lead industrial procurement due to established automation and thermal management compatibility, while coin cell configurations serve the fastest-growing segment in implantable medical devices where volumetric density governs design. Primary battery technology occupies the mature margin pool in defense and oil-and-gas telemetry, whereas rechargeable variants attract development capital from telecommunications infrastructure seeking cycle-life improvements.
FAA hazardous material rules, EU Battery Regulation sustainability mandates, and FDA quality system requirements collectively shape cell design, transport classification, and market access documentation across jurisdictions. ISO standards for quality management and IEC safety certifications further constrain supplier qualification timelines for medical and aviation buyers. Stakeholders must monitor how transport regulators reconcile lithium metal restrictions with the proliferation of remote IoT deployments requiring extended field life.
Market Dynamics
The EU Battery Regulation's mandatory carbon footprint declarations and digital battery passports are forcing cell manufacturers to reconfigure supply chains and documentation systems before the 2027 enforcement deadline. This regulatory architecture is compressing qualification timelines and elevating compliance costs across all export-oriented production facilities.
Growth Catalysts
- Remote IoT telemetry proliferation:Oil-and-gas pipeline operators in the United States are deploying decade-life sensors in Arctic and subsea installations where maintenance access is economically prohibitive.
- REACH substance restrictions:The European Chemicals Agency's tightening controls on mercury and cadmium alternatives are redirecting industrial buyers toward lithium thionyl chloride chemistries for guaranteed compliance.
- Defense electronics modernization:Germany's Bundeswehr is accelerating procurement of high-reliability power systems for battlefield communication and unmanned platforms requiring extended shelf life.
Market Restraints
- Lithium metal supply concentration:Spodumene processing and lithium metal refining capacity clusters in Australia and China create single-source vulnerability for anode material procurement.
- FAA hazardous material transport classification:Lithium metal content triggers Class 9 dangerous goods restrictions that inflate logistics costs and limit air freight options for field deployment.
- Rechargeable lithium-ion substitution:Falling costs of solid-state and silicon-anode rechargeable systems are capturing applications where decade-life requirements have softened to 3-5 year replacement cycles.
Strategic Opportunities
- India's medical device manufacturing expansion:CDSCO regulatory harmonization with FDA standards is attracting implantable device contract manufacturers seeking localized battery sourcing.
- EU Green Deal circular economy mandates:Battery passport traceability requirements favor suppliers with established recycling partnerships and closed-loop material recovery systems.
- Edge computing infrastructure:Telecommunications operators are installing autonomous power nodes in remote cell towers where grid connectivity is unreliable and maintenance dispatch costs exceed battery replacement economics.
Industry Challenges
- Electrolyte handling expertise scarcity:Thionyl chloride's toxicity and moisture sensitivity demand specialized cleanroom technicians that battery manufacturers struggle to recruit and retain.
- IEC 60086-4 safety certification timelines:Medical and aviation buyers require 18-24 month validation cycles that delay revenue recognition for new cell formats.
- Legacy system voltage compatibility:Industrial telemetry networks running on 3.0V lithium-manganese dioxide architectures require hardware redesigns to accommodate 3.6V nominal outputs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Thionyl Chloride Battery Market |
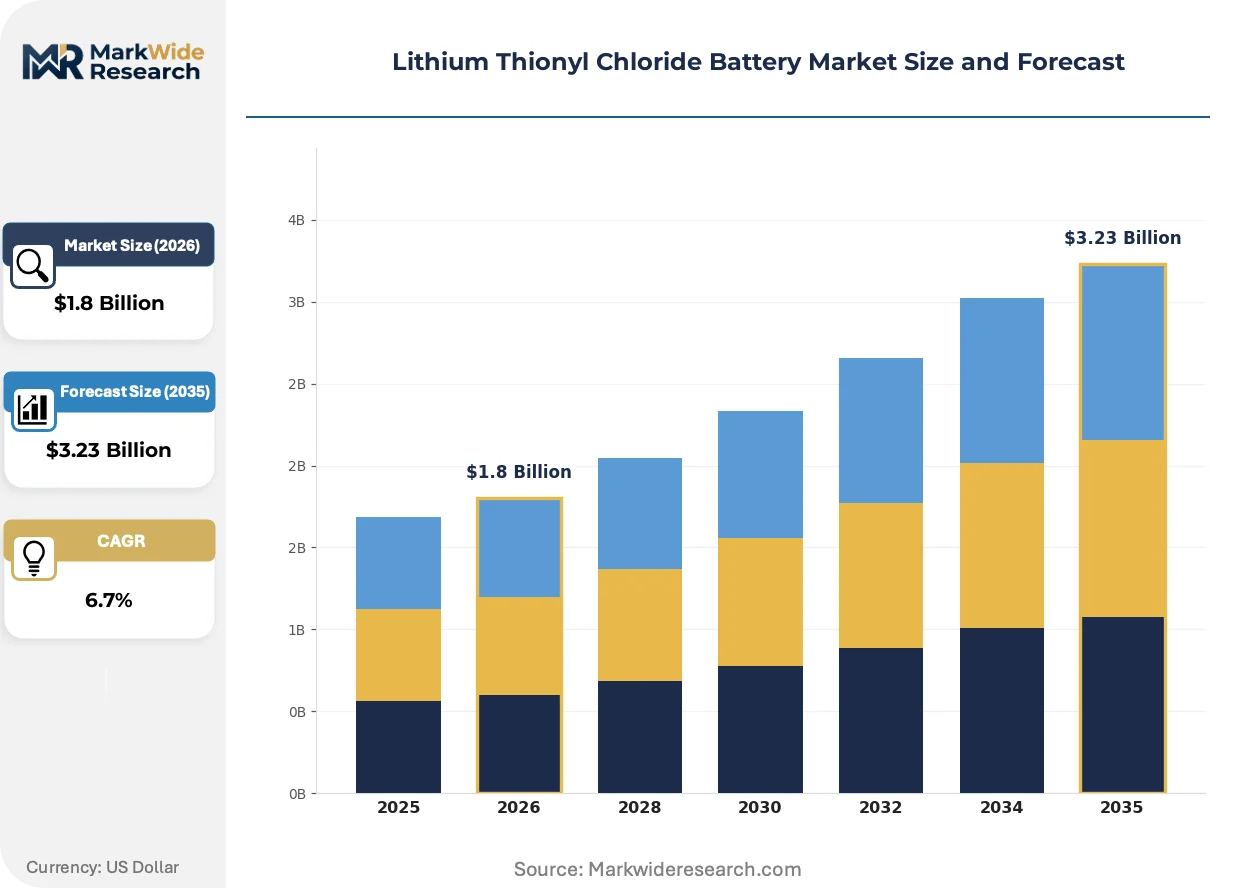
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cylindrical, Prismatic, Coin Cell, Button Cell Technology: Primary Battery, Secondary Battery, Hybrid Battery, Rechargeable Battery Application: Aerospace, Defense, Medical Devices, Consumer Electronics End User: Manufacturing, Healthcare, Automotive, Telecommunications |
| Companies Covered | Saft, Maxell, Ltd., Ultralife Corporation, VARTA AG, Panasonic Corporation, Tadiran Batteries Ltd., EaglePicher Technologies, Bren-Tronics, Inc., EVE Energy Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Thionyl Chloride Battery Market Shifts & Advancements
Cell architecture and manufacturing processes are converging around reliability verification and predictive failure modeling. Suppliers are investing in real-time impedance monitoring and solid-electrolyte interface stabilization to extend operational lifespans beyond nominal ratings.
Glass-to-metal seal technology is electrifying hermetic enclosure design for implantable medical applications. Cardiac device manufacturers in Switzerland and the United States are adopting these seals at accelerated qualification paces. The technology is compressing failure rates in long-term implantable power systems below one percent per decade.
Japan's METI has issued revised guidelines for stationary energy storage safety testing that incorporate thermal runaway propagation assessments previously reserved for automotive applications. Industrial battery integrators must now submit extended abuse-test documentation for grid-tied installations. Telecom infrastructure developers in Japan are responding by specifying cells with redundant safety venting and ceramic separator layers.
Buyers are consolidating vendor relationships around suppliers offering integrated predictive maintenance platforms. Defense contractors and medical device OEMs are displacing transactional spot purchasing with multi-year performance contracts that bundle cell supply, field monitoring, and replacement logistics. This pattern is most visible in Germany and the United States where procurement functions have merged reliability engineering with sourcing authority.
Lithium Thionyl Chloride Battery Market Segmentation
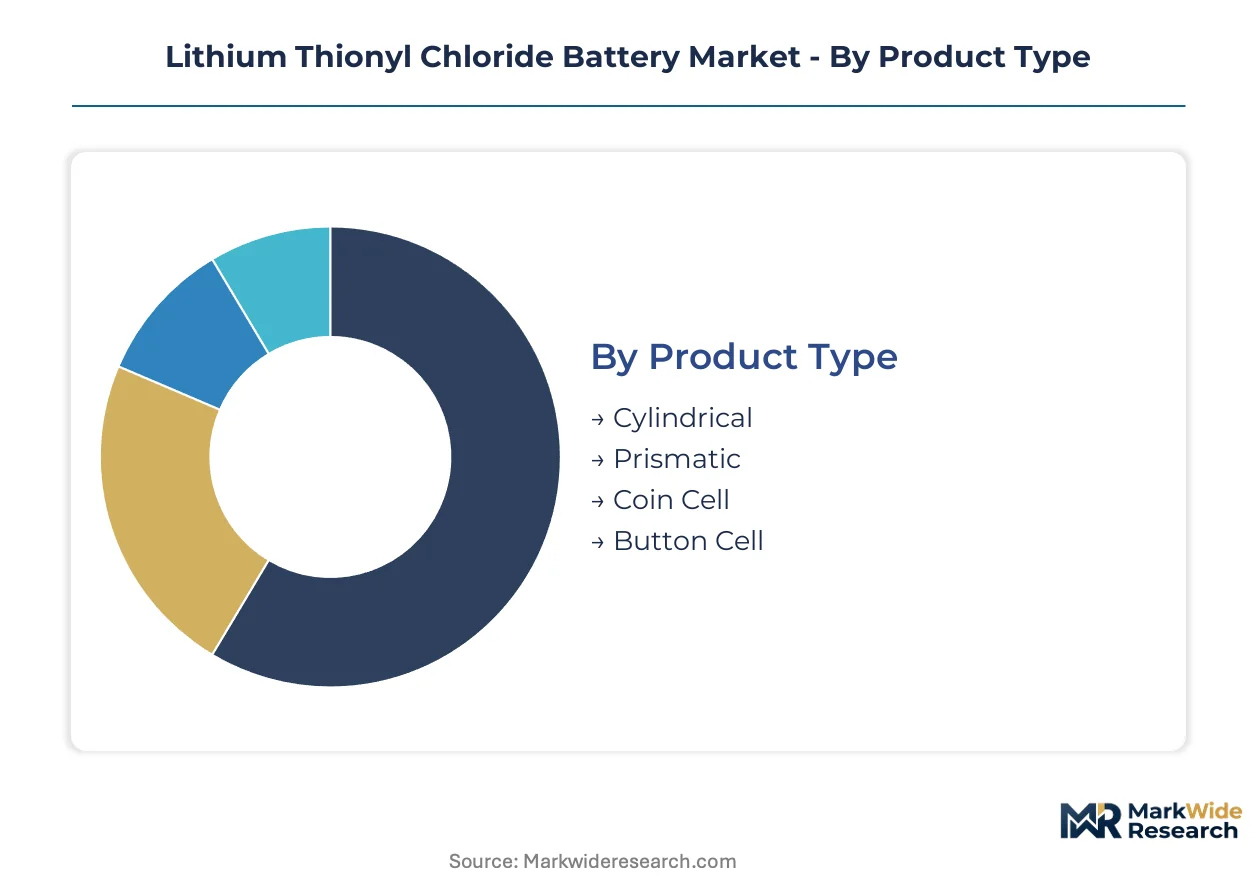
Segmentation in lithium thionyl chloride batteries reveals how cell architecture, electrochemistry, and end-use certification requirements partition procurement behavior. Buyers in defense and medical verticals impose qualification barriers that filter supplier participation across each category.
Product Type:
Cell geometry determines automation compatibility, thermal management architecture, and hermetic sealing complexity.
- Cylindrical:Rolled electrode construction with established winding automation supports high-volume defense and industrial telemetry procurement. Demand concentrates in Germany and the United States where precision instrumentation clusters require decade-life power with proven supply chain traceability.
- Coin Cell:Stacked electrode architecture maximizes volumetric energy density for spatially constrained implantable devices. Swiss and United States cardiac device manufacturers are accelerating qualification of glass-to-metal seal variants that compress failure rates below one percent per decade.
- Prismatic:Pouch-compatible formats suit custom industrial enclosures with non-standard cavity dimensions.
- Button Cell:Compact variants serve consumer electronics backup power with lower cycle-life requirements.
Mature deployment sits with cylindrical formats. Newer deployment is concentrated in coin cell configurations.
Technology:
Electrochemical reversibility separates procurement into single-use reliability versus cycle-life optimization tradeoffs.
- Primary Battery:Non-rechargeable lithium-thionyl chloride chemistry delivers sub-one-percent annual self-discharge for unmaintained remote installations. Oil-and-gas telemetry operators in Arctic and subsea United States infrastructure specify primary cells where maintenance access costs exceed replacement economics.
- Secondary Battery:Rechargeable variants attract telecommunications capital seeking cycle-life improvements for grid-tied edge computing nodes. Japanese METI safety guidelines now mandate thermal runaway propagation testing that elevates documentation burdens for stationary energy storage integrators.
- Hybrid Battery:Dual-chemistry architectures combine primary energy density with secondary burst capability for intermittent high-load applications.
- Rechargeable Battery:Solid-state and silicon-anode substitutes are capturing applications where decade-life requirements have compressed to three-to-five-year replacement cycles.
Primary technology anchors defense and oil-and-gas margin pools. Rechargeable variants are expanding most quickly in telecommunications infrastructure.
Application:
Certification intensity and failure consequence severity stratify procurement specifications across verticals.
- Medical Devices:FDA quality system requirements and IEC 60086-4 safety certifications impose eighteen-to-twenty-four-month validation timelines for implantable power systems. CDSCO regulatory harmonization in India is attracting contract manufacturers seeking localized battery sourcing for cardiac and neuromodulation devices.
- Defense:Extended shelf-life requirements for battlefield communication and unmanned platforms drive procurement in Germany's Bundeswehr modernization programs. FAA hazardous material transport classification restricts air freight options for field deployment logistics.
- Aerospace:High-altitude and satellite applications leverage heritage aerospace supplier relationships with established failure-mode documentation.
- Consumer Electronics:Lower certification barriers enable faster supplier qualification but compress margin structures.
Medical and defense applications concentrate value capture. Consumer electronics represents the volume-accessible tier with compressed qualification overhead.
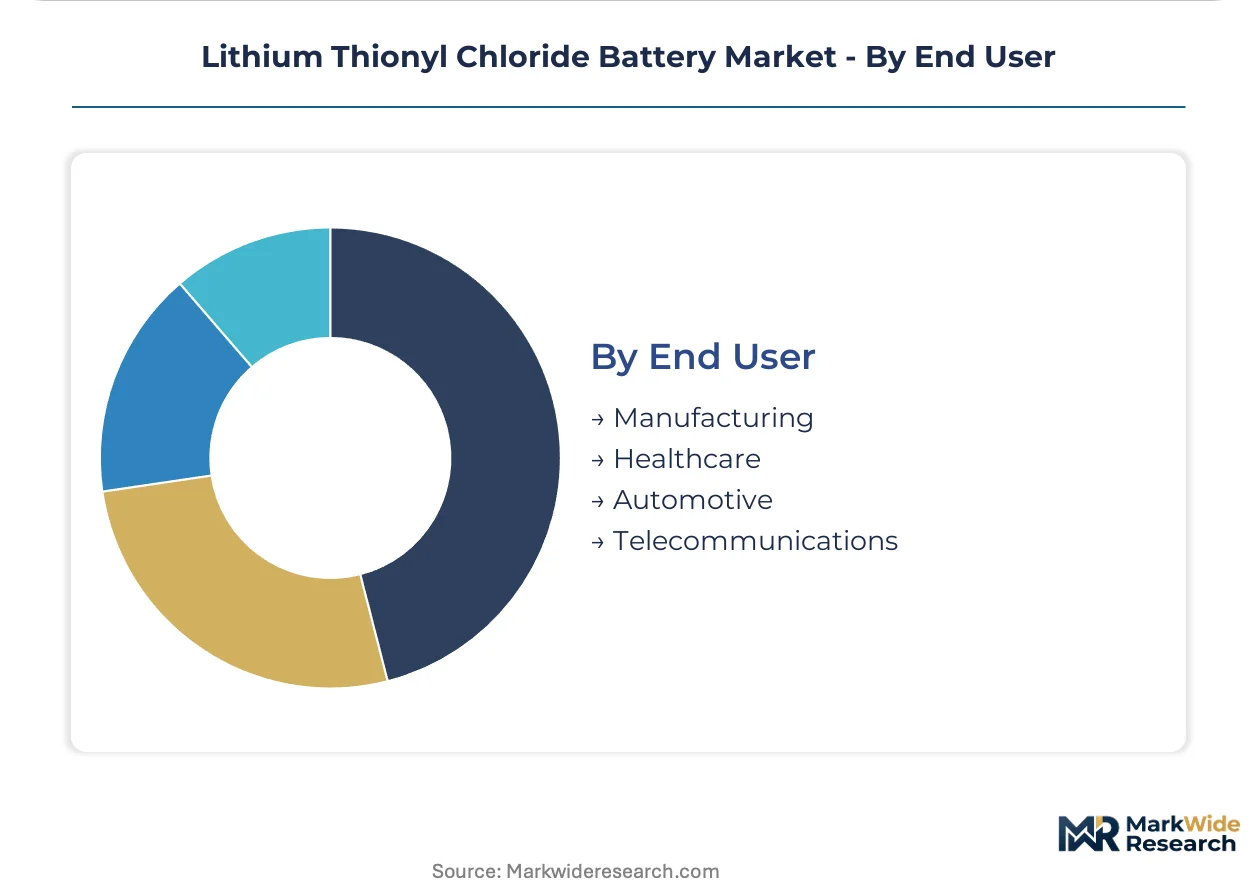
End User:
Procurement authority alignment with reliability engineering functions determines contract structure and vendor consolidation patterns.
- Healthcare:Medical device OEMs are displacing transactional purchasing with multi-year performance contracts bundling cell supply, field monitoring, and replacement logistics. FDA-validated device lifecycles require suppliers with established quality management systems and closed-loop material recovery partnerships.
- Telecommunications:Remote cell tower operators face maintenance dispatch costs that exceed autonomous power node replacement economics, favoring predictive maintenance subscriptions.
- Manufacturing:Industrial automation and process control systems specify decade-life backup power for critical sensor networks.
- Automotive:Telematics and tire pressure monitoring systems represent emerging volume with softened longevity requirements relative to primary industrial applications.
Healthcare procurement is consolidating around integrated reliability platforms. Telecommunications is gaining share fastest as edge computing infrastructure expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in East Asia and Western Europe while consumption concentrates in defense and medical device manufacturing hubs across Germany, Japan, and the United States. This geographic split creates logistics complexity around lithium metal anode sourcing and hazardous material transport compliance.
United States
Oil-and-gas telemetry operators in Arctic Alaska and Gulf of Mexico subsea infrastructure specify decade-life primary cells where maintenance access costs render replacement uneconomical. FAA Class 9 dangerous goods restrictions inflate logistics costs and limit air freight options for field deployment. Houston and Denver anchor precision instrumentation clusters serving defense electronics and industrial automation verticals.
Germany
Bundeswehr modernization programs accelerate procurement of high-reliability power systems for battlefield communication and unmanned platforms requiring extended shelf life. EU Battery Regulation carbon footprint declarations and digital passport requirements compress qualification timelines before the 2027 enforcement deadline. Bavaria and Baden-Württemberg concentrate medical device OEMs consolidating vendor relationships around integrated predictive maintenance platforms.
Japan
Telecommunications infrastructure developers specify cells with redundant safety venting and ceramic separator layers following METI revised guidelines for stationary energy storage safety testing. Precision manufacturing scale supports high-volume defense and industrial telemetry procurement. Tokyo and Osaka metropolitan areas host cardiac device manufacturers accelerating qualification of glass-to-metal seal coin cell variants.
Switzerland
Cardiac and neuromodulation device manufacturers drive demand for coin cell configurations where volumetric density governs implantable design constraints. Swissmedic quality system requirements align with FDA validation timelines for eighteen-to-twenty-four-month certification cycles. Zurich and Basel clusters specialize in hermetic enclosure technology compressing failure rates below one percent per decade.
India
CDSCO regulatory harmonization with FDA standards attracts implantable device contract manufacturers seeking localized battery sourcing for cardiac and neuromodulation applications. Manufacturing expansion targets import substitution for medical-grade power systems currently procured from East Asian suppliers. Maharashtra and Karnataka host emerging precision electronics clusters serving domestic healthcare OEMs.
Lithium Thionyl Chloride Battery Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the lithium thionyl chloride battery landscape. Integrated cell manufacturers with captive electrolyte handling and hermetic sealing capabilities command premium positioning in medical and defense procurement. Three archetypes dominate: heritage aerospace suppliers leveraging failure-mode documentation, precision manufacturing specialists from East Asia, and medical-grade power system integrators with FDA-validated quality systems. Competitive moves concentrate on multi-year performance contracting and predictive maintenance subscription bundling.
Within the heritage aerospace tier, Saft anchors high-altitude and defense contract positioning through established reliability engineering relationships. Maxell, Ltd. exemplifies East Asian precision manufacturing scale serving industrial telemetry and consumer electronics verticals. Ultralife Corporation occupies the medical-grade specialization vector with FDA-validated device lifecycle capabilities. These three represent distinct competitive positioning archetypes rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Saft |
| Maxell, Ltd. |
| Ultralife Corporation |
| VARTA AG |
| Panasonic Corporation |
| Tadiran Batteries Ltd. |
| EaglePicher Technologies |
| Bren-Tronics, Inc. |
| EVE Energy Co., Ltd. |
| Others |
Supply & Pricing Matrix
Bundeswehr procurement consolidation around multi-year performance contracts is forcing cell manufacturers to absorb qualification documentation costs upfront, compressing margins on standard-grade cylindrical formats while elevating premium capture for FDA-validated medical-grade systems.
Pricing Analysis
Margin tightening in industrial telemetry reflects REACH-driven chemistry switches and EU Battery Regulation compliance investments. Three-tier pricing structure across medical-grade, defense-certified, and industrial-standard levels separates procurement by certification intensity. Pricing pressure stems from rechargeable lithium-ion substitution in softened longevity applications. Oil-and-gas operators show highest price sensitivity; cardiac device OEMs accept premium positioning for hermetic seal reliability.
Supply Chain Analysis
Single-source vulnerability sits with Australian spodumene processing and Chinese lithium metal refining for anode material procurement. Thionyl chloride catholyte production draws from German and Japanese specialty chemical suppliers. Distribution runs through defense logistics channels and medical device OEM direct procurement with limited spot market liquidity. Tariff exposure on lithium metal imports from China elevates landed cost volatility for North American integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EU Battery Regulation carbon footprint declarations and digital passport mandates erect barrier-to-entry moats favoring incumbents with established documentation systems and recycling partnerships.
For Market Incumbents: Hedge against rechargeable substitution by accelerating glass-to-metal seal capacity for implantable medical applications and securing captive thionyl chloride supply through backward integration into specialty chemical production. Solid-state battery cost curves threaten decade-life primary cell positioning in telecommunications infrastructure. For New Entrants and Emerging Players: The premium-to-economy price-point gap in Indian medical device manufacturing offers white-space access as CDSCO harmonization attracts contract manufacturers seeking localized sourcing. Target cardiac and neuromodulation device suppliers with IEC 60086-4 pre-certified coin cell formats and bundled predictive maintenance subscriptions. For Investors and Strategic Acquirers: The window for entry favors electrolyte handling specialists with cleanroom technician retention and established FAA dangerous goods logistics capabilities. Five-to-ten-year viability hinges on EU Green Deal circular economy mandate compliance. Watch for METI safety guideline expansion beyond stationary storage as inflection signal for Japanese telecommunications infrastructure demand.| Strategic Initiative | Industry Significance |
|---|---|
| Glass-to-Metal Seal Capacity Expansion | Swiss and United States cardiac device manufacturers compress implantable failure rates below one percent per decade. |
| EU Battery Passport Compliance Investment | Digital documentation systems satisfy 2027 enforcement deadlines for carbon footprint declarations. |
| India Manufacturing Localization | CDSCO harmonization attracts implantable device contract manufacturers seeking import substitution. |
| Predictive Maintenance Platform Development | German and United States defense contractors displace transactional purchasing with multi-year performance contracts. |
| Thionyl Chloride Supply Security | Captive production of moisture-sensitive catholyte reduces single-source vulnerability in specialty chemical procurement. |
Research Methodology
Multi-period observation of IEC certification timelines, FAA transport classification amendments, and EU regulatory enforcement patterns anchored the trend analysis, supplemented by interviews with biomedical engineers at cardiac device OEMs, GPO contracts managers at hospital purchasing committees, defense procurement officers at Bundeswehr modernization programs, and oil-and-gas telemetry operators in Arctic infrastructure. Secondary validation drew from FDA 510(k) filings, ECHA REACH substance restriction updates, EU Battery Regulation delegated acts, and customs trade data for lithium metal anode imports. Bottom-up cell format demand modeling triangulated against top-down end-use vertical spending patterns.
Segment-weighting across cylindrical, coin cell, prismatic, and button cell geometries combined with primary battery, secondary battery, hybrid, and rechargeable technology splits shaped the analytical framework over the projection horizon. Medical device, defense, aerospace, and consumer electronics application categories were modeled alongside healthcare, telecommunications, manufacturing, and automotive end-user procurement patterns. CAGRs derived from regression analysis of historical qualification cycle compression and regulatory cost pass-through elasticity. Thionyl chloride handling expertise scarcity and lithium metal supply concentration served as industry-specific forecast inputs.
Inputs from FDA quality system inspection records and METI safety guideline revision drafts were available through the study window; gaps in real-time Bundeswehr procurement pipeline data introduce uncertainty bands around defense segment projections. Forecasts reflect documented assumptions regarding REACH substance restriction timelines and EU Battery Regulation enforcement consistency. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Battery Voltage Recorder Market
Batteries
Li-Mno2 Button Battery Market
Batteries
Wireless Power Bank Market
Batteries
Bangladesh Lead Acid Battery Market
Batteries
Redox Flow Battery Market
Batteries
Battery Pack Balancer Market
Batteries
Power Battery Sealant Market
Batteries
Global Coke Oven Batteries Market
Batteries
Asia-Pacific Rechargeable Battery Market
Batteries
Lithium-Fluorinated Graphite Batteries Market
Batteries
Latin America Automotive Lead-Acid Battery Market
Batteries
Valve Regulated Lead-Acid (VRLA) Batteries Market
Batteries
Global Lithium Titanate (LTO) Batteries Market
Batteries
Southeast Asia Battery Market
Batteries
South America Battery Cell Market
Batteries
Battery Terminal Brushes Market