
 United Kingdom Plastic Packaging Market | 2026-2036
United Kingdom Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Plastic Packaging Market Analytics
Mono-material flexible film technology is tilting the UK plastic packaging sector toward simpler recycling streams. Berry Global Group leverages its blown film extrusion network to supply major grocery retailers with polyethylene-based formats. Amcor plc anchors its position through pharmaceutical blister lidding and healthcare barrier films. Mondi plc competes with kraft-paper hybrid structures that reduce plastic weight in e-commerce mailers.
United Kingdom plastic packaging encompasses thermoformed, extruded, and molded polymer structures engineered to protect, preserve, and present consumer and industrial goods, with typical wall thicknesses ranging from 0.25 mm for flexible films to 2.5 mm for rigid containers. Polyethylene dominates the material mix for stretch wrap and carrier bags due to its toughness and heat-sealability, while PET leads in bottle applications for carbonated drinks and personal care products where clarity and barrier performance matter. Films represent the most mature segment with thin margin pools, whereas pouches capture faster growth as brands replace glass jars and metal cans with lightweight, shelf-extending alternatives. Blow molding remains the workhorse process for hollow containers, though injection molding gains precision-driven demand in healthcare vials and closures.
The UK Environment Agency enforces the Plastic Packaging Tax, which mandates minimum recycled content thresholds and reshapes raw material procurement for converters across England, Scotland, and Wales. BSI standards for food-contact plastics and the UK REACH framework govern chemical safety and migration limits, raising compliance costs for importers while protecting domestic manufacturers. Stakeholders must track how extended producer responsibility schemes and deposit-return system legislation alter collection infrastructure economics and post-consumer resin availability before committing capacity expansions.
Market Dynamics
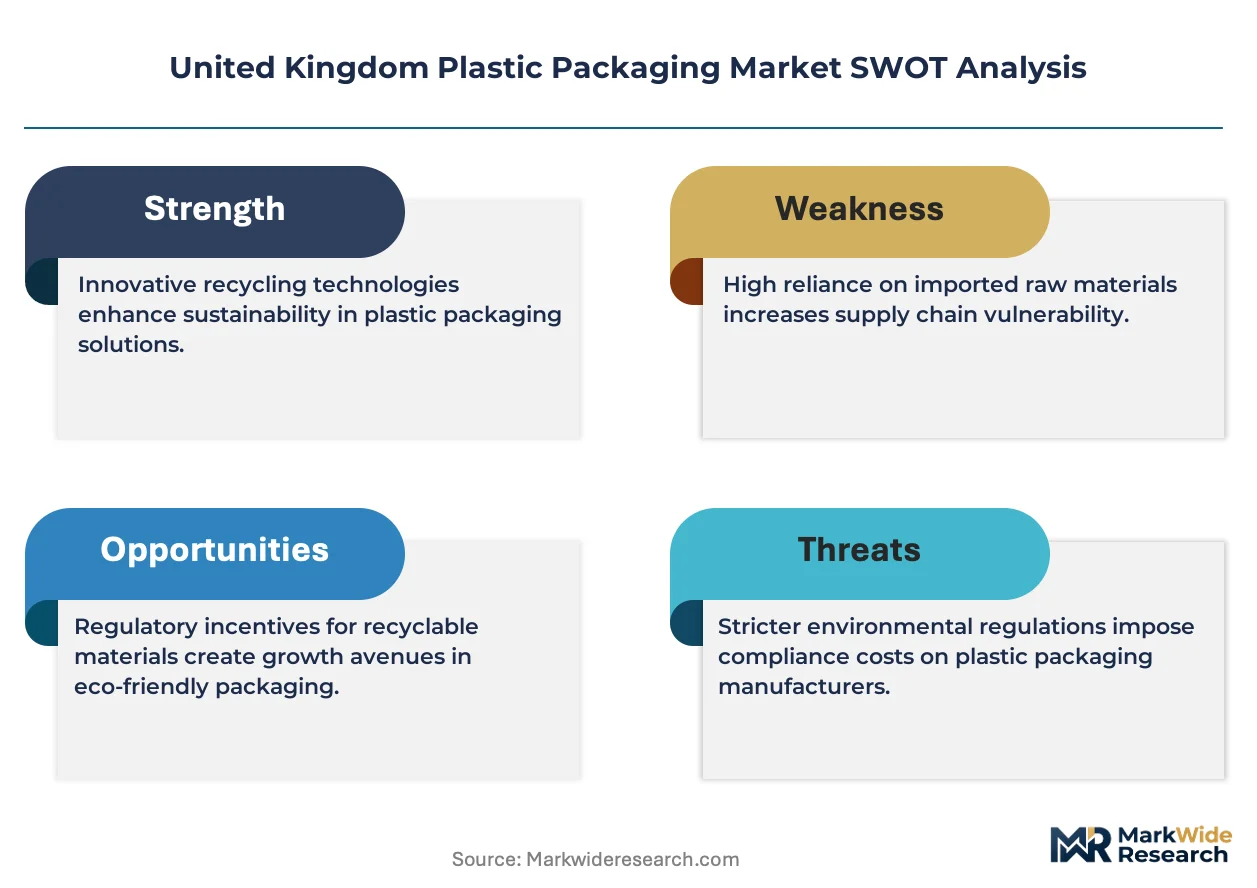
The UK Plastic Packaging Tax is compressing virgin resin demand while forcing converters to rebuild supply chains around post-consumer feedstock. This fiscal mechanism now dominates capital allocation decisions across England's Midlands manufacturing corridor and Scottish conversion facilities.
Growth Catalysts
- Extended Producer Responsibility schemes:The UK's impending packaging waste regulations mandate higher recycling targets, driving investment in mono-material film lines that simplify mechanical reprocessing.
- Flexible pouch technology:Food brands in ambient sauces and ready meals are accelerating format switches from glass jars to retortable polyethylene structures, cutting transport emissions and shelf-space costs.
- Midlands manufacturing concentration:England's central corridor hosts dense clusters of blown film extruders and thermoformers, creating localized ecosystem efficiencies in technical service and spare parts logistics.
Market Restraints
- Recycled resin price volatility:Post-consumer polyethylene flake trades at unpredictable premiums to virgin polymer, eroding margin stability for converters lacking long-term offtake contracts.
- Single-source mechanical recycling dependence:The UK lacks domestic chemical recycling capacity, concentrating advanced reprocessing know-how in Netherlands and German facilities.
- Barrier performance ceiling:Mono-material polyethylene structures cannot match metallized film oxygen transmission rates, limiting penetration in ultra-sensitive pharmaceutical and infant nutrition applications.
Strategic Opportunities
- Northern England industrial corridor:Yorkshire and Lancashire offer underutilized polymer compounding infrastructure suitable for post-consumer resin upgrading and specialty masterbatch production.
- Pharmaceutical serialization integration:Track-and-trace mandates create white space for packaging converters combining barrier films with printed electronics for authentication.
- Digital watermarks and AI sorting:Convergence of invisible marker technologies with near-infrared detection systems enables higher-purity post-consumer stream separation, improving resin quality for food-contact applications.
Industry Challenges
- Food-contact certification timelines:Novel barrier coatings and recycled content formulations face extended safety evaluation periods under UK REACH, delaying commercial launches by 18-24 months.
- Legacy extrusion asset retrofitting:Converting existing blown film lines to handle higher percentages of post-consumer resin requires screw and die modifications that disrupt production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Plastic Packaging Market |
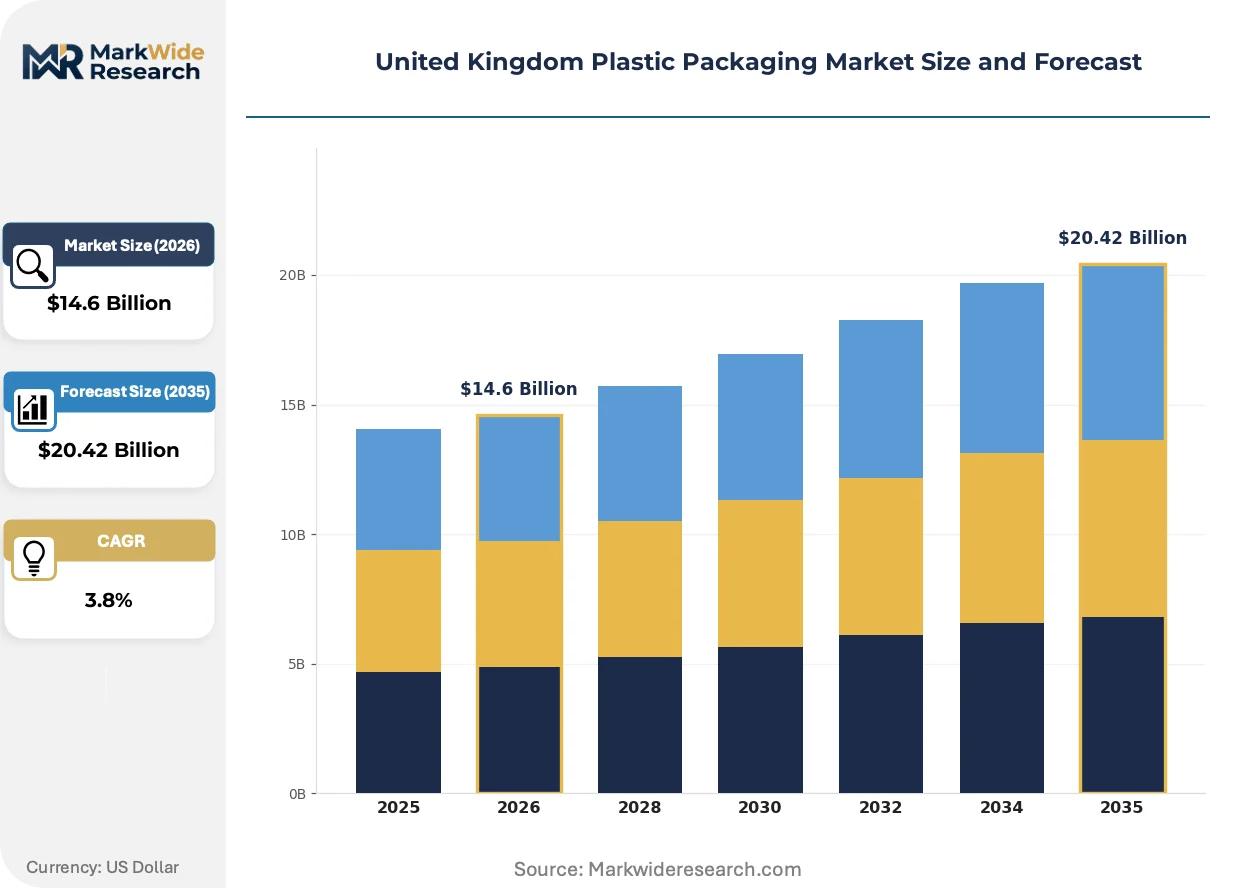
| Market Size in 2026 | $14.6 Billion |
| Market Size in 2035 | $20.42 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Pouches, Containers, Films End User: Food & Beverage, Healthcare, Personal Care, Household Products Material: Polyethylene, Polypropylene, PET, PVC Manufacturing Stage: Blow Molding, Injection Molding, Extrusion, Thermoforming |
| Companies Covered | Berry Global Group, Charpak Limited, Amcor plc, Fusion Group Limited, Coral Products PLC, Mondi plc, Coveris Holdings S.A., Plastipak, Smurfit WestRock, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Plastic Packaging Market Evolving Landscape
Digital traceability infrastructure is rewiring how converters demonstrate compliance and capture premium positioning. Three interconnected developments are compressing traditional specification cycles and enabling faster format innovation.
Digital printing technology is digitizing short-run packaging production, allowing food brands to execute regional flavor variants without plate changeover costs. Mid-sized retailers in Scotland and Wales are adopting this for private-label seasonal ranges. The technology is digitizing inventory management by collapsing minimum order quantities and enabling just-in-time replenishment models previously uneconomical for plastic formats.
The UK Environment Agency's enforcement of Plastic Packaging Tax thresholds is tightening recycled content verification requirements. Converters must now document mass balance through audited supply chains rather than self-declaration. Food and beverage applications face the steepest compliance burden, with major grocery retailers demanding third-party certification before contract renewal.
Direct sourcing from compounders is displacing traditional distributor relationships among mid-sized packaging buyers. Purchasing managers in England's East Midlands are negotiating resin formulations with specified post-consumer percentages, bypassing standard stock-keeping-unit catalogs. This pattern concentrates in personal care and household chemical segments where brand owners prioritize sustainability credentials in shelf presentation.
United Kingdom Plastic Packaging Market Segmentation
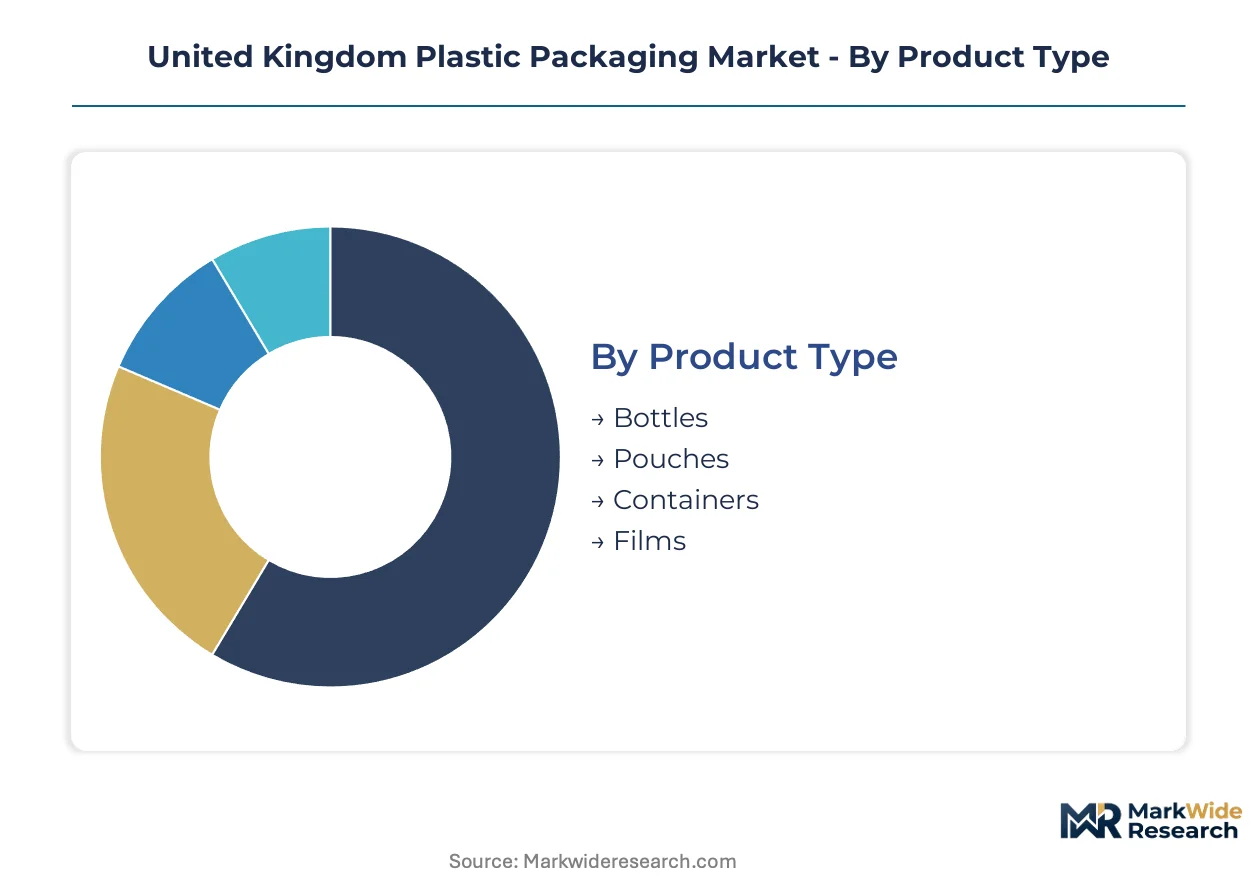
Segmentation reveals how UK converters allocate capital across formats and processes under Plastic Packaging Tax pressure. Distinct technical requirements and compliance burdens separate high-margin pharmaceutical films from commoditized carrier bag extrusion.
Product Type:
After-sales technical service intensity varies sharply across formats, with complex multilayer structures demanding ongoing formulation support.
- Bottles:PET dominates carbonated beverage and personal care applications where clarity and CO₂ barrier performance are critical. Blow molding lines in England's Midlands corridor supply major grocery retailers with lightweighted formats that cut transport emissions.
- Pouches:Retortable polyethylene structures are displacing glass jars in ambient sauces and ready meals, though oxygen barrier limitations constrain penetration in ultra-sensitive applications.
- Containers:Thermoformed tubs serve dairy and fresh produce segments with short specification cycles and high volume turnover.
- Films:Stretch wrap and shrink formats operate on thin margins with minimal differentiation beyond gauge consistency.
Bottles hold the largest share; momentum sits with pouches.
End User:
Cost tier stratification separates premium healthcare barrier specifications from price-sensitive household chemical bulk formats.
- Food & Beverage:Grocery retailers drive mono-material adoption to meet Extended Producer Responsibility targets, with ambient shelf-stable categories leading format switches.
- Healthcare:Blister lidding and vial applications demand pharmaceutical-grade barrier performance and serialization-ready surfaces for track-and-trace compliance.
- Personal Care:Brand owners prioritize shelf-present sustainability credentials, accelerating direct sourcing of specified recycled content formulations.
- Household Products:Concentrated chemical resistance requirements favor HDPE bottles with established recycling stream compatibility.
Food & Beverage commands the greatest volume; healthcare offers the steepest margin expansion trajectory.
Material:
Volume concentration in polyethylene reflects its dominance in flexible formats and established mechanical recycling infrastructure.
- Polyethylene:LDPE and HDPE grades cover stretch wrap, carrier bags, and milk bottles, with post-consumer flake availability determining converter procurement strategies.
- Polypropylene:Clarified grades serve ready meal trays and caps where heat resistance exceeds polyethylene capabilities.
- PET:Bottle-grade resin leads carbonated soft drink and personal care clarity applications with established deposit-return collection economics.
- PVC:Pharmaceutical blister packs and medical tubing retain niche demand despite environmental pressure and limited recycling pathways.
Polyethylene represents the largest installed base; polypropylene is expanding most quickly in food service applications.
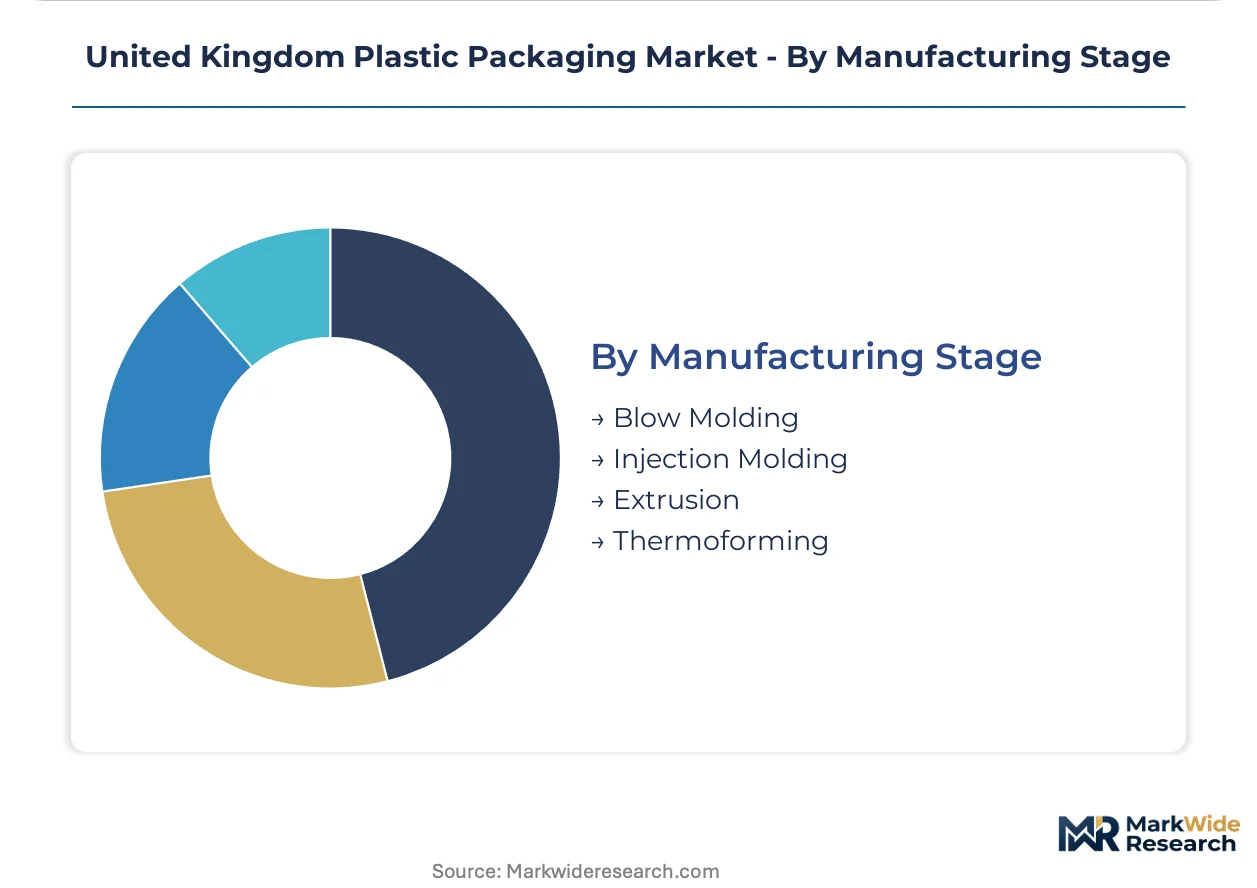
Manufacturing Stage:
Customer type segmentation separates brand-direct specification relationships from distributor-mediated commodity procurement.
- Blow Molding:Hollow container production serves beverage and household chemical segments with high output rates and limited customization.
- Injection Molding:Precision closures and healthcare vials demand tight tolerance control and cleanroom-capable facilities concentrated in Yorkshire.
- Extrusion:Blown film lines supply retail and industrial flexible formats, with post-consumer resin handling capability becoming a competitive differentiator.
- Thermoforming:Sheet-fed and roll-fed processes produce dairy tubs and produce trays with rapid tool changeover for seasonal volume spikes.
Extrusion maintains the broadest installed capacity; injection molding captures the highest value per kilogram processed.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food and beverage brand procurement teams concentrate purchasing power across England's industrial corridors, driving converter investment toward recycled-content film capacity and mono-material format development.
England Midlands
Blown film extruders and thermoformers cluster along the M1 and M6 corridors to serve grocery retail distribution networks. The UK Environment Agency enforces Plastic Packaging Tax compliance thresholds that mandate minimum recycled content documentation. Birmingham and Leicester host dense concentrations of polyethylene processing lines where converters retrofit equipment for post-consumer resin handling.
Scotland
Whisky and seafood exporters drive demand for high-barrier flexible formats and rigid containers with extended shelf-life performance. Scottish Environment Protection Agency regulations align with UK REACH chemical safety frameworks for food-contact applications. Glasgow and Edinburgh conversion facilities specialize in pharmaceutical-grade barrier films and healthcare packaging serialization.
Wales
Manufacturing supply chains serving automotive and industrial sectors sustain demand for durable transit packaging and protective films. Natural Resources Wales administers waste permitting that affects post-consumer collection infrastructure development. South Wales valleys retain polymer compounding capacity now repurposing toward recycled content masterbatch production for flexible formats.
Northern England
Yorkshire and Lancashire offer underutilized industrial real estate suitable for post-consumer resin upgrading and specialty film manufacturing. UK Environment Agency permitting processes govern new extrusion line installations and emissions compliance. Manchester and Leeds corridors attract converters seeking lower operational costs than Southeast England while maintaining access to retail distribution networks.
London and Southeast
Brand headquarters and procurement functions concentrate specification authority for national retail chains and export-oriented food processors. Greater London Authority waste strategies influence packaging design requirements for municipal collection compatibility. Kent and Essex host import-dependent distribution hubs where converters face pressure to demonstrate recycled content verification for major grocery contracts.
United Kingdom Plastic Packaging Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. Berry Global Group and Amcor plc anchor consolidated positions through scale-driven supply relationships with major grocery retailers. Mondi plc exemplifies the integrated paper-plastic hybrid specialist archetype. Smurfit WestRock represents the fiber-based packaging conglomerate expanding into plastic substitution formats. Competitive moves concentrate on recycled content supply chain reconstruction and mono-material film line investments rather than capacity expansion.
Among UK-based converters, Charpak Limited and Coral Products PLC occupy mid-market positions serving regional food processors and industrial customers with specification-flexible production runs. Fusion Group Limited exemplifies the specialist fabricator archetype focused on technical barrier applications. Coveris Holdings S.A. and Plastipak represent multinational platform operators leveraging pan-European resin procurement networks. These named entities anchor competitive dynamics without dominating market structure, as fragmented regional converters retain share in short-run and customized format segments.
| Leading Market Players |
|---|
| Berry Global Group |
| Charpak Limited |
| Amcor plc |
| Fusion Group Limited |
| Coral Products PLC |
| Mondi plc |
| Coveris Holdings S.A. |
| Plastipak |
| Smurfit WestRock |
| Others |
Value Network & Pricing Analysis
Idle blown film capacity in England's East Midlands is pressuring converters to accept thinner margins on commodity stretch wrap while simultaneously forcing investment in post-consumer resin handling equipment that commands premium pricing from sustainability-focused grocery retailers.
Pricing Analysis
Cost-plus contracts indexed to ICIS polyethylene assessments dominate procurement between major compounders and Midlands-based extruders. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade barrier films with UK REACH food-contact certification from industrial stretch wrap and thin-gauge carrier bags. Pricing pressure stems from post-consumer flake trading at volatile premiums to virgin polymer, compressing converter margins on recycled-content mandates. Food and beverage brand procurement teams exhibit highest price sensitivity, while healthcare specification engineers prioritize barrier performance over unit cost.
Supply Chain Analysis
Tariff exposure between the United Kingdom and European Union member states dominates supply chain risk planning for resin importers dependent on Rotterdam-Antwerp petrochemical hubs. Raw material sourcing draws from Saudi Arabian ethylene crackers, Belgian polymerization facilities, and domestic Teesside steam crackers operating at reduced rates. Single-source mechanical recycling dependence on Netherlands and German reprocessing facilities creates vulnerability to cross-border regulatory friction. Distribution runs through Midlands consolidation hubs serving grocery retail distribution centers with just-in-time replenishment schedules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across England's regional converter base creates acquisition targets as Extended Producer Responsibility schemes force smaller players toward compliance investments they cannot finance independently.
For Market Incumbents: Harden market position by acquiring Yorkshire-based injection molding capacity with cleanroom certification for pharmaceutical serialization integration. Backward integration into post-consumer resin compounding secures supply chain control against flake price volatility from Netherlands reprocessors. Prioritize mono-material film line retrofits in Birmingham corridor facilities to defend share against Mondi's kraft-paper hybrid substitution. For New Entrants and Emerging Players: Build out digital printing capabilities serving Scotland and Wales private-label seasonal ranges where plate changeover costs block incumbent flexibility. Northern England's underutilized polymer compounding infrastructure offers lowest-cost entry for specialty masterbatch production targeting personal care sustainability credentials. Lead with direct sourcing relationships that bypass distributor markups on specified recycled content formulations. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pharmaceutical barrier film specialists with multi-year serialization contracts and technical service bundling. Five-to-ten year viability favors converters with demonstrated UK Environment Agency audit compliance and verified mass balance documentation. Track inflection through major grocery retailer contract renewal cycles where third-party recycled content certification becomes mandatory for supplier retention.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Consumer Resin Integration | UK Environment Agency tax compliance requires minimum recycled content thresholds with audited mass balance documentation. |
| Mono-Material Film Line Investment | Extended Producer Responsibility targets drive mechanical recycling compatibility for grocery retail distribution networks. |
| Pharmaceutical Serialization Partnership | Track-and-trace mandates create demand for barrier films with integrated printed electronics authentication layers. |
| Digital Watermark Deployment | AI-enabled near-infrared sorting improves post-consumer stream purity for food-contact resin applications. |
| Regional Compounding Acquisition | South Wales masterbatch capacity repurposes toward recycled content upgrading for flexible format converters. |
Research Methodology
Desk research of UK Environment Agency regulatory filings, ICIS polymer price assessments, and British Standards Institution certification databases preceded structured interviews with blown film plant managers, grocery retail packaging procurement leads, pharmaceutical barrier film specification engineers, and post-consumer resin compounder technical directors. Primary fieldwork across England's Midlands corridor and Scottish conversion facilities was cross-validated against secondary trade flow data and UK REACH compliance documentation. Bottom-up capacity estimates from individual extrusion line audits were triangulated against top-down resin consumption figures from customs records.
Assumptions around UK Plastic Packaging Tax threshold enforcement intensity and Extended Producer Responsibility implementation timelines were held fixed across baseline scenarios, while post-consumer resin price volatility and chemical recycling capacity development in continental Europe were varied in sensitivity testing. Segmentation modeling incorporated product type, end-use industry vertical, material grade, and manufacturing process dimensions alongside regional regulatory cluster differentiation. CAGRs were derived from installed capacity utilization trends and format substitution elasticity estimates, with pharmaceutical serialization mandates and deposit-return system legislation treated as demand-shaping inputs.
Stress conditions across recycled resin availability, cross-border tariff regimes, and UK REACH evaluation timelines were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement consistency and mechanical recycling yield rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Polyethylene Corrugated Packaging Market
Plastic Packaging
Plastic Carboy Market
Plastic Packaging
Blow Molded Plastic Bottles Market
Plastic Packaging
France Plastic Bottles Market
Plastic Packaging
Saudi Arabia Plastic Packaging Market
Plastic Packaging
Europe BPA Free Plastic Market
Plastic Packaging
Europe Personal Care Plastic Tube Packaging Market
Plastic Packaging
Asia Pacific Plastic Bottles Market
Plastic Packaging
Corrugated Plastic Trays Market
Plastic Packaging
South Africa Rigid Plastic Packaging Market
Plastic Packaging
Plastic Ampoules Market
Plastic Packaging
Plastic Jar Packaging Market
Plastic Packaging
GCC PET Packaging Market
Plastic Packaging
Plastic Lab Totes Market
Plastic Packaging
Plastic Aerosol Packaging Market
Plastic Packaging
Polyethylene Terephthalate (PET) Market