
 United States Animal Feed Additives Market | 2026-2036
United States Animal Feed Additives Market Size, Share, and Industry Trends Forecast 2026-2036
United States Animal Feed Additives Market Insights
Multi-source procurement for active ingredients is pivoting as compounders seek supply security amid input volatility. Cargill Incorporated leverages its integrated nutrition platform to control formulation-to-farm distribution. DSM-Firmenich anchors its position through precision premix services and premix-to-feed mill partnerships. BASF competes on synthetic vitamin scale, while Evonik Industries specializes in amino acid biotechnology for swine and poultry ration optimization.
Animal feed additives comprise biologically active substances including enzymes, probiotics, antioxidants, and amino acids incorporated at parts-per-million to grams-per-ton inclusion rates to enhance feed conversion efficiency, gut health, and nutrient bioavailability in livestock production systems. Amino acids and enzymes command the largest product type positions due to their quantifiable return on feed cost in monogastric diets. Poultry application leads volume consumption, though aquaculture represents the fastest-growing demand pool as domestic catfish and salmonid operations intensify. Liquid formulations gain share in automated dosing systems, while powder and granular forms retain dominance in on-farm mixing operations across midwestern feed mills.
The FDA's Veterinary Feed Directive and EPA nutrient management oversight shape product registration pathways and on-farm usage documentation requirements for medicated and non-medicated additives alike. USDA Organic standards and state-level nutrient trading programs in the Chesapeake Bay watershed further constrain formulation choices for producers serving premium supply chains. Stakeholders must monitor pending FDA guidance on live microbial products and state-level phosphorus index regulations that will determine next-generation enzyme adoption thresholds.
Market Dynamics
The FDA's Veterinary Feed Directive has compressed antibiotic usage windows while EPA nutrient management rules in Chesapeake Bay watershed states are forcing phosphorus reformulation across swine and poultry operations.
Growth Catalysts
- Enzyme biotechnology maturation:Phytase and carbohydrase inclusion rates now deliver quantifiable feed conversion improvements in Iowa and North Carolina integrator operations, replacing mineral phosphate supplements.
- USDA Organic certification expansion:Premium supply chain requirements in California and Pacific Northwest dairy systems are mandating probiotic and botanical additive protocols that command formulation premiums.
- State-level nutrient trading programs:Maryland and Virginia phosphorus credit markets create direct economic incentives for enzyme adoption in watershed-constrained poultry operations.
Market Restraints
- Synthetic vitamin input volatility:Petrochemical feedstock fluctuations and Chinese precursor supply concentration create margin compression for domestic vitamin A and E compounders.
- Live microbial product stability limits:Probiotic viability through pelleting temperatures and storage duration constrains inclusion rates in commercial feed mill thermal processing.
- FDA live microbial guidance uncertainty:Pending regulatory categorization of direct-fed microbials as drugs versus feed additives creates registration timeline risk and capital allocation hesitation.
Strategic Opportunities
- Aquaculture intensification:Domestic catfish operations in Mississippi Delta and salmonid recirculating systems in Idaho represent underpenetrated species segments for amino acid and enzyme formulations.
- Automated liquid dosing systems:Precision delivery infrastructure at commercial feed mills enables real-time enzyme adjustment based on grain metabolizable energy variability.
- Conservation Reserve Program alignment:USDA environmental quality incentives for reduced nutrient runoff create co-funding pathways for enzyme and phytase adoption in contract grower networks.
Industry Challenges
- Microbiome science talent scarcity:Strain selection and host-specific efficacy validation require specialized fermentation and gastrointestinal physiology expertise that outpaces university pipeline output.
- Multi-state registration coordination:Individual state feed control official requirements for product licensing create administrative burden for national distribution of novel additive categories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Animal Feed Additives Market |
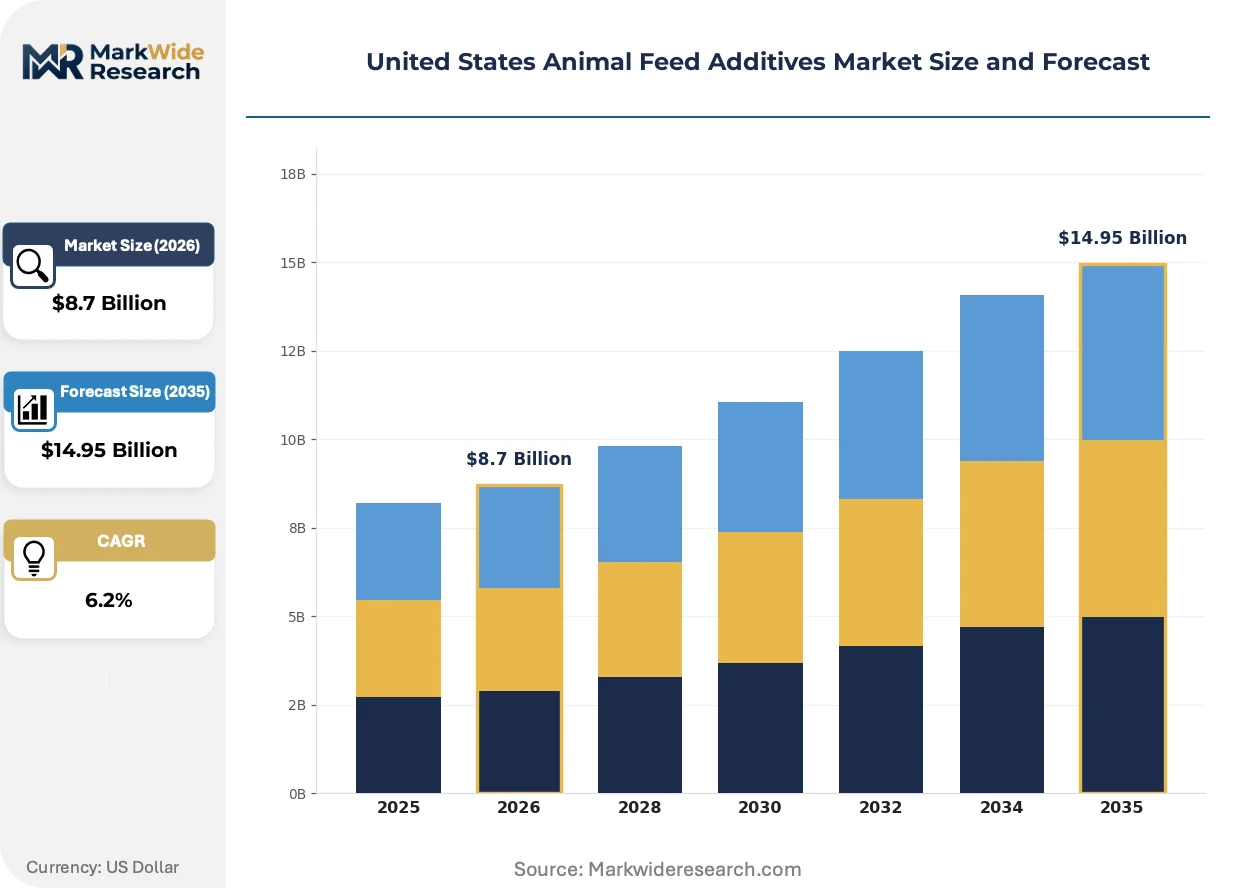
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.95 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antioxidants, Probiotics, Enzymes, Amino Acids Application: Poultry, Swine, Ruminants, Aquaculture Form: Liquid, Powder, Granular, Pellet Distribution Channel: Online Retail, Distributors, Direct Sales, Feed Stores |
| Companies Covered | Archer Daniels Midland Company, Cargill Incorporated, DSM-Firmenich, Adisseo, Nutreco, Land O'Lakes, BASF, Evonik Industries, Kemin Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Animal Feed Additives Market Trends and Innovations
Digital feed formulation platforms are compressing the cycle between laboratory efficacy data and on-farm inclusion rate adjustments, collapsing traditional trial-to-adoption timelines in vertically integrated operations.
Precision microbiome modulation is unifying genomic screening of host intestinal populations with strain-specific probiotic design. Large poultry integrators in the Southeast are deploying this approach within 18-month product refresh cycles. The technology is unifying formerly separate veterinary and nutrition decision workflows into single-platform management.
EPA Chesapeake Bay Total Maximum Daily Load enforcement is tightening phosphorus discharge permits for Maryland and Virginia poultry operations. This industrial consequence is accelerating phytase superdosing protocols and alternative mineral source evaluation. Layer operations in Delmarva are responding with 500-700 FTU per kilogram inclusion rates that exceed standard nutritional requirements.
Integrator procurement consolidation is compressing supplier qualification timelines and demanding outcome-guaranteed additive contracts. Midwestern feed mills serving independent pork producers are losing volume to captive supply arrangements with national compounders. This pattern is most visible in Iowa where three integrators control over sixty percent of state finishing capacity.
United States Animal Feed Additives Market Segmentation
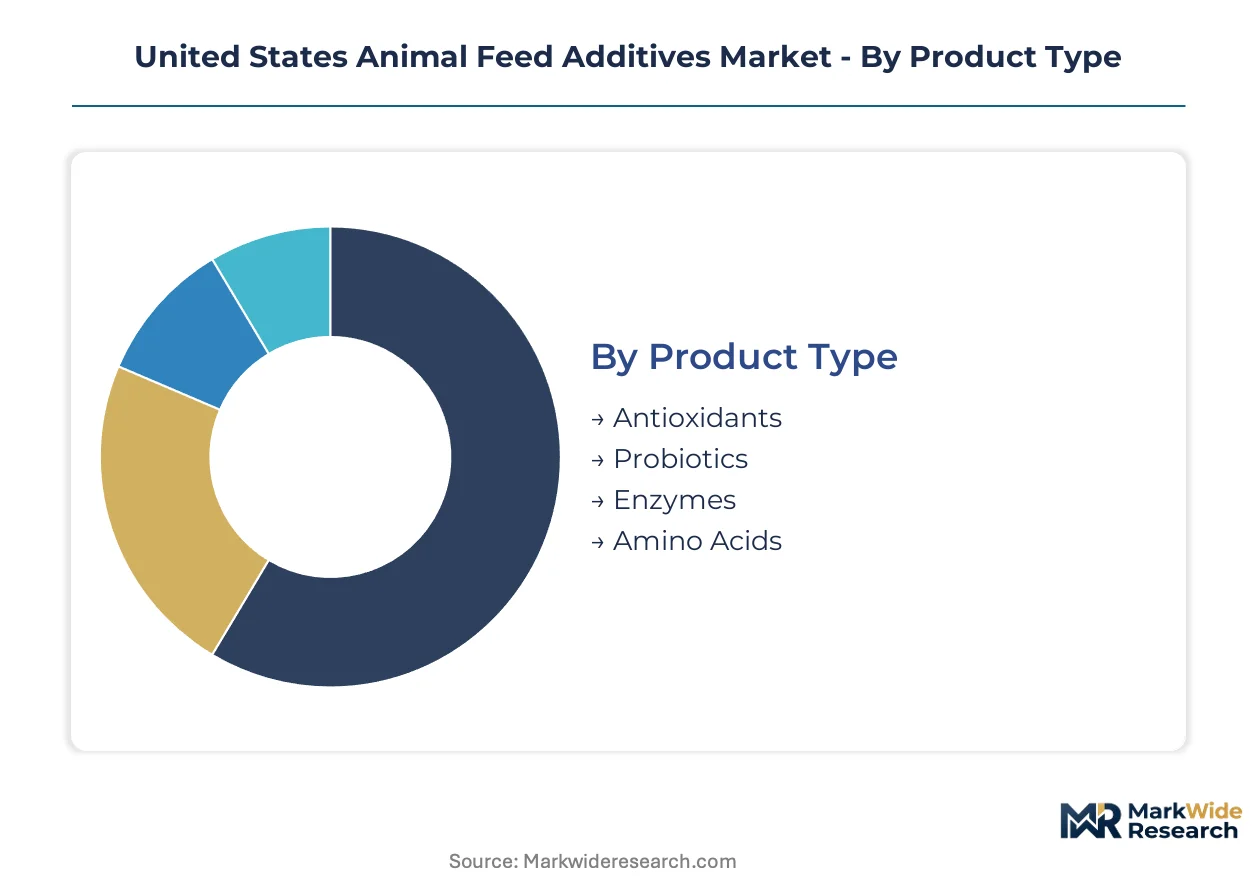
Feed additive segmentation in the United States reveals how capital deployment, regulatory exposure, and species-specific nutrition science intersect. Distinct procurement patterns emerge across product categories, with vertically integrated operations driving volume concentration in specific segments while independent producers sustain fragmented demand pools.
Product Type:
Capital intensity varies sharply across product categories, with biotechnology-derived segments requiring fermentation infrastructure and strain development pipelines that demand sustained R&D commitment.
- Enzymes:Phytase and carbohydrase formulations require precision fermentation capacity and thermostability engineering for pelleting survival. Demand concentrates in Iowa and North Carolina pork and poultry integrators where feed conversion efficiency directly contracts with procurement pricing.
- Amino Acids:Lysine, methionine, and threonine production depends on Corynebacterium glutamicum fermentation at industrial scale. Synthetic biology advances are displacing traditional extraction methods in domestic manufacturing facilities.
- Probiotics:Direct-fed microbials face viability constraints through thermal processing and gastric passage.
- Antioxidants:Ethoxyquin and BHT formulations serve fat preservation in rendered ingredient streams.
Most installed capacity flows through enzymes. Expansion is steepest in probiotics as FDA live microbial guidance clarity approaches.
Application:
Species-specific digestive physiology dictates formulation complexity and regulatory oversight intensity, with monogastric applications commanding stricter nutrient density management than ruminant systems.
- Poultry:Broiler and layer operations drive phytase superdosing adoption in the Southeast, where EPA Chesapeake Bay phosphorus regulations force 500-700 FTU per kilogram inclusion rates exceeding standard nutritional matrices.
- Swine:Nursery and grow-finish phases in Iowa and North Carolina integrate synthetic amino acids and acidifiers to reduce soybean meal dependency and manage post-weaning gut health transitions.
- Ruminants:Dairy systems in California and Wisconsin deploy ionophores and yeast cultures for rumen fermentation modulation.
- Aquaculture:Domestic catfish operations in the Mississippi Delta and Idaho salmonid recirculating systems represent underpenetrated demand for species-specific amino acid formulations.
Volume concentration sits with poultry. Aquaculture climbs the fastest as domestic protein production intensifies.
Form:
Processing technology compatibility and dosing precision requirements create divergent capital allocation patterns across physical delivery systems.
- Powder:Standard inclusion in on-farm mixing operations across midwestern feed mills where batch consistency depends on manual or mechanical dispersion.
- Liquid:Automated dosing systems at commercial feed mills enable real-time enzyme adjustment based on grain metabolizable energy variability, requiring precision pump infrastructure and tank farm investment.
- Granular:Flowability optimization for bulk handling systems in large integrator feed mills.
- Pellet:Pre-formed inclusion for specific species rations with reduced dust generation.
Powder retains dominant share. Liquid gains share fastest as mill automation accelerates.
Distribution Channel:
Customer scale and technical service requirements fragment channel economics, with national compounders capturing integrator volume while regional distributors serve independent producer networks.
- Direct Sales:National compounders maintain captive supply arrangements with Iowa and North Carolina integrators controlling majority state finishing capacity, embedding formulation scientists within customer operations.
- Distributors:Regional warehouse networks serve independent pork producers in the Midwest with technical support and inventory financing.
- Feed Stores:Local retail points supply hobby farms and small-scale livestock operations with packaged additives.
- Online Retail:E-commerce platforms penetrate hobbyist and specialty producer segments with limited technical service attachment.
Direct sales command largest volume flow. Online retail expands most quickly in hobby farm segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Producers are relocating formulation operations toward states with weaker phosphorus discharge enforcement, creating a cost-of-compliance arbitrage that reshapes procurement geography. The EPA's Chesapeake Bay Total Maximum Daily Load rules have compressed margins in Maryland and Virginia while Iowa and North Carolina attract volume through integrator concentration. State-level nutrient trading programs now determine enzyme adoption economics across watershed boundaries.
Iowa
Pork integrators command over sixty percent of state finishing capacity, driving synthetic amino acid and acidifier procurement at scale. The state's nutrient management rules remain less stringent than Chesapeake Bay watershed standards, attracting contract grower networks seeking compliance cost relief. Des Moines and Sioux City anchor feed mill automation investments serving captive supply arrangements with national compounders.
North Carolina
Vertically integrated poultry operations generate concentrated demand for phytase superdosing and probiotic protocols. State-level phosphorus regulations lag behind Maryland and Virginia, though coastal watershed rules are tightening. The Research Triangle hosts fermentation research partnerships linking university microbiome programs to integrator product development cycles.
California
Premium dairy supply chains mandate USDA Organic certification, requiring probiotic and botanical additive protocols that command formulation premiums. The state's Central Valley air quality regulations constrain feed mill expansion, pushing procurement toward out-of-state compounders. Fresno and Tulare counties concentrate organic transition investments as processors lock in certified milk supply.
Maryland and Virginia
EPA Chesapeake Bay enforcement has forced 500-700 FTU per kilogram phytase inclusion rates exceeding standard nutritional matrices. State nutrient trading programs create direct economic incentives for enzyme adoption in Delmarva poultry operations. Salisbury and Harrisonburg feed mills are retrofitting liquid dosing infrastructure to manage superdosing precision requirements.
Idaho
Salmonid recirculating aquaculture systems represent underpenetrated demand for species-specific amino acid formulations. State water rights regulations favor closed-containment operations that intensify feed additive precision requirements. Twin Falls anchors aquaculture biotechnology clustering as domestic protein production scales beyond traditional capture fisheries.
United States Animal Feed Additives Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue microbiome modulation and precision fermentation niches. The market structures around three tiers: integrated nutrition platforms controlling formulation-to-farm distribution, synthetic biology specialists commanding amino acid scale, and regional premix compounders serving independent producer networks. Strategic archetypes include captive supply arrangers, precision service providers, and commodity vitamin manufacturers. Consolidation pressures favor backward integration into strain development and forward integration into on-farm technical service.
Among integrated nutrition platforms, Cargill Incorporated exemplifies the captive supply model through control of formulation-to-farm distribution. DSM-Firmenich represents the precision service archetype, anchoring market position through premix-to-feed mill partnerships. BASF occupies the commodity scale tier, competing on synthetic vitamin manufacturing scope. These three entities illustrate how capital deployment patterns fragment across biotechnology intensity, geographic coverage, and customer scale specialization.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Incorporated |
| DSM-Firmenich |
| Adisseo |
| Nutreco |
| Land O'Lakes |
| BASF |
| Evonik Industries |
| Kemin Industries |
| Others |
Pricing and Supply Chain Analysis
Captive supply arrangements between national compounders and Iowa-North Carolina integrators anchor both procurement leverage and formulation pricing power across the United States animal feed additives market. This integration pattern compresses distributor margins while elevating outcome-based contract premiums for enzyme and probiotic protocols.
Pricing Analysis
Distributor margin compression runs through midwestern feed mills serving independent pork producers as captive direct sales capture volume. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with USDA Organic protocols commanding formulation premiums. Cost compression in synthetic vitamins is intensifying because Chinese precursor supply concentration creates input volatility. Independent producers exhibit highest price sensitivity, while vertically integrated poultry operations prioritize feed conversion returns over unit cost.
Supply Chain Analysis
Domestic-content mandates under USDA Organic standards and state-level nutrient trading programs are reshaping sourcing toward domestic fermentation capacity and verified supply chains. Manufacturing concentrates in the United States, China, and the Netherlands for amino acid fermentation infrastructure. Raw material dependencies include petrochemical feedstocks for synthetic vitamins, agricultural substrates for fermentation, and mineral phosphate sources. Single-source vulnerability in Chinese vitamin precursor supply creates structural risk. Distribution runs through direct sales to integrators and regional distributor networks to independent producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States animal feed additives market offers margin-expansion pathways through precision microbiome modulation premiums and enzyme superdosing protocols that reduce mineral phosphate dependency.
For Market Incumbents: Hedge against FDA live microbial guidance uncertainty by diversifying registration pipelines across enzyme and amino acid categories while building captive fermentation capacity in Iowa and North Carolina. Invest in thermostability engineering to address probiotic viability constraints through pelleting temperatures. Secure strain development partnerships with Research Triangle microbiome programs to outpace university pipeline limitations. For New Entrants and Emerging Players: Precision fermentation platforms for species-specific aquaculture formulations offer a technology-first wedge into underpenetrated Idaho salmonid and Mississippi Delta catfish operations. Target automated liquid dosing infrastructure at commercial feed mills seeking real-time enzyme adjustment capabilities. Pursue co-funding alignment with USDA Conservation Reserve Program incentives for nutrient runoff reduction. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-state registration coordination burdens constrain national distribution of novel additive categories. Long-term viability favors backward integration into strain development and forward integration into on-farm technical service. Acquisition targets include regional premix compounders with embedded relationships in independent producer networks. Watch FDA guidance clarity on live microbial categorization as the inflection indicator for capital allocation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Expansion | Domestic Corynebacterium glutamicum facilities reduce Chinese amino acid precursor dependency. |
| Backward Integration into Strain Development | In-house microbiome screening accelerates probiotic product refresh cycles for poultry integrators. |
| USDA Organic Certification Investment | Premium supply chain access in California Central Valley commands formulation price premiums. |
| Automated Liquid Dosing Infrastructure | Real-time enzyme adjustment at commercial feed mills captures grain metabolizable energy variability. |
| Conservation Reserve Program Alignment | Co-funding pathways for enzyme adoption reduce contract grower network nutrient compliance costs. |
Research Methodology
Direct dialogue with feed mill operations managers, integrator procurement directors, fermentation research scientists, state feed control officials, and USDA regulatory affairs specialists grounded the qualitative foundation. Secondary validation drew from FDA Veterinary Feed Directive filings, EPA Chesapeake Bay Total Maximum Daily Load enforcement records, USDA Organic certification databases, and state nutrient trading program transaction logs. Bottom-up volume triangulation across product categories reconciled with top-down market sizing.
Segment-level outputs across enzymes, amino acids, probiotics, and antioxidants by species application and formulation form were generated across the analysis window. CAGRs were derived from regression analysis against feed conversion efficiency benchmarks and regulatory adoption curves. Modeled inputs included integrator capacity expansion pipelines, state phosphorus index regulation timelines, and precision fermentation technology maturation rates.
The model holds under continued FDA enforcement of antibiotic oversight and stable EPA Chesapeake Bay phosphorus discharge limits; deviation in live microbial regulatory categorization or watershed enforcement intensity would shift adoption trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biologicals
Edible Fungus Market
Agricultural Biologicals
Animal Feed Additives Market
Agricultural Biologicals
Africa Feed Enzymes Market
Agricultural Biologicals
Soil Inoculants Market
Agricultural Biologicals
Europe Agricultural Microbials Market
Agricultural Biologicals
Global Agricultural Inoculant Market
Agricultural Biologicals
Agricultural Microbials Market
Agricultural Biologicals
Agricultural Activator Adjuvants Market
Agricultural Biologicals
Asia Pacific Silage Inoculant Market
Agricultural Biologicals
Asia-Pacific Agricultural Microbial Market
Agricultural Biologicals
South America Agricultural Microbials Market
Agricultural Biologicals
North America Feed Prebiotics Market
Agricultural Biologicals
Agricultural Biofungicides Market
Agricultural Biologicals
Insect Feed Market
Agricultural Biologicals
South America Beta-Glucan Market
Agricultural Biologicals
South America Feed Mycotoxin Detoxifiers Market