
 South America Silage Inoculant Market | 2026-2036
South America Silage Inoculant Market Size, Share, and Industry Trends Forecast 2026-2036
South America Silage Inoculant Market Analytics
Project finance for on-farm fermentation equipment is fragmenting competitive access across South America. Cargill leverages its grain origination infrastructure to bundle inoculant supply with feed programs. Lallemand, Inc. anchors its position through specialized microbial strain libraries suited to tropical forage conditions. BASF competes via controlled-release formulation technology that extends product efficacy in variable climates.
Silage inoculants are live microbial preparations, typically containing lactic acid bacteria at concentrations exceeding 100,000 colony-forming units per gram, applied to chopped forage to accelerate acidification and preserve nutritional value for ruminant feed. Liquid formulations dominate volume sales due to ease of application through existing spray systems on large Brazilian operations, while powder formulations retain margin pools in smallholder segments where storage stability matters. Natural inoculants capture growing share as ANVISA scrutiny tightens on synthetic preservative residues in dairy supply chains.
ANVISA coordinates with Brazil's Ministry of Agriculture on feed additive registration timelines that determine product launch sequencing. Argentina's Senasa enforces import protocols for microbial strains that shape which suppliers gain market access. Stakeholders must monitor regulatory divergence between Mercosur harmonization talks and national implementation pathways.
Market Dynamics
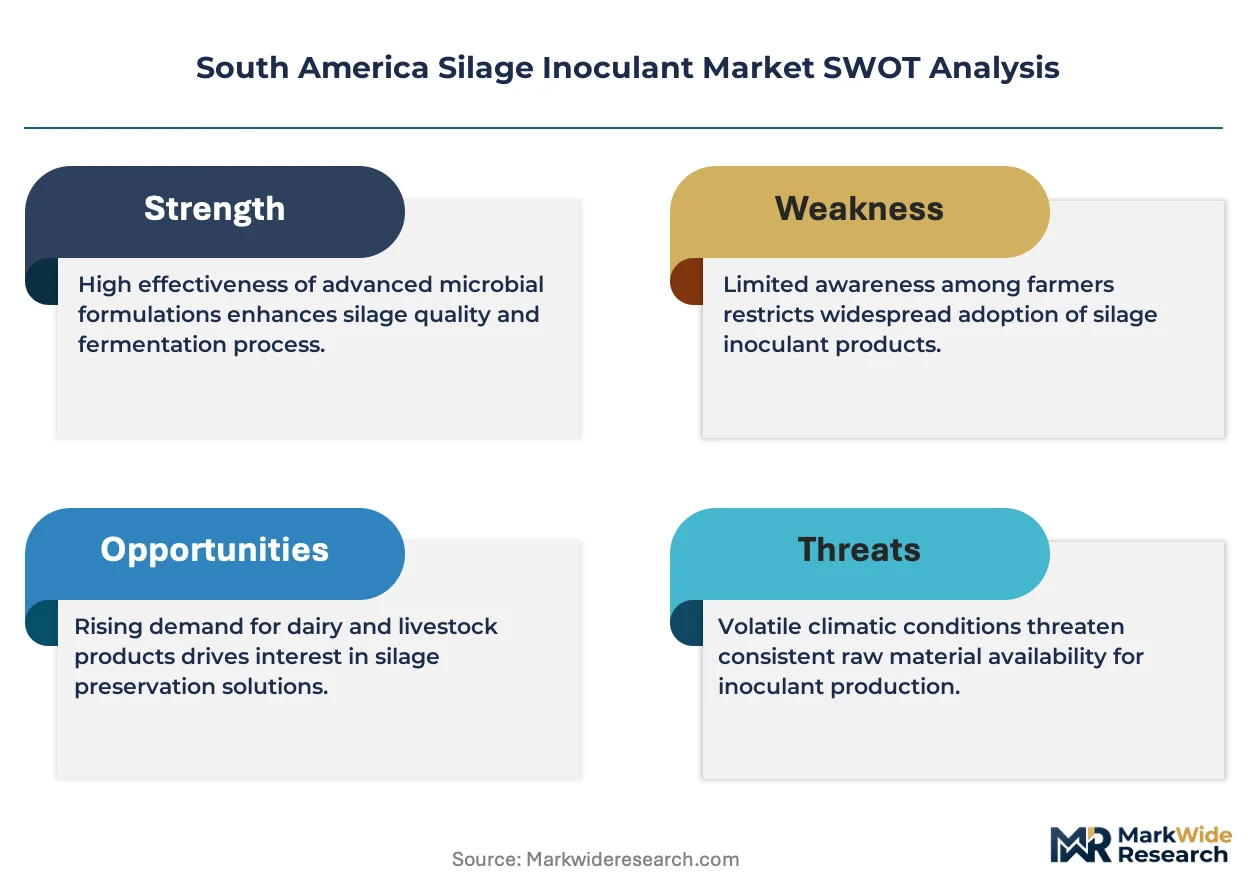
ANVISA's tightening scrutiny on synthetic preservative residues is compressing formulation choices across Brazilian dairy supply chains, forcing suppliers to revalidate microbial strain portfolios under evolving feed additive standards.
Growth Catalysts
- Natural inoculant demand:Brazil's southern dairy cooperatives are mandating residue-free preservation protocols, pulling procurement toward live microbial preparations certified under ANVISA's updated feed additive registry.
- ANVISA-Senasa coordination:Mercosur harmonization talks on microbial strain import protocols are reducing cross-border registration duplication, accelerating product launch sequencing for suppliers active in both Brazil and Argentina.
- Tropical forage adaptation:Specialized lactic acid bacteria strains engineered for high-temperature fermentation stability are penetrating Paraguayan and Uruguayan operations previously served by generic formulations.
Market Restraints
- Strain import friction:Argentina's Senasa enforces quarantine protocols for novel microbial isolates that extend validation timelines by 12-18 months, freezing supplier expansion into Buenos Aires province feed markets.
- Formulation cost volatility:Concentrated lactic acid bacteria cultures require temperature-controlled logistics chains that amplify working capital intensity for distributors serving Mato Grosso's remote cattle operations.
- Application equipment gaps:Smallholder segments in northeastern Brazil lack calibrated spray systems, forcing reliance on higher-cost powder formulations with inferior field efficacy.
Strategic Opportunities
- Paraguay market entry:Underpenetrated dairy sectors in Alto Paraná and Itapúa departments present first-mover advantages for suppliers bundling inoculant supply with technical advisory services.
- Controlled-release convergence:Integration of microencapsulation technology with tropical-adapted strains enables premium positioning for variable-climate efficacy claims in Colombia's emerging silage market.
- Cooperative procurement platforms:Brazil's southern dairy cooperatives are consolidating input purchasing through digital tender platforms, creating direct supplier access channels that bypass traditional distribution markups.
Industry Challenges
- Microbiologist talent scarcity:Fermentation science expertise concentrates in São Paulo and Porto Alegre research clusters, leaving field technical support understaffed across Argentina's Pampas expansion zones.
- Strain bank certification delays:ANVISA's microbial identity verification protocols require whole-genome sequencing documentation that stretches compliance timelines for novel product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Silage Inoculant Market |
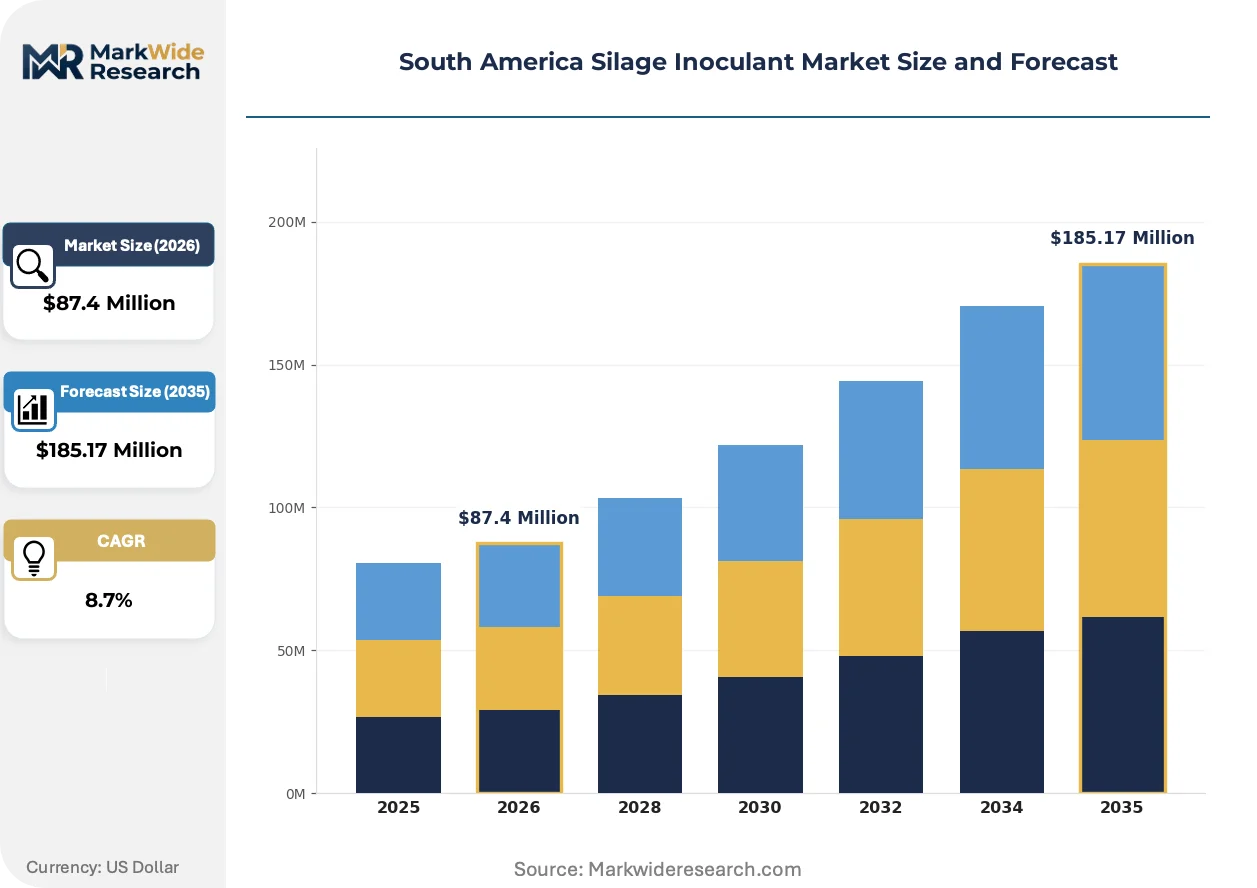
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $185.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Inoculants, Chemical Additives, Liquid Formulations, Powder Formulations Application: Dairy Cattle, Beef Cattle, Goats, Sheep Distribution Channel: Direct Sales, Online Retail, Agricultural Supply Stores, Cooperative Units Customer Type: Farmers, Distributors, Agricultural Companies, Consultants |
| Companies Covered | Kemin Industries, Chr. Hansen, Corteva Agriscience, Cargill, BASF, ADM, EW Group, FMC Corporation, Lallemand, Inc., Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Silage Inoculant Market Evolving Landscape
Formulation technology and procurement infrastructure are undergoing parallel transformation, with liquid application systems and residue-free certification protocols compressing traditional competitive advantages.
Microencapsulation technology is migrating from pharmaceutical adjuvant applications into silage inoculant formulations, shielding lactic acid bacteria from desiccation stress during tropical storage. Large Brazilian dairy operations in Paraná and Santa Catarina are piloting these formulations to reduce reapplication frequency. The technology is compressing margin pools for conventional liquid products by extending efficacy windows and reducing per-ton treatment costs.
ANVISA's 2023 feed additive registry overhaul introduced tiered safety assessment pathways for live microbial preparations, creating accelerated review tracks for strains with documented history of safe use. This regulatory architecture favors established suppliers with deep strain libraries over new entrants lacking multi-year safety dossiers. Brazilian dairy processors are now requiring ANVISA registration certificates as a procurement gate, filtering non-compliant imports from smaller Argentine suppliers.
Buyer consolidation through cooperative procurement platforms is disintermediating traditional agricultural input distributors across Brazil's southern states. Dairy cooperatives in Rio Grande do Sul are aggregating annual inoculant demand into single-tender contracts, compressing supplier margins while demanding bundled technical support services. This pattern is most visible in municipalities with high cooperative penetration, where independent farm-level purchasing has declined sharply over the past three seasons.
South America Silage Inoculant Market Segmentation
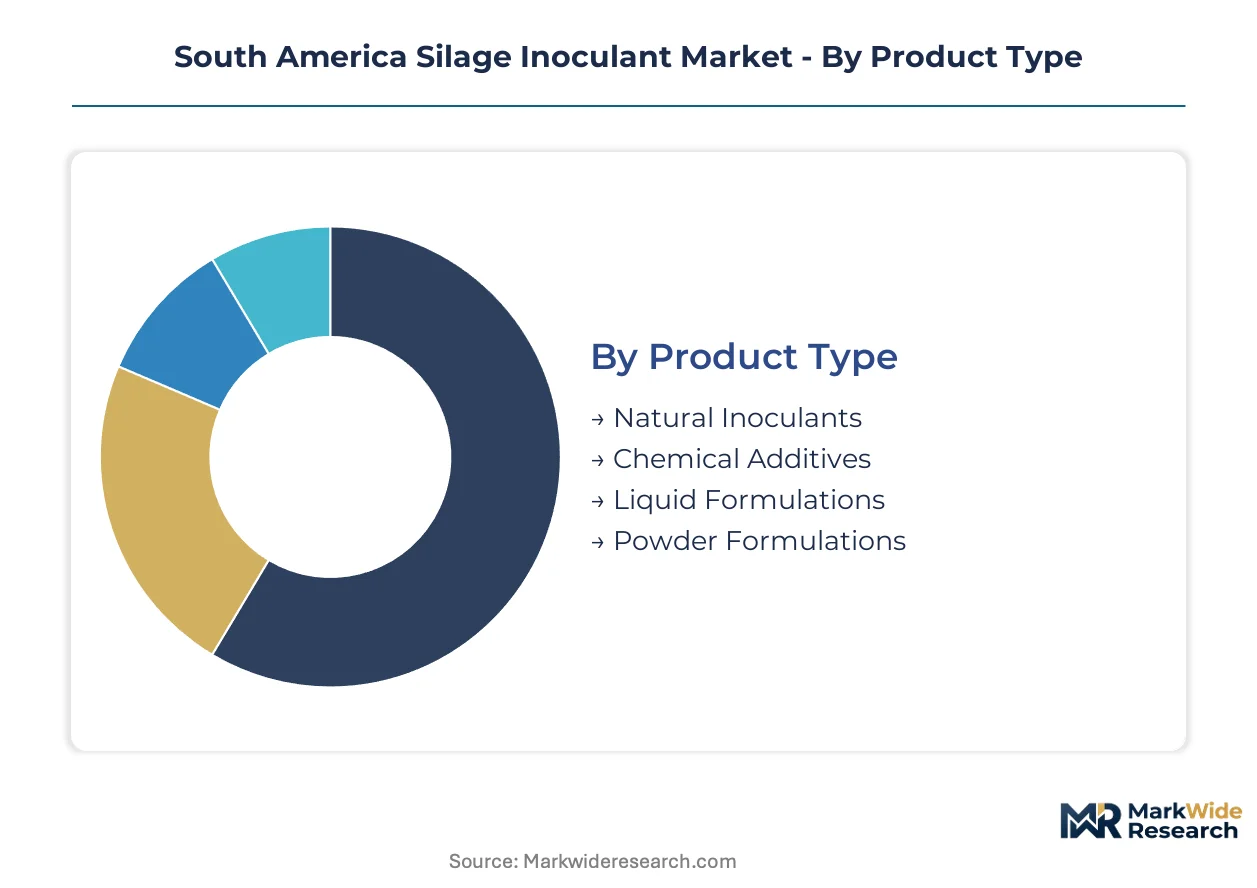
Silage inoculant procurement in South America fragments across four distinct dimensions, each shaping supplier engagement models and margin capture. Technical service intensity varies dramatically by product chemistry and livestock species served.
Product Type:
After-sales technical support requirements differ sharply between live microbial preparations and synthetic alternatives, with natural inoculants demanding sustained field advisory for fermentation monitoring.
- Liquid Formulations:These aqueous suspensions of lactic acid bacteria integrate directly into mechanical spray systems on large Brazilian dairy operations in Paraná and Santa Catarina. ANVISA registration certificates for live microbial strains are becoming mandatory procurement gates for southern cooperative buyers.
- Natural Inoculants:Comprising certified live cultures without synthetic preservative residues, these preparations command premium positioning as Brazilian dairy processors enforce residue-free protocols. Demand concentrates among Rio Grande do Sul cooperatives supplying export-oriented milk pools.
- Powder Formulations:Lyophilized bacterial cultures with extended ambient storage stability serve northeastern Brazilian smallholders lacking refrigerated distribution access.
- Chemical Additives:Synthetic acidification agents face contracting formulation space under tightening ANVISA residue scrutiny across Brazilian supply chains.
By volume, liquid formulations lead. By growth pace, natural inoculants are expanding most quickly.
Application:
Species-specific rumen microbiology drives divergent efficacy requirements, with dairy operations demanding higher fermentation precision than beef backgrounding systems.
- Dairy Cattle:High-producing Holstein herds in Brazil's southern states require stable lactic acid fermentation to preserve protein and energy density for milk yield optimization. ANVISA-registered live cultures are displacing generic formulations as processor residue standards tighten.
- Beef Cattle:Backgrounding and finishing operations across Mato Grosso and Argentina's Pampas prioritize dry matter preservation over nutrient density, accepting broader microbial strain tolerances.
- Sheep:Smaller flock sizes in Uruguay's wool-meat systems generate fragmented demand served through agricultural supply store networks rather than direct technical service.
- Goats:Specialty dairy goat operations in Brazil's Minas Gerais highlands represent a niche segment with limited dedicated inoculant formulation development.
Dairy cattle applications dominate revenue contribution. Beef cattle applications show steepest expansion trajectory as Brazilian feedlot capacity scales.
Distribution Channel:
Channel economics reflect customer scale and technical service bundling requirements, with cooperative procurement platforms compressing traditional distributor margins.
- Cooperative Units:Aggregated tender platforms across Rio Grande do Sul and Santa Catarina dairy cooperatives are consolidating annual inoculant demand into single-contract awards. Direct supplier access bypasses traditional agricultural input distribution markups while demanding bundled fermentation advisory.
- Direct Sales:Large integrated beef operations in Mato Grosso and Paraguayan cattle companies negotiate volume contracts with technical service riders for on-farm application training.
- Agricultural Supply Stores:Independent retail networks serve smallholder segments in northeastern Brazil with powder formulations and limited technical support.
- Online Retail:Emerging digital procurement channels are penetrating price-sensitive segments where standardized formulations require minimal advisory intervention.
Cooperative units capture the fastest-growing share. Agricultural supply stores retain the largest transaction volume.
Customer Type:
Buyer sophistication and technical staff availability determine service intensity and pricing tolerance across the customer base.
- Farmers:Direct purchasers range from technologically advanced southern Brazilian dairy cooperatives to resource-constrained northeastern smallholders with divergent formulation and service requirements.
- Distributors:Temperature-controlled logistics capabilities and fermentation science expertise concentrate among distributors serving Paraná and Santa Catarina, leaving Argentina's Pampas expansion zones understaffed.
- Agricultural Companies:Integrated crop-livestock operations in Mato Grosso bundle inoculant procurement with grain origination and feed supply contracts.
- Consultants:Independent nutrition advisors in Brazil's southern states influence strain selection decisions for mid-scale operations lacking in-house technical capacity.
Farmers represent the deepest volume pool. Consultants are gaining influence fastest as advisory outsourcing accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands premium pricing power across the South America silage inoculant market, while Argentine suppliers absorb margin compression from extended Senasa validation timelines. This asymmetry concentrates supplier investment in Brazil's southern dairy corridors.
Brazil
Paraná and Santa Catarina dairy cooperatives drive volume demand through consolidated tender platforms. ANVISA's 2023 feed additive registry overhaul mandates whole-genome sequencing documentation for novel microbial strains. São Paulo research clusters anchor strain development capabilities, while Rio Grande do Sul cooperatives enforce residue-free procurement protocols.
Argentina
Buenos Aires province feed markets attract supplier interest despite Senasa quarantine protocols stretching novel isolate validation to 18 months. The Pampas region's expanding cattle operations generate backgrounding demand with broader microbial tolerances. Córdoba's agricultural research institutes concentrate limited fermentation science expertise.
Paraguay
Alto Paraná and Itapúa departments present underpenetrated dairy sectors with first-mover positioning potential. The country's national agricultural regulator coordinates with Mercosur harmonization frameworks on microbial import standards. Asunción-based distributors lack temperature-controlled logistics infrastructure for concentrated bacterial cultures.
Uruguay
Wool-meat systems in central departments generate fragmented inoculant demand through agricultural supply store networks. Mercosur trade protocols facilitate Brazilian supplier access without duplicate registration requirements. Montevideo's limited technical service capacity constrains adoption of fermentation monitoring protocols.
Colombia
Emerging silage adoption in the Andean highlands creates demand for variable-climate efficacy claims. The country's national food and drug regulator applies evolving standards for live microbial feed additives. Bogotá's procurement channels remain underdeveloped for specialized inoculant distribution.
South America Silage Inoculant Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with strain libraries and formulation technology. The South America silage inoculant market structures around three tiers: multinational agribusiness conglomerates with grain origination infrastructure, specialized microbial technology firms with tropical-adapted strain banks, and regional distributors with temperature-controlled logistics capabilities. Competitive moves concentrate on bundling inoculant supply with feed programs, and on microencapsulation technology licensing for extended efficacy claims.
Among the specialized microbial technology tier, Lallemand, Inc. and Chr. Hansen occupy positions defined by live culture expertise and strain portfolio depth. Cargill represents the integrated agribusiness archetype, leveraging grain origination infrastructure for bundled supply relationships. BASF anchors the formulation technology vector through controlled-release capabilities. These three exemplify how competitive positioning fragments between biological asset control, supply chain integration, and delivery mechanism innovation.
| Leading Market Players |
|---|
| Kemin Industries |
| Chr. Hansen |
| Corteva Agriscience |
| Cargill |
| BASF |
| ADM |
| EW Group |
| FMC Corporation |
| Lallemand, Inc. |
| Others |
Value Network & Pricing Analysis
Strain library concentration in São Paulo and Porto Alegre research clusters feeds margin capture into ANVISA-registered formulation tiers, while temperature-controlled logistics costs in Mato Grosso and Argentina's Pampas compress distributor working capital returns.
Pricing Analysis
The customization-premium spread separates configured-to-order tropical strain formulations from standard liquid suspensions. Three-tier pricing structure across premium, standard, and economy levels tracks ANVISA registration status and bundled technical advisory intensity. Price differentiation hinges on whole-genome sequencing documentation and cooperative procurement scale. Cost compression in powder formulations serving northeastern smallholders is intensifying because spray equipment gaps force reliance on higher-cost, lower-efficacy alternatives. Dairy cooperatives in Rio Grande do Sul exhibit least price sensitivity; independent agricultural supply store purchasers in Paraguay show highest elasticity.
Supply Chain Analysis
Contract-manufacturing concentration for lactic acid bacteria cultures rests with Brazilian biotech foundries in São Paulo state and Argentine fermentation facilities in Buenos Aires province. Geographic supply concentration centers on Brazil, Argentina, and limited Paraguayan blending operations. Raw material dependencies include concentrated bacterial cultures, specialized growth media, and temperature-stable packaging substrates. Single-source vulnerability runs through ANVISA-certified strain banks with multi-year safety dossiers. Distribution runs through cooperative procurement platforms in southern Brazil, direct sales to integrated beef operations, and agricultural supply store networks for smallholder segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cooperative procurement platform economics in Brazil's southern dairy corridors marks a platform-economics inflection, with digital tender aggregation interoperability reshaping supplier access and margin compression dynamics.
For Market Incumbents: Build switching-cost moats through embedded fermentation monitoring telemetry and multi-year technical advisory contracts. Deepen strain library certification under ANVISA's accelerated review tracks to filter emerging Argentine competitors lacking multi-year safety dossiers. Add captive temperature-controlled logistics capacity in Mato Grosso to defend against distributor margin erosion from remote cattle operations. For New Entrants and Emerging Players: Build out technical advisory capabilities targeting Paraguay's Alto Paraná and Itapúa dairy sectors, where incumbent presence remains thin and cooperative procurement infrastructure is underdeveloped. Penetrate through bundled inoculant supply with on-farm fermentation training, leveraging Mercosur harmonization to bypass duplicate registration burdens faced by Brazilian entrants. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional distributors holding temperature-controlled logistics networks but lacking strain development capabilities. Long-term viability favors platforms integrating formulation technology with cooperative procurement access. Watch for ANVISA registration certificate requirements becoming mandatory procurement gates across Argentine dairy processors as harmonization pressure builds.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Library Expansion | Deepens ANVISA registration moats against competitors lacking multi-year safety dossiers. |
| Microencapsulation Licensing | Extends efficacy claims in Colombia's variable-climate Andean highlands expansion zones. |
| Cooperative Platform Integration | Bypasses traditional agricultural input distribution markups in Rio Grande do Sul tenders. |
| Tropical Strain Development | Captures Paraguayan and Uruguayan operations previously served by generic formulations. |
| Temperature-Controlled Logistics Buildout | Reduces working capital intensity for distributors serving remote Mato Grosso cattle operations. |
Research Methodology
A standing panel of fermentation science directors, dairy cooperative procurement managers, ANVISA regulatory affairs specialists, and agricultural supply store operators provided ongoing calibration. Primary interviews with these stakeholders combined with secondary validation from ANVISA feed additive registry filings, Senasa import protocol documentation, Mercosur harmonization frameworks, and Brazilian dairy cooperative annual reports. Bottom-up strain registration timelines and top-down cooperative procurement volume aggregation enabled triangulation.
Scenario-bracketing framed projections across the analysis window, modeling ANVISA regulatory acceleration against Senasa quarantine extension risks. Segmentation dimensions included formulation type, livestock species, distribution channel, and customer sophistication tier. CAGRs derived from cooperative tender volume trajectories and strain adoption curves in tropical versus temperate zones. Forecast inputs incorporated ANVISA registration pipeline velocity and cooperative procurement platform penetration rates.
Stress conditions across ANVISA-Senasa regulatory divergence, temperature-controlled logistics cost volatility, and cooperative procurement consolidation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding Mercosur harmonization progress and strain bank certification timelines. Quarterly review of ANVISA registration certificate procurement gate adoption and cooperative tender platform expansion is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Fungicides Market
Agricultural Chemicals
Middle East and Africa Agricultural Pheromones Market
Agricultural Chemicals
Middle East Feed Binders Market
Agricultural Chemicals
Feed Micronutrients Market
Agricultural Chemicals
Animal Feed Enzymes Market
Agricultural Chemicals
Philippines Feed Additives Market
Agricultural Chemicals
North America Herbicide Market
Agricultural Chemicals
North America Fungicide Market
Agricultural Chemicals
Triazole Fungicides Market
Agricultural Chemicals
Aquafeed Additives Market
Agricultural Chemicals
Feed Antibiotics Market
Agricultural Chemicals
North America Castor Oil Market
Agricultural Chemicals
Feed Preservatives Market
Agricultural Chemicals
North America Silage Additives Market
Agricultural Chemicals
GCC Feed Premix Market
Agricultural Chemicals
South America Soil Treatment Market