
 Chitosan for Agriculture Market | 2026-2036
Chitosan for Agriculture Market Size, Share, and Industry Trends Forecast 2026-2036
Chitosan for Agriculture Market Insights
The capital-intensity gap between integrated crustacean-waste processors and standalone biopolymer formulators is collapsing as fermentation-based production routes lower entry barriers. Primex ehf leverages its Icelandic marine biomass access to sustain vertical integration from raw material to finished agricultural grades. KitoZyme S.A. competes through fungal chitosan technology leadership, eliminating marine supply chain dependencies entirely. Zhejiang Golden-Shell Pharmaceutical Co. Ltd. anchors Asia-Pacific supply with coastal processing infrastructure and state-backed biorefinery investments.
Chitosan for agriculture comprises deacetylated chitin polysaccharides, typically 70-95% deacetylation, derived from crustacean shells or fungal mycelia through alkaline treatment and refined for film-forming, antimicrobial, and plant elicitor functions. Its primary purpose centers on crop protection, yield enhancement, and soil health restoration without synthetic chemical residues. Chitosan liquid formulations lead commercial volumes due to ease of tank-mixing with existing spray equipment, while chitosan oligosaccharides represent the fastest-expanding product class as precision agriculture demands lower-molecular-weight bioactive fractions. Seed treatment applications command premium positioning within the value chain, whereas soil amendment segments compete on volume scale and distributor relationships.
EPA biopesticide registration pathways and EU REACH compliance requirements shape product development timelines and cross-border market access for agricultural chitosan suppliers. China's NMPA and Ministry of Agriculture standards govern domestic quality thresholds and residue limits for biostimulant applications. India's FSSAI and Central Insecticides Board oversight extends to import clearance and local formulation approvals. Stakeholders must monitor regulatory divergence between biopesticide and biostimulant classification frameworks, as this distinction determines registration costs, label claims, and addressable farmer segments across priority markets.
Market Dynamics
Fermentation-based chitosan production is collapsing the capital-intensity gap between integrated crustacean processors and standalone biopolymer formulators, redrawing competitive boundaries across agricultural input supply chains.
Growth Catalysts
- EU F-Gas Regulation:The tightening phase-down schedule for fluorinated greenhouse gases is accelerating farmer substitution toward chitin-derived crop protection inputs across European vegetable and fruit operations.
- Precision agriculture adoption:Variable-rate application systems favor low-molecular-weight chitosan oligosaccharides that integrate cleanly with drone-mounted spray equipment and sensor-calibrated dosing.
- Shrimp processing waste concentration:Coastal biorefinery clusters in China, India, and Brazil secure feedstock-advantaged production positions for regional agricultural chitosan supply.
Market Restraints
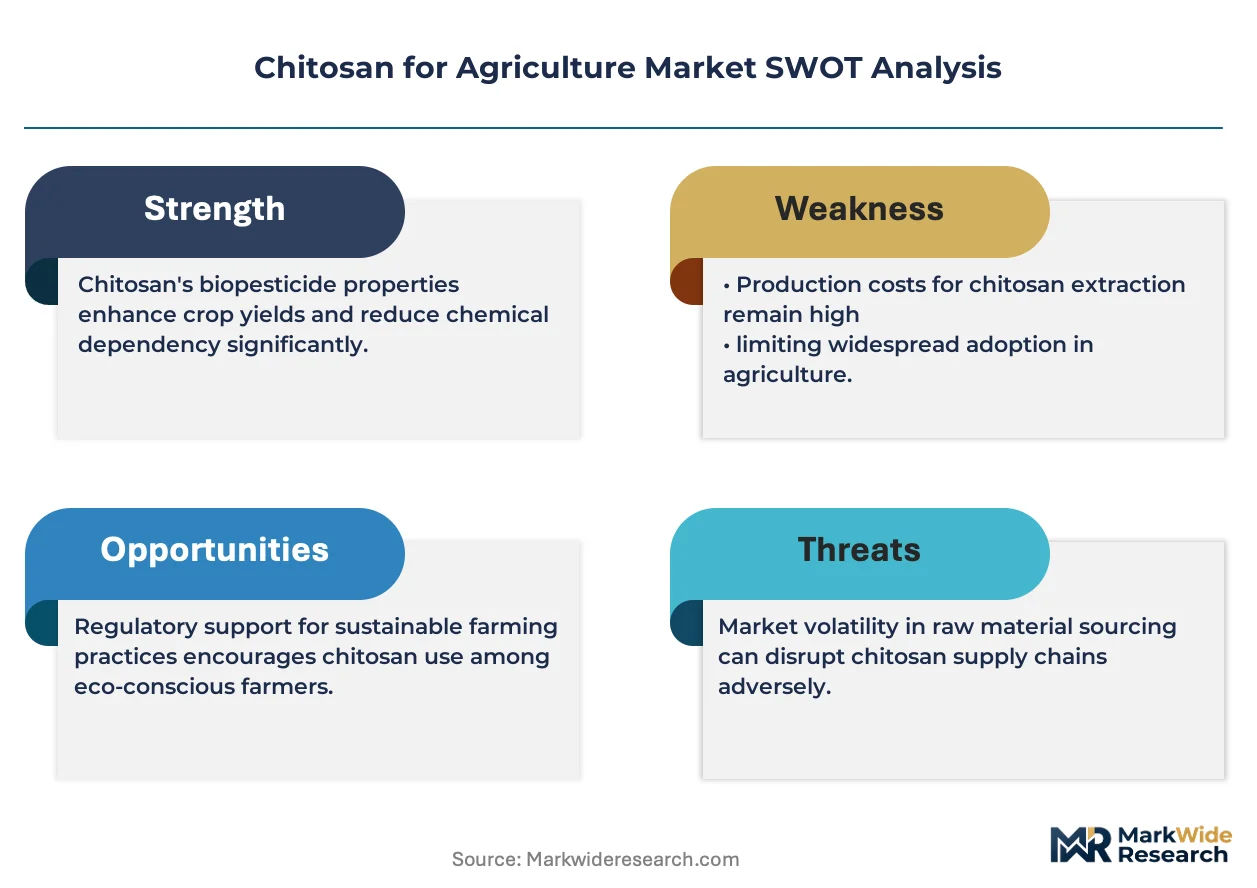
- Alkaline reagent cost volatility:Sodium hydroxide and potassium hydroxide price swings directly compress margins for crustacean-shell deacetylation processors without long-term chemical supply contracts.
- Marine supply chain concentration:Seasonal shrimp harvesting patterns and single-source coastal processing dependencies create raw material availability bottlenecks for non-integrated formulators.
- EPA registration timelines:Biopesticide pathway requirements extend product commercialization cycles by 24-36 months versus conventional chemical registration, delaying revenue recognition for novel chitosan active formulations.
Strategic Opportunities
- Biostimulant regulatory arbitrage:EU fertilizer regulation revisions and China's biostimulant standardization create faster market entry pathways than biopesticide classifications, enabling broader label claims.
- Fungal chitosan technology:Mycelium-derived production eliminates marine supply dependencies entirely, opening inland manufacturing locations without coastal feedstock access.
- Seed treatment premium positioning:Coating applications for high-value row crops command price multiples over bulk soil amendments, rewarding formulation sophistication and proprietary delivery system development.
Industry Challenges
- Deacetylation degree standardization:Inconsistent 70-95% deacetylation specifications across NMPA, EPA, and EFSA jurisdictions complicate cross-border product registration and manufacturing scale economics.
- Formulation-tank compatibility testing:Agricultural distributors demand extensive compatibility validation against existing pesticide and fertilizer portfolios, extending technical service requirements and customer acquisition costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chitosan for Agriculture Market |
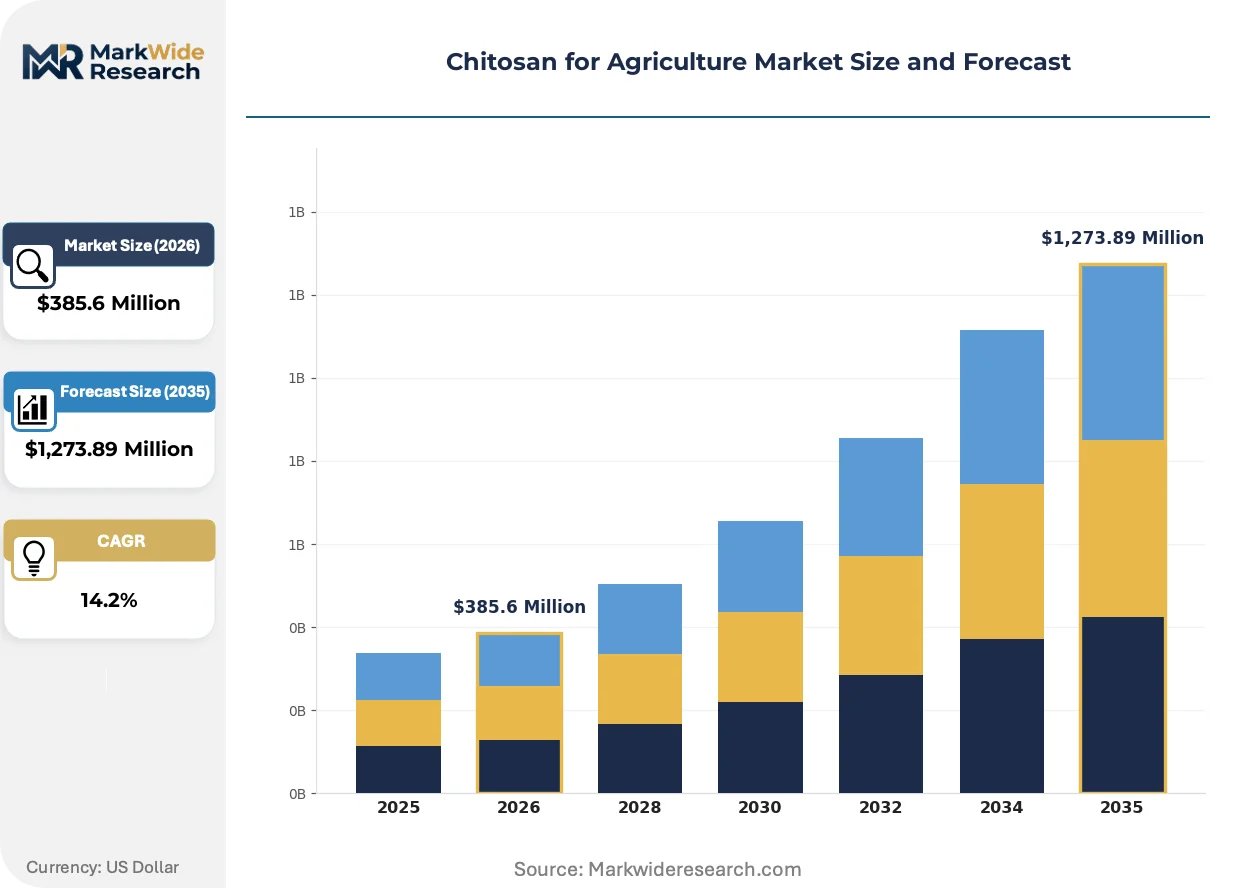
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,273.89 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chitosan Oligosaccharides, Chitosan Liquid, Chitosan Powder, Chitosan Granules Application: Seed Treatment, Soil Amendment, Foliar Spray, Pest Management Distribution Channel: Online Retail, Agricultural Distributors, Farm Supply Stores, Direct Sales End User: Farmers, Agricultural Researchers, Crop Producers, Horticulturists |
| Companies Covered | Zhejiang Golden-Shell Pharmaceutical Co. Ltd., Taizhou City Fengrun Biochemical Co. Ltd., Primex ehf, Panvo Organics Pvt. Ltd., BIO21 Co. Ltd., KitoZyme S.A., T.C. Bio Corporation, Xianju Tengwang Chitosan Factory, Advanced Biopolymers AS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chitosan for Agriculture Market Trends and Innovations
Biological manufacturing routes and precision application technologies are actively restructuring how agricultural chitosan reaches farm fields, compressing legacy supply chain configurations in the process.
Enzymatic deacetylation technology is decomposing the traditional alkaline processing monopoly in chitosan manufacturing. Specialty chemical suppliers and agricultural biotechnology firms are piloting enzyme-catalyzed routes at commercial scale in Denmark and the Netherlands. This biological approach is decomposing the capital barrier that previously protected integrated crustacean processors from standalone entrants, enabling distributed production closer to end-use markets.
REACH registration requirements for polymer substances are tightening purity and impurity disclosure standards for chitosan imports into European Union member states. The European Chemicals Agency's updated guidance on natural polymer derivatives now demands extensive ecotoxicological dossiers for agricultural applications. Seed treatment formulators targeting German and French markets are responding by consolidating supplier qualification programs around REACH-compliant manufacturers with existing substance registrations.
Farmer purchasing cooperatives are consolidating input procurement decisions across larger geographic footprints, compressing distributor margins and favoring direct manufacturer relationships. This concentration is displacing traditional agricultural chemical wholesalers in Brazil's Mato Grosso soybean belt and India's Punjab wheat districts. Chitosan suppliers with technical service capabilities and volume pricing flexibility are capturing preferred supplier status within these consolidated buying structures.
Chitosan for Agriculture Market Segmentation
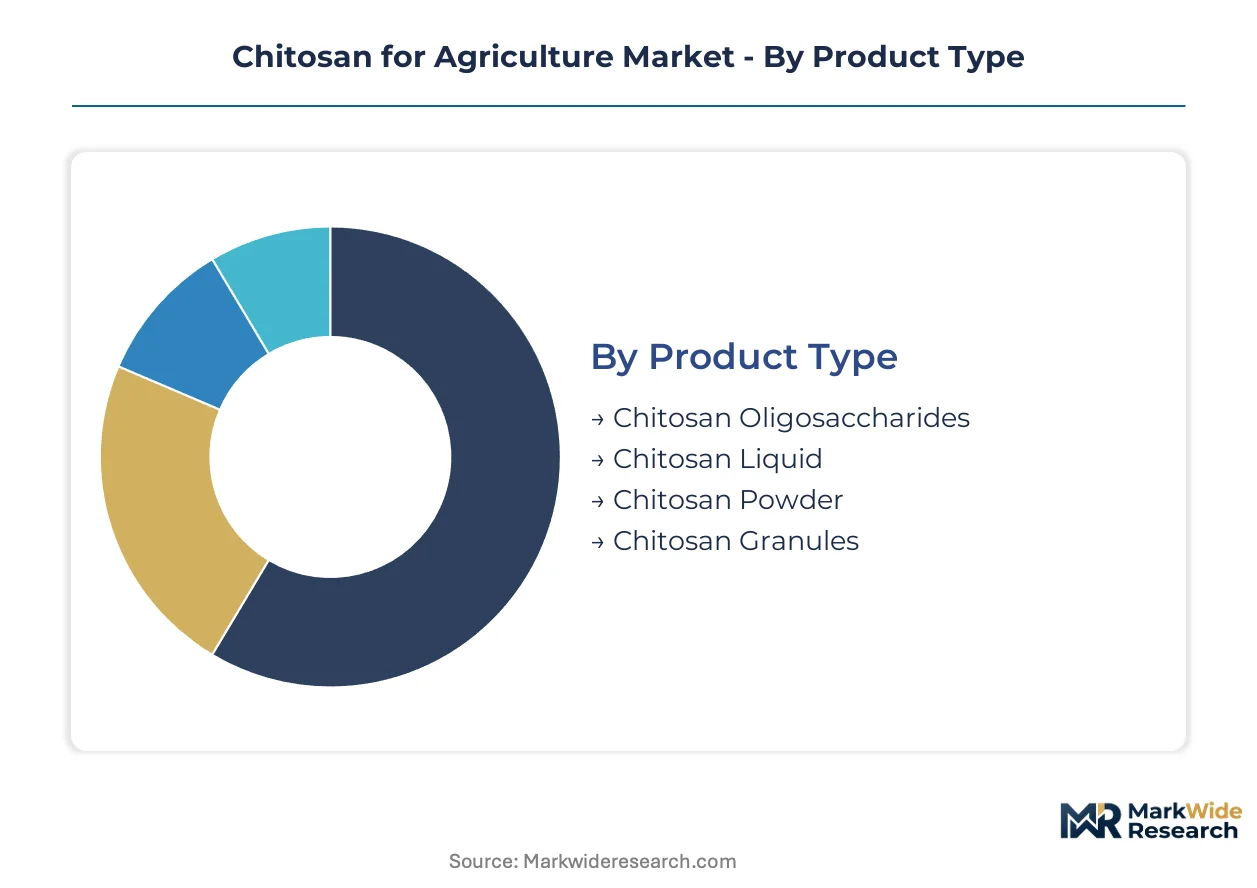
Chitosan for agriculture splits across formulation chemistry, application method, and customer procurement patterns. Each axis reveals distinct margin profiles and regulatory exposure that shape supplier positioning strategies.
Product Type:
Substitution pressure from synthetic biostimulants and mineral fertilizers concentrates most intensely on commodity-grade powders where price parity determines farmer switching costs.
- Chitosan Oligosaccharides:Low-molecular-weight fractions (typically below 10 kDa) engineered for systemic plant signaling and precision dosing compatibility. Demand clusters in China's Shandong greenhouse complexes and the Netherlands' glasshouse vegetable sector where sensor-calibrated application systems dominate. Enzymatic hydrolysis production costs currently limit penetration to high-value horticulture.
- Chitosan Liquid:Ready-to-use aqueous formulations standardized for immediate tank-mixing with existing spray equipment. Brazilian soybean cooperatives and Indian Punjab wheat belts drive volume procurement through distributor networks seeking minimal handling complexity. Alkaline deacetylation supply chains in coastal Vietnam and Indonesia anchor regional cost positions.
- Chitosan Powder:Deacetylated chitin flakes requiring on-farm dissolution, favored by large-scale grain operations with captive mixing infrastructure. Price competition from conventional nitrogen stabilizers constrains label pricing flexibility.
- Chitosan Granules:Slow-release matrices for soil incorporation, competing directly with lignosulfonate and humic acid soil conditioners on cost-per-hectare metrics.
Chitosan Liquid anchors the volume base while Chitosan Oligosaccharides gains share at the steepest rate.
Application:
Cost tier differentiation separates premium-positioned seed treatments from commodity soil amendments where distributor rebates determine commercial success.
- Seed Treatment:Film-forming coatings delivering localized antimicrobial protection and germination enhancement. Bayer and Syngenta distribution networks in Germany and France prioritize REACH-registered chitosan suppliers for hybrid corn and oilseed rape programs. Registration as a seed-applied biostimulant avoids biopesticide pathway delays.
- Soil Amendment:Bulk applications for structure improvement and microbiome modulation. China's Hebei and Shandong provinces deploy provincial subsidy programs for chitosan-enhanced organic fertilizers, creating volume concentration distinct from export-oriented horticulture markets.
- Foliar Spray:Leaf-surface biofilm formation for drought stress mitigation, competing with seaweed extracts and amino acid biostimulants on application timing flexibility.
- Pest Management:Elicitor-induced systemic resistance targeting fungal and nematode pressure, requiring EPA biopesticide registration in the US and parallel national pathways in Brazil and India.
Soil Amendment commands the widest farmer reach while Seed Treatment captures the highest margin per treated hectare.
Distribution Channel:
Volume concentration in agricultural distributor networks reflects the technical service requirements for compatibility testing against existing pesticide portfolios.
- Agricultural Distributors:Regional wholesalers with formulation laboratories and field agronomist staff. Brazil's Mato Grosso and India's Maharashtra procurement cooperatives consolidate purchases through preferred supplier agreements demanding volume pricing and technical support commitments.
- Direct Sales:Manufacturer-to-farm relationships for large-scale row crop operations. Primex ehf and KitoZyme S.A. maintain dedicated account teams for Nordic and Benelux greenhouse consortia respectively.
- Online Retail:E-commerce platforms targeting smallholder horticulturists and organic certification holders in fragmented European markets.
- Farm Supply Stores:Local retail points for immediate procurement, dominant in US Midwest grain belts and Australian broadacre regions.
Agricultural Distributors handle the bulk of commercial volume while Direct Sales expands most quickly among precision agriculture adopters.
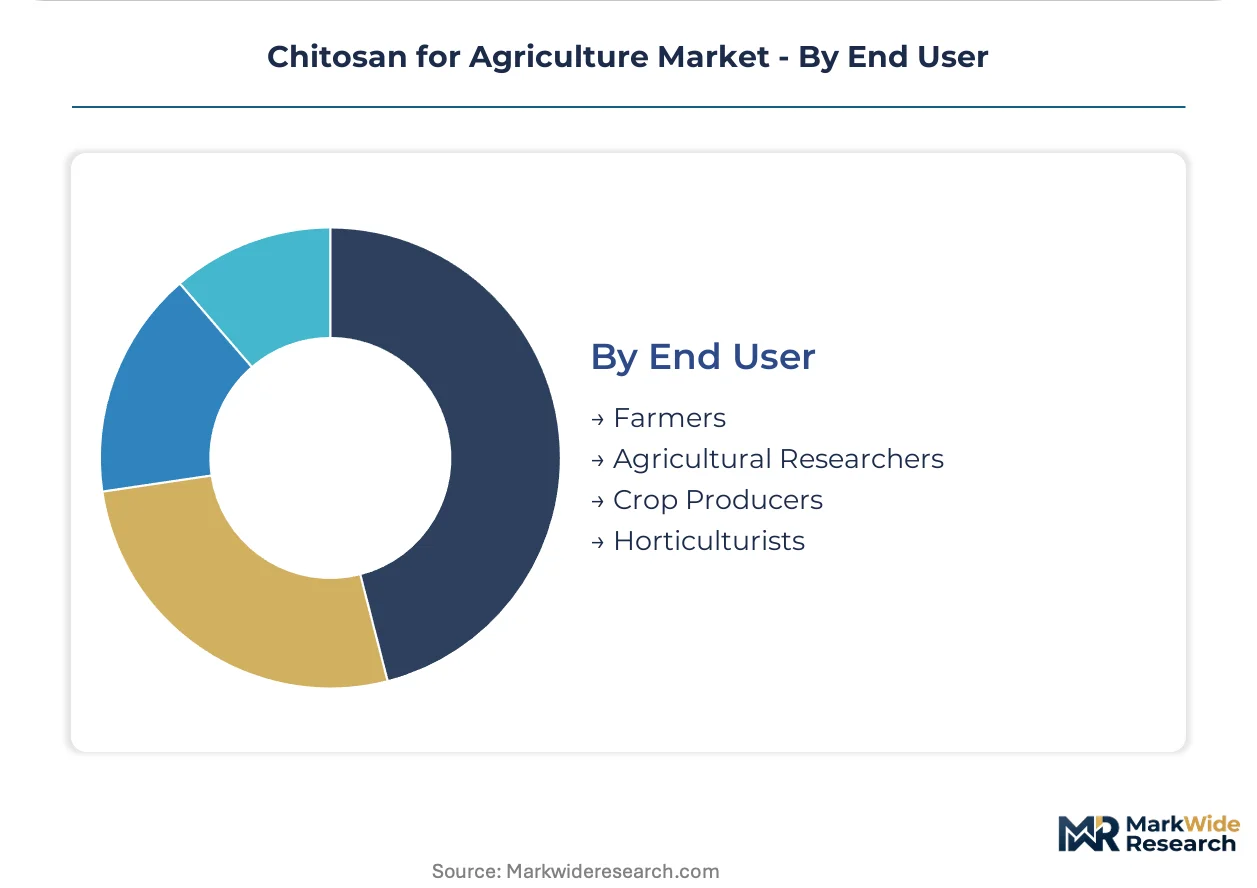
End User:
Customer type maturity separates research-driven early adopters from price-sensitive commodity producers.
- Farmers:Owner-operators and cooperative members making input decisions based on per-hectare return calculations. China's new agricultural operating entities and Brazil's no-till soybean specialists represent contrasting scale concentrations.
- Crop Producers:Corporate farming enterprises with centralized procurement and documented sustainability commitments for export market access.
- Agricultural Researchers:University and government experiment stations conducting field trials for registration support and label expansion. Wageningen University and Research in the Netherlands and China's Chinese Academy of Agricultural Sciences drive protocol standardization.
- Horticulturists:Protected cultivation specialists in Spain's Almería, Mexico's Sinaloa, and Turkey's Antalya demanding residue-free certification for EU supermarket supply chains.
Farmers represent the foundational demand base while Agricultural Researchers influence adoption trajectories through trial data dissemination.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across agricultural chitosan markets. Smallholder-dominated regions prioritize cost-per-hectare metrics, while greenhouse-intensive economies absorb premiums for precision-grade formulations.
China
Provincial subsidy programs in Hebei and Shandong drive soil amendment volume through organic fertilizer blending mandates. NMPA quality thresholds and Ministry of Agriculture residue standards govern domestic biostimulant registration. Coastal biorefinery clusters in Zhejiang leverage shrimp processing waste concentration for feedstock-advantaged production.
Brazil
No-till soybean specialists in Mato Grosso and Paraná deploy chitosan seed treatments for nematode suppression in export-oriented row crops. ANVISA biopesticide pathways and parallel biostimulant classifications create dual registration options. Procurement cooperatives in the Cerrado belt consolidate purchases through preferred supplier agreements demanding technical support commitments.
United States
Midwest grain operations with captive mixing infrastructure favor powder formulations for nitrogen stabilization programs. EPA biopesticide registration timelines extend commercialization cycles, pushing suppliers toward biostimulant classifications where USDA organic certification compatibility expands addressable segments. California Central Valley horticulturists drive precision agriculture adoption for residue-free supermarket supply chains.
India
Punjab wheat belts and Maharashtra procurement cooperatives channel volume through agricultural distributor networks with formulation laboratories. FSSAI and Central Insecticides Board oversight governs import clearance and local formulation approvals. Coastal processing infrastructure in Gujarat and Andhra Pradesh secures crustacean waste feedstock for regional manufacturers.
Netherlands
Glasshouse vegetable operations in Westland and North Holland deploy sensor-calibrated chitosan oligosaccharide dosing through drone-mounted spray systems. ECHA REACH requirements and EFSA biostimulant guidance shape supplier qualification programs. Wageningen University research partnerships influence protocol standardization across Benelux greenhouse consortia.
Chitosan for Agriculture Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the agricultural chitosan supply base. Integrated crustacean-waste processors maintain feedstock cost advantages through coastal biorefinery control, while fungal fermentation specialists eliminate marine supply dependencies entirely. Three archetypes dominate: vertically integrated marine biomass processors, mycelium-based technology platforms, and regional formulation specialists serving distributor networks. Capacity expansion and strategic partnerships represent the dominant competitive moves as fermentation routes lower entry barriers.
Among Asian pharmaceutical-grade manufacturers, Zhejiang Golden-Shell Pharmaceutical Co. Ltd. and Taizhou City Fengrun Biochemical Co. Ltd. occupy positions anchored by coastal processing infrastructure and state-backed biorefinery investments. KitoZyme S.A. exemplifies the fungal technology archetype, representing production routes that bypass marine supply chains entirely.
| Leading Market Players |
|---|
| Zhejiang Golden-Shell Pharmaceutical Co. Ltd. |
| Taizhou City Fengrun Biochemical Co. Ltd. |
| Primex ehf |
| Panvo Organics Pvt. Ltd. |
| BIO21 Co. Ltd. |
| KitoZyme S.A. |
| T.C. Bio Corporation |
| Xianju Tengwang Chitosan Factory |
| Advanced Biopolymers AS |
| Others |
Pricing and Supply Chain Analysis
Ninety-day sodium hydroxide supply contracts anchor pricing power for coastal crustacean processors, compressing margins for non-integrated formulators exposed to spot chemical markets. This inventory-lead dynamic concentrates margin capture in Zhejiang and Vietnamese biorefinery clusters while forcing standalone agricultural chitosan suppliers toward fungal fermentation alternatives.
Pricing Analysis
After-sales technical service contracts for tank-mix compatibility testing drive lifetime value beyond commodity product margins. Three-tier pricing structure across pharmaceutical-grade, agricultural-grade, and feed-grade specifications stratifies the market, with deacetylation degree and heavy metal certification as primary differentiation levers. Cost compression in liquid formulations is intensifying because Vietnamese and Indonesian processors expand alkaline deacetylation capacity. Smallholder cooperatives in India's Punjab wheat belts exhibit highest price sensitivity, while Dutch glasshouse consortia absorb premiums for REACH-registered oligosaccharide fractions.
Supply Chain Analysis
Malacca Strait shipping lanes channel crustacean shell feedstock from Indonesian shrimp processing clusters to Zhejiang biorefineries, creating a logistics chokepoint for Asian agricultural chitosan supply. Production gravity centers on China, Vietnam, and Brazil where coastal waste concentration meets provincial subsidy programs. Sodium hydroxide and fungal mycelium feedstocks draw from chemical manufacturing and controlled fermentation facilities respectively. Single-source coastal processing dependencies create raw material availability bottlenecks during monsoon harvesting disruptions. Distribution runs through agricultural distributor networks with formulation laboratories in Brazil's Mato Grosso and India's Maharashtra.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Agricultural input cyclicality is recovering as EU F-Gas Regulation phase-down schedules accelerate farmer substitution away from fluorinated greenhouse gas crop protection. This regulatory-driven replacement cycle creates durable demand tailwinds for chitin-derived biostimulants.
For Market Incumbents: Consolidate backward integration into coastal shrimp processing infrastructure to secure sodium hydroxide-advantaged feedstock positions against fungal fermentation entrants. Lock in long-term alkaline reagent supply contracts before chemical price volatility erodes crustacean-route cost advantages. Prioritize REACH registration maintenance for seed treatment formulators targeting Bayer and Syngenta distribution networks in Germany and France.
For New Entrants and Emerging Players: Technical service gaps in tank-mix compatibility validation present white-space openings for precision agriculture specialists. Target China's Shandong greenhouse complexes and the Netherlands' Westland glasshouse sector where sensor-calibrated oligosaccharide dosing systems command premium positioning. Pursue fungal chitosan production routes to bypass marine supply chain seasonality and establish inland manufacturing without coastal feedstock dependencies.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across enzymatic deacetylation sub-segments as biological manufacturing routes democratize production access. Five-to-ten year viability favors technology platforms with dual marine and fungal production capabilities rather than single-source crustacean processors. Watch for EPA biopesticide registration timeline compression as the signal indicating regulatory pathway arbitrage opportunities between biostimulant and biopesticide classifications.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Deacetylation Scale-Up | Biological processing routes collapse capital barriers protecting legacy alkaline processors in Denmark and Netherlands. |
| REACH Registration Consolidation | Seed treatment formulators prioritize ECHA-compliant suppliers for German and French hybrid corn programs. |
| Fungal Fermentation Capacity Build | Mycelium-derived production eliminates marine supply dependencies for inland manufacturing locations. |
| Direct-to-Cooperative Distribution | Brazil's Mato Grosso procurement consortia displace traditional agricultural chemical wholesalers. |
| Provincial Subsidy Alignment | Hebei and Shandong organic fertilizer blending mandates create volume concentration for soil amendment suppliers. |
Research Methodology
Initial hypotheses were tested against primary input from agricultural distributor procurement managers, biorefinery plant operators, seed treatment formulators, and regulatory affairs specialists at EPA and ECHA, then refined against secondary validation. Bottom-up triangulation combined customs data on chitosan derivative trade flows, NMPA biostimulant registration filings, and SEC disclosures from agricultural input manufacturers. Top-down cross-checks integrated EU F-Gas Regulation implementation timelines and provincial subsidy program announcements from China's Ministry of Agriculture.
Variance decomposition across product type, application method, deacetylation grade tier, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume build-ups and price trajectory assumptions. Forecast inputs incorporated enzymatic hydrolysis cost curves and precision agriculture adoption rates for drone-mounted spray compatibility.
Underlying assumptions cover sustained EU Green Deal implementation, stable alkaline reagent supply contracts, and consistent shrimp harvesting patterns, with deviation risk concentrated in EPA registration timeline extensions and monsoon disruption severity. Practitioners should keep alternative scenarios live as fermentation technology cost curves and biostimulant standardization timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biologicals
Animal Feed Additives Market
Agricultural Biologicals
Humic-Based Biostimulants Market
Agricultural Biologicals
United States Animal Feed Additives Market
Agricultural Biologicals
North America Animal Feed Additives Market
Agricultural Biologicals
Middle East and Africa Bio-Stimulants Market
Agricultural Biologicals
South America Feed Mycotoxin Detoxifiers Market
Agricultural Biologicals
Insect Feed Market
Agricultural Biologicals
Agricultural Adjuvants Market
Agricultural Biologicals
North America Feed Prebiotics Market
Agricultural Biologicals
Global Silage Inoculants Market
Agricultural Biologicals
Europe Agricultural Microbials Market
Agricultural Biologicals
Baobab Market
Agricultural Biologicals
Europe Silage Inoculant Market
Agricultural Biologicals
Global Organic Trace Minerals for Animal Feeds Market
Agricultural Biologicals
Microbial Agricultural Inoculants Market
Agricultural Biologicals
Agricultural Activator Adjuvants Market