
 Latin America Animal Feed Additives Market | 2026-2036
Latin America Animal Feed Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Animal Feed Additives Market Analysis
The capital-intensity divergence between integrated multinationals and regional blenders is unwinding competitive stability across Latin America. Cargill leverages its captive soybean processing infrastructure to control premix input costs from crushing through finished additive formulation. DSM anchors its position through specialized carotenoid and vitamin production tailored to tropical heat-stress conditions in Brazilian poultry houses.
Animal feed additives comprise functional micro-ingredients—amino acids, vitamins, minerals, and enzymes—dosed at grams per ton to optimize nutrient absorption, gut health, and growth performance in livestock. Industrial premix manufacturing employs precision blending and coating technologies to ensure thermostability and uniform dispersion in high-temperature pelleting processes. Amino acids command the deepest margin pools among product categories due to their irreplaceable role in least-cost feed formulation. Poultry applications generate the highest volume throughput across Latin America, while aquaculture represents the fastest-expanding end-use as Chilean salmon farmers intensify production.
Brazil's MAPA, Mexico's SENASICA, and Argentina's SENASA collectively enforce residue limits and antibiotic restrictions that elevate demand for enzyme-based and organic acid alternatives. REACH-aligned chemical safety protocols from Europe increasingly shape import standards for specialty additives entering Mercosur trade channels. Stakeholders must monitor regulatory harmonization pressures between national agencies and evolving EU Green Deal alignment requirements affecting export-oriented livestock supply chains.
Market Dynamics
Brazil's MAPA enforcement of antibiotic growth promoter bans is compressing procurement timelines and redirecting capital toward enzyme and probiotic alternatives across integrated poultry operations.
Growth Catalysts
- Regulatory mandate acceleration:Brazil's MAPA restrictions on antibiotic growth promoters are compelling feed mills to reformulate rations with enzyme-based alternatives. This creates immediate demand pull for thermostable phytase and xylanase products.
- Integrated processor expansion:Brazil's Central-West soybean belt houses expanding broiler operations from JBS and BRF that demand precision-formulated premixes. These facilities require additives that optimize feed conversion ratios in high-density housing.
- Enzyme technology maturation:Next-generation carbohydrases now withstand pelleting temperatures above 85°C without coating degradation. This technical advance eliminates a major formulation barrier for tropical feed mills.
Market Restraints
- Soybean input cost volatility:Brazil's position as the world's largest soybean exporter exposes premix manufacturers to commodity price swings. Crushing margin compression directly affects amino acid feedstock economics.
- Import dependency concentration:Specialty vitamin premixes and carotenoids rely heavily on Chinese manufacturing. Supply chain disruptions from port congestion or trade policy shifts create formulation bottlenecks.
- Technical substitution ceiling:Organic acid alternatives to antibiotics face efficacy limitations in necrotic enteritis control. This biological constraint restricts complete antibiotic replacement in certain production phases.
Strategic Opportunities
- Colombian market underpenetration:Colombia's poultry sector maintains lower additive inclusion rates than Brazilian benchmarks. Rising domestic protein consumption creates whitespace for precision nutrition services.
- Aquaculture application emergence:Chilean salmon farmers are intensifying production density and require gut health additives for sea lice stress mitigation. This vertical demands specialized marine-grade formulations.
- EU Green Deal alignment:Mercosur export-oriented livestock operations face mounting pressure to demonstrate deforestation-free supply chains. Additive verification systems that trace soy provenance command premium positioning.
Industry Challenges
- Formulation chemist scarcity:Latin American universities produce limited graduates with combined nutrition science and thermoprocessing expertise. This talent gap constrains premix manufacturer R&D expansion.
- Multi-agency compliance complexity:Brazil's MAPA, Mexico's SENASICA, and Argentina's SENASA maintain non-harmonized residue testing protocols. Product registration across jurisdictions demands duplicative stability studies and documentation.
- Legacy system integration friction:Automated dosing equipment from older feed mill installations lacks precision for micro-ingredient dispersion. Retrofit costs compete with greenfield automation investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Animal Feed Additives Market |
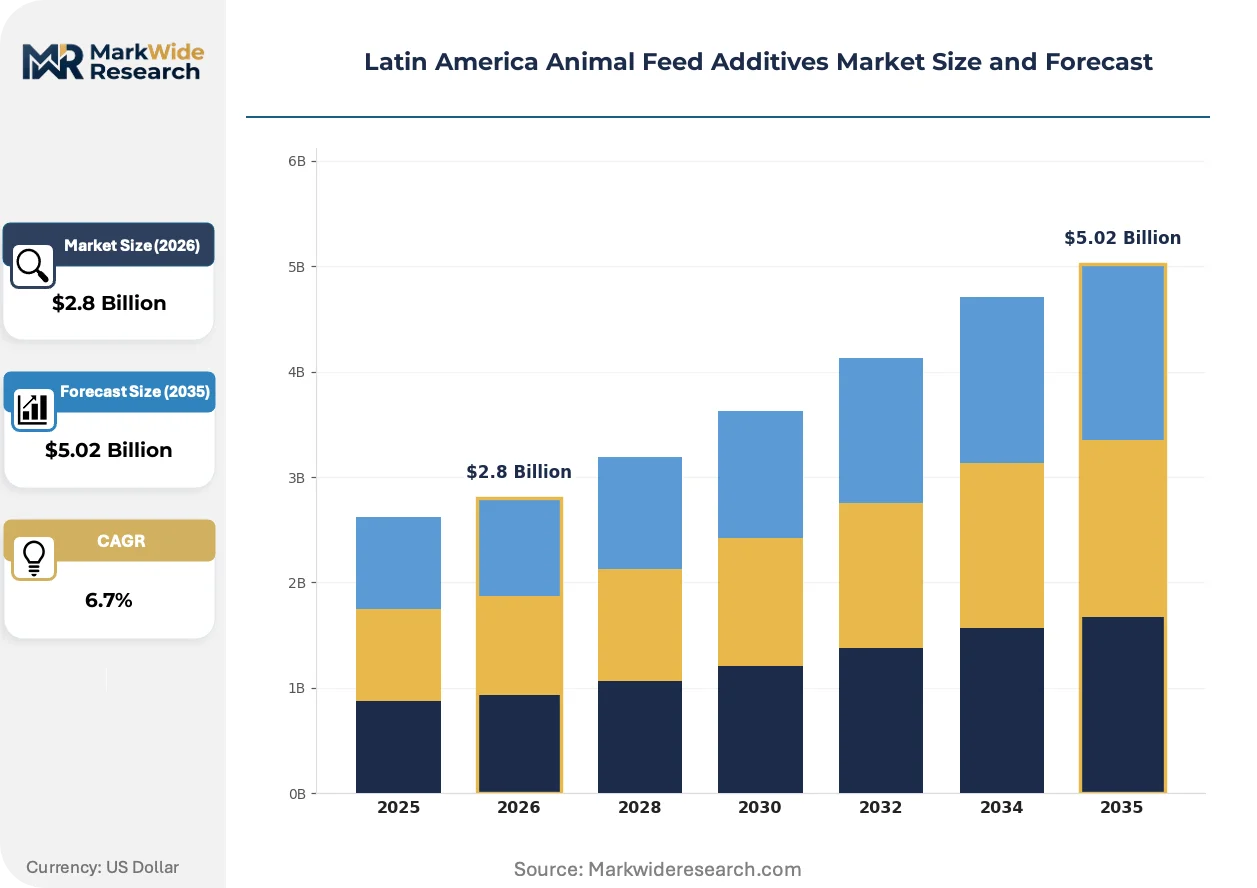
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amino Acids, Vitamins, Minerals, Enzymes Application: Poultry, Swine, Ruminants, Aquaculture End User: Livestock Farmers, Feed Manufacturers, Veterinary Clinics, Research Institutions Distribution Channel: Online Retail, Direct Sales, Wholesalers, Distributors |
| Companies Covered | DSM, DuPont, Cargill, Alltech, Novozymes, ADM, Evonik, Ajinomoto, BASF, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Animal Feed Additives Market Emerging Trajectories
Precision fermentation and synthetic biology are compressing production economics for amino acids and enzymes, while regulatory pressure on antibiotic residues accelerates alternative validation protocols across Latin American jurisdictions.
Encapsulated organic acid blends with targeted-release kinetics are bifurcating the gut health segment from traditional acidifier commodities. Brazilian integrators with vertically controlled feed mills are adopting these precision-delivery systems at scale. This technology shift is compressing margins for standard acidifier suppliers while creating premium pricing power for coating technology specialists.
Brazil's MAPA has tightened maximum residue limits for antibiotic traces in exported poultry, mirroring EU Green Deal alignment pressures. This regulatory tightening forces feed mills to maintain dual formulation tracks for domestic and export markets. Poultry operations supplying EU-destinated product are most affected, accelerating investment in enzyme-based growth promotion.
Direct mill procurement from additive manufacturers is displacing traditional distributor intermediaries in Brazil's Central-West corridor. Large integrated processors now negotiate volume contracts for amino acids and enzymes directly with DSM and Cargill. This channel compression is most visible in Mato Grosso and Goiás states where JBS and Minerva operate captive feed production at scale.
Latin America Animal Feed Additives Market Segmentation
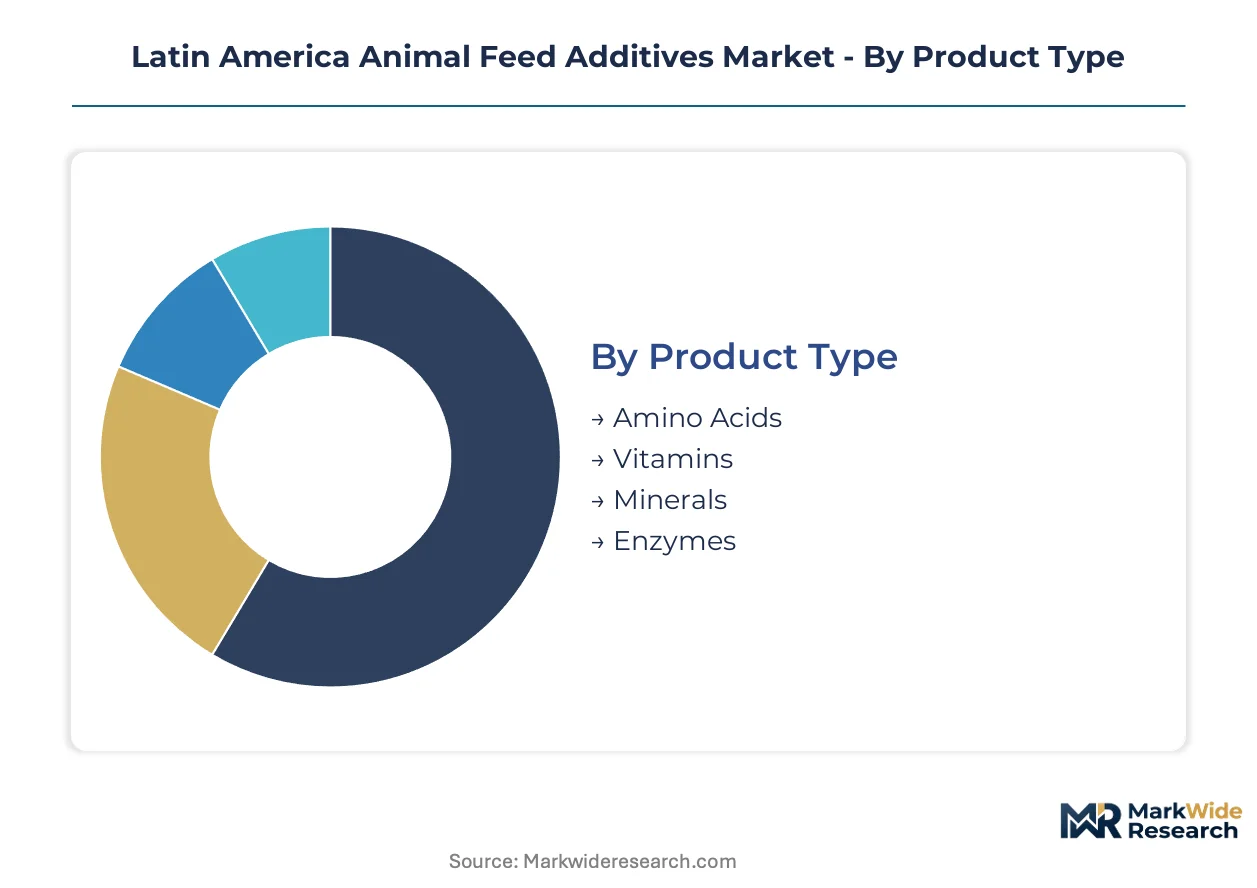
Feed additive procurement patterns diverge sharply across product chemistry, livestock species, and channel structure. Regulatory pressure on antibiotic residues and heat-stress formulation requirements create distinct margin profiles within each segment cluster.
Product Type:
MAPA's antibiotic growth promoter restrictions in Brazil elevate enzyme alternatives while amino acid economics track crushing margins in the Central-West soybean belt.
- Amino Acids:Lysine, methionine, and threonine constitute irreplaceable building blocks for least-cost ration formulation. Demand concentrates in Brazil's integrated poultry operations where JBS and BRF optimize feed conversion ratios through precision inclusion rates.
- Enzymes:Thermostable phytase and xylanase formulations withstand pelleting temperatures above 85°C without coating degradation. Brazilian feed mills in Mato Grosso and Goiás are accelerating procurement as antibiotic alternatives face mandatory substitution timelines.
- Vitamins:Fat-soluble and water-soluble micronutrients address tropical heat-stress conditions in open-sided Brazilian poultry houses.
- Minerals:Organic and inorganic trace element premixes support bone development and metabolic function across high-density livestock operations.
Amino acids handle the majority of throughput; enzymes are gaining share fastest on regulatory substitution mandates.
Application:
Volume scale and growth velocity separate poultry dominance from aquaculture emergence across Latin American protein production.
- Poultry:Broiler and layer operations generate the deepest additive consumption pools through vertically integrated supply chains. Brazil's Central-West corridor houses the densest concentration of captive feed mills serving export-oriented slaughter facilities.
- Aquaculture:Chilean salmon farmers intensifying production density require specialized gut health additives for sea lice stress mitigation. Marine-grade formulations with targeted-release kinetics command premium positioning in Puerto Montt and Chiloé processing zones.
- Swine:Sow and finishing operations in southern Brazil and Mexico's Yucatán Peninsula utilize acidifier blends for pathogen control in tropical climates.
- Ruminants:Beef cattle feedlots in Argentina's Pampas region and dairy operations in Minas Gerais employ ionophores and buffer compounds for rumen efficiency.
Poultry commands the dominant volume position; aquaculture is expanding most quickly on production intensification.
End User:
Procurement sophistication and formulation control separate integrated processors from fragmented livestock operations.
- Feed Manufacturers:Industrial premix blenders in Brazil's soybean belt operate automated dosing lines requiring thermostable micro-ingredient specifications. These facilities negotiate direct contracts with amino acid and enzyme suppliers, compressing traditional distributor margins.
- Livestock Farmers:Independent producers in Colombia and Peru rely on commercial premix services with lower inclusion rates than Brazilian integrated benchmarks.
- Veterinary Clinics:Specialty practitioners prescribe therapeutic additive protocols for metabolic disorders and gut health interventions.
- Research Institutions:Universities and extension services validate alternative growth promoter efficacy under tropical conditions.
Feed manufacturers capture the bulk of commercial volume; livestock farmers show the steepest expansion trajectory as protein consumption rises.
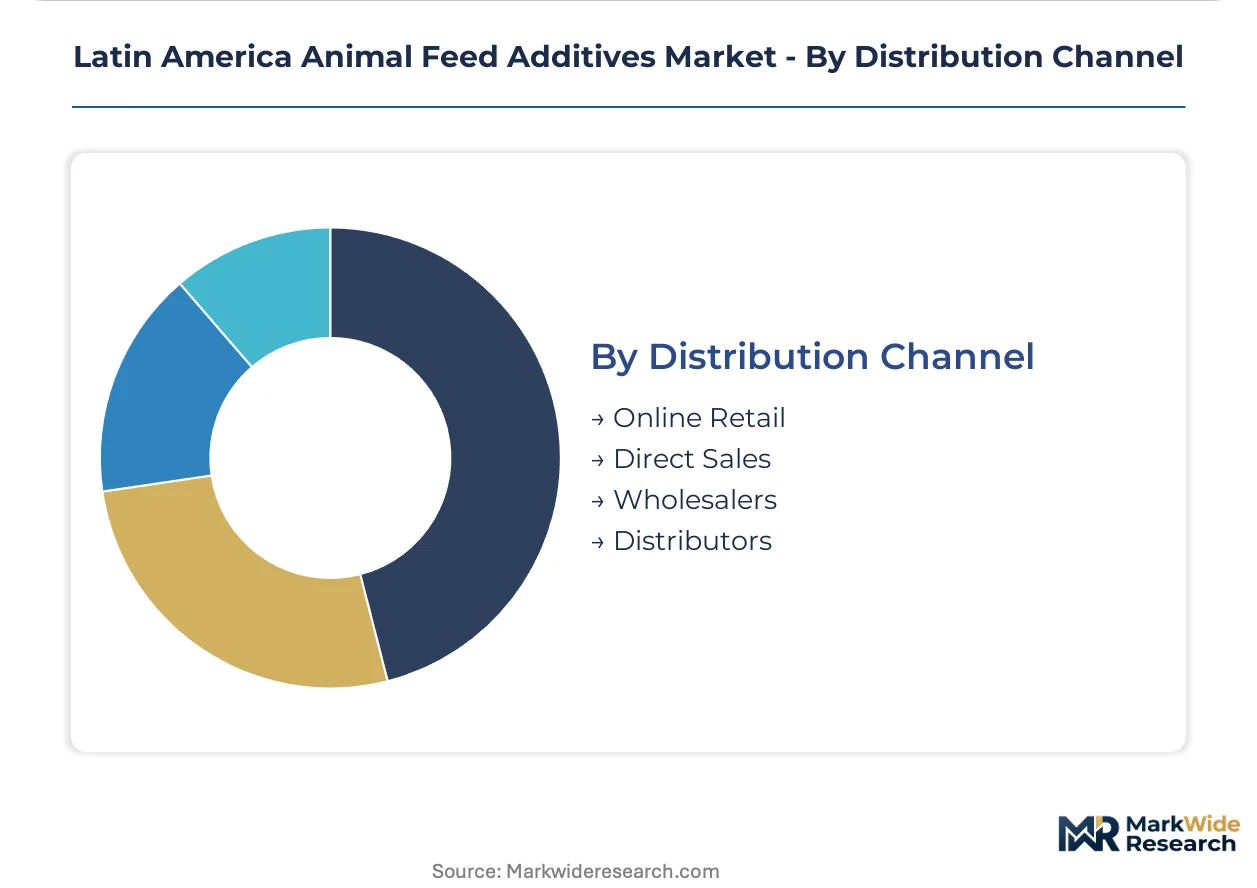
Distribution Channel:
Channel compression in Brazil's Central-West contrasts with distributor dependency in peripheral markets.
- Direct Sales:DSM and Cargill negotiate volume contracts directly with JBS, BRF, and Minerva for amino acids and enzymes. This bypass eliminates traditional wholesaler markups in Mato Grosso and Goiás states.
- Distributors:Regional blenders in Colombia, Peru, and Ecuador maintain reliance on specialized intermediaries for vitamin premixes and carotenoids.
- Wholesalers:Bulk commodity handlers supply standard mineral and acidifier products to smaller feed mills.
- Online Retail:Digital procurement platforms serve micro-scale livestock operations with packaged supplement offerings.
Direct sales channels manage the largest throughput; distributor networks are climbing fastest on geographic expansion into underpenetrated Andean markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's integrated poultry operations consume additives at inclusion rates nearly double Colombian benchmarks, while Chilean aquaculture demands specialized marine-grade formulations unavailable elsewhere in the region.
Brazil
JBS and BRF operate captive feed mills across Mato Grosso and Goiás states with automated dosing lines requiring thermostable enzyme specifications. MAPA's antibiotic growth promoter restrictions compel immediate reformulation with phytase and xylanase alternatives. São Paulo state houses DSM's carotenoid production facilities tailored to tropical heat-stress conditions in open-sided poultry houses.
Mexico
SENASICA enforces residue limits that elevate demand for organic acid blends in Yucatán Peninsula swine operations. Guanajuato's dairy clusters employ buffer compounds for rumen efficiency in high-altitude production zones. Direct procurement contracts between integrated processors and amino acid suppliers are compressing traditional distributor margins in the Bajío region.
Argentina
SENASA maintains non-harmonized testing protocols with Brazilian MAPA standards, duplicating stability study requirements for cross-border premix registration. Buenos Aires province feedlots utilize ionophores for beef cattle rumen efficiency. Rosario's crushing infrastructure supplies soybean meal feedstock to regional premix blenders facing margin compression from commodity price swings.
Chile
Puerto Montt and Chiloé salmon farmers intensify production density and require gut health additives for sea lice stress mitigation. Marine-grade formulations with targeted-release kinetics command premium positioning unavailable from standard poultry-oriented suppliers. Regulatory alignment with EU export standards drives verification systems for deforestation-free supply chain documentation.
Colombia
Domestic protein consumption expansion creates whitespace for precision nutrition services in poultry operations maintaining lower additive inclusion rates than Brazilian benchmarks. Antioquia and Cundinamarca departments concentrate commercial premix demand from independent producers. Distributor networks remain essential for vitamin premix procurement given limited direct mill infrastructure.
Latin America Animal Feed Additives Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational agricultural conglomerates controlling captive soybean processing infrastructure while regional blenders compete on formulation flexibility. Three archetypes dominate: integrated commodity processors with backward integration into amino acid feedstocks, specialized enzyme and probiotic technology licensors, and precision premix blenders serving fragmented livestock operations. Capacity expansion in Brazil's Central-West corridor and strategic partnerships for thermostable coating technology represent the dominant competitive vectors.
Within the integrated processor tier, Cargill and ADM exemplify upstream control over crushing economics that shapes premix input cost structures. DSM occupies a distinct position as a specialized carotenoid and vitamin producer with production assets positioned for tropical formulation requirements. Among enzyme technology providers, Novozymes represents the thermostability-focused archetype addressing pelleting temperature barriers that constrain alternative growth promoter adoption.
| Leading Market Players |
|---|
| DSM |
| DuPont |
| Cargill |
| Alltech |
| Novozymes |
| ADM |
| Evonik |
| Ajinomoto |
| BASF |
| Others |
Supply Flow & Price Mechanics
Long-term volume contracts between Brazilian integrators and amino acid suppliers lock in both feedstock access and cost visibility across multi-year procurement cycles. These arrangements insulate JBS and BRF operations from soybean crushing margin volatility while compressing spot-market participation for regional blenders.
Pricing Analysis
After-sales technical service and formulation consulting drive lifetime value for premix manufacturers serving Latin American integrators. Three-tier pricing structure across premium, standard, and economy levels separates thermostable enzyme formulations from commodity acidifiers and generic mineral blends. Pricing pressure stems from direct mill procurement bypassing distributor markups in Brazil's Central-West corridor. Independent livestock farmers in Colombia and Peru exhibit highest price sensitivity due to limited scale economies, while Chilean salmon operations accept premium marine-grade positioning.
Supply Chain Analysis
China and India anchor global production of specialty vitamin premixes and carotenoid feedstocks serving Latin American formulators. Brazilian crushing infrastructure feeds amino acid economics while European enzyme technology licensors supply thermostable coating innovations. Supply chain risk centers on single-source dependency for marine-grade gut health additives in Chilean aquaculture. Distribution runs through direct sales channels for integrated processors and regional distributor networks for fragmented livestock operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across MAPA, SENASICA, and SENASA creates specialized compliance niches that reward formulation expertise over commodity scale. Antibiotic substitution mandates splinter demand into enzyme, probiotic, and organic acid alternatives with distinct technical requirements.
For Market Incumbents: Shield market position through backward integration into soybean crushing assets and captive thermostable enzyme production. DSM and Cargill leverage existing Central-West infrastructure to absorb margin compression from commodity price swings. Certification investment in EU Green Deal alignment protocols secures premium positioning for export-oriented Brazilian poultry supply chains. For New Entrants and Emerging Players: Lead with precision fermentation capabilities targeting Colombian poultry operations maintaining sub-Brazilian additive inclusion rates. Aquaculture gut health formulations for Chilean salmon farmers offer specialized marine-grade positioning unavailable from standard poultry suppliers. Technical service partnerships with Antioquia and Cundinamarca independent producers provide channel access without direct mill infrastructure investment. For Investors and Strategic Acquirers: Capital is best deployed toward enzyme technology licensors with thermostable coating IP and established MAPA registration pathways. Long-term viability hinges on regulatory substitution mandates hardening across Latin American jurisdictions. Watch for SENASICA-SENASA harmonization initiatives as inflection indicators for cross-border premix consolidation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Thermostable Enzyme Capacity Expansion | Brazilian feed mills in Mato Grosso require phytase formulations surviving 85°C pelleting temperatures. |
| Precision Fermentation Partnership | Synthetic biology platforms compress amino acid production economics for least-cost ration formulation. |
| EU Green Deal Certification Program | Deforestation-free supply chain verification commands premium positioning in Mercosur export channels. |
| Colombian Distribution Channel Expansion | Antioquia poultry operations seek precision nutrition services at lower inclusion rate benchmarks. |
| Marine-Grade Formulation Development | Puerto Montt salmon farmers require targeted-release gut health additives for sea lice stress mitigation. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with feed mill formulation chemists, procurement directors at integrated processors, MAPA regulatory affairs specialists, and distributor network managers. Secondary validation drew from customs trade databases, MAPA residue limit notifications, SENASICA enforcement bulletins, crushing margin reports, and SEC filings from listed agricultural conglomerates. Bottom-up volume modeling triangulated against top-down macroeconomic protein consumption projections.
Across the analysis window, forecasts incorporate livestock species segmentation, product chemistry tiers, distribution channel structures, and regulatory cluster alignment. CAGRs derive from historical premix consumption patterns, projected broiler and aquaculture output intensification, and enzyme substitution elasticity estimates under antibiotic restriction scenarios. Modeled inputs include soybean meal price trajectories, pelleting temperature compliance requirements, and marine-grade formulation premium persistence.
Forecasts assume regulatory continuity in MAPA, SENASICA, and SENASA enforcement regimes; material policy shifts would require re-modeling substitution timelines and cross-border registration requirements. Specific risks include EU Green Deal alignment acceleration, Chinese vitamin premix supply disruptions, and precision fermentation cost compression altering amino acid competitive economics. Recalibration cycles align with material shifts in regulatory substitution mandates and crushing margin volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biologicals
United States Animal Feed Additives Market
Agricultural Biologicals
Monolaurin for Feed Market
Agricultural Biologicals
Animal Feed Additives Market
Agricultural Biologicals
Global Inoculants Market
Agricultural Biologicals
North America Feed Prebiotics Market
Agricultural Biologicals
Baobab Market
Agricultural Biologicals
North America Feed Mycotoxin Detoxifiers Market
Agricultural Biologicals
Asia Pacific Silage Inoculant Market
Agricultural Biologicals
Europe Silage Inoculant Market
Agricultural Biologicals
Insect Feed Market
Agricultural Biologicals
Edible Fungus Market
Agricultural Biologicals
South America Biostimulants Market
Agricultural Biologicals
Soil Inoculants Market
Agricultural Biologicals
Acetoin Natural Market
Agricultural Biologicals
Chitosan for Agriculture Market
Agricultural Biologicals
Microbial Agricultural Inoculants Market