
 Cement Market | 2026-2036
Cement Market Size, Share, and Industry Trends Forecast 2026-2036
Cement Market Intelligence
Fly ash and slag-based supplementary cementitious materials is pivoting product economics away from pure Portland formulations. Holcim leverages its global R&D network to develop low-carbon binders across multiple continents. Anhui Conch Cement anchors its cost position through captive limestone reserves and integrated grinding capacity. CRH competes by controlling distribution infrastructure in densely populated urban corridors.
Cement is a hydraulic binder produced by calcining limestone and clay at approximately 1450°C, then grinding the resulting clinker with gypsum to achieve a specific surface area of 300-400 m²/kg for standard strength development. Its primary commercial purpose is to react with water and aggregate to form concrete, the world's most consumed manufactured material by mass. Portland cement dominates current output but faces margin compression from carbon pricing, while blended cement captures expanding share as fly ash and slag availability improves near steel and power clusters. Infrastructure development represents the fastest-growing application segment, driven by megaproject pipelines across South and Southeast Asia where public works agencies specify bulk delivery.
The US EPA enforces Portland cement Maximum Achievable Control Technology standards for particulate and mercury emissions, while India's BIS mandates IS 269 and IS 455 quality certifications for domestic and imported cement. The EU Green Deal's embedded carbon requirements are restricting market access for high-clinker imports into European ports. Stakeholders must monitor regulatory divergence between carbon-intensive legacy capacity and emerging low-carbon certification schemes.
Market Dynamics
The European Union's Carbon Border Adjustment Mechanism is compressing margins for clinker-intensive producers while redirecting investment toward calcined clay and alternative binder chemistries across manufacturing footprints.
Growth Catalysts
- India's National Infrastructure Pipeline:Public works agencies specify bulk delivery for transport and urban development projects, absorbing record volumes of construction-grade cement from domestic producers.
- EU Green Deal embedded carbon requirements:Import restrictions at European ports create preferential market access for low-clinker cement, rewarding producers with decarbonized supply chains.
- Supplementary cementitious materials availability:Fly ash and slag streams from proximate steel and power clusters enable blended cement formulations that reduce production costs and carbon intensity simultaneously.
Market Restraints
- Energy cost volatility:Natural gas and petcoke price swings in key producing regions compress operating margins for energy-intensive clinker calcination.
- Limestone reserve concentration:Captive quarry access concentrates among vertically integrated majors, raising entry barriers for independent grinding operations.
- Clinker substitution limits:Structural performance requirements in high-strength concrete applications cap the technical penetration of low-clinker alternatives.
Strategic Opportunities
- Southeast Asia megaproject pipelines:Vietnam, Indonesia, and the Philippines are specifying bulk cement for port, rail, and hydropower developments with multi-decade demand visibility.
- Carbon capture integration:Post-combustion capture retrofits at existing kilns qualify for EU Innovation Fund support and generate tradeable carbon removal credits.
- Ready-mix concrete channel consolidation:Direct distribution partnerships with construction majors bypass fragmented trader networks and improve pricing power.
Industry Challenges
- Process engineer scarcity:Specialized expertise in alternative fuel co-processing and calcined clay activation is concentrated among a limited cohort of technical specialists.
- Low-carbon certification complexity:Divergent methodologies between EU EPD, Indian GreenPro, and emerging ISO standards create compliance overhead for multi-territory producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cement Market |
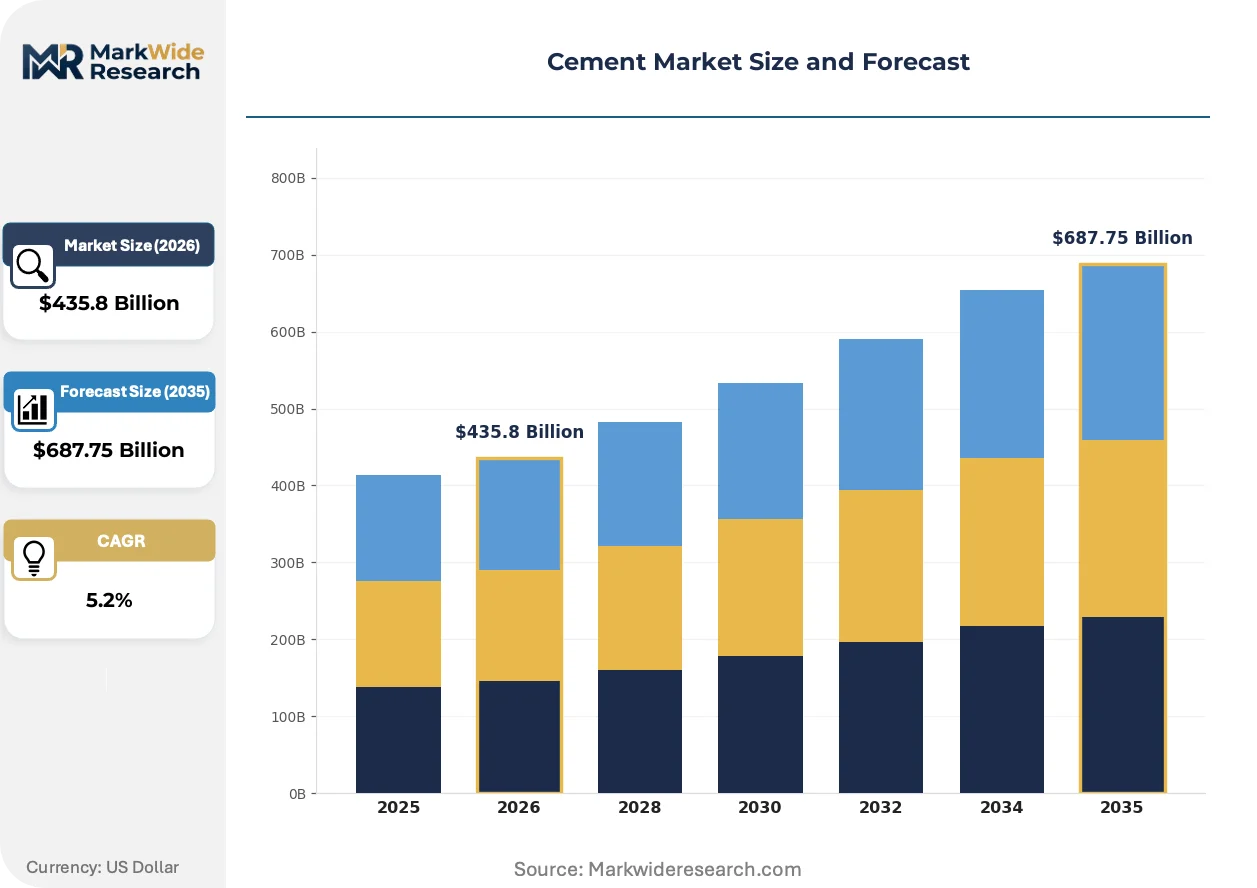
| Market Size in 2026 | $435.8 Billion |
| Market Size in 2035 | $687.75 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portland Cement, Blended Cement, Masonry Cement, Hydrophobic Cement, Expansive Cement Application: Residential Construction, Commercial Projects, Infrastructure Development, Industrial Facilities, Marine Construction Packaging Type: Bags, Bulk, Bulk Bags, Paper Sacks, Plastic Bags End User: Construction Contractors, Building Material Suppliers, Infrastructure Developers, Real Estate Developers, Public Works Agencies |
| Companies Covered | HeidelbergCement, China Resources Cement, China National Building Material, Buzzi Unicem, CRH, Anhui Conch Cement, Cemex, Votorantim Group, Holcim, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cement Market Strategic Shifts & Innovations
Calcined clay activation, carbon capture retrofitting, and procurement model centralization are restructuring how cement is formulated, produced, and contracted across major demand centers.
LC3 (limestone calcined clay cement) is unifying the historically separate supply chains of kaolin processing and clinker grinding into integrated manufacturing configurations. Infrastructure agencies in India and Brazil are specifying LC3 for dam and highway foundations, compressing the premium traditionally commanded by pure Portland formulations. The technology is unifying quality control standards across clay suppliers and cement plants that previously operated without technical coordination.
The EU Carbon Border Adjustment Mechanism entered transitional reporting phases in October 2023, requiring embedded emissions documentation for cement imports. European producers with verified low-clinker production are securing preferential offtake terms from public procurement frameworks. High-clinker imports from Turkey and North Africa face mounting compliance costs and restricted market access at Mediterranean ports.
Construction majors are consolidating procurement through direct long-term supply agreements that displace spot-market purchasing. LafargeHolcim and Heidelberg Materials are negotiating decade-long contracts with infrastructure developers in India and Vietnam, locking in volume commitments and co-investment in dedicated grinding capacity. This concentration is most visible in South Asian markets where public-private partnership structures dominate megaproject development.
Cement Market Segmentation
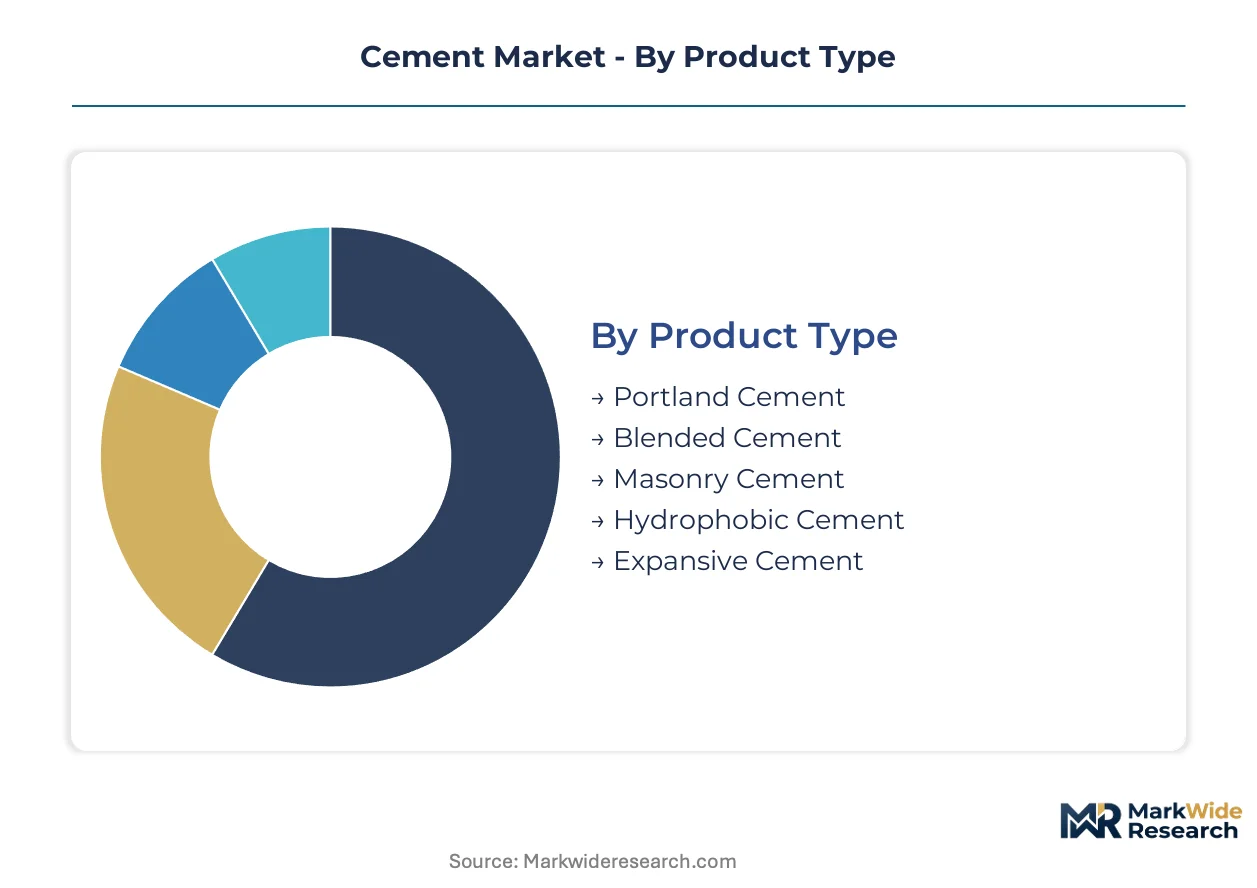
Cement producers configure product portfolios around clinker chemistry, delivery format, and procurement relationships. Each segmentation dimension carries distinct margin profiles and capital requirements that reshape competitive positioning across regional markets.
Product Type:
Standardization dominates commodity-grade output while specialty formulations command specification premiums in demanding environments.
- Portland Cement:Composed of 95% clinker with gypsum addition for setting control, this formulation achieves compressive strengths of 32.5-52.5 MPa under EN 197-1 standards. Demand concentrates in high-rise commercial cores across the Gulf Cooperation Council where structural engineers specify CEM I for load-bearing columns. Clinker-intensive production faces mounting carbon cost exposure under EU CBAM transitional rules.
- Blended Cement:Incorporates 6-35% supplementary cementitious materials—fly ash, slag, or limestone—reducing embodied carbon by 15-40% versus pure Portland. India's National Infrastructure Pipeline specifies PPC and PSC grades for dam foundations and highway paving, absorbing record volumes from domestic producers with proximate power plant and steel mill partnerships.
- Masonry Cement:Contains higher lime content and air-entraining agents for mortar workability in brick and block laying.
- Hydrophobic Cement:Treated with oleic acid or stearic acid to repel moisture during storage and transport in monsoon-exposed supply chains.
- Expansive Cement:Formulated with calcium sulfoaluminate to generate controlled expansion compensating for shrinkage in mass concrete pours.
Most installed capacity flows through Portland Cement. Expansion is steepest in Blended Cement.
Application:
Project scale and procurement channel determine volume commitment visibility and payment security for producers.
- Infrastructure Development:Megaprojects—ports, rail corridors, hydropower—specify bulk delivery with decade-long demand visibility and sovereign-backed payment terms. Vietnam's North-South Expressway and Indonesia's Trans-Java Toll Road are absorbing multi-million-tonne annual commitments from integrated producers with dedicated grinding terminals.
- Residential Construction:Fragmented contractor bases and seasonal demand patterns create working capital intensity and price volatility exposure.
- Commercial Projects:High-rise developments in urban cores specify high-strength grades with certified low-carbon credentials for green building ratings.
- Industrial Facilities:Manufacturing plants and warehouses demand sulfate-resistant formulations for foundation durability in aggressive soil conditions.
- Marine Construction:Sea walls, breakwaters, and offshore platforms require blended formulations with enhanced chloride resistance.
Volume concentrates in Infrastructure Development. Margin expansion is most pronounced in Commercial Projects.
Packaging Type:
Logistics economics and handling infrastructure at destination dictate format selection across distribution networks.
- Bulk:Delivered via pneumatic tanker to dedicated site silos, eliminating bagging costs and reducing handling damage. Urban ready-mix concrete plants and large infrastructure sites with silo infrastructure specify bulk for 80%+ of procurement in mature markets.
- Bulk Bags:One-tonne flexible intermediate bulk containers bridge the gap between bulk silo requirements and bagged flexibility for mid-scale projects.
- Bags:50kg woven polypropylene sacks serve rural construction and retail hardware channels where mechanized handling is unavailable.
- Paper Sacks:Multi-wall kraft construction for moisture-sensitive specialty formulations in premium positioning.
- Plastic Bags:Polyethylene variants for extreme humidity environments where moisture ingress degrades product quality.
Cost efficiency peaks in Bulk delivery. Format diversification is accelerating in Bulk Bags.
End User:
Procurement sophistication and technical specification authority vary sharply across buyer categories.
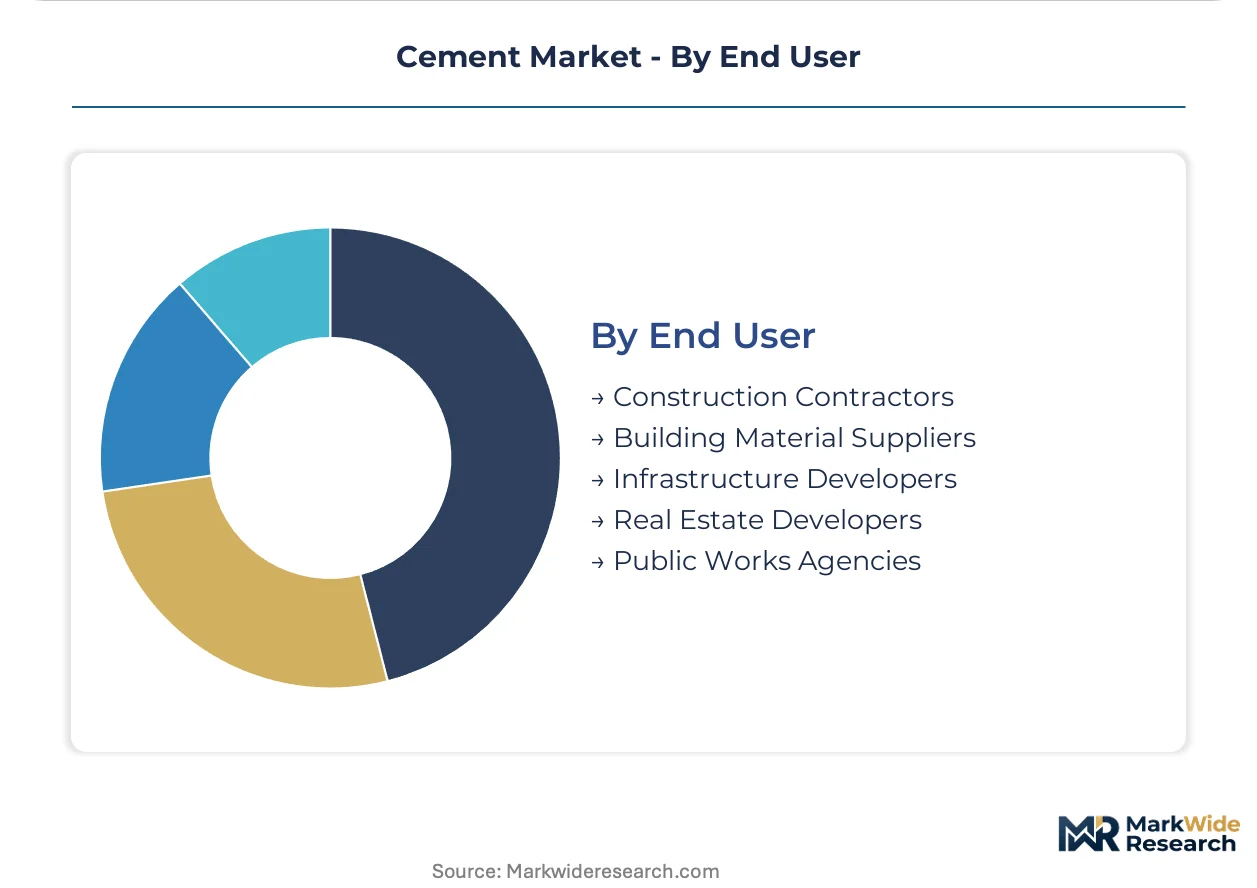
- Public Works Agencies:Central and state governments specify quality-certified product through competitive tender with price-indexed adjustment clauses. India's Ministry of Road Transport and Highways mandates IS 269 compliance with third-party testing for National Highway projects.
- Infrastructure Developers:Public-private partnership concessionaires negotiate long-term supply agreements with volume commitments and co-investment in dedicated capacity.
- Construction Contractors:Project-based procurement with spot market exposure and working capital constraints.
- Real Estate Developers:Vertical construction specialists with centralized procurement functions and sustainability scoring requirements.
- Building Material Suppliers:Distributor and retailer networks aggregating fragmented rural demand with inventory financing exposure.
Contract security is strongest with Public Works Agencies. Technical specification influence is concentrating with Infrastructure Developers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's National Infrastructure Pipeline absorbs record cement volumes as the dominant demand cluster across emerging economies. Regulatory divergence between carbon-intensive legacy capacity and low-carbon certification schemes is redirecting trade flows at major port complexes.
India
The National Infrastructure Pipeline drives unprecedented consumption of construction-grade cement for highway and dam foundations. India's BIS mandates IS 269 and IS 455 quality certifications for all domestic and imported product. Western Maharashtra and Gujarat host integrated grinding clusters supplying bulk deliveries to Mumbai-Ahmedabad corridor megaprojects.
China
Urban rail transit and hydropower expansions sustain massive clinker demand despite construction sector moderation. MIIT enforces dual carbon goals that cap emissions intensity per tonne of cement produced. The Yangtze River Delta concentration around Shanghai-Nanjing anchors domestic blending capacity for reduced-clinker formulations.
United States
Inflation Reduction Act infrastructure disbursements accelerate port and bridge rehabilitation contracts specifying bulk delivery. The US EPA enforces Portland cement Maximum Achievable Control Technology standards for particulate and mercury emissions. Texas and California grinding terminals capture barge and rail arbitrage from Mexican clinker imports.
Germany
Commercial high-rise cores in Frankfurt and Munich specify low-carbon cement for green building ratings compliance. The EU Green Deal's embedded carbon requirements restrict market access for high-clinker imports at Hamburg and Bremerhaven. The Rhine-Ruhr industrial corridor concentrates calcined clay activation R&D and alternative fuel co-processing infrastructure.
Vietnam
The North-South Expressway and Trans-Asia railway corridor generate multi-million-tonne annual cement commitments from sovereign-backed developers. The country's national construction regulator mandates quality testing for all public works procurement. Ha Long Bay limestone quarries and Hai Phong grinding terminals supply bulk deliveries to Red River Delta infrastructure sites.
Cement Market Key Industry Players
Capacity expansion dominates the current landscape as producers position grinding terminals near megaproject corridors. The vendor base concentrates among vertically integrated majors with captive limestone reserves and integrated distribution infrastructure. Two strategic archetypes prevail: scale-driven integrated producers controlling quarry-to-delivery value chains, and regional specialists leveraging proximate supplementary cementitious materials streams. M&A consolidation and strategic partnerships represent the dominant competitive moves, with majors acquiring grinding assets to secure offtake visibility.
Among Asia-Pacific-based producers, Anhui Conch Cement and China National Building Material exemplify scale-driven archetypes with integrated quarry and grinding positions. HeidelbergCement anchors the European low-carbon transition vector through calcined clay and alternative binder development. These three occupy positions that reflect divergent geographic risk exposure and decarbonization pathway selection across regulatory jurisdictions.
| Leading Market Players |
|---|
| HeidelbergCement |
| China Resources Cement |
| China National Building Material |
| Buzzi Unicem |
| CRH |
| Anhui Conch Cement |
| Cemex |
| Votorantim Group |
| Holcim |
| Others |
Cost & Logistics Intelligence
Process engineer scarcity in Germany's Rhine-Ruhr corridor widens labor-cost spreads between premium low-carbon formulations and commodity-grade output. This skill concentration feeds into pricing-tier differentiation as EU CBAM compliance costs compound with technical wage premiums.
Pricing Analysis
Input-cost pass-through from petcoke and natural gas volatility compresses margins at the economy tier while premium low-carbon grades capture carbon-cost recovery. Pricing stratifies across premium certified-low-carbon, standard blended, and economy Portland tiers. Cost compression in economy-grade clinker is intensifying because energy-intensive kilns absorb fuel price spikes without pricing power. Public works agencies exhibit highest price sensitivity through competitive tender structures, while infrastructure developers with sovereign backing show lowest sensitivity due to decade-long volume commitments.
Supply Chain Analysis
Single-source vulnerability sits with Turkish and North African clinker exporters facing EU CBAM documentation requirements at Mediterranean ports. Geographic supply concentration centers on China, India, and Vietnam for integrated grinding capacity. Raw material dependencies rest on captive limestone reserves, fly ash streams from proximate power plants, and granulated blast furnace slag from steel clusters. Tariff exposure from carbon border adjustments constitutes the dominant structural risk. Distribution runs through dedicated bulk terminals serving megaproject corridors and ready-mix concrete plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on calcined clay activation cost-down curves and premium-tier certification premiums displacing commodity-grade volume.
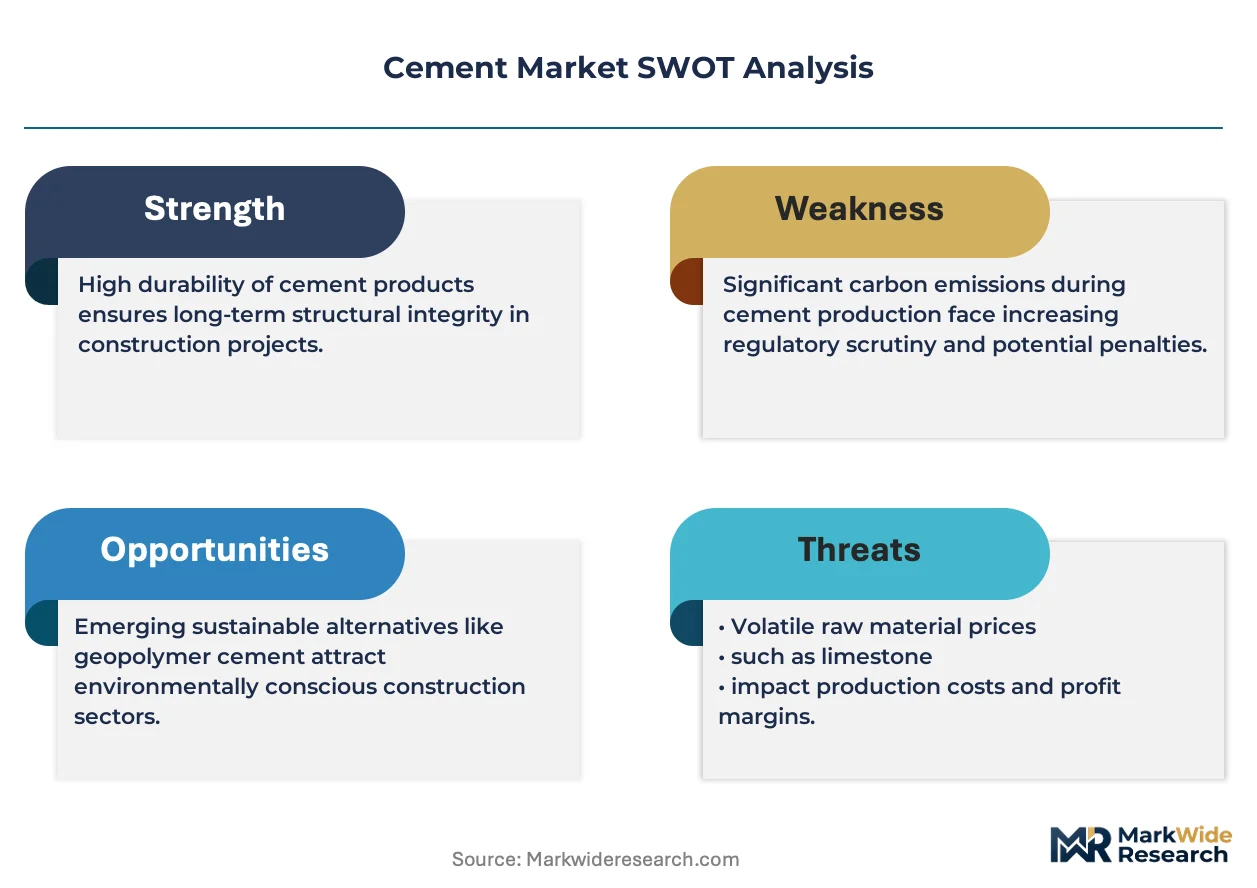
For Market Incumbents: Lock in long-term offtake agreements with India's National Infrastructure Pipeline concessionaires before CBAM-equivalent mechanisms spread to Asian markets. Secure captive limestone reserves in Vietnam's Red River Delta to defend against emerging regional specialists with proximate supplementary cementitious materials access. Prioritize calcined clay R&D investment to maintain specification authority as LC3 standards consolidate. For New Entrants and Emerging Players: Ready-mix concrete channel partners in Indonesia's Trans-Java corridor offer the most penetrable entry vector. Target blended cement supply to mid-scale infrastructure developers underserved by integrated majors. Pursue direct distribution partnerships bypassing fragmented trader networks. For Investors and Strategic Acquirers: Integrated cement majors with captive quarry positions are the most active acquirer in this space, consolidating grinding terminals near megaproject sites. Five-to-ten year viability favors producers with verified low-carbon production pathways and sovereign-contract backing. Watch for EU Innovation Fund disbursement acceleration as the inflection signal for carbon capture retrofit economics.| Strategic Initiative | Industry Significance |
|---|---|
| Calcined Clay Activation Scale-Up | LC3 production unifies kaolin and clinker supply chains under unified quality standards. |
| Carbon Capture Retrofit Installation | Post-combustion capture at existing kilns qualifies for EU Innovation Fund support. |
| Long-Term Supply Agreement Negotiation | Decade-long contracts with India's infrastructure developers lock in volume visibility. |
| Backward Integration into Limestone Reserves | Captive quarry access in Vietnam's Ha Long Bay region secures cost position. |
| Ready-Mix Concrete Channel Partnership | Direct distribution to construction majors bypasses fragmented trader networks. |
Research Approach
Direct dialogue with kiln operations managers, procurement leads at infrastructure developers, BIS certification auditors, and ready-mix concrete plant engineers grounded qualitative findings. Secondary validation drew from India BIS certification databases, EU CBAM transitional reporting disclosures, US EPA MACT enforcement records, and customs trade data. Bottom-up project pipeline analysis and top-down cement consumption modeling provided triangulation.
Output projections across the analysis window reflect segmented modeling by product type, application, packaging format, and end-user procurement sophistication. CAGRs were derived from volume-weighted growth rates across infrastructure, residential, commercial, and industrial demand clusters. Forecast inputs incorporated limestone reserve depletion curves, supplementary cementitious materials availability by regional industrial cluster, and carbon pricing trajectory assumptions.
Revisions become necessary when EU CBAM enforcement intensifies, India's infrastructure disbursement pace shifts, or calcined clay activation technology achieves cost parity with conventional clinker. Forecasts reflect documented assumptions about regulatory implementation timelines and energy price stabilization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Steel Sleepers Market
Building Materials
Europe Concrete Admixtures Market
Building Materials
United States Architectural Coatings Market
Building Materials
India Dry Mix Mortar Market
Building Materials
Concrete Admixtures Market
Building Materials
Light Gauge Steel Framing Market
Building Materials
Europe Fireproof Cladding Market
Building Materials
Asia-Pacific Shotcrete Market
Building Materials
Cribbing Blocks Market
Building Materials
North America Concrete Admixtures Market
Building Materials
Africa Green Cement Market
Building Materials
Australia Architectural Coatings Market
Building Materials
Gravity Retaining Wall Market
Building Materials
Fireproof Cladding Market
Building Materials
Italy Cement Market
Building Materials
GCC Concealed Cistern Market