
 Southeast Asia Repair and Rehabilitation Market | 2026-2036
Southeast Asia Repair and Rehabilitation Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Repair and Rehabilitation Market Analytics
Aftermarket service revenue for structural rehabilitation is fragmenting across Southeast Asia as contractors diversify from new-build dependence toward lifecycle asset management. Gamuda Berhad leverages its Malaysian infrastructure portfolio to capture recurring maintenance contracts on expressways and rail assets. PT Waskita Karya (Persero) Tbk anchors Indonesian government rehabilitation tenders through state-linked project pipelines. China Harbour Engineering Company Ltd competes on cost-engineered concrete repair packages for port and coastal defense structures across the region.
Repair and rehabilitation encompasses the technical restoration of structural integrity to deteriorated concrete, steel, and composite infrastructure using pressure grouting, carbon-fiber reinforcement, cathodic protection, and polymer-modified patching systems to extend service life and restore load-bearing capacity. The industrial purpose centers on deferring capital replacement while meeting updated seismic and safety performance thresholds. Infrastructure application dominates contract value across Southeast Asia, while sustainable solutions technology is gaining fastest traction as green financing instruments attach to retrofit projects. Modern techniques such as automated structural monitoring and drone-assisted damage assessment are concentrating margin pools in technology-integrated service bundles rather than labor-only repair.
Indonesia's Ministry of Public Works and Housing enforces national building codes that mandate periodic structural audits for public facilities, directly stimulating certified rehabilitation demand. Malaysia's Construction Industry Development Board aligns contractor licensing with continuing education in repair methodologies, restricting market access to qualified practitioners. Vietnam's Ministry of Construction issues technical standards for post-disaster structural assessment that shape procurement specifications for international contractors. Stakeholders must monitor how ASEAN mutual recognition arrangements for engineering qualifications reshape competitive boundaries between domestic and cross-border service providers.
Market Dynamics
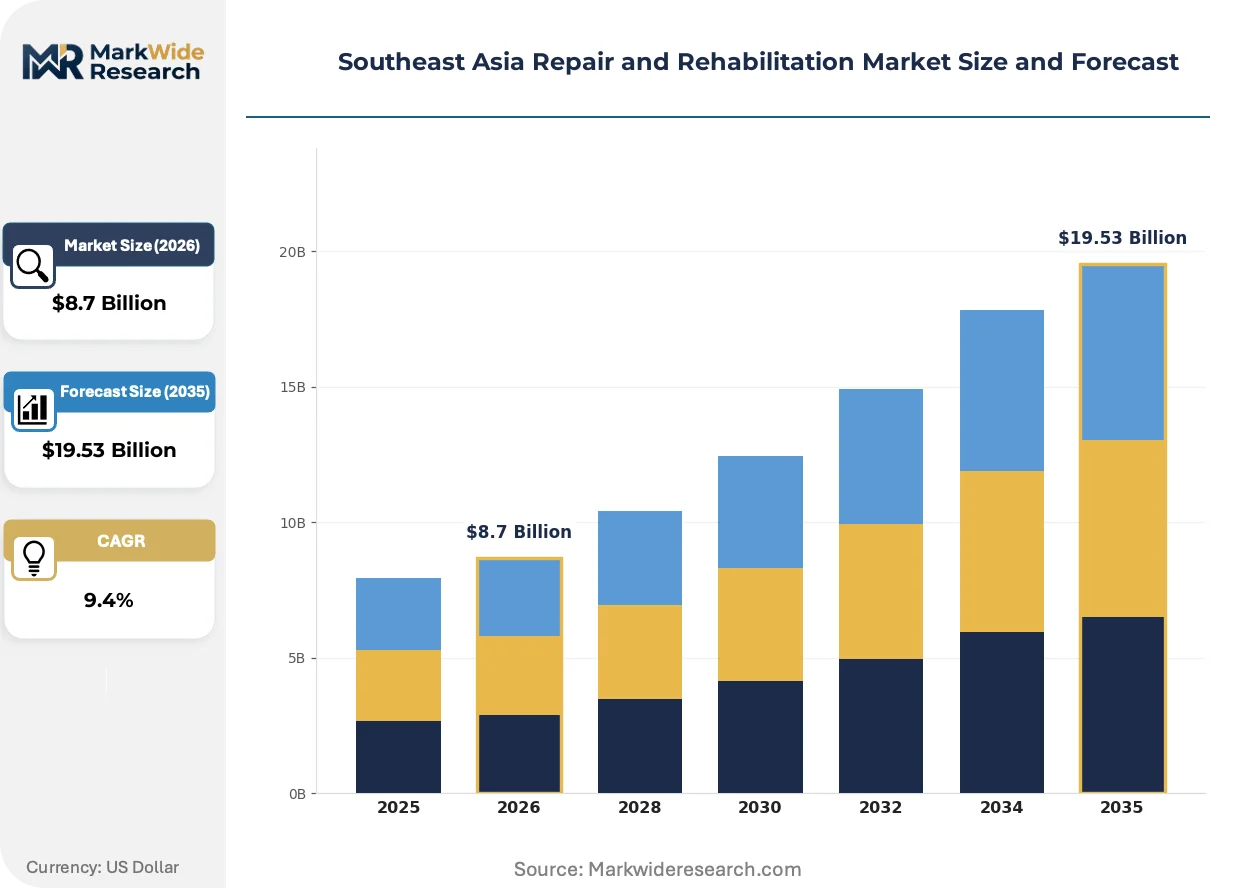
Seismic retrofit mandates across Indonesia's Java corridor are compressing contractor procurement timelines while redirecting technical capacity from new-build toward lifecycle asset preservation. Government enforcement of structural audit cycles is institutionalizing recurring revenue streams for certified rehabilitation specialists.
Growth Catalysts
- Carbon-fiber reinforcement systems:Lightweight composite materials are displacing steel plate bonding in bridge deck repairs across Vietnamese expressway networks. Transportation agencies specify CFRP for rapid-lane-reopening protocols.
- Malaysia's green building retrofit standards:The Construction Industry Development Board ties contractor licensing to sustainable rehabilitation credentials. Green financing instruments now attach performance clauses to material lifecycle assessments.
- Post-disaster assessment protocols:Vietnam's Ministry of Construction mandates rapid structural evaluation frameworks after seismic events. International contractors compete for emergency rehabilitation tenders under accelerated procurement windows.
Market Restraints
- Specialized polymer-modified patching compounds:Import dependence on Japanese and European chemical suppliers exposes margins to currency volatility and maritime freight congestion.
- Cathodic protection system integration:Coastal defense structures in the Philippines require marine-grade anode materials with limited regional fabrication capacity.
- Technical qualification reciprocity gaps:ASEAN mutual recognition arrangements for engineering credentials remain incomplete, fragmenting cross-border service deployment.
Strategic Opportunities
- Drone-assisted damage assessment:Aerial LiDAR and photogrammetry are compressing structural survey timelines for Indonesian toll-road operators. Technology-integrated service bundles capture margin pools unavailable to labor-only contractors.
- Philippines secondary city infrastructure:Cebu and Davao municipal governments lack in-house rehabilitation capacity. International specialists can establish maintenance partnerships before local competitors consolidate.
- Pressure grouting automation:Robotic injection systems are converging with real-time grout flow monitoring. Equipment suppliers can lease integrated platforms to mid-tier contractors unable to fund capex directly.
Industry Challenges
- Certified welding technician scarcity:Steel bridge rehabilitation in Indonesia outpaces vocational training pipeline output. Contractors poach qualified personnel across project sites, inflating labor costs.
- Polymer-curing environmental controls:Tropical humidity in Malaysian coastal zones degrades epoxy bond strength. Contractors must deploy climate-controlled enclosures, compressing project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Repair and Rehabilitation Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Maintenance, Restoration, Refurbishment, Reconstruction Application: Infrastructure, Residential, Commercial, Industrial End User: Government, Private Sector, Non-Profit, Contractors Technology: Traditional Methods, Modern Techniques, Sustainable Solutions, Smart Repairs |
| Companies Covered | CHEC Construction (M) Sdn Bhd, China Harbour Engineering Company Ltd, China State Construction Engineering Corporation, Gamuda Berhad, Penta-Ocean Construction Co Ltd, PT Pembangunan Perumahan (Persero) Tbk, PT Surya Cipta Teknik, PT Jaya Teknik Indonesia, PT Waskita Karya (Persero) Tbk, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Repair and Rehabilitation Market Evolving Landscape
Automated structural monitoring systems are displacing manual inspection regimes across Southeast Asian infrastructure portfolios. Real-time sensor networks enable predictive maintenance scheduling that compresses rehabilitation cycle timing.
Embedded fiber-optic strain sensors are digitizing load-path analysis for aging concrete viaducts. Indonesian state highway authorities deploy these systems on Java corridor toll bridges to prioritize intervention sequencing. Continuous data streams compress engineering assessment timelines from weeks to hours, reallocating specialist labor toward design rather than diagnosis.
Malaysia's Construction Industry Development Board now mandates continuing education modules in non-destructive evaluation techniques for contractor license renewal. The policy forces technical upskilling across mid-tier firms previously reliant on visual inspection protocols. Steel and concrete specialists must demonstrate proficiency in ultrasonic pulse velocity and ground-penetrating radar interpretation to bid on public rehabilitation contracts.
Asset owners in Vietnam's port sector are unbundling engineering design from construction execution in rehabilitation tenders. Terminal operators separately procure structural assessment services, then competitively bid implementation work. This disintermediation compresses contractor margins on bundled contracts while creating specialized niches for technology-focused inspection firms. Ho Chi Minh City container terminals pilot this model for quay wall corrosion remediation programs.
Southeast Asia Repair and Rehabilitation Market Segmentation
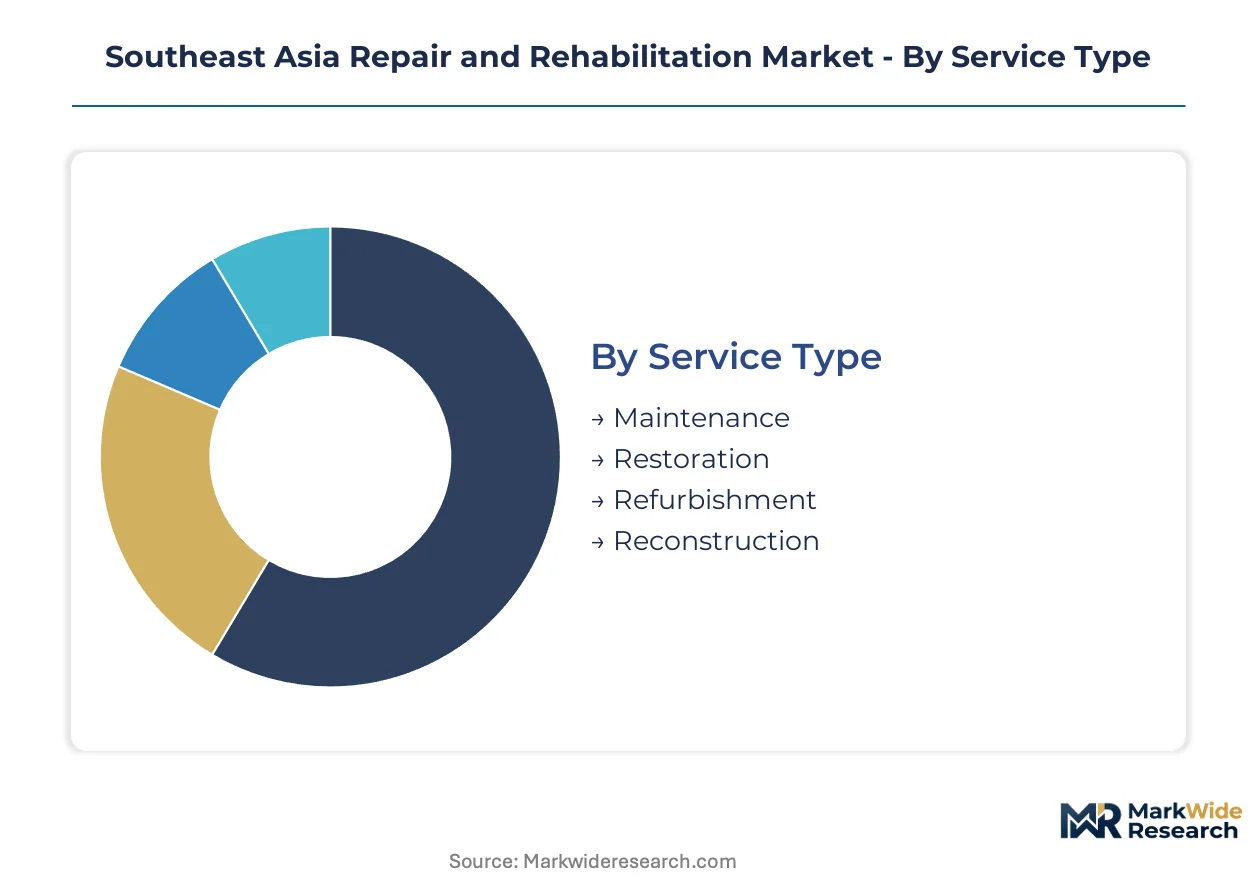
Segmentation in the Southeast Asia repair and rehabilitation market reveals how contract value, technical complexity, and procurement authority distribute across distinct service configurations. Understanding these divisions enables contractors to align capability investments with where margin pools concentrate.
Service Type:
Mature maintenance contracts dominate recurring revenue while reconstruction represents the emerging high-value frontier as seismic mandates intensify.
- Maintenance:Scheduled inspection and preventive intervention on bridges, tunnels, and public buildings using pressure grouting and polymer patching. Indonesian state highway authorities on the Java corridor bundle these into multi-year frameworks that guarantee contractor cash flow visibility.
- Restoration:Structural integrity recovery for heritage assets and aging public facilities requiring material compatibility with original construction. Demand clusters in Malaysian urban cores where CIDB licensing mandates govern heritage-sensitive methodologies.
- Refurbishment:Functional upgrade of building systems without structural intervention, common in commercial retrofits.
- Reconstruction:Complete rebuild of failed or obsolete structures following disaster events or service-life expiration.
Maintenance handles the majority of throughput; reconstruction is the fastest mover on share.
Application:
Cost tier separation runs deep between capital-intensive infrastructure and margin-compressed residential work.
- Infrastructure:Bridge deck repairs, seawall rehabilitation, and tunnel lining replacement using cathodic protection and carbon-fiber reinforcement. Vietnamese expressway networks specify CFRP for rapid-lane-reopening protocols that minimize traffic disruption revenue loss.
- Residential:Individual building structural repairs and facade restoration, typically procured through fragmented owner-direct contracts.
- Commercial:Office and retail retrofit programs driven by green building certification requirements in Kuala Lumpur and Singapore.
- Industrial:Manufacturing facility floor slab repairs and corrosion protection for process equipment foundations.
Infrastructure commands the highest contract values; commercial is expanding most quickly as green financing instruments attach to retrofit projects.
End User:
Customer type determines procurement sophistication and payment security across the region.
- Government:National and provincial agencies procuring through tender processes with extended payment cycles but volume concentration. Indonesia's Ministry of Public Works and Housing mandates periodic structural audits that feed directly into certified rehabilitation demand pipelines.
- Private Sector:Corporate asset owners and real estate investment trusts prioritizing lifecycle cost optimization over lowest-bid selection.
- Non-Profit:Limited procurement activity concentrated in post-disaster humanitarian reconstruction.
- Contractors:Subcontracted specialist services for tier-one builders lacking in-house rehabilitation capability.
Government accounts for the dominant procurement volume; private sector is climbing the fastest as institutional investors professionalize asset management.
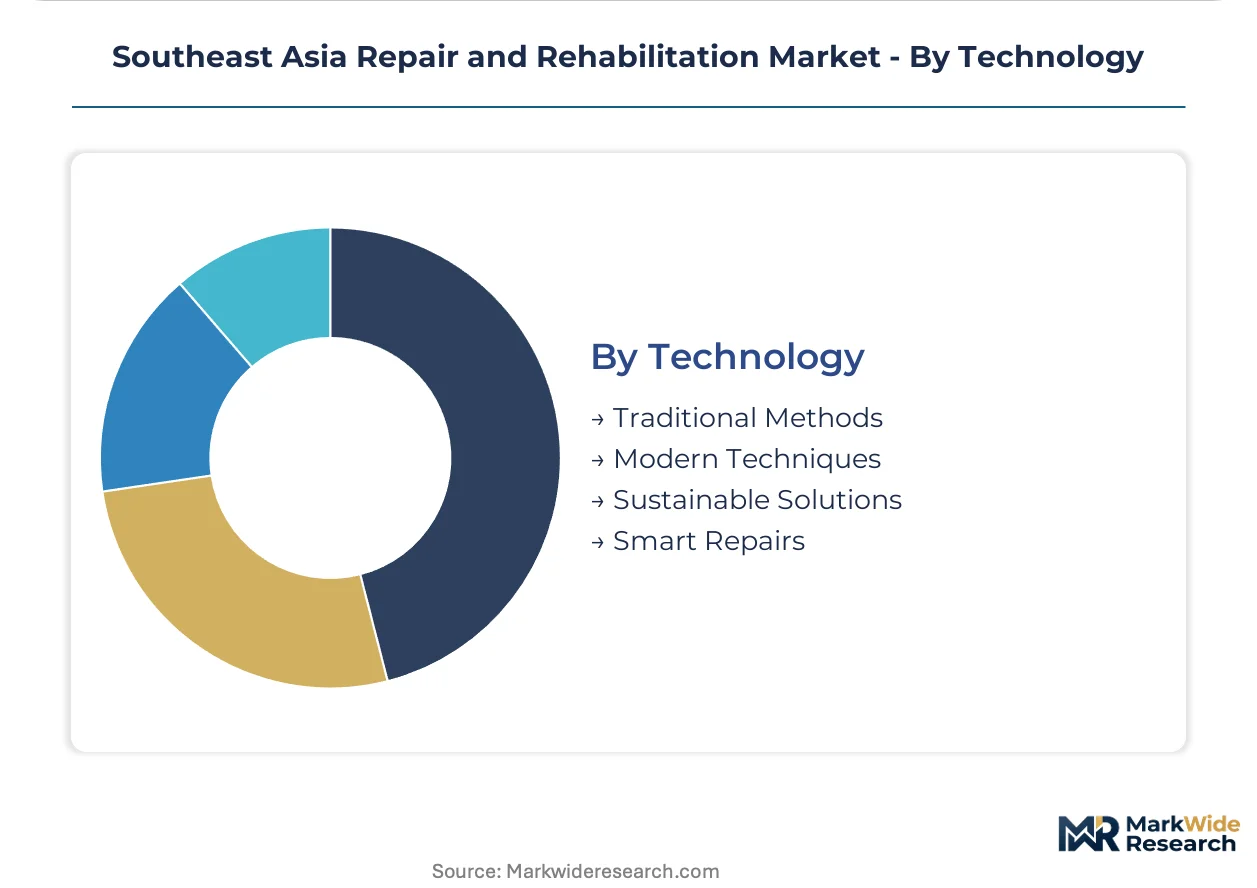
Technology:
Supply concentration in equipment and materials creates tiered access barriers between technology categories.
- Traditional Methods:Manual concrete removal, steel plate bonding, and visual inspection protocols. Philippine mid-tier contractors rely on these for cost-engineered coastal defense repairs where marine-grade anode materials face import constraints.
- Modern Techniques:Automated structural monitoring, drone-assisted damage assessment, and robotic pressure grouting. Indonesian toll-road operators deploy aerial LiDAR to compress survey timelines from weeks to hours.
- Sustainable Solutions:Low-carbon material alternatives and lifecycle-assessed retrofit systems required for green financing eligibility in Malaysia.
- Smart Repairs:Embedded fiber-optic strain sensors and real-time predictive maintenance platforms for aging viaduct prioritization.
Traditional methods still process the highest contract count; smart repairs are gaining share fastest as sensor costs decline and data analytics capability spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia concentrates rehabilitation demand in seismic retrofit mandates, while Malaysia diverges toward green-certified building retrofits and Vietnam prioritizes rapid post-disaster assessment frameworks. Each national market deploys repair capital toward distinct structural risk profiles.
Indonesia
Java corridor toll-road operators and state highway authorities drive contract volume through multi-year maintenance frameworks. The Ministry of Public Works and Housing enforces periodic structural audit cycles that feed certified rehabilitation pipelines. Jakarta and Surabaya anchor demand clusters where seismic retrofit requirements converge with network expansion programs.
Malaysia
Green building retrofit standards redirect contractor investment toward sustainable material lifecycle assessments. The Construction Industry Development Board ties licensing renewal to continuing education in non-destructive evaluation techniques. Kuala Lumpur commercial asset owners attach green financing performance clauses to rehabilitation procurement specifications.
Vietnam
Expressway networks specify carbon-fiber reinforcement for rapid-lane-reopening protocols that minimize traffic disruption revenue loss. The Ministry of Construction mandates technical standards for post-disaster structural assessment that shape international contractor procurement. Ho Chi Minh City container terminals pilot disaggregated tender models separating engineering design from construction execution.
Philippines
Cebu and Davao municipal governments lack in-house rehabilitation capacity, creating partnership entry points for international specialists. Coastal defense structures require marine-grade anode materials with limited regional fabrication capacity. Manila Bay port authorities procure cathodic protection systems under accelerated emergency rehabilitation windows.
Singapore
Institutional asset owners professionalize lifecycle cost optimization over lowest-bid selection for commercial and industrial retrofit programs. The Building and Construction Authority mandates periodic structural integrity assessments for aging public housing stock. Jurong industrial zone operators deploy automated structural monitoring for predictive maintenance scheduling on process equipment foundations.
Southeast Asia Repair and Rehabilitation Market Competitive Landscape
Capability concentration sits with state-linked contractors holding privileged access to government tender pipelines; scale advantage sits with diversified infrastructure conglomerates leveraging cross-sector project portfolios. The market structures around three archetypes: domestic state-owned enterprises anchoring public procurement, regional diversified contractors capturing recurring maintenance frameworks, and international specialists competing on cost-engineered technical packages. Competitive moves center on technology licensing for automated monitoring systems and strategic partnerships to secure green financing eligibility.
Among Malaysian infrastructure conglomerates, Gamuda Berhad occupies a position exemplifying the diversified contractor archetype through expressway and rail asset portfolios. Indonesian state-linked contractors PT Waskita Karya (Persero) Tbk and PT Pembangunan Perumahan (Persero) Tbk represent the domestic public-sector tier with privileged pipeline access. China Harbour Engineering Company Ltd sits within the international specialist segment competing on coastal and port structure rehabilitation packages.
| Leading Market Players |
|---|
| CHEC Construction (M) Sdn Bhd |
| China Harbour Engineering Company Ltd |
| China State Construction Engineering Corporation |
| Gamuda Berhad |
| Penta-Ocean Construction Co Ltd |
| PT Pembangunan Perumahan (Persero) Tbk |
| PT Surya Cipta Teknik |
| PT Jaya Teknik Indonesia |
| PT Waskita Karya (Persero) Tbk |
| Others |
Value Network & Pricing Analysis
Johor Bahru's polymer-modified patching compound manufacturing cluster anchors regional supply capacity, with its production dynamics directly translating into pricing power for Indonesian and Vietnamese contractors bidding on seismic retrofit frameworks. Japanese and European chemical suppliers dominate specialty resin formulations, compressing margins for mid-tier rehabilitation specialists dependent on imported cathodic protection anodes.
Pricing Analysis
Project-based contracting structures dominate Southeast Asian rehabilitation procurement, with multi-year maintenance frameworks from Indonesian state highway authorities offering cash flow visibility against spot-market spot purchases for emergency post-disaster interventions. Price differentiation centers on certification tier under Malaysia's CIDB licensing regime and vertical integration into carbon-fiber reinforcement material supply. Pricing pressure stems from currency volatility affecting Japanese epoxy resin imports, with government procurement entities showing lowest price sensitivity due to mandated structural audit compliance deadlines.
Supply Chain Analysis
Tariff exposure between Japan and Indonesia disrupts carbon-fiber sheet and specialty polymer supply schedules for bridge deck rehabilitation contractors. Manufacturing concentrates in Japan, Germany, and South Korea for high-performance composite materials, while regional fabrication for marine-grade anodes remains underdeveloped in the Philippines. Raw material dependencies include epoxy resins, carbon-fiber prepregs, and zinc-alloy anode materials. Distribution runs through authorized chemical distributors and direct OEM relationships with port authorities and toll-road operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
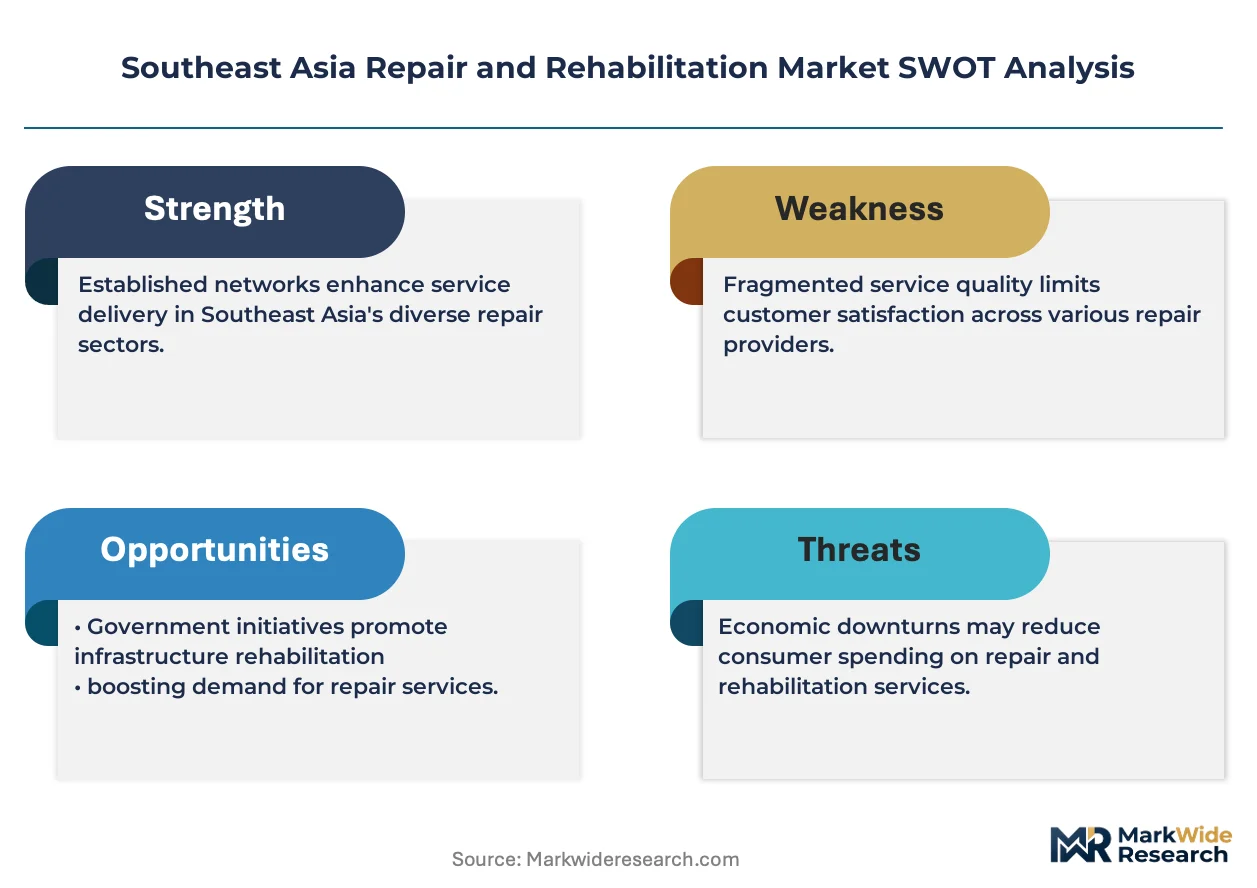
This market functions as a regulatory-entrenchment defensive moat. Contractor licensing requirements under Malaysia's CIDB and Indonesia's Ministry of Public Works and Housing create switching costs that protect incumbent positions from unqualified competitors.
For Market Incumbents: Harden certification barriers by accelerating investment in non-destructive evaluation training modules before CIDB mandates expand across ASEAN mutual recognition arrangements. Deepen backward integration into carbon-fiber reinforcement material supply to offset Japanese import cost volatility threatening steel bridge rehabilitation margins. Lock in multi-year Java corridor maintenance frameworks before international specialists establish local fabrication partnerships.
For New Entrants and Emerging Players: Secondary city municipal governments in Cebu and Davao represent the most penetrable entry point, with these localities lacking in-house rehabilitation capacity and emergency procurement windows accelerating vendor qualification. Drone-assisted damage assessment technology bundles offer a differentiated go-to-market angle against labor-only contractors, capturing margin pools from Indonesian toll-road operators compressing survey timelines.
For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because seismic retrofit mandates and structural audit cycles institutionalize maintenance contract visibility independent of new-build construction cycles. Acquisition targets should emphasize technology-integrated service providers with automated monitoring system deployment capability. Monitor ASEAN engineering qualification reciprocity negotiations as the signal for cross-border competitive boundary shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing for Automated Monitoring | Embedded fiber-optic sensor deployment captures predictive maintenance contracts from Indonesian state highway authorities. |
| Green Certification Investment | Malaysia's CIDB continuing education mandates create competitive exclusion for uncredentialed rehabilitation contractors. |
| Regional Fabrication Partnership | Local marine-grade anode production reduces Philippine coastal defense project exposure to import freight congestion. |
| Multi-Year Maintenance Framework | Indonesian Java corridor toll-road operators guarantee cash flow visibility through bundled preventive intervention contracts. |
| Drone-Assisted Assessment Capability | Aerial LiDAR integration compresses structural survey timelines from weeks to hours for Vietnamese expressway networks. |
Research Methodology
Cross-validation between primary interviews with infrastructure asset managers and secondary trade data anchors the qualitative findings on procurement pattern shifts across the analysis window. The research team conducted structured discussions with toll-road operation executives, structural engineering consultants, government procurement officers at Indonesia's Ministry of Public Works and Housing, and chemical distribution specialists. Secondary validation drew from customs records on polymer and composite material imports, ASEAN construction industry development board policy filings, and infrastructure maintenance contract award disclosures. Bottom-up project pipeline assessments triangulate against top-down national infrastructure budget allocations.
Calibration against historical contract award patterns and disclosed maintenance framework values stabilizes the segmentation-level projections across service type, application, and technology categories. The analytical framework models infrastructure versus commercial versus residential end-use splits alongside traditional versus modern versus smart repair technique adoption curves. CAGRs derive from disclosed government infrastructure spending trajectories and contractor backlog growth patterns. Forecast inputs include seismic retrofit mandate enforcement timelines and green financing instrument attachment rates to building retrofit specifications.
Practitioners should monitor ASEAN mutual recognition arrangement completion for engineering qualifications and Japanese-European chemical supplier capacity expansion announcements for early signals of competitive boundary shifts. Forecasts reflect assumptions on continued government enforcement of structural audit cycles and stable maritime freight corridors for specialty material imports. Macroeconomic currency volatility, regulatory acceleration of green building standards, or breakthroughs in robotic pressure grouting automation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction and Engineering
Curtain Wall Market
Construction and Engineering
Latex Caulk Market
Construction and Engineering
Machined Springs Market
Construction and Engineering
Acoustic Ceiling Tiles Market
Construction and Engineering
Saudi Arabia Transportation Infrastructure Construction Market
Construction and Engineering
Europe Forklift Truck Market
Construction and Engineering
Wall Hung Boilers Market
Construction and Engineering
Rubber Track Pads for Construction Machinery Market
Construction and Engineering
Loader Bucket Attachments Market
Construction and Engineering
Digital Cutting Machine Market
Construction and Engineering
Precast Concrete Retaining Walls Market
Construction and Engineering
North America Concrete Cellulose Fiber Reinforcement Market
Construction and Engineering
Asia-Pacific Waterproofing Solutions Market
Construction and Engineering
Oil and Gas Pipeline Fabrication and Construction Market
Construction and Engineering
Wood Shingles Market
Construction and Engineering
Manual Welding Positioner Market