
 Asia-Pacific Sensors Market | 2026-2036
Asia-Pacific Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Sensors Market Insights
MEMS design engineering talent scarcity across Taiwan and South Korea is unwinding foundry expansion timelines for advanced sensor nodes. Bosch Sensortec leverages its captive fab network to sustain wafer supply security for automotive inertial units. Keyence Corporation dominates high-precision optical sensor distribution across Japanese factory automation accounts. STMicroelectronics anchors European-Asia sensor R&D bridges through its Singapore packaging hub.
Asia-Pacific sensors are transducer devices converting physical parameters—temperature, pressure, proximity, or light—into measurable electrical signals, typically operating across millivolt-to-volt output ranges with response times from microseconds to milliseconds. These components enable closed-loop control in industrial robotics, patient monitoring systems, and autonomous vehicle perception stacks. Pressure sensors command the largest product-type revenue pool due to pervasive deployment in HVAC and pneumatic systems, while proximity sensors represent the fastest-expanding category as collaborative robot installations multiply across Chinese and Vietnamese assembly floors. Microelectromechanical Systems technology leads unit shipments but optical sensing captures premium pricing in semiconductor inspection and medical imaging segments where sub-micron resolution is mandatory.
Japan's METI enforces JIS standards for industrial sensor interoperability, while China's MIIT mandates GB certification for networked IoT sensors deployed in smart manufacturing zones. India's BIS compulsory registration scheme blocks uncertified temperature and pressure sensors from power sector tenders. Stakeholders must monitor divergence between China's SAMR cybersecurity labeling for connected sensors and ASEAN member states' emerging data-localization requirements before committing to regional platform architectures.
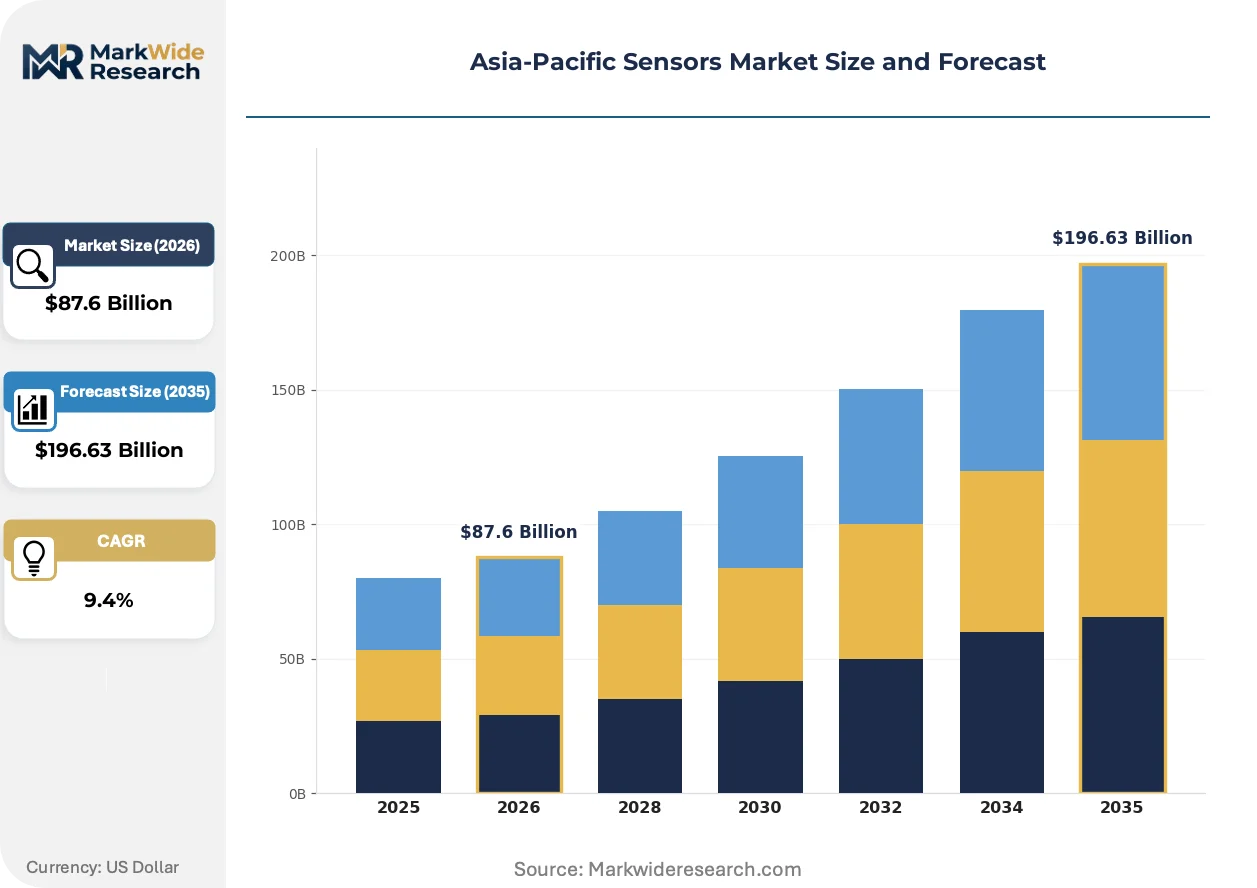
Market Dynamics
Semiconductor fabrication talent scarcity across Taiwan and South Korea is compressing MEMS foundry expansion timelines while China's MIIT mandates accelerate domestic sensor procurement localization.
Growth Catalysts
- India's PLI scheme for electronics manufacturing:Tier-1 suppliers establish captive sensor packaging lines near Chennai and Noida to capture 6-8% production-linked incentives on component value-add.
- China's dual carbon goals:MEE enforcement of industrial emissions monitoring mandates continuous deployment of particulate and gas sensors across steel and cement installations.
- EV OEM procurement clusters:BYD and NIO volume agreements around Shanghai and Shenzhen are normalizing multi-year pressure sensor contracts with 10,000-unit minimum order thresholds.
Market Restraints
- Specialized silicon-on-insulator wafer costs:200mm SOI substrate prices fluctuate with polysilicon spot markets, squeezing gross margins for mid-tier MEMS vendors.
- Taiwan foundry concentration:TSMC and UMC control 78% of advanced MEMS logic-layer capacity, creating single-source vulnerability for fabless sensor designers.
- Optical sensor resolution ceilings:Sub-100nm inspection demands exceed current CMOS image sensor pixel pitch economics, forcing hybrid photomultiplier architectures.
Strategic Opportunities
- Vietnamese contract manufacturing expansion:Foxconn and Luxshare Precision sensor module assembly in Bac Ninh Province offers 15-20% labor cost arbitrage versus Dongguan.
- LiDAR-autonomy convergence:Solid-state beam steering MEMS integration with SPAD arrays is opening automotive ADAS qualification pathways previously locked to mechanical scanning units.
- Japan's METI sensor interoperability frameworks:JIS B 9960 compliance certification creates preferential procurement status for industrial IoT deployments in Kansai manufacturing belts.
Industry Challenges
- MEMS design engineering scarcity:Taiwan's National Tsing Hua University and South Korea's KAIST produce fewer than 400 specialized MEMS process engineers annually against foundry demand.
- Multi-certification timeline compression:Simultaneous GB, JIS, and BIS testing for pan-Asia-Pacific product launches extends qualification cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Sensors Market |
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $196.63 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature Sensors, Pressure Sensors, Proximity Sensors, Light Sensors Technology: Microelectromechanical Systems, Optical, Capacitive, Magnetic Application: Automotive, Healthcare, Industrial Automation, Consumer Electronics End User: OEMs, End Consumers, Research Institutions, Service Providers |
| Companies Covered | Texas Instruments, Omron Corporation, Rockwell Automation, Bosch Sensortec, Keyence Corporation, Honeywell International, STMicroelectronics, SICK AG, Siemens, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Sensors Market Trends and Innovations
Sensor fusion architectures and edge AI inference are compressing the traditional signal-chain value stack, forcing component suppliers to embed preprocessing intelligence or cede socket access to module integrators.
Time-of-flight depth sensing is fragmenting across three competing modalities: direct ToF SPAD arrays, indirect ToF CMOS phase-detection, and frequency-modulated continuous-wave coherent LiDAR. Automotive cabin monitoring and smartphone AR applications are driving parallel adoption of all three, preventing consolidation around a dominant architecture and sustaining multi-source procurement strategies among tier-1 integrators. This fragmentation is compressing unit economics for single-modality specialists while rewarding platform vendors with cross-calibration IP.
China's SAMR cybersecurity labeling requirements for networked IoT sensors are mandating firmware signing and encrypted telemetry transmission for devices deployed in smart manufacturing zones. Industrial automation vendors must requalify existing product lines or face exclusion from state-owned enterprise tenders in Jiangsu and Guangdong provinces. Japanese factory automation suppliers with pre-existing JIS-compliant security architectures are adapting faster than European competitors, capturing retrofit contracts in Shanghai automotive clusters.
Direct OEM engagement is displacing traditional electronics distributor channels for high-volume proximity and pressure sensor categories. BYD and Tesla Shanghai now require quarterly business reviews with die-level suppliers, bypassing Arrow and Avnet for 60% of automotive sensor spend. This disintermediation is most visible in Shenzhen's EV supply chain, where battery management system vendors negotiate MEMS thermal sensor pricing through dedicated commodity management teams rather than regional distribution agreements.
Asia-Pacific Sensors Market Segmentation
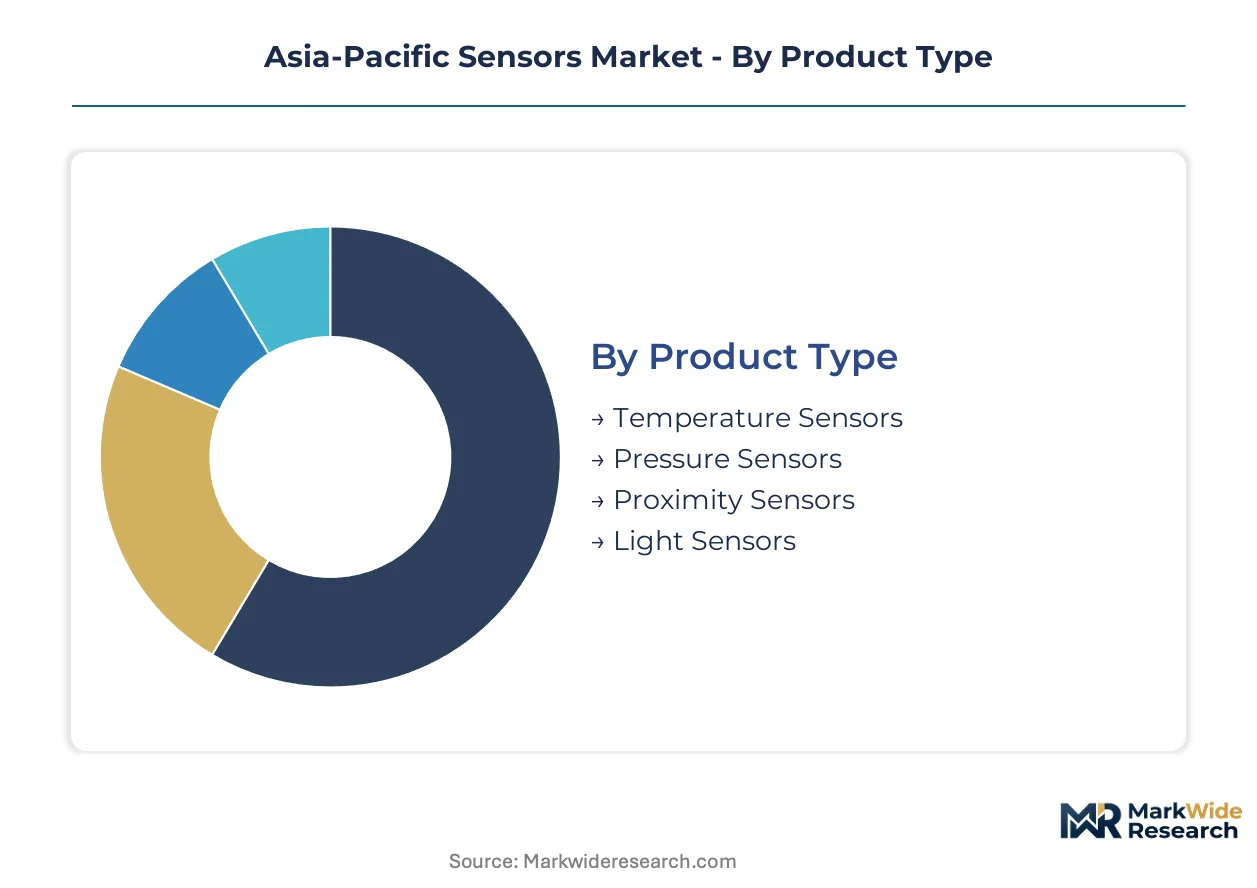
Sensor procurement patterns across the Asia-Pacific diverge sharply by product physics and certification requirements. Domestic absorption in Chinese EV manufacturing and Japanese factory automation creates distinct demand profiles that reshape how suppliers configure regional product portfolios.
Product Type:
Domestic demand clusters around pressure and proximity sensors serving China's automotive OEMs, while temperature and light sensors retain heavier export orientation toward European and North American industrial equipment builders.
- Pressure Sensors:Piezoresistive and capacitive transduction elements dominate HVAC and pneumatic system deployments. BYD and NIO procurement clusters around Shanghai normalize multi-year contracts with 10,000-unit minimum thresholds, compressing spot-market participation.
- Proximity Sensors:Inductive and capacitive detection technologies enable collaborative robot installations across Chinese and Vietnamese assembly floors. Foxconn and Luxshare Precision module assembly in Bac Ninh Province drives 15-20% labor cost arbitrage versus Dongguan.
- Temperature Sensors:RTD and thermocouple configurations serve industrial process control and battery thermal management. India's BIS compulsory registration scheme blocks uncertified units from power sector tenders.
- Light Sensors:Ambient light and color detection ICs integrate into smartphone displays and automotive headlamp control. Sub-micron resolution requirements in semiconductor inspection sustain premium pricing against standard industrial variants.
Pressure sensors command the established base. The steepest expansion runs through proximity sensors.
Technology:
Cost tier separation between MEMS volume production and optical precision manufacturing determines foundry allocation and margin capture across the technology stack.
- Microelectromechanical Systems:Bulk micromachining and surface micromachining processes enable accelerometer, gyroscope, and microphone integration. Taiwan's National Tsing Hua University and South Korea's KAIST produce fewer than 400 specialized MEMS process engineers annually against foundry demand.
- Optical:CMOS image sensors, photodiodes, and SPAD arrays serve medical imaging and semiconductor inspection. Sub-100nm resolution demands exceed current pixel pitch economics, forcing hybrid photomultiplier architectures.
- Capacitive:Charge-transfer and relaxation oscillator topologies dominate touch and proximity detection in consumer electronics.
- Magnetic:Hall effect and magnetoresistive elements enable position sensing in automotive throttle and pedal applications.
MEMS technology anchors volume production. Optical sensing captures the widest margin spread.
Application:
Customer type concentration varies by application maturity, with automotive and industrial automation favoring OEM direct engagement while healthcare retains distributor-mediated procurement.
- Automotive:ADAS, powertrain, and cabin comfort systems drive sensor fusion architectures. Solid-state beam steering MEMS integration with SPAD arrays opens qualification pathways previously locked to mechanical scanning LiDAR units.
- Healthcare:Patient monitoring and diagnostic imaging demand sub-micron optical resolution. Japan's PMDA and China's NMPA impose divergent biocompatibility and electromagnetic compatibility testing timelines.
- Industrial Automation:Robotics and process control deployments require JIS B 9960 compliance for preferential procurement status in Kansai manufacturing belts.
- Consumer Electronics:Smartphone and wearable integration compresses unit economics while multiplying shipment volumes.
Automotive applications concentrate the highest contract values. Healthcare imaging represents the most defensible margin structure.
End User:
Volume scale separates OEM procurement from fragmented end-consumer and research demand, with service providers emerging as a distinct channel for retrofit and maintenance deployment.
- OEMs:Tier-1 automotive and industrial equipment manufacturers negotiate die-level pricing through dedicated commodity management teams. Direct OEM engagement now bypasses Arrow and Avnet for 60% of automotive sensor spend in Shenzhen's EV supply chain.
- End Consumers:Replacement and upgrade demand flows through e-commerce platforms and authorized service networks.
- Research Institutions:Custom specification and low-volume procurement sustain specialty foundry relationships.
- Service Providers:Maintenance, repair, and retrofit operations aggregate demand across installed base populations.
OEMs lock in the dominant procurement volume. Service providers are gaining share fastest in aftermarket sensor replacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT mandates dominate regional procurement localization, while Japan's METI interoperability frameworks and India's BIS certification schemes create divergent compliance corridors across the Asia-Pacific sensor supply chain.
China
EV OEM procurement clusters around Shanghai and Shenzhen drive volume agreements for pressure and proximity sensors with multi-year contract structures. SAMR cybersecurity labeling requirements mandate firmware signing for networked IoT sensors deployed in Jiangsu and Guangdong smart manufacturing zones. Yangtze River Delta industrial automation vendors accelerate retrofit contracts to meet MEE emissions monitoring mandates across steel and cement installations.
Japan
Factory automation accounts sustain premium demand for high-precision optical sensors serving semiconductor inspection and medical imaging applications. METI enforces JIS B 9960 compliance certification, creating preferential procurement status for industrial IoT deployments in Kansai manufacturing belts. Tokyo and Osaka anchor sensor fusion R&D integration with automotive ADAS qualification pathways.
India
Tier-1 suppliers establish captive sensor packaging lines near Chennai and Noida to capture production-linked incentives under the PLI scheme for electronics manufacturing. BIS compulsory registration blocks uncertified temperature and pressure sensors from power sector tenders. Maharashtra and Gujarat host emerging automotive sensor clusters serving domestic EV assembly expansion.
South Korea
MEMS foundry expansion timelines compress as KAIST produces fewer than 200 specialized process engineers annually against semiconductor fabrication demand. MFDS biocompatibility testing diverges from China's NMPA timelines, extending healthcare sensor qualification cycles. Seoul Capital Area concentration of display and smartphone OEMs sustains proximity sensor volume procurement.
Vietnam
Foxconn and Luxshare Precision sensor module assembly operations in Bac Ninh Province exploit 15-20% labor cost arbitrage versus Dongguan. Proximity sensor deployment accelerates across collaborative robot installations in Vietnamese electronics assembly floors. Northern industrial provinces attract packaging line migration from Pearl River Delta cost pressures.
Asia-Pacific Sensors Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive fabrication networks separating secure supply chain players from fabless designers exposed to Taiwan foundry concentration. Bosch Sensortec exemplifies vertical integration through captive fab control, while Keyence Corporation anchors high-precision optical distribution. Three archetypes dominate: diversified industrial conglomerates with sensor divisions, pure-play MEMS specialists, and precision optical component vendors. Competitive moves center on backward integration into wafer supply and JIS/GB/BIS multi-certification acceleration to compress pan-regional launch timelines.
Within the diversified industrial tier, Texas Instruments and Honeywell International occupy positions spanning automotive and industrial automation sensor sockets. Omron Corporation and Rockwell Automation exemplify factory automation specialists with entrenched distribution across Japanese and North American accounts respectively. Bosch Sensortec represents the vertically integrated archetype with captive MEMS fabrication securing automotive inertial unit supply. STMicroelectronics anchors European-Asia R&D bridges through Singapore packaging operations. These five entities illustrate how geographic origin and structural configuration determine competitive positioning across divergent certification corridors.
| Leading Market Players |
|---|
| Texas Instruments |
| Omron Corporation |
| Rockwell Automation |
| Bosch Sensortec |
| Keyence Corporation |
| Honeywell International |
| STMicroelectronics |
| SICK AG |
| Siemens |
| Others |
Pricing and Supply Chain Analysis
Multi-year pressure sensor offtake agreements between BYD, NIO, and Shanghai-based suppliers lock in wafer allocation visibility while capping annual price escalation corridors. These contract structures concentrate procurement power among automotive OEMs and compress spot-market participation for mid-tier MEMS vendors.
Pricing Analysis
Price spreads between Japanese JIS-certified optical sensors and Chinese GB-standard variants sustain 25-40% premiums in Kansai manufacturing belts. Three-tier pricing structure across automotive-grade, industrial-grade, and consumer-grade certification levels differentiates margin capture. Cost compression in consumer proximity sensors intensifies as Foxconn and Luxshare Precision migrate module assembly to Bac Ninh Province. Automotive OEMs exhibit lowest price sensitivity due to multi-year qualification timelines, while consumer electronics brands drive aggressive annual cost-down targets.
Supply Chain Analysis
Taiwan and South Korea anchor MEMS wafer fabrication, while China dominates sensor module assembly and domestic EV procurement clusters. Polysilicon spot markets and 200mm SOI substrate availability feed into foundry cost structures. Single-source vulnerability concentrates around TSMC and UMC control of advanced MEMS logic-layer capacity. Distribution runs through direct OEM commodity management teams for 60% of automotive sensor spend, bypassing traditional Arrow and Avnet channels in Shenzhen's EV supply chain.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific sensors market sits at a regulatory-technology inflection where China's SAMR cybersecurity mandates and solid-state LiDAR MEMS convergence are rewriting qualification pathways and procurement hierarchies.
For Market Incumbents: Consolidate captive fab control or secure long-term foundry capacity reservations as Taiwan's National Tsing Hua University MEMS engineering pipeline fails to match demand. Accelerate simultaneous GB, JIS, and BIS certification to compress pan-regional launch timelines against fabless competitors exposed to qualification delays. Defensive positioning hinges on backward integration into wafer supply and JIS B 9960 compliance pre-certification for Kansai manufacturing belt access. For New Entrants and Emerging Players: Aftermarket sensor replacement services for installed industrial automation bases represent under-served white space where incumbent OEMs cede socket access to module integrators. Target Vietnamese contract manufacturing expansion in Bac Ninh Province for 15-20% labor cost arbitrage on proximity sensor module assembly. Solid-state LiDAR MEMS-SPADC array integration for automotive ADAS qualification offers the most penetrable technology gap against mechanical scanning incumbents. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated specialists with captive fabrication and multi-certification portfolios. Acquisition targets should display Singapore or Malaysia packaging hub presence bridging European-Asia R&D corridors and pre-qualified SAMR firmware signing capabilities. Monitor KAIST and National Tsing Hua University MEMS engineering graduation rates as supply-side constraint inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Certification Acceleration | Simultaneous GB, JIS, and BIS testing compresses pan-regional launch timelines by 8-14 months. |
| Captive Fab Network Expansion | Bosch Sensortec's in-house MEMS production secures automotive inertial unit supply against Taiwan foundry concentration. |
| Vietnamese Module Assembly Migration | Foxconn and Luxshare Precision operations in Bac Ninh Province exploit labor cost arbitrage versus Dongguan. |
| Solid-State LiDAR MEMS Integration | Beam steering MEMS with SPAD arrays opens automotive ADAS qualification pathways previously locked to mechanical units. |
| Cybersecurity Firmware Signing | SAMR labeling mandates encrypted telemetry transmission for Jiangsu and Guangdong smart manufacturing zone access. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of MIIT procurement mandates, METI JIS standard filings, and BIS compulsory registration databases. Primary interviews spanned MEMS process engineers at Taiwan foundries, automotive Tier 1 procurement managers in Shanghai and Shenzhen, and industrial automation channel heads in Osaka and Nagoya. Secondary validation drew from semiconductor trade customs data, EV OEM supplier disclosure filings, and ASEAN electronics manufacturing migration reports. Bottom-up sensor shipment modeling triangulates against top-down regional electronics production value estimates.
Segmentation dimensions modeled include product physics (pressure, proximity, temperature, light), technology tier (MEMS volume, optical precision, capacitive, magnetic), application vertical (automotive ADAS, healthcare imaging, industrial automation, consumer electronics), and end-user procurement archetype (OEM direct, distributor-mediated, service provider aftermarket). CAGRs derive from regression against EV production forecasts, factory automation capital expenditure cycles, and PLI scheme incentive uptake trajectories. Forecast inputs incorporate polysilicon spot price volatility corridors and KAIST MEMS engineering graduation trendlines.
Underlying assumptions cover continued MIIT localization mandates, JIS B 9960 enforcement stability, and BIS registration scheme expansion, with deviation risk concentrated in Taiwan semiconductor fabrication talent pipeline constraints and SAMR cybersecurity labeling timeline acceleration. Recalibration cycles align with material shifts in dual carbon goal enforcement intensity and EV OEM procurement cluster geographic migration patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Off-Highway Machine Position and Angle Sensor Components Market
Sensors and Controls
Global Temperature Sensors Market
Sensors and Controls
3D Profile Sensors Market
Sensors and Controls
Microsensor Market
Sensors and Controls
Semiconductor Pyrometers Market
Sensors and Controls
Steam Flow Meter Market
Sensors and Controls
Piezoelectric MEMS Resonators Market
Sensors and Controls
Asia-Pacific Digital Thermometer Market
Sensors and Controls
Condition Monitoring Sensors Market
Sensors and Controls
Surface Vision and Inspection Market
Sensors and Controls
Capacitive Proximity Sensor Market
Sensors and Controls
China PV Monitoring Systems Market
Sensors and Controls
Wired Occupancy Sensors Market
Sensors and Controls
Latin America Wearable Sensors Market
Sensors and Controls
North America Occupancy Sensors Market
Sensors and Controls
Global Smart Biosensors Market