
 Condition Monitoring Sensors Market | 2026-2036
Condition Monitoring Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Condition Monitoring Sensors Market Outlook
Wind energy is consolidating its position as the fastest-rising end-use vertical for condition monitoring sensors, displacing traditional fossil-fuel maintenance budgets. SKF Group leverages its bearing expertise to anchor predictive maintenance solutions across European turbine fleets. Emerson Electric Co. competes through wireless vibration platforms that extend into offshore installations.
Condition monitoring sensors are electromechanical or solid-state devices that measure physical parameters including vibration amplitude, temperature fluctuations, and pressure differentials to detect equipment degradation before functional failure. These sensors typically operate across frequency ranges from 0.1 Hz to 20 kHz and communicate via 4-20 mA analog loops or digital IoT protocols to centralized diagnostic systems. Vibration sensors dominate installed base volumes due to their maturity in rotating machinery applications, while IoT-enabled wireless units represent the fastest-expanding technology segment as edge computing architectures reduce latency in fault detection. Temperature sensors occupy stable margin pools in thermal process industries where drift tolerance requirements sustain premium pricing.
The EU Machinery Directive and OSHA machine guarding standards shape product certification requirements and installation protocols across industrial facilities. ISO 17359 condition monitoring guidelines and IEC 61508 functional safety standards further define sensor performance benchmarks and SIL ratings for critical infrastructure applications. Stakeholders must weigh wireless infrastructure investments against wired system reliability when deploying sensors in hazardous environments with explosive atmosphere classifications.
Market Dynamics
The transition from scheduled maintenance to predictive maintenance workflows is compressing replacement cycles and expanding sensor deployment density across industrial asset bases. This operational pivot demands continuous data streams from electromechanical and solid-state sensing elements.
Growth Catalysts
- EU Machinery Directive compliance mandates:Equipment safety certification requirements under the 2006/42/EC directive are forcing industrial operators to install continuous monitoring systems on critical rotating machinery.
- Wind energy capacity expansion:Offshore and onshore turbine installations require vibration and temperature sensors to manage gearbox and generator reliability across remote locations.
- Edge computing architectures:Distributed processing capabilities are reducing latency thresholds for fault detection, enabling real-time decision-making without cloud dependency.
Market Restraints
- MEMS fabrication concentration:Advanced accelerometer and gyroscope production clusters in East Asian foundries create supply vulnerability for Western sensor integrators.
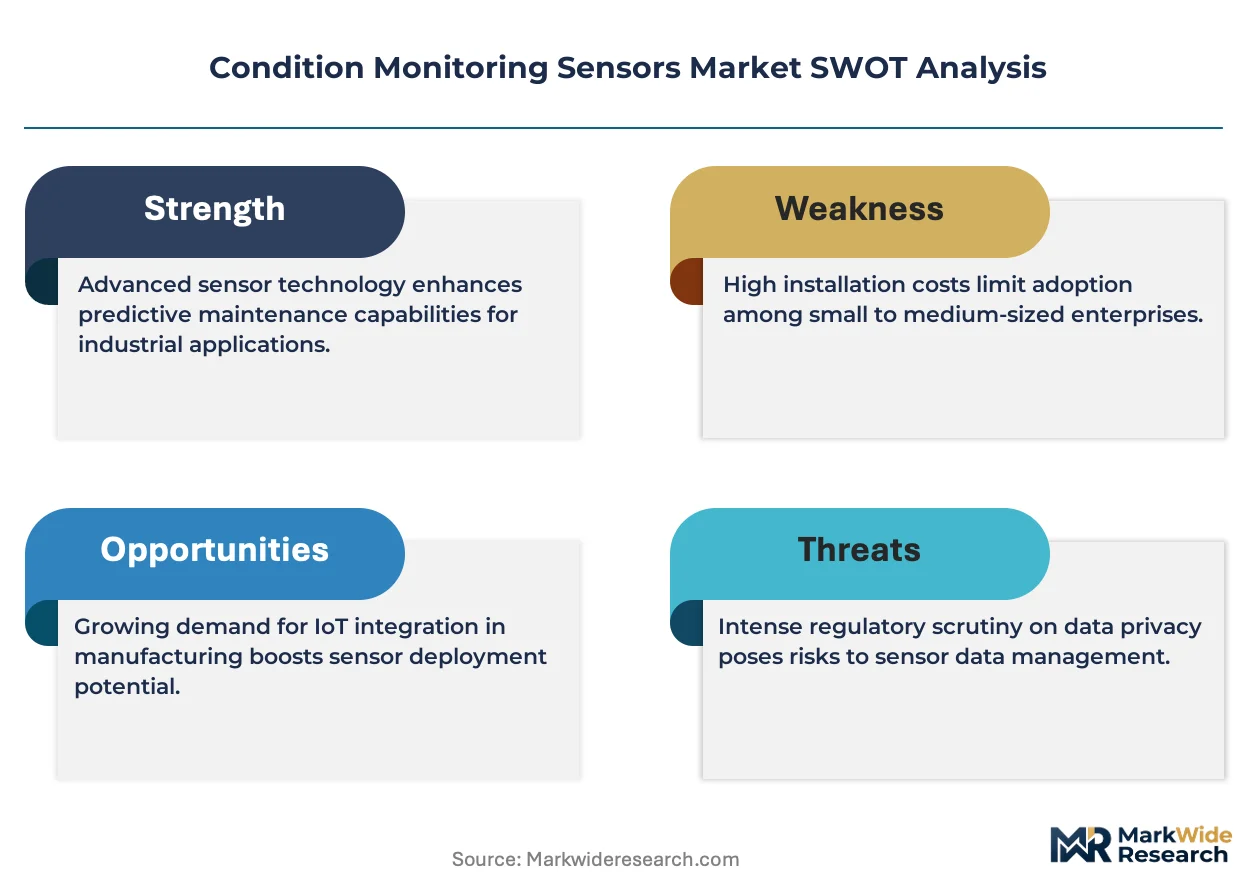
- Explosive atmosphere certification costs:ATEX and IECEx compliance for hazardous environment deployments adds 15-25% to unit economics, constraining adoption in oil and gas processing.
- Wired infrastructure lock-in:Legacy 4-20 mA analog loop investments in process industries slow wireless retrofit cycles despite IoT protocol advantages.
Strategic Opportunities
- India manufacturing automation:Production-linked incentive schemes and industrial corridor development are creating first-mover advantages for predictive maintenance solution providers.
- Battery energy storage systems:Thermal runaway prevention requirements in lithium-ion installations are opening dedicated sensor categories for temperature and gas detection.
- Digital twin convergence:Physics-based modeling integrated with live sensor feeds is enabling simulation-driven maintenance scheduling for complex assets.
Industry Challenges
- Vibration analyst certification scarcity:ISO 18436-2 qualified personnel shortages in maintenance departments limit interpretation capabilities for spectral analysis data.
- Interoperability protocol fragmentation:Competing IoT standards across OPC UA, MQTT, and proprietary platforms complicate multi-vendor system integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Condition Monitoring Sensors Market |
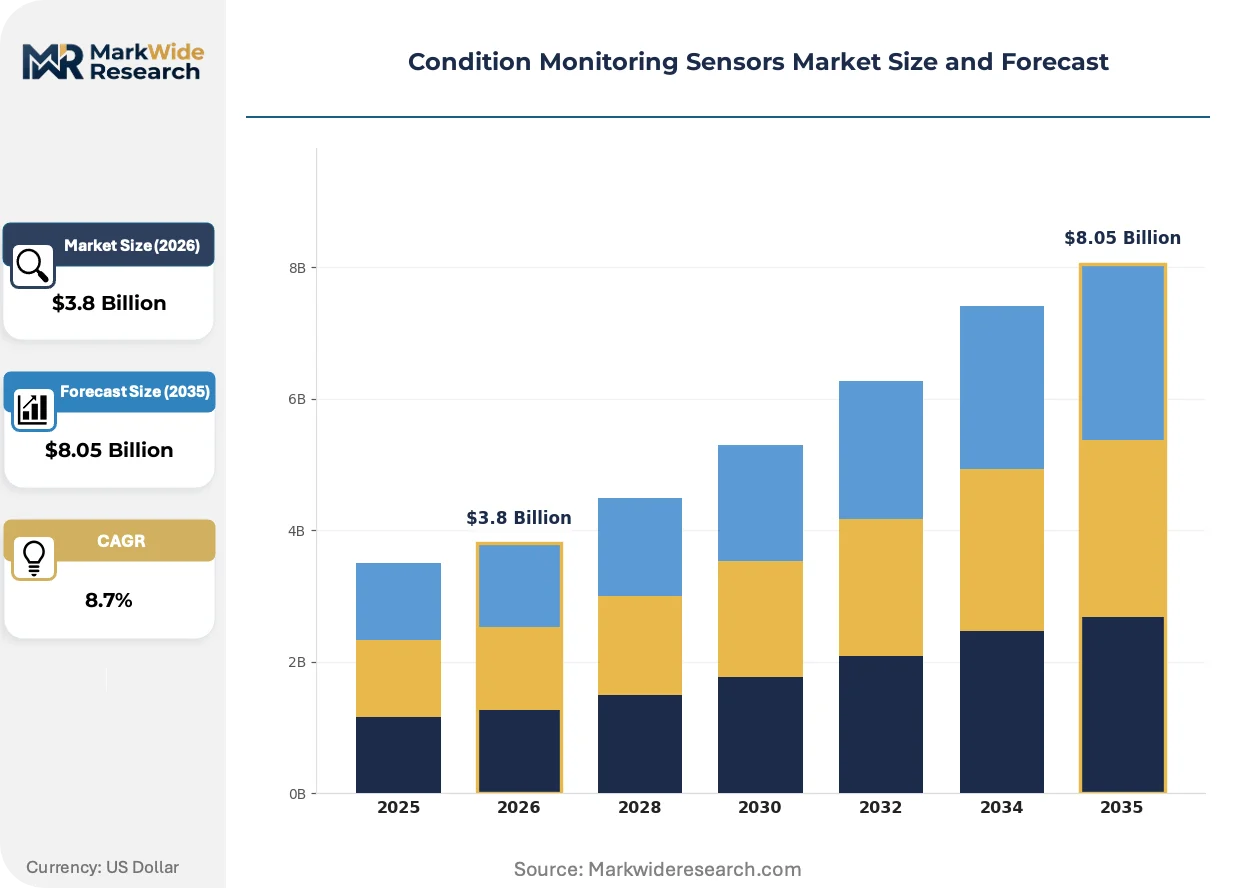
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vibration Sensors, Temperature Sensors, Pressure Sensors, Ultrasonic Sensors Technology: Wireless, Wired, IoT-Enabled, Analog End User: Manufacturing, Oil & Gas, Aerospace, Automotive Application: Predictive Maintenance, Asset Management, Quality Control, Process Optimization |
| Companies Covered | Emerson Electric Co., SKF Group, Honeywell International Inc., General Electric, ABB Ltd., Siemens AG, Rockwell Automation Inc., Schaeffler Group, Fluke Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Condition Monitoring Sensors Market Strategic Shifts
Wireless vibration sensing is compressing installation costs and expanding monitoring coverage to previously uneconomical asset classes. Three converging developments are accelerating this transformation.
Energy harvesting from machine vibration is electrifying power-autonomous sensor designs, eliminating battery replacement logistics. Food and beverage processors with washdown requirements are adopting these self-powered units at accelerated pace. This technology is electrifying deployment economics in environments where sealed enclosures and cable routing previously prohibited monitoring.
OSHA machine guarding enforcement actions are tightening documentation requirements for equipment safety systems. Industrial facilities face elevated liability exposure for unmonitored mechanical hazards. Metalworking and stamping operations in the United States are responding with integrated safety-rated sensor networks that combine condition data with interlock functionality.
Asset-as-a-service contracting is altering capital equipment procurement patterns. Original equipment manufacturers retain ownership while charging for uptime guarantees, embedding sensor infrastructure as a bundled cost. Heavy machinery and compressed air system vendors in Germany are pioneering this model, shifting buyer relationships from transactional to performance-based.
Condition Monitoring Sensors Market Segmentation
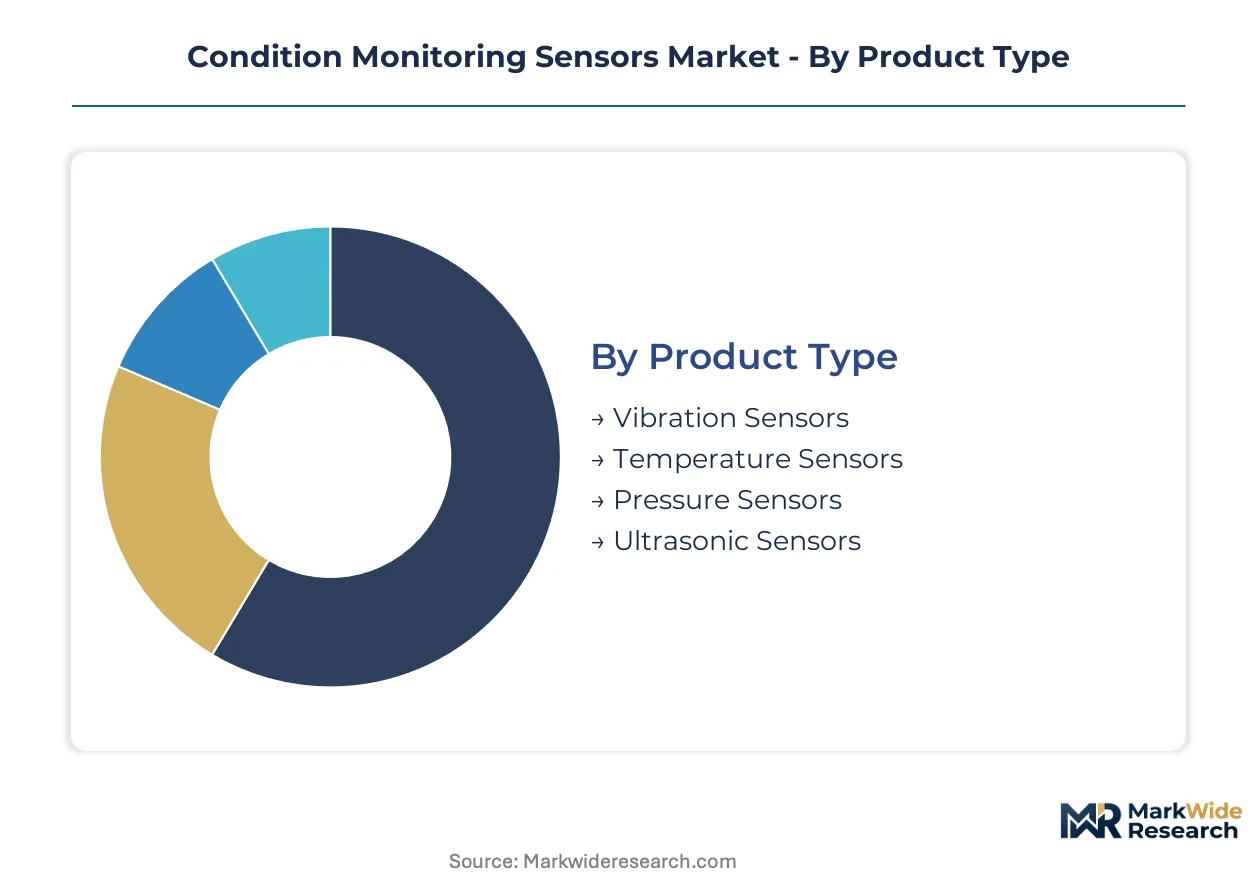
Condition monitoring sensors serve heterogeneous industrial environments where sensor selection hinges on signal fidelity requirements, infrastructure maturity, and hazardous area classifications. Segmentation reveals how technology choices bifurcate between legacy analog installations and wireless IoT architectures.
Product Type:
Supply concentration for MEMS accelerometer dies in East Asian foundries shapes tiered availability across sensor categories.
- Vibration Sensors:Piezoelectric and MEMS accelerometers measure mechanical oscillation across 0.1 Hz to 20 kHz frequency bands. Manufacturing facilities in Germany and the United States deploy these most densely for rotating machinery protection. Demand concentrates where ISO 17359 compliance mandates continuous bearing monitoring.
- Temperature Sensors:Thermocouples and RTDs track thermal drift in process equipment with ±0.1°C precision in premium configurations. Thermal process industries sustain premium pricing tiers due to drift tolerance specifications.
- Pressure Sensors:Piezoresistive and capacitive transducers detect differential pressure across hydraulic and pneumatic systems.
- Ultrasonic Sensors:High-frequency acoustic emission detectors identify crack propagation and lubrication failures in gearbox applications.
Vibration sensors absorb the bulk of installed capacity; IoT-enabled wireless units are expanding most quickly.
Technology:
Cost tier differentiation separates capital-intensive wired retrofits from greenfield wireless deployments.
- Wireless:Battery-powered and energy-harvesting units transmit via IEEE 802.15.4 or proprietary protocols to edge gateways. Wind energy operators favor these for offshore turbine monitoring where cable routing proves uneconomical.
- IoT-Enabled:Cloud-integrated sensors with onboard processing execute local analytics before data transmission. Edge computing architectures reduce latency thresholds for fault detection in critical infrastructure.
- Wired:4-20 mA analog loops and fieldbus networks dominate process industry installations with established instrument infrastructure.
- Analog:Legacy voltage and current output sensors persist in facilities with slow modernization cycles.
Wired infrastructure retains the majority of legacy installations; IoT-enabled architectures are climbing the fastest.
End User:
Application maturity varies sharply across verticals with divergent safety certification burdens.
- Manufacturing:Metalworking, automotive assembly, and food processing plants deploy vibration and temperature sensors for predictive maintenance workflows. OSHA machine guarding enforcement drives integrated safety-rated sensor networks in United States facilities.
- Oil & Gas:Refineries and upstream installations require ATEX and IECEx certified sensors for explosive atmosphere zones. Certification costs add 15-25% to unit economics, constraining deployment density.
- Aerospace:Engine health monitoring and airframe structural sensing demand MIL-STD qualified components with traceable calibration chains.
- Automotive:EV battery thermal runaway prevention and powertrain quality testing create specialized sensor requirements.
Manufacturing absorbs the bulk of installed capacity; battery energy storage applications are gaining share fastest.
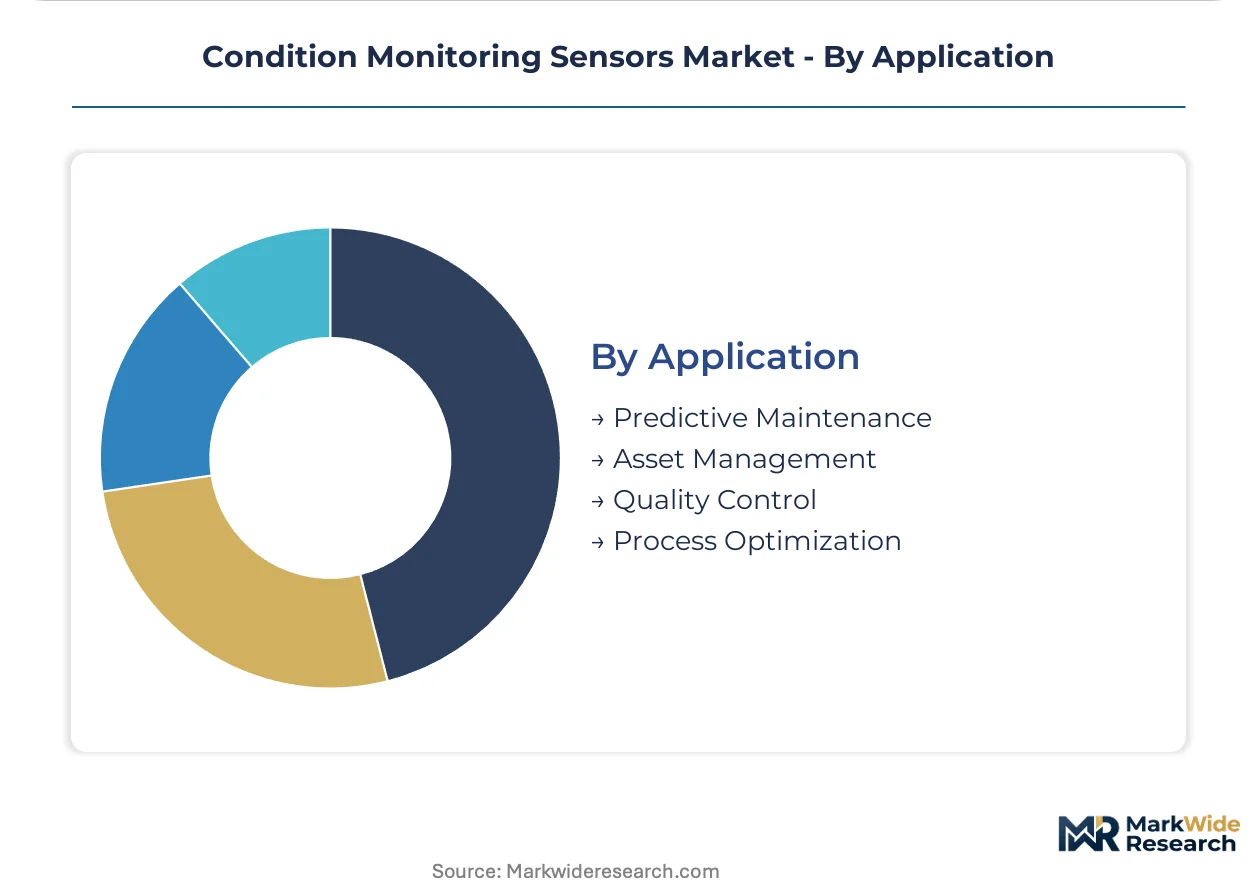
Application:
Customer procurement patterns separate capital equipment buyers from performance-contracting service models.
- Predictive Maintenance:Continuous monitoring replaces time-based inspection schedules, compressing sensor replacement cycles. Asset-as-a-service contracting embeds sensor infrastructure as bundled uptime guarantees.
- Asset Management:Digital twin integration with live sensor feeds enables simulation-driven maintenance scheduling for complex rotating equipment.
- Quality Control:In-process vibration monitoring detects tool wear and dimensional drift in precision machining operations.
- Process Optimization:Real-time thermal and pressure data feeds advanced process control loops in chemical and pharmaceutical manufacturing.
Predictive maintenance absorbs the bulk of sensor deployment; digital twin convergence applications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Dongguan concentrate MEMS foundry capacity for sensor component supply. Industrial automation corridors in Germany's Ruhr region and the US Midwest drive dense deployment of predictive maintenance infrastructure. Regulatory tightening across multiple jurisdictions accelerates certification requirements for continuous monitoring systems.
United States
OSHA machine guarding enforcement actions elevate liability exposure for unmonitored mechanical hazards in metalworking operations. The Department of Labor's National Emphasis Program on amputations mandates documentation for safety-rated sensor networks. Detroit-area automotive stamping plants and Houston petrochemical complexes represent dense installation clusters for vibration and temperature monitoring systems.
Germany
The EU Machinery Directive 2006/42/EC forces continuous monitoring system installation on critical rotating machinery across industrial facilities. The country's Federal Ministry for Economic Affairs backs Industrie 4.0 adoption through standardized interface protocols for sensor integration. Bavarian precision engineering clusters and North Rhine-Westphalian steel operations anchor predictive maintenance deployment density.
China
MIIT smart manufacturing initiatives accelerate sensor deployment across provincial industrial transformation programs. GB standards for machinery safety tighten certification requirements for condition monitoring equipment in hazardous environments. Yangtze River Delta electronics manufacturing and Pearl River Delta automotive assembly drive volume demand for IoT-enabled wireless units.
India
Production-linked incentive schemes for manufacturing automation create first-mover advantages for predictive maintenance solution providers. The Central Electricity Authority mandates continuous monitoring for grid-connected renewable assets above specified capacity thresholds. Gujarat's industrial corridors and Tamil Nadu's automotive clusters represent emerging demand concentration for vibration sensing infrastructure.
Japan
METI's Society 5.0 roadmap embeds predictive maintenance within smart factory transformation programs. JIS standards for rotating machinery protection establish performance benchmarks for sensor certification. Chubu region's precision tool manufacturing and Kansai's steel processing operations sustain premium-tier demand for high-fidelity monitoring systems.
Condition Monitoring Sensors Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated industrial conglomerates commanding premium positions in process industries while component specialists capture volume in discrete manufacturing. The vendor base organizes around three strategic archetypes: bearing-centric maintenance solution providers, diversified automation platforms with sensor divisions, and pure-play instrumentation specialists. Consolidation activity concentrates among automation platforms seeking predictive maintenance capabilities, while technology licensing agreements proliferate between MEMS foundries and Western sensor integrators.
Among diversified industrial technology groups, Emerson Electric Co., SKF Group, and Honeywell International Inc. exemplify contrasting strategic positions. Emerson Electric Co. represents the automation-platform archetype with wireless vibration capabilities extending into offshore energy applications. SKF Group anchors the bearing-centric maintenance solution model across European wind turbine fleets. Honeywell International Inc. occupies a position bridging process industry instrumentation with aerospace-qualified sensing technologies.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| SKF Group |
| Honeywell International Inc. |
| General Electric |
| ABB Ltd. |
| Siemens AG |
| Rockwell Automation Inc. |
| Schaeffler Group |
| Fluke Corporation |
| Others |
Value Chain & Pricing Dynamics
EU Machinery Directive compliance mandates gate both qualified supply and premium-tier pricing access for condition monitoring sensor vendors, forcing industrial operators toward certified suppliers while compressing margins for non-compliant tier-two manufacturers. ATEX and IECEx certification requirements add structural cost layers that stratify the vendor base between safety-rated premium providers and uncertified economy alternatives.
Pricing Analysis
Lead-time-driven pricing creates sharp differentiation between spot inventory discounts and premium surcharges for expedited delivery of certified sensors. Three-tier pricing structure across premium, standard, and economy levels separates ATEX-certified units from general industrial-grade and uncertified alternatives, with price differentiation hinging on certification grade and volume scale. Cost compression in economy tiers is intensifying because MEMS foundry overcapacity in East Asia feeds commoditized accelerometer supply. Small and mid-sized metalworking facilities in the United States exhibit highest price sensitivity, while offshore wind operators in the North Sea absorb premium pricing for hazardous-area-rated wireless units.
Supply Chain Analysis
MEMS accelerometer die supply rests on Taiwanese and South Korean foundry capacity, with piezoelectric crystal sourcing concentrated in Japanese and German specialty material producers. Silicon wafer substrates, rare-earth magnetic materials for energy-harvesting designs, and ceramic packaging substrates constitute critical input dependencies. Single-source vulnerability in advanced MEMS fabrication creates exposure to geopolitical disruption or export control tightening. Distribution runs through industrial automation distributors, OEM captive service networks, and direct enterprise sales to large turbine manufacturers and process plant operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Machinery Directive 2006/42/EC erects a cost-of-compliance barrier that advantages incumbent vendors with established certification infrastructure while filtering out undercapitalized entrants unable to sustain ATEX and IECEx qualification investments.
For Market Incumbents: Lock in certification moats by accelerating IEC 61508 SIL-rated product line expansion before regulatory tightening spreads to Asian markets. Vertical integration into MEMS packaging capabilities in Germany or the United States reduces foundry concentration risk. Capacity addition in India's industrial corridors captures production-linked incentive demand before local competitors achieve scale. Channel control through asset-as-a-service contracting models shifts buyer relationships toward sticky performance-based arrangements that resist price erosion. For New Entrants and Emerging Players: Battery energy storage system operators represent an underserved buyer archetype with thermal runaway prevention requirements outpacing established vendor specialization. Food and beverage processors with washdown sanitation needs create white-space for energy-harvesting sensor designs that eliminate battery maintenance logistics. India's manufacturing automation corridors offer the most penetrable geography given first-mover timing and limited local competition. A go-to-market angle anchored to digital twin integration partnerships with industrial software platforms bypasses direct confrontation with bearing-centric maintenance incumbents. For Investors and Strategic Acquirers: Emerson Electric's wireless vibration platform expansion into offshore wind is the leading indicator that energy-harvesting architectures are crossing from niche to mainstream adoption. Long-term viability in this market hinges on sensor-to-software integration depth rather than component manufacturing scale alone. Acquisition targets should emphasize vendors with edge computing firmware stacks and established API ecosystems for digital twin platforms. A small set of named triggers warrants ongoing watch: IEC 61508 SIL-3 certification attainment rates, energy-harvesting sensor shipment volumes from food and beverage verticals, and Indian PLI scheme beneficiary lists for predictive maintenance equipment.| Strategic Initiative | Industry Significance |
|---|---|
| Energy-Harvesting Sensor Platform Launch | Eliminates battery logistics for food processors and offshore wind operators demanding sealed, cable-free installations. |
| Digital Twin Software Integration | Physics-based modeling partnerships with Siemens or ABB platforms embed sensors within simulation-driven maintenance workflows. |
| ATEX Certification Acceleration | IECEx qualification for Zone 0/1 deployments captures oil and gas budgets constrained by 15-25% certification cost premiums. |
| India Manufacturing Footprint Expansion | PLI scheme alignment positions vendors for automotive and renewable asset monitoring demand in Gujarat and Tamil Nadu corridors. |
| Asset-as-a-Service Contracting Model | Uptime guarantee structures shift German heavy machinery procurement from transactional to recurring revenue relationships. |
Study Parameters
SEC 10-K filings, EU Machinery Directive implementation reports, and IEA wind energy deployment databases formed the secondary backbone for market sizing and competitive positioning analysis. Primary interviews with maintenance directors at German automotive stamping plants, vibration analysts certified to ISO 18436-2, and procurement leads at North Sea offshore wind operators validated demand assumptions and pricing dynamics. Bottom-up unit economics modeling triangulated against top-down industrial automation spending forecasts produced convergent market estimates.
Historical trendline analysis across sensor shipment volumes, certification registration databases, and wireless protocol adoption curves established baseline growth trajectories. Segmentation modeling incorporated product type, technology architecture, end-user vertical, and application mode dimensions alongside geographic regulatory cluster differentiation. CAGRs derived from fitted growth curves adjusted for MEMS supply constraints and industrial capital expenditure cyclicality. Forecast inputs included edge computing infrastructure deployment rates, wind turbine installation pipelines, and battery energy storage system capacity additions.
Revisions become necessary when ATEX certification backlogs extend beyond equipment procurement cycles, when MEMS foundry utilization shifts trigger supply rationing, or when Indian PLI scheme disbursement delays alter manufacturing automation investment timing. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Wearable Thermometers Market
Sensors and Controls
Europe Wearable Sensors Market
Sensors and Controls
Blue-Green Algae Sensors Market
Sensors and Controls
Home Automation Sensors Market
Sensors and Controls
Occupancy Sensor Market
Sensors and Controls
Latin America Wireless Sensors Market
Sensors and Controls
Gimbal Market
Sensors and Controls
Thermal Flow Meter Market
Sensors and Controls
Environmental Noise Cancellation Microphones Market
Sensors and Controls
Global Linear Encoder Market
Sensors and Controls
Acoustic Sensors Market
Sensors and Controls
Digital Humidity Sensor Market
Sensors and Controls
Global Hazardous Location Thermostats Market
Sensors and Controls
Europe Temperature Sensors Market
Sensors and Controls
United States Scintillator Market
Sensors and Controls
Magnetic Absorption Data Line Market