
 Microsensor Market | 2026-2036
Microsensor Market Size, Share, and Industry Trends Forecast 2026-2036
Microsensor Market Foresight
Asian MEMS foundry expansion is realigning supply availability for automotive and industrial buyers. Bosch Sensortec leverages in-house wafer fabrication to sustain cost leadership in consumer-grade motion sensing. STMicroelectronics anchors European supply through its integrated MEMS production in Italy and France. Texas Instruments competes by extending analog front-end integration into silicon-based pressure sensor modules.
A microsensor converts physical, chemical, or biological stimuli into measurable electrical signals using structures typically below one millimeter in scale, with MEMS devices fabricated through photolithography, thin-film deposition, and deep reactive ion etching on silicon wafers. These components enable closed-loop control, safety interlocks, and real-time diagnostics across automotive, medical, and industrial systems. Pressure sensors occupy the largest product category due to pervasive deployment in engine management and HVAC systems, while gas sensors represent the fastest-expanding segment as industrial safety mandates tighten and smart agriculture adoption broadens. MEMS technology leads by volume because semiconductor-compatible batch processing drives unit economics, though optical sensing captures premium positioning in healthcare applications where drift tolerance and selectivity matter most.
EPA emissions rules and NHTSA safety standards in the United States compel automotive suppliers to certify microsensor accuracy under thermal cycling and vibration stress, while REACH and RoHS frameworks in Europe restrict hazardous substances in sensor packaging and bonding materials. China's GB standards and MIIT directives set domestic performance benchmarks that foreign vendors must meet for market access. Stakeholders should monitor how converging automotive electrification and medical device digitization reshape certification requirements and sourcing geography.
Market Dynamics
Automotive electrification is compressing development cycles for powertrain-grade pressure and temperature sensors, forcing suppliers to recalibrate wafer fab capacity toward automotive-qualified MEMS processes.
Growth Catalysts
- EPA emissions mandates:US automotive OEMs must deploy real-time exhaust gas monitoring, expanding demand for NOx and particulate matter sensors in diesel and hybrid powertrains.
- Silicon photonics integration:Biomedical device manufacturers are embedding optical microsensors into continuous glucose monitors, replacing electrochemical methods with drift-resistant interferometric detection.
- China's domestic MEMS foundry buildout:Pressure sensor module output from Jiangsu and Zhejiang provinces is reducing lead times for industrial automation buyers.
Market Restraints
- Specialized wafer supply concentration:SOI (silicon-on-insulator) substrate production concentrates among three Japanese and German suppliers, exposing automotive sensor fabs to allocation risk.
- Platinum group metal cost volatility:Automotive exhaust gas sensors require palladium and rhodium catalyst layers, with price swings directly compressing gross margins on high-temperature sensing elements.
- Technical ceiling in selectivity:Metal-oxide gas sensors face inherent cross-sensitivity to humidity and VOC mixtures, limiting deployment in precision agriculture without costly signal processing augmentation.
Strategic Opportunities
- India's industrial safety mandate expansion:Factory licensing reforms under the Occupational Safety, Health and Working Conditions Code are mandating fixed gas detection networks in chemical processing zones.
- Edge AI convergence with MEMS:On-sensor inference engines are enabling predictive maintenance signatures in rotating machinery, bypassing cloud latency for vibration anomaly detection.
- EU Green Deal F-Gas Regulation:Phasedown of hydrofluorocarbon refrigerants is accelerating demand for leak detection microsensors in commercial HVAC retrofit installations.
Industry Challenges
- MEMS process engineer scarcity:Deep reactive ion etching and wafer-level packaging expertise concentrates among aging specialists in Germany and the United States, constraining foundry expansion timelines.
- Multi-domain certification complexity:Medical-grade pressure sensors for infusion pumps must satisfy FDA 510(k) pathways alongside ISO 13485 quality systems, extending product launch cycles by 14-22 months.
- Automotive PPAP timeline compression:Tier-1 suppliers face simultaneous qualification demands from Detroit, Stuttgart, and Shanghai engineering centers, straining validation lab capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microsensor Market |
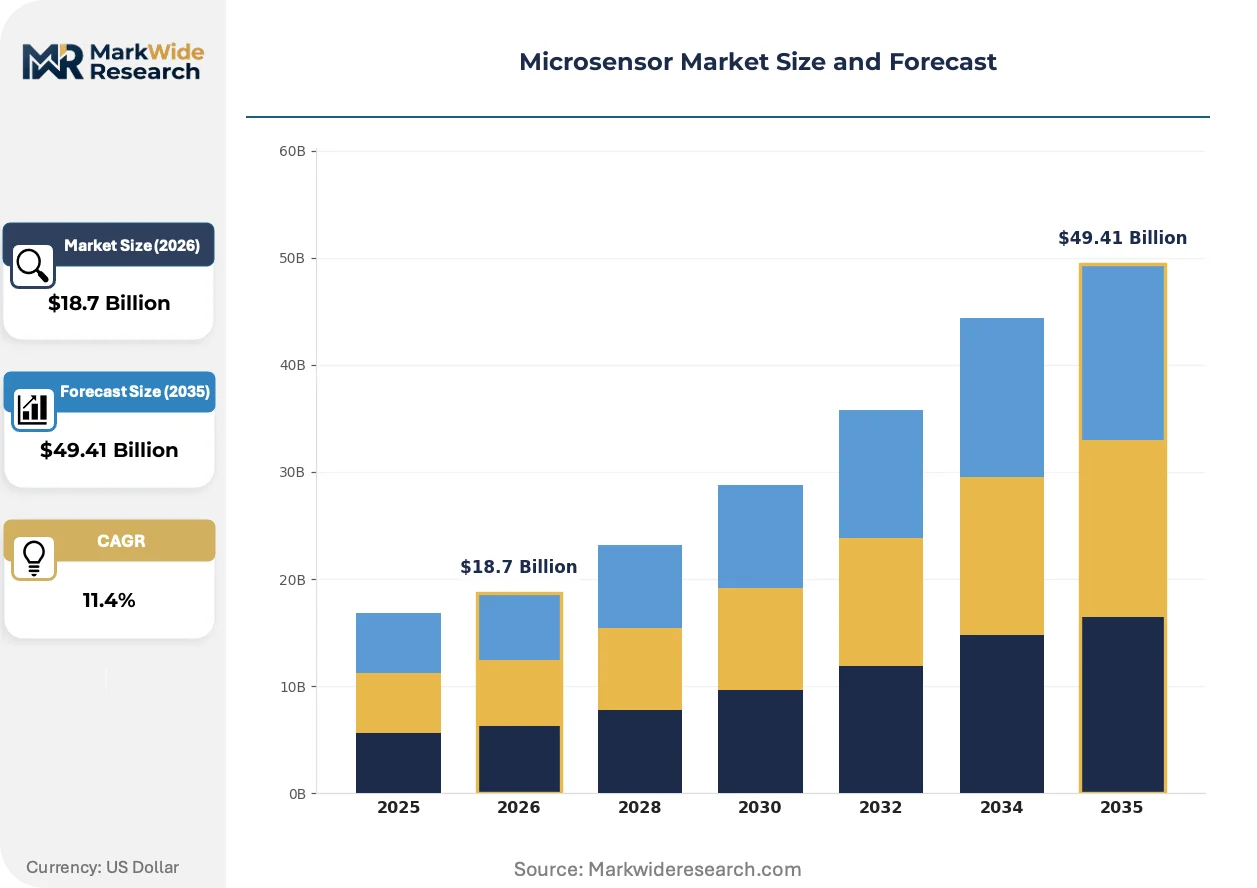
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature Sensors, Pressure Sensors, Gas Sensors, Humidity Sensors Technology: MEMS, Optical, Acoustic, Bimetallic End User: Healthcare, Automotive, Aerospace, Industrial Automation Application: Environmental Monitoring, Wearable Devices, Smart Agriculture, Home Automation |
| Companies Covered | Analog Devices, Infineon Technologies, Bosch Sensortec, Omron Corporation, TE Connectivity, STMicroelectronics, Honeywell International, Sensirion AG, Texas Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microsensor Market Shifts & Advancements
Sensor fusion architectures are collapsing discrete component counts, with multi-physics microsensors replacing separate pressure, temperature, and humidity modules in compact IoT endpoints.
Photonic crystal fiber microsensors are electrifying structural health monitoring in civil infrastructure. German bridge operators are embedding fiber Bragg grating arrays into concrete rehabilitation projects, replacing strain gauge networks with electromagnetic-interference-immune optical interrogation. This displacement is compressing maintenance inspection intervals from annual manual surveys to continuous remote telemetry.
REACH substance restriction amendments are forcing material substitutions in sensor bonding and encapsulation. European medical device manufacturers must eliminate bisphenol-A and certain phthalates from disposable blood pressure transducers, triggering reformulation of biocompatible epoxies and silicone gels. The diagnostic catheter segment is responding fastest, with Swiss and Irish contract manufacturers qualifying alternative polymer systems ahead of 2026 sunset dates.
Direct procurement from foundries is displacing traditional component distribution for high-volume automotive programs. Tier-1 sensor module suppliers in Michigan and Bavaria are establishing annual volume agreements with TSMC and GlobalFoundries MEMS lines, bypassing broadline electronics distributors. This channel compression is most visible in tire pressure monitoring systems, where single-source silicon contracts now cover 40-60% of North American and German OEM demand.
Microsensor Market Segmentation
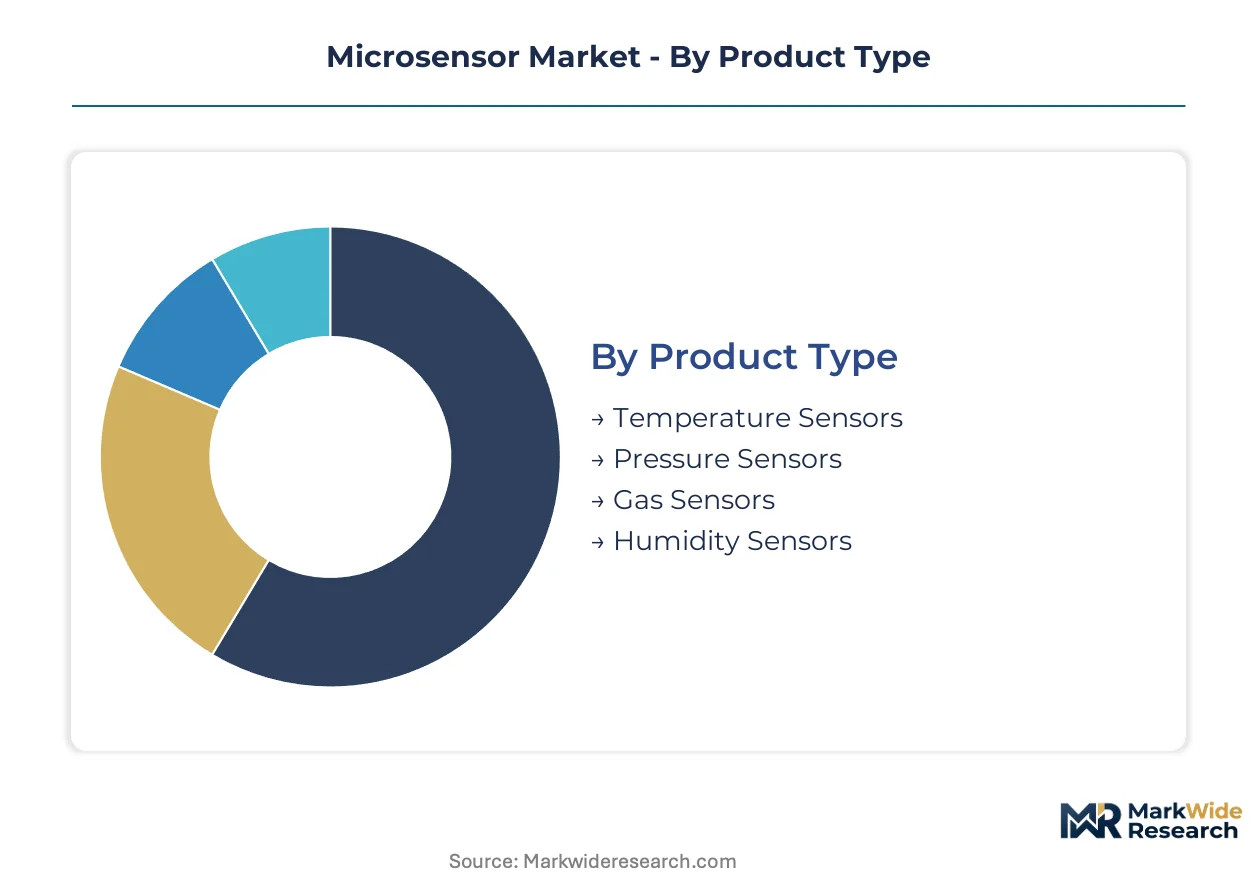
Microsensor procurement decisions hinge on specification trade-offs between precision, environmental tolerance, and integration complexity. Understanding how demand fragments across product architectures, fabrication methods, and use cases clarifies where suppliers must concentrate R&D and capacity investments.
Product Type:
Specification requirements vary sharply by measurand, with thermal stability and pressure range defining automotive qualification thresholds while selectivity dominates gas detection procurement.
- Pressure Sensors:Piezoresistive MEMS diaphragms bonded to glass or silicon substrates deliver millibar-level resolution for manifold absolute pressure measurement. Demand concentrates in Stuttgart and Detroit powertrain programs where EPA emissions mandates require real-time intake and exhaust monitoring.
- Gas Sensors:Metal-oxide semiconductors and electrochemical cells detect CO, NOx, and VOC concentrations with ppm sensitivity. Deployment is climbing fastest in Zhejiang province chemical parks and EU Green Deal F-Gas refrigerant leak detection retrofits.
- Temperature Sensors:Thermistors and RTDs provide thermal feedback for battery management systems.
- Humidity Sensors:Capacitive polymer films measure relative moisture in HVAC and agricultural environments.
Mature deployment sits with pressure sensors. Newer deployment is concentrated in gas sensors.
Technology:
Process economics and performance ceilings separate batch-fabricated silicon approaches from specialty methods requiring discrete assembly.
- MEMS:Photolithography and deep reactive ion etching on 200mm wafers enable sub-millimeter mechanical structures with integrated signal conditioning. Volume demand clusters in consumer motion sensing and automotive tire pressure modules where TSMC and GlobalFoundries MEMS lines anchor supply.
- Optical:Fiber Bragg gratings and interferometric architectures achieve immunity to electromagnetic interference for structural health monitoring. Swiss diagnostic catheter manufacturers and German bridge operators drive premium positioning where drift tolerance outweighs unit cost.
- Acoustic:Piezoelectric resonators and surface acoustic wave devices detect mechanical stress and fluid properties.
- Bimetallic:Differential thermal expansion strips provide passive temperature switching for thermal protection.
MEMS dominates unit economics. Optical commands premium positioning in healthcare and infrastructure.
End User:
Certification intensity and procurement scale vary dramatically across buyer categories, with automotive and medical imposing the most stringent validation protocols.
- Automotive:Powertrain, chassis, and cabin systems require AEC-Q100 qualified components with -40°C to 150°C operational range. OEMs in Bavaria and Michigan are consolidating annual volume agreements directly with foundries to secure allocation.
- Healthcare:FDA 510(k) and ISO 13485 compliance extends development cycles for infusion pump pressure transducers and continuous glucose monitor optical elements. Irish and Swiss contract manufacturers are reformulating biocompatible encapsulants ahead of REACH substance restrictions.
- Aerospace:DO-160 environmental testing governs altitude, vibration, and temperature extremes for flight-critical sensing.
- Industrial Automation:Factory licensing reforms under India's Occupational Safety Code are mandating fixed gas detection networks in chemical processing zones.
Automotive generates the highest volume demand. Healthcare imposes the steepest certification barriers.
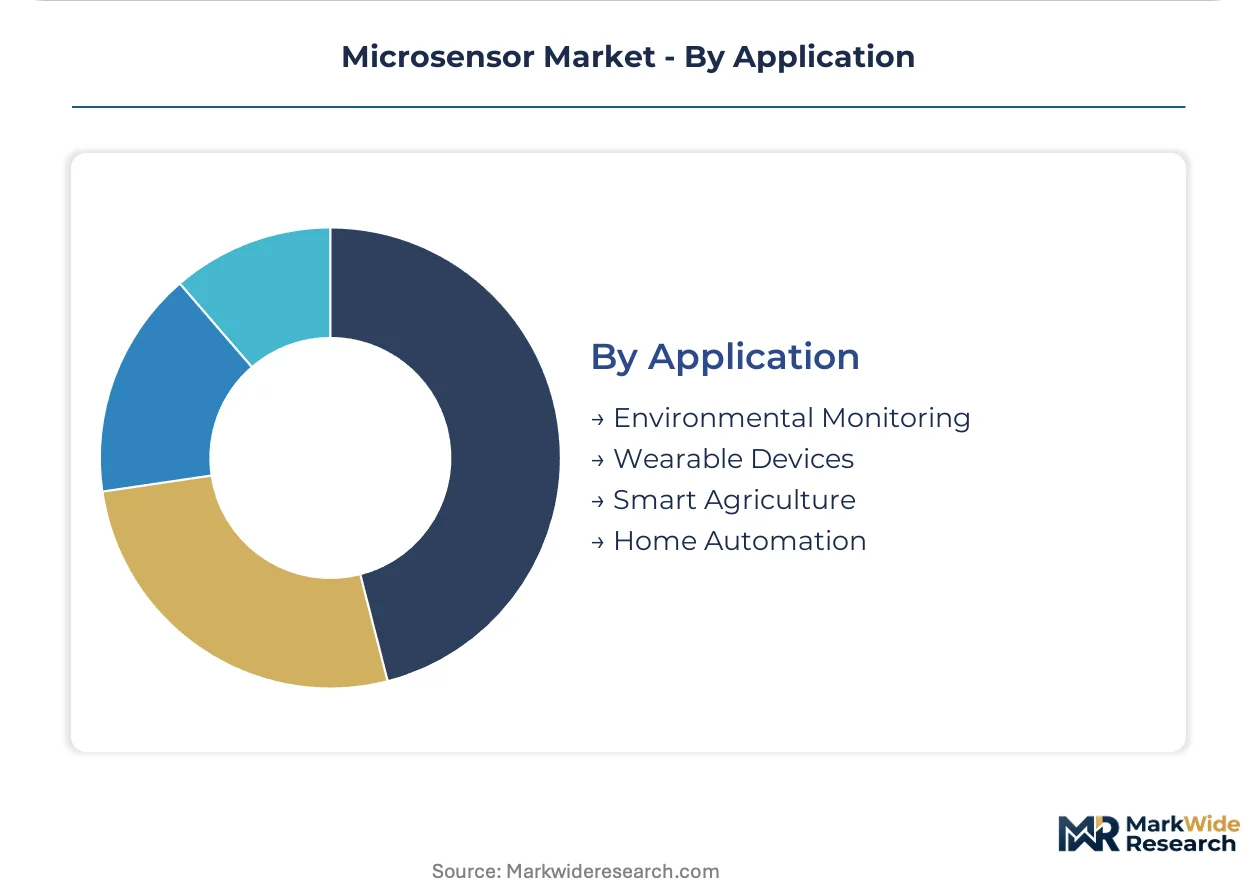
Application:
Use case fragmentation determines packaging form factors and power budgets, from battery-constrained wearables to mains-powered environmental stations.
- Environmental Monitoring:Distributed sensor networks track air quality, water chemistry, and soil conditions with low-power wireless backhaul. Chinese smart city deployments and EU urban air quality directives are expanding node density requirements.
- Wearable Devices:Miniaturized inertial and biometric sensors integrate into fitness bands and medical patches. Silicon photonics is displacing electrochemical methods in continuous glucose monitoring for drift-resistant interferometric detection.
- Smart Agriculture:Soil moisture and greenhouse gas sensors enable precision irrigation and livestock environment control.
- Home Automation:Occupancy, air quality, and climate sensors feed building management algorithms.
Environmental monitoring scales through infrastructure investment. Wearable devices are gaining share fastest through medical digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon-on-insulator wafer supply from Japan and Germany underpins microsensor fabrication capacity across automotive and industrial hubs. Regional demand patterns diverge sharply between electrification-driven automotive programs and medical device digitization clusters.
United States
EPA emissions mandates and NHTSA safety standards compel automotive OEMs in Michigan and Tennessee to certify pressure and gas sensors under thermal cycling stress. FDA 510(k) pathways govern infusion pump pressure transducers from Irish and Swiss contract manufacturers serving US healthcare markets. Detroit engineering centers anchor powertrain sensor qualification timelines.
China
MIIT directives and GB standards set domestic performance benchmarks for foreign vendor market access. Jiangsu and Zhejiang province foundries expand MEMS capacity for pressure and gas sensing modules. Shanghai and Suzhou clusters concentrate tire pressure monitoring system production for domestic EV programs.
Germany
REACH substance restrictions and RoHS frameworks restrict hazardous substances in sensor packaging and bonding materials. KBA certification requirements govern automotive sensor accuracy validation. Bavaria anchors integrated MEMS production for European supply security.
Japan
METI industrial policy supports MEMS foundry modernization for automotive and robotics applications. JIS standards govern sensor interchangeability in factory automation networks. Nagoya and Osaka prefectures concentrate piezoelectric resonator fabrication for industrial sensing.
India
Factory licensing reforms under the Occupational Safety, Health and Working Conditions Code mandate fixed gas detection networks in chemical processing zones. BIS certification requirements localize sensor performance validation. Gujarat and Maharashtra industrial corridors drive procurement for refinery and petrochemical safety systems.
Microsensor Market Competitive Landscape
Global majors compete with regional champions across fabrication scale and certification depth. Market structure tilts toward consolidated supply at the wafer level with fragmented module assembly. Three archetypes dominate: integrated semiconductor conglomerates with captive MEMS lines, specialized sensor houses with process expertise, and diversified industrials with automotive certification heritage. Competitive moves concentrate on direct foundry contracting and biocompatible material reformulation ahead of regulatory deadlines.
Among European integrated producers, STMicroelectronics and Infineon Technologies exemplify the captive-fabrication archetype, anchoring regional supply security through in-house wafer processing. Bosch Sensortec represents the specialized sensor house model with concentrated motion-sensing expertise. These three entities occupy positions spanning consumer electronics qualification through automotive-grade reliability certification.
| Leading Market Players |
|---|
| Analog Devices |
| Infineon Technologies |
| Bosch Sensortec |
| Omron Corporation |
| TE Connectivity |
| STMicroelectronics |
| Honeywell International |
| Sensirion AG |
| Texas Instruments |
| Others |
Supply & Pricing Matrix
Silicon photonics integration into biomedical sensing is simultaneously collapsing per-unit detection costs and concentrating procurement leverage among optical MEMS foundries with qualified biocompatible packaging lines. This technology transition rewards suppliers that have already amortized deep ultraviolet lithography investments, while squeezing margins for electrochemical sensor houses facing replacement.
Pricing Analysis
Warranty and calibration service bundling separates automotive-grade pressure sensor contracts from unbundled industrial spot purchases. Three-tier pricing structure across AEC-Q100 certified, industrial-grade, and consumer-level tiers reflects validation cost recovery and volume scale. Pricing pressure stems from Chinese domestic MEMS foundry expansion in Jiangsu province compressing module costs. Automotive OEMs in Stuttgart and Detroit exhibit lowest price sensitivity due to qualification lock-in, while agricultural sensor buyers face acute cost compression.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale automotive demand, bypassing broadline distributors for tire pressure monitoring and powertrain sensing programs. SOI wafer supply concentrates among Japanese and German substrate specialists, with MEMS fabrication anchored in Taiwan, China, and Italy. Palladium and rhodium catalyst layers for exhaust gas sensors draw from South African and Russian mining concentration. Single-source vulnerability in specialized wafer supply exposes automotive sensor fabs to allocation risk during capacity crunches.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SOI wafer supply concentration among three global substrate suppliers props pricing power for qualified automotive MEMS foundries, creating structural margin protection for incumbents with secured allocation agreements.
For Market Incumbents: Extend captive fabrication capacity in Italy and Bavaria to defend against Chinese foundry cost aggression. Secure long-term SOI wafer offtake agreements with Japanese substrate houses before allocation tightening. Deepen AEC-Q100 certification portfolios to lock in automotive platform engineering cycles. For New Entrants and Emerging Players: Direct-to-factory digital procurement platforms offer white-space entry for mid-volume industrial automation buyers underserved by tier-1 automotive-focused distributors. Target India's chemical processing zones under Occupational Safety Code gas detection mandates. Lead with cloud-connected sensor-as-a-service models bypassing capital-intensive foundry investment. For Investors and Strategic Acquirers: Re-rating potential sits with specialized optical MEMS houses given silicon photonics displacement of electrochemical glucose monitoring. Five-to-ten year viability favors targets with FDA 510(k) clearance pathways and REACH-compliant material libraries. Watch for inflection in bridge rehabilitation project awards signaling fiber Bragg grating demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Biocompatible Material Reformulation | Swiss and Irish contract manufacturers qualify alternative polymer systems ahead of REACH sunset dates. |
| Direct Foundry Contracting | Michigan and Bavaria tier-1 suppliers establish annual volume agreements with TSMC MEMS lines. |
| Edge AI Sensor Integration | On-sensor inference engines enable predictive maintenance signatures bypassing cloud latency. |
| Optical MEMS Capacity Expansion | German bridge operators embed fiber Bragg grating arrays replacing strain gauge networks. |
| India Gas Detection Network Buildout | Gujarat and Maharashtra industrial corridors mandate fixed detection under Occupational Safety Code reforms. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with MEMS process engineers, automotive tier-1 procurement managers, biomedical device regulatory leads, and foundry operations directors. SEC 10-K disclosures, EPA certification databases, FDA 510(k) filings, and MIIT directive publications provided demand-side validation. Bottom-up wafer capacity modeling and top-down end-use consumption estimates were reconciled through iterative triangulation.
Shipment volume reconciliation across foundry output reports and OEM bill-of-materials data streams grounded the analytical framework. Segmentation dimensions modeled include product type, fabrication technology, end-user certification tier, and regional regulatory cluster. CAGRs were derived from logistic diffusion curves fitted to adoption data across automotive electrification and medical digitization cycles. SOI wafer allocation assumptions and REACH substance restriction timelines fed sensitivity testing.
The model holds under stable foundry capacity expansion and regulatory phase-in schedules; deviation in platinum group metal price volatility or SOI substrate supply disruption would shift volume trajectories. Forecasts reflect documented assumptions regarding MEMS process yield improvements and optical sensing substitution rates. Periodic stress-testing of base assumptions against foundry utilization reports and regulatory amendment announcements is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Virtual Sensors Market
Sensors and Controls
Tactile Indicators Market
Sensors and Controls
MEMS Market
Sensors and Controls
Automotive MEMS Sensor Market
Sensors and Controls
Fork Sensor Market
Sensors and Controls
Electrochemical Sensor Market
Sensors and Controls
Europe Emission Monitoring System Market
Sensors and Controls
ASEAN Safety Sensors and Switches Market
Sensors and Controls
High-Precision Confocal Sensor Market
Sensors and Controls
Volatile Organic Compound Gas Sensor Market
Sensors and Controls
Nano Positioning System Market
Sensors and Controls
Laser Displacement Sensor Market
Sensors and Controls
Meteorological Equipment Market
Sensors and Controls
High-Voltage Isolation and Leakage Sensor Components Market
Sensors and Controls
IoT Sensor Market
Sensors and Controls
Global MEMS and Sensors Market