
 3D Profile Sensors Market | 2026-2036
3D Profile Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
3D Profile Sensors Market Analytics
Sub-micron precision tier is redrawing competitive boundaries in 3D profile sensing. Infineon Technologies leverages its MEMS fabrication depth to sustain cost leadership in time-of-flight chipsets. Keyence Corporation anchors premium positioning through direct sales channels and application-engineered laser triangulation systems. Cognex Corporation specializes in vision-integrated profile sensors for high-speed packaging lines.
3D profile sensors are optoelectronic devices that capture surface geometry through structured light projection, laser triangulation, or time-of-flight pulse measurement, typically resolving features below 50 micrometers for dimensional verification and robotic guidance. Laser sensors dominate current volume shipments due to mature supply chains and broad industrial compatibility, while lidar-based profile systems represent the fastest-expanding technology segment as autonomous mobile robots proliferate in warehouses and factories. Camera systems capture the largest margin pool because multi-array CMOS architectures command premium pricing in semiconductor wafer inspection and medical device manufacturing.
FDA device-quality regulations and EU CE marking under the MDR framework compel sensor vendors to validate measurement traceability and software cybersecurity before healthcare and automotive OEM qualification. EPA energy-efficiency guidelines and OSHA machine-safety standards further shape product design requirements for factory-floor deployment. Stakeholders must monitor convergence between ISO metrology standards and emerging EU AI Act conformity protocols to anticipate certification burdens that will differentiate market-access winners from laggards.
Market Dynamics
Sub-micron precision requirements in automotive inline inspection and semiconductor wafer metrology are compressing sensor replacement cycles and forcing vendors to re-architect optical subsystems around AI-integrated edge processing.
Growth Catalysts
- EU AI Act Conformity Mandates:CE marking under the EU AI Act is compelling automotive and medical device OEMs to source certified 3D profile sensors with validated measurement traceability, accelerating platform standardization.
- Autonomous Mobile Robot Proliferation:Warehouse automation in Germany, China, and the United States is pulling demand for lidar-based profile systems that enable real-time obstacle detection and navigation in dynamic environments.
- MEMS Fabrication Scale:Time-of-flight chipsets manufactured at semiconductor-grade volumes are collapsing per-unit costs for mid-range industrial sensors, expanding addressable applications in packaging and logistics.
Market Restraints
- Specialized Optical Component Concentration:German and Japanese suppliers dominate precision laser diode and diffractive optical element production, creating single-source vulnerability for tier-two sensor assemblers.
- Technical Resolution Ceilings:Structured light systems face fundamental limits below five micrometers due to speckle noise and thermal drift, ceding sub-micron applications to atomic force microscopy and white-light interferometry.
- OSHA Machine-Safety Compliance Burden:Factory-floor deployment of high-power laser triangulation sensors requires extensive guarding, interlock systems, and operator certification that extends commissioning timelines.
Strategic Opportunities
- India Precision Manufacturing Clusters:PLI scheme incentives for electronics and automotive component production are creating first-mover advantage for sensor vendors establishing localized calibration and service infrastructure.
- Convergence of 3D Profile Sensing with Collaborative Robotics:Force-torque sensors and profile cameras are merging into unified end-effector modules that reduce integration complexity for small-batch manufacturers.
- EU Green Deal Circular Economy Requirements:CE marking under extended producer responsibility frameworks is favoring modular sensor designs with field-replaceable optical engines and standardized data interfaces.
Industry Challenges
- Multi-Domain Certification Timelines:Simultaneous FDA device-quality validation for medical applications and ISO metrology traceability for industrial contracts is stretching engineering resources at mid-cap vendors.
- Embedded AI Firmware Talent Scarcity:Real-time point-cloud processing on edge compute architectures demands rare combinations of optical physics, signal processing, and low-latency software engineering expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Profile Sensors Market |
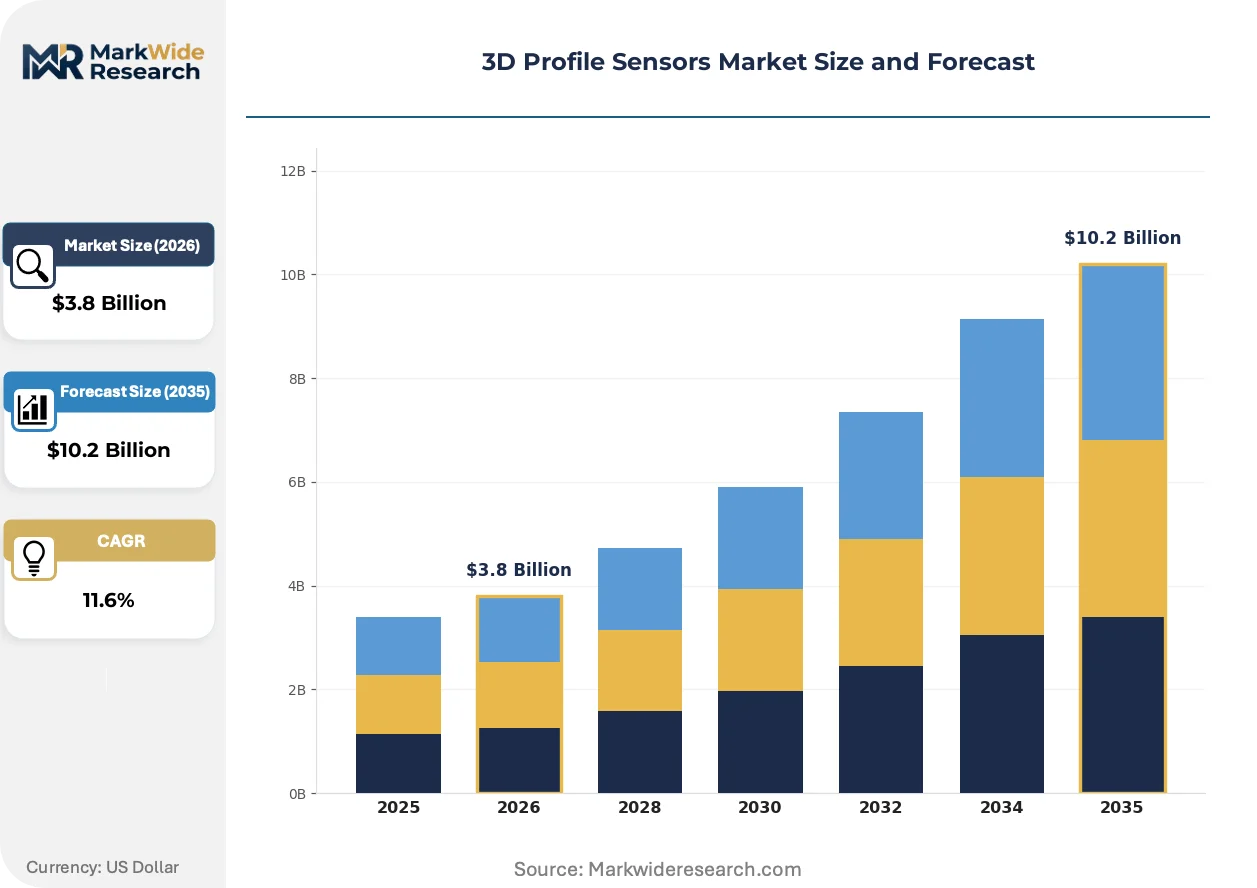
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.2 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Sensors, Camera Systems, Optical Devices, Microcontrollers End User: Automotive Manufacturers, Aerospace Firms, Electronics Manufacturers, Healthcare Facilities Technology: Structured Light, Time-of-Flight, Stereo Vision, Lidar Application: Quality Control, Robotics, Packaging Inspection, Surface Profiling |
| Companies Covered | Infineon Technologies, Cognex Corporation, Keyence Corporation, Sony Group Corporation, Microchip Technology Inc., STMicroelectronics, LMI Technologies, ifm electronic, OmniVision Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Profile Sensors Market Evolving Landscape
Computational imaging architectures and embedded AI inference are compressing the traditional separation between data acquisition and analysis, enabling real-time dimensional feedback loops that were previously hardware-limited.
Solid-state scanning lidar is decomposing the mechanical complexity that previously constrained profile sensor reliability in high-vibration automotive welding cells. Tier-one suppliers in Stuttgart and Detroit are specifying solid-state units for inline body-panel inspection, accepting moderate range penalties in exchange for MTBF improvements above fifty thousand hours. This reliability shift is decomposing the aftermarket service revenue model that sustained legacy vendors.
REACH restrictions on heavy metals and halogenated flame retardants are forcing redesign of sensor housings and cable assemblies for European industrial customers. The regulation's industrial consequence is accelerated adoption of aluminum-magnesium alloy enclosures and bio-based potting compounds that maintain EMI shielding performance. Semiconductor wafer inspection equipment manufacturers are most affected, with Dutch and German OEMs now requiring full material disclosure from subcomponent suppliers.
Buyer consolidation among contract electronics manufacturers is compressing vendor qualification cycles and favoring sensor platforms with unified software stacks across multiple factory sites. Foxconn and Jabil are consolidating approved vendor lists, displacing regional sensor distributors with direct OEM relationships. This concentration is most visible in Shenzhen and Penang, where procurement teams are standardizing on single-platform deployments to reduce training and spare-part complexity.
3D Profile Sensors Market Segmentation
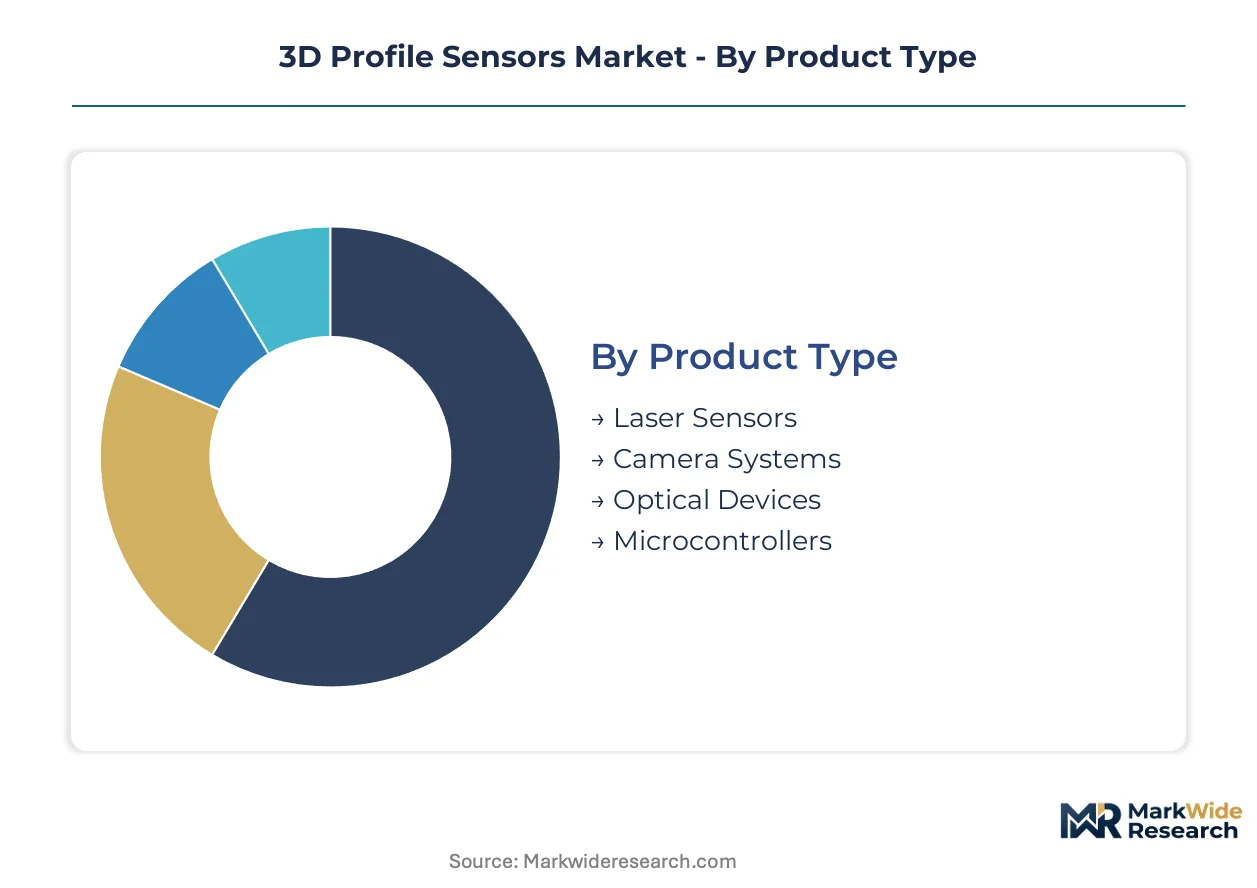
Segmentation in 3D profile sensors reveals how optical physics, regulatory compliance, and automation intensity fragment demand across incompatible technical specifications. Procurement patterns diverge sharply between high-volume logistics applications tolerating centimeter-grade accuracy and semiconductor wafer inspection demanding sub-micron resolution.
Product Type:
Laser sensors dominate domestic manufacturing bases in Germany and Japan where automotive welding cells require proven reliability. Camera systems and optical devices flow through export channels serving multinational electronics contract manufacturers.
- Laser Sensors:Triangulation-based units project coherent beams onto target surfaces, measuring deformation angles to calculate depth with typical resolutions of 10-50 micrometers. German automotive OEMs in Stuttgart and Wolfsburg specify these for inline body-panel gap inspection, driven by KBA safety certification requirements for robotic welding cells.
- Camera Systems:Multi-array CMOS architectures capture structured light patterns or stereo disparities, enabling full-field measurement rather than single-point profiling. Demand concentrates in Dutch semiconductor equipment manufacturing and Swiss medical device production, where FDA device-quality validation and MDR traceability requirements command premium pricing tiers.
- Optical Devices:Diffractive elements and precision lens assemblies from Japanese and German suppliers.
- Microcontrollers:Edge-compute units handling real-time point-cloud processing and AI inference.
Laser sensors command the established base. The steepest expansion runs through camera systems.
End User:
Cost tier stratification separates capital-intensive automotive and aerospace qualification programs from electronics manufacturers optimizing per-unit sensor economics. Healthcare facilities represent the premium tier where regulatory validation costs dominate procurement decisions.
- Automotive Manufacturers:Inline quality control for powertrain components, body assembly, and battery pack dimensional verification. Chinese EV producers in Shenzhen and Shanghai are pulling volume for lidar-based robotic guidance systems.
- Aerospace Firms:Turbine blade measurement and composite layup inspection requiring NIST-traceable calibration chains. US and French suppliers face FAA and EASA airworthiness documentation burdens that extend vendor qualification timelines.
- Electronics Manufacturers:Foxconn and Jabil facilities in Penang and Mexico standardizing on unified sensor platforms.
- Healthcare Facilities:Surgical navigation and prosthetic fitting applications under FDA and MDR frameworks.
Electronics manufacturers drive current volume procurement. Healthcare facilities are climbing the fastest toward premium-tier margins.
Technology:
Volume deployment favors mature structured light and time-of-flight architectures with established supply chains. Lidar and stereo vision segments expand through emerging autonomous mobile robot installations.
- Structured Light:Projected fringe patterns deformed by surface topology enable full-field capture at speeds exceeding laser point scanning. German machine builders integrate these into automotive assembly lines where five-micrometer precision suffices for most stamped-metal applications.
- Time-of-Flight:MEMS-fabricated emitters and SPAD detectors measure photon flight times, collapsing per-unit costs for mid-range logistics and packaging applications. Infineon's semiconductor-grade production in Austria supplies this expanding segment.
- Stereo Vision:Dual-camera triangulation without active illumination, preferred in eye-safe collaborative robotics.
- Lidar:Solid-state scanning units specified for high-vibration warehouse automation in US and Chinese distribution centers.
Structured light commands the established base. The steepest expansion runs through lidar.
Application:
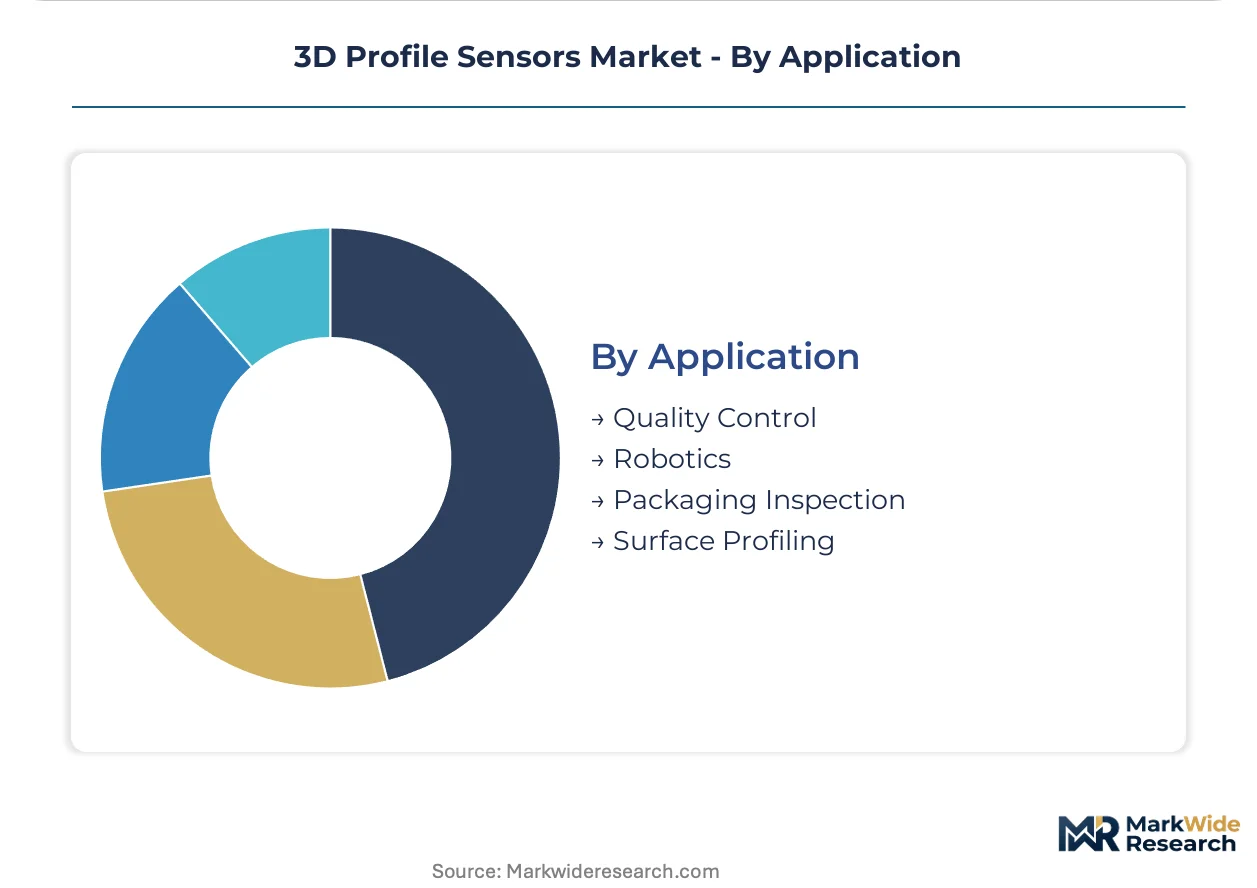
Customer type fragmentation separates process-embedded quality control from discrete robotic guidance installations. Surface profiling retains niche positioning in semiconductor and precision optics manufacturing.
- Quality Control:Inline dimensional verification triggering automatic reject gates, dominant in German automotive and Japanese electronics manufacturing where ISO metrology traceability is mandatory.
- Robotics:Real-time pose estimation and obstacle detection for autonomous mobile robots and collaborative arms. Warehouse operators in the United States and China are pulling demand for systems integrating profile sensing with force-torque feedback.
- Packaging Inspection:Label placement and seal integrity verification in food and pharmaceutical lines.
- Surface Profiling:Sub-micron roughness measurement for semiconductor wafers and optical components.
Quality control commands the established base. The steepest expansion runs through robotics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision laser diode and diffractive optical element production clusters in Germany and Japan concentrate upstream supply for 3D profile sensor assembly. Automotive OEM qualification programs and semiconductor fabrication investments pull demand toward manufacturing hubs with established metrology infrastructure.
United States
Warehouse automation in distribution centers across Ohio and Pennsylvania drives lidar-based profile system procurement for autonomous mobile robots. OSHA machine-safety standards govern high-power laser triangulation deployment on factory floors. Detroit-area automotive OEMs specify solid-state scanning units for inline body-panel inspection, accepting range trade-offs for reliability gains.
Germany
Stuttgart and Wolfsburg automotive clusters demand sub-micron precision for powertrain component verification and robotic welding guidance. KBA safety certification requirements and EU AI Act conformity mandates compel vendors to validate measurement traceability before OEM qualification. Munich-based semiconductor equipment manufacturers integrate structured light systems for wafer metrology applications.
China
Shenzhen and Shanghai EV producers pull volume for lidar-based robotic guidance in battery pack assembly lines. MIIT industrial automation directives and dual carbon goals accelerate sensor adoption for energy-efficient manufacturing processes. Foxconn facilities in Zhengzhou standardize on unified sensor platforms to reduce spare-part complexity across multiple sites.
Japan
Osaka and Nagoya electronics manufacturing bases sustain demand for camera systems in semiconductor packaging inspection. METI technology roadmaps prioritize MEMS fabrication scale for time-of-flight chipset cost reduction. Yokohama-based machine builders integrate stereo vision modules into collaborative robotics for eye-safe human-robot interaction.
India
PLI scheme incentives for electronics and automotive component production create first-mover openings for sensor vendors establishing calibration infrastructure. BIS standards for industrial equipment safety shape product design requirements for factory-floor deployment. Tamil Nadu precision manufacturing clusters in Chennai and Coimbatore attract localized service and support investments from multinational suppliers.
3D Profile Sensors Market Competitive Landscape
Concentration sits with diversified semiconductor conglomerates and specialized machine vision houses. The vendor base splits between integrated conglomerates leveraging captive MEMS fabrication and focused specialists commanding premium positioning through application-engineered systems. Two strategic archetypes dominate: semiconductor-grade volume producers collapsing per-unit costs through wafer-scale manufacturing, and direct-sales specialists embedding application engineering into customer qualification workflows. Competitive moves center on backward integration into optical component supply and geographic expansion through localized calibration facilities.
Within the semiconductor-grade tier, Infineon Technologies and STMicroelectronics exemplify volume-driven positioning through MEMS fabrication depth. Among machine vision specialists, Keyence Corporation occupies a position anchored by direct sales channels and application-engineered laser triangulation systems. Cognex Corporation sits within the vision-integrated segment, representing the convergence of profile sensing with packaging line automation. Sony Group Corporation and OmniVision Technologies anchor the image sensor supply layer that underpins multi-array CMOS architectures in premium inspection applications.
| Leading Market Players |
|---|
| Infineon Technologies |
| Cognex Corporation |
| Keyence Corporation |
| Sony Group Corporation |
| Microchip Technology Inc. |
| STMicroelectronics |
| LMI Technologies |
| ifm electronic |
| OmniVision Technologies |
| Others |
Value Network & Pricing Analysis
Solid-state lidar substitution for mechanical scanning units is redrawing supply geography toward Taiwanese MEMS foundries and compressing pricing premiums for automotive-grade reliability tiers. This component transition simultaneously concentrates optical engine procurement and collapses the aftermarket service margins that sustained legacy vendors.
Pricing Analysis
EU AI Act conformity mandates dictate the pricing tier structure across the 3D profile sensor landscape. Three-tier pricing stratifies across certified premium platforms for medical device OEMs, standard industrial configurations for automotive welding cells, and economy time-of-flight chipsets for logistics applications. Price differentiation rests on measurement traceability grade and cybersecurity validation depth. Cost compression in mid-range industrial tiers is intensifying because MEMS fabrication scale at Infineon and STMicroelectronics collapses per-unit chipset economics. Electronics contract manufacturers exhibit highest price sensitivity, while healthcare facilities under FDA and MDR frameworks tolerate premium positioning for validated metrology chains.
Supply Chain Analysis
Just-in-time inventory preferences dominate German and Japanese automotive OEM procurement, while strategic stockpiling of precision laser diodes persists among tier-two sensor assemblers facing single-source vulnerability. German and Japanese suppliers anchor precision laser diode and diffractive optical element production. Raw material dependencies draw from rare-earth phosphors for laser emitters, high-purity silicon for SPAD detectors, and aluminum-magnesium alloys for REACH-compliant enclosures. Single-source vulnerability for precision optical components creates structural supply risk. Distribution runs through direct OEM relationships consolidated by Foxconn and Jabil, displacing regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The 3D profile sensor market is recovering from a cyclical trough in industrial automation capital expenditure. Automotive OEM qualification cycles and warehouse automation buildouts in Germany, China, and the United States provide the cyclical uplift.
For Market Incumbents: Shield embedded firmware margins by deepening in-house production of AI inference accelerators and securing captive supply of precision diffractive optical elements from German and Japanese sources. MEMS fabrication scale at semiconductor conglomerates threatens cost leadership in time-of-flight chipsets. Certification investment in EU AI Act conformity protocols and FDA device-quality validation creates switching costs that lock in automotive and medical OEM relationships. For New Entrants and Emerging Players: Localized calibration and service infrastructure gaps in Indian precision manufacturing clusters present first-mover openings under PLI scheme incentives. Target Tamil Nadu electronics and automotive component production zones where multinational vendors have underinvested in field service density. A calibration-as-a-service go-to-market angle bypasses the capital intensity of full sensor manufacturing while capturing recurring revenue from BIS-compliant industrial deployments. For Investors and Strategic Acquirers: EU AI Act implementation reshapes the acquisition landscape toward sensor platforms with pre-validated measurement traceability and modular optical engine architectures. Long-term viability over a multi-year horizon favors targets with embedded AI firmware capabilities and established automotive OEM qualification pipelines. The signal to monitor is consolidation in contract electronics manufacturing approved vendor lists, which will determine which sensor platforms achieve scale economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical Component Supply | Captive supply of German and Japanese precision laser diodes reduces single-source vulnerability for tier-two assemblers. |
| EU AI Act Conformity Certification | CE marking validation accelerates automotive and medical OEM qualification timelines ahead of non-compliant competitors. |
| Localized Calibration Infrastructure Deployment | PLI scheme incentives in India reward first-mover establishment of service density in Tamil Nadu manufacturing clusters. |
| Solid-State Lidar Platform Standardization | MTBF improvements above fifty thousand hours meet Detroit and Stuttgart automotive welding cell reliability specifications. |
| Embedded AI Firmware Development | Real-time point-cloud processing on edge compute architectures addresses talent scarcity in optical physics and signal processing convergence. |
Research Methodology
A spread of perspectives from automotive OEM platform engineers, semiconductor equipment procurement leads, machine vision system integrators, and warehouse automation operators converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation drawing from SEC filings, customs and trade data, IHS Markit vehicle production databases, and hospital procurement records. Bottom-up sensor shipment modeling and top-down industrial automation capex triangulation anchored volume and value estimates.
Segmentation dimensions modeled include product type, end user industry, technology architecture, and application across the projection horizon. CAGRs were derived from trend extrapolation of automotive inline inspection adoption, semiconductor wafer metrology equipment shipments, and autonomous mobile robot deployment trajectories. Industry-specific forecast inputs incorporated MIIT industrial automation directives, EU Green Deal circular economy requirements, and OSHA machine-safety compliance timelines.
Material uncertainties — regulatory enforcement intensity for EU AI Act conformity, MEMS fabrication yield improvements, and tariff exposure on precision optical component trade — sit outside the modeled envelope. Forecasts reflect assumptions about sustained automotive EV production growth and warehouse automation capital allocation. Revision becomes warranted when semiconductor equipment capex or automotive OEM qualification cycle durations cross thresholds that alter sensor replacement velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Digital Pool Thermometers Market
Sensors and Controls
Europe MEMS and Sensors Market
Sensors and Controls
Middle East and Africa Wearable Sensors Market
Sensors and Controls
Turbomachinery Control Systems Market
Sensors and Controls
APAC Pressure Sensors Market
Sensors and Controls
United States Chemical Sensors Market
Sensors and Controls
Global Tilt Sensor Market
Sensors and Controls
Water Cut Monitor Market
Sensors and Controls
Environmental Noise Cancellation Microphones Market
Sensors and Controls
Mexico Pressure Sensor Market
Sensors and Controls
Active Sensor Market
Sensors and Controls
Electronic Differential Control Module Market
Sensors and Controls
Middle East and Africa Vibration Sensors Market
Sensors and Controls
Occupancy Sensor Market
Sensors and Controls
North America Pressure Sensors Market
Sensors and Controls
United States Smart Sensors Market