
 Asia-Pacific Digital Thermometer Market | 2026-2036
Asia-Pacific Digital Thermometer Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Digital Thermometer Market Analytics
Remote patient monitoring subscriptions is expanding the addressable base beyond one-time hardware sales across the Asia-Pacific digital thermometer landscape. OMRON Healthcare leverages its connected health platform to anchor recurring revenue streams in Japan's home-care segment. Terumo Corporation sustains hospital-grade precision through vertically controlled sensor calibration in its domestic manufacturing footprint. A&D Company, Limited competes on price-performance in China's pharmacy retail channel with Bluetooth-enabled forehead units.
A digital thermometer measures body temperature through electronic heat sensors, typically employing thermistors or infrared detectors with accuracy thresholds of ±0.1°C for clinical validation and ±0.2°C for consumer-grade devices. The primary commercial purpose spans fever screening in clinical settings, home health management, and integrated vital-sign monitoring within connected care ecosystems. Forehead infrared units lead volume across Asia-Pacific pharmacy counters due to non-contact hygiene protocols established during pandemic response frameworks. Connected Health represents the fastest-expanding technology tier as hospitals in South Korea and Australia deploy Bluetooth-integrated devices into electronic health record workflows. In-Ear segments retain margin concentration in pediatric and precision-medicine applications where tympanic membrane proximity delivers superior thermal fidelity.
Japan's PMDA enforces Class II medical device certification for clinical-grade digital thermometers, while Australia's TGA mandates ISO 80601-2-56 compliance for infrared units entering hospital procurement channels. India's CDSCO has streamlined registration pathways under its 2017 Medical Device Rules, accelerating market access for both domestic manufacturers and imported connected-health platforms. China's NMPA now requires cybersecurity documentation for Bluetooth-enabled thermometers, adding compliance layers that favor established multinationals with dedicated regulatory affairs teams. Stakeholders must monitor divergence between national data-localization requirements and cross-border cloud connectivity architectures as connected-health penetration deepens.
Market Dynamics
Japan's aging-care infrastructure and India's PLI scheme for medical devices are creating divergent demand poles across the Asia-Pacific digital thermometer landscape. Home healthcare networks in South Korea and Australia are accelerating Bluetooth-integrated thermometer deployment into electronic health record workflows, compressing replacement cycles and elevating cybersecurity compliance burdens simultaneously.
Growth Catalysts
- PLI scheme incentives:India's production-linked incentive framework for medical devices is attracting component manufacturers to establish domestic thermistor and sensor calibration facilities, reducing import dependency for infrared detector assemblies.
- Home healthcare expansion:Japan's community-based integrated care systems are mandating remote vital-sign monitoring for discharged patients, creating institutional pull for connected forehead units with cloud data transmission.
- Bluetooth-integrated workflows:South Korean hospital networks are embedding Bluetooth-enabled thermometers into fever screening protocols, eliminating manual temperature logging and reducing nursing documentation burden.
Market Restraints
- Semiconductor input volatility:Thermistor and microcontroller shortages from Taiwan-based foundries are extending lead times for precision sensor modules, compressing margins on consumer-grade forehead units.
- Regulatory fragmentation:Divergent cybersecurity documentation requirements between China's NMPA and Australia's TGA are forcing manufacturers to maintain parallel certification tracks, elevating compliance overhead.
- Disposable probe cover dependency:Hospital-grade in-ear segments remain tethered to single-use hygienic sheath supply chains concentrated in Malaysian rubber processing facilities, exposing cost structures to petrochemical price swings.
Strategic Opportunities
- Indonesia's pharmacy retail expansion:The country's pharmacy chain consolidation is creating shelf-space competition where Bluetooth-enabled forehead units can displace mercury thermometer residual stock in Jakarta and Surabaya metropolitan networks.
- Vietnam's manufacturing relocation:Multinational thermometer brands are establishing final assembly operations in Bac Ninh and Hai Phong industrial zones to access ASEAN tariff preferences and offset China-origin duty exposure.
- Pediatric precision segments:Tympanic membrane proximity sensing for neonatal applications represents an underexploited margin tier where clinical validation protocols from Japan's PMDA create defensible certification moats.
Industry Challenges
- Embedded systems firmware talent scarcity:Bluetooth Low Energy stack optimization and medical-grade cybersecurity implementation require specialized engineering capabilities concentrated in Shenzhen and Taipei, creating recruitment bottlenecks for manufacturers expanding connected health portfolios.
- Calibration equipment capex intensity:Blackbody radiator chambers and traceable temperature reference standards necessary for PMDA Class II certification demand seven-figure capital commitments, favoring incumbents with established metrology laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Digital Thermometer Market |
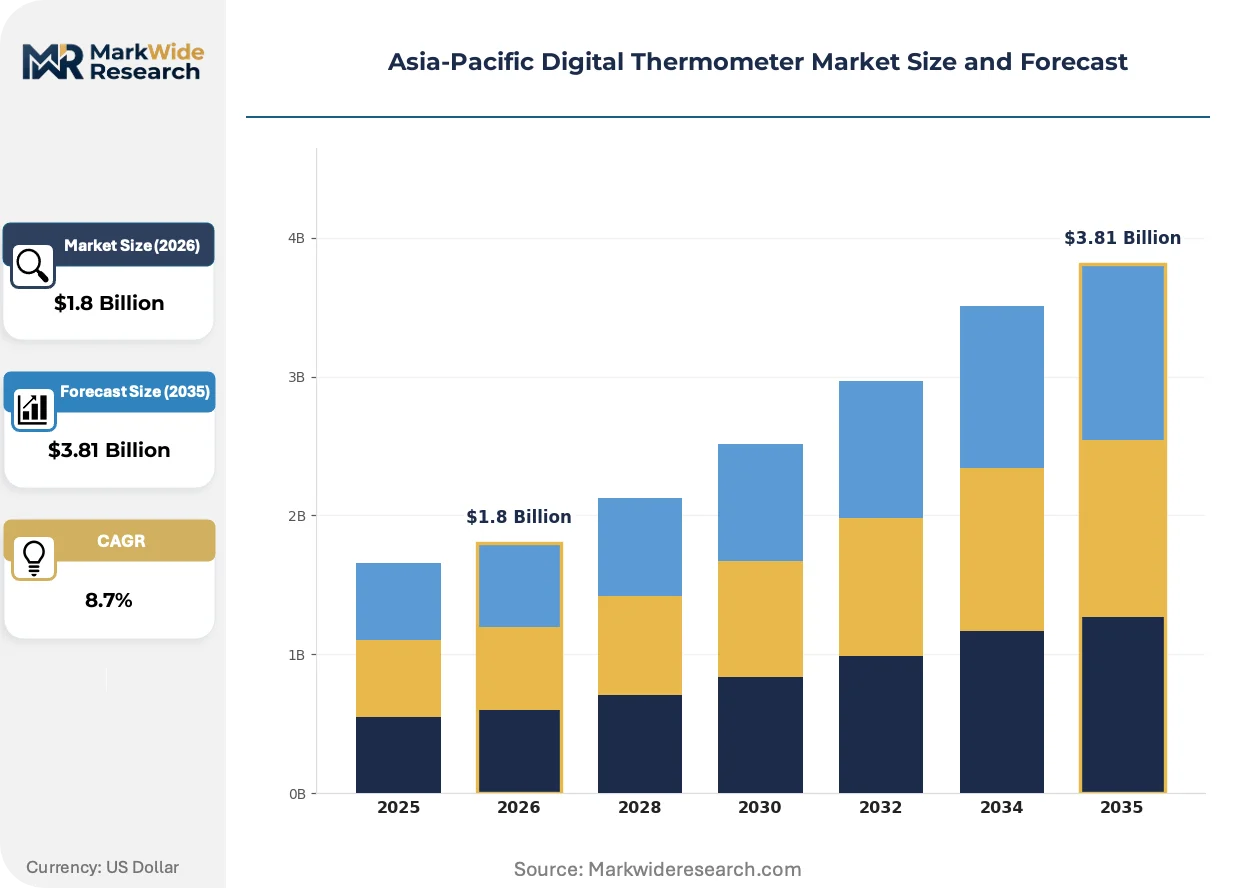
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: In-Ear, Forehead, Oral, Blood Pressure End User: Home Users, Hospitals, Clinics, Laboratories Distribution Channel: Online Retail, Pharmacies, Supermarkets, Specialty Stores Technology: Infrared, Digital LCD, Bluetooth, Connected Health |
| Companies Covered | OMRON Healthcare, Terumo Corporation, Medline Industries, A&D Company, Limited, Geratherm Medical AG, Teledyne FLIR, AMETEK, Inc., Fairhaven Health, Kinsa Health, LLC, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Digital Thermometer Market Evolving Landscape
Sensor miniaturization and edge computing integration are compressing the traditional separation between consumer wellness devices and clinical-grade diagnostic tools across Asia-Pacific thermometer supply chains. Regulatory pressure on data localization is forcing architecture redesigns that favor regional cloud partnerships over global platforms.
Multi-spectral infrared detection is modularizing across forehead thermometer product lines, enabling simultaneous surface temperature and ambient compensation readings without external calibration references. Japanese hospital procurement networks are piloting these units in fever screening gateways at Osaka and Tokyo medical centers, collapsing the historical distinction between screening-grade and diagnostic-grade thermal hardware.
China's NMPA cybersecurity documentation mandate for Bluetooth-enabled medical devices is forcing firmware architecture disclosures that previously constituted trade secrets. Domestic manufacturers with dedicated regulatory affairs teams in Beijing and Shanghai are accelerating certification timelines, while smaller importers face extended review queues or voluntary market withdrawal.
Subscription-based remote patient monitoring is displacing one-time hardware transactions in Japan's home-care segment, with thermometer readings bundled into monthly vital-sign monitoring fees. Pharmacy retail channels in Australia's metropolitan networks are responding by unbundling device sales from data platform access, creating two-tier purchasing options that separate hardware-only buyers from connected-ecosystem subscribers.
Asia-Pacific Digital Thermometer Market Segmentation
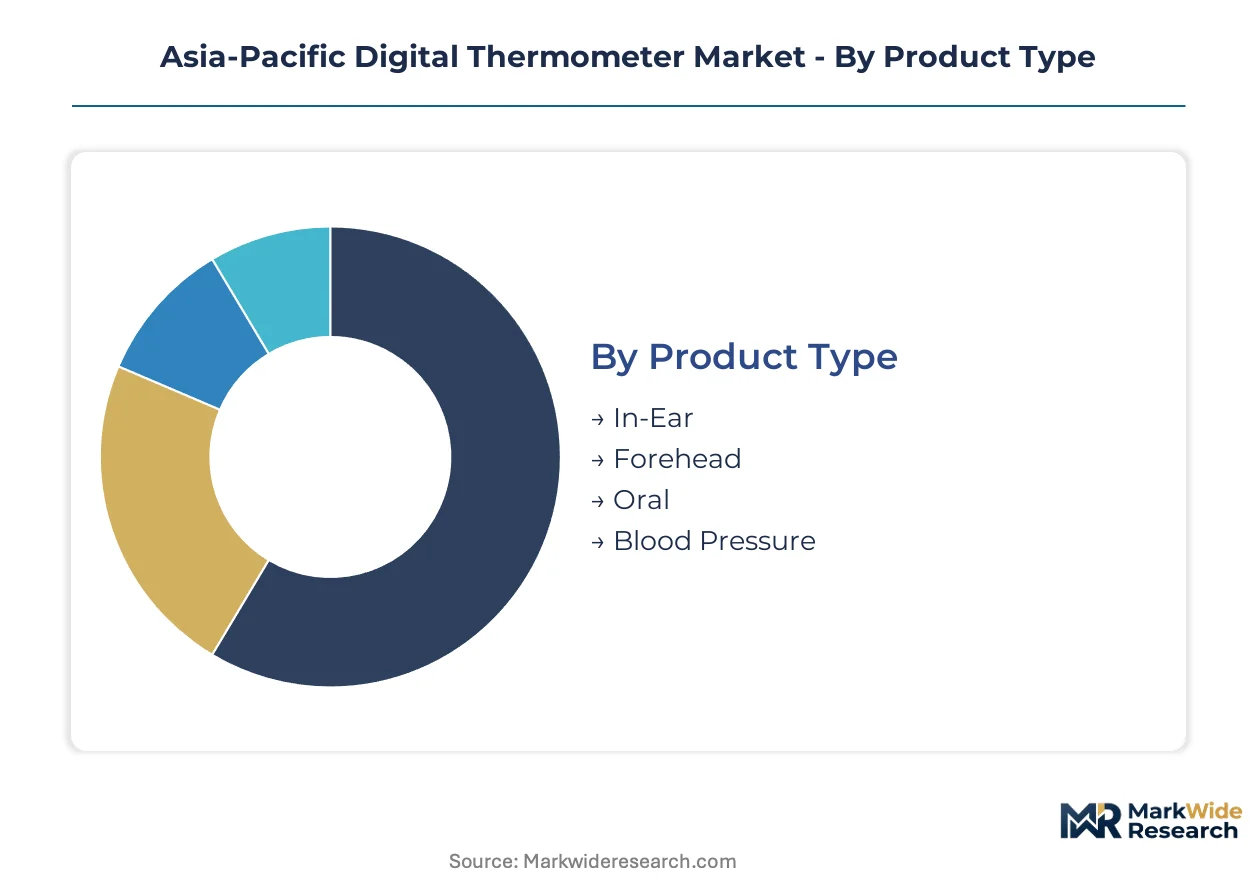
Segmentation in the Asia-Pacific digital thermometer market reveals how supply chain configuration, regulatory pathways, and channel economics concentrate margin capture across distinct product tiers. Manufacturers calibrate certification investments and firmware architectures to match the precision demands and connectivity requirements of each segment.
Product Type:
Supply concentration for sensor modules and calibration equipment tilts manufacturing advantage toward segments with scaleable production platforms and transferable metrology investments.
- Forehead:Non-contact infrared units dominate pharmacy retail volumes across China and Southeast Asia, with demand concentrating in fever screening protocols established during pandemic response frameworks. PMDA Class II certification requirements in Japan elevate entry barriers for clinical-grade variants, compressing margin competition to established multinationals with dedicated regulatory affairs teams.
- In-Ear:Tympanic membrane proximity sensing delivers superior thermal fidelity for neonatal and precision-medicine applications, with demand anchoring in Japan's aging-care facilities and South Korean hospital networks. Single-use probe cover supply chains concentrated in Malaysian rubber processing facilities tether cost structures to petrochemical volatility.
- Oral:Consumer-grade digital LCD variants serve price-sensitive home users across India's tier-2 and tier-3 cities, competing against residual mercury thermometer stock.
- Blood Pressure:Integrated vital-sign monitoring devices bundle temperature sensing with cardiovascular metrics, targeting Australia's remote patient monitoring subscriptions and Japan's connected health platforms.
Today's leader: Forehead. Tomorrow's challenger: In-Ear.
End User:
Application-driven procurement patterns split the market between institutional buyers with compliance mandates and retail consumers prioritizing price-performance tradeoffs.
- Hospitals:Clinical-grade infrared and connected health devices anchor procurement in China's tier-1 hospital networks and South Korean electronic health record integration projects. Australia's TGA mandates ISO 80601-2-56 compliance for infrared units entering hospital channels, forcing parallel certification tracks with China's NMPA cybersecurity documentation requirements.
- Home Users:Bluetooth-enabled forehead units with smartphone integration capture recurring revenue through data platform subscriptions in Japan's community-based integrated care systems. India's pharmacy retail expansion concentrates demand in price-competitive digital LCD segments.
- Clinics:Mid-tier precision devices balance diagnostic reliability with capital constraints, serving Indonesia's consolidating pharmacy chains and Vietnam's provincial healthcare networks.
- Laboratories:Traceable calibration standards and blackbody radiator verification protocols dominate procurement, with Japan's PMDA certification creating defensible moats for established metrology laboratories.
Institutional buyers command pricing power through volume aggregation; home segments expand most quickly via subscription monetization.
Distribution Channel:
Channel economics reshape competitive positioning as e-commerce platforms disintermediate traditional pharmacy networks and direct-to-patient models capture recurring revenue streams.
- Online Retail:E-commerce platforms in China and India aggregate price-transparent comparison shopping for consumer-grade devices, compressing margins on undifferentiated digital LCD variants. Subscription-based remote patient monitoring platforms in Japan bypass retail entirely, bundling thermometer hardware into monthly vital-sign monitoring fees.
- Pharmacies:Indonesia's pharmacy chain consolidation in Jakarta and Surabaya metropolitan networks creates shelf-space competition where Bluetooth-enabled forehead units displace mercury thermometer residual stock. Australia's metropolitan pharmacy networks unbundle device sales from data platform access, creating two-tier purchasing options.
- Supermarkets:Mass-market consumer-grade oral thermometers serve emergency purchase occasions and price-sensitive demographics across India's urban centers.
- Specialty Stores:Medical equipment distributors target institutional procurement with clinical-grade certification support and calibration service bundling in Japan and South Korea.
Platform intermediation accelerates in consumer segments; service bundling defends position in institutional channels.
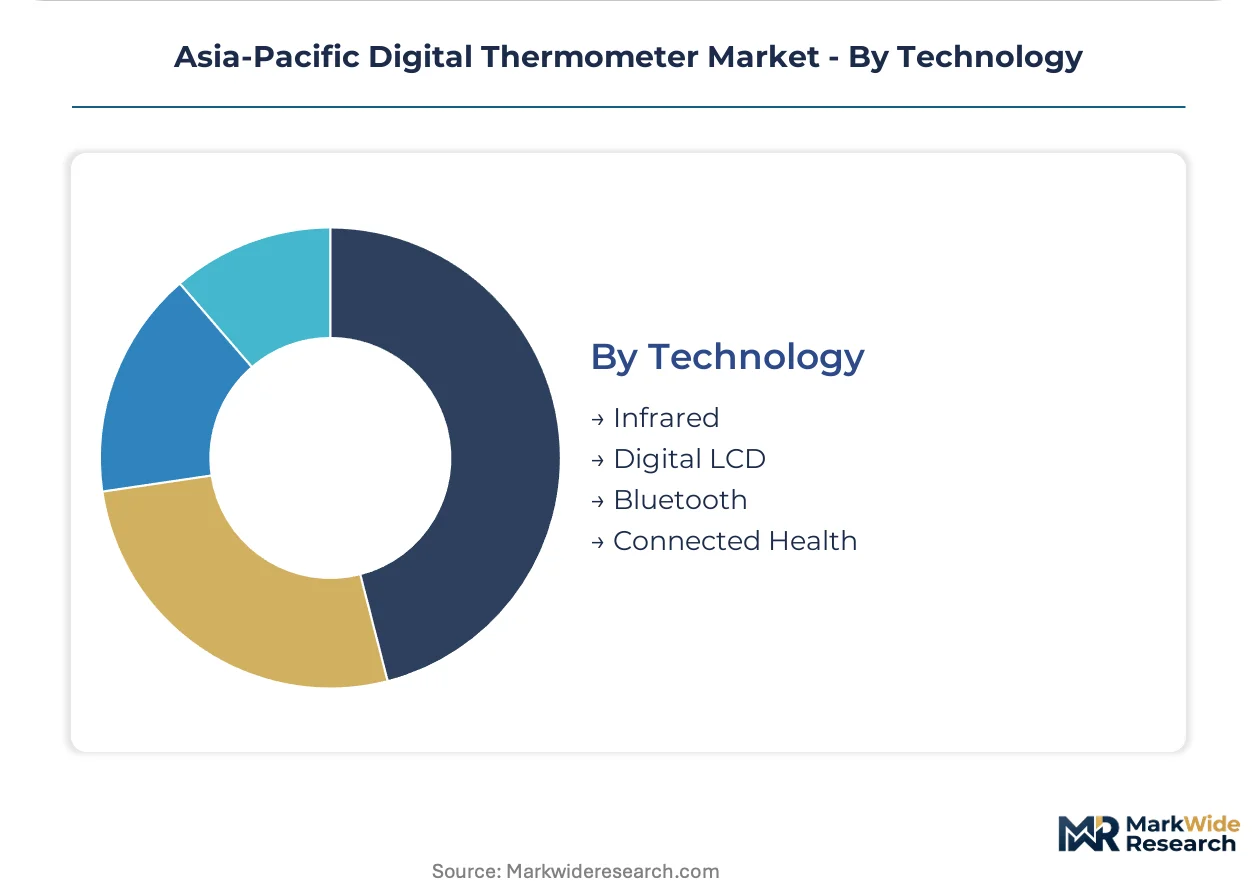
Technology:
Technology tier stratification reflects the compression between consumer wellness devices and clinical-grade diagnostic tools, with connectivity mandates forcing firmware architecture disclosures.
- Connected Health:Bluetooth-integrated devices with cloud data transmission represent the steepest expansion trajectory, as South Korean hospital networks embed thermometers into fever screening protocols and Japan's community-based integrated care systems mandate remote vital-sign monitoring. China's NMPA cybersecurity documentation mandate forces architecture disclosures that favor domestic manufacturers with dedicated regulatory affairs teams in Beijing and Shanghai.
- Infrared:Multi-spectral detection modules enabling simultaneous surface temperature and ambient compensation readings are piloting in Osaka and Tokyo medical centers, collapsing historical distinctions between screening-grade and diagnostic-grade hardware.
- Bluetooth:Low Energy stack optimization and medical-grade cybersecurity implementation require specialized engineering capabilities concentrated in Shenzhen and Taipei, creating recruitment bottlenecks for manufacturers expanding connected health portfolios.
- Digital LCD:Mature consumer-grade technology serves price-sensitive volume segments across India and Southeast Asia, with minimal differentiation beyond brand recognition and retail placement.
Certification burden concentrates advantage in connected tiers; price competition commoditizes legacy display technologies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's tier-1 hospital networks drive institutional procurement volumes, while India's pharmacy retail expansion concentrates demand in price-competitive consumer segments. Divergent regulatory pathways between Japan's PMDA and Australia's TGA are fragmenting certification requirements across the region.
China
Demand concentrates in tier-1 hospital networks deploying Bluetooth-integrated thermometers into electronic health record workflows. NMPA cybersecurity documentation mandates for connected devices favor domestic manufacturers with dedicated regulatory affairs teams in Beijing and Shanghai. Shenzhen engineering clusters specialize in Bluetooth Low Energy stack optimization for medical-grade applications.
Japan
Community-based integrated care systems mandate remote vital-sign monitoring for discharged patients, creating institutional pull for connected forehead units. PMDA enforces Class II medical device certification for clinical-grade digital thermometers, elevating entry barriers. Osaka and Tokyo medical centers pilot multi-spectral infrared detection modules in fever screening gateways.
India
Pharmacy retail expansion in tier-2 and tier-3 cities concentrates demand in price-sensitive digital LCD segments competing against residual mercury thermometer stock. CDSCO registration pathways under 2017 Medical Device Rules accelerate market access for domestic and imported platforms. Maharashtra and Gujarat industrial corridors attract component manufacturers under PLI scheme incentives for thermistor and sensor calibration facilities.
South Korea
Hospital networks embed Bluetooth-enabled thermometers into fever screening protocols, eliminating manual temperature logging and reducing nursing documentation burden. MFDS aligns with international standards for connected health device approval, streamlining cross-border certification. Seoul metropolitan procurement networks aggregate volume for electronic health record integration projects.
Australia
Remote patient monitoring subscriptions displace one-time hardware transactions in metropolitan pharmacy networks, unbundling device sales from data platform access. TGA mandates ISO 80601-2-56 compliance for infrared units entering hospital procurement channels. Sydney and Melbourne healthcare systems drive connected health adoption in home-care segments.
Asia-Pacific Digital Thermometer Market Competitive Landscape
Top-tier vendors anchor hospital-grade certification tiers, while mid-scale specialists compete on price-performance in pharmacy retail channels. The vendor base stratifies across three archetypes: multinational health technology conglomerates with dedicated regulatory affairs teams, regional electronics manufacturers with sensor calibration capabilities, and emerging connected-health platforms with subscription monetization models. Competitive moves center on geographic manufacturing relocation to access tariff preferences and portfolio diversification into integrated vital-sign monitoring devices.
Within the multinational health technology tier, OMRON Healthcare and Terumo Corporation exemplify established market anchors with vertically controlled domestic manufacturing footprints. A&D Company, Limited occupies a position among Japanese precision instrument specialists competing across price-performance segments. These three entities represent distinct strategic postures: connected health platform anchoring, hospital-grade precision manufacturing, and retail channel price competition.
| Leading Market Players |
|---|
| OMRON Healthcare |
| Terumo Corporation |
| Medline Industries |
| A&D Company, Limited |
| Geratherm Medical AG |
| Teledyne FLIR |
| AMETEK, Inc. |
| Fairhaven Health |
| Kinsa Health, LLC |
| Others |
Value Network & Pricing Analysis
China's tier-1 hospital procurement networks concentrate demand for clinical-grade connected thermometers, anchoring a contract-based pricing model where NMPA cybersecurity certification tiers separate premium Bluetooth-integrated units from standard infrared variants. This buyer concentration forces manufacturers to absorb compliance costs upfront while competing on multi-year service bundling.
Pricing Analysis
Capacity additions in Vietnam's Bac Ninh and Hai Phong industrial zones are reshaping price floors for consumer-grade forehead units by offsetting China-origin duty exposure. Three-tier pricing structure across premium, standard, and economy levels stratifies by PMDA Class II certification status and Bluetooth Low Energy stack complexity. Cost compression in India's pharmacy retail channel intensifies because PLI scheme incentives attract domestic thermistor manufacturers, eroding import-dependent cost structures. Home users in Southeast Asia exhibit highest price sensitivity, while Japan's aging-care facilities accept premium positioning for cloud-integrated remote monitoring subscriptions.
Supply Chain Analysis
Firmware engineering talent scarcity in Shenzhen and Taipei clusters constrains production scale-up for Bluetooth-enabled medical devices across the region. Taiwan-based foundries and Malaysian rubber processing facilities anchor component supply for precision sensor modules and disposable probe sheaths. Single-source vulnerability in semiconductor thermistor supply chains exposes manufacturers to foundry allocation volatility. Distribution runs through Indonesia's consolidating pharmacy chains and Australia's direct-to-patient remote monitoring platforms, bypassing traditional retail in subscription-heavy segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as demographic aging across Japan, South Korea, and Australia institutionalizes remote vital-sign monitoring into standard discharge protocols.
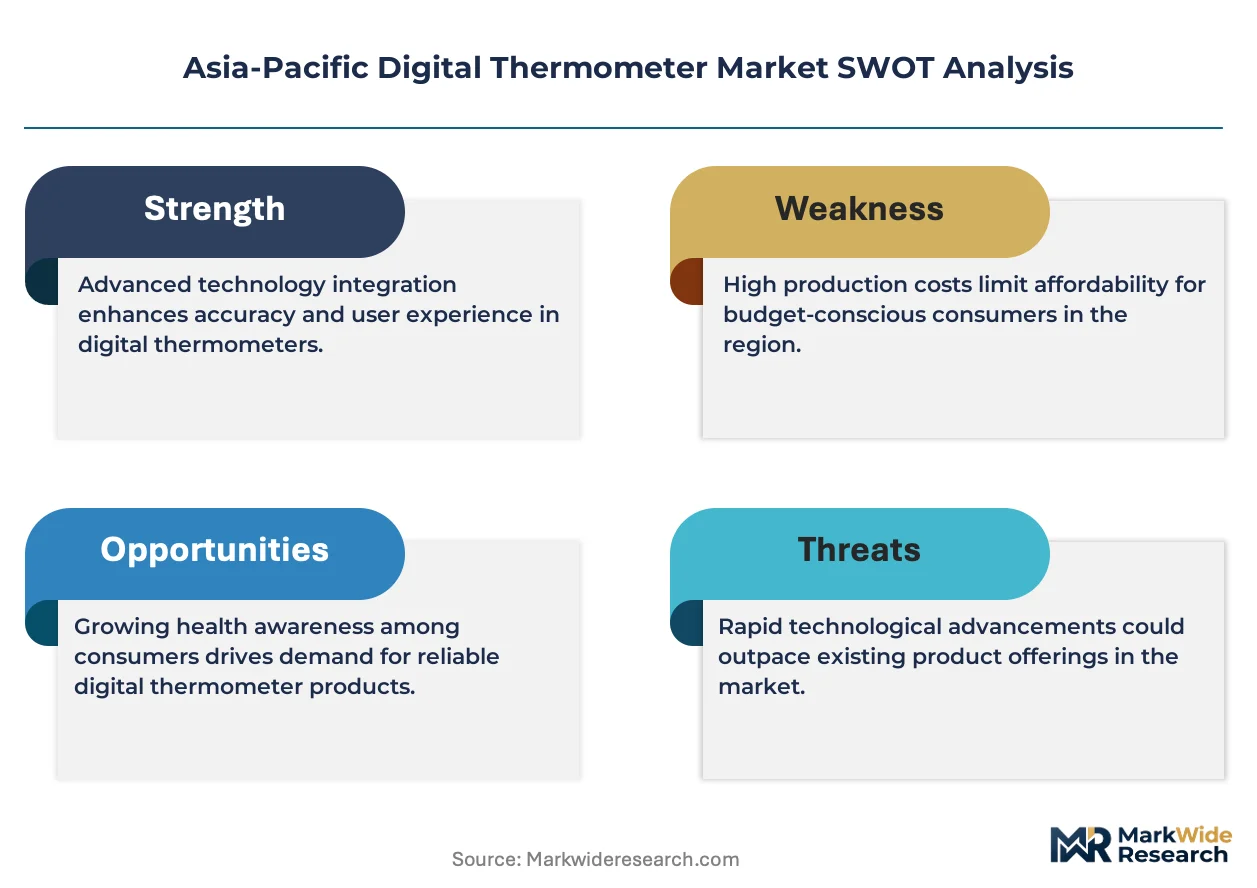
For Market Incumbents: Acquire specialized firmware engineering capabilities in Shenzhen and Taipei to secure Bluetooth Low Energy optimization talent before recruitment bottlenecks widen. Deepen backward integration into thermistor calibration facilities under India's PLI scheme to offset Taiwan foundry dependency. Defend against emerging connected-health platforms by bundling hospital-grade certification with cloud data platform subscriptions. For New Entrants and Emerging Players: India's CDSCO registration pathways under 2017 Medical Device Rules open a window for price-competitive digital LCD variants in tier-2 and tier-3 pharmacy networks. Target Indonesia's pharmacy chain consolidation in Jakarta and Surabaya where Bluetooth-enabled forehead units displace residual mercury stock. Pursue pediatric precision segments in neonatal applications where PMDA clinical validation protocols create defensible certification moats against commoditized competition. For Investors and Strategic Acquirers: Health technology conglomerates with dedicated regulatory affairs teams are the most active acquirer in this space, seeking connected-health platforms with recurring revenue models. Five-to-ten year viability hinges on subscription monetization penetration in Japan's home-care segment and South Korea's hospital network integration. Watch for divergence between China's NMPA data-localization mandates and cross-border cloud connectivity architectures as the inflection signal for platform scalability constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Bluetooth Low Energy Stack Optimization | Seoul hospital networks demand seamless EHR integration for fever screening protocols. |
| NMPA Cybersecurity Certification Investment | Domestic manufacturers with Beijing regulatory teams accelerate market access timelines. |
| PLI Scheme Manufacturing Relocation | Maharashtra and Gujarat corridors reduce import dependency for infrared detector assemblies. |
| Multi-Spectral Infrared Module Development | Osaka and Tokyo medical centers pilot ambient-compensated screening-grade hardware. |
| Subscription Platform Unbundling | Australian pharmacies separate hardware sales from data access to capture dual customer tiers. |
Research Methodology
Coverage spans China, Japan, India, South Korea, and Australia, with primary inputs from each market's hospital procurement committees, biomedical engineering directors, pharmacy chain category managers, and connected health platform operators. Secondary validation draws from NMPA cybersecurity documentation filings, PMDA Class II certification registries, CDSCO registration databases, and GPO contract aggregators. Bottom-up sensor module production estimates triangulate against top-down thermometer shipment data across the analysis window.
Rate-of-change decomposition separates volume expansion from value migration across product type, end user, distribution channel, and technology tier dimensions. CAGRs derive from segment-level growth trajectory modeling calibrated to regulatory approval timelines and procurement cycle phasing. Forecast inputs incorporate PLI scheme capacity buildout schedules, hospital EHR integration project pipelines, and pharmacy retail consolidation trajectories without year-specific anchoring.
Revisions become necessary when NMPA cybersecurity mandates expand beyond Bluetooth-enabled devices, Taiwan foundry allocation disrupts thermistor supply continuity, or Japan's community-based integrated care systems shift reimbursement structures for remote monitoring. Material deviation in these triggers warrants pause and re-evaluation of connected-health penetration assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
PM2.5 Sensors Market
Sensors and Controls
Digital Temperature Gauge Market
Sensors and Controls
Electronic Differential Control Module Market
Sensors and Controls
Global Rotation Laser Market
Sensors and Controls
Air Pressure Sensor Market
Sensors and Controls
Advanced Sensor Market
Sensors and Controls
Echo Sounder Market
Sensors and Controls
Wireless Flow Sensors Market
Sensors and Controls
VOC Sensors and Monitors Market
Sensors and Controls
Europe Water Detection Sensors Market
Sensors and Controls
France Air Purifier Market
Sensors and Controls
RTD Temperature Sensors Market
Sensors and Controls
Solid Flow Rate Valve Control Market
Sensors and Controls
Electromagnetic Tracking Systems Market
Sensors and Controls
China Industrial Sensors Market
Sensors and Controls
In-Display Fingerprint Sensors Market