
 Global Temperature Sensors Market | 2026-2036
Global Temperature Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Temperature Sensors Market Outlook
Market Context
Silicon carbide is hardening as the preferred substrate material for high-temperature sensing elements, displacing traditional ceramic bases in industrial probe assemblies. TE Connectivity leverages captive semiconductor fabrication to sustain cost leadership across thermocouple junction supply. Honeywell International Inc. anchors North American aerospace certification programs with precision RTD portfolios. Robert Bosch GmbH dominates automotive under-hood sensor integration through in-house MEMS production.
Technical Definition and Segment Structure
Temperature sensors are transducer devices that convert thermal energy into electrical signals through thermoelectric, resistive, or radiative principles, typically operating across ranges from -200°C to 1,700°C depending on sensing element composition. Their primary purpose is to enable closed-loop process control, safety interlocks, and environmental monitoring across continuous manufacturing and regulated environments. Thermocouples occupy the mature industrial core where replacement cycles and standardization compress margins, while infrared technology leads growth in non-contact food safety and semiconductor wafer inspection. Digital output segments are displacing analog architectures in HVAC and building automation as BACnet and Modbus integration becomes default.
Regulatory Framework
FDA 21 CFR Part 820 quality system requirements shape validation protocols for healthcare temperature sensors, while EPA emissions monitoring mandates under 40 CFR Part 60 dictate thermocouple accuracy classes in utility stack applications. IEC 60584 and IEC 60751 standards define tolerance grades that determine market access for international suppliers. Stakeholders must monitor convergence between functional safety standards and cybersecurity requirements as wireless temperature nodes proliferate in critical infrastructure.
Market Dynamics
Silicon carbide substrate adoption is compressing traditional ceramic probe supply chains while Taiwan and South Korean semiconductor fabs accelerate sensor procurement for process node control. This materials transition is redistributing value capture from legacy thermocouple assemblers toward compound semiconductor fabricators.
Growth Catalysts
- EU F-Gas Regulation:Mandatory refrigerant phase-down is forcing HVAC and cold chain operators across Germany, France, and Italy to replace gas-dependent monitoring with solid-state infrared and MEMS temperature nodes.
- Automotive electrification:Battery thermal management systems in electric vehicles require 8-12 discrete sensors per pack, concentrating demand in Germany's automotive sensor corridor and South Korea's EV battery belt.
- Silicon carbide substrates:SiC wafers enable sensing elements operating above 1,000°C with faster response times, opening industrial furnace and aerospace propulsion applications previously closed to platinum-rhodium thermocouples.
Market Restraints
- Platinum group metal volatility:Rhodium and palladium price swings directly impact Type B, R, and S thermocouple production economics, compressing margins for industrial probe assemblers dependent on noble metal wire.
- Taiwan semiconductor concentration:Advanced MEMS temperature sensor die fabrication concentrates in Hsinchu Science Park fabs, creating single-point vulnerability for automotive and medical supply chains.
- IEC 60584 tolerance enforcement:Stringent international standard certification timelines delay new supplier market entry by 18-24 months, freezing competitive dynamics in precision industrial segments.
Strategic Opportunities
- India industrial automation:PLI scheme incentives for semiconductor and pharmaceutical manufacturing are creating first-time demand for calibrated temperature monitoring in Ahmedabad and Bengaluru process plants.
- Wired-to-wireless conversion:ISA100 and WirelessHART temperature transmitters are penetrating oil and gas facilities where cabling costs exceed sensor hardware by 5:1 ratios.
- Cybersecurity-integrated safety:IEC 62443 certification for wireless temperature nodes is becoming a procurement filter in US critical infrastructure, rewarding early movers with FERC-regulated utility relationships.
Industry Challenges
- MEMS process engineering scarcity:Foundry-grade expertise in wafer-level vacuum packaging for absolute temperature references concentrates in South Korea and the Netherlands, constraining capacity expansion.
- FDA 21 CFR Part 820 validation timelines:Healthcare sensor qualification protocols extend development cycles by 12-18 months, delaying revenue recognition for patient monitoring and cold chain pharmaceutical applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Temperature Sensors Market |
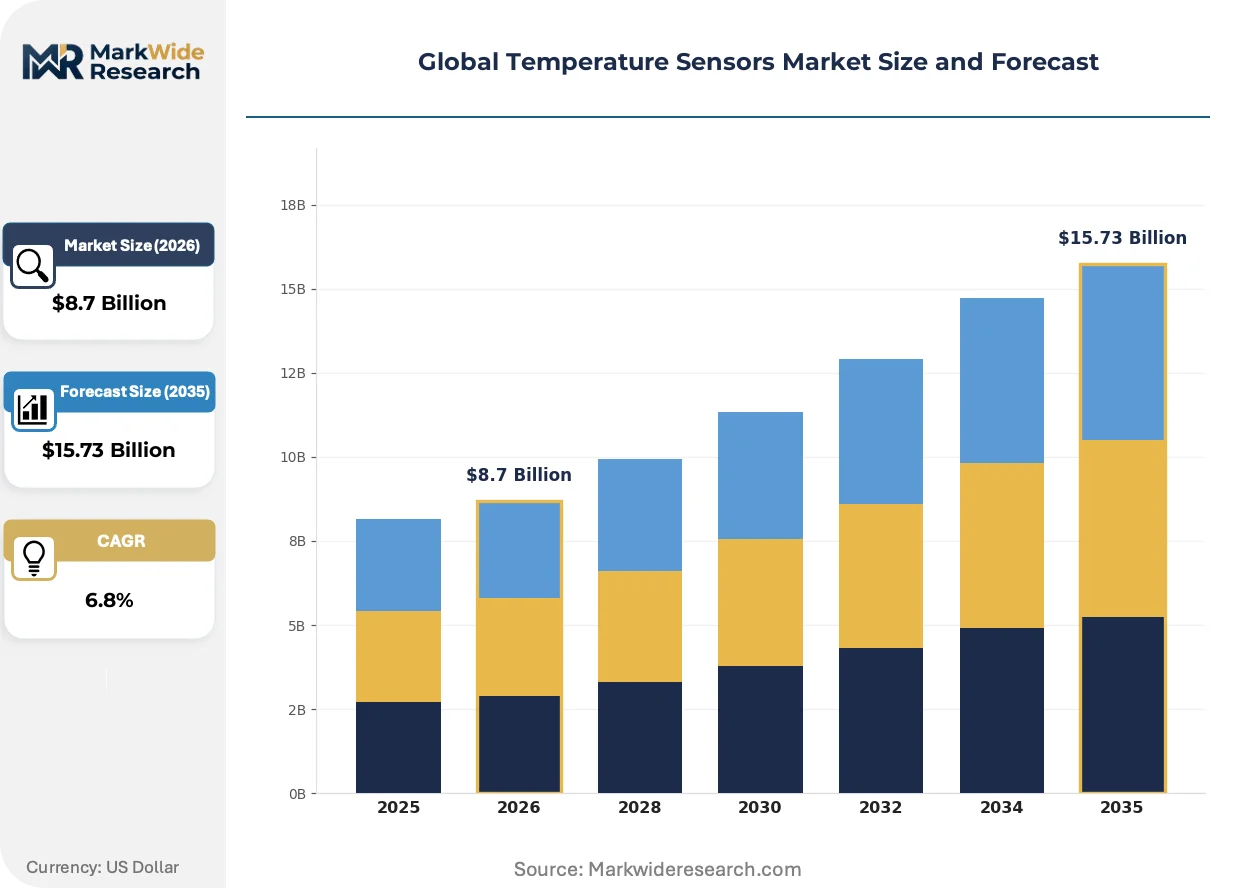
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermocouples, Thermistors, Resistance Temperature Detectors, Bimetallic Temperature Sensors Technology: Infrared, Analog, Digital, Wireless End User: Manufacturing, HVAC, Automotive, Healthcare Installation: Indoor, Outdoor, Fixed, Portable |
| Companies Covered | STMicroelectronics, TE Connectivity, Honeywell International Inc., NXP Semiconductors, Emerson Electric Co., Texas Instruments Incorporated, Robert Bosch GmbH, Microchip Technology Inc., Analog Devices, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Temperature Sensors Market Strategic Shifts
Digital output architectures are displacing analog signal conditioning across building automation and industrial control, while regulatory pressure on refrigerant systems accelerates solid-state sensing adoption. These shifts are compressing traditional component supply chains and elevating software-integrated solution providers.
Platinum thin-film RTD elements on silicon nitride substrates are expanding into aerospace turbine monitoring and semiconductor wafer processing equipment. Engine OEMs and fab tool builders specify these for ±0.1°C stability across -200°C to 850°C ranges. This precision tier is expanding into medical device sterilization validation, compressing market space for wire-wound alternatives.
Japan's METI carbon neutrality roadmap and the EU F-Gas Regulation are mandating refrigerant leak detection with temperature-correlated pressure monitoring in commercial refrigeration. Cold chain operators in Germany and France must retrofit supermarket display cases and transport containers with solid-state sensors by fixed compliance deadlines. Equipment OEMs are integrating multi-parameter nodes that combine temperature, humidity, and pressure to satisfy both regulations with single hardware platforms.
Automotive tier-one suppliers are consolidating sensor procurement under long-term partnership frameworks rather than spot purchasing. Battery pack manufacturers in South Korea and Germany now require 7-10 year supply agreements with guaranteed price corridors and joint development roadmaps. This relationship compression is marginalizing catalog distributors and elevating direct OEM engagement for MEMS temperature die suppliers.
Global Temperature Sensors Market Segmentation
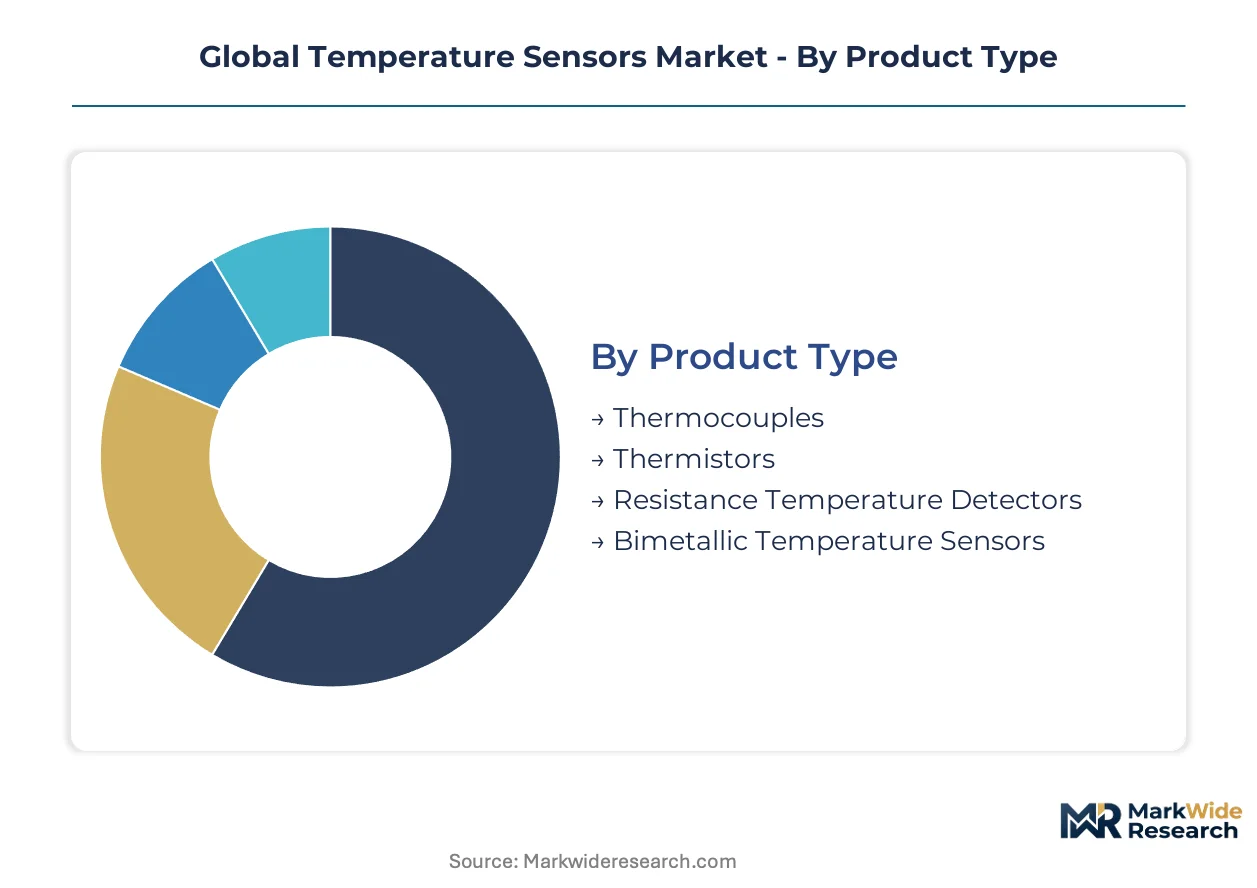
Segmentation in temperature sensors reveals divergent margin structures and integration requirements. Product type determines raw material exposure to platinum group metals, while technology choice governs software integration depth and recurring revenue potential.
Product Type:
Thermocouples dominate standalone industrial deployments where probe replacement cycles drive recurring revenue, while RTDs and thermistors embed increasingly into OEM systems with longer design-in horizons.
- Thermocouples:Junctions of dissimilar metals generate microvolt-level signals proportional to temperature differential. Demand concentrates in German steel foundries and US utility stack monitoring where EPA 40 CFR Part 60 mandates continuous emissions thermocouple accuracy. Platinum-rhodium wire price volatility compresses assembler margins.
- Resistance Temperature Detectors:Platinum thin-film or wire-wound elements offer ±0.1°C stability across -200°C to 850°C ranges. Aerospace turbine OEMs and semiconductor wafer processing equipment builders in Taiwan specify these for precision thermal profiling, displacing thermocouples in calibration-critical applications.
- Thermistors:Ceramic semiconductor oxides deliver high sensitivity in narrow temperature bands. Automotive battery management systems in South Korea embed NTC thermistors for cell-level thermal runaway detection.
- Bimetallic Temperature Sensors:Differential expansion of bonded metal strips triggers mechanical switching. HVAC safety interlocks and food service equipment in France and Italy retain these for cost-driven temperature limit applications.
Thermocouples lead volumes today; RTDs are gaining share fastest in precision-tier applications.
Technology:
Cost tier stratification separates legacy analog architectures from digital and wireless platforms commanding integration premiums.
- Infrared:Non-contact pyrometers and thermal imagers detect radiated energy from target surfaces. Food safety inspectors in Germany and semiconductor wafer inspection tools in Hsinchu fabs drive adoption where physical contact risks contamination or damage.
- Analog:Voltage or current output signals require external conditioning electronics. Mature industrial installed bases in US manufacturing plants sustain replacement demand despite digital displacement pressure.
- Digital:Integrated ADC and communication protocols enable direct BACnet or Modbus integration. Building automation retrofits across EU commercial real estate favor these for reduced wiring complexity.
- Wireless:ISA100 and WirelessHART transmitters eliminate cabling in oil and gas facilities. US FERC-regulated utilities specify IEC 62443-certified nodes for critical infrastructure monitoring.
Analog leads installed base today; wireless is expanding most quickly in greenfield industrial deployments.
End User:
Application maturity determines specification rigor, with healthcare and automotive demanding validated supply chains versus manufacturing's price-sensitive replacement cycles.
- Manufacturing:Process control in chemical reactors, metal treatment, and packaging lines. Indian pharmaceutical plants under PLI scheme incentives are creating first-time demand for calibrated temperature monitoring in Ahmedabad and Bengaluru.
- HVAC:Climate control and refrigerant system monitoring. EU F-Gas Regulation mandates solid-state sensor retrofits in German and French supermarket display cases by fixed compliance deadlines.
- Automotive:Battery thermal management and powertrain monitoring. Electric vehicle battery packs require 8-12 discrete sensors per pack, concentrating procurement in Germany's automotive sensor corridor.
- Healthcare:Patient monitoring, sterilization validation, and pharmaceutical cold chain. FDA 21 CFR Part 820 quality system requirements extend development cycles by 12-18 months for qualified suppliers.
Manufacturing leads volume today; automotive is climbing the fastest on electrification-driven sensor proliferation.
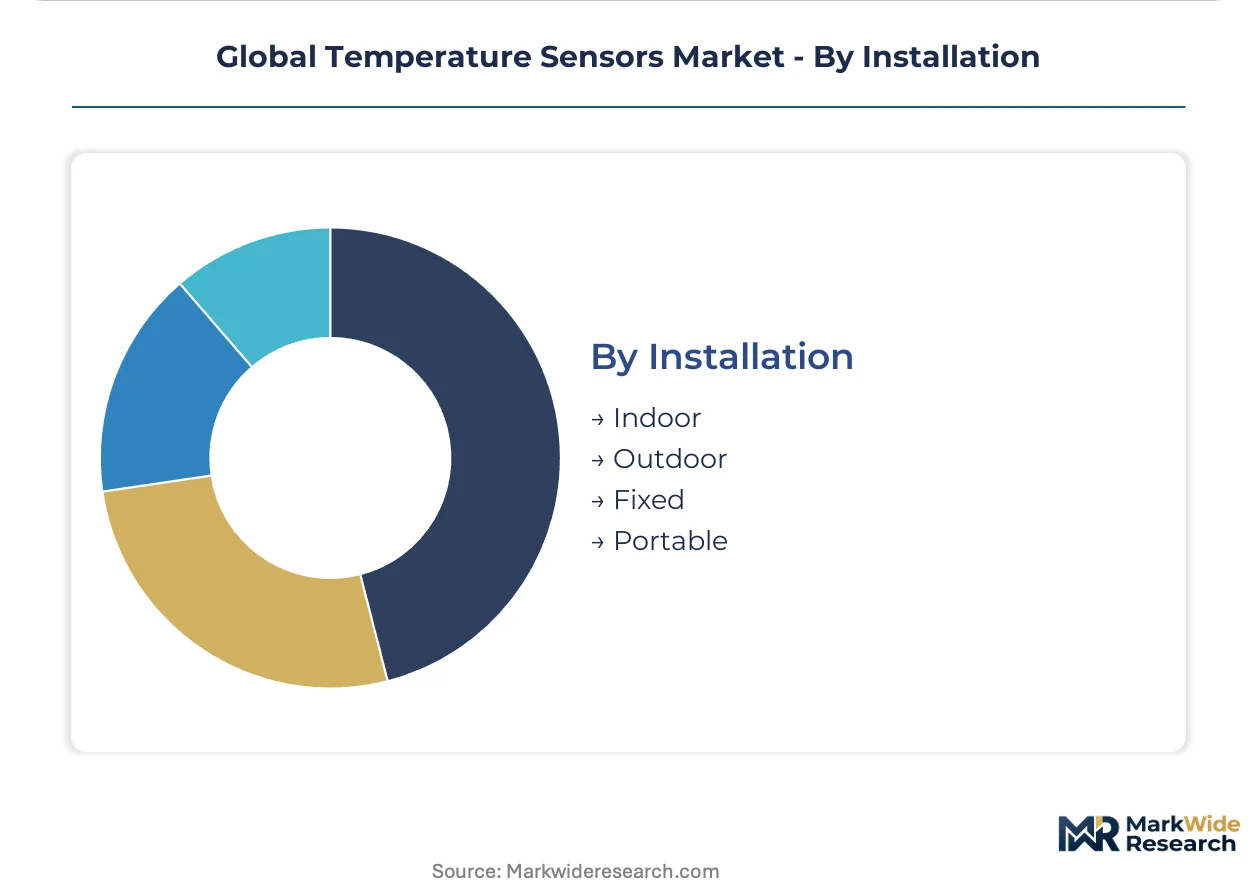
Installation:
Volume scale separates fixed infrastructure deployments from portable instrumentation serving maintenance and field service applications.
- Indoor:Controlled environment monitoring in data centers, laboratories, and commercial buildings. BACnet integration requirements favor digital output architectures.
- Outdoor:Weather-exposed applications in energy infrastructure and transportation. Housings must meet IP ratings for moisture and particulate ingress.
- Fixed:Permanent mounting in process equipment and building systems. Represents the volume base across all end-use segments.
- Portable:Handheld calibrators and spot-check instruments for field service. Maintenance teams in oil and gas facilities deploy these for verification of fixed sensor accuracy.
Fixed installation dominates volume today; portable is expanding fastest in predictive maintenance programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park anchors the most concentrated advanced sensor fabrication cluster, with Taiwan's semiconductor foundries supplying precision MEMS die for automotive and medical temperature monitoring systems worldwide.
United States
FERC-regulated utilities drive demand for IEC 62443-certified wireless temperature nodes in critical power infrastructure. EPA 40 CFR Part 60 mandates continuous emissions monitoring with thermocouple accuracy classes in utility stack applications. Houston's oil and gas facilities deploy ISA100 transmitters where cabling costs exceed hardware by five-to-one ratios.
Germany
Automotive battery pack manufacturers require eight-to-twelve discrete sensors per electric vehicle, concentrating procurement in the country's automotive sensor corridor. EU F-Gas Regulation mandates solid-state sensor retrofits in supermarket refrigeration systems by fixed compliance deadlines. Stuttgart's tier-one suppliers now demand seven-to-ten year supply agreements with guaranteed price corridors.
South Korea
EV battery belt manufacturers embed NTC thermistors for cell-level thermal runaway detection in high-voltage packs. The country's national industrial regulator enforces stringent functional safety standards for automotive sensor qualification. Foundry-grade expertise in wafer-level vacuum packaging concentrates in Seoul Capital Area fabs, constraining capacity expansion for absolute temperature references.
Japan
METI's carbon neutrality roadmap mandates refrigerant leak detection with temperature-correlated pressure monitoring in commercial refrigeration systems. Semiconductor wafer processing equipment builders specify platinum thin-film RTD elements for precision thermal profiling. Nagoya's industrial automation sector drives replacement demand for calibrated temperature monitoring in continuous manufacturing.
India
PLI scheme incentives for semiconductor and pharmaceutical manufacturing create first-time demand for calibrated process control sensors. The national standards body enforces certification timelines that delay new supplier market entry. Ahmedabad and Bengaluru process plants are retrofitting with closed-loop temperature monitoring for pharmaceutical manufacturing compliance.
Global Temperature Sensors Market Competitive Environment
Global majors compete with regional champions across compound semiconductor fabrication and precision assembly tiers. The market structures around three distinct player categories: integrated device manufacturers with captive MEMS foundries, specialized sensor assemblers dependent on noble metal wire supply, and building automation solution providers bundling digital output architectures. Consolidation pressures concentrate in automotive tier-one supply chains, while fragmentation persists in industrial probe replacement markets. Strategic moves center on backward integration into silicon carbide substrate supply and long-term partnership frameworks displacing spot purchasing.
Within the integrated device manufacturer tier, STMicroelectronics and Texas Instruments Incorporated exemplify scale-driven compound semiconductor fabrication. TE Connectivity occupies a position bridging precision assembly with semiconductor-level manufacturing integration. Robert Bosch GmbH anchors automotive under-hood sensor supply through in-house MEMS production capabilities. These three represent divergent archetypes: pure-play semiconductor fabrication, hybrid assembly-with-fabrication, and vertically integrated automotive systems supply.
| Leading Market Players |
|---|
| STMicroelectronics |
| TE Connectivity |
| Honeywell International Inc. |
| NXP Semiconductors |
| Emerson Electric Co. |
| Texas Instruments Incorporated |
| Robert Bosch GmbH |
| Microchip Technology Inc. |
| Analog Devices, Inc. |
| Others |
Value Chain & Pricing Dynamics
Rhodium and palladium price indices cascade through thermocouple supply chains into three distinct pricing tiers: precision aerospace RTDs commanding stability premiums, automotive MEMS die sold through long-term contract corridors, and industrial probe replacements competing on spot-market metal economics. Platinum group metal volatility compresses assembler margins while silicon carbide substrate scarcity elevates compound semiconductor fabricators into price-setting positions.
Pricing Analysis
Input-cost pass-through from noble metal wire markets governs thermocouple pricing, with Type B, R, and S junctions tracking London Metal Exchange rhodium quotations on 30-60 day lags. Three-tier pricing structure across precision calibration, industrial standard, and economy replacement levels separates aerospace turbine OEMs from German steel foundries and HVAC maintenance contractors. Pricing pressure stems from automotive tier-one consolidation toward seven-to-ten year supply agreements with fixed price corridors, squeezing spot-market distributors. Healthcare and aerospace buyers exhibit lowest price sensitivity due to FDA 21 CFR Part 820 and FAA certification lock-in, while commercial HVAC retrofitters drive hardest bargain on solid-state sensor retrofits.
Supply Chain Analysis
Wafer-level vacuum packaging expertise scarcity in Seoul Capital Area and Eindhoven constrains absolute temperature reference capacity expansion for automotive and medical grade MEMS die. Taiwan, South Korea, and Germany anchor precision fabrication, with Hsinchu Science Park fabs supplying MEMS temperature die and Stuttgart's automotive sensor corridor consuming pack-integrated thermistors. Raw material dependencies center on platinum-rhodium wire for thermocouples, silicon carbide wafers for high-temperature sensing elements, and ceramic substrates for industrial probe assemblies. Single-source vulnerability concentrates in Hsinchu for advanced MEMS die fabrication, threatening automotive and medical supply continuity. Distribution runs through direct OEM engagement for tier-one automotive and aerospace contracts, while catalog distributors serve industrial replacement markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
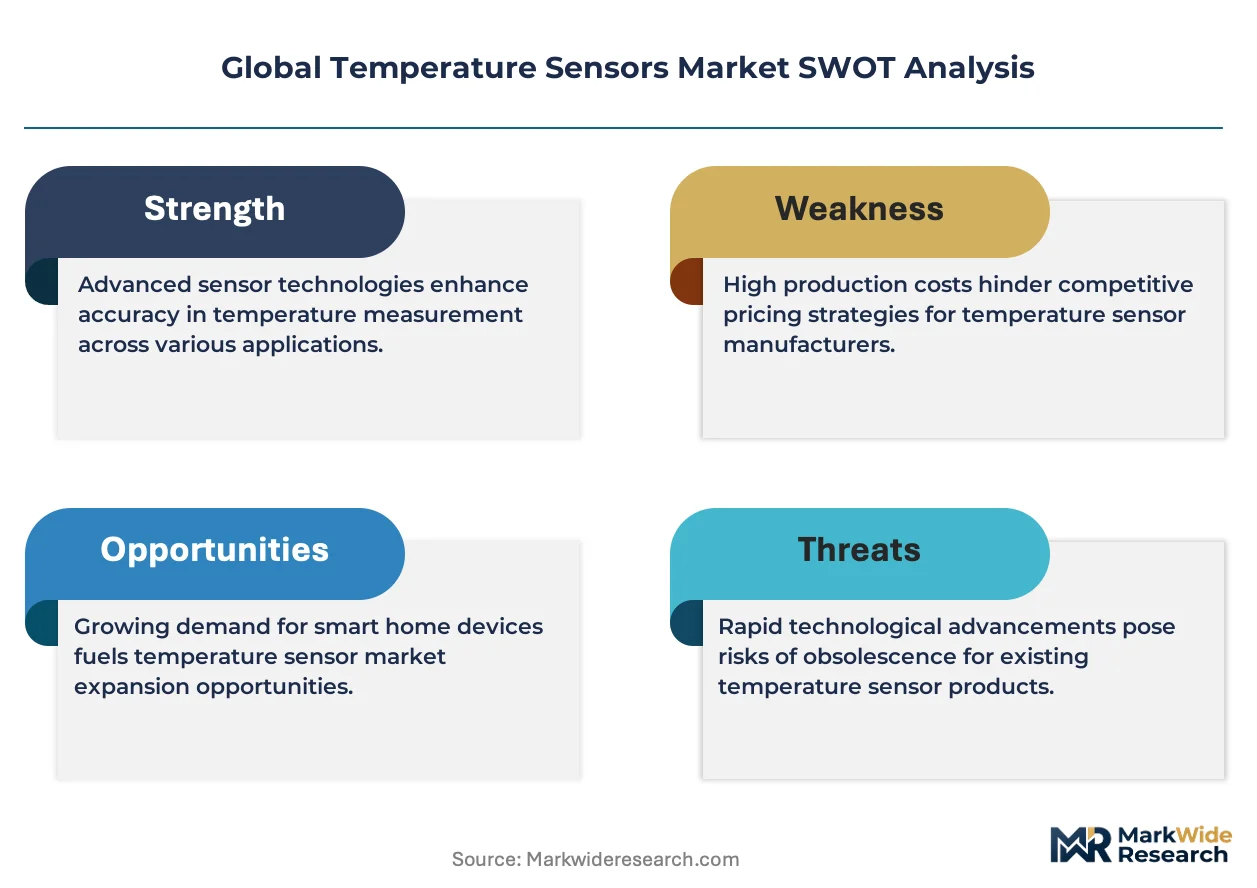
This market operates as a regulatory compounder where EU F-Gas Regulation mandates on refrigerant phase-downs are forcing solid-state sensor retrofits across German and French cold chain infrastructure, embedding demand visibility into compliance deadlines.
For Market Incumbents: Cement captive silicon carbide substrate supply through backward integration or long-term offtake agreements with compound semiconductor foundries, insulating precision RTD production from ceramic probe supply chain compression. Defend automotive tier-one relationships by embedding joint development roadmaps into battery thermal management system design cycles, countering emerging MEMS specialists from South Korea seeking platform standardization wins. For New Entrants and Emerging Players: Wireless temperature transmitters with ISA100 and WirelessHART protocols offer the most penetrable wedge for oil and gas facilities where cabling costs dominate total installed cost. Target US FERC-regulated utilities with IEC 62443-certified nodes as cybersecurity-integrated safety becomes procurement-filter mandatory. Pursue hospital system partnerships for patient monitoring applications where FDA validation timelines deter incumbent expansion. For Investors and Strategic Acquirers: Asymmetric upside sits with compound semiconductor fabricators possessing wafer-level vacuum packaging capability for absolute temperature references, a capacity-constrained tier with automotive and medical demand tailwinds. Five-to-ten year viability favors specialists with proven IEC 60584 and IEC 60751 certification timelines already navigated. Monitor EU F-Gas Regulation compliance deadline acceleration as inflection signal for solid-state sensor retrofit demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Substrates | Captive silicon carbide wafer supply secures high-temperature sensing element cost leadership against platinum-rhodium volatility. |
| Long-term Supply Agreement Standardization | Seven-to-ten year automotive contracts with price corridors lock in EV battery pack sensor volumes through electrification ramp. |
| IEC 62443 Certification Investment | Cybersecurity-integrated wireless nodes unlock FERC-regulated utility procurement filters in critical infrastructure monitoring. |
| Joint Development Roadmap Embedding | Early-stage collaboration with Stuttgart tier-one suppliers secures platform design-in for battery thermal management systems. |
| Healthcare Validation Pipeline Expansion | FDA 21 CFR Part 820 qualification capacity extends development cycle coverage for patient monitoring and pharmaceutical cold chain. |
Study Parameters
Multiple input streams — primary interviews with MEMS process engineers, automotive tier-one procurement directors, and pharmaceutical plant calibration specialists; secondary validation through IEC standard documentation, EPA 40 CFR Part 60 enforcement records, and EU F-Gas Regulation compliance filings; plus customs data on platinum-rhodium wire trade flows — were reconciled through bottom-up and top-down triangulation. Semiconductor foundry capacity disclosures, automotive production schedules, and hospital procurement database trends provided demand-side anchors.
Data-stream reconciliation across product type, technology architecture, end-use vertical, and geographic production cluster dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume build-ups and value-per-unit trajectories incorporated silicon carbide substrate adoption curves, automotive electrification sensor proliferation rates, and regulatory compliance deadline effects as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to platinum group metal price volatility, Taiwan semiconductor concentration disruptions, and IEC standard revision timelines. Material deviation in EU F-Gas Regulation enforcement intensity or automotive battery pack sensor count specifications warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Acoustic Breathing Sensor Market
Sensors and Controls
Global Mid-And-High-Level Precision GPS Receiver Market
Sensors and Controls
Global Hall Effect Current Sensor Market
Sensors and Controls
Global Digital Temperature and Humidity Sensor Market
Sensors and Controls
Gimbal Market
Sensors and Controls
APAC Proximity Sensors Market
Sensors and Controls
Global Smartphone Sensors Market
Sensors and Controls
PID Controller Market
Sensors and Controls
Global Space Sensors and Actuators Market
Sensors and Controls
ECG Sensor Market
Sensors and Controls
North America Temperature Sensor Market
Sensors and Controls
Ultrasonic Air in Line Sensor Market
Sensors and Controls
Timing Device Market
Sensors and Controls
Differential Pressure Sensor Market
Sensors and Controls
Biopotential Sensor Market
Sensors and Controls
Air Particle Monitor System Market