
 Pneumonia Treatment Market | 2026-2036
Pneumonia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Pneumonia Treatment Market Outlook
The divergence between premium branded antibiotics and commodity generic formulations is realigning procurement strategies across health systems. Pfizer Inc. leverages its vaccine portfolio to anchor premium positioning in pneumococcal prevention. Teva Pharmaceutical Industries Ltd. competes on cost-engineered oral generics that sustain volume share in emerging markets. Abbott Laboratories differentiates through point-of-care diagnostic bundling that extends its treatment ecosystem reach.
Pneumonia treatment encompasses pharmaceutical and biological interventions designed to eliminate infectious pathogens, modulate inflammatory response, and prevent disease recurrence in affected lung tissue. Antibiotics targeting Streptococcus pneumoniae and atypical organisms remain the backbone of community-acquired cases, with intravenous formulations reserved for severe hypoxic patients requiring hospitalization. Vaccines command the strongest margin pools due to multi-dose pediatric schedules and adult revaccination protocols, while oral antibiotics dominate volume throughput across clinic and home care settings. Hospital-acquired pneumonia therapies face escalating formulary scrutiny as resistance profiles complicate empiric selection.
FDA antimicrobial resistance frameworks and EMA's PRAB measures are tightening clinical evidence requirements for new antibiotic approvals, directly shaping R&D investment allocation. WHO Essential Medicines List revisions and national stewardship mandates in India and China are restricting broad-spectrum agent use to culture-confirmed cases. Stakeholders must monitor regulatory divergence between accelerated-access pathways for novel mechanisms and restricted-use policies for legacy agents.
Market Dynamics
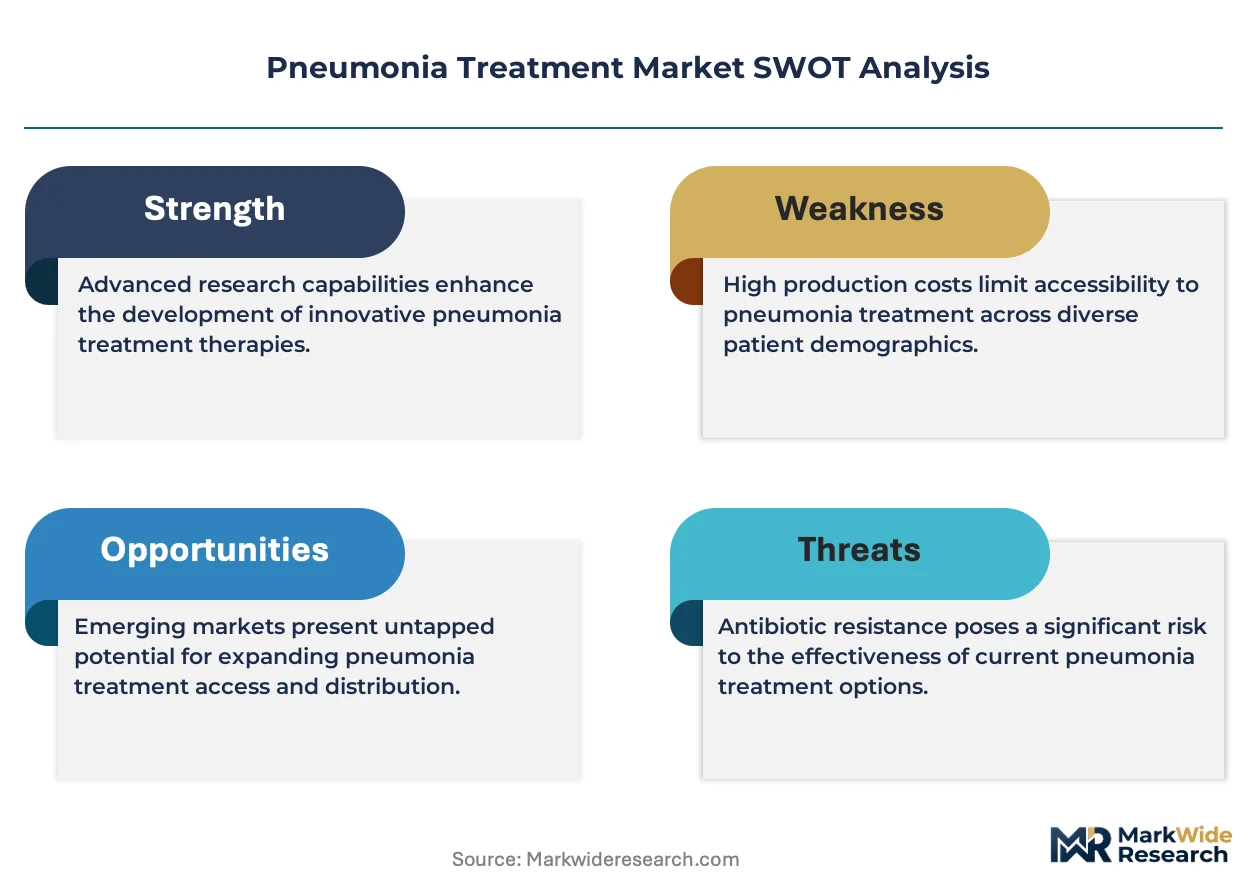
Antimicrobial resistance surveillance networks are compressing the commercial lifespan of legacy antibiotics, forcing manufacturers to accelerate novel mechanism discovery while hospital formularies impose tiered access restrictions based on resistance profiles.
Growth Catalysts
- FDA's LPAD Pathway:The Limited Population Antibacterial Drug framework accelerates approval timelines for pathogens with documented resistance gaps, incentivizing developers to target MDR Klebsiella and Acinetobacter strains.
- India's AMR National Action Plan:Central government funding for diagnostic infrastructure at district hospitals is expanding culture-guided therapy penetration beyond tertiary centers into secondary care networks.
- mRNA Vaccine Platforms:Self-amplifying RNA technologies are reducing pneumococcal conjugate production timelines from months to weeks, enabling rapid serotype replacement responses.
Market Restraints
- API Supply Concentration:Over 60% of oral amoxicillin active pharmaceutical ingredient originates from Chinese manufacturers, creating single-source vulnerability during environmental compliance shutdowns.
- Clinical Trial Cost Escalation:Non-inferiority study designs for hospital-acquired pneumonia require 1,000+ patient enrollment due to mortality endpoint variability, inflating Phase III budgets beyond $200 million.
- Phage Therapy Substitution:Bacteriophage cocktails for Pseudomonas aeruginosa lung infections are advancing through compassionate-use programs in Georgia and Poland, threatening polymyxin revenue pools.
Strategic Opportunities
- Sub-Saharan Africa Immunization Gaps:Gavi funding transitions in Nigeria and Ethiopia are creating procurement windows for pentavalent and pneumococcal vaccines at price points above traditional UNICEF tenders.
- Point-of-Care CRISPR Diagnostics:SHERLOCK and DETECTR platforms detecting Streptococcus pneumoniae in 30 minutes are enabling same-day targeted therapy initiation in urgent care settings.
- China's Essential Medicines List Expansion:NMPA inclusion of novel cephalosporin-beta-lactamase inhibitor combinations triggers provincial hospital mandatory procurement quotas.
Industry Challenges
- Microbiology Workforce Shortage:Clinical laboratory scientist training programs in the United States graduated 12% fewer candidates in 2023 than 2019, delaying culture turnaround times.
- Legacy EHR Integration:Antibiotic stewardship decision-support modules require 18-24 month implementation cycles to interface with Cerner and Epic installations without disrupting clinical workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pneumonia Treatment Market |
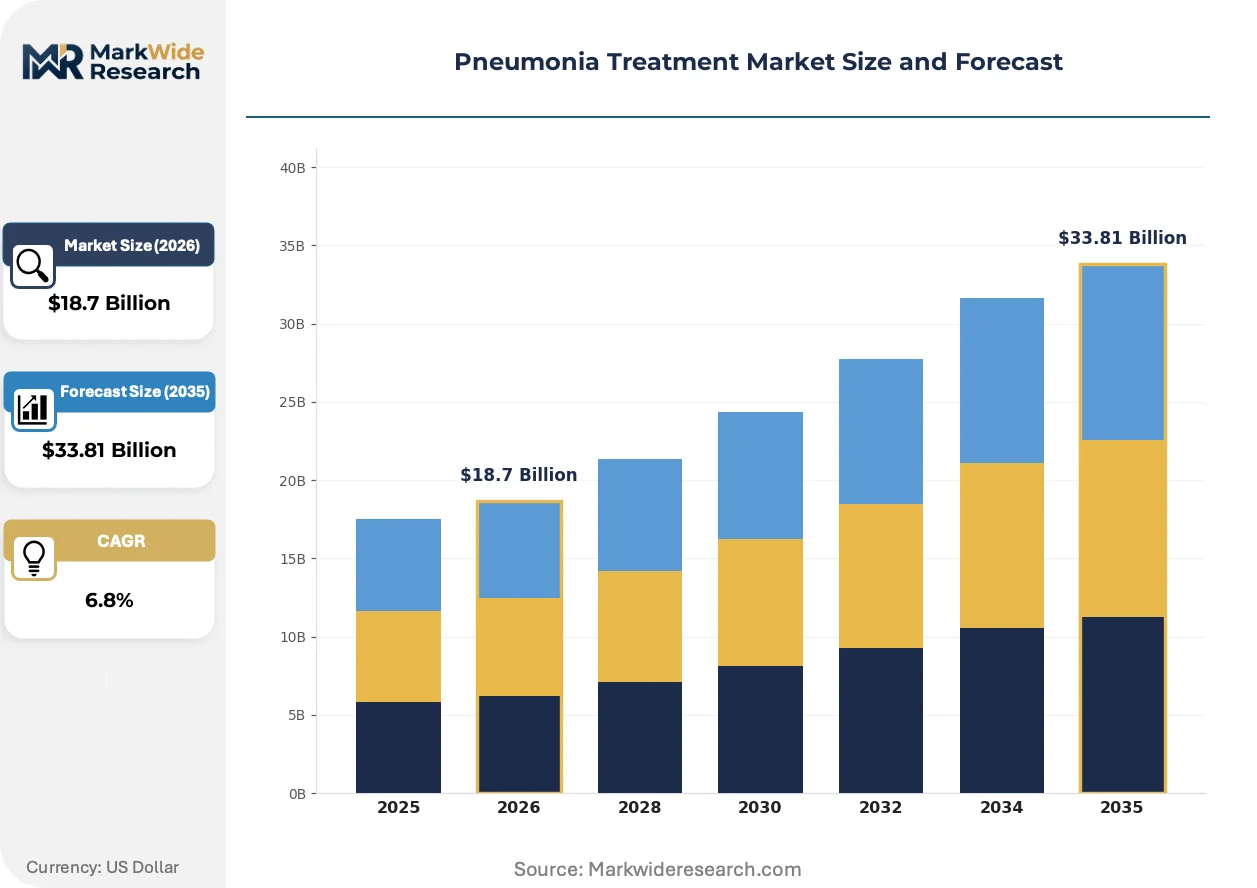
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antibiotics, Antivirals, Corticosteroids, Vaccines End User: Hospitals, Clinics, Home Care, Long-term Care Facilities Administration Route: Oral, Intravenous, Inhalation, Intramuscular Therapy Area: Community-acquired Pneumonia, Hospital-acquired Pneumonia, Ventilator-associated Pneumonia, Aspiration Pneumonia |
| Companies Covered | Pfizer Inc., Teva Pharmaceutical Industries Ltd., Abbott Laboratories, Baxter International Inc., Viatris, AstraZeneca, Novartis AG, Sanofi, Merck & Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pneumonia Treatment Market Strategic Shifts
Artificial intelligence is compressing antibiotic discovery timelines while regulatory frameworks fragment across jurisdictions, creating divergent commercialization pathways for novel agents.
Inhaled dry-powder formulations of ciprofloxacin and amikacin are achieving lung epithelial lining fluid concentrations tenfold higher than intravenous equivalents. Cystic fibrosis centers in Germany and the United States are adopting these platforms for chronic Pseudomonas suppression. This delivery modality is electrifying the chronic infection maintenance segment by enabling outpatient administration that displaces lengthy hospital infusions.
EMA's PRAB (Priority Antimicrobials) designation now mandates environmental risk assessments for manufacturing discharge, extending approval timelines by 8-12 months for novel agents. Pharmaceutical manufacturers are retrofitting API synthesis facilities with advanced oxidation processes to meet predicted no-effect concentration limits. The hospital-acquired pneumonia pipeline faces the steepest compliance burden as sponsors navigate divergent FDA and EMA ecotoxicology expectations.
Hospital systems are unbundling antibiotic stewardship from infectious disease department budgets and establishing standalone quality metrics tied to executive compensation. United States health systems exceeding CMS SEP-1 bundle compliance thresholds now capture 2% Medicare reimbursement adjustments. This behavioral shift concentrates formulary influence within pharmacy and therapeutics committees, compressing physician autonomy in empiric selection.
Pneumonia Treatment Market Segmentation
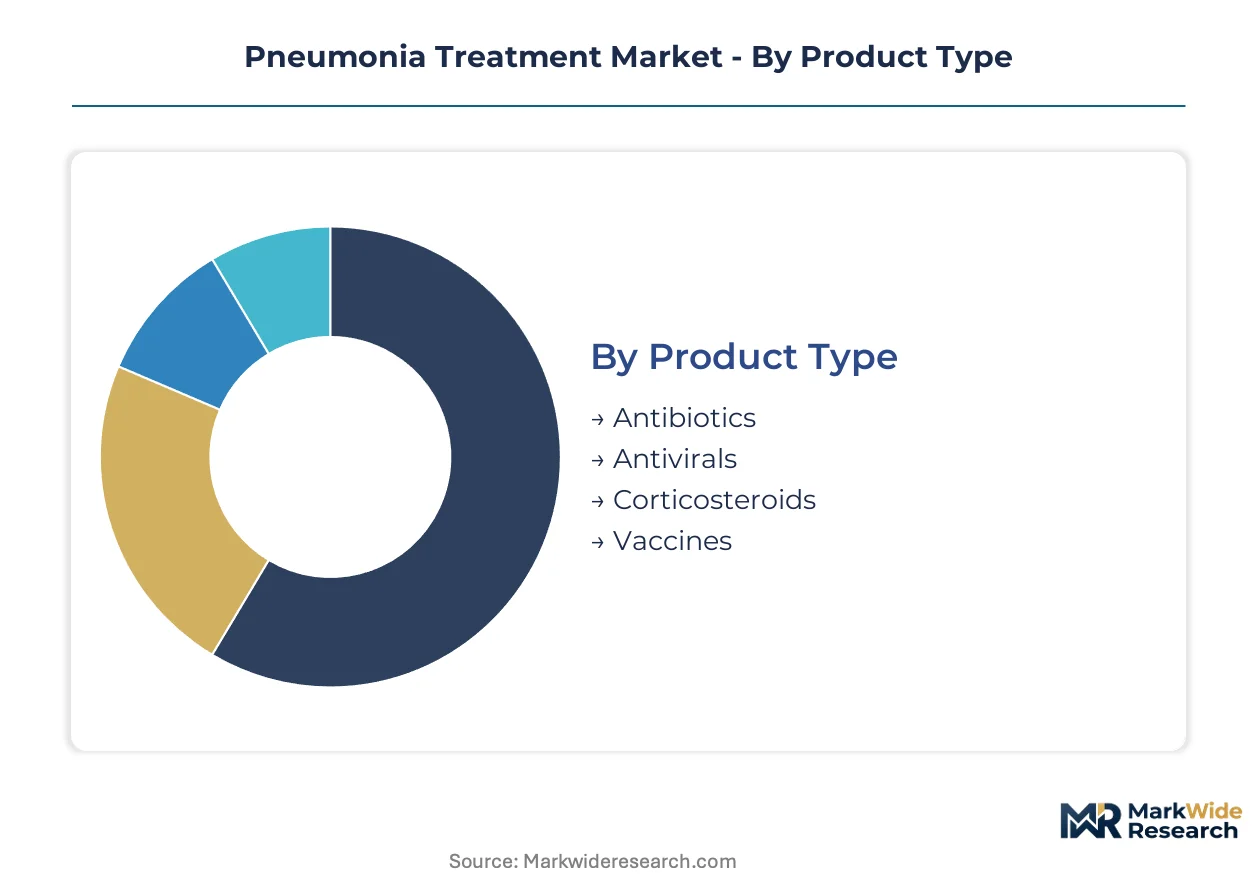
Pneumonia treatment procurement varies sharply across product categories, with vaccines and novel antibiotics facing distinct regulatory pathways while generic formulations compete on tender pricing. Understanding segment-specific approval burdens and demand concentration points enables manufacturers to align R&D investment with accessible revenue pools.
Product Type:
EMA's PRAB designation and FDA's LPAD pathway create divergent certification timelines: novel mechanisms require environmental risk assessments extending approval by 8-12 months, while legacy generics navigate abbreviated ANDA routes.
- Antibiotics:Beta-lactam, macrolide, and fluoroquinolone formulations targeting Streptococcus pneumoniae and atypical pathogens. Oral amoxicillin dominates volume in India's district hospital networks where CDSCO's Essential Medicines List mandates procurement quotas. Hospital formularies impose tiered access restrictions based on resistance surveillance data.
- Vaccines:Pneumococcal conjugate and polysaccharide preparations commanding the strongest margin pools through multi-dose pediatric schedules and adult revaccination protocols. Self-amplifying mRNA platforms are compressing production timelines from months to weeks, enabling rapid serotype replacement responses in United States and China immunization programs.
- Antivirals:Oseltamivir and baloxavir formulations for influenza-associated pneumonia prophylaxis and treatment.
- Corticosteroids:Adjunctive dexamethasone and methylprednisolone therapies modulating inflammatory response in severe hypoxic cases.
Leading the category by volume: Antibiotics. Growing fastest: Vaccines.
End User:
Reimbursement structures and stewardship mandates fragment demand across settings, with United States health systems capturing 2% Medicare adjustments for SEP-1 bundle compliance while India's district hospitals expand culture-guided therapy penetration.
- Hospitals:Tertiary and secondary acute care facilities managing severe hypoxic patients requiring intravenous formulations and oxygen support. Antibiotic stewardship decision-support modules require 18-24 month EHR integration cycles with Cerner and Epic installations.
- Clinics:Outpatient and urgent care settings where point-of-care CRISPR diagnostics enable same-day targeted therapy initiation.
- Home Care:Post-discharge oral antibiotic completion and chronic infection maintenance through inhaled dry-powder platforms.
- Long-term Care Facilities:Skilled nursing environments where aspiration pneumonia incidence drives prophylactic protocol development.
Volume concentrates in Hospitals. Steepest expansion trajectory: Home Care.
Administration Route:
Delivery modality selection directly shapes manufacturing investment, with inhaled formulations requiring specialized particle engineering facilities while oral generics compete on API cost engineering.
- Oral:Tablet and suspension formulations dominating outpatient throughput across clinic and home care settings. Over 60% of amoxicillin API originates from Chinese manufacturers, creating single-source vulnerability during environmental compliance shutdowns.
- Intravenous:Hospital-reserved formulations for severe hypoxic patients, with non-inferiority study designs requiring 1,000+ patient enrollment and Phase III budgets exceeding $200 million.
- Inhalation:Dry-powder ciprofloxacin and amikacin achieving lung epithelial lining fluid concentrations tenfold higher than intravenous equivalents.
- Intramuscular:Vaccine and depot antibiotic delivery in pediatric and adult immunization protocols.
Oral routes dominate volume. Inhalation is climbing the fastest.
Therapy Area:
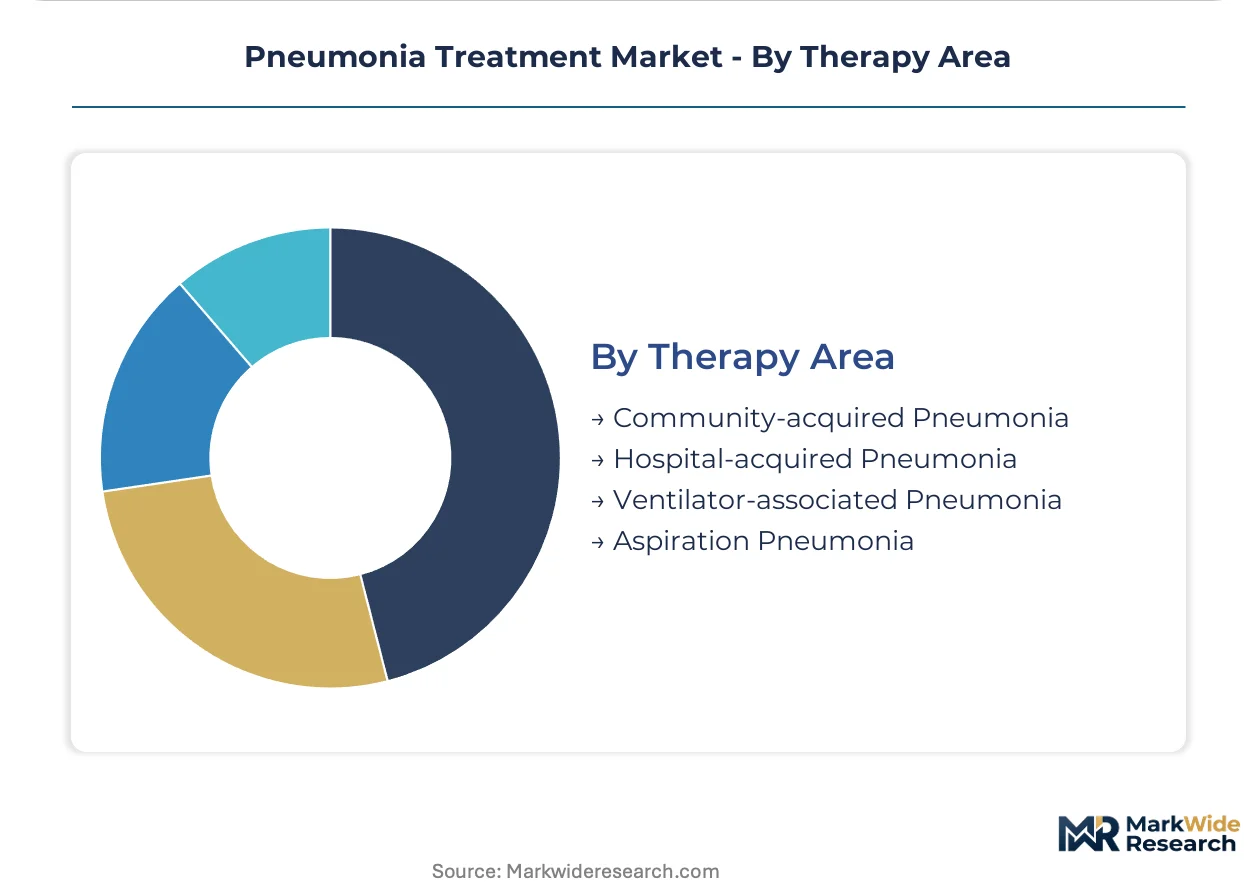
Resistance surveillance networks compress commercial lifespans differentially across settings, with hospital-acquired strains facing the steepest formulary scrutiny as MDR Klebsiella and Acinetobacter profiles complicate empiric selection.
- Community-acquired Pneumonia:Outpatient-dominant infections where Streptococcus pneumoniae remains the predominant pathogen and oral antibiotics sustain volume share.
- Hospital-acquired Pneumonia:Nosocomial infections occurring 48+ hours after admission, facing escalating formulary scrutiny and restricted-use policies for broad-spectrum agents pending culture confirmation.
- Ventilator-associated Pneumonia:ICU-acquired infections in mechanically ventilated patients where polymyxin revenue pools face substitution threat from advancing bacteriophage cocktails.
- Aspiration Pneumonia:Long-term care and neurologically compromised patient populations requiring distinct prophylactic and therapeutic protocols.
Community-acquired Pneumonia leads by volume. Ventilator-associated Pneumonia is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Philadelphia's pharmaceutical corridor anchors vaccine production scale-up for pneumococcal conjugate programs serving North American immunization schedules. Manufacturing investments cluster along Interstate 95 between Pennsylvania and New Jersey.
United States
FDA's LPAD pathway accelerates novel antibacterial approvals targeting resistant Klebsiella and Acinetobacter strains. Medicare SEP-1 bundle compliance thresholds now tie 2% reimbursement adjustments to antibiotic stewardship performance. Boston's biotech cluster concentrates mRNA vaccine platform development for rapid serotype replacement response.
Germany
EMA's PRAB designation mandates environmental risk assessments extending novel agent approval timelines by 8-12 months. Cystic fibrosis centers in Munich and Heidelberg adopt inhaled dry-powder ciprofloxacin for chronic Pseudomonas suppression. The country's national pharmaceutical regulator tightens manufacturing discharge standards under EU Green Deal implementation.
India
CDSCO's Essential Medicines List mandates procurement quotas for oral amoxicillin across district hospital networks. Central government AMR National Action Plan expands diagnostic infrastructure into secondary care beyond tertiary centers. Hyderabad's API manufacturing belt concentrates cost-engineered generic production for export markets.
China
NMPA inclusion of novel cephalosporin-beta-lactamase inhibitor combinations triggers provincial hospital mandatory procurement quotas. National immunization budgets scale pneumococcal conjugate coverage into county-level healthcare networks. Shanghai's biopharma zone concentrates self-amplifying RNA technology transfer partnerships.
Brazil
ANVISA streamlines approval pathways for pentavalent and pneumococcal vaccines as Gavi funding transitions create procurement windows above traditional UNICEF tenders. São Paulo's research hospitals pilot point-of-care CRISPR diagnostics for same-day Streptococcus pneumoniae detection. The country's national immunization program expands adult revaccination protocols.
Pneumonia Treatment Market Competitive Environment
Capital-heavy vaccine manufacturers compete with asset-light generic formulators across divergent margin structures. The market consolidates around three strategic tiers: premium innovators commanding pediatric schedule anchorage, mid-scale differentiated players bundling diagnostics with therapy, and volume-driven cost engineers capturing tender markets. Portfolio diversification into mRNA platforms and stewardship software represents the dominant competitive maneuver, followed by backward integration into API synthesis to mitigate Chinese supply concentration.
Among diversified pharmaceutical conglomerates, Pfizer Inc. and AstraZeneca exemplify premium-tier positioning through vaccine portfolio anchorage, while Teva Pharmaceutical Industries Ltd. occupies the cost-engineered generic tier. Abbott Laboratories represents the diagnostic-therapy bundling archetype. These three companies illustrate the structural divergence between margin-driven prevention platforms and volume-dependent acute care formulations.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Abbott Laboratories |
| Baxter International Inc. |
| Viatris |
| AstraZeneca |
| Novartis AG |
| Sanofi |
| Merck & Co., Inc. |
| Others |
Value Chain & Pricing Dynamics
Backward integration into active pharmaceutical ingredient synthesis anchors both supply security and margin defense for pneumonia treatment manufacturers navigating Chinese source concentration. Captive production of beta-lactam intermediates insulates formulators from environmental compliance shutdowns while preserving pricing power in tender markets where amoxicillin procurement quotas dominate district hospital purchasing.
Pricing Analysis
Outcome-linked reimbursement anchors value-based pricing for novel antibiotics qualifying under FDA's LPAD pathway, with Medicare SEP-1 bundle compliance thresholds capturing 2% reimbursement adjustments for stewardship performance. Three-tier pricing structure across premium, standard, and economy levels separates patented mRNA vaccines from branded hospital formulations and commodity oral generics. Cost compression in the generic tier intensifies because Indian and Chinese manufacturers compete on API engineering margins. Government procurement bodies in emerging markets exhibit highest price sensitivity, while United States hospital systems accepting value-based contracts demonstrate lowest sensitivity due to bundled reimbursement capture.
Supply Chain Analysis
Cold chain logistics costs for pneumococcal conjugate vaccines constrain distribution reach into sub-Saharan African markets where Gavi funding transitions create procurement windows. API manufacturing concentrates in China, India, and Italy, with oral amoxicillin synthesis drawing from Chinese petrochemical feedstocks and Indian fermentation capacity. Single-source vulnerability from environmental compliance shutdowns at Yangtze River Delta facilities threatens global oral antibiotic availability. Distribution runs through government immunization programs for vaccines and tender-based hospital procurement for antibiotics, with point-of-care diagnostic bundling emerging as an alternative channel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antimicrobial resistance surveillance networks are compressing commercial lifespans of legacy antibiotics, forcing consolidation among manufacturers lacking novel mechanism pipelines or captive API supply.
For Market Incumbents: To counter bacteriophage therapy substitution threatening polymyxin revenue pools, incumbents should accelerate self-amplifying mRNA vaccine platform investments and secure backward integration into beta-lactam intermediate synthesis. Captive API production insulates margin structures from Chinese environmental compliance volatility while pediatric schedule anchorage preserves pricing power against emerging generic entrants. For New Entrants and Emerging Players: Diagnostic-therapy bundling partnerships with urgent care networks offer the most penetrable entry vector, particularly for point-of-care CRISPR platforms enabling same-day Streptococcus pneumoniae detection. White-space concentrates in Sub-Saharan African immunization gaps where Gavi funding transitions create procurement windows above traditional UNICEF tenders. A go-to-market strategy centered on provincial hospital mandatory procurement quotas in China leverages NMPA Essential Medicines List inclusion triggers. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-scale differentiated players with diagnostic-therapy bundling capabilities and established stewardship software integration. Long-term viability across the projection horizon favors manufacturers with mRNA platform optionality and captive API synthesis rather than pure-play generic formulators facing margin compression. The signal to watch is FDA LPAD pathway approval velocity for novel mechanisms targeting MDR Klebsiella and Acinetobacter, which indicates R&D productivity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Self-Amplifying mRNA Platform Investment | Compresses pneumococcal conjugate production timelines from months to weeks for serotype replacement response. |
| Captive API Synthesis Buildout | Insulates oral antibiotic margins from Chinese environmental compliance shutdowns at Yangtze River facilities. |
| Point-of-Care Diagnostic Bundling | Extends treatment ecosystem reach into urgent care settings with 30-minute Streptococcus pneumoniae detection. |
| Antibiotic Stewardship Software Integration | Captures 2% Medicare SEP-1 bundle reimbursement adjustments through EHR decision-support modules. |
| EMA PRAB Environmental Risk Assessment Preparation | Preempts 8-12 month approval timeline extensions through advanced oxidation process retrofitting. |
Study Parameters
FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone, supplemented by formulary database audits and CMS Medicare reimbursement records. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers validated quantitative assumptions. Bottom-up and top-down triangulation reconciled patient population estimates with manufacturer-reported volume data across administration routes and therapy areas.
Bottom-up modeling anchored patient flow analysis through diagnosis, treatment initiation, and completion rates by setting and severity. Segmentation dimensions included product type, end user, administration route, therapy area, and regional regulatory cluster. CAGRs derived from log-linear trend fitting across the analysis window, with scenario weighting for FDA LPAD pathway acceleration and EMA PRAB environmental compliance delays. Industry-specific inputs incorporated resistance surveillance network data and immunization schedule adoption curves.
Caveats apply where FDA antimicrobial resistance initiative pacing or Chinese API manufacturing environmental enforcement could materially shift the outlook. Forecasts reflect assumptions about stewardship mandate penetration and mRNA technology transfer partnership velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
Respiratory Disorders Treatment Market
Respiratory Therapy
Bronchial Thermoplasty Market
Respiratory Therapy
Idiopathic Pulmonary Fibrosis Management Market
Respiratory Therapy
Artificial Lung Market
Respiratory Therapy
Respiratory Antiviral Treatment Market
Respiratory Therapy
United States Idiopathic Pulmonary Fibrosis Treatment Market
Respiratory Therapy
Global Oxygen Therapy Market
Respiratory Therapy
Oscillating Positive Expiratory Pressure (OPEP) Devices Market
Respiratory Therapy
Interventional Pulmonology Market
Respiratory Therapy
Global Positive Airway Pressure Market
Respiratory Therapy
Opioid-Induced Respiratory Depression Market
Respiratory Therapy
Respiratory Gating Market
Respiratory Therapy
Alpha-1 Antitrypsin Deficiency (AATD) Treatment Market
Respiratory Therapy
Global Bronchitis Treatment Market
Respiratory Therapy
Croup Treatment Market
Respiratory Therapy
Breathing Disorders Treatment Market