
 Cough Systems Market | 2026-2036
Cough Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Cough Systems Market Outlook
MDR compliance timelines in Europe are restructuring the cost-of-entry calculus for cough system manufacturers seeking CE marking. Koninklijke Philips N.V. leverages its respiratory portfolio breadth to sustain multi-regional registrations across notified bodies. Hill-Rom Services, Inc. anchors its position through hospital channel control and critical care integration. Electromed specializes in mechanical insufflation-exsufflation technology, occupying a defensible niche in home care segments.
Cough systems encompass mechanical and electronic devices designed to simulate natural cough mechanics through positive-negative pressure cycling, typically operating at inspiratory pressures of 30-50 cm H₂O and expiratory flows exceeding 160 L/min to clear retained airway secretions. These devices serve primary commercial purpose in preventing pneumonia and respiratory failure among patients with neuromuscular weakness or impaired cough reflex. Electronic devices with feedback control architecture command premium positioning due to real-time pressure modulation capabilities, while portable systems represent the fastest-expanding configuration as ambulatory and home-based respiratory protocols gain clinical traction. Smart systems integrating sensor-based monitoring are emerging as a concentrated margin pool, though manual devices retain substantial volume in price-sensitive procurement environments.
FDA 510(k) pathways and the EU MDR framework collectively shape product validation burdens, with FDA demanding clinical evidence for novel pneumatic architectures and MDR requiring sustained post-market surveillance for electronic cough systems. ISO 80601-2-74 standards for respiratory ventilatory equipment directly influence design specifications for mechanical cough assist platforms across both jurisdictions. Stakeholders must monitor evolving reimbursement codes for home-based airway clearance therapy, as payer decisions will determine whether portable and smart system adoption extends beyond tertiary hospital settings into community pulmonary care.
Market Dynamics
FDA clearance pathways for mechanical cough assist devices are tightening validation requirements for new entrants, while MDR compliance timelines in Europe restructure cost-of-entry calculus for CE marking. This regulatory compression is concentrating competitive advantage among established respiratory portfolios with multi-regional registration capabilities.
Growth Catalysts
- Home Care Protocol Expansion:Pulmonary clinics across the United States are deploying non-invasive airway management systems to reduce hospital readmission rates for neuromuscular patients.
- ISO 80601-2-74 Harmonization:Unified respiratory ventilatory equipment standards are streamlining design specifications for mechanical cough assist platforms across FDA and EU jurisdictions.
- Medicare Reimbursement Alignment:Payer decisions covering home-based airway clearance therapy are accelerating portable system adoption beyond tertiary hospital settings.
Market Restraints
- Post-Market Surveillance Burden:EU MDR requires sustained clinical follow-up for electronic cough systems, elevating compliance costs for manufacturers without established notified body relationships.
- Pneumatic Component Concentration:Precision pressure sensors and valve assemblies for 30-50 cm H₂O operating ranges source predominantly from German and Japanese specialty suppliers.
- Manual Device Price Anchoring:Basic mechanical insufflation-exsufflation units retain substantial procurement volume in cost-sensitive hospital purchasing environments.
Strategic Opportunities
- Smart System Integration:Sensor-based monitoring platforms with real-time pressure modulation capabilities represent a concentrated margin pool in premium positioning.
- Community Pulmonary Penetration:Ambulatory care networks in France and the Netherlands are piloting portable cough system protocols for post-ICU respiratory rehabilitation.
- Reimbursement Code Expansion:Emerging CPT and HCPCS coverage determinations for mechanical cough assist in pediatric neuromuscular populations are creating new addressable segments.
Industry Challenges
- Clinical Evidence Generation:Novel pneumatic architectures require prospective studies demonstrating non-inferiority to established 160 L/min expiratory flow benchmarks.
- Cross-Border Registration Synchronization:Divergent FDA 510(k) and EU MDR evidence requirements force parallel rather than sequential market entry strategies.
- Legacy System Interoperability:Hospital IT infrastructure for respiratory device data integration lacks standardized protocols for cough system output capture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cough Systems Market |
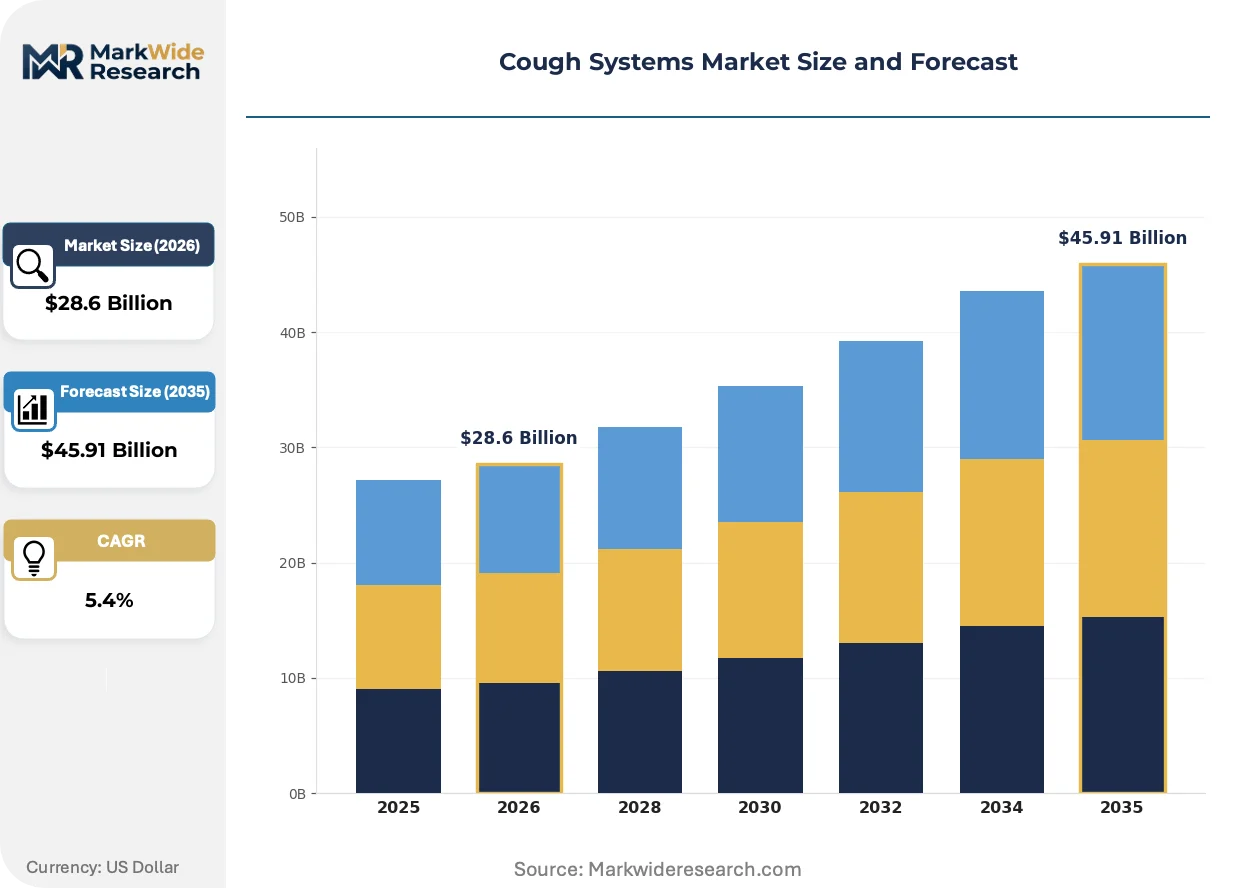
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $45.91 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Devices, Electronic Devices, Smart Systems, Manual Devices, Portable Systems Application: Respiratory Therapy, Sputum Collection, Airway Clearance, Diagnostic Aid, Patient Monitoring End User: Hospitals, Pulmonary Clinics, Diagnostic Laboratories, Home Care Patients, Rehabilitation Centers Technology: Ultrasonic, Pneumatic, Vibratory, Electric Motor, Sensor-based, Feedback Control |
| Companies Covered | Koninklijke Philips N.V., Hill-Rom Services, Inc., Ventec Life Systems, Vitality Medical, Oxygen Concentrator Store, Electromed, United Hayek Industries Inc., Dima Italia Srl, Air Liquide Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cough Systems Market Strategic Shifts
Feedback control architecture is displacing open-loop pneumatic designs across premium device tiers, while ambulatory protocol adoption is compressing the form factor specifications that define competitive viability. These shifts are reconfiguring R&D allocation across mechanical and electronic platform development.
Closed-loop pressure modulation with real-time respiratory mechanics sensing is electrifying the premium tier of mechanical cough assist devices. Critical care units in tertiary hospitals are adopting these systems for ventilator-weaning patients requiring precise secretion management. The technology is electrifying margin structures by enabling outcome-based contracting models that tie reimbursement to pneumonia prevention metrics.
The EU Medical Device Regulation's enhanced clinical evaluation requirements are extending time-to-market for electronic cough systems by 12-18 months compared to the previous Medical Device Directive framework. Manufacturers must now submit post-market clinical follow-up plans with annual safety reporting to notified bodies. Home care segments with shorter product lifecycles are responding by accelerating manual device refreshes while deferring smart system launches.
Hospital procurement departments are unbundling after-sales service contracts from device purchases, forcing manufacturers to compete on transparent lifecycle cost models rather than bundled maintenance premiums. Group purchasing organizations are consolidating respiratory equipment buying across integrated delivery networks. This behavior is most visible in the United States, where Medicare bundled payment programs for chronic respiratory conditions are shifting accountability to hospital systems.
Cough Systems Market Segmentation
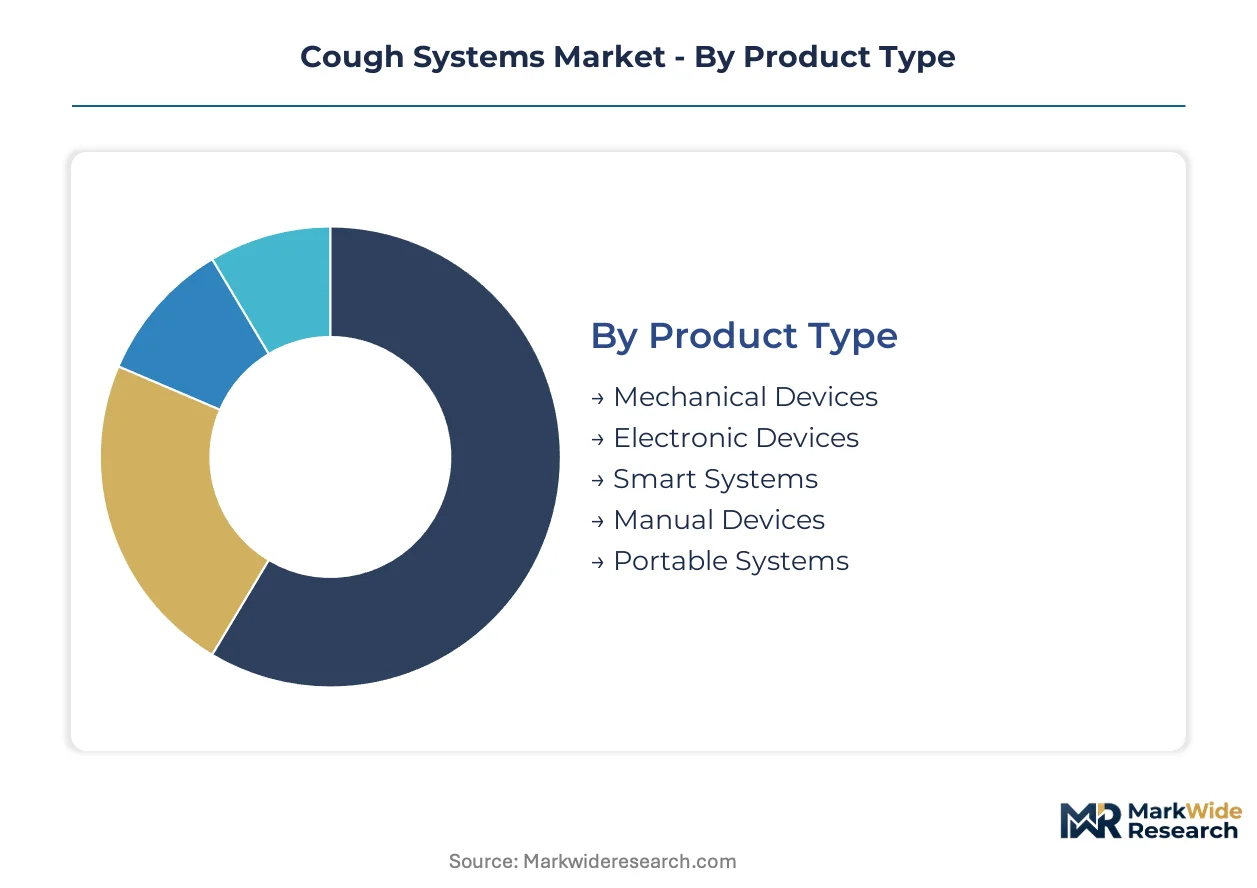
Cough systems manufacturers configure product portfolios across four intersecting dimensions that determine reimbursement eligibility, regulatory pathway, and channel strategy. Each segmentation axis carries distinct margin profiles and competitive intensity.
Product Type:
Standardization dominates at the economy tier while customization increases with sensor integration and connectivity architecture.
- Mechanical Devices:Positive-negative pressure cycling systems operate at 30-50 cm H₂O inspiratory pressure with expiratory flows exceeding 160 L/min. Hospital procurement in the United States concentrates demand here for ventilator-weaning protocols, though manual device price anchoring constrains premium positioning.
- Electronic Devices:Feedback control architecture enables real-time pressure modulation through closed-loop pneumatic systems. Pulmonary clinics in France and the Netherlands are piloting these platforms for post-ICU respiratory rehabilitation, with Medicare reimbursement alignment accelerating portable configurations.
- Smart Systems:Sensor-based monitoring with respiratory mechanics sensing and outcome-based contracting capabilities.
- Manual Devices:Basic insufflation-exsufflation units retaining volume in cost-sensitive procurement environments.
- Portable Systems:Compressed form factors for ambulatory and home-based airway clearance protocols.
Leading the category by volume: Mechanical Devices. Expanding most quickly: Portable Systems.
Application:
Reimbursement code availability varies sharply across clinical use cases, concentrating margin in indications with established payer coverage.
- Respiratory Therapy:Core indication for neuromuscular weakness management with established clinical protocols.
- Sputum Collection:Diagnostic specimen acquisition with standardized collection methodologies.
- Airway Clearance:Secretion mobilization for cystic fibrosis and bronchiectasis populations.
- Diagnostic Aid:Adjunctive use in pulmonary function testing and bronchoscopy preparation.
- Patient Monitoring:Real-time respiratory mechanics tracking with predictive analytics integration.
Volume concentration: Respiratory Therapy. Steepest expansion trajectory: Patient Monitoring.
End User:
Channel control determines pricing power, with hospital systems leveraging GPO consolidation against manufacturer list prices.
- Hospitals:Tertiary care units drive specification requirements for 160 L/min expiratory flow benchmarks and ISO 80601-2-74 compliance. Critical care integration demands closed-loop pressure modulation, though procurement departments are unbundling after-sales service contracts to force transparent lifecycle cost models.
- Pulmonary Clinics:Ambulatory networks in the United States are deploying non-invasive airway management to reduce hospital readmission rates for neuromuscular patients, with emerging CPT coverage determinations for mechanical cough assist in pediatric populations creating new addressable segments.
- Diagnostic Laboratories:Sputum collection and specimen handling with standardized device specifications.
- Home Care Patients:Medicare reimbursement alignment is strongest here, driving portable system adoption beyond tertiary settings.
- Rehabilitation Centers:Post-acute respiratory rehabilitation with protocol-driven device utilization.
Revenue concentration: Hospitals. Gaining share fastest: Home Care Patients.
Technology:
Component sourcing geography shapes cost structures, with precision pressure sensors and valve assemblies concentrating among German and Japanese specialty suppliers.
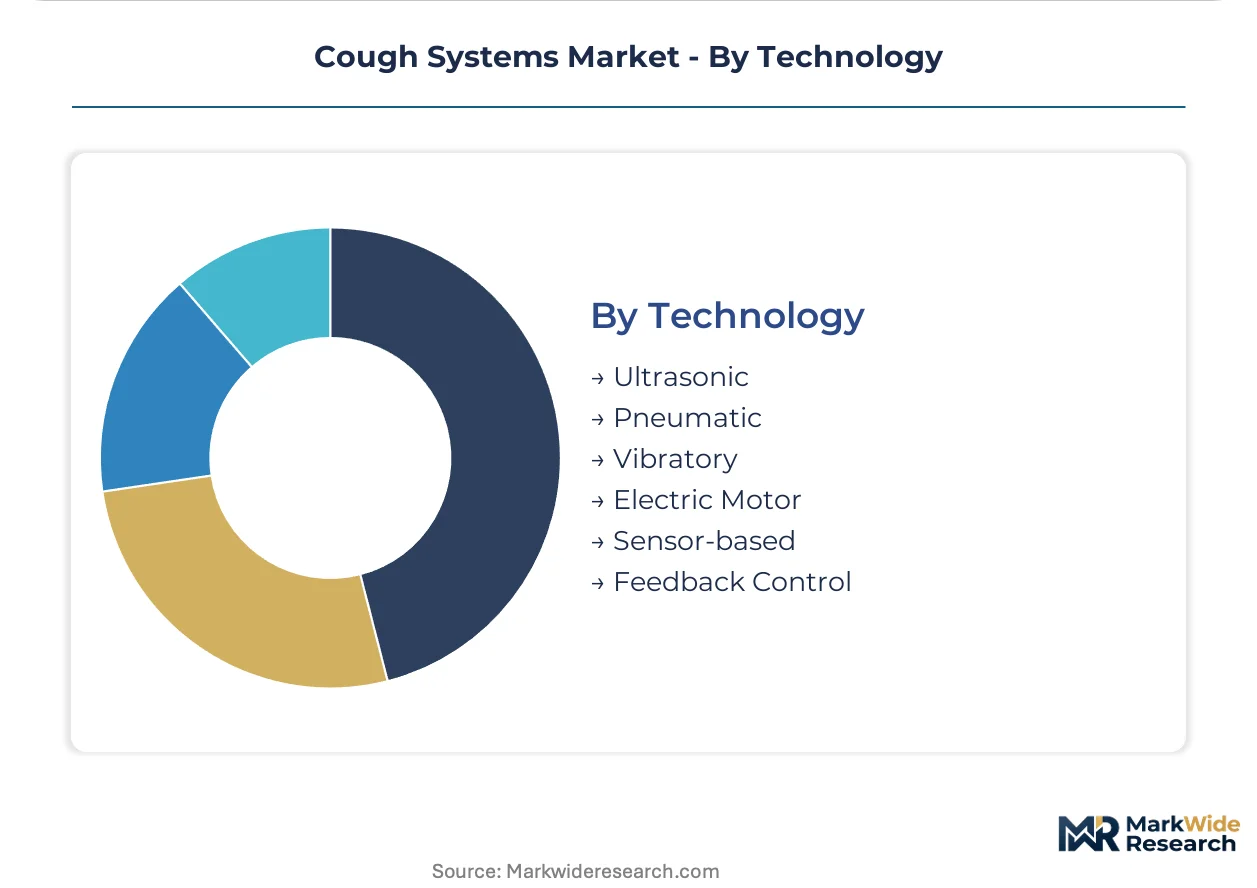
- Ultrasonic:High-frequency acoustic wave generation for secretion mobilization.
- Pneumatic:Compressed gas-driven pressure cycling with established reliability profiles.
- Vibratory:Oscillating positive expiratory pressure devices for airway clearance.
- Electric Motor:Electromechanical actuation for portable system miniaturization.
- Sensor-based:Respiratory mechanics monitoring with real-time data capture.
- Feedback Control:Closed-loop architecture enabling outcome-based contracting models that tie reimbursement to pneumonia prevention metrics.
Technology maturity: Pneumatic. Climbing the fastest: Feedback Control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MedTech innovation zones in the Netherlands and Massachusetts concentrate cough system R&D through tax-advantaged facilities. These hubs accelerate regulatory prototyping for FDA and EU MDR submissions. Manufacturing scale distributes across German precision component suppliers and US final assembly operations.
United States
Medicare reimbursement alignment for home-based airway clearance therapy drives portable system demand among neuromuscular patients. FDA 510(k) pathways for mechanical cough assist devices now require clinical evidence for novel pneumatic architectures. Boston's medical device corridor hosts critical care integration pilots for ventilator-weaning protocols in tertiary hospitals.
Germany
Precision pressure sensors and valve assemblies for 30-50 cm H₂O operating ranges source predominantly from German specialty suppliers serving global manufacturers. EU MDR compliance timelines extend time-to-market for electronic cough systems by 12-18 months versus the previous Medical Device Directive. Stuttgart's industrial automation cluster supplies pneumatic componentry to cough system assemblers across Europe.
France
Ambulatory care networks pilot portable cough system protocols for post-ICU respiratory rehabilitation in Paris and Lyon hospital systems. ANSM post-market surveillance requirements align with EU MDR's sustained clinical follow-up mandates for electronic devices. The Île-de-France region concentrates pulmonary clinic deployment of non-invasive airway management systems.
Netherlands
Community pulmonary penetration accelerates through Dutch reimbursement frameworks covering mechanical insufflation-exsufflation for home care patients. Eindhoven's health technology campus supports sensor-based monitoring platform development for smart cough systems. Rotterdam's medical logistics hub distributes portable devices to Benelux rehabilitation centers.
Japan
PMDA regulatory harmonization with ISO 80601-2-74 standards streamlines market entry for respiratory ventilatory equipment manufacturers. METI funding for home healthcare devices supports miniaturization of electromechanical actuation systems. Osaka's precision manufacturing district produces compact pneumatic assemblies for Asian-market portable configurations.
Cough Systems Market Competitive Environment
US-based respiratory portfolio companies anchor one tier; European specialists in mechanical insufflation-exsufflation technology hold differentiated positions in home care segments. Market structure concentrates among established players with multi-regional registration capabilities, as FDA and EU MDR compliance costs exclude new entrants. Three archetypes dominate: diversified MedTech conglomerates with hospital channel control, dedicated cough system specialists with niche technology depth, and respiratory equipment distributors with service integration models. Competitive moves center on unbundling after-sales service contracts to force transparent lifecycle cost models, and accelerating smart system launches to capture outcome-based contracting opportunities.
Within the diversified MedTech tier, Koninklijke Philips N.V. and Hill-Rom Services, Inc. exemplify portfolio breadth strategies that sustain multi-regional registrations across notified bodies. Among dedicated specialists, Electromed occupies a defensible position in mechanical insufflation-exsufflation technology for home care segments. These three anchors demonstrate how regulatory compression favors established respiratory portfolios with pre-existing FDA clearances and EU notified body relationships.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Hill-Rom Services, Inc. |
| Ventec Life Systems |
| Vitality Medical |
| Oxygen Concentrator Store |
| Electromed |
| United Hayek Industries Inc. |
| Dima Italia Srl |
| Air Liquide Medical Systems |
| Others |
Value Chain & Pricing Dynamics
EU MDR post-market surveillance mandates gate qualified supply access for electronic cough systems while compressing premium-tier pricing power for manufacturers lacking established notified body relationships. Hospital procurement departments unbundle after-sales service contracts to force transparent lifecycle cost models, squeezing margins across pneumatic component tiers.
Pricing Analysis
Short lead-time premiums command 15-25% markups over standard delivery windows for precision pressure sensors and valve assemblies, while spot inventory of manual devices trades at distressed clearing levels. Three-tier pricing structure across premium, standard, and economy levels segments by feedback control architecture sophistication and ISO 80601-2-74 certification tier. Pricing pressure stems from group purchasing organization consolidation across US integrated delivery networks. Home care patients exhibit highest price sensitivity; critical care units in tertiary hospitals demonstrate lowest.
Supply Chain Analysis
Reverse-logistics flows for refurbishment and remanufacturing concentrate in German and Japanese facilities serving global cough system assemblers with recertified precision components. Precision pressure sensors and valve assemblies for 30-50 cm H₂O operating ranges source predominantly from German and Japanese specialty suppliers. Supply chain risk centers on single-source vulnerability for electromechanical actuation subassemblies. Distribution runs through hospital procurement departments, GPO contracts, and direct-to-patient channels for home care segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Feedback control architecture is displacing open-loop pneumatic designs across premium device tiers, creating a technology-transition window where closed-loop pressure modulation capabilities determine competitive viability. Legacy mechanical insufflation-exsufflation platforms face margin compression as smart systems capture outcome-based contracting opportunities.
For Market Incumbents: Lock in multi-regional registration capabilities across FDA and EU notified bodies before MDR compliance timelines extend further. Anchor hospital channel control through critical care integration pilots for ventilator-weaning protocols. Defend against emerging smart system specialists by accelerating sensor-based monitoring platform launches tied to pneumonia prevention metrics. For New Entrants and Emerging Players: Begin with portable system configurations for home care patients where Medicare reimbursement alignment creates addressable white space. Target pediatric neuromuscular populations with emerging CPT coverage determinations as the most penetrable segment. Pursue direct-to-patient go-to-market angles bypassing consolidated GPO procurement channels. For Investors and Strategic Acquirers: FDA 510(k) clearance for novel pneumatic architectures is the leading indicator that electronic cough system specialists have crossed the clinical evidence threshold for premium positioning. Focus acquisition screening on dedicated mechanical insufflation-exsufflation technology firms with defensible home care segment positions. Monitor reimbursement code expansion for mechanical cough assist in pediatric populations as the inflection signal for addressable market step-change.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance timelines extend time-to-market for electronic cough systems by 12-18 months versus previous directives. |
| Hospital System Partnership | Critical care integration pilots in Boston's medical device corridor establish ventilator-weaning protocol specifications. |
| Software Companion Development | Real-time respiratory mechanics sensing enables outcome-based contracting tied to pneumonia prevention metrics. |
| Reimbursement Strategy | Medicare alignment for home-based airway clearance therapy accelerates portable system adoption beyond tertiary settings. |
| Backward Integration | In-house production of precision pressure sensors reduces dependency on German and Japanese specialty suppliers. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with respiratory therapists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. FDA 510(k) databases, EU MDR notified body submissions, ISO 80601-2-74 certification registries, and Medicare reimbursement code determinations provided structured validation. Bottom-up demand modeling across end-user segments triangulated against top-down market sizing from manufacturer revenue disclosures.
Granularity-level modeling deployed product type, application, end user, and technology dimensions at the country level for the United States, Germany, France, Netherlands, and Japan. CAGRs derived from segment-level volume and value trajectories across the projection horizon, with cross-validation against pulmonary clinic deployment rates and home care patient adoption curves. Forecast inputs incorporated ISO 80601-2-74 harmonization progress and MDR compliance timeline shifts.
Underlying measurement precision varies by segment; electronic devices and smart systems carry tighter precision than manual devices due to structured regulatory filings. Forecasts reflect assumptions about Medicare reimbursement continuity and EU MDR notified body capacity. Practitioners should monitor FDA 510(k) pathway tightening and pediatric CPT coverage determinations for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
Alpha-1 Antitrypsin Deficiency (AATD) Augmentation Therapy Market
Respiratory Therapy
Asia-Pacific Topical Oxygen Therapy Market
Respiratory Therapy
Pulmonary Fibrosis Treatment Market
Respiratory Therapy
Severe Acute Respiratory Syndrome Treatment Market
Respiratory Therapy
Compression Therapy Market
Respiratory Therapy
Respiratory Antiviral Treatment Market
Respiratory Therapy
United States Idiopathic Pulmonary Fibrosis Treatment Market
Respiratory Therapy
Opioid-Induced Respiratory Depression Market
Respiratory Therapy
Metered Dose Inhalers Market
Respiratory Therapy
Respiratory Disorders Treatment Market
Respiratory Therapy
Pneumoconiosis Treatment Market
Respiratory Therapy
Chronic Obstructive Pulmonary Disease Treatment Market
Respiratory Therapy
Lung (Pulmonary) Airway Disease Treatment Market
Respiratory Therapy
Global Hypoxia Treatment Market
Respiratory Therapy
China Topical Oxygen Therapy Market
Respiratory Therapy
Human Respiratory Syncytial Virus (RSV) Treatment Market