
 Asia-Pacific Topical Oxygen Therapy Market | 2026-2036
Asia-Pacific Topical Oxygen Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Topical Oxygen Therapy Market Insights
Portable oxygen concentrator miniaturization is tilting manufacturing priorities toward wearable, battery-powered platforms across the Asia-Pacific. Mölnlycke Health Care AB leverages its wound care heritage to dominate hospital procurement channels in Japan and Australia. EO2 Concepts specializes in continuous diffusion technology that sustains premium positioning in chronic wound protocols. AOTI, Inc. anchors the segment with multi-modality systems that integrate topical oxygen with negative pressure therapy.
Asia-Pacific Topical Oxygen Therapy encompasses devices that deliver pure oxygen directly to dermal tissue at pressures at or slightly above atmospheric levels, typically through sealed occlusive dressings or inflatable chambers that maintain oxygen concentrations exceeding standard ambient air. These systems serve primarily to accelerate angiogenesis, reduce edema, and enhance collagen deposition in hypoxic wound beds across clinical and home settings. Oxygen Concentrators currently lead product type revenue due to their versatility across hospital and home care environments, while Topical Applicators represent the fastest-expanding category as outpatient burn management protocols proliferate. Among applications, Wound Healing commands the dominant margin pool given recurrent treatment cycles for diabetic foot ulcers and pressure injuries, whereas Cosmetic Procedures show accelerating uptake in South Korean and Thai aesthetic clinics.
Japan's PMDA and Australia's TGA enforce divergent clinical evidence requirements for topical oxygen device registration, creating fragmented market access timelines that favor established manufacturers with dedicated regulatory affairs teams. China's NMPA medical device classification rules mandate in-country testing for oxygen delivery systems, effectively filtering smaller foreign entrants from direct hospital sales channels. India's CDSCO import licensing framework for hyperbaric and topical oxygen equipment adds further complexity to supply chain planning. Stakeholders must monitor evolving reimbursement coding decisions across national health insurance schemes to anticipate volume inflection points in home care versus institutional settings.
Market Dynamics
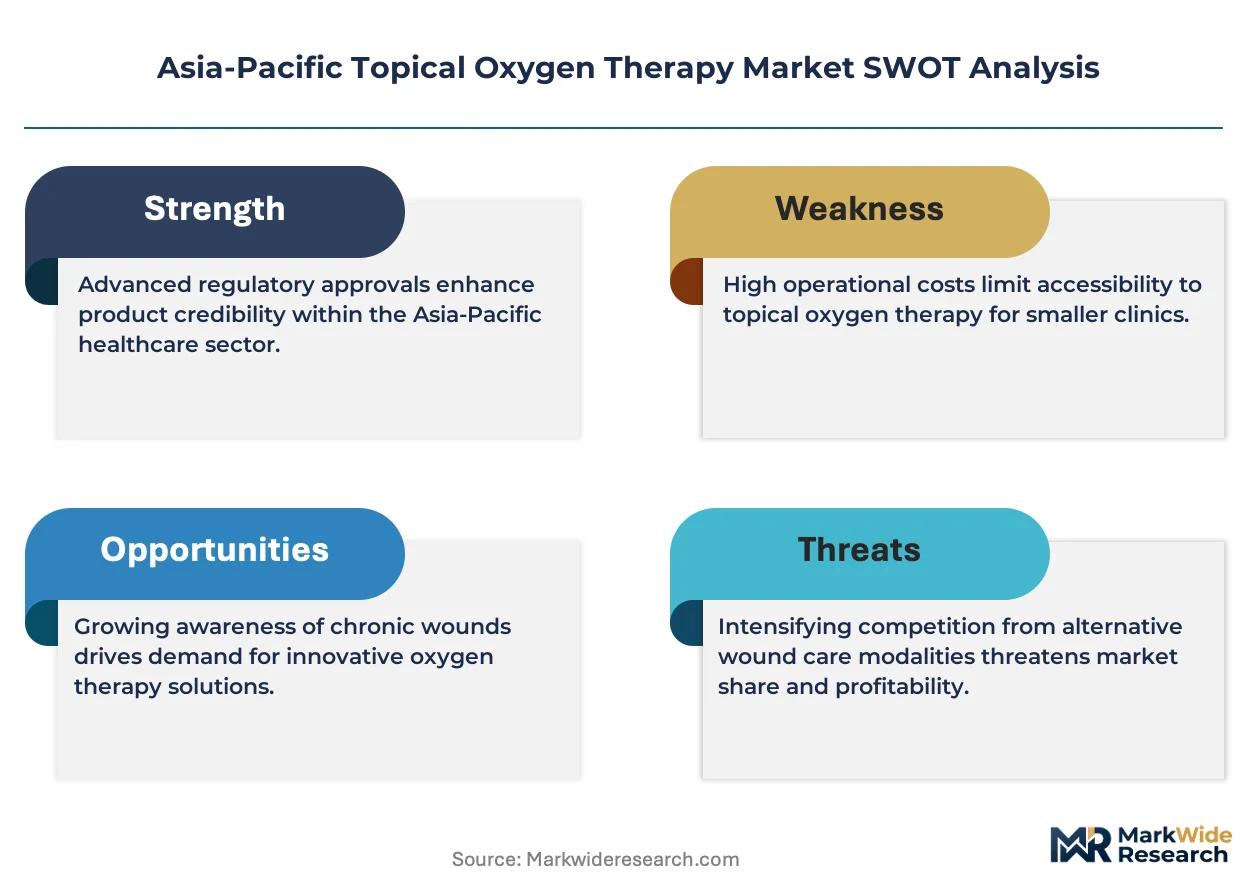
Portable oxygen concentrator miniaturization is redirecting capital toward wearable, battery-powered platforms that collapse the distinction between hospital-grade and home-use devices across the Asia-Pacific.
Growth Catalysts
- Japan's PMDA streamlined pathways:Expedited medical device approval processes for oxygen delivery systems accelerate time-to-market for next-generation topical oxygen platforms.
- Chronic wound management protocols:Australian hospital expansion of diabetic foot ulcer programs creates institutional pull for continuous diffusion technology in tertiary care settings.
- Tier-one hospital upgrades:China's dermatology and burn center modernization drives procurement of multi-modality systems integrating topical oxygen with negative pressure therapy.
Market Restraints
- Input cost volatility:Lithium-ion battery price fluctuations squeeze margins on portable concentrator manufacturing.
- Regulatory friction:China's NMPA in-country testing mandate filters smaller foreign entrants from direct hospital sales channels.
- Substitution threat:Hyperbaric oxygen therapy centers in South Korea and Thailand compete for severe wound cases.
Strategic Opportunities
- Underpenetrated home care:India's nascent home health infrastructure offers first-mover positioning for rental-based topical oxygen service models.
- Regulatory tailwind:Australia's TGA reimbursement coding evolution for chronic wound devices anticipates volume inflection toward outpatient settings.
- Technology convergence:Integration of topical oxygen with wearable biosensors enables real-time tissue oxygenation monitoring in post-surgical recovery.
Industry Challenges
- Specialized clinical training gaps:Burn centers and wound care clinics face shortages of technicians certified for multi-modality oxygen system operation.
- Certification timeline compression:PMDA and TGA divergent clinical evidence requirements fragment market access timelines for single-product portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Topical Oxygen Therapy Market |
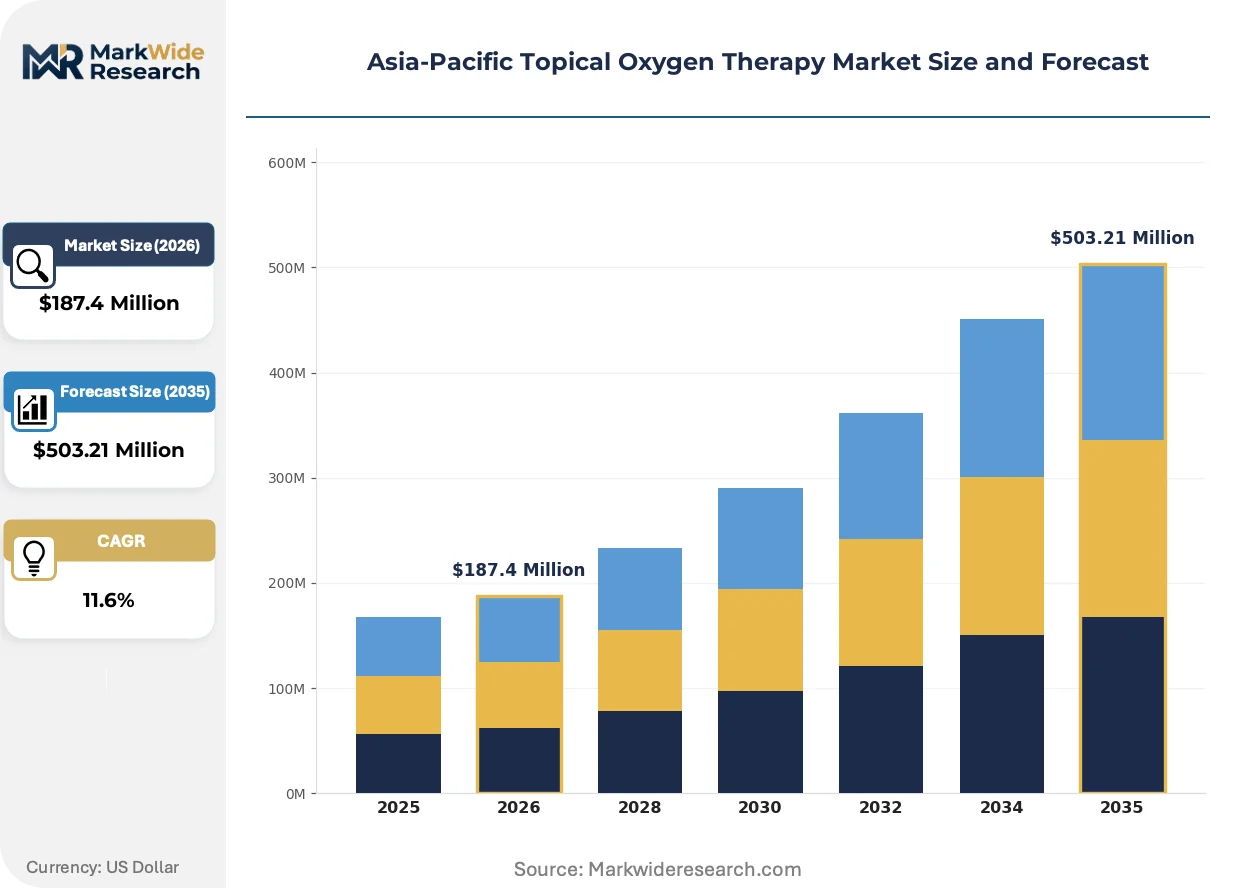
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oxygen Concentrators, Hyperbaric Chambers, Topical Applicators, Hypobaric Units Application: Wound Healing, Psoriasis Treatment, Cosmetic Procedures, Burn Management End User: Hospitals, Clinics, Home Care Settings, Research Institutes Distribution Channel: Online Retail, Direct Sales, Wholesalers, Distributors |
| Companies Covered | AOTI, Inc., Inotec AMD Ltd., EO2 Concepts, Mölnlycke Health Care AB, OxyBand Technologies, Sechrist Industries, Inc., HAUX-LIFE-SUPPORT GmbH, OxyHeal International, HEARMEC Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Topical Oxygen Therapy Market Trends and Innovations
Miniaturization, regulatory harmonization pressures, and shifting site-of-care preferences are compressing traditional boundaries between institutional and home-based oxygen delivery across the Asia-Pacific.
Wearable topical oxygen patches utilizing solid-state oxygen generation are collapsing the equipment footprint required for ambulatory wound care. Japanese and Australian home health agencies pilot these systems for post-discharge diabetic foot ulcer management. The technology is collapsing capital barriers to patient self-administration outside hospital settings.
Japan's PMDA and Australia's TGA are converging toward ISO 13485 quality management system recognition for medical device registration. This alignment reduces duplicate audit burdens for manufacturers serving both markets. Australian wound care distributors are consolidating supplier relationships to leverage cross-jurisdictional certification efficiency.
Hospital procurement departments in China and South Korea are unbundling device acquisition from consumables contracts. Tier-one networks negotiate direct oxygen concentrator purchases while sourcing occlusive dressings through separate supply agreements. This bifurcation is most visible in Shanghai and Seoul burn center purchasing patterns.
Asia-Pacific Topical Oxygen Therapy Market Segmentation
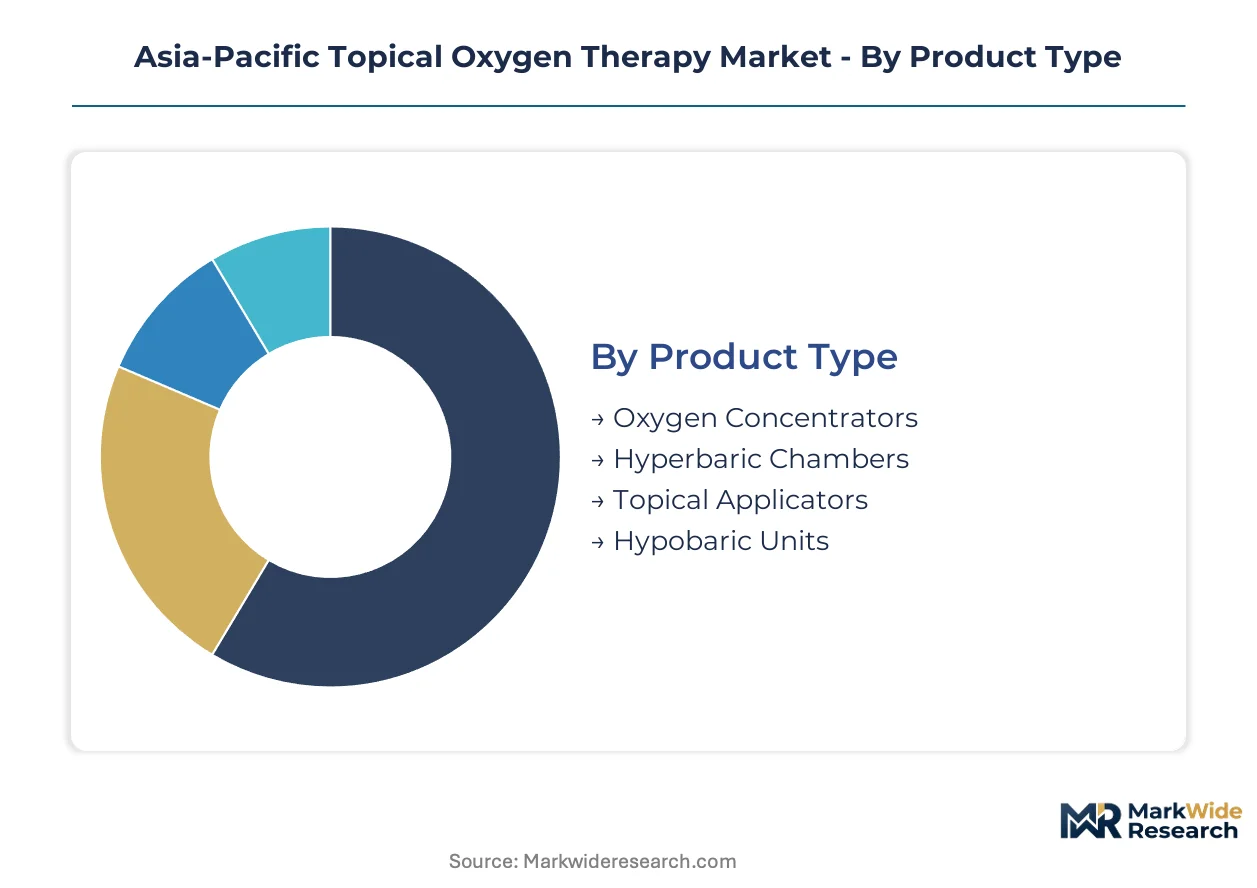
Topical oxygen therapy segmentation reveals how device specifications, clinical protocols, and procurement pathways fragment demand across the Asia-Pacific. Understanding these divisions exposes where manufacturers concentrate R&D investment and which channels capture margin.
Product Type:
Cost tier differentiation separates capital-intensive institutional systems from portable units targeting outpatient and home environments.
- Oxygen Concentrators:Electrochemical or pressure-swing adsorption systems generating medical-grade oxygen at 90-95% purity. Australian tertiary hospitals and Japan's wound care centers prioritize these for continuous ambulatory delivery in diabetic foot ulcer protocols. Procurement concentrates through group purchasing organizations serving Melbourne and Sydney metropolitan networks.
- Topical Applicators:Sealed occlusive dressings with integrated oxygen delivery manifolds sustain localized hyperoxia at wound beds. South Korean and Thai aesthetic clinics drive demand for single-use disposable formats in post-laser recovery applications. The category benefits from China's NMPA streamlined Class II device registration for non-invasive oxygen delivery.
- Hyperbaric Chambers:Rigid or flexible enclosures enabling systemic oxygen pressurization above atmospheric levels.
- Hypobaric Units:Reduced-pressure chambers for specialized altitude simulation and research applications.
Oxygen Concentrators command the established base. The steepest expansion runs through Topical Applicators.
Application:
Clinical utility determines reimbursement coding and thereby volume concentration across institutional versus outpatient settings.
- Wound Healing:Chronic diabetic foot ulcers, pressure injuries, and venous leg ulcers constitute the core revenue pool. Australia's TGA reimbursement alignment with chronic disease management plans sustains recurrent treatment cycles in public hospital networks. Japan's aging demographics expand eligible patient populations for home-based oxygen delivery.
- Cosmetic Procedures:Post-ablative laser and aesthetic surgery recovery protocols utilize topical oxygen to reduce erythema and accelerate re-epithelialization. Bangkok and Seoul clinic chains integrate these systems into premium service bundles for medical tourism segments.
- Psoriasis Treatment:Adjunctive oxygen therapy for plaque reduction and inflammation management in dermatology settings.
- Burn Management:Acute thermal and chemical injury protocols employing topical oxygen to limit eschar formation and support graft viability.
Wound Healing anchors institutional procurement. Cosmetic Procedures gain share fastest in private clinic networks.
End User:
Customer type segmentation tracks the migration of care delivery from acute facilities toward decentralized settings.
- Hospitals:Tertiary burn centers and wound care units in Shanghai, Tokyo, and Melbourne drive capital equipment procurement. China's tier-one hospital network upgrades prioritize multi-modality systems integrating topical oxygen with negative pressure wound therapy.
- Home Care Settings:Post-discharge diabetic foot ulcer management and elderly wound care create rental-based service opportunities. India's nascent home health infrastructure offers first-mover positioning for portable concentrator deployment.
- Clinics:Outpatient dermatology and wound care facilities requiring intermediate-capacity systems.
- Research Institutes:Academic medical centers investigating oxygen delivery kinetics and tissue regeneration mechanisms.
Hospitals retain the volume base. Home Care Settings show the sharpest trajectory shift.
Distribution Channel:
Supply concentration patterns reflect regulatory complexity and service intensity requirements across the Asia-Pacific.
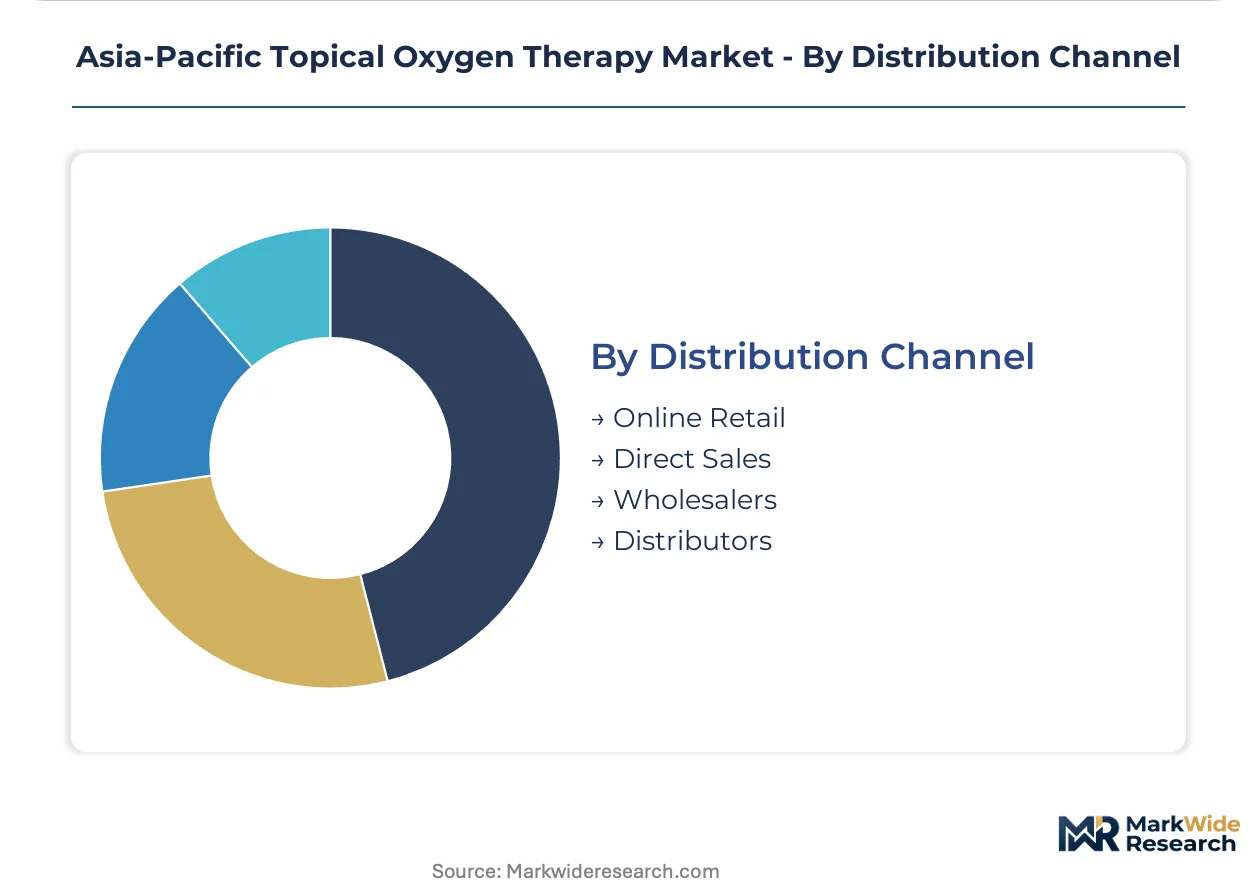
- Direct Sales:Manufacturer field teams engage hospital procurement departments and wound care specialists for capital equipment placement. Australia's TGA and Japan's PMDA registration requirements favor established vendors with dedicated regulatory affairs infrastructure.
- Distributors:Regional medical device specialists manage import logistics, in-country testing compliance, and clinician training. Chinese distributors navigate NMPA oxygen delivery system classification rules for foreign manufacturers.
- Online Retail:E-commerce platforms serve portable concentrator and consumable sales to home care patients and small clinics.
- Wholesalers:Bulk procurement intermediaries handling high-volume disposable dressing and cannula supply.
Direct Sales dominates capital equipment placement. Distributors capture the fastest expansion in cross-border market access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments and home health agencies constitute the dominant buyer archetypes across the Asia-Pacific, with divergent regulatory requirements fragmenting vendor access timelines.
Japan
Japan's aging demographics expand eligible patient populations for home-based oxygen delivery in diabetic foot ulcer management. PMDA streamlined approval pathways for oxygen delivery systems accelerate time-to-market for next-generation topical oxygen platforms. Tokyo and Osaka metropolitan wound care centers drive institutional procurement of multi-modality systems.
China
China's tier-one hospital networks prioritize dermatology and burn center modernization with integrated topical oxygen and negative pressure therapy systems. NMPA medical device classification rules mandate in-country testing for oxygen delivery systems, filtering smaller foreign entrants from direct hospital sales channels. Shanghai burn centers exhibit unbundled procurement patterns separating device acquisition from consumables contracts.
Australia
Australian tertiary hospitals expand chronic wound management programs creating institutional pull for continuous diffusion technology. TGA reimbursement coding evolution for chronic wound devices anticipates volume inflection toward outpatient settings. Melbourne and Sydney metropolitan networks concentrate procurement through group purchasing organizations serving wound care units.
South Korea
South Korean aesthetic clinics drive demand for topical oxygen in post-ablative laser recovery protocols within premium medical tourism service bundles. MFDS medical device registration requirements shape market access for foreign manufacturers entering the dermatology segment. Seoul clinic chains integrate these systems into cosmetic procedure workflows targeting regional medical tourism segments.
India
India's nascent home health infrastructure offers first-mover positioning for rental-based topical oxygen service models in post-discharge diabetic foot ulcer management. CDSCO import licensing framework for hyperbaric and topical oxygen equipment adds complexity to supply chain planning for foreign manufacturers. Maharashtra and Karnataka urban centers concentrate early home care deployment pilots.
Asia-Pacific Topical Oxygen Therapy Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement pathways. Established wound care conglomerates leverage hospital group purchasing relationships against technology-focused entrants with differentiated delivery mechanisms. Three archetypes dominate: heritage wound care suppliers with regulatory infrastructure, continuous diffusion technology specialists, and multi-modality system integrators. Competitive moves concentrate on cross-jurisdictional certification efficiency and unbundled consumables contracting.
Within the heritage medical device tier, Mölnlycke Health Care AB anchors hospital procurement channel control through established wound care relationships. EO2 Concepts exemplifies the continuous diffusion technology specialist archetype sustaining premium positioning in chronic wound protocols. AOTI, Inc. occupies the multi-modality integration position combining topical oxygen delivery with complementary therapeutic platforms.
| Leading Market Players |
|---|
| AOTI, Inc. |
| Inotec AMD Ltd. |
| EO2 Concepts |
| Mölnlycke Health Care AB |
| OxyBand Technologies |
| Sechrist Industries, Inc. |
| HAUX-LIFE-SUPPORT GmbH |
| OxyHeal International |
| HEARMEC Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Lithium-ion battery cell manufacturing concentration in South Korea and Japan directly determines where margin pools accumulate in downstream portable concentrator assembly. Cost pass-through mechanics from cathode material suppliers to device OEMs concentrate pricing power with integrated electrochemical system producers serving Australian and Japanese hospital procurement channels.
Pricing Analysis
Cost-plus contracts indexed to lithium carbonate spot benchmarks dominate concentrator procurement between tier-one Chinese manufacturers and Australian hospital group purchasing organizations. Price differentiation hinges on battery energy density certification tiers and ISO 13485 quality management system compliance status. Pricing pressure stems from cathode active material cost volatility transmitted through quarterly contract adjustments. Home care rental operators exhibit highest price sensitivity due to thin utilization economics, whereas Japanese tertiary burn centers prioritize clinical performance over unit cost.
Supply Chain Analysis
Electronics manufacturing services concentration in Taiwan and southern China controls printed circuit board and power management module capacity for portable oxygen platforms. Raw material dependencies center on lithium carbonate from Australian hard-rock spodumene operations, cobalt hydroxide from Indonesian processing facilities, and medical-grade polymer films from Japanese specialty chemical producers. Single-source vulnerability in solid-state oxygen generation membrane supply creates exposure for wearable patch manufacturers. Distribution runs through regional medical device distributors managing NMPA and TGA import compliance for foreign OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as site-of-care migration splits demand between institutional capital equipment and portable home-use platforms. Australia's reimbursement coding evolution and India's home health infrastructure gaps exemplify how demand-side shifts fragment procurement pathways.
For Market Incumbents: Insulate hospital procurement channel control through exclusive consumables bundling contracts that lock in multi-modality system users. Deepen backward integration into lithium-ion battery pack assembly to capture margin compression from cathode material volatility. Counter portable specialist entrants by accelerating TGA and PMDA certification timelines for next-generation wearable platforms.
For New Entrants and Emerging Players: India's underpenetrated home care infrastructure offers first-mover positioning for rental-based topical oxygen service models targeting post-discharge diabetic foot ulcer management. Target Maharashtra and Karnataka urban centers for pilot deployment of portable concentrator subscription services. Leverage distributor partnerships to navigate CDSCO import licensing complexity without direct regulatory infrastructure investment.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed wound care technology platforms seeking exit liquidity through strategic consolidation. Five-to-ten year viability hinges on convergence toward integrated oxygen-biosensor systems capturing outpatient monitoring spend. Monitor Australia's TGA reimbursement coding decisions for chronic wound devices as volume inflection signal toward home care settings.
| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | TGA coding alignment with chronic disease management plans unlocks Australian public hospital procurement volume. |
| Regulatory Harmonization | ISO 13485 mutual recognition between PMDA and TGA reduces duplicate audit burdens for cross-market manufacturers. |
| Technology Convergence | Wearable biosensor integration enables real-time tissue oxygenation monitoring in post-surgical recovery protocols. |
| Channel Partnership | Chinese distributor alliances navigate NMPA in-country testing mandates for foreign oxygen delivery system entrants. |
| Service Model Innovation | Rental-based portable concentrator deployment captures India's nascent home health infrastructure expansion. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with wound care clinicians, hospital procurement committee members, biomedical equipment engineers, and regional medical device distributors. Secondary validation drew from TGA reimbursement coding registers, PMDA medical device approval databases, NMPA classification rulings, and hospital group purchasing organization contract disclosures. Bottom-up demand modeling across product type, application, and end-user segments was triangulated against top-down market sizing from trade flow and import licensing records.
Calibration against historical volume inflection points in comparable medical device categories anchored growth trajectory assumptions across the projection horizon. Segmentation dimensions modeled include device portability tier, clinical application protocol, care delivery setting, and national regulatory cluster. CAGRs were derived from elasticity-adjusted penetration curves applied to demographic and disease prevalence forecasts. Industry-specific inputs incorporated diabetic foot ulcer incidence projections and burn center capacity expansion pipelines.
Practitioners should monitor lithium carbonate price volatility, PMDA approval pathway modifications, and Australian reimbursement coding revisions for early signals requiring forecast adjustment. Cross-checking against comparable chronic wound technology adoption curves in European and North American markets is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
Chronic Obstructive Pulmonary Disease Treatment Market
Respiratory Therapy
Pleural Effusion Treatment Market
Respiratory Therapy
Global Pulmonary Surfactant Market
Respiratory Therapy
Severe Acute Respiratory Syndrome Treatment Market
Respiratory Therapy
Idiopathic Pulmonary Fibrosis Management Market
Respiratory Therapy
Alpha-1 Antitrypsin Deficiency (AATD) Augmentation Therapy Market
Respiratory Therapy
Artificial Lung Market
Respiratory Therapy
Global Dyspnea Treatment Market
Respiratory Therapy
Breathing Disorders Treatment Market
Respiratory Therapy
Asthma and COPD Biomarkers Market
Respiratory Therapy
Pulmonary Fibrosis Treatment Market
Respiratory Therapy
Home Respiratory Therapy Market
Respiratory Therapy
Asia Pacific Respiratory Therapeutic Devices Market
Respiratory Therapy
Global Hypoxia Treatment Market
Respiratory Therapy
Respiratory Inhaler Market
Respiratory Therapy
Idiopathic Pulmonary Fibrosis (IPF) Treatment Market