
 Asthma and COPD Biomarkers Market | 2026-2036
Asthma and COPD Biomarkers Market Size, Share, and Industry Trends Forecast 2026-2036
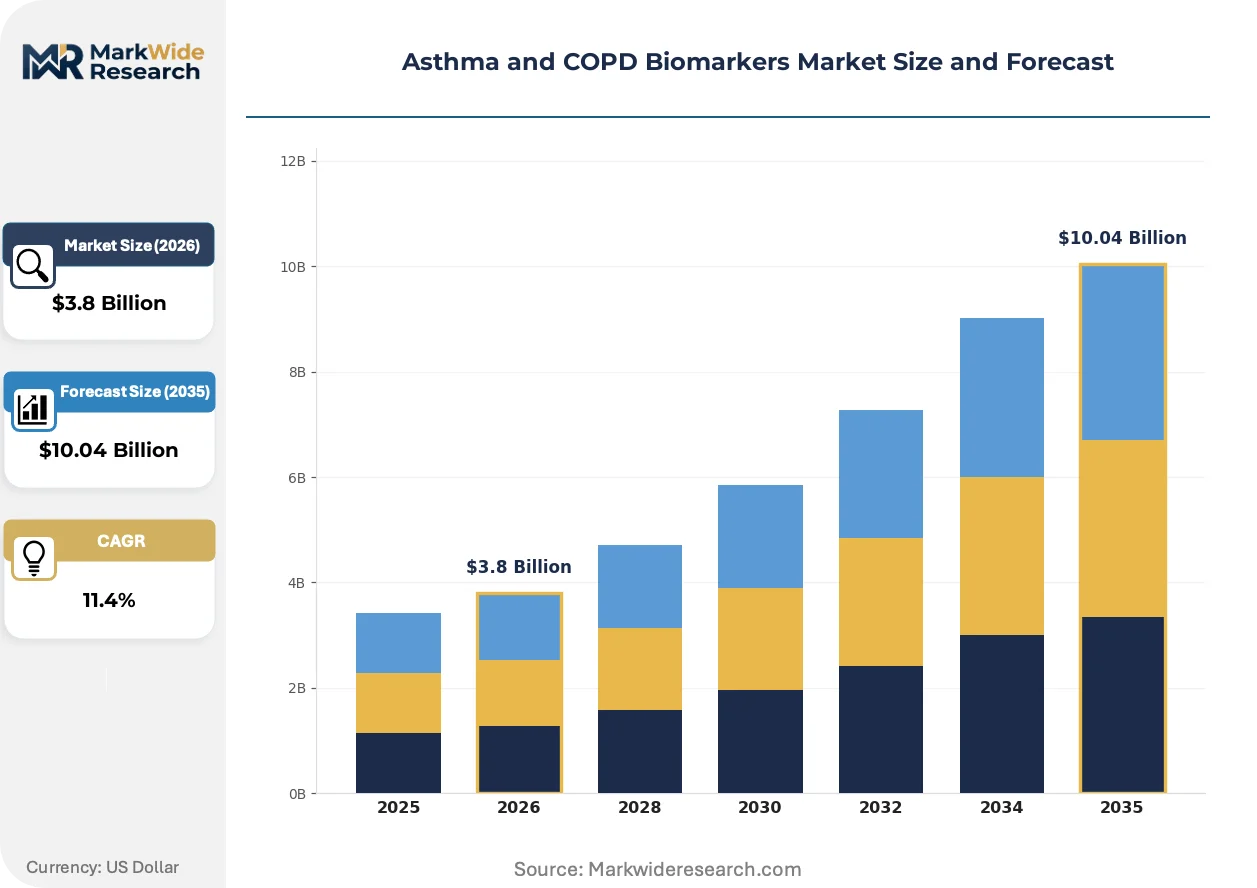
Asthma and COPD Biomarkers Market Outlook
The divide between premium molecular biomarker platforms and commodity point-of-care tests is hardening as reimbursement policies favor validated clinical utility data. AstraZeneca plc leverages its biologics pipeline to anchor demand for eosinophil-directed companion diagnostics in severe asthma. Thermo Fisher Scientific Inc. sustains technology leadership through integrated mass spectrometry workflows that span research and clinical settings. Boehringer Ingelheim International GmbH competes by embedding biomarker strategies directly into COPD trial designs across multiple continents.
Asthma and COPD biomarkers comprise measurable biological indicators—spanning inflammatory cytokines, exhaled nitric oxide, serum IgE, and sputum eosinophils—detected through blood tests, breath analysis, or imaging techniques to characterize airway inflammation, guide therapy selection, and monitor treatment response in obstructive lung diseases. The inflammatory cytokines segment dominates current revenue as IL-4, IL-5, and IL-13 pathways underpin approved biologic therapies, while exhaled nitric oxide testing grows fastest among breath-based methods due to its noninvasive repeatability in outpatient monitoring. Diagnostic tools applications command the largest share of biomarker spending, though personalized medicines represents the fastest-expanding category as pharmaceutical firms require molecular stratification for targeted therapy development.
FDA oversight of in vitro diagnostics and companion devices shapes product development timelines and clinical evidence requirements for US market entry, while EMA's In Vitro Diagnostic Regulation and MDR frameworks impose parallel conformity standards across European markets. The EU AI Act introduces additional scrutiny for algorithm-driven biomarker interpretation tools, compressing development margins for software-integrated platforms. Stakeholders must monitor evolving payer evidence requirements for biomarker-guided therapy reimbursement, as health technology assessment bodies increasingly demand cost-effectiveness proof linked to specific patient subpopulations.
Market Dynamics
The precision medicine transition is compressing biomarker platform economics as pharmaceutical sponsors demand validated companion diagnostics ahead of biologic launches, forcing diagnostic firms to absorb clinical trial costs earlier in development cycles.
Growth Catalysts
- Biologics pipeline expansion:Severe asthma and COPD drug development programs require eosinophil and FeNO stratification, pulling diagnostic demand into Phase II trials.
- FDA Breakthrough Device designation:Expedited review pathways for novel breath-based biomarkers reduce time-to-market for point-of-care platforms targeting outpatient monitoring.
- Integrated care network consolidation:United States health systems are centralizing respiratory specialty services, creating captive demand for standardized phenotyping protocols.
Market Restraints
- Reimbursement evidence thresholds:US CMS and private payers require prospective health economic data linking biomarker results to reduced exacerbation rates, extending commercialization timelines.
- Specialized mass spectrometry supply concentration:Clinical-grade LC-MS/MS instrumentation depends on German and US component suppliers, exposing capacity constraints during demand surges.
- EU AI Act algorithmic scrutiny:Machine learning-based biomarker interpretation tools face conformity assessment burdens that compress software margins and delay deployment.
Strategic Opportunities
- Underpenetrated pediatric asthma monitoring:FeNO testing protocols remain inconsistently applied in US pediatric pulmonology practices, representing white space for age-calibrated devices.
- EMA In Vitro Diagnostic Regulation harmonization:Common technical documentation standards across EU member states reduce redundant certification costs for multi-market launches.
- Telehealth-integrated home testing:Remote patient monitoring platforms are embedding Bluetooth-enabled breath analyzers, creating direct-to-consumer channel potential.
Industry Challenges
- Multiplex assay validation complexity:Simultaneous quantification of IL-4, IL-5, IL-13, and TSLP requires cross-platform standardization that delays clinical adoption.
- Laboratory information system integration:Biomarker result reporting into Epic and Cerner EHR environments demands customized HL7 FHIR interfaces that extend implementation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asthma and COPD Biomarkers Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Biomarker Type: Inflammatory Cytokines, Exhaled Nitric Oxide, Serum IgE, Sputum Eosinophils Testing Method: Biomass Analysis, Blood Test, Breath Test, Imaging Techniques Application: Diagnostic Tools, Therapeutic Monitoring, Clinical Trials, Personalized Medicines End User: Hospitals, Research Institutions, Diagnostic Laboratories, Homecare Settings |
| Companies Covered | AstraZeneca plc, GlaxoSmithKline plc, Novartis AG, Boehringer Ingelheim International GmbH, Thermo Fisher Scientific Inc., Abbott Laboratories, Merck & Co., Inc., Teva Pharmaceutical Industries Ltd., Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asthma and COPD Biomarkers Market Strategic Shifts
Digital biomarker extraction from continuous respiratory monitoring is displacing episodic clinic-based testing, while volatile organic compound profiling advances toward noninvasive COPD subtyping without sputum induction.
Volatile organic compound breath analysis is converging with machine learning pattern recognition to enable COPD phenotyping without invasive sampling. Pulmonology clinics in the Netherlands and United Kingdom are piloting these platforms for rapid exacerbation risk stratification. The technology is converging with existing spirometry workflows to compress diagnostic visit duration and reduce specialist referral backlogs.
EMA's In Vitro Diagnostic Regulation and MDR frameworks impose parallel conformity standards that reshape product development roadmaps for European market entry. Manufacturers must maintain post-market surveillance systems and periodic safety update reporting that increase ongoing compliance overhead. Breath-based companion diagnostics face particular scrutiny where algorithmic components trigger EU AI Act intersection requirements.
Hospital procurement departments are unbundling biomarker testing from bundled respiratory care contracts, creating direct purchasing relationships with specialized diagnostic laboratories. This disintermediation concentrates volume with reference labs capable of high-complexity mass spectrometry rather than hospital-affiliated pathology departments. The shift is most visible in United States metropolitan markets where integrated delivery networks renegotiate service line agreements.
Asthma and COPD Biomarkers Market Segmentation
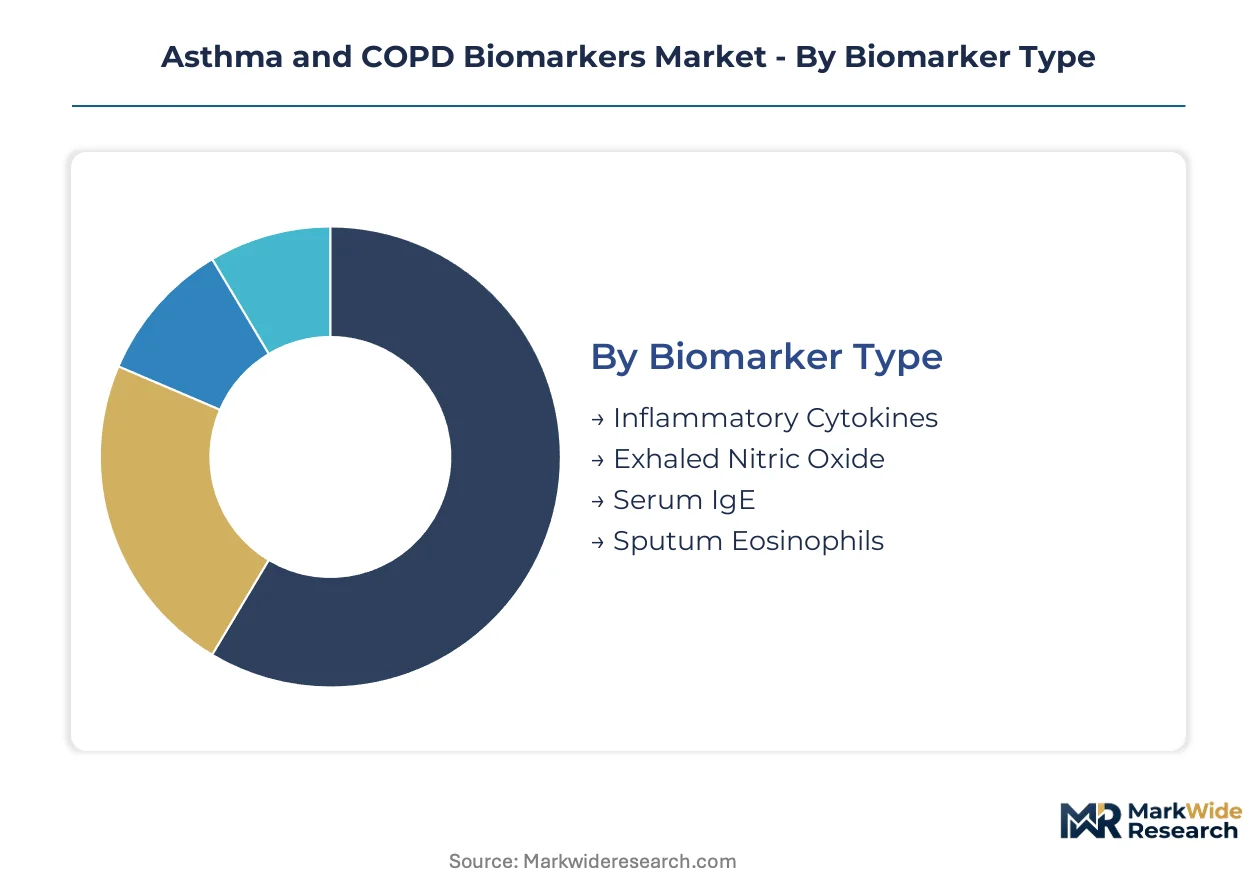
Biomarker segmentation in asthma and COPD directs capital allocation across divergent technology maturity curves. Platform choices determine regulatory pathway complexity and reimbursement velocity.
Biomarker Type:
Standardization dominates inflammatory markers while novel breath-based indicators require bespoke validation protocols.
- Inflammatory Cytokines:Quantifiable proteins including IL-4, IL-5, IL-13, and TSLP measured through immunoassay platforms. Pharmaceutical sponsors in the United States embed these markers into Phase II trial protocols for biologic patient stratification, pulling demand from centralized reference laboratories.
- Exhaled Nitric Oxide:Fractional concentration of NO in exhaled breath (FeNO) captured via chemiluminescence or electrochemical sensors. Dutch and United Kingdom pulmonology clinics deploy FeNO for rapid outpatient monitoring, compressing specialist visit duration while satisfying EMA companion diagnostic requirements for corticosteroid response prediction.
- Serum IgE:Immunoglobulin E levels indicating allergic sensitization through standardized immunoassay.
- Sputum Eosinophils:Direct inflammatory cell quantification via induced sputum cytology.
Leading the category by volume: Inflammatory Cytokines. Growing fastest: Exhaled Nitric Oxide.
Testing Method:
Cost tier separation emerges between capital-intensive imaging infrastructure and disposable point-of-care consumables.
- Breath Test:Noninvasive volatile organic compound and FeNO analysis via handheld electrochemical or optical sensors. United States integrated care networks standardize these devices across respiratory service lines to reduce specialist referral backlogs, though CMS reimbursement requires prospective health economic validation.
- Blood Test:Serum-based cytokine and IgE quantification through automated immunoassay analyzers. Hospital-affiliated laboratories in Germany and the United States concentrate volume here due to established LC-MS/MS workflows and predictable EMA/FDA regulatory pathways.
- Biomass Analysis:Cellular and proteomic characterization from tissue or fluid samples.
- Imaging Techniques:CT and MRI-derived structural biomarkers for airway remodeling assessment.
Highest margin concentration: Breath Test. Steepest volume trajectory: Blood Test.
Application:
Customer type bifurcation separates pharmaceutical sponsor requirements from clinical diagnostic procurement.
- Diagnostic Tools:Standardized testing protocols for disease confirmation and severity grading. Diagnostic laboratories in the United States and Netherlands capture revenue through high-throughput cytokine panels, though unbundling from bundled care contracts concentrates volume with reference labs possessing mass spectrometry capability.
- Personalized Medicines:Companion diagnostic development co-validated with targeted biologic therapies. EMA's In Vitro Diagnostic Regulation and FDA Breakthrough Device pathways shape development timelines here, with algorithmic interpretation tools triggering additional EU AI Act scrutiny.
- Therapeutic Monitoring:Serial biomarker measurement for treatment response assessment.
- Clinical Trials:Exploratory and validated endpoints for drug development programs.
Revenue concentration: Diagnostic Tools. Expanding most quickly: Personalized Medicines.
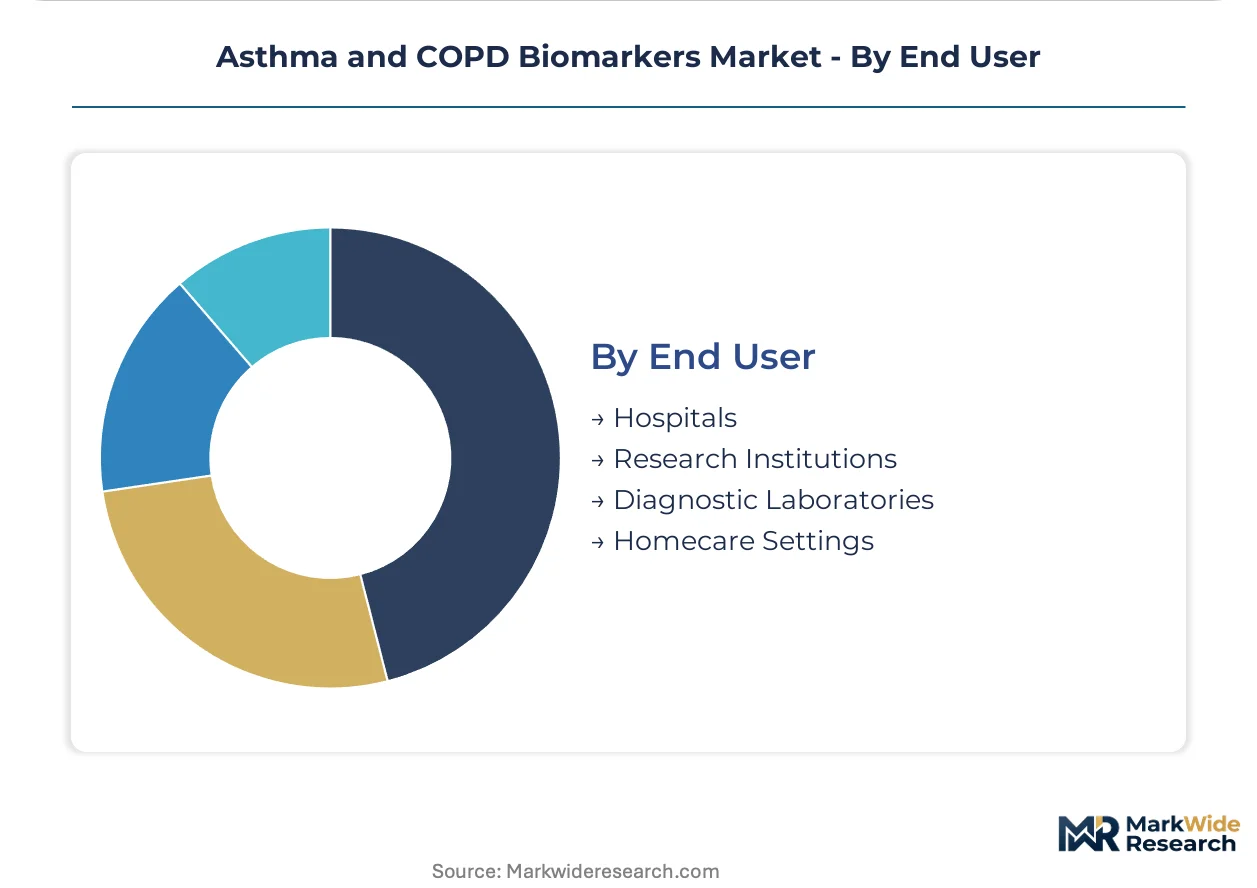
End User:
Supply concentration favors diagnostic laboratories as hospital procurement unbundles testing from respiratory care contracts.
- Diagnostic Laboratories:High-complexity reference facilities performing centralized cytokine and mass spectrometry analysis. Metropolitan United States markets exhibit pronounced volume concentration here as integrated delivery networks renegotiate service line agreements, bypassing hospital-affiliated pathology departments.
- Hospitals:Acute and specialty care settings with embedded pulmonology services. German university hospitals maintain in-house FeNO and spirometry integration, though EHR connectivity demands customized HL7 FHIR interfaces that extend implementation cycles.
- Research Institutions:Academic medical centers conducting exploratory biomarker discovery.
- Homecare Settings:Telehealth-integrated remote monitoring via Bluetooth-enabled breath analyzers.
Volume leadership: Diagnostic Laboratories. Gaining share fastest: Homecare Settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors North American biomarker platform development through its concentration of academic medical centers and precision medicine infrastructure. The metropolitan corridor hosts integrated care networks piloting point-of-care breath testing protocols for severe asthma management.
United States
FDA Breakthrough Device designations accelerate commercialization timelines for FeNO-based companion diagnostics in severe asthma. CMS reimbursement pathways require prospective health economic validation linking biomarker results to reduced hospitalization rates. The Research Triangle Park corridor in North Carolina concentrates mass spectrometry contract research organizations serving pharmaceutical sponsor trials.
Germany
EMA's In Vitro Diagnostic Regulation harmonization reduces redundant certification costs for multi-market product launches. German university hospitals in Heidelberg and Munich maintain integrated FeNO-spirometry workflows for outpatient COPD monitoring. The country's national pharmaceutical regulator enforces post-market surveillance requirements for algorithmic biomarker interpretation tools.
United Kingdom
NHS England's respiratory specialty networks standardize eosinophil-directed phenotyping protocols across integrated care systems. The Medicines and Healthcare products Regulatory Agency aligns with EMA frameworks while maintaining national variation in companion diagnostic assessment. Manchester and Birmingham pulmonology clinics pilot volatile organic compound breath analysis for rapid exacerbation risk stratification.
Netherlands
Dutch integrated care networks concentrate pediatric asthma monitoring capabilities in Utrecht and Rotterdam metropolitan regions. The country's national health technology assessment body demands cost-effectiveness proof linked to specific patient subpopulations for biomarker-guided therapy reimbursement. Leiden's life sciences cluster hosts reference laboratories performing high-throughput cytokine panels for European pharmaceutical sponsors.
Japan
PMDA's Sakigake designation system expedites review pathways for novel breath-based biomarkers targeting outpatient monitoring. Japanese pharmaceutical firms embed inflammatory cytokine stratification into Phase II trial protocols for biologic development. The Kansai region's Osaka-Kobe corridor concentrates diagnostic device manufacturing for Asia-Pacific distribution.
Asthma and COPD Biomarkers Market Competitive Environment
Premium-margin players sit above commodity-margin players across regulatory validation depth and clinical evidence requirements. Pharmaceutical-anchored firms leverage biologics pipelines to pull companion diagnostic demand, while independent diagnostic platforms compete on mass spectrometry workflow integration. Three archetypes dominate: integrated biopharma-diagnostic alliances, reference laboratory networks, and point-of-care device specialists. Competitive moves concentrate on FDA/EMA co-validation strategies and telehealth-embedded home testing channel development.
Within the integrated biopharma tier, AstraZeneca plc and Boehringer Ingelheim International GmbH exemplify pipeline-anchored biomarker strategies, while Thermo Fisher Scientific Inc. occupies a position bridging research and clinical mass spectrometry workflows. These three firms represent divergent approaches to capturing value from precision medicine transition pressures.
| Leading Market Players |
|---|
| AstraZeneca plc |
| GlaxoSmithKline plc |
| Novartis AG |
| Boehringer Ingelheim International GmbH |
| Thermo Fisher Scientific Inc. |
| Abbott Laboratories |
| Merck & Co., Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Koninklijke Philips N.V. |
| Others |
Value Chain & Pricing Dynamics
Companion diagnostic validation tiers bifurcate the Asthma and COPD Biomarkers Market into premium molecular platforms and commodity point-of-care tests, with FDA Breakthrough Device designation and EMA In Vitro Diagnostic Regulation compliance separating pricing power and supplier concentration. Pharmaceutical sponsors absorb clinical trial costs for validated platforms, while reimbursement evidence thresholds from US CMS compress margins for unvalidated alternatives.
Pricing Analysis
Value-based pricing anchored to reduced exacerbation rates dominates companion diagnostic platforms, with pharmaceutical sponsors paying premium fees for eosinophil-directed stratification validated through Phase II trials. Price differentiation rests on FDA Breakthrough Device status and EMA harmonization depth, with algorithmic interpretation tools facing additional EU AI Act compliance costs. Pricing pressure intensifies in point-of-care breath testing as CMS demands prospective health economic validation. Hospital procurement committees exhibit highest price sensitivity, while integrated care networks prioritize clinical utility over unit cost.
Supply Chain Analysis
Dual-sourcing requirements for clinical-grade LC-MS/MS instrumentation mandate multi-supplier qualification across German and US component manufacturers, constraining capacity during demand surges. Geographic supply concentration centers on Germany for precision optics, the United States for electrochemical sensors, and Japan for miniaturized detection modules. Raw material dependencies include high-purity reagents, specialized optical coatings, and rare-earth magnet components. Single-source vulnerability in ion source technology creates bottleneck risk. Distribution runs through reference laboratory networks rather than hospital-affiliated pathology departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asthma and COPD Biomarkers Market is consolidating around regulatory-validated platforms, with EMA In Vitro Diagnostic Regulation and FDA evidence requirements forcing subscale diagnostic firms toward acquisition or exit.
For Market Incumbents: Deepen vertical integration into mass spectrometry component supply through captive production of ion source technology, reducing exposure to German supplier concentration. Anchor companion diagnostic portfolios to AstraZeneca and Boehringer Ingelheim biologics pipelines, securing Phase II trial embedded demand before emerging entrants achieve regulatory validation. Defend against point-of-care commoditization by locking integrated care networks into multi-year phenotyping protocols. For New Entrants and Emerging Players: Telehealth-integrated home testing channels offer the most penetrable white space, with Bluetooth-enabled breath analyzers bypassing hospital procurement consolidation. Target pediatric asthma monitoring in US metropolitan markets, where FeNO protocols remain inconsistently applied and age-calibrated devices face limited incumbent competition. Pursue direct-to-consumer positioning through remote patient monitoring platforms, embedding reimbursement strategy from launch rather than retrofitting clinical utility evidence. For Investors and Strategic Acquirers: Exit pathways concentrate in reference laboratory network acquisitions by integrated delivery networks seeking high-complexity mass spectrometry capability. Long-term viability favors platforms with FDA-EMA co-validation and algorithmic interpretation tools cleared under EU AI Act frameworks. Watch for CMS reimbursement pathway expansion for biomarker-guided therapy as the signal indicating inflection toward mass-market adoption.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Expedited review compresses time-to-market for FeNO-based companion diagnostics in severe asthma. |
| EMA In Vitro Diagnostic Regulation Harmonization | Common technical documentation standards reduce redundant certification costs across EU member states. |
| Telehealth Platform Integration | Bluetooth-enabled breath analyzers embedded in remote monitoring create direct-to-consumer channel potential. |
| Reference Laboratory Network Acquisition | Integrated delivery networks concentrate high-complexity mass spectrometry volume, bypassing hospital pathology departments. |
| Biologics Pipeline Co-Validation | Pharmaceutical sponsors embed inflammatory cytokine stratification into Phase II trials, pulling diagnostic demand forward. |
Study Parameters
FDA filings, EMA submission databases, and ClinicalTrials.gov records formed the secondary backbone, supplemented by formulary database analysis and CMS Medicare reimbursement data. Primary interviews with regulatory affairs leads at diagnostic manufacturers, formulary directors at integrated care networks, hospital procurement managers, and payer access specialists validated secondary findings. Bottom-up and top-down triangulation cross-checked unit volume assumptions against pharmaceutical sponsor trial enrollment patterns and reference laboratory throughput data.
Bottom-up modeling segmented the market across biomarker type, testing method, application, and end user, with regional regulatory clusters treated as distinct adoption environments. CAGRs were derived from fitted growth curves applied to validated base-year estimates, incorporating pharmaceutical pipeline progression timelines and reimbursement pathway expansion scenarios. Industry-specific forecast inputs included biologics approval trajectories, EU AI Act implementation phases, and integrated care network consolidation patterns.
The model holds under stable FDA-EMA regulatory convergence and continued biologics pipeline investment; deviation in CMS reimbursement policy or EU AI Act enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
Nitric Oxide Management Systems Market
Respiratory Therapy
Global Pulmonary Surfactant Market
Respiratory Therapy
Respiratory Disorders Treatment Market
Respiratory Therapy
Global Dyspnea Treatment Market
Respiratory Therapy
Artificial Lung Market
Respiratory Therapy
Healthcare Powered Air Purifying Respirator Market
Respiratory Therapy
United States Idiopathic Pulmonary Fibrosis Treatment Market
Respiratory Therapy
Respiratory Antiviral Treatment Market
Respiratory Therapy
Global Acute Respiratory Distress Syndrome (ARDS) Treatment Market
Respiratory Therapy
Pleural Effusion Treatment Market
Respiratory Therapy
Pneumonia Treatment Market
Respiratory Therapy
Global Positive Airway Pressure Market
Respiratory Therapy
Idiopathic Pulmonary Fibrosis Management Market
Respiratory Therapy
Pediatric Respiratory Disease Treatment Market
Respiratory Therapy
Alpha-1 Antitrypsin Deficiency (AATD) Augmentation Therapy Market
Respiratory Therapy
Pneumoconiosis Treatment Market