
 Asia Pacific Residential Vacuum Cleaners Market | 2026-2036
Asia Pacific Residential Vacuum Cleaners Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Residential Vacuum Cleaners Market Outlook
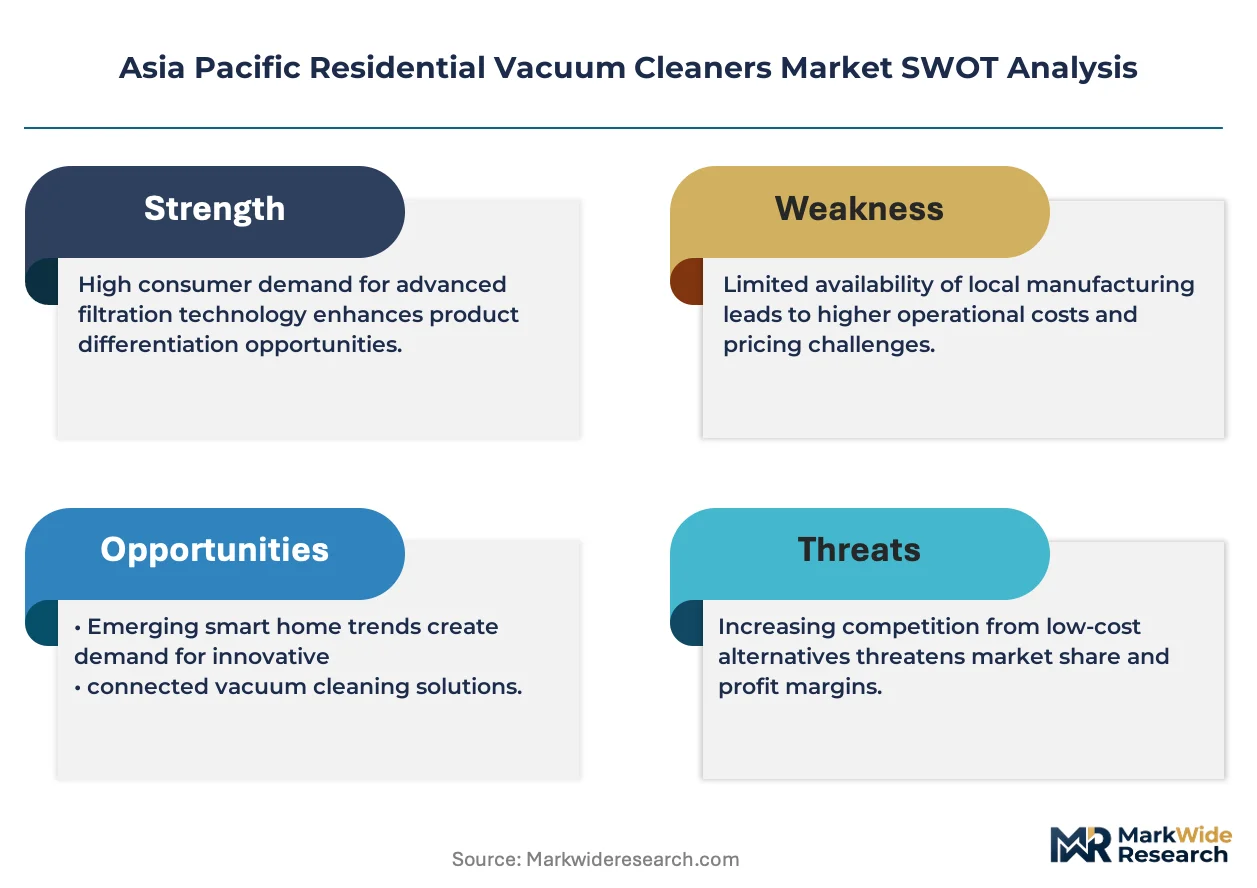
GB 4706.7-2014 household appliance safety certification is collapsing the supplier base in China, forcing smaller OEMs to either invest in testing infrastructure or exit the residential vacuum segment entirely. Dyson Limited sustains premium positioning through cyclone airflow R&D intensity and direct-to-consumer channel control across Japan and Australia. Eureka Forbes dominates India's canister and water-purifier-adjacent cleaning portfolio, leveraging decades of dealer network density that newer entrants struggle to replicate. Samsung Electronics Co. Ltd competes on smart-home ecosystem integration, embedding vacuum robots within its broader IoT platform to anchor customer loyalty.
Asia Pacific residential vacuum cleaners encompass electrically powered suction devices designed for domestic debris removal, typically operating at 100-240V with airflow rates between 20-40 liters per second and filtration thresholds capturing particles down to 0.3 microns for allergen containment. These appliances serve the primary commercial purpose of maintaining indoor air quality and surface hygiene across carpet, hard floor, and upholstery substrates found in compact urban dwellings. Robotic units now represent the fastest-growing product type as lithium-ion battery energy density improvements and simultaneous localization and mapping algorithms reduce human intervention requirements. Bagless technology leads volume share due to lower lifetime ownership costs, though bagged formats retain margin concentration among allergy-sensitive households in Japan and South Korea where HEPA-sealed disposal commands pricing premiums.
China's SAMR enforces GB energy efficiency labeling that directly shapes product development roadmaps, while Japan's METI administers Top Runner standards that progressively raise minimum suction performance thresholds. India's BIS certification mandate for electronic goods, implemented through the Compulsory Registration Order, creates a six-to-nine month market access lag for unregistered imports. Australia's E3 program harmonizes with New Zealand to maintain trans-Tasman efficiency benchmarks that filter out sub-tier imports. Stakeholders must monitor how India's PLI scheme for white goods manufacturing reshapes local production economics versus continued reliance on Chinese component sourcing, as tariff and compliance cost trajectories will determine competitive viability for mid-market brands.
Market Dynamics
GB 4706.7-2014 household appliance safety certification is collapsing China's supplier base, forcing smaller OEMs to either invest in testing infrastructure or exit the residential vacuum segment entirely. This regulatory compression is reshaping competitive positioning across the Asia Pacific manufacturing landscape.
Growth Catalysts
- Urban apartment densification:Compact living spaces in Seoul, Tokyo, and Shanghai favor robotic and cordless formats. Lithium-ion battery energy density improvements reduce human intervention requirements.
- India's PLI scheme for white goods:Production-linked incentives reshape local production economics versus continued reliance on Chinese component sourcing. Tariff and compliance cost trajectories determine competitive viability for mid-market brands.
- Smart-home ecosystem integration:IoT platform embedding anchors customer loyalty through appliance connectivity. Vacuum robots now function as data collection nodes within broader home automation architectures.
Market Restraints
- GB standards compliance costs:SAMR energy efficiency labeling and electromagnetic compatibility testing create six-figure certification barriers. Smaller OEMs lack capital to maintain testing infrastructure.
- Lithium supply concentration:Battery cell manufacturing concentrates in Chinese industrial clusters. Geopolitical friction threatens component access for assemblers in India and Southeast Asia.
- HEPA filtration technical limits:Allergen capture thresholds below 0.3 microns require sealed system engineering. Japanese and South Korean allergy-sensitive households demand premium pricing that mid-tier brands cannot meet.
Strategic Opportunities
- Vietnam and Indonesia underpenetration:Manual cleaning tools dominate these markets. Rising disposable incomes accelerate upgrade trajectories similar to India's tier-1 cities.
- Simultaneous localization and mapping convergence:SLAM algorithm refinement combines with computer vision advances. Autonomous navigation accuracy opens premium positioning for robotic units.
- Australia's E3 program harmonization:Trans-Tasman efficiency benchmarks with New Zealand filter out sub-tier imports. Compliant manufacturers gain preferential channel access across both markets.
Industry Challenges
- BIS certification timeline compression:India's Compulsory Registration Order creates six-to-nine month market access lags. Unregistered imports face customs detention and distributor reluctance.
- SLAM algorithm talent scarcity:Robotics software engineering commands premium compensation in Shenzhen and Bangalore. Incumbents poach from automotive autonomous driving divisions.
- Bagless-to-bagged platform switching costs:Manufacturing retooling for HEPA-sealed disposal systems requires cleanroom assembly investments. Allergy-focused product lines demand separate supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Residential Vacuum Cleaners Market |
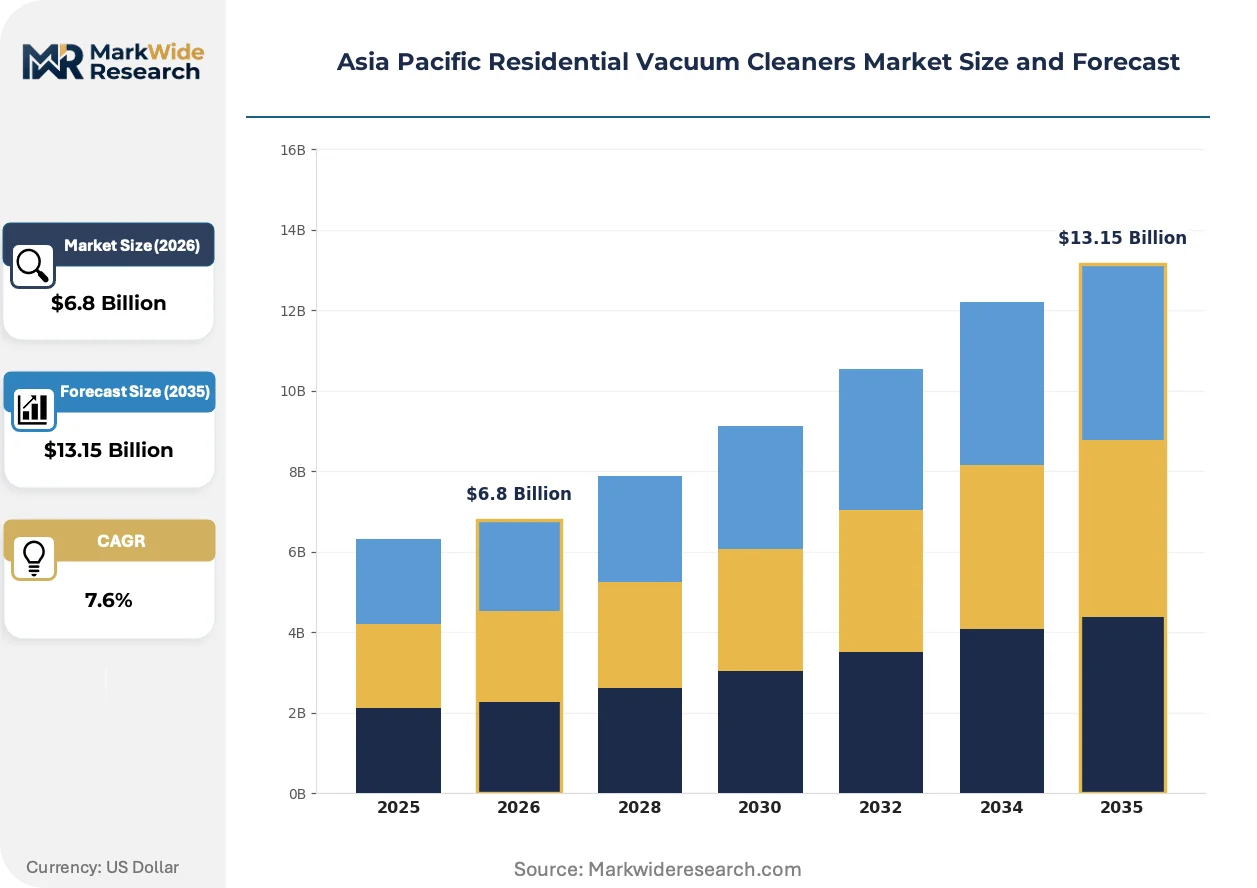
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Upright, Canister, Robotic, Handheld Technology: Bagless, Bagged, Corded, Cordless Applications: Carpet, Hard Floor, Upholstery, Stairs Customer Type: Households, Cleaning Services, Property Managers, Rentals |
| Companies Covered | Eureka Forbes, Haier Group Corporation, Dyson Limited, iRobot Corporation, Samsung Electronics Co. Ltd, Electrolux AB, Groupe SEB, Panasonic Holdings Corporation, Bissell Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Residential Vacuum Cleaners Market Strategic Shifts
Robotic autonomy is displacing manual intervention as the defining performance metric across the Asia Pacific residential vacuum segment. Three converging developments are compressing traditional competitive advantages.
SLAM-enabled navigation is displacing random-bounce cleaning patterns in premium robotic units. Urban apartment dwellers in Tokyo and Shanghai adopt these systems at replacement cycle compression rates. The technology is displacing mid-tier canister vacuum relevance in sub-800-square-foot dwellings.
METI's Top Runner standards progressively raise minimum suction performance thresholds across Japanese retail channels. Domestic manufacturers accelerate R&D spending to maintain shelf placement. Cordless stick formats face the steepest compliance cost escalation as battery and motor efficiency requirements tighten simultaneously.
Direct-to-consumer channel unbundling disrupts traditional dealer network economics. Eureka Forbes' decades-old density in Indian tier-1 cities now competes with Dyson's online-first warranty and service models. This shift concentrates most visibly in Australian and Japanese markets where logistics infrastructure supports same-day delivery expectations.
Asia Pacific Residential Vacuum Cleaners Market Segmentation
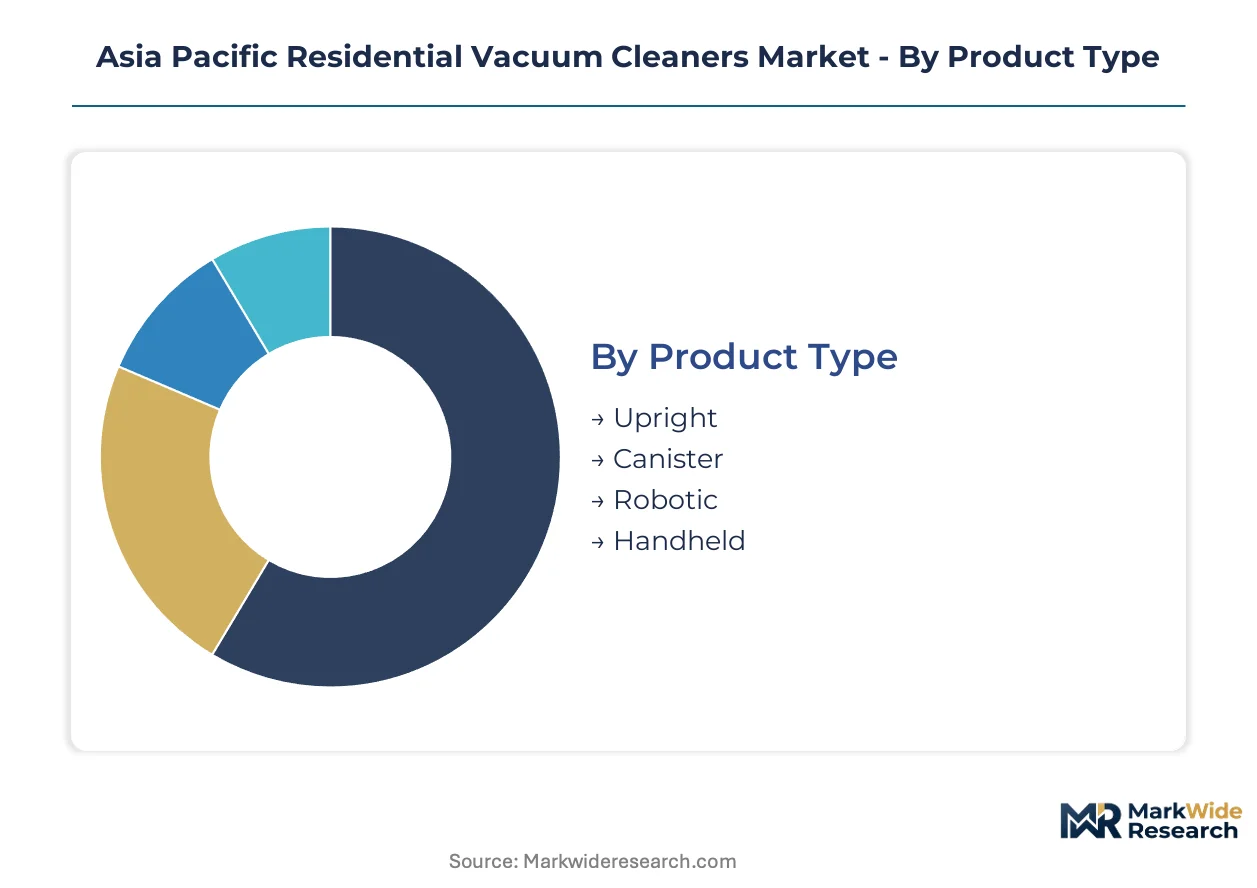
Segmentation in Asia Pacific residential vacuum cleaners reveals how urban living constraints and regulatory pressures fragment demand across formats. Substitution dynamics between manual cleaning tools and powered appliances vary sharply by housing density and income tier.
Product Type:
Robotic units exert the strongest substitution pressure on traditional formats as SLAM-enabled navigation compresses replacement cycles in compact dwellings.
- Robotic:Autonomous units deploy simultaneous localization and mapping algorithms with lithium-ion power systems. Demand concentrates in Tokyo and Shanghai sub-800-square-foot apartments where hands-free operation offsets space constraints.
- Canister:Flexible hose configurations with separate motor housings dominate multi-surface cleaning. Indian tier-1 cities sustain volume through Eureka Forbes dealer networks as households upgrade from manual tools.
- Upright:Integrated brush-roll systems target carpet-dominant markets with direct-drive motors.
- Handheld:Compact lithium-powered units serve quick-cleaning needs and vehicle interiors.
Canister formats anchor the volume base while robotic units gain share at the steepest rate.
Technology:
Cost tier stratification separates premium sealed systems from mass-market bagless alternatives as BIS and GB compliance costs reshape viable positioning.
- Bagless:Cyclone separation eliminates recurring bag purchases through centrifugal particle capture. Australian E3 program harmonization with New Zealand filters sub-tier imports, advantaging compliant manufacturers with trans-Tasman channel access.
- Cordless:Stick-format lithium-ion systems trade runtime for maneuverability. METI Top Runner standards escalate battery and motor efficiency requirements, forcing R&D acceleration among Japanese domestic manufacturers.
- Bagged:HEPA-sealed disposal commands allergy-sensitive premiums in Japan and South Korea.
- Corded:Sustained suction power persists in price-sensitive segments despite mobility constraints.
Bagless technology anchors the volume base while cordless formats expand most quickly.
Applications:
Surface-specific engineering requirements fragment procurement as hard-floor dominance in Northeast Asia diverges from carpet retention in Australia.
- Hard Floor:Soft-bristle brush rolls and suction-only modes protect delicate surfaces. Seoul apartment dwellers drive demand as polished concrete and engineered wood finishes proliferate in new construction.
- Carpet:Motorized brush bars with adjustable height settings extract embedded debris. Australian suburban housing stock sustains relevance despite regional hard-floor trends.
- Upholstery:Mini motorized tools and crevice attachments target fabric maintenance.
- Stairs:Lightweight portability requirements favor cordless stick and handheld formats.
Hard floor cleaning anchors the volume base while carpet applications retain margin concentration.
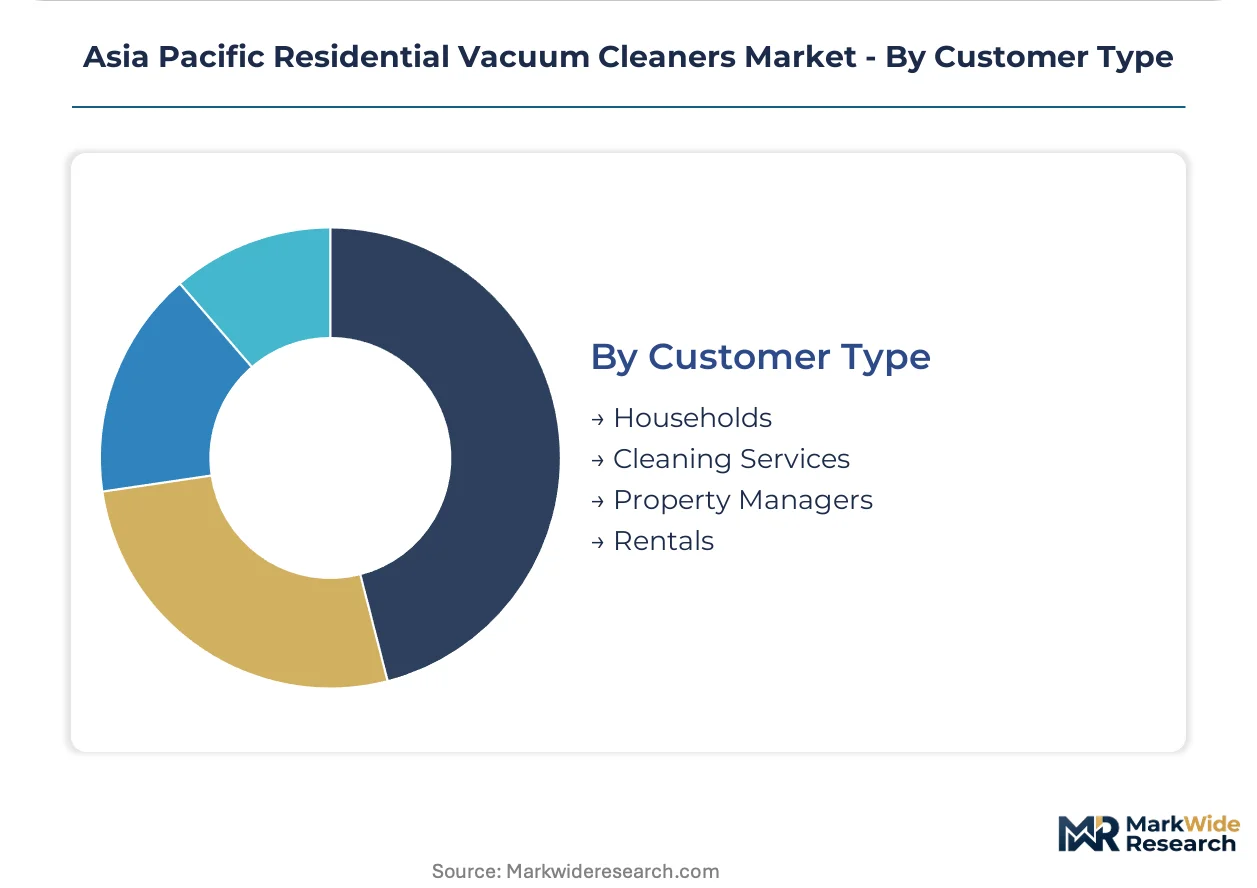
Customer Type:
Volume concentration among households contrasts with service-sector procurement patterns as India's PLI scheme reshapes local production economics.
- Households:End-consumer purchases dominate unit economics with replacement cycles compressing in premium segments. Rising disposable incomes in Vietnam and Indonesia accelerate upgrade trajectories from manual tools.
- Cleaning Services:Commercial durability requirements prioritize corded canister reliability over cordless convenience. Fleet procurement concentrates in Australian and Japanese urban centers with established service economies.
- Property Managers:Bulk acquisition for rental unit turnover favors standardized mid-tier specifications.
- Rentals:Short-term accommodation providers demand compact storage and rapid deployment features.
Households anchor the volume base while cleaning services demonstrate the steepest procurement expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban apartment dwellers in Seoul, Tokyo, and Shanghai represent the fastest-expanding buyer archetype as compact living spaces favor robotic and cordless formats. India's tier-1 cities concentrate volume demand where rising disposable incomes accelerate upgrades from manual cleaning tools. Regulatory divergence across SAMR, METI, and BIS jurisdictions reshapes competitive access.
China
Apartment densification in Shanghai and Shenzhen drives robotic vacuum adoption as lithium-ion battery density improves. SAMR enforces GB 4706.7-2014 household appliance safety certification that collapses the supplier base, forcing smaller OEMs to exit or invest in testing infrastructure. Manufacturing clusters in Guangdong and Zhejiang provinces consolidate around compliant mid-market producers.
Japan
Allergy-sensitive households in Tokyo and Osaka command premium pricing for HEPA-sealed disposal systems. METI administers Top Runner standards that progressively raise minimum suction performance thresholds, accelerating R&D spending among domestic manufacturers. Nagoya-based engineering centers refine cordless stick motor efficiency to maintain retail shelf placement.
India
Tier-1 cities Mumbai and Delhi-NCR sustain canister vacuum volume through established dealer networks as households upgrade from manual tools. BIS certification under the Compulsory Registration Order creates six-to-nine month market access lags for unregistered imports. Maharashtra and Karnataka industrial corridors attract PLI scheme investments for white goods manufacturing.
South Korea
Seoul apartment dwellers adopt SLAM-enabled robotic units at compressed replacement cycles. MFDS-equivalent appliance safety frameworks align with electromagnetic compatibility requirements that filter sub-tier imports. Incheon and Suwon manufacturing bases supply compact-format lithium-powered systems for Northeast Asian export markets.
Australia
Suburban carpet-dominant housing stock sustains upright vacuum relevance despite hard-floor trends in new construction. The E3 program harmonizes with New Zealand to maintain trans-Tasman efficiency benchmarks that filter out non-compliant imports. Sydney and Melbourne distribution hubs prioritize same-day delivery logistics for direct-to-consumer channel expansion.
Asia Pacific Residential Vacuum Cleaners Market Competitive Environment
Player mix skews toward diversified electronics conglomerates with adjacent appliance portfolios. Market structure concentrates around three to four dominant ecosystem integrators while mid-tier specialists face margin compression from regulatory compliance costs. Strategic archetypes include smart-home platform anchors, cyclone-technology premium positioners, and dealer-network density builders. Competitive moves center on direct-to-consumer channel unbundling and simultaneous localization and mapping algorithm refinement.
Within the premium-tier vector, Dyson Limited exemplifies cyclone airflow R&D intensity and direct-to-consumer control across Japan and Australia. Eureka Forbes anchors dealer-network density in Indian tier-1 cities through decades-old distribution infrastructure. Samsung Electronics Co. Ltd occupies the smart-home ecosystem integration position, embedding vacuum robots within broader IoT platforms to anchor customer loyalty.
| Leading Market Players |
|---|
| Eureka Forbes |
| Haier Group Corporation |
| Dyson Limited |
| iRobot Corporation |
| Samsung Electronics Co. Ltd |
| Electrolux AB |
| Groupe SEB |
| Panasonic Holdings Corporation |
| Bissell Inc. |
| Others |
Value Chain & Pricing Dynamics
Lithium-ion battery cell substitution for nickel-metal hydride power systems is redrawing procurement geography toward Chinese industrial clusters while compressing margin structures across cordless and robotic product tiers. This input transition simultaneously elevates working capital requirements for assemblers and concentrates pricing power among cell manufacturers with captive cathode material access.
Pricing Analysis
Cost-plus contracts with quarterly lithium carbonate indexation dominate procurement between battery suppliers and vacuum OEMs. Three-tier pricing structure across premium, standard, and economy levels reflects GB 4706.7-2014 certification status and HEPA filtration performance tiers. Pricing pressure stems from SAMR energy efficiency labeling compliance costs that smaller manufacturers cannot absorb. Price-sensitive buyers in Indian tier-2 cities prioritize economy-tier corded canister units, while Tokyo apartment dwellers accept premium robotic pricing for SLAM-enabled navigation.
Supply Chain Analysis
China anchors lithium-ion cell production through CATL and BYD manufacturing bases in Fujian and Guangdong provinces. South Korea and Japan supply precision brushless motors and HEPA filtration media that feed from specialized component ecosystems. Single-source vulnerability concentrates in NCM cathode precursor refining where Chinese refiners control processing capacity. Distribution runs through regional electronics retail chains in Japan and Australia, direct-to-consumer platforms in urban China, and dense dealer networks across Indian tier-1 cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SLAM algorithm engineering talent scarcity constrains product development velocity across the competitive set, with poaching from automotive autonomous driving divisions inflating compensation costs beyond mid-tier specialist reach.
For Market Incumbents: Secure exclusive SLAM software licensing agreements with Shenzhen and Bangalore robotics engineering studios before automotive competitors expand hiring. Defend margin position by backward integration into lithium cell pack assembly within Indian PLI scheme corridors, reducing exposure to Chinese component tariff volatility. Accelerate GB 4706.7-2014 pre-certification for next-generation cordless stick platforms to maintain retail shelf placement as SAMR tightens enforcement timelines. For New Entrants and Emerging Players: BIS fast-track certification through Indian testing laboratories opens six-to-nine month market access acceleration versus standard registration timelines. Target Vietnam and Indonesia manual-tool replacement cycles where rising disposable incomes outpace established brand presence. Enter through cleaning services fleet procurement channels in Australian urban centers, offering commercial durability warranties that differentiate from household-focused incumbents. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors component-integrated platform players over pure-brand marketing operations. Long-term viability rests on captive battery supply and IoT ecosystem embedding rather than cyclone technology differentiation alone. Acquisition target archetype: mid-market robotic OEMs with SLAM navigation IP and established GB certification but underutilized Indian distribution infrastructure. Signal to watch: PLI scheme capacity utilization rates crossing threshold levels that trigger tariff protection relaxation for Chinese component imports.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Expansion | Dyson's online-first warranty model in Japan and Australia bypasses traditional dealer economics. |
| SLAM Algorithm In-House Development | Samsung's IoT platform embedding captures navigation data for broader smart-home ecosystem loyalty. |
| GB 4706.7-2014 Pre-Certification Investment | Early compliance secures retail shelf placement as SAMR collapses non-compliant supplier base. |
| Indian PLI Scheme Manufacturing Footprint | Local assembly reduces BIS registration lag and tariff exposure on Chinese lithium cells. |
| HEPA-Sealed Disposal System R&D | Allergy-sensitive households in Tokyo and Osaka command pricing premiums for bagged format innovation. |
Study Parameters
Desk research of customs trade databases, SAMR certification registries, and METI Top Runner compliance filings preceded structured interviews with product development directors at Japanese and South Korean appliance manufacturers, supply chain managers at Guangdong-based OEMs, and category buyers at Australian electronics retail chains. Primary fieldwork with Indian dealer network operators and Vietnamese distributor principals validated secondary estimates of manual-to-powered appliance upgrade trajectories. Bottom-up unit shipment modeling triangulated against top-down consumer expenditure surveys across the analysis window.
Variance decomposition across product type, technology tier, and regional regulatory cluster shaped the analytical framework. CAGRs derived from logistic diffusion curves fitted to robotic vacuum adoption rates in compact urban dwellings, with cordless stick format penetration calibrated against lithium-ion energy density improvement curves. Forecast inputs incorporated BIS registration timeline distributions, PLI scheme capacity buildout schedules, and SLAM algorithm cost reduction trajectories throughout the projection horizon.
Underlying assumptions cover sustained lithium supply from Chinese industrial clusters, stable GB standard enforcement intensity, and incremental METI efficiency threshold escalation, with deviation risk concentrated in geopolitical friction affecting component access and abrupt SAMR certification timeline compression. Recalibration cycles align with material shifts in PLI scheme disbursement patterns and robotic navigation technology cost curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Smart Connected Water Purifier Market
Household Items
Soap Dispenser Market
Household Items
US Hand Dryers Market
Household Items
Indoor Humidifier Market
Household Items
Electric Soap Dispenser Market
Household Items
Cookware Market
Household Items
Smart Fridge Market
Household Items
Stainless Steel Vacuum Flask Market
Household Items
Air Freshener Market
Household Items
Industrial Floor Mats Market
Household Items
India Air Purifier Market
Household Items
Middle East and Africa Air Purifier Market
Household Items
Residential Water Purifier Market
Household Items
Smart Fork Market
Household Items
Infuser Water Bottles Market
Household Items
Neck Pillows Market