
 Bounce House Market | 2026-2036
Bounce House Market Size, Share, and Industry Trends Forecast 2026-2036
Bounce House Market Analysis
Event planner consolidation across the United States is repositioning procurement power toward larger corporate hospitality firms that negotiate multi-unit bounce house contracts for seasonal festival circuits. Blast Zone leverages direct-to-consumer channel control to sustain margins in the residential segment. Jungle Jumps anchors its position through specialized manufacturing of commercial-grade units with reinforced stitching protocols. Moonwalk USA competes by dominating the rental operator aftermarket with replacement part availability and repair services.
Bounce houses are sealed inflatable structures fabricated from PVC-coated vinyl or laminated nylon, engineered to maintain structural integrity under dynamic load conditions through continuous blower airflow systems. Their primary commercial purpose is to provide contained recreational environments for supervised physical activity at temporary events and permanent entertainment venues. The commercial product type leads in absolute revenue contribution due to higher unit values and replacement frequency, while the residential category exhibits faster volume expansion as backyard ownership normalizes post-pandemic. Material segmentation shows vinyl sustaining the largest share owing to puncture resistance and UV stability, though polyurethane blends are gaining traction in premium water slide configurations where flex-fatigue performance matters.
ASTM F2374 and its state-level adoptions through California's Department of Industrial Relations and Texas Department of Insurance shape product certification requirements, effectively filtering non-compliant imports from market access. The Consumer Product Safety Commission maintains active recall monitoring and incident reporting databases that influence manufacturer liability exposure and insurance underwriting standards. Stakeholders must monitor evolving municipal permitting frameworks for public park installations, as these local ordinances increasingly dictate anchoring specifications and operator training mandates that cascade back to product design requirements.
Market Dynamics
ASTM F2374's tightening flame-resistance and anchoring mandates are forcing manufacturers to reformulate material compositions and redesign blower-attachment systems, compressing margins for non-specialized suppliers while rewarding vertically integrated producers with captive testing capabilities.
Growth Catalysts
- Municipal Park Modernization:School districts across the United States are replacing aging playground infrastructure with commercial-grade inflatable installations, creating steady institutional procurement pipelines.
- REACH-Compliant Material Substitution:European operators are accelerating vinyl replacement cycles to meet evolving phthalate restrictions, driving aftermarket demand for certified component systems.
- Family Entertainment Center Diversification:FEC operators are expanding inflatable attraction portfolios beyond traditional arcade revenue streams, prioritizing high-throughput obstacle courses and interactive sport configurations.
Market Restraints
- PVC Resin Price Volatility:Petrochemical feedstock fluctuations directly compress manufacturing margins for vinyl-dominant product lines, forcing pass-through pricing to rental operators.
- Chinese Component Concentration:Blower motor and continuous airflow system supply chains cluster in Guangdong province, exposing procurement to tariff and logistics disruption risks.
- ASTM F2374 Compliance Friction:State-level adoption variations through California's Department of Industrial Relations and Texas Department of Insurance create fragmented certification requirements that filter non-compliant imports from market access.
Strategic Opportunities
- Polyurethane Water Slide Premiumization:Polyurethane blends are gaining traction in premium water slide configurations where flex-fatigue performance matters, commanding higher unit values than standard vinyl alternatives.
- Direct-to-Consumer Channel Expansion:Residential segment normalization post-pandemic is enabling manufacturers to bypass rental operator intermediaries and capture margin through owned e-commerce platforms.
- IRAH-Eligible Commercial Installations:United States municipal park districts can access federal infrastructure funding for ADA-compliant recreational equipment, redirecting procurement toward certified commercial-grade bounce house systems.
Industry Challenges
- Certification Timeline Compression:ASTM F2374 testing protocols and state-level permitting frameworks are extending product launch cycles, requiring manufacturers to maintain larger pre-certified inventory buffers.
- Anchor System Integration Complexity:Evolving municipal anchoring specifications demand engineering coordination between inflatable fabricators and site-specific soil engineers, fragmenting project delivery timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bounce House Market |
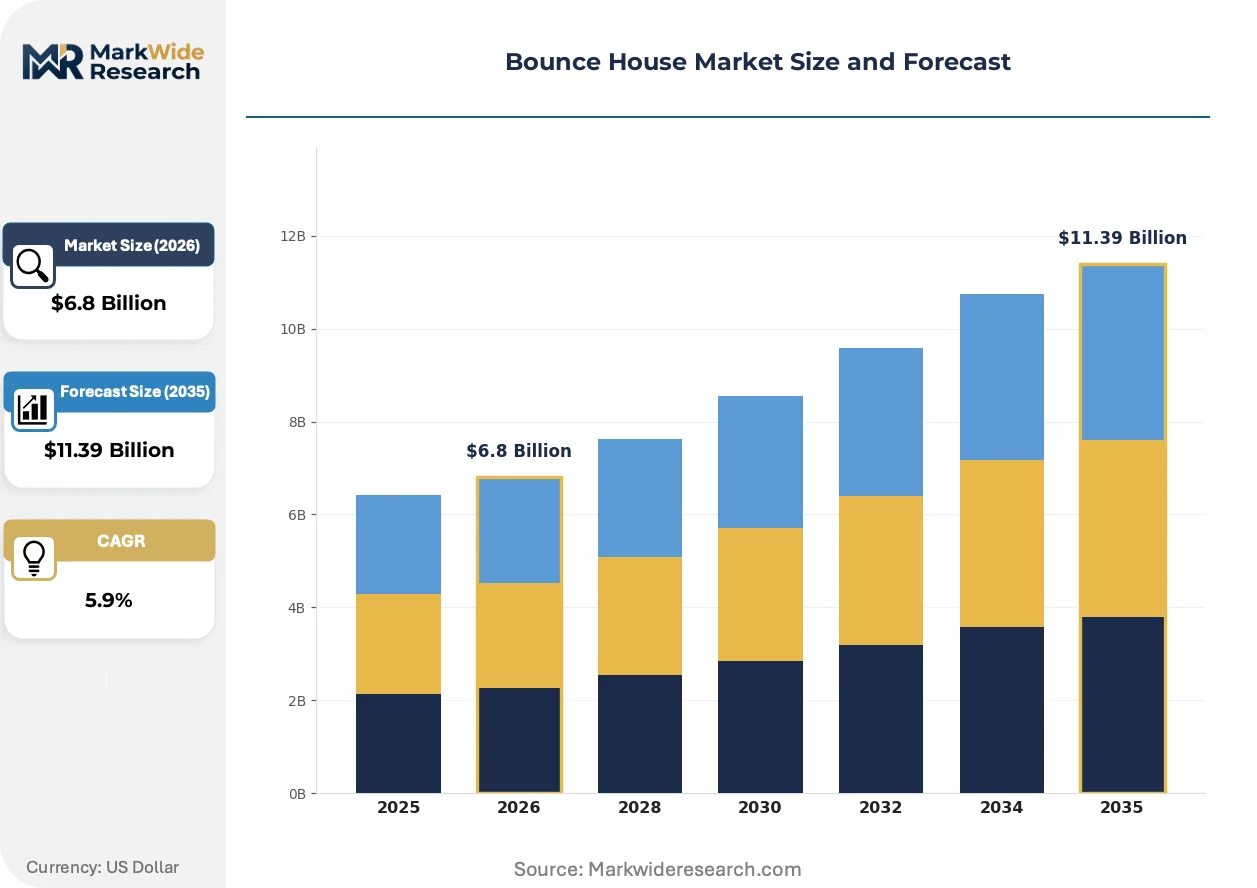
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.39 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Commercial, Residential, Inflatable Slides, Water Slides End User: Event Planners, Schools, Rental Companies, Family Entertainment Centers Material: Vinyl, Nylon, Polyurethane, PVC Age Group: Children, Teens, Adults, Mixed Age |
| Companies Covered | Blast Zone, Bounceland, JumpOrange, Happy Jump, Jungle Jumps, Big Top Inflatables, Moonwalk USA, Inflatable HQ, AirMyFun, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bounce House Market Emerging Trajectories
Digital blower control systems and smart pressure monitoring are converging with traditional inflatable fabrication, enabling predictive maintenance models that reshape rental operator asset management practices.
Pressure-sensing blower technology is unifying airflow regulation with real-time structural integrity monitoring. United States-based rental operators with fleet sizes exceeding fifty units are adopting these systems fastest. This convergence is unifying equipment uptime guarantees with insurance underwriting data, compressing traditional inspection cycles into continuous remote monitoring protocols.
ASTM International is expanding F2374 scope to address interactive inflatable sport configurations and obstacle course elements. Manufacturers serving the United States market must now certify multi-activity structures under unified rather than component standards. Commercial-grade product lines face the steepest compliance recertification burdens, with California and Texas adopting divergent enforcement timelines.
Corporate hospitality firms are consolidating event procurement through multi-unit seasonal contracts, displacing fragmented single-rental transactions. Festival circuit operators in the United States now negotiate directly with manufacturers for dedicated inventory pools. This concentration is most visible in the southwestern United States, where municipal fair circuits and private festival operators have merged purchasing functions under shared logistics providers.
Bounce House Market Segmentation
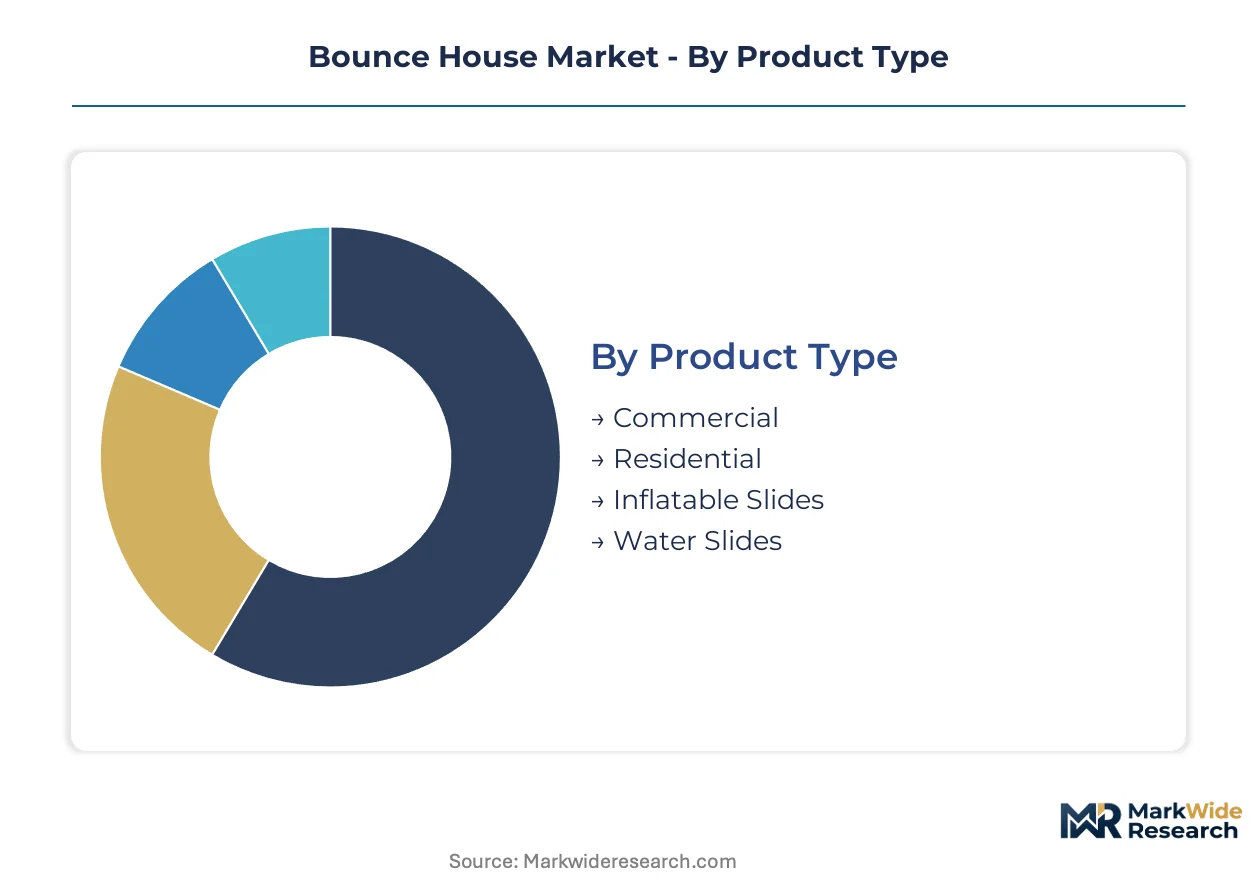
ASTM F2374 compliance requirements fragment across product categories, forcing manufacturers to maintain separate certification portfolios for commercial versus residential lines. Material specifications and end-use applications further complicate procurement decisions, as municipal purchasers demand flame-resistant vinyl while residential buyers prioritize portability over certification depth.
Product Type:
ASTM F2374 mandates diverge sharply across this dimension, with commercial units requiring continuous blower certification and residential products facing lighter anchoring protocols.
- Commercial:PVC-coated vinyl structures engineered for continuous blower operation under dynamic load conditions. Municipal park districts and school systems in the United States concentrate procurement here, driven by institutional liability requirements and ADA accessibility mandates.
- Residential:Laminated nylon configurations designed for intermittent backyard use with smaller footprint blowers. Post-pandemic ownership normalization in United States suburban markets accelerates volume expansion, though unit values trail commercial equivalents significantly.
- Inflatable Slides:Dual-lane configurations with integrated climb surfaces and slide planes.
- Water Slides:Polyurethane-blend constructions targeting premium backyard installations.
Commercial sits at the top of the volume ranking, with Residential climbing the fastest.
End User:
Procurement scale and contract structure vary dramatically across customer types, from fragmented single-event rentals to consolidated multi-season festival circuits.
- Event Planners:Corporate hospitality firms negotiating dedicated inventory pools for seasonal festival circuits. Southwestern United States operators have merged purchasing functions under shared logistics providers, compressing vendor margins through volume concentration.
- Schools:Public district procurement pipelines accessing IRAH-eligible federal infrastructure funding. ADA-compliant recreational equipment mandates redirect capital expenditure toward certified commercial-grade systems with documented anchor engineering.
- Rental Companies:Fleet operators with fifty-plus units adopting pressure-sensing blower technology for predictive maintenance.
- Family Entertainment Centers:Diversification beyond arcade revenue streams into high-throughput obstacle configurations.
Rental Companies capture the largest absolute procurement scale, with Family Entertainment Centers expanding most quickly.
Material:
REACH phthalate restrictions and ASTM flame-resistance mandates are accelerating substitution timelines across European and North American supply chains.
- Vinyl:PVC-coated formulations sustaining dominant share through puncture resistance and UV stability. REACH-compliant substitution cycles in Europe drive aftermarket demand for certified component systems as operators replace legacy inventory.
- Polyurethane:Premium water slide configurations where flex-fatigue performance commands higher unit values than standard vinyl alternatives. California and Texas adoption timelines for updated F2374 scope create divergent certification windows.
- Nylon:Lightweight residential applications prioritizing portability over durability.
- PVC:Base resin formulations facing petrochemical feedstock price volatility.
Vinyl maintains the steepest volume position, with Polyurethane gaining share fastest in premium configurations.
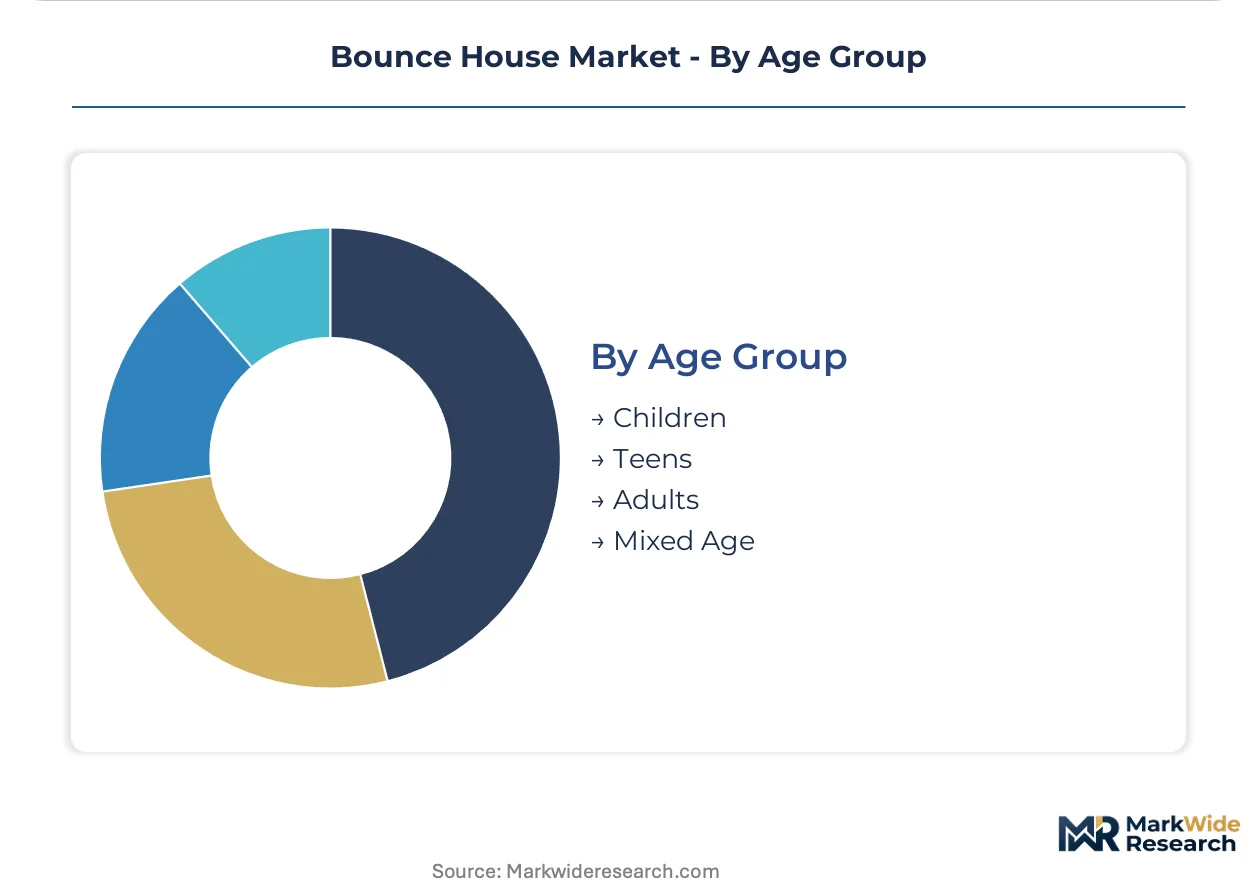
Age Group:
Structural load specifications and activity containment requirements scale directly with user size and physical capability.
- Children:Lower wall heights and reduced blower pressure specifications dominate institutional procurement for elementary school installations. United States municipal park districts specify these configurations for supervised public access environments.
- Teens:Intermediate load ratings supporting competitive sport configurations and obstacle course elements. ASTM F2374 expanded scope now requires unified rather than component certification for multi-activity structures.
- Adults:Reinforced stitching protocols and elevated anchoring specifications for corporate event and fitness applications.
- Mixed Age:Modular designs with adjustable pressure zones accommodating simultaneous use across age cohorts.
Children occupies the highest procurement volume, with Mixed Age showing the steepest expansion trajectory as multi-generational entertainment venues proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized manufacturing clusters in Guangdong province anchor global blower motor production, while municipal procurement teams in United States park districts concentrate institutional demand.
United States
Municipal park districts and school systems drive commercial-grade procurement through IRAH-eligible federal infrastructure funding. ASTM F2374 compliance requirements filter non-compliant imports from market access. Dallas and Houston rental operators negotiate multi-unit seasonal contracts for southwestern festival circuits.
China
Guangdong province hosts concentrated blower motor and continuous airflow system manufacturing. GB standards and export certification requirements shape product specifications for international shipment. Shenzhen and Dongguan industrial clusters supply component systems to North American and European assemblers.
Germany
REACH phthalate restrictions accelerate vinyl replacement cycles among European rental operators. ECHA chemical safety protocols drive certified component aftermarket demand. Bavarian manufacturing centers produce flame-resistant material formulations for institutional export markets.
Canada
Municipal recreation departments in Ontario and British Columbia replace aging playground infrastructure with commercial inflatable installations. Health Canada product safety monitoring influences manufacturer liability exposure. Toronto-based event planners consolidate procurement through corporate hospitality networks.
Mexico
Northern border states serve as logistics hubs for United States-bound component shipments. Local municipal governments expand family entertainment center permitting frameworks. Monterrey industrial parks host assembly operations for North American distribution.
Bounce House Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across material fabrication, blower systems, and rental operations. The vendor base spans vertically integrated manufacturers with captive testing capabilities and fragmented regional assemblers dependent on imported components. Three archetypes dominate: residential direct-to-consumer brands, commercial-grade specialists with reinforced fabrication protocols, and rental operator service providers with replacement part networks. Competitive moves center on ASTM F2374 certification pre-positioning and municipal procurement relationship cultivation.
Among United States-based fabricators, Blast Zone, Jungle Jumps, and Moonwalk USA occupy distinct positioning within the competitive structure. Blast Zone exemplifies the direct-to-consumer archetype with channel control strategies. Jungle Jumps anchors the commercial-grade specialist tier through manufacturing focus. Moonwalk USA represents the rental operator service model with aftermarket positioning. These three companies collectively illustrate the segmentation between residential volume plays, institutional quality tiers, and operator support ecosystems.
| Leading Market Players |
|---|
| Blast Zone |
| Bounceland |
| JumpOrange |
| Happy Jump |
| Jungle Jumps |
| Big Top Inflatables |
| Moonwalk USA |
| Inflatable HQ |
| AirMyFun |
| Others |
Supply Flow & Price Mechanics
Petrochemical feedstock indices for PVC resin establish baseline cost floors that cascade through three distinct pricing tiers, with certified commercial-grade units commanding premiums over residential alternatives while tariff exposure on Chinese blower components compresses margins at the mid-market tier.
Pricing Analysis
Capacity additions in Guangdong province are reshaping price floors for blower motor assemblies, forcing North American assemblers to absorb logistics premiums or pass through to rental operators. Three-tier pricing structure across premium, standard, and economy levels separates ASTM F2374-certified commercial units with documented anchor engineering from uncertified residential imports and refurbished fleet equipment. Price differentiation hinges on certification depth and volume scale, with municipal procurement pools extracting double-digit discounts through multi-season contracts. Cost compression in the standard tier is intensifying because REACH-compliant vinyl formulations carry European material premiums.
Supply Chain Analysis
Regional distribution centers in Dallas, Toronto, and Monterrey anchor hub-and-spoke patterns for North American fulfillment, with inventory buffers sized to ASTM F2374 recertification timelines. Manufacturing draws from China for blower systems, Germany for flame-resistant material formulations, and Vietnam for laminated nylon residential components. Raw material dependencies rest on PVC resin, polyurethane blends, and continuous airflow electronics. Single-source vulnerability concentrates in Guangdong province motor production. Distribution runs through rental operator fleets and direct-to-consumer e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
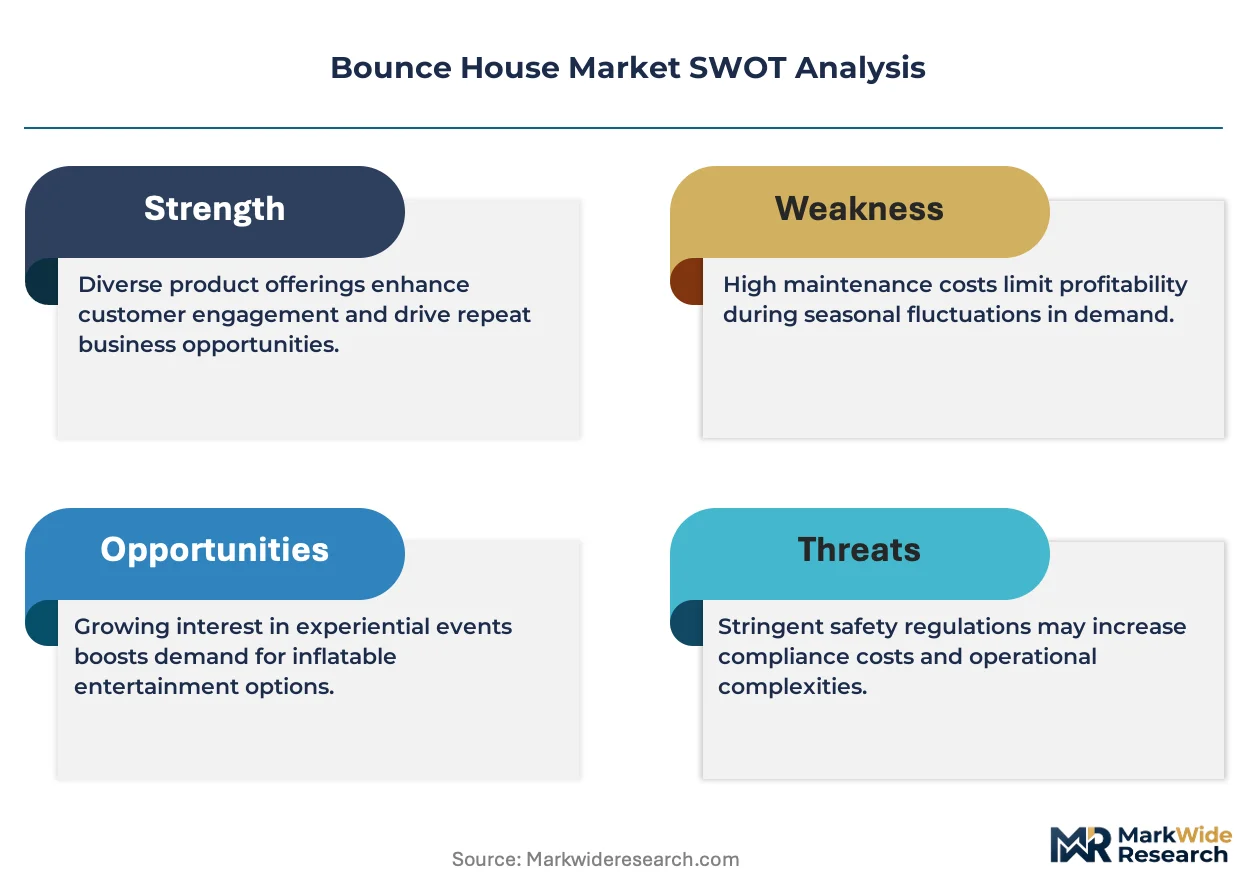
Margin expansion opportunities concentrate in premium-tier polyurethane water slide configurations and captive testing capabilities that filter non-compliant competitors from municipal procurement channels.
For Market Incumbents: Anchor market position through backward integration into blower system assembly and captive ASTM F2374 certification laboratories. Defend against emerging direct-to-consumer brands by locking multi-year exclusive supply contracts with consolidated event planner networks. Prioritize California and Texas regulatory pre-positioning ahead of divergent enforcement timelines. For New Entrants and Emerging Players: Smart pressure monitoring technology offers a technology-first wedge into rental operator fleet management services, bypassing capital-intensive fabrication. Target the residential segment's fastest volume expansion through owned e-commerce platforms with drop-ship fulfillment from Asian component suppliers. White-space exists in ADA-compliant municipal installations accessing IRAH-eligible federal infrastructure funding. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated fabricators holding captive testing capabilities and established municipal procurement relationships. Long-term viability favors producers with demonstrated compliance navigation across fragmented state-level adoption frameworks. Watch for inflection in municipal permitting velocity as indicator of institutional demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ASTM F2374 Certification Pre-Positioning | California and Texas adoption timelines create first-mover advantage in municipal procurement. |
| Backward Integration into Blower Assembly | Guangdong supply concentration exposes margins to tariff and logistics disruption risks. |
| Direct-to-Consumer Channel Launch | Post-pandemic residential normalization enables margin capture bypassing rental intermediaries. |
| Polyurethane Water Slide Premium Tier | Flex-fatigue performance commands higher unit values than standard vinyl alternatives. |
| Predictive Maintenance Platform Partnership | Pressure-sensing blower technology compresses inspection cycles into continuous remote monitoring. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific manufacturing clusters, with primary inputs from each region combined with secondary validation. Interviews with rental fleet operators, municipal procurement officers, inflatable fabricators, and ASTM compliance consultants anchored qualitative assessment. Secondary sources include customs trade data, CPSC recall databases, state-level permitting frameworks, and SEC filings from diversified conglomerates with inflatable exposure. Bottom-up unit economics triangulated against top-down market sizing.
Granularity-level framing modeled product type, material composition, end-user archetype, and geographic regulatory cluster at the country-state level. CAGRs derived from segment-level volume trajectories and value-per-unit assumptions across the projection horizon. Industry-specific inputs incorporated IRAH funding allocation patterns, REACH substitution cycle timelines, and blower motor import tariff exposure.
The model holds under stable petrochemical feedstock pricing and current tariff schedules; deviation in PVC resin volatility or Guangdong logistics disruption would shift volume and value outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Toys and Games
Male Sex Toys Market
Toys and Games
Remote Control Toys Market
Toys and Games
Dildo Sex Toy Market
Toys and Games
Toys and Games Market
Toys and Games
Remote Control Products - Hobby Market
Toys and Games
Cat Toys Market
Toys and Games
Fabric Toys Market
Toys and Games
Global Stem Toys Market
Toys and Games
Wooden Toys Market
Toys and Games
Plastic Toy Storage Market
Toys and Games
Action Figures Market
Toys and Games
Global Fidget Toys Market
Toys and Games
K-12 Instructive Toy Market
Toys and Games
Global Educational Toy Market
Toys and Games
Toy Building Blocks Market
Toys and Games
United States Toys Market