
 Soap Dispenser Market | 2026-2036
Soap Dispenser Market Size, Share, and Industry Trends Forecast 2026-2036
Soap Dispenser Market Intelligence
Refill-subscription programs is decoupling hardware from recurring revenue in the soap dispenser industry. GOJO Industries leverages its institutional distribution network to anchor recurring supply contracts across healthcare systems. Rubbermaid Commercial Products sustains manufacturing scale through vertical control over polymer molding operations. Simplehuman differentiates via sensor-calibration technology that reduces battery waste in premium residential units.
A soap dispenser is a liquid-delivery device engineered with piston pumps, infrared sensors, or gravity-fed reservoirs to dispense measured volumes of soap or sanitizer; stainless steel variants withstand chloride exposure in food-processing environments while automatic units deploy piezoelectric sensors with activation thresholds below 100 milliseconds. Plastic manual dispensers still occupy the largest installed base in budget-sensitive school districts, though touch-free automatic units represent the fastest-growing margin pool as hospitals prioritize cross-contamination protocols. Wall-mounted configurations dominate commercial washroom specifications, while countertop designs lead residential renovation channels through design-forward aesthetics.
EPA WaterSense certification and FDA sanitation standards govern product performance claims in the United States, while the EU Ecodesign Directive and CE marking regulate energy consumption and material safety for automatic units sold across Europe. China's GB standards for antimicrobial plastics and SAMR quality inspections create divergent compliance pathways for exporters. Stakeholders must monitor how building-code harmonization between national regulators affects modular retrofit demand versus full-fixture replacement cycles.
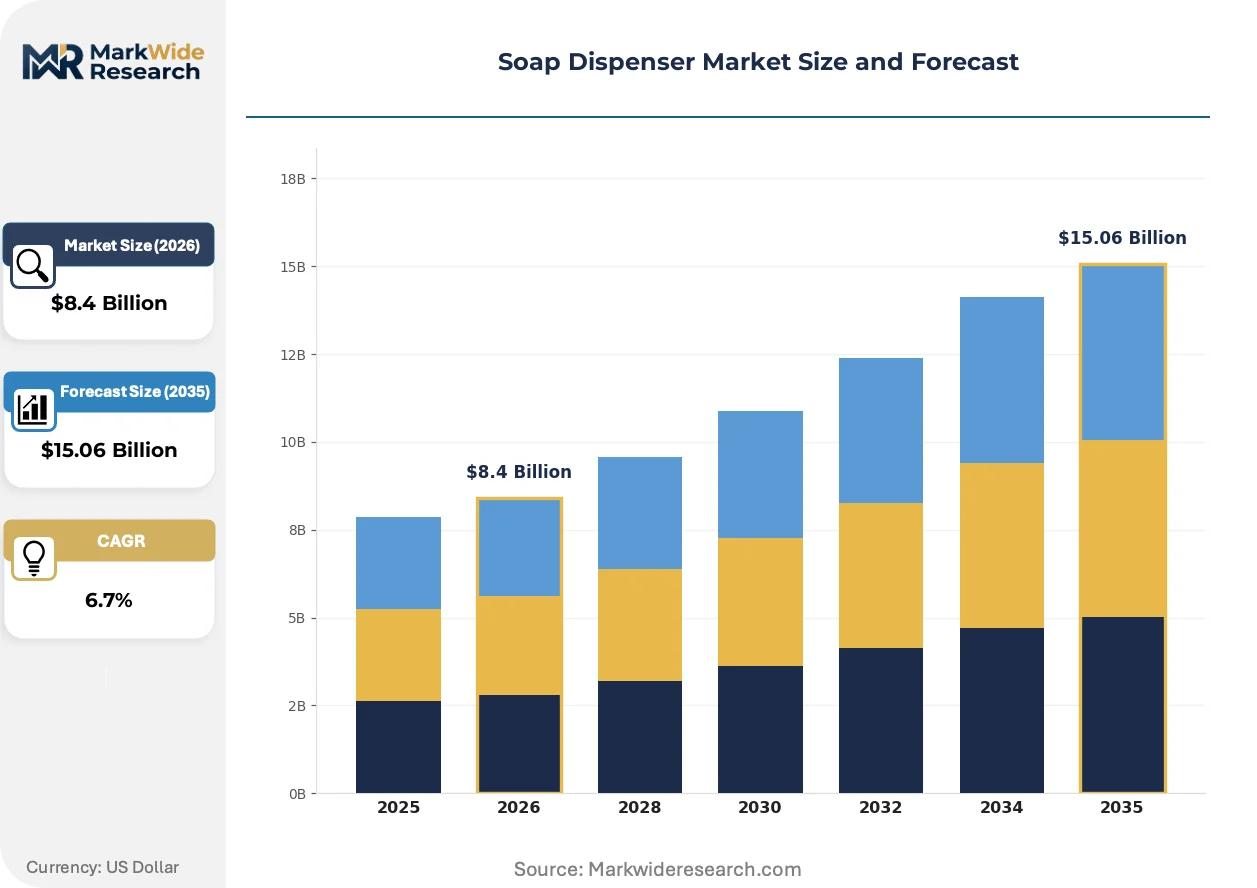
Market Dynamics
The soap dispenser market is restructuring around infection-control mandates in healthcare facilities and the decoupling of hardware sales from recurring consumable revenue through subscription-based refill programs. These forces are compressing traditional capital-equipment cycles while extending vendor-customer relationships across multi-year supply contracts.
Growth Catalysts
- Healthcare Infection Protocols:Joint Commission accreditation standards in the United States now mandate touch-free dispensing in acute-care settings. Hospital procurement teams prioritize sensor-activated units to reduce cross-contamination risks.
- Commercial Building Codes:Germany's federal sanitation regulations require touch-free fixtures in all public washrooms constructed after 2024. Municipal enforcement drives replacement demand across airports, transit hubs, and government buildings.
- Sensor Miniaturization:Piezoelectric infrared modules with sub-100-millisecond activation thresholds enable battery-efficient automatic dispensing. This technology reduces maintenance intervals in high-traffic facilities.
Market Restraints
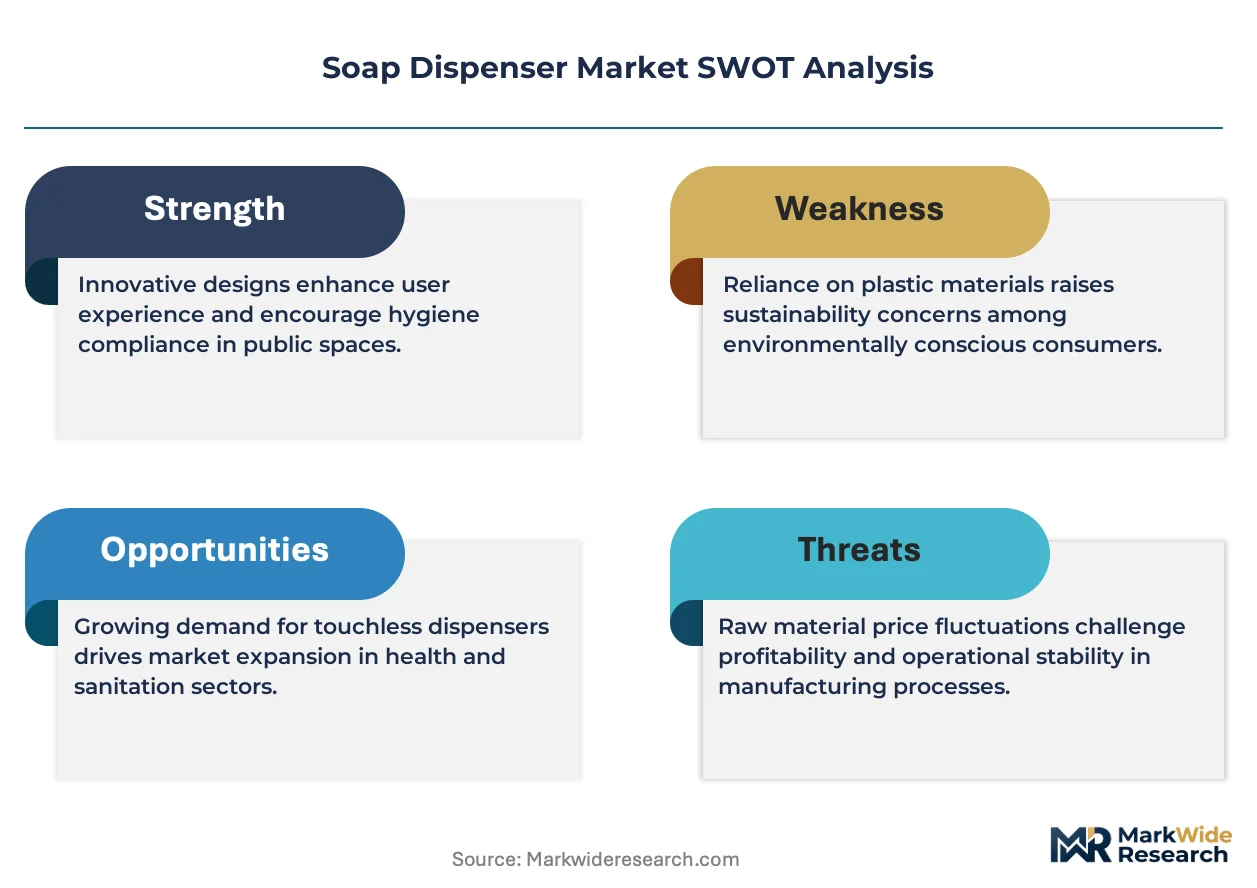
- Polymer Resin Volatility:ABS and polypropylene feedstock prices fluctuate with crude oil derivatives. Dispensers with high plastic content face margin compression during petrochemical supply disruptions.
- Supply Concentration Risk:Precision sensor modules for automatic units concentrate among Taiwanese and South Korean component suppliers. Geographic clustering creates vulnerability to regional logistics constraints.
- Manual Dispenser Entrenchment:Budget-constrained school districts and municipal facilities retain plastic pump dispensers with decade-long replacement cycles. This installed base slows premium automatic adoption in the education vertical.
Strategic Opportunities
- India Sanitation Infrastructure:Swachh Bharat Mission expansion funds public washroom construction in tier-2 and tier-3 cities. BIS certification for antimicrobial plastics creates compliant supply pathways for automatic dispenser manufacturers.
- Subscription Commerce Integration:Direct-to-consumer refill programs bypass traditional retail shelf space constraints. Residential buyers accept recurring charges for concentrated soap cartridges paired with premium sensor hardware.
- IoT Convergence:Cloud-connected dispensers with usage-analytics capabilities merge facility management software with consumable replenishment. This convergence enables predictive maintenance contracts in hospitality and corporate campus settings.
Industry Challenges
- Multi-Jurisdiction Certification Burden:Automatic units require simultaneous EPA WaterSense validation, FCC electromagnetic compliance, and FDA sanitation claims verification for US market entry. Parallel testing extends product launch timelines by 8-14 months.
- Legacy Fixture Integration Complexity:Retrofit installations must accommodate non-standard wall cavity depths and electrical rough-in configurations from 1980s-1990s construction. Custom mounting hardware strains project profitability for renovation contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soap Dispenser Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.06 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Automatic, Wall-mounted, Countertop Material: Plastic, Stainless Steel, Glass, Aluminum End User: Hospitals, Restaurants, Schools, Offices Distribution Channel: Online, Retail, Direct Sales, Wholesale |
| Companies Covered | Bobrick Washroom Equipment, Rubbermaid Commercial Products, GOJO Industries, Umbra, Kimberly-Clark Corporation, TOTO Ltd., American Specialties, Sloan Valve Company, Simplehuman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soap Dispenser Market Strategic Shifts & Innovations
Sensor calibration algorithms and antimicrobial surface coatings are compressing the performance gap between premium and mid-tier automatic dispensers. These advances are forcing hardware manufacturers to differentiate through software-enabled service layers rather than physical specifications alone.
Piezoelectric proximity detection with adaptive sensitivity adjustment is automating dose-volume optimization based on hand positioning. Food-processing plants in the United States and Germany are adopting these units to minimize soap waste while maintaining HACCP compliance. The technology is automating the shift from fixed-output pumps to variable-dispensing systems that reduce consumable costs by 15-25 percent in high-volume environments.
EPA WaterSense certification requirements for flow-rate limits and leak-prevention testing are tightening product development specifications. Manufacturers must redesign internal valve mechanisms to pass accelerated lifecycle testing under chlorinated water exposure. Healthcare and hospitality segments in California and Texas face the steepest compliance ramps as state procurement codes adopt federal efficiency benchmarks ahead of national mandates.
Facility managers are consolidating vendor relationships around full-spectrum hygiene contracts that bundle dispensers, consumables, and waste removal. This consolidation displaces fragmented purchasing across separate maintenance, procurement, and infection-control departments. The pattern is most pronounced in United Kingdom NHS trusts and United States hospital systems pursuing GPO-negotiated enterprise agreements.
Soap Dispenser Market Segmentation
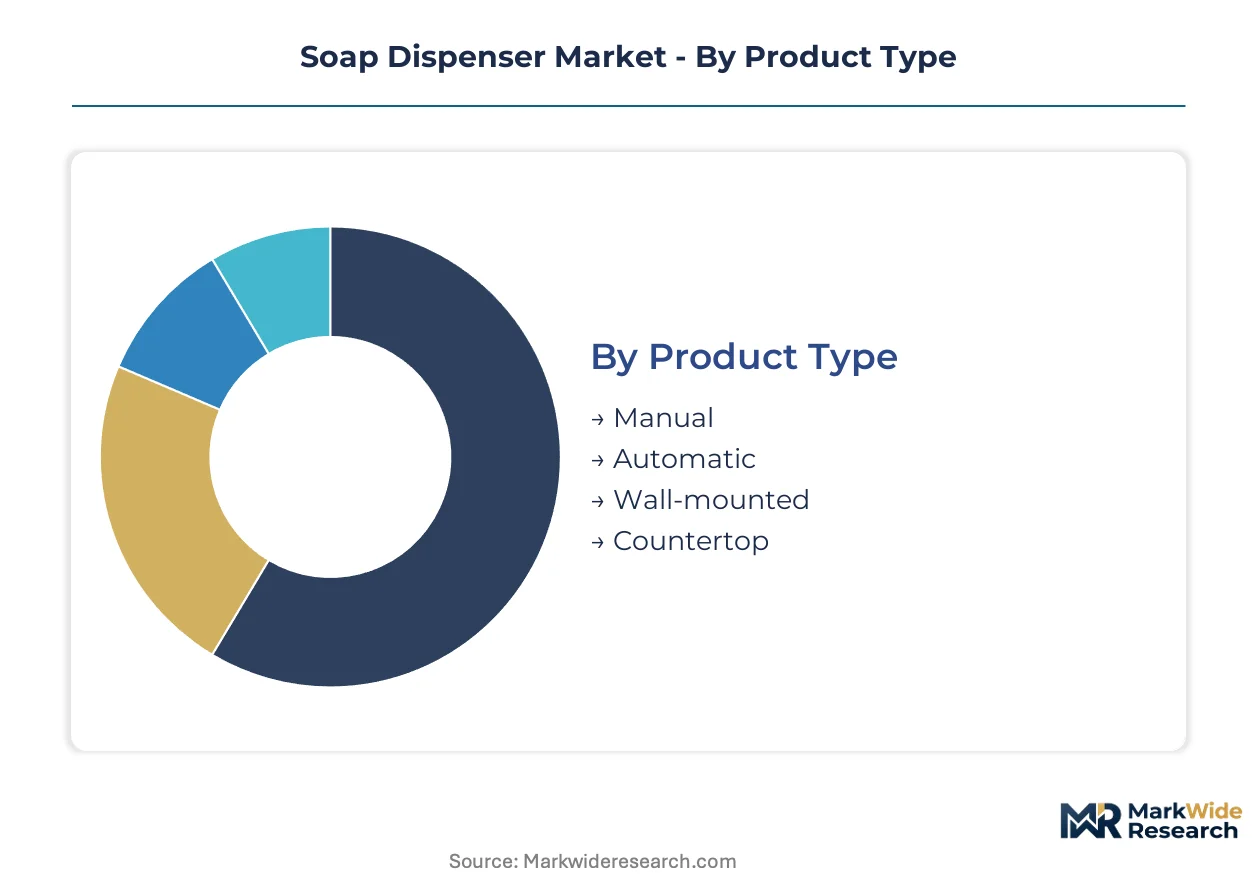
Segmentation in the soap dispenser market reveals divergent procurement logics across healthcare, foodservice, and education verticals. Product specifications, material durability requirements, and channel economics fragment demand into distinct competitive arenas with incompatible vendor capabilities.
Product Type:
Standardization dominates budget channels while customization concentrates in premium healthcare and hospitality specifications.
- Manual:Piston-pump mechanisms with ABS or polypropylene housings deliver fixed-volume dosing without electrical components. Schools and municipal facilities in budget-constrained districts retain these units for decade-long replacement cycles, slowing automatic adoption in the education vertical.
- Automatic:Piezoelectric infrared sensors with sub-100-millisecond activation thresholds enable touch-free dispensing. Hospital procurement teams in the United States prioritize these units under Joint Commission accreditation standards mandating sensor-activated systems to reduce cross-contamination risks.
- Wall-mounted:Flush or surface-mounted configurations integrate with commercial washroom specifications. These units dominate airport, transit hub, and government building installations where space optimization and vandal resistance matter.
- Countertop:Freestanding designs with design-forward aesthetics lead residential renovation channels. Premium sensor-calibration technology reduces battery waste in high-end residential units.
Most installed capacity flows through Manual dispensers. Expansion is steepest in Automatic.
Material:
Cost tier stratification separates commodity polymer supply from specialty metal fabrication serving regulated environments.
- Plastic:ABS and polypropylene variants dominate volume production through injection molding. Budget-sensitive school districts and quick-service restaurants favor these units despite vulnerability to UV degradation and chloride exposure.
- Stainless Steel:304 and 316-grade alloys withstand chloride exposure in food-processing environments. Germany's commercial building codes and United States FDA sanitation standards drive specification of these units in HACCP-compliant facilities.
- Glass:Borosilicate or soda-lime reservoirs enable visual soap-level monitoring. Boutique hospitality settings and premium residential bathrooms specify these for aesthetic differentiation.
- Aluminum:Anodized or powder-coated finishes balance weight reduction with corrosion resistance. These units occupy a mid-tier position between plastic economy and stainless steel premium segments.
Plastic holds the largest installed base. Stainless Steel commands the steepest expansion trajectory in regulated commercial environments.
End User:
Application-specific compliance requirements fragment vendor relationships across infection-control, food-safety, and budget-optimization priorities.
- Hospitals:Acute-care settings mandate touch-free dispensing under accreditation standards. Procurement teams bundle these units with recurring supply contracts for antimicrobial soap formulations.
- Restaurants:HACCP compliance and FDA sanitation standards govern specification. Fast-casual chains balance upfront hardware costs against consumable replenishment economics.
- Schools:Decade-long capital replacement cycles and maintenance staff capacity constraints favor manual pump dispensers. District procurement prioritizes durability over sensor technology.
- Offices:Corporate campus facility managers consolidate vendor relationships around full-spectrum hygiene contracts bundling dispensers, consumables, and waste removal.
Hospitals anchor premium specification. Offices are expanding most quickly through IoT-enabled predictive maintenance contracts.
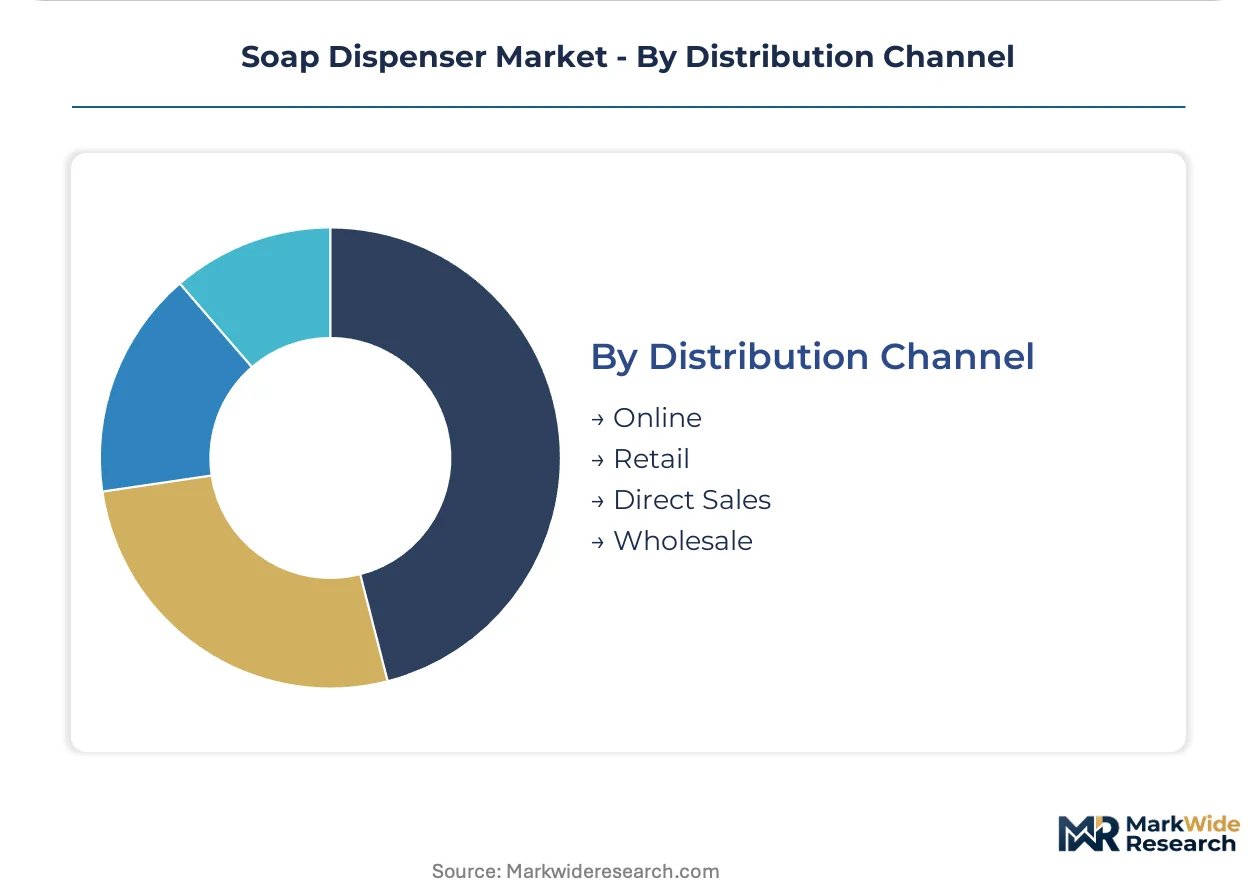
Distribution Channel:
Channel economics reshape margin capture as subscription commerce bypasses traditional retail shelf constraints.
- Online:Direct-to-consumer refill programs pair premium sensor hardware with concentrated soap cartridge subscriptions. Residential buyers accept recurring charges bypassing retail markups.
- Retail:Big-box and specialty home goods stores stock countertop designs for renovation-driven purchase. Shelf space constraints limit SKU breadth to proven volume movers.
- Direct Sales:Institutional distribution networks anchor recurring supply contracts across healthcare systems. Field sales teams negotiate multi-year enterprise agreements with procurement and infection-control departments.
- Wholesale:Janitorial supply distributors serve contractor and facility maintenance channels. These intermediaries aggregate fragmented demand from smaller commercial accounts.
Wholesale moves the largest unit volume. Online is gaining share fastest through subscription commerce integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany mandates touch-free fixtures in public washrooms while the United States drives hospital procurement through Joint Commission standards. These regulatory divergences create distinct competitive arenas across developed markets.
United States
Hospital systems in California and Texas consolidate vendor relationships around full-spectrum hygiene contracts bundling dispensers, consumables, and waste removal. EPA WaterSense certification and FDA sanitation standards govern product performance claims. The Joint Commission accreditation standards mandate touch-free dispensing in acute-care settings, driving sensor-activated unit adoption in the Northeast and Midwest hospital clusters.
Germany
Federal sanitation regulations require touch-free fixtures in all public washrooms constructed after 2024, driving replacement demand across airports and transit hubs. The EU Ecodesign Directive and CE marking regulate energy consumption and material safety for automatic units. Industrial fabricators in North Rhine-Westphalia and Bavaria supply stainless steel variants for HACCP-compliant food-processing environments.
China
GB standards for antimicrobial plastics and SAMR quality inspections create divergent compliance pathways for domestic and export-oriented manufacturers. The MIIT promotes sensor miniaturization through industrial upgrading programs. Production clusters in the Yangtze River Delta and Pearl River Delta concentrate precision sensor module assembly for automatic dispenser exports.
India
Swachh Bharat Mission expansion funds public washroom construction in tier-2 and tier-3 cities, creating demand for cost-optimized automatic units. BIS certification for antimicrobial plastics establishes compliant supply pathways for dispenser manufacturers. Maharashtra and Gujarat host emerging fabrication capacity serving domestic institutional procurement.
Japan
METI efficiency standards and JIS quality certifications shape premium product specifications for hospitality and corporate campus segments. Sensor-calibration technology development concentrates in the Kanto and Kansai industrial corridors. Tokyo-based facility managers prioritize IoT-connected dispensers with usage-analytics capabilities for predictive maintenance contracts.
Soap Dispenser Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with institutional channels favoring established hygiene brands while residential renovation channels reward design-forward positioning. The vendor base organizes around three tiers: multinational hygiene conglomerates with captive distribution, mid-scale specialists with vertical control over polymer molding or sensor integration, and regional fabricators serving price-sensitive municipal procurement. Consolidation pressures concentrate in the middle tier as sensor module costs decline and subscription commerce erodes traditional wholesale margins. Strategic moves center on backward integration into consumable formulation and forward integration into facility management software.
Among US-based hygiene specialists, GOJO Industries and Kimberly-Clark Corporation exemplify the institutional-channel archetype with recurring supply contract structures. Rubbermaid Commercial Products occupies a position representing manufacturing-scale players with in-house polymer molding operations. Simplehuman anchors the premium residential tier through design-forward positioning and direct-to-consumer subscription integration.
| Leading Market Players |
|---|
| Bobrick Washroom Equipment |
| Rubbermaid Commercial Products |
| GOJO Industries |
| Umbra |
| Kimberly-Clark Corporation |
| TOTO Ltd. |
| American Specialties |
| Sloan Valve Company |
| Simplehuman |
| Others |
Cost & Logistics Intelligence
ABS resin and polypropylene pellet costs cascade through three distinct pricing tiers as they move from Yangtze River Delta petrochemical complexes through injection molding operations to finished dispenser assemblies. Crude oil derivative volatility compresses margins at the economy tier while stainless steel alloy premiums insulate German and Japanese fabricators serving HACCP-regulated food processing facilities.
Pricing Analysis
Capacity additions in China's precision sensor module clusters are reshaping price floors for automatic dispenser assemblies. Three-tier pricing structure across premium, standard, and economy levels separates subscription-integrated hardware from basic pump mechanisms. Price differentiation hinges on EPA WaterSense certification grade and sensor calibration precision. Cost compression in the plastic manual tier is intensifying because school district procurement prioritizes decade-long replacement cycles over feature upgrades. Municipal facilities exhibit the highest price sensitivity; hospital systems pursuing Joint Commission compliance show the least.
Supply Chain Analysis
Container freight rates from Taiwanese sensor foundries to North American distribution hubs directly affect landed costs for automatic dispenser assemblies. Manufacturing concentrates in China, Germany, and the United States. Feedstock dependencies draw from Saudi Arabian petrochemical complexes for polymer resins and South Korean wafer fabs for piezoelectric infrared modules. Single-source vulnerability concentrates in precision sensor supply. Distribution runs through janitorial supply wholesalers aggregating fragmented commercial demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The soap dispenser market functions as a stable compounder anchored by infection-control mandates that institutionalize recurring procurement cycles across healthcare and foodservice verticals.
For Market Incumbents: Anticipate margin compression from sensor module commoditization by deepening captive supply of antimicrobial soap formulations. Lock in multi-year enterprise agreements with hospital GPOs before subscription commerce erodes traditional wholesale channels. Vertical integration into consumable chemistry represents the critical defensive lever.
For New Entrants and Emerging Players: The mid-tier price gap between premium sensor-calibrated units and economy plastic pumps offers white-space entry for aluminum-bodied automatic dispensers with modular retrofit compatibility. Target India's tier-2 city sanitation infrastructure under Swachh Bharat Mission funding. Pursue BIS certification pathways to anchor institutional procurement relationships.
For Investors and Strategic Acquirers: Roll-up economics work for regional janitorial supply distributors because fragmented facility maintenance spending is consolidating around full-spectrum hygiene contracts. The five-to-ten year viability window favors platforms with recurring revenue attachment. Acquisition targets should demonstrate captive distribution in healthcare or hospitality verticals. Monitor EPA WaterSense adoption velocity in state procurement codes as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Consumable Formulation | Captures recurring revenue streams that hardware margins cannot sustain under sensor commoditization pressure. |
| IoT Platform Integration | Enables predictive maintenance contracts that merge dispenser hardware with facility management software layers. |
| Certification Pre-Investment | Accelerates EPA WaterSense and FDA sanitation claims verification to compress product launch timelines. |
| Direct-to-Consumer Subscription Launch | Bypasses retail shelf space constraints through concentrated soap cartridge paired with premium sensor hardware. |
| Geographic Manufacturing Footprint Expansion | Establishes regional assembly capacity in India to serve Swachh Bharat Mission procurement with BIS-compliant supply. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to triangulate demand signals. Primary fieldwork engaged hospital procurement managers, facility maintenance directors at corporate campuses, GPO contracts specialists, and janitorial supply distributors. Secondary validation drew from EPA WaterSense certification databases, FDA sanitation standard filings, customs trade records for polymer resin imports, and hospital procurement contract disclosures. Bottom-up unit economics modeling reconciled against top-down market sizing across product type, material grade, and end-use vertical.
Segment-weighting approaches allocated value share based on installed base turnover rates and replacement cycle timing. The analytical framework modeled manual, automatic, wall-mounted, and countertop configurations across plastic, stainless steel, glass, and aluminum material tiers. End-use segmentation captured hospitals, restaurants, schools, and offices with distinct compliance requirements. CAGRs were derived from regression analysis of historical procurement volume against regulatory mandate implementation schedules. Forecast inputs incorporated sensor miniaturization cost curves and subscription commerce penetration assumptions.
The model assumes a particular technology adoption path; alternative pathways for piezoelectric infrared sensor deployment would alter the outlook if battery efficiency improvements accelerate faster than projected. Forecasts reflect assumptions about Joint Commission mandate enforcement consistency and German federal sanitation regulation compliance timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Lunch Box Market
Household Items
Ironing Boards Market
Household Items
India Non-Stick Cookware Market
Household Items
Stainless Steel Toilet Paper Dispenser Market
Household Items
Russia Residential Water Heaters Market
Household Items
Smart Shower Market
Household Items
Waterless Aroma Diffuser Market
Household Items
Toilet Deodorant Market
Household Items
Washing Machine Cleaner Market
Household Items
Asia-Pacific Hand Dryer Market
Household Items
Shower Heads Market
Household Items
India Air Purifier Market
Household Items
Dry Cleaning and Laundry Market
Household Items
Window Rain Guards Market
Household Items
Kuwait Gas Hobs Market
Household Items
Japan Cookware Market