
 Smart Fridge Market | 2026-2036
Smart Fridge Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Fridge Market Analysis
Buyer concentration among property developers and multi-unit residential operators is recalibrating procurement patterns across the smart fridge value chain. Samsung Electronics leverages its vertical integration in display and semiconductor manufacturing to control component costs. LG Electronics anchors its position through deep R&D investment in AI-driven food management systems. Whirlpool Corporation competes primarily on brand strength and installer relationships in North American builder channels.
A smart fridge integrates refrigeration hardware with IoT connectivity, embedded sensors, and touchscreen interfaces to enable remote monitoring, inventory tracking, and energy optimization through variable compressor modulation. French Door configurations lead in average selling price and household preference, while Built-in units concentrate margin pools among premium kitchen renovation projects. Energy Efficiency technology carries growing weight in utility rebate eligibility and consumer purchasing decisions across major markets.
EPA Energy Star certification and EU Ecodesign requirements shape minimum efficiency thresholds and testing protocols, directly influencing product roadmaps and manufacturing cost structures. FCC compliance governs wireless connectivity modules in US-bound units, while China's GB standards and MIIT circulars regulate domestic smart appliance interoperability. Stakeholders must monitor evolving refrigerant phase-down schedules and cybersecurity labeling mandates that will determine market access and retrofit liability.
Market Dynamics
Utility rebate programs tied to EPA Energy Star certification and EU Ecodesign compliance are forcing manufacturers to redesign compressor architectures and refrigerant systems ahead of regulatory deadlines. This efficiency-first mandate is compressing development cycles while elevating procurement scrutiny among property developers and multi-unit residential operators.
Growth Catalysts
- EPA Energy Star certification:Eligibility for utility rebate programs in the United States accelerates replacement cycles among cost-conscious residential households. Rebate thresholds now determine minimum feature sets for mass-market units.
- French Door configuration preference:Households renovating premium kitchens drive volume at higher average selling prices. This segment captures disproportionate margin pools relative to unit share.
- China's GB standards and MIIT circulars:Domestic smart appliance interoperability mandates create captive demand for locally certified connectivity modules. Manufacturers with in-country testing facilities gain accelerated market access.
Market Restraints
- Refrigerant phase-down schedules:Transition costs for hydrofluorocarbon alternatives elevate manufacturing complexity. Supply constraints for low-global-warming-potential refrigerants compress margin structures during the transition window.
- Display panel concentration:Korean and Taiwanese semiconductor foundries control advanced OLED and mini-LED supply for touchscreen interfaces. Geographic concentration creates input cost volatility and allocation risk.
- Cybersecurity labeling mandates:Emerging FCC and EU requirements for connected appliance security certification extend product launch timelines. Compliance testing adds fixed costs that disadvantage smaller manufacturers.
Strategic Opportunities
- Germany's building renovation wave:Federal subsidies for energy-efficient home upgrades create pull-through demand for premium Built-in configurations. Kitchen renovation projects concentrate in urban centers with strict local efficiency codes.
- AI-driven food management convergence:Integration of computer vision with inventory tracking algorithms enables subscription grocery linkages. Technology partnerships with retail platforms unlock recurring revenue streams.
- Direct-to-installer channel development:Bypassing traditional retail through builder and contractor networks captures specification authority earlier in the purchase journey. This channel rewards localized service capabilities over brand advertising scale.
Industry Challenges
- Embedded systems security engineering:Shortage of firmware developers with IoT hardening expertise extends development timelines. Compensation inflation for this talent pool elevates R&D cost structures.
- Legacy HVAC integration complexity:Smart fridge energy optimization algorithms require coordination with existing home climate systems. Interoperability testing across fragmented building automation protocols consumes engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Fridge Market |
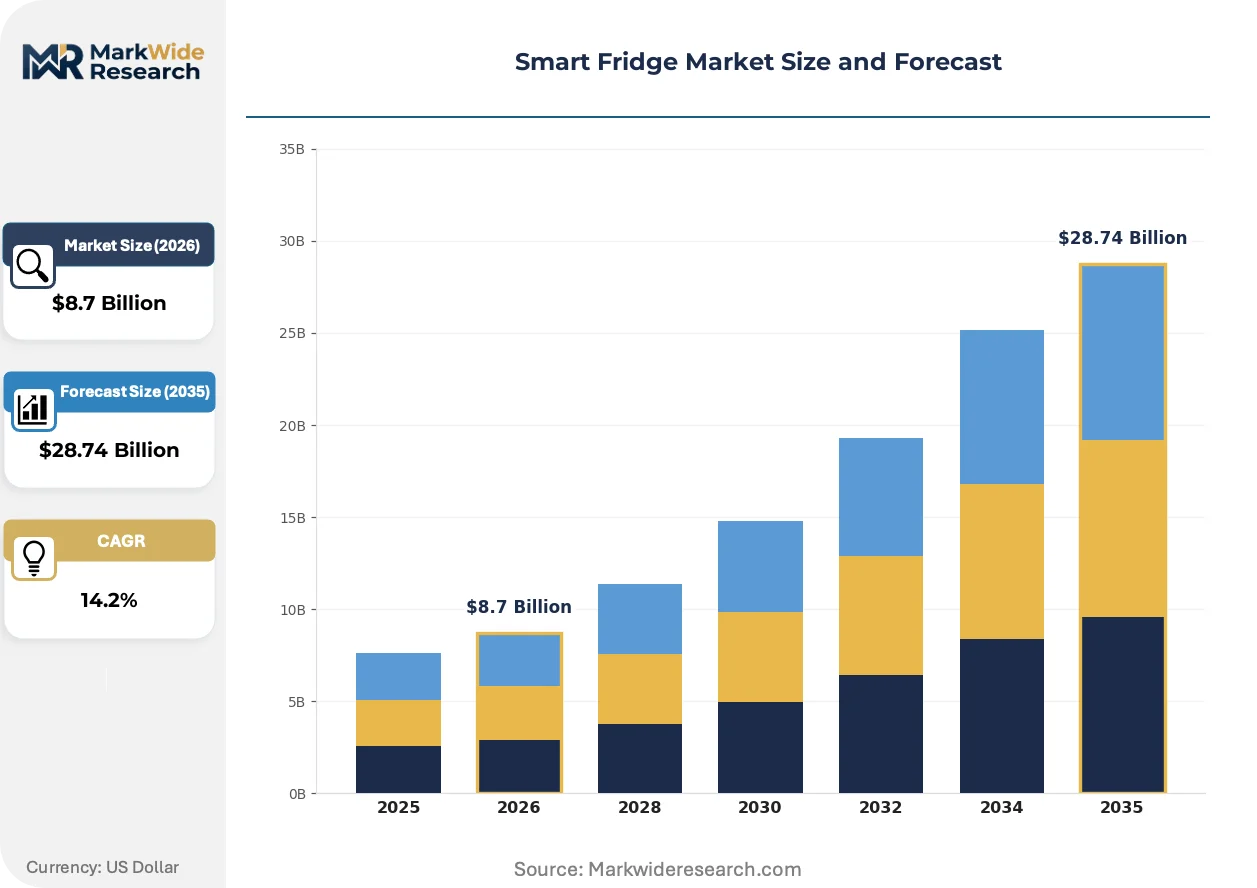
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Top-Freezer, Side-by-Side, French Door, Built-in Technology: IOT Connectivity, Smart Sensors, Touchscreen Interface, Energy Efficiency End User: Households, Restaurants, Retailers, Hospitality Distribution Channel: Online Retailers, Specialty Stores, Hypermarkets, Direct Sales |
| Companies Covered | Bosch Group, Café (GE Appliances subsidiary), Samsung Electronics, Siemens AG, Hisense, LG Electronics, Whirlpool Corporation, Hitachi, GE Appliances, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Fridge Market Emerging Trajectories
Variable compressor modulation technology is displacing fixed-speed architectures as the baseline for utility rebate eligibility. This hardware transition is compressing the performance gap between mid-tier and premium units while elevating software differentiation as the primary competitive battleground.
Edge computing for food recognition is decentralizing image processing from cloud-dependent architectures to on-device inference engines. Residential households with intermittent connectivity demand offline functionality for core inventory features. This shift reduces latency for door-open detection while compressing ongoing cloud service costs for manufacturers.
The EU F-Gas Regulation and accompanying refrigerant phase-down timelines are accelerating R-600a and R-290 adoption across European manufacturing lines. Compressor suppliers with hydrocarbon-compatible platforms capture specification authority with OEMs. German and French certification bodies are expanding testing capacity to accommodate accelerated product recertification cycles.
Builder channel specification authority is consolidating procurement decisions among multi-unit residential developers with standardized appliance packages. Traditional retail foot traffic for major appliances compresses as property developers pre-specify units during construction. This concentration is most visible in the United States Sun Belt and German metropolitan housing developments where new construction volumes remain elevated.
Smart Fridge Market Segmentation
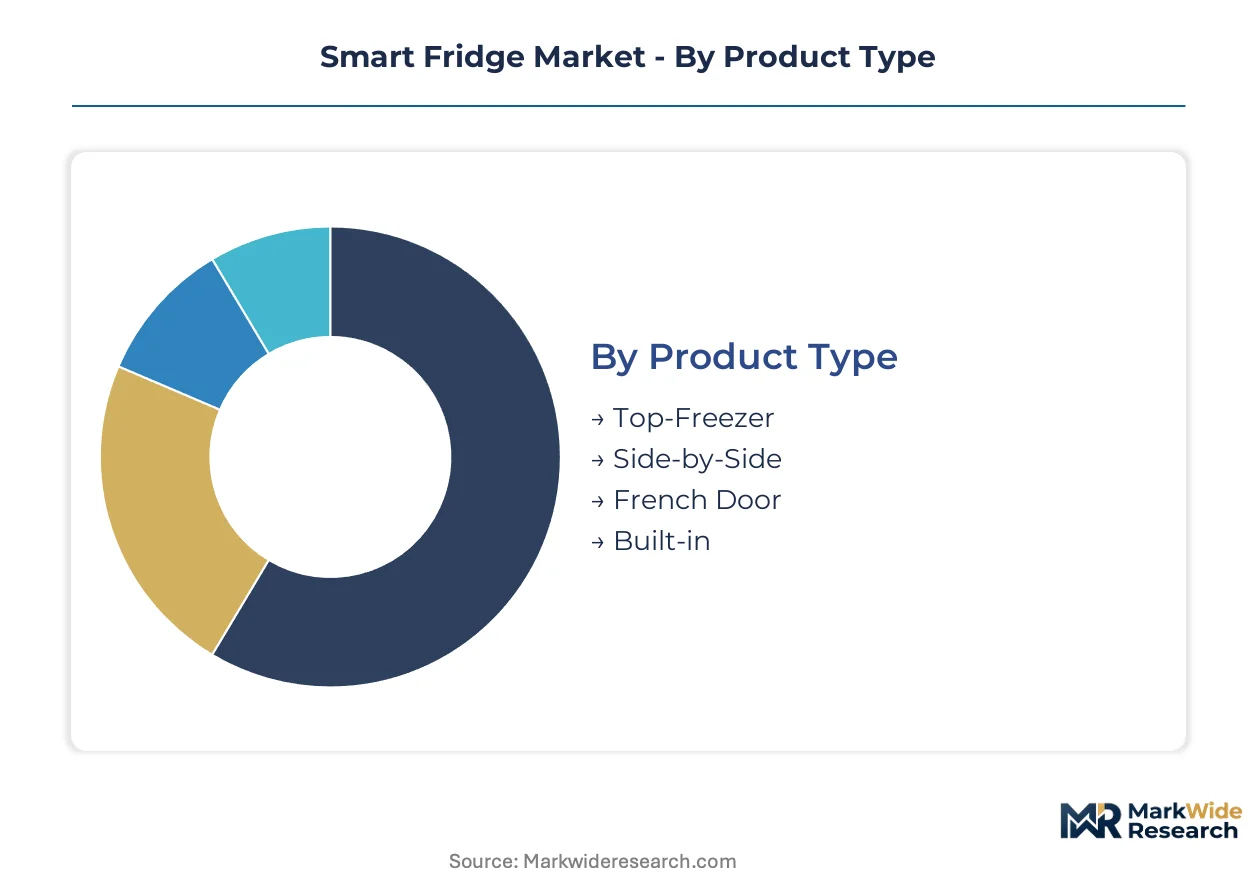
Smart fridge segmentation reveals how regulatory certification requirements, channel economics, and end-use operational demands fragment procurement patterns across the value chain. Manufacturers must align product architectures with distinct compliance burdens and buyer specifications to capture volume in each category.
Product Type:
EPA Energy Star certification and EU Ecodesign compliance thresholds vary by configuration, with larger multi-door units facing stricter testing protocols and refrigerant charge limits.
- French Door:Three-door architecture with bottom freezer compartment and dual refrigerator columns. Residential renovation demand concentrates in the United States and Germany where premium kitchen specifications dominate. EPA rebate eligibility thresholds now mandate variable compressor modulation as baseline for this tier.
- Built-in:Panel-ready units designed for seamless cabinetry integration with custom hinge systems. German metropolitan housing developments and US Sun Belt multi-unit residential projects drive specification volume. EU F-Gas Regulation hydrocarbon refrigerant mandates elevate recertification costs for European-bound production.
- Side-by-Side:Vertical split configuration with adjacent refrigerator and freezer compartments. Compact footprint suits urban household density in Chinese tier-one cities.
- Top-Freezer:Traditional over-under arrangement with smallest installed footprint. Mass-market replacement cycles in North American suburban households sustain baseline volume.
French Door sits at the top of the volume ranking, with Built-in climbing the fastest.
Technology:
Cost tier stratification separates premium sensor suites from baseline connectivity modules, with FCC and CE marking requirements governing wireless subsystem certification.
- Energy Efficiency:Variable compressor modulation and adaptive defrost algorithms optimize consumption profiles. Utility rebate program eligibility in the United States and Germany hinges on certified performance thresholds. EPA Energy Star Version 7.0 testing protocols now disqualify fixed-speed architectures from rebate eligibility.
- Smart Sensors:Multi-point temperature monitoring, door-open detection, and ambient humidity tracking enable predictive maintenance alerts. Restaurant and hospitality end-users in Germany prioritize sensor redundancy for HACCP compliance documentation.
- IOT Connectivity:Wi-Fi and Bluetooth modules enabling remote monitoring and firmware updates. China's GB standards and MIIT circulars mandate domestic interoperability certification for connectivity subsystems.
- Touchscreen Interface:Embedded display panels for inventory visualization and recipe integration. Supply concentration in Korean and Taiwanese semiconductor foundries elevates input cost volatility.
Energy Efficiency captures the largest addressable base through regulatory mandate, with Smart Sensors expanding most quickly among commercial end-users.
End User:
Application-specific operational demands dictate durability specifications, warranty terms, and service network requirements across buyer categories.
- Households:Residential replacement and renovation procurement with sensitivity to utility rebate economics. United States suburban households and German urban condominium owners represent concentrated demand pools with divergent efficiency code requirements.
- Restaurants:Commercial kitchen deployments requiring NSF certification and rapid temperature recovery performance. Health department inspection protocols in the United States mandate continuous temperature logging capabilities.
- Hospitality:Hotel and extended-stay properties with standardized appliance packages across property portfolios. Multi-unit procurement authority concentrates specification decisions among national operators.
- Retailers:Convenience stores and small-format grocers with display case integration requirements. Energy optimization algorithms must coordinate with existing HVAC infrastructure.
Households dominate absolute unit volume, with Restaurants gaining share fastest as commercial kitchen upgrade cycles accelerate.
Distribution Channel:
Customer type and purchase timing determine channel economics, with builder-direct procurement bypassing traditional retail margin structures.
- Direct Sales:Manufacturer relationships with property developers and multi-unit residential operators. Builder channel specification authority in the United States Sun Belt and German metropolitan housing developments compresses traditional retail foot traffic.
- Online Retailers:E-commerce platforms capturing replacement cycle demand from research-intensive residential buyers. Post-purchase installation coordination remains a service gap.
- Specialty Stores:Kitchen design showrooms with consultation-driven premium configuration sales. German federal renovation subsidies pull through Built-in specification at point of design.
- Hypermarkets:Mass-market volume for standard configurations with immediate availability. Price transparency pressures margin structures for undifferentiated units.
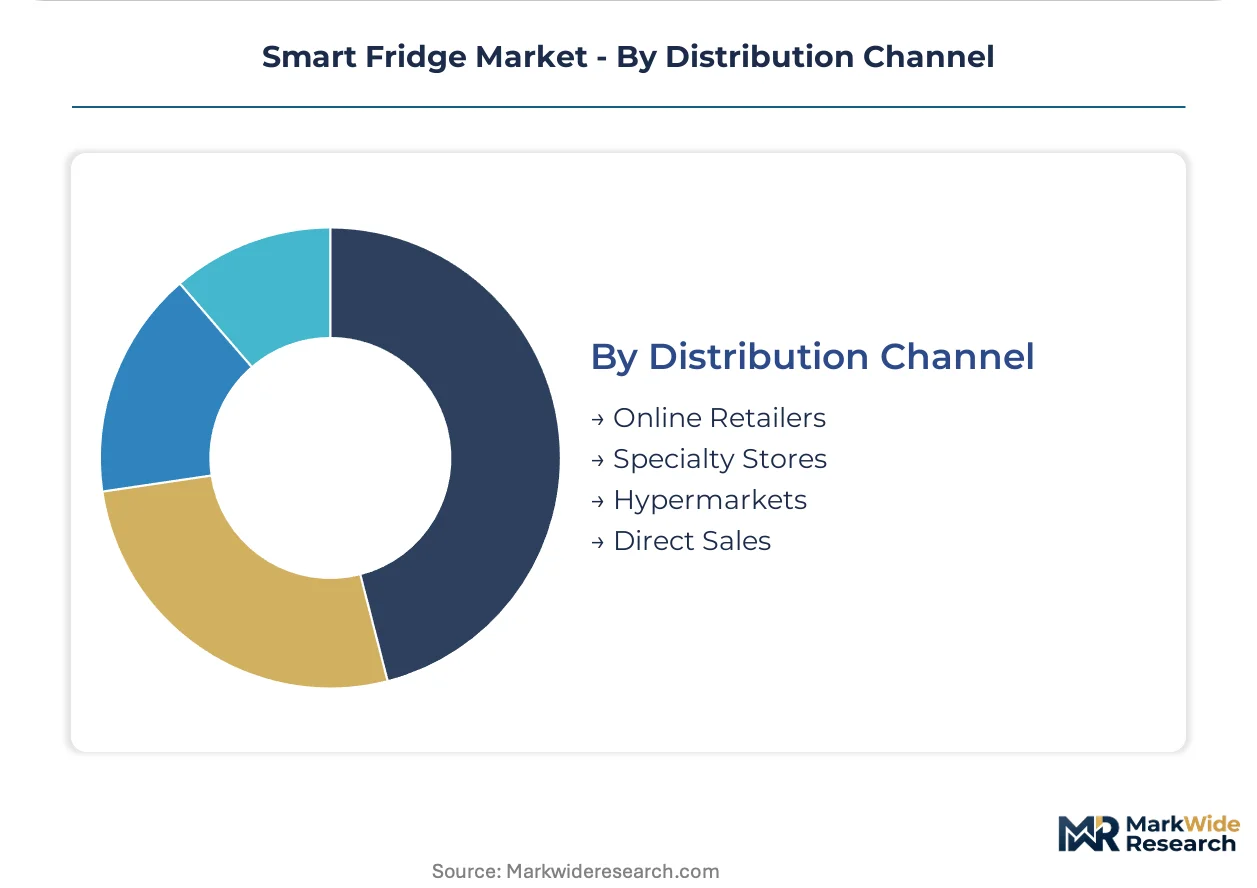
Direct Sales leads channel volume through builder concentration, with Online Retailers climbing fastest as replacement cycle research behavior shifts digital.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States and China diverge sharply in smart fridge adoption mechanics, with American households responding to utility rebate economics while Chinese buyers prioritize domestic interoperability certification. Germany occupies a distinct position where federal renovation subsidies intersect with stringent EU efficiency mandates.
United States
Suburban household replacement cycles and Sun Belt multi-unit residential construction sustain volume demand. EPA Energy Star Version 7.0 testing protocols now disqualify fixed-speed compressor architectures from rebate eligibility. Dallas-Fort Worth and Phoenix metropolitan housing developments concentrate builder-channel procurement authority for standardized appliance packages.
China
Tier-one urban household density and domestic smart home ecosystem integration propel specification requirements. MIIT circulars and GB standards mandate in-country interoperability certification for connectivity subsystems. Shanghai and Shenzhen manufacturing clusters host testing facilities that accelerate market access for locally certified modules.
Germany
Federal subsidies for energy-efficient building renovations create pull-through demand for premium built-in configurations. EU F-Gas Regulation hydrocarbon refrigerant mandates elevate recertification costs and compress development timelines. Berlin and Munich metropolitan housing developments concentrate kitchen renovation projects with strict local efficiency codes.
Japan
Compact urban dwelling constraints and METI efficiency labeling programs shape product form factor requirements. JIS standards govern smart appliance interoperability within domestic IoT ecosystems. Osaka and Nagoya industrial corridors host compressor suppliers with hydrocarbon-compatible platform development.
South Korea
Advanced display panel manufacturing concentration and domestic smart home penetration create integrated supply advantages. MFDS-equivalent appliance safety certification and KCC wireless compliance govern export-bound production. Seoul Capital Area conglomerates leverage captive semiconductor foundry access for touchscreen interface cost control.
Smart Fridge Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions, creating a structure where scale advantages in component manufacturing clash with agility in software differentiation. Samsung Electronics and LG Electronics anchor the upper tier through captive display and semiconductor supply chains. Whirlpool Corporation and GE Appliances occupy positions built on installer network density and builder channel relationships. Strategic moves concentrate on vertical integration into connectivity modules and direct-to-developer channel development bypassing traditional retail.
Among diversified Korean conglomerates, Samsung Electronics and LG Electronics exemplify archetypes leveraging backward integration into display panels and compressor technologies. Bosch Group and Siemens AG represent German engineering-focused positions emphasizing precision manufacturing and EU regulatory compliance. Hisense anchors a Chinese cost-optimization archetype with domestic certification advantages. These three groupings—Korean integrated conglomerates, German precision engineers, and Chinese scale players—capture distinct margin pools across efficiency certification tiers.
| Leading Market Players |
|---|
| Bosch Group |
| Café (GE Appliances subsidiary) |
| Samsung Electronics |
| Siemens AG |
| Hisense |
| LG Electronics |
| Whirlpool Corporation |
| Hitachi |
| GE Appliances |
| Others |
Supply Flow & Price Mechanics
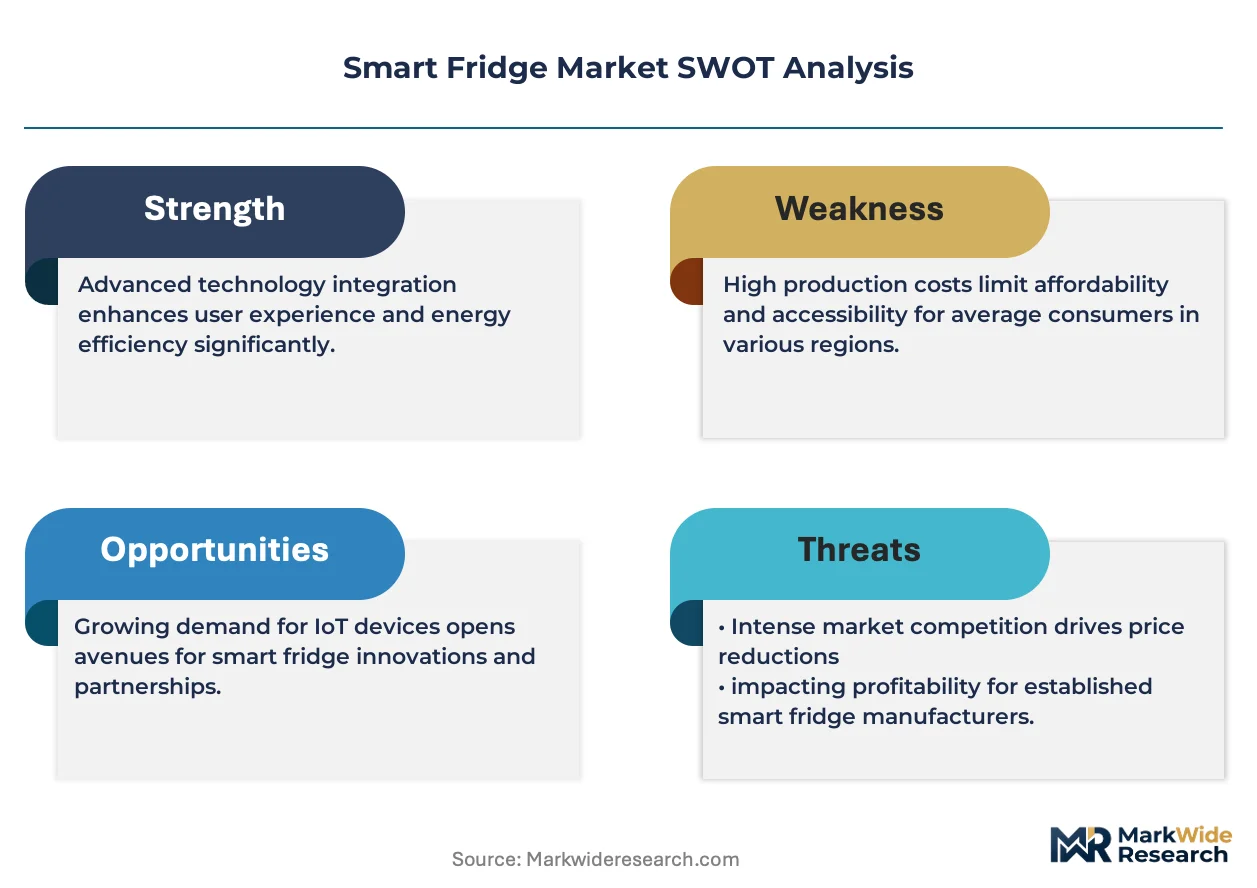
Neodymium and copper price indices cascade through compressor motor and wiring harness costs, compressing margin structures for mid-tier manufacturers while Korean conglomerates with captive magnet supply neutralize input volatility. This commodity exposure stratifies pricing power across certification tiers, with EPA Energy Star rebate eligibility becoming the primary wedge between premium and standard positioning.
Pricing Analysis
Capacity additions in South Korea and Taiwan are reshaping price floors for advanced display panels used in touchscreen interfaces. Three-tier pricing structure across premium, standard, and economy levels separates French Door configurations with variable compressor modulation from fixed-speed Top-Freezer units. Cost compression in the mid-tier is intensifying because utility rebate thresholds now disqualify older architectures. Mass-market suburban households exhibit highest price sensitivity, while German metropolitan renovation buyers prioritize efficiency certification over upfront cost.
Supply Chain Analysis
China's MIIT circulars and GB standards mandate domestic-content certification for connectivity modules, compelling foreign OEMs to localize subsystem sourcing. Manufacturing concentrates in China, South Korea, and Vietnam for final assembly, while advanced OLED panels and compressor motors draw from Taiwanese and Korean foundries. Single-source vulnerability in mini-LED driver ICs elevates allocation risk during demand surges. Distribution runs through builder-direct channels for multi-unit residential projects and specialty kitchen showrooms for premium renovation specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart fridge market functions as a geographic-arbitrage play where EPA rebate economics in the United States and EU Ecodesign mandates in Germany create divergent product specification requirements, rewarding manufacturers with dual-certification capabilities.
For Market Incumbents: Extend backward integration into compressor controller firmware to defend against emerging white-label entrants with modular connectivity platforms. Prioritize certification investment for EPA Energy Star Version 7.0 and EU F-Gas hydrocarbon compatibility ahead of regulatory deadlines. Channel control through direct-to-developer relationships in Sun Belt metropolitan housing markets anchors specification authority.
For New Entrants and Emerging Players: Capture commercial kitchen retrofit demand in Germany where HACCP compliance documentation and sensor redundancy requirements create specification barriers for consumer-focused incumbents. Restaurant end-users represent the most penetrable segment given accelerated upgrade cycles and fragmented procurement. A go-to-market angle through foodservice equipment distributors bypasses retail margin structures entirely.
For Investors and Strategic Acquirers: Asymmetric upside sits with compressor suppliers with hydrocarbon-compatible platform development and in-country testing facilities in Germany and France. Long-term viability hinges on regulatory compliance capabilities across multiple jurisdictions rather than brand scale. The inflection indicator to watch is accelerated recertification cycle announcements from EU notified bodies signaling refrigerant transition urgency.
| Strategic Initiative | Industry Significance |
|---|---|
| Variable Compressor Platform Development | EPA Energy Star Version 7.0 compliance secures utility rebate eligibility in US residential channels. |
| Hydrocarbon Refrigerant Transition | EU F-Gas Regulation mandates R-600a and R-290 adoption across European manufacturing lines. |
| Direct-to-Installer Channel Expansion | Builder channel specification authority in Dallas-Fort Worth and Phoenix compresses retail foot traffic. |
| Edge Computing Food Recognition | On-device inference engines reduce cloud service costs and enable offline inventory functionality. |
| AI-Driven Retail Platform Integration | Computer vision partnerships with grocery platforms unlock subscription revenue streams from household data. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with appliance procurement managers at multi-unit residential developers, compressor platform engineers at OEM suppliers, regulatory affairs leads at certification bodies, and kitchen design consultants at specialty showrooms with secondary validation from EPA Energy Star certification databases, EU Ecodesign preparatory study documents, MIIT circular filings, and customs trade records for refrigeration equipment. Bottom-up unit shipment modeling and top-down value triangulation anchored volume estimates.
Historical reference periods spanning pre-pandemic baseline through efficiency mandate acceleration established trajectory anchors across the projection horizon. Segmentation modeling incorporated product configuration, technology tier, end-use application, and distribution channel dimensions alongside regional regulatory cluster differentiation. CAGRs derived from fitted growth curves adjusted for replacement cycle timing and rebate program phase-in schedules, with compressor technology transition rates and builder channel penetration serving as industry-specific forecast inputs.
Refrigerant phase-down schedule acceleration, cybersecurity labeling mandate expansion, and display panel supply allocation disruptions are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding regulatory timeline adherence and technology cost curves. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Air Humidifier Market
Household Items
Automatic Dishwashing Products Market
Household Items
Garbage Disposals Market
Household Items
Basin, Bowl, and Cup Market
Household Items
US Handheld Vacuum Cleaners Market
Household Items
Soap Tablet Market
Household Items
Dryer Sheets Market
Household Items
Hydralight Lanterns Market
Household Items
Portable Vacuum Cleaner Market
Household Items
North America Car Air Freshener Market
Household Items
Robot Vacuum Cleaners Market
Household Items
Industrial Floor Mats Market
Household Items
Stick Vacuum Cleaner Market
Household Items
Command Hooks Market
Household Items
MENA POU Water Purifiers Market
Household Items
Air Purifier Market