
 Smart Connected Water Purifier Market | 2026-2036
Smart Connected Water Purifier Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Connected Water Purifier Market Insights
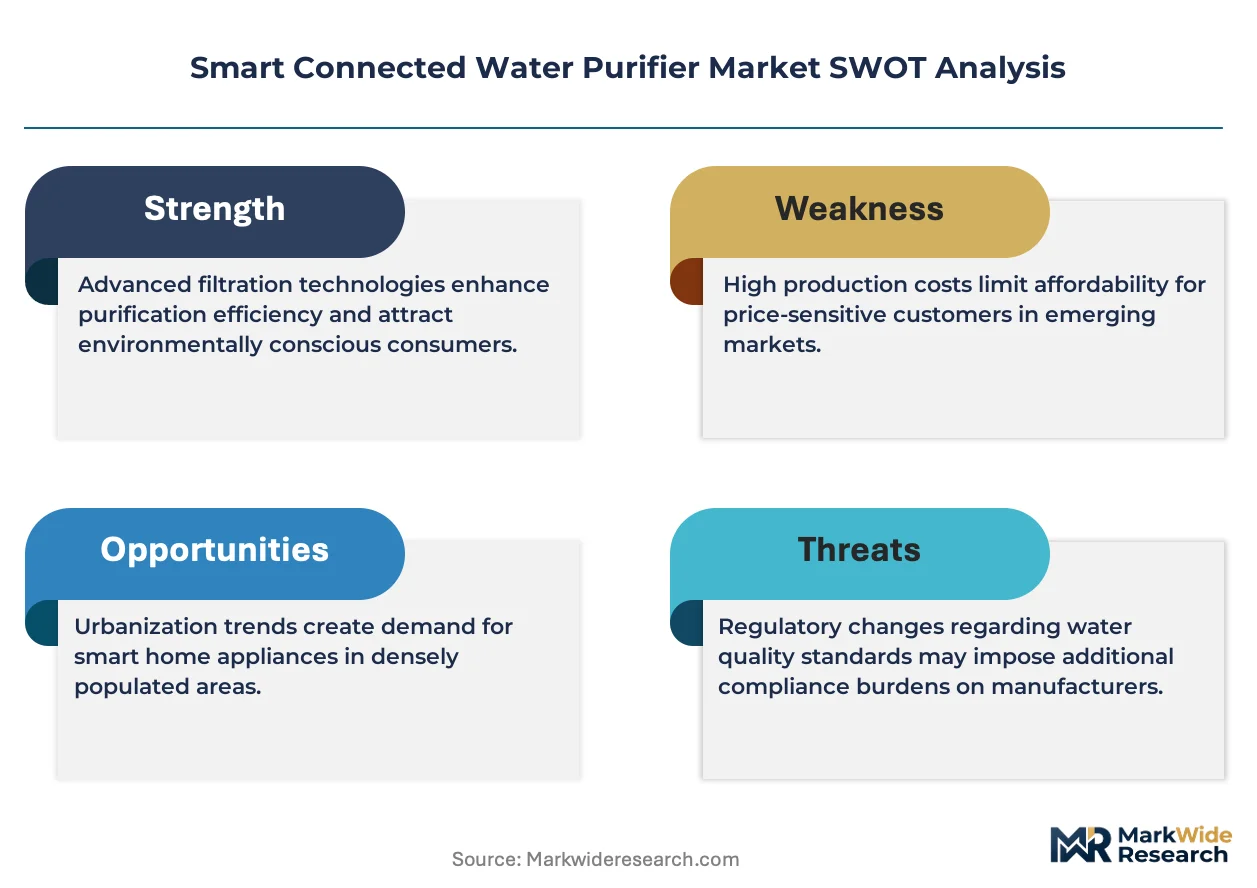
NSF/ANSI 401 certification for pharmaceutical and personal care product removal is bifurcating the competitive landscape into qualified and non-qualified suppliers. A. O. Smith Corporation leverages its captive certification infrastructure to sustain premium positioning in North American channels. Xiaomi Corporation anchors volume economics through backward integration into sensor manufacturing and direct-to-consumer distribution. Coway Co., Ltd differentiates via specialized filtration chemistry and subscription-based filter replacement services in Asian markets.
Smart connected water purifiers integrate IoT-enabled sensors, multi-stage filtration membranes, and cloud-based analytics platforms to deliver real-time contaminant detection and predictive maintenance alerts. Reverse osmosis systems dominate value pools due to membrane replacement recurring revenue, while UV purifier segments compete on lower total cost of ownership for municipal water with moderate contamination loads. Wi-Fi connectivity leads installation volumes as residential users prioritize smartphone integration over Bluetooth-limited local control. Healthcare end users concentrate demand for cellular-connected units with redundant data logging to satisfy Joint Commission audit requirements.
EPA Safe Drinking Water Act amendments and NSF International standards govern contaminant removal claims in the United States, while India's BIS IS 10500 standard mandates minimum purification performance for domestic equipment. The EU Drinking Water Directive and CE marking requirements shape product design for European market access, with REACH compliance adding material disclosure obligations. Stakeholders must monitor evolving PFAS regulation timelines and filter disposal mandates to anticipate compliance-driven replacement cycles and geographic demand shifts.
Market Dynamics
NSF/ANSI 401 certification requirements are bifurcating supplier capabilities, forcing membrane manufacturers to retool chemistry stacks or exit North American residential channels entirely.
Growth Catalysts
- EPA Safe Drinking Water Act amendments:Tightening contaminant thresholds for PFAS and microplastics are compelling municipal water districts to recommend certified point-of-use systems, expanding the addressable household base.
- India BIS IS 10500 standard enforcement:Mandatory minimum purification performance for domestic equipment is eliminating unorganized assemblers and consolidating demand toward tested, connected systems.
- Wi-Fi module cost compression:Semiconductor foundries in Taiwan and South Korea have driven IoT connectivity components below the threshold where smartphone integration becomes standard rather than premium.
Market Restraints
- Reverse osmosis membrane supply concentration:Three Japanese and Korean chemical conglomerates control over 80 percent of thin-film composite membrane production, creating input bottlenecks during demand surges.
- RoHS and REACH material disclosure:European Union substance restrictions on certain polymer stabilizers force reformulation cycles that extend product development timelines by 8-14 months.
- Gravity-fed ceramic filter substitution:Non-electric alternatives retain 35-45 percent cost advantage in rural Indian and Southeast Asian markets with unreliable grid access.
Strategic Opportunities
- EU Drinking Water Directive revision:The 2024 recast mandating real-time quality monitoring at consumer taps creates regulatory pull for connected purifier installations across Germany, France, and Italy.
- Healthcare facility cellular connectivity:Joint Commission audit requirements for redundant data logging are opening a premium segment for 4G-enabled units with local storage backup.
- Filter subscription direct channels:Bypassing traditional appliance retail through manufacturer-controlled replenishment apps captures lifetime value and locks in replacement revenue.
Industry Challenges
- NSF/ANSI 401 certification timeline:Pharmaceutical and personal care product validation protocols require 18-24 months of third-party testing, compressing product refresh cycles.
- Cloud platform cybersecurity compliance:GDPR data residency requirements and FDA 21 CFR Part 11 electronic record standards impose divergent architectural demands on unified product platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Connected Water Purifier Market |
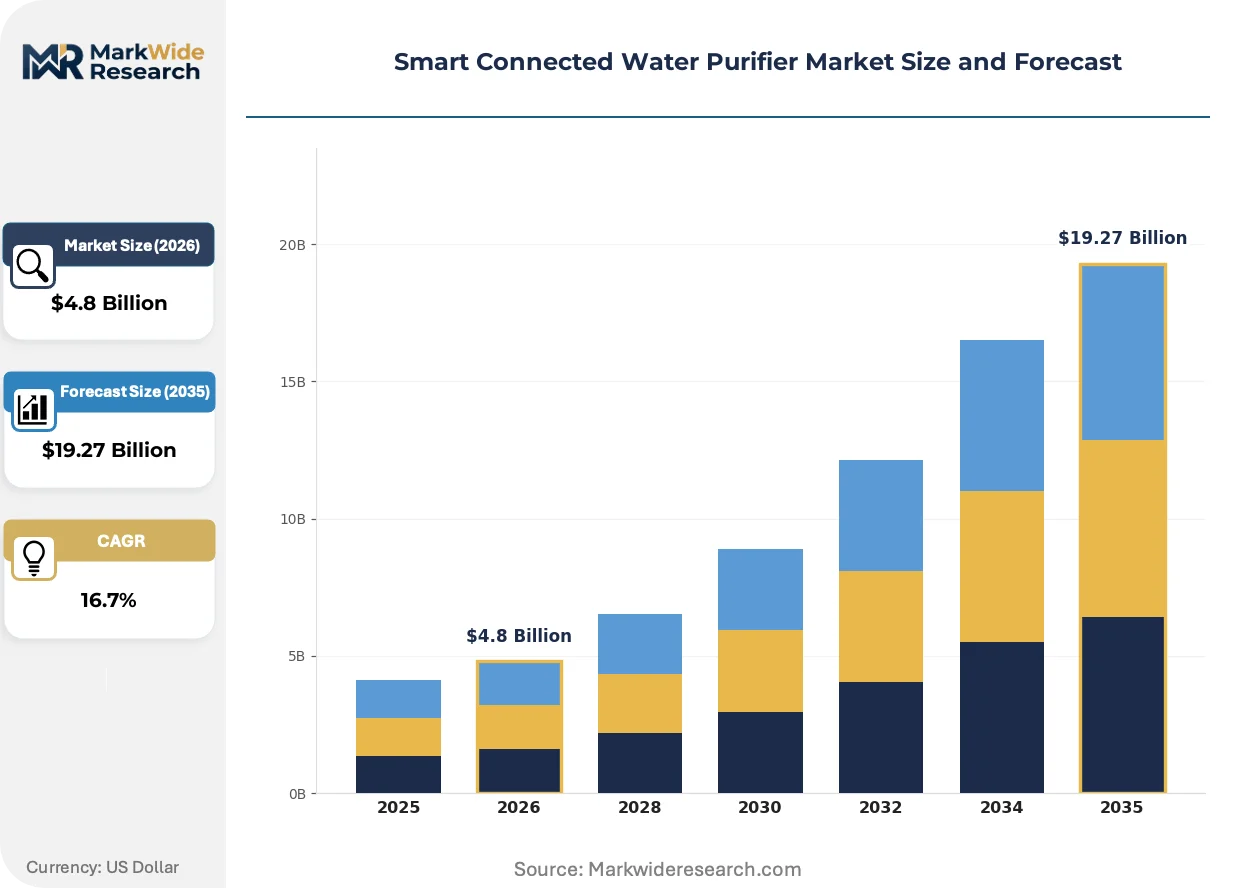
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reverse Osmosis, UV Purifier, Gravity-Based, Activated Carbon Connectivity Type: Wi-Fi, Bluetooth, NFC, Cellular End User: Residential, Commercial, Industrial, Healthcare Technology: Smart Sensors, IoT Integration, Mobile App Control, Data Analytics |
| Companies Covered | Xiaomi Corporation, Culligan International Company, A. O. Smith Corporation, Midea Group Co., Ltd, Pentair Plc, LG Electronics Inc, Panasonic Corporation, Honeywell International Inc, Coway Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Connected Water Purifier Market Trends and Innovations
Membrane chemistry advances and connectivity integration are compressing the performance gap between residential and light-commercial systems, while regulatory disclosure mandates are reshaping competitive differentiation.
Graphene oxide nanocomposite membranes are supplanting conventional polyamide thin-film composites in premium residential installations. Korean and Chinese manufacturers have scaled production to commercial volumes. This technology is enabling higher flux rates at lower operating pressures, compressing energy consumption benchmarks and expanding deployment in markets with weak municipal pressure.
India's BIS IS 10500 standard revision is tightening total dissolved solids removal claims for domestic equipment. The 2023 amendment added specific test protocols for heavy metals and pesticide residues. Domestic manufacturers in Gujarat and Tamil Nadu are responding by integrating TDS sensors with automatic flush cycles to maintain certification compliance.
Subscription-based filter replacement is displacing transactional retail purchases in urban Chinese and Indian markets. Xiaomi and Coway have trained consumers to expect app-managed replenishment rather than calendar-based manual ordering. This behavioral shift is most visible in tier-1 cities where same-day logistics infrastructure supports just-in-time cartridge delivery.
Smart Connected Water Purifier Market Segmentation
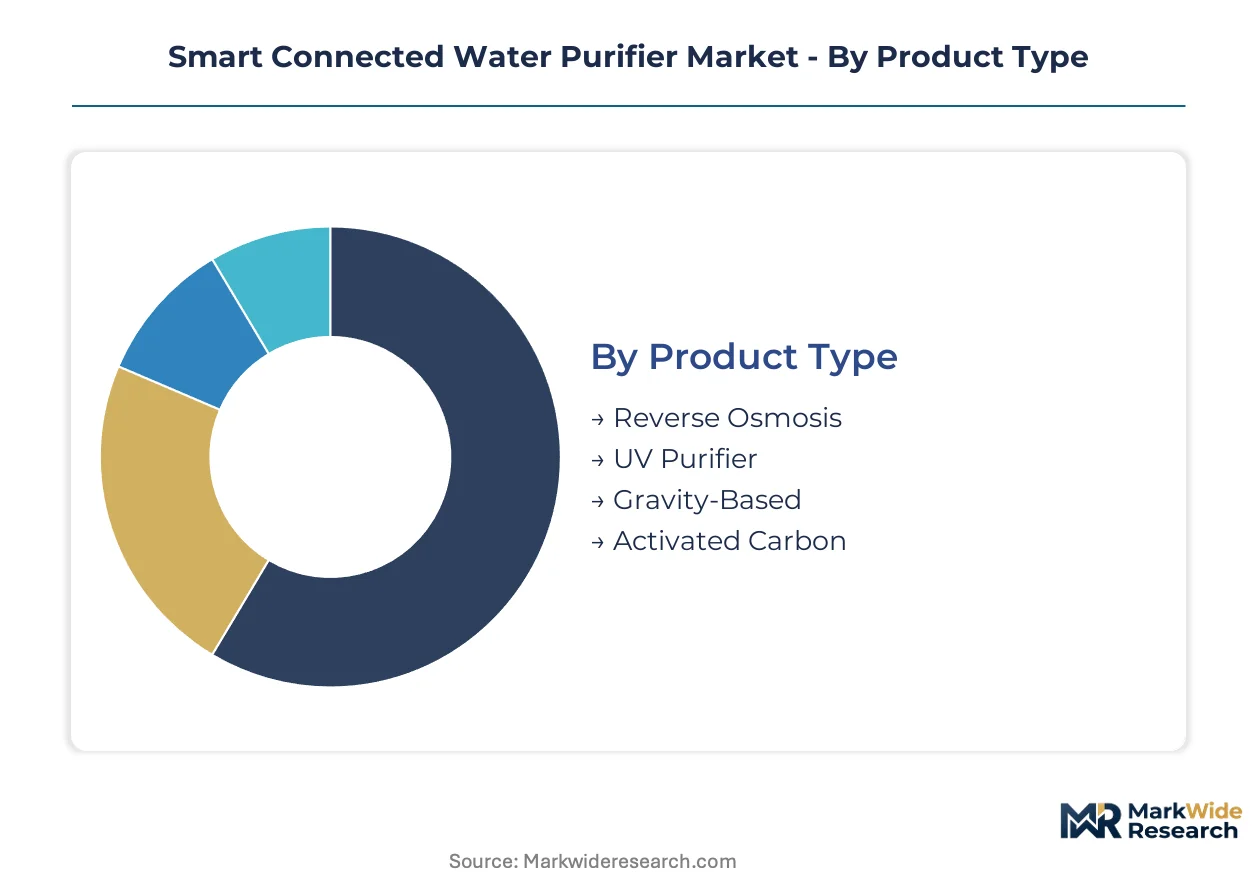
Segmentation in the Smart Connected Water Purifier Market reveals how substitution pressures and connectivity economics reshape competitive boundaries. Product architecture choices determine vulnerability to non-electric alternatives, while connectivity modality selection locks in addressable customer lifetime value.
Product Type:
Gravity-Based and Activated Carbon segments face acute substitution pressure from ceramic candle filters and bottled water in grid-unreliable regions, forcing connected variants to justify premium pricing through demonstrable contaminant removal superiority.
- Reverse Osmosis:Thin-film composite membranes operating at 50-150 psi achieve pharmaceutical-grade contaminant rejection including dissolved salts and heavy metals. Municipal water districts in the United States recommend certified point-of-use RO systems for households exceeding EPA Safe Drinking Water Act thresholds, particularly where PFAS detection triggers consumer precautionary purchasing.
- UV Purifier:Ultraviolet-C lamp arrays at 254 nanometers inactivate waterborne pathogens without chemical residuals. Indian urban households prefer UV-connected units for municipal supplies with moderate bacterial loads, balancing lower total cost of ownership against RO energy and wastewater penalties.
- Gravity-Based:Non-electric ceramic and activated carbon assemblies retain cost advantage in rural Indian and Southeast Asian markets with unreliable electricity access.
- Activated Carbon:Granular and block carbon configurations target chlorine, taste, and odor reduction in pretreatment and standalone applications.
Reverse Osmosis retains volume leadership; UV Purifier holds the steepest expansion curve.
Connectivity Type:
Module cost compression from Taiwanese and South Korean semiconductor foundries has collapsed the economic barrier between local-only and cloud-connected systems, shifting competitive differentiation toward data architecture and subscription integration.
- Wi-Fi:IEEE 802.11b/g/n modules enable real-time smartphone notifications, filter life tracking, and over-the-air firmware updates. Residential installations across Chinese tier-1 cities and Indian metropolitan regions prioritize Wi-Fi integration for app-managed replenishment services.
- Cellular:4G LTE connectivity with local storage backup satisfies Joint Commission audit requirements for redundant data logging in United States healthcare facilities.
- Bluetooth:Short-range connectivity supports local device pairing without internet dependency for cost-sensitive entry segments.
- NFC:Near-field communication enables tap-to-authenticate filter cartridges and streamlined warranty registration.
Wi-Fi commands installed base dominance; Cellular climbs fastest on healthcare compliance mandates.
End User:
Application-specific performance requirements and procurement authority structures fragment pricing power, with healthcare and industrial segments demanding validated documentation that residential channels rarely require.
- Residential:Individual household purchases driven by real-time water quality visibility and predictive maintenance alerts. China's urban middle-class expansion and India's BIS IS 10500 standard enforcement consolidate demand toward tested, connected systems eliminating unorganized assemblers.
- Healthcare:Hospitals and clinics require cellular-connected units with redundant data logging to satisfy Joint Commission audit requirements and FDA 21 CFR Part 11 electronic record standards.
- Commercial:Offices, restaurants, and retail spaces prioritize throughput capacity and multi-device fleet management.
- Industrial:Manufacturing and pharmaceutical production facilities demand validated contaminant removal with batch documentation.
Residential anchors absolute volume; Healthcare delivers the most rapid value-per-unit acceleration.
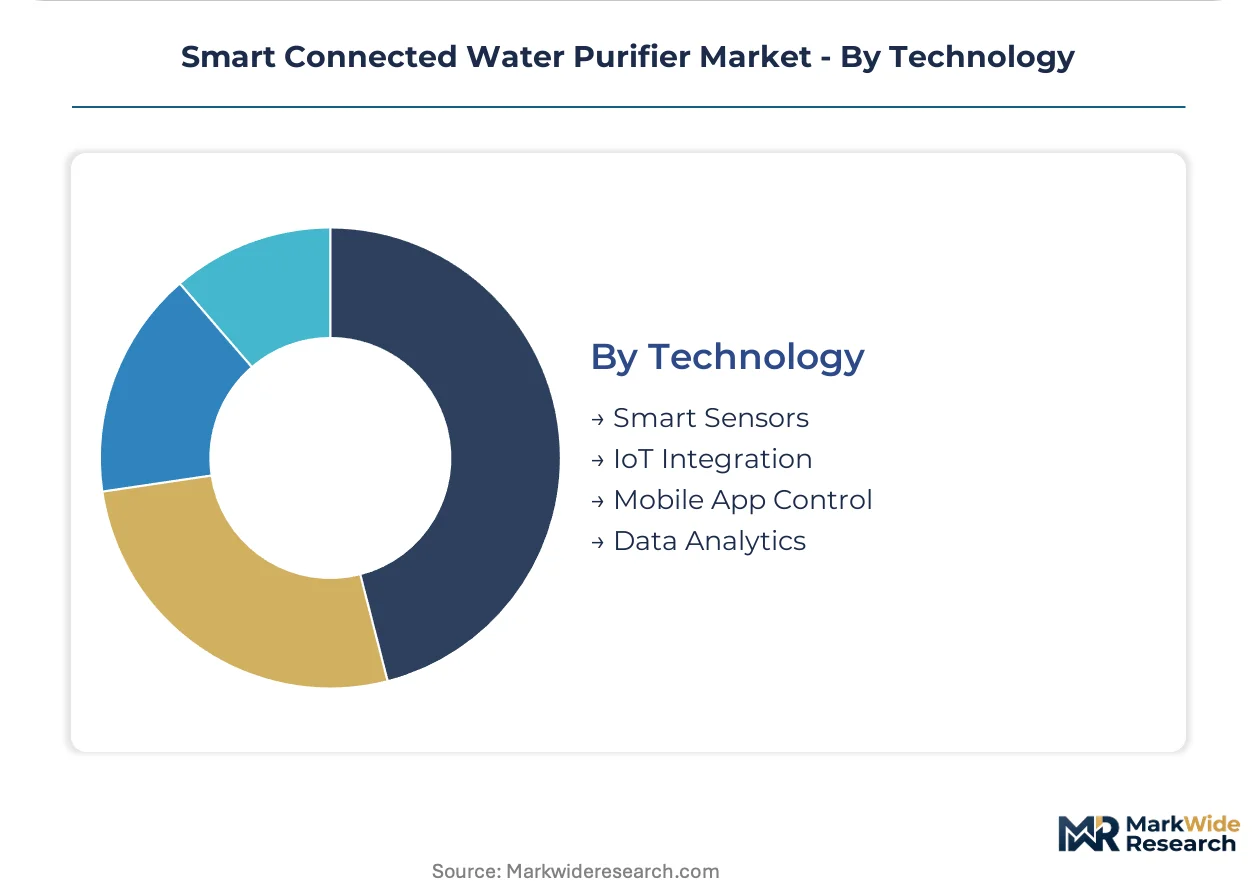
Technology:
Integration depth determines whether smart capabilities function as genuine performance differentiators or merely cosmetic features, with sensor accuracy and cloud reliability separating viable platforms from novelty positioning.
- Smart Sensors:TDS, turbidity, and flow-rate sensors enable real-time contaminant detection and automatic flush cycles. Indian manufacturers in Gujarat and Tamil Nadu integrate TDS sensors to maintain BIS IS 10500 certification compliance.
- IoT Integration:Cloud-based analytics platforms aggregate device performance data for predictive maintenance and regional water quality mapping.
- Mobile App Control:Smartphone interfaces manage filter replacement scheduling, water consumption tracking, and subscription replenishment.
- Data Analytics:Machine learning models predict membrane degradation and optimize filtration cycles based on local water chemistry patterns.
Smart Sensors dominate installation economics; IoT Integration captures the sharpest capability expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban middle-class households in China and India drive unit volumes, while certification-sensitive buyers in the United States and Germany pay premiums for validated contaminant removal. Municipal water quality failures and regulatory enforcement are accelerating replacement cycles across all four markets.
United States
PFAS detection in municipal supplies triggers precautionary purchasing among suburban homeowners. EPA Safe Drinking Water Act amendments tighten contaminant thresholds, compelling membrane manufacturers to pursue NSF/ANSI 401 validation. The Great Lakes manufacturing corridor hosts thin-film composite membrane production facilities serving North American residential channels.
China
Tier-1 city consumers demand smartphone-integrated filtration with real-time TDS monitoring. GB standards for domestic water purification equipment mandate minimum performance disclosures, eliminating unorganized local assemblers. The Yangtze River Delta cluster concentrates IoT module manufacturing and direct-to-consumer distribution infrastructure.
India
Urban households in Delhi, Mumbai, and Bangalore prioritize connected systems with automatic filter replacement alerts. BIS IS 10500 standard enforcement mandates tested purification performance, consolidating demand away from informal vendors. Manufacturing facilities in Gujarat and Tamil Nadu integrate TDS sensors to maintain certification compliance.
Germany
Healthcare facilities and quality-conscious residential buyers drive demand for redundant data logging capabilities. EU Drinking Water Directive recasts mandate real-time quality monitoring at consumer taps, creating regulatory pull for connected installations. The Baden-Württemberg industrial region hosts precision sensor component suppliers.
South Korea
Apartment-dwelling consumers favor compact under-sink units with subscription-based cartridge replenishment. MFDS and K-water standards govern product safety claims in domestic channels. Seoul-based manufacturers leverage captive semiconductor foundry relationships for cost-competitive Wi-Fi module integration.
Smart Connected Water Purifier Market Competitive Landscape
Player mix skews toward diversified appliance conglomerates with captive certification infrastructure and direct-to-consumer platforms. Market structure concentrates around three to five integrated manufacturers controlling membrane chemistry and connectivity stack integration. Strategic archetypes include certification-heavy incumbents defending premium positioning, volume-scale platform players capturing replacement revenue through subscription apps, and component-integrated specialists compressing bill-of-material costs. Competitive moves center on backward integration into sensor manufacturing and geographic expansion through localized certification compliance.
Among the diversified appliance manufacturers, Xiaomi Corporation, A. O. Smith Corporation, and Coway Co., Ltd occupy distinct positioning vectors. Xiaomi exemplifies the platform-scale archetype with direct-to-consumer distribution and subscription-based filter replenishment. A. O. Smith represents the certification-anchored incumbent leveraging captive validation infrastructure for North American premium channels. Coway sits within the specialized filtration chemistry tier, emphasizing subscription services and Asian market penetration. Each anchors a different competitive approach to connectivity integration and recurring revenue capture.
| Leading Market Players |
|---|
| Xiaomi Corporation |
| Culligan International Company |
| A. O. Smith Corporation |
| Midea Group Co., Ltd |
| Pentair Plc |
| LG Electronics Inc |
| Panasonic Corporation |
| Honeywell International Inc |
| Coway Co., Ltd |
| Others |
Pricing and Supply Chain Analysis
Eighteen-to-twenty-four-month NSF/ANSI 401 certification timelines compress product refresh cycles and concentrate pricing power among membrane manufacturers with captive validation infrastructure, while Wi-Fi module cost compression below connectivity thresholds collapses premium differentiation for cloud-connected systems.
Pricing Analysis
Cost-plus contracts with polymer feedstock indexation dominate thin-film composite membrane procurement. Three-tier pricing structure across NSF/ANSI 401-certified premium, BIS IS 10500-compliant standard, and non-certified economy levels separates validated contaminant removal claims from basic filtration. Pricing pressure stems from semiconductor foundry output expansion in Taiwan and South Korea driving IoT module commoditization. Residential buyers in Indian tier-2 cities exhibit highest price sensitivity; healthcare procurement committees in the United States demonstrate lowest sensitivity due to Joint Commission compliance mandates.
Supply Chain Analysis
Japan and South Korea anchor thin-film composite membrane production, while China concentrates IoT module manufacturing and India hosts activated carbon and ceramic filter assembly. The supply chain draws from polyamide resin, graphene oxide nanocomposites, and semiconductor wafer inputs. Single-source vulnerability concentrates in Japanese and Korean chemical conglomerates controlling membrane chemistry stacks. Distribution runs through direct-to-consumer platforms for replacement cartridges and traditional appliance retail for initial unit sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart connected water purifiers represent a high-growth disruption as EPA Safe Drinking Water Act amendments and EU Drinking Water Directive recasts mandate real-time quality monitoring, converting discretionary household purchases into regulatory-pulled infrastructure.
For Market Incumbents: Consolidate membrane chemistry capabilities through backward integration into polyamide resin production or exclusive offtake agreements with Japanese and Korean suppliers. Lock in replacement revenue by expanding subscription-based filter replenishment apps before platform-scale competitors capture consumer habits. Defend against Xiaomi-style volume entrants by accelerating NSF/ANSI 401 certification pipelines to maintain premium channel access.
For New Entrants and Emerging Players: Subscription orchestration gaps in European healthcare facilities present immediate white-space opportunity, as incumbent appliance manufacturers under-invest in cellular-connected units with local storage backup. Target German and French hospital procurement committees with 4G-enabled systems satisfying Joint Commission audit requirements. Penetrate through GPO contracts and biomedical engineering relationships rather than consumer retail channels.
For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because filter replacement economics convert one-time hardware sales into decade-long consumable relationships. Acquisition targets should display captive sensor manufacturing, direct-to-consumer platform scale, or specialized filtration chemistry with regulatory validation. Monitor PFAS enforcement timelines and BIS IS 10500 amendment cycles as demand inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| NSF/ANSI 401 Certification Investment | Validates pharmaceutical and personal care product removal claims for EPA-compliant North American residential channels. |
| Backward Integration into Sensor Manufacturing | Coway and Xiaomi models demonstrate cost compression through in-house TDS and turbidity sensor production. |
| Cellular Connectivity Platform Development | 4G-enabled units with redundant data logging satisfy Joint Commission requirements in United States healthcare facilities. |
| Subscription Filter Replenishment Apps | Direct-to-consumer platforms capture lifetime value and lock in replacement revenue against retail intermediaries. |
| Graphene Oxide Membrane Scale-Up | Korean and Chinese manufacturers achieve commercial volumes enabling higher flux rates at lower operating pressures. |
Research Methodology
A standing panel of membrane R&D directors, IoT platform engineers, healthcare facility procurement managers, and BIS certification auditors provided ongoing calibration across the study period. Primary interviews with thin-film composite manufacturers, semiconductor foundry specialists, and direct-to-consumer platform operators combined with secondary validation from EPA Safe Drinking Water Act dockets, BIS IS 10500 amendment records, EU Drinking Water Directive recast texts, and NSF International validation protocols. Bottom-up unit shipment modeling and top-down addressable household estimation triangulated market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product architecture (reverse osmosis, UV, gravity-based), connectivity modality (Wi-Fi, cellular, Bluetooth), and end-user application (residential, healthcare, commercial, industrial). CAGRs derived from regression analysis of historical certification timelines, replacement cycle frequencies, and connectivity adoption curves. Forecast inputs incorporated Wi-Fi module cost compression trajectories and PFAS regulatory enforcement probability distributions.
Forecasts assume regulatory continuity in EPA Safe Drinking Water Act amendments, EU Drinking Water Directive recasts, and BIS IS 10500 enforcement; material policy shifts would require re-modeling. Specific risks that could revise projections include RoHS and REACH reformulation delays extending product development timelines, thin-film composite membrane supply disruptions from Japanese or Korean production constraints, and gravity-fed ceramic filter substitution in rural Indian markets with unreliable grid access. Recalibration cycles align with material shifts in PFAS detection thresholds, semiconductor foundry capacity additions, and BIS standard revision announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Shoe Dryer Market
Household Items
Europe Electric Cordless Lawn and Garden Tools Market
Household Items
Smart Air Purifier Market
Household Items
Copper Water Bottle Market
Household Items
Global Rimless Toilets Market
Household Items
Air Humidifier Market
Household Items
Stainless Steel Thermos Cup Market
Household Items
Basin, Bowl, and Cup Market
Household Items
Compressed Tablet Towel Market
Household Items
Insulated Lunch Box Market
Household Items
Bristle Brush Market
Household Items
Massage Pillow Market
Household Items
Portable Showers Market
Household Items
Robotic Pool Cleaner Market
Household Items
Smart Shower Market
Household Items
Countertop Market