
 Infuser Water Bottles Market | 2026-2036
Infuser Water Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Infuser Water Bottles Market Foresight
Fitness enthusiast procurement is shifting toward higher-capacity insulated infusers as gym culture and home workout routines embed reusable hydration into daily habits. CamelBak Products LLC leverages its outdoor heritage to sustain strong positioning among adventure-oriented buyers. Hydro Flask anchors premium pricing through double-wall vacuum insulation technology. Contigo competes aggressively on leak-proof sealing mechanisms that target commuter and office worker segments.
An infuser water bottle integrates a removable chamber for fruits, herbs, or tea leaves within a sealed vessel, typically constructed from Tritan copolyester, borosilicate glass, or food-grade stainless steel with silicone gaskets to prevent flavor contamination and leakage. The primary commercial purpose centers on enabling flavored hydration without added sugars or artificial ingredients, serving health-conscious consumers across fitness, workplace, and travel contexts. Stainless steel infuser variants lead on margin pools due to durability premiums and thermal retention capabilities, while collapsible silicone formats represent the fastest-growing structural segment among space-constrained travelers. Glass infuser demand concentrates among consumers prioritizing chemical purity, though breakage risk limits mass-market penetration relative to plastic and metal alternatives.
The FDA regulates food-contact substances under 21 CFR standards, constraining permissible plasticizers and colorants in infuser chamber materials. The EU REACH framework and F-Gas Regulation on fluorinated greenhouse gases shape insulation gas choices and chemical disclosure obligations for bottles sold across European markets. California's Proposition 65 warning requirements add state-level compliance complexity for US distribution. Stakeholders must monitor evolving chemical restriction lists and thermal performance certification standards to maintain market access and justify premium positioning.
Market Dynamics
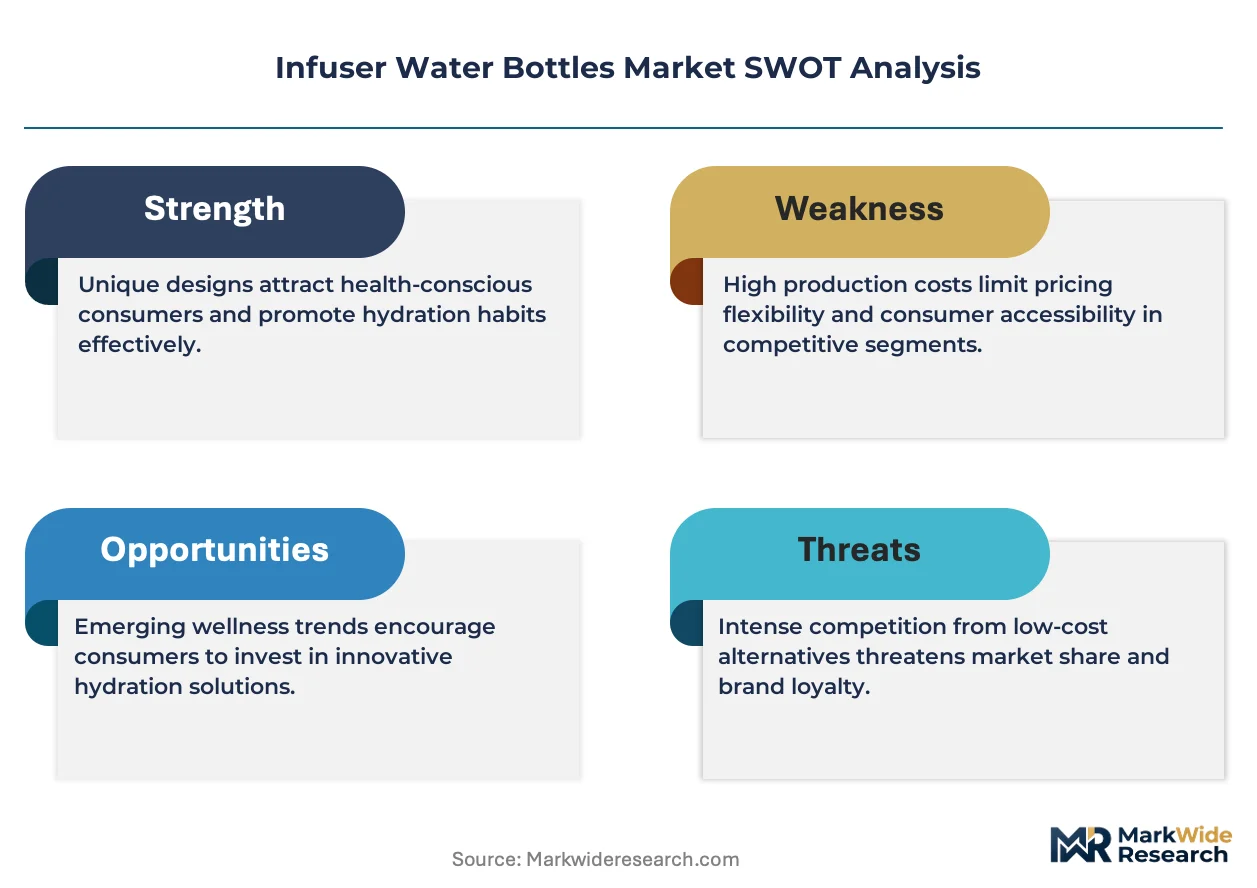
The EU's REACH regulation is tightening chemical disclosure requirements for Tritan copolyester infuser chambers, forcing manufacturers to accelerate material substitutions and supply chain requalification timelines across European distribution channels.
Growth Catalysts
- Fitness culture embedding:Gym operators and home workout platforms are normalizing flavored hydration rituals, expanding BPA-free insulated infuser procurement among health clubs and direct-to-consumer channels.
- REACH chemical transparency:The EU's expanded substance restriction lists are accelerating adoption of borosilicate glass and food-grade stainless steel alternatives among compliance-focused importers.
- Commuter hydration routines:Office worker segments in Germany, the United States, and Japan are integrating leak-proof infusers into daily transit patterns, sustaining replacement cycle demand.
Market Restraints
- Silicone gasket cost volatility:Food-grade silicone input prices fluctuate with petrochemical feedstock markets, compressing margin pools on economy-tier plastic infuser variants.
- Glass breakage liability:Borosilicate infuser formats carry higher return and warranty costs, limiting mass-market retailer shelf space allocation relative to metal and polymer alternatives.
- California Proposition 65 friction:Warning label requirements for certain plasticizers create state-level compliance complexity that fragments US distribution packaging strategies.
Strategic Opportunities
- Collapsible silicone travel formats:Space-constrained luggage and digital nomad mobility patterns are opening volume expansion in Japan and Germany for compressible infuser architectures.
- Double-wall vacuum insulation convergence:Thermal retention technology from outdoor beverage containers is migrating into infuser designs, enabling premium pricing in cold-brew tea and infused water segments.
- Corporate wellness program procurement:Employer-sponsored hydration initiatives are creating direct institutional sales channels bypassing traditional retail markup structures.
Industry Challenges
- Food-contact certification timelines:FDA 21 CFR and EFSA material approvals require 12-18 month validation cycles that delay new polymer introductions and lock in incumbent suppliers.
- Flavor cross-contamination prevention:Silicone seal engineering and chamber isolation design demands specialized polymer science expertise that concentrates among a limited supplier base.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infuser Water Bottles Market |
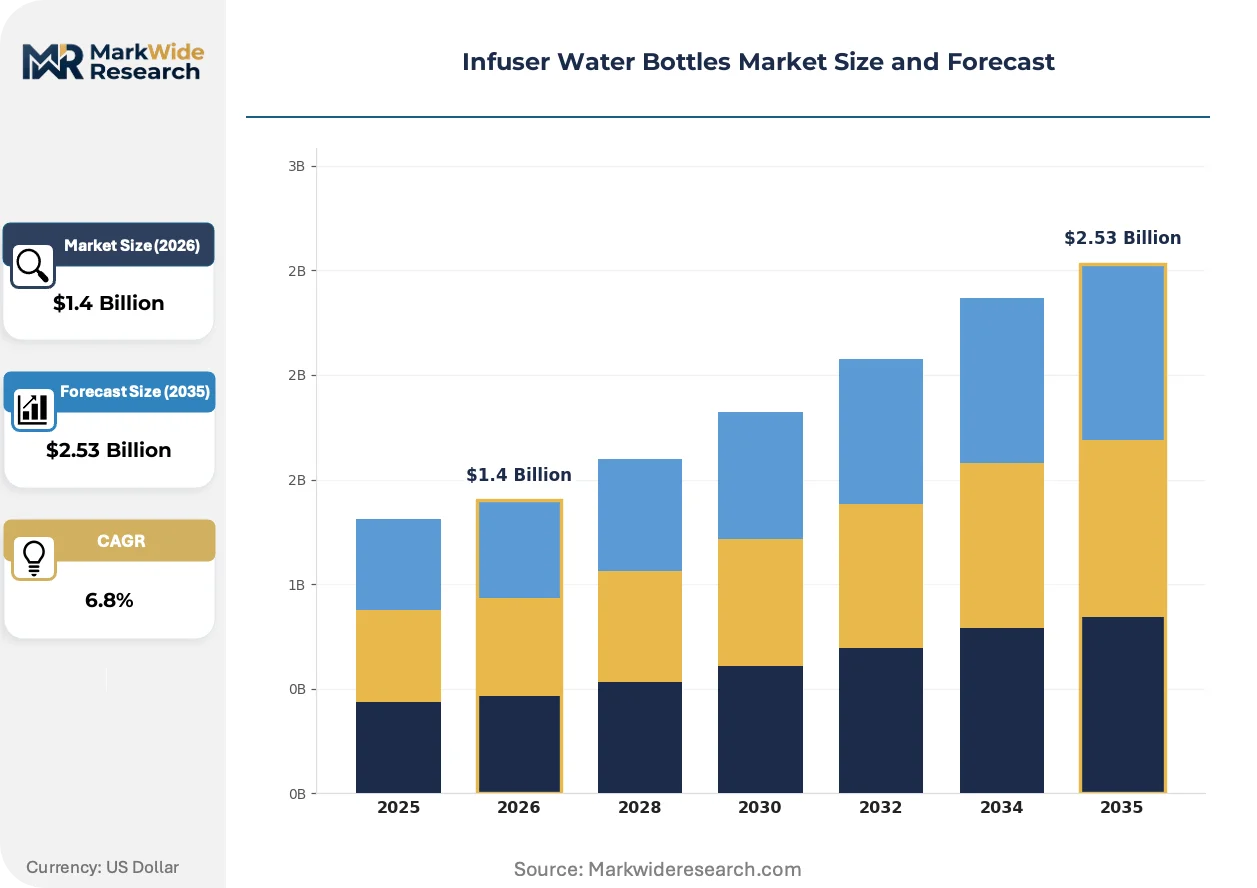
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass Infuser, Plastic Infuser, Stainless Steel Infuser, Collapsible Infuser Feature: Leak-proof, Insulated, Filtered, Eco-friendly End User: Fitness Enthusiasts, Office Workers, Travelers, Outdoor Adventurers Capacity: 500ml, 700ml, 1000ml, 1500ml |
| Companies Covered | Stanley, S’well, CamelBak Products LLC, Air Up GmbH, Asobu, Contigo, Owala, Infuse Pro, Hydro Flask, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infuser Water Bottles Market Shifts & Advancements
Material science advances and regulatory chemical restrictions are converging to reshape infuser construction, thermal performance claims, and distribution channel strategies across fitness, workplace, and travel use cases.
Copper-lined vacuum insulation is absorbing thermal performance expectations from premium outdoor beverage categories into infuser formats. Fitness enthusiasts and cold-brew tea consumers are adopting these variants for extended temperature retention during workouts and commutes. This technology is absorbing margin compression pressures on single-wall stainless steel alternatives by establishing new performance tiers that justify price premiums.
The EU F-Gas Regulation is constraining fluorinated greenhouse gas choices in insulation manufacturing processes, compelling thermal bottle producers to certify alternative gas fills and disclose supply chain emissions. European importers are reformulating supplier qualification criteria to prioritize REACH-compliant material declarations. German retailers are demanding batch-level chemical traceability documentation that exceeds baseline EU requirements.
Employer direct procurement is consolidating hydration equipment purchasing through corporate wellness vendors and facilities management platforms. Traditional sporting goods and housewares distributors are losing share to specialized B2B wellness service providers. This pattern concentrates in United States technology and financial services sectors where employee amenity budgets sustain premium infuser specifications.
Infuser Water Bottles Market Segmentation
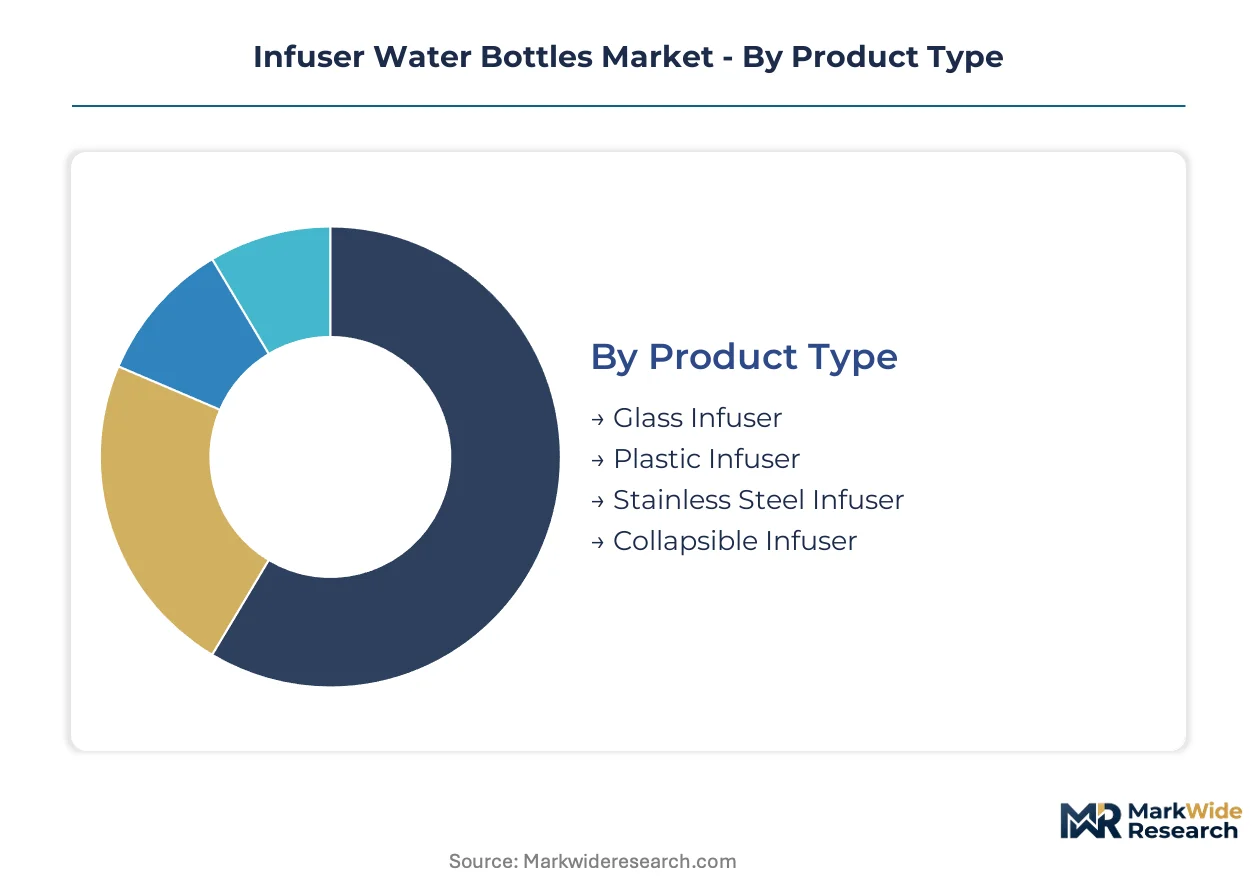
Infuser water bottle procurement patterns diverge sharply across material preferences, thermal requirements, and mobility constraints. Each segment carries distinct certification burdens and margin profiles that reshape supplier qualification strategies and distribution channel selection.
Product Type:
FDA 21 CFR food-contact substance approvals govern all polymer variants, while EU REACH chemical disclosure requirements intensify scrutiny on plastic infuser chambers. Stainless steel formats face additional nickel migration testing under EFSA protocols.
- Glass Infuser:Borosilicate construction delivers chemical purity without plasticizer contamination risks. Demand concentrates among German and Japanese consumers prioritizing transparency and taste neutrality, though breakage liability elevates return costs and limits mass-retailer shelf allocation.
- Stainless Steel Infuser:Double-wall vacuum insulation variants command premium positioning through thermal retention performance. Fitness enthusiasts across the United States and Germany are expanding procurement of these formats for cold-brew tea and extended workout hydration.
- Plastic Infuser:Tritan copolyester dominates economy-tier production with BPA-free certification as baseline entry requirement.
- Collapsible Infuser:Silicone-compressible architectures target space-constrained travelers in Japan and Germany with fold-flat storage profiles.
Stainless steel infuser sits at the top of the volume ranking, with collapsible infuser climbing the fastest.
Feature:
Feature differentiation maps directly onto price tier stratification and end-use occasion specificity. Thermal performance and sealing integrity attract divergent engineering investments and warranty cost structures.
- Leak-proof:Silicone gasket engineering and threaded seal design prevent transit spills for commuter segments. Office workers in Germany and the United States prioritize this specification for daily bag-carry routines.
- Insulated:Copper-lined vacuum chambers extend temperature retention for cold-brew tea and infused water applications. Fitness enthusiasts are absorbing these variants into home workout and gym culture hydration rituals.
- Filtered:Activated carbon or mesh screen integration removes chlorine and particulates for taste-sensitive consumers.
- Eco-friendly:Recycled content certification and end-of-life recyclability claims align with corporate wellness procurement criteria.
Leak-proof specification anchors current volume leadership, while insulated variants gain share fastest among premium repositioning efforts.
End User:
End user segmentation reveals divergent replacement cycle frequencies and specification trade-off tolerances. Institutional procurement channels are reshaping traditional retail distribution patterns for specific segments.
- Fitness Enthusiasts:Higher-capacity insulated formats dominate with thermal retention and durability as non-negotiable specifications. Home workout platform integrations and health club amenity programs are normalizing flavored hydration rituals across Germany and the United States.
- Office Workers:Leak-proof sealing and single-hand operation prioritize transit convenience and desk-side use. Commuter patterns in Japan and Germany sustain replacement demand through wear-and-tear cycles.
- Travelers:Collapsible and lightweight formats address luggage constraints and TSA compliance for air mobility.
- Outdoor Adventurers:Impact-resistant construction and extended capacity support hiking and camping hydration requirements.
Fitness enthusiasts occupy the top volume position, with office workers expanding most quickly through employer-sponsored wellness program channels.
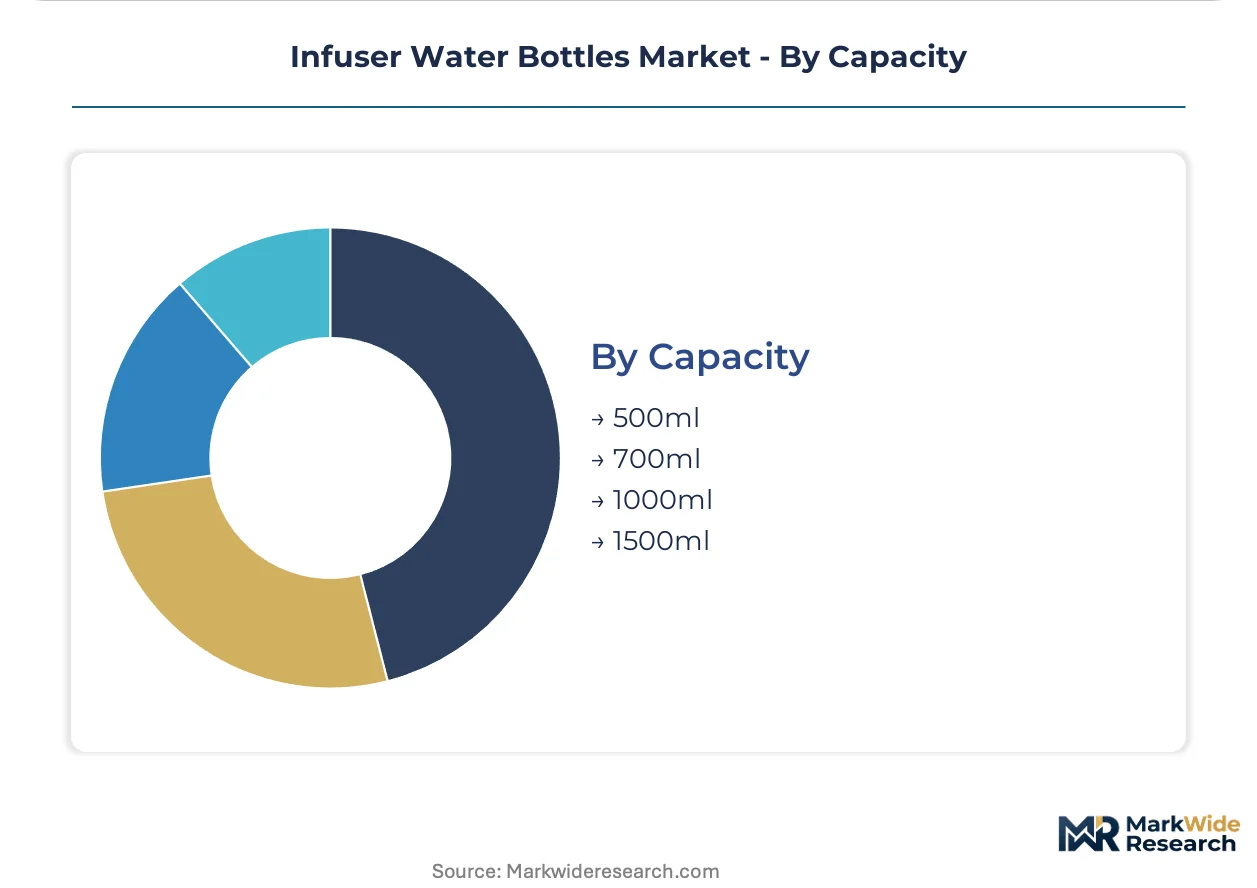
Capacity:
Capacity selection reflects usage occasion duration and portability trade-offs. Manufacturing economies concentrate in mid-range formats with tooling amortization spread across highest production volumes.
- 500ml:Compact pocket formats target minimalist carry and short-duration hydration. Travelers in Japan favor this specification for urban mobility and bag-weight reduction.
- 700ml:Mid-range versatility balances portability with adequate volume for standard workday or workout sessions. Office workers across Germany and the United States treat this as default procurement specification.
- 1000ml:Extended duration formats support all-day hydration without refill requirements.
- 1500ml:Maximum capacity variants address outdoor adventurer and intensive training segment requirements.
700ml capacity leads volume rankings, with 1000ml formats showing steepest expansion trajectory among fitness culture embedding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision manufacturing clusters around Stuttgart and Hamburg anchor European infuser bottle production, with REACH compliance documentation serving as the de facto export standard for premium stainless steel and glass variants across adjacent markets.
Germany
Fitness culture embedding and commuter hydration routines drive procurement of leak-proof insulated formats among office workers in Berlin and Munich. ECHA's REACH substance restriction lists force manufacturers to accelerate borosilicate glass and food-grade stainless steel substitutions. The Stuttgart industrial corridor concentrates vacuum insulation technology suppliers serving premium thermal retention specifications.
United States
Home workout platform integrations and health club amenity programs normalize flavored hydration rituals from Austin to Denver. FDA 21 CFR food-contact substance approvals constrain permissible plasticizers in Tritan copolyester chambers. California's Proposition 65 warning requirements fragment distribution packaging strategies, with Los Angeles and San Francisco retailers demanding batch-level chemical traceability exceeding federal baselines.
Japan
Space-constrained urban mobility and digital nomad travel patterns expand demand for collapsible silicone formats in Tokyo and Osaka. METI's product safety standards govern food-grade silicone gasket specifications for compressible architectures. The Kansai manufacturing belt around Osaka anchors specialized polymer science expertise for flavor cross-contamination prevention engineering.
United Kingdom
Corporate wellness program procurement channels reshape institutional purchasing through London-based facilities management platforms. The UK's post-Brexit chemical regulatory divergence from REACH creates dual compliance burdens for imported infuser components. Manchester and Birmingham distribution hubs handle cross-border logistics for EU-manufactured glass and stainless steel variants.
China
Contract manufacturing scale and tooling amortization efficiencies concentrate Tritan copolyester and silicone gasket production in Guangdong and Zhejiang provinces. SAMR's national food-contact material standards align gradually with international certification requirements. The Pearl River Delta cluster supplies collapsible infuser architectures for Japanese and German brand owners.
Infuser Water Bottles Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbents extend thermal retention capabilities from outdoor beverage categories into infuser formats. The vendor base organizes across three tiers: heritage outdoor brands with vacuum insulation expertise, housewares specialists with leak-proof sealing engineering, and direct-to-consumer challengers with collapsible travel architectures. Strategic archetypes include thermal performance leaders, commuter convenience optimizers, and space-constrained mobility specialists. M&A activity targets specialized silicone seal engineering capabilities, while capacity expansion concentrates in REACH-compliant European and FDA-registered North American facilities.
Within the heritage outdoor tier, CamelBak Products LLC and Hydro Flask exemplify thermal technology migration strategies, with the former leveraging adventure-oriented positioning and the latter anchoring premium pricing through double-wall vacuum insulation heritage. Contigo occupies a position within the commuter convenience archetype, representing leak-proof sealing mechanism specialization for daily transit patterns. Air Up GmbH sits within the flavor innovation vector, demonstrating European-based challenger positioning through alternative hydration enhancement approaches. These three companies collectively illustrate the competitive spectrum from outdoor heritage through commuter functionality to sensory technology differentiation.
| Leading Market Players |
|---|
| Stanley |
| S'well |
| CamelBak Products LLC |
| Air Up GmbH |
| Asobu |
| Contigo |
| Owala |
| Infuse Pro |
| Hydro Flask |
| Others |
Supply & Pricing Matrix
Polymer science expertise concentrated in Germany's Kansai manufacturing belt and Guangdong's Pearl River Delta cluster drives labor-cost differentials that widen pricing-tier spreads between REACH-compliant stainless steel variants and economy-tier Tritan copolyester formats. FDA 21 CFR certification timelines and EFSA nickel migration testing requirements embed compliance premiums into premium-tier positioning.
Pricing Analysis
Food-grade silicone input cost pass-through from petrochemical feedstock markets compresses margin pools on economy-tier plastic infuser variants while copper-lined vacuum insulation technology absorbs pricing pressure through performance-tier premiums. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and thermal retention capability, with California Proposition 65 compliance costs fragmenting US distribution packaging strategies. Office workers in Germany and Japan exhibit highest price sensitivity for commuter formats, while fitness enthusiasts absorb premium positioning for cold-brew tea applications.
Supply Chain Analysis
Container freight rate volatility from Guangdong and Zhejiang provinces to German distribution hubs and US West Coast ports shapes landed cost differentials between contract-manufactured and REACH-registered European production. Tritan copolyester, food-grade silicone gaskets, and borosilicate glass feed from China's Pearl River Delta cluster, Japan's Kansai belt, and Germany's Stuttgart corridor. Single-source vulnerability concentrates in specialized silicone seal engineering for flavor cross-contamination prevention. Distribution runs through traditional sporting goods and housewares channels, with corporate wellness vendors capturing institutional procurement share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EU REACH substance restriction list expansions accelerate material substitution demand and compliance documentation premiums.
For Market Incumbents: To counter margin compression from silicone gasket cost volatility, accelerate backward integration into food-grade polymer compounding capabilities and lock in multi-year REACH certification maintenance contracts with Stuttgart-area testing laboratories. Anchor channel control through exclusive corporate wellness program partnerships that bypass retail markup structures. For New Entrants and Emerging Players: REACH chemical transparency requirements in Germany open a window for borosilicate glass and food-grade stainless steel challengers to capture compliance-focused importer procurement. Target Japan's digital nomad segment with collapsible silicone architectures certified under METI product safety standards. Pursue direct-to-consumer launch through home workout platform integrations. For Investors and Strategic Acquirers: Specialized B2B wellness service providers are the most active acquirer in this space, consolidating employer direct procurement channels. Long-term viability hinges on regulatory certification moats rather than brand equity alone. Watch for batch-level chemical traceability documentation demands from German retailers as inflection indicator for compliance-cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Material Substitution | EFSA nickel migration testing and ECHA substance restrictions lock in premium-tier positioning for European manufacturers. |
| Corporate Wellness Channel Expansion | Employer-sponsored hydration initiatives in US technology and financial services sectors bypass traditional retail markups. |
| Double-Wall Vacuum Insulation Convergence | Thermal retention technology from outdoor beverage categories migrates into infuser designs for cold-brew tea segments. |
| Silicone Seal Engineering Acquisition | Specialized polymer science expertise for flavor cross-contamination prevention concentrates among limited supplier base. |
| Collapsible Format Premium Repositioning | Space-constrained luggage and digital nomad mobility in Japan and Germany open volume expansion for compressible architectures. |
Research Methodology
Bottom-up fitness enthusiast and office worker demand modeling reconciled against top-down Tritan copolyester and stainless steel supply tracking forms the analytical core of this study. Primary interviews with brand managers at heritage outdoor equipment companies, category buyers at German and US retailers, silicone seal engineering specialists in Japan's Kansai belt, and corporate wellness program procurement officers combined with secondary validation from FDA 21 CFR food-contact substance filings, ECHA REACH registration databases, METI product safety standard disclosures, and customs trade records for infuser bottle imports.
Input-output matrices mapped polymer raw material flows through Guangdong contract manufacturers to end-use segmentation across capacity tiers, thermal performance specifications, and regional regulatory clusters. Modeled dimensions span material type, insulation feature, end-user archetype, and capacity format across the analysis window. CAGRs derived from regression against fitness culture embedding indices and commuter hydration routine penetration rates, with cold-brew tea consumption trends and employer wellness budget allocations as industry-specific forecast inputs.
Revisions become necessary when ECHA expands REACH substance restriction lists, FDA accelerates 21 CFR food-contact approval timelines, or container freight rates from Chinese manufacturing clusters experience sustained volatility. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
US Soap Dispenser Market
Household Items
Global Disposable Toilet Seat Covers Market
Household Items
Europe Coin-Operated Laundries Market
Household Items
North America Glassware Market
Household Items
Dishwasher Tablets Market
Household Items
Aquarium Heaters and Chillers Market
Household Items
Asia-Pacific Digital Showers Market
Household Items
Global Wet Vacuum Cleaner Market
Household Items
Barbeque Grill Market
Household Items
Disposable Napkins Market
Household Items
Coin-Operated Laundries Market
Household Items
Indoor Humidifier Market
Household Items
Basin, Bowl, and Cup Market
Household Items
Industrial Vacuum Cleaner Market
Household Items
US Handheld Vacuum Cleaners Market
Household Items
Manual Bottle Opener Market