
 Electric Soap Dispenser Market | 2026-2036
Electric Soap Dispenser Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Soap Dispenser Market Foresight
The capability gap between sensor-integrated manufacturers and basic assembly houses is collapsing as infrared module costs fall and firmware becomes commoditized. TOTO LTD. leverages its Japan-based ceramics and electronics supply chain to dominate premium wall-mounted installations in commercial washrooms. simplehuman sustains brand strength through direct-to-consumer channels and design-forward countertop units that command shelf space at specialty retailers. Shenzhen SVAVO Intelligent Technology Co., Ltd competes on manufacturing scale, shipping high-volume automatic dispensers to facility management contractors across Asia and the Middle East.
An electric soap dispenser is an electronically actuated liquid or foam delivery device employing infrared proximity sensors, peristaltic pumps, or piezoelectric mechanisms to dispense measured doses without manual contact, typically operating on battery or AC power with IP-rated housings for moisture resistance. Its primary commercial purpose is to reduce cross-contamination in high-traffic hygiene environments while controlling consumable usage through calibrated dosing algorithms. Automatic technology leads unit shipments due to standardized sensor costs, yet hybrid systems combining touchless activation with manual backup represent the fastest-growing configuration as facilities seek redundancy against power failures. Stainless steel material commands the margin pool in healthcare and premium commercial segments, while plastic dominates residential volume through price-accessible countertop designs.
The FDA regulates antimicrobial soap claims and device sanitation standards in healthcare settings, while EPA oversees chemical compatibility of dispenser materials with registered sanitizers. ECHA REACH compliance shapes European market access by restricting certain phthalates in plastic housings and nickel release rates from stainless steel finishes. Stakeholders must monitor evolving building codes in Germany, California, and Japan that increasingly mandate touchless fixtures in public infrastructure bids, as specification decisions made by architects and procurement officers will determine which technology-material combinations secure long-term volume commitments.
Market Dynamics
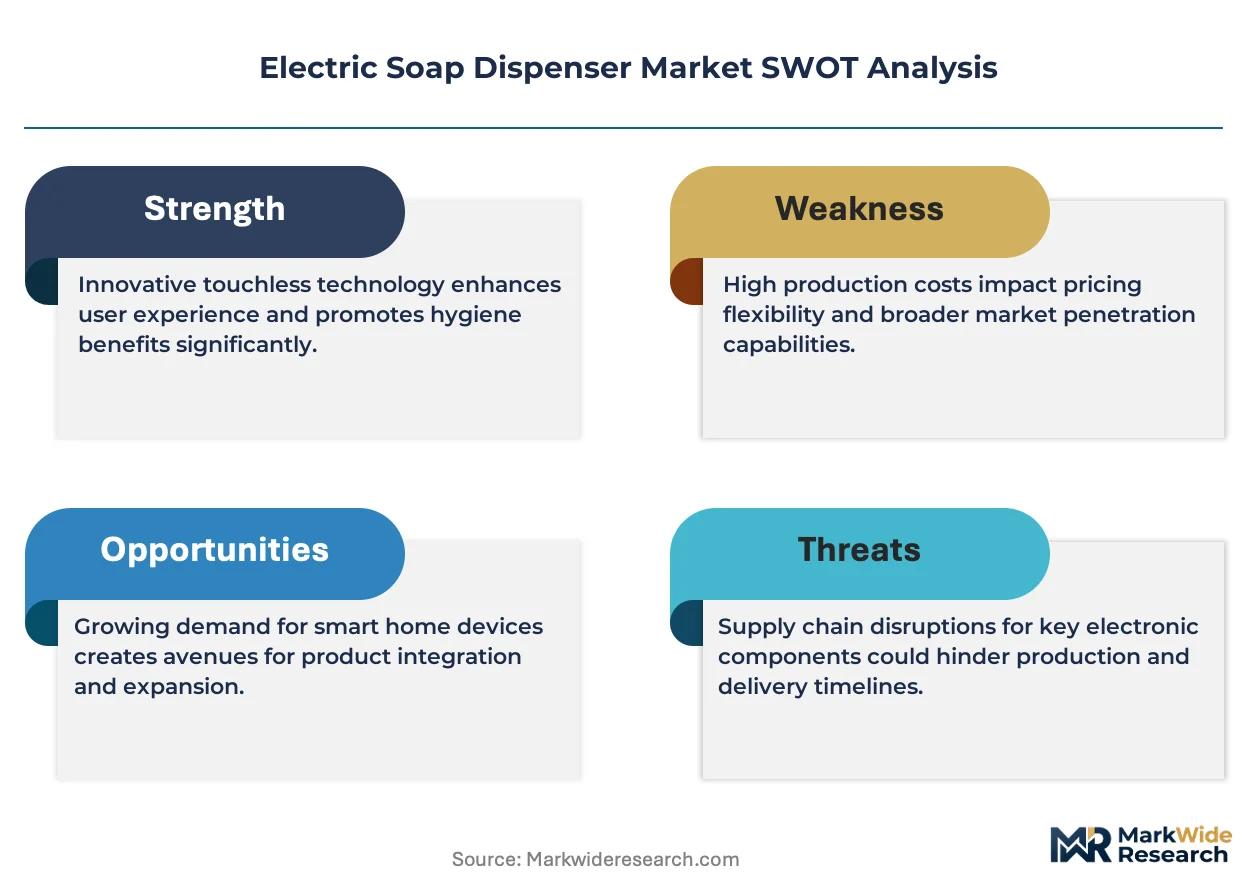
Infrared proximity sensor costs have collapsed below the threshold where basic assembly houses can match integrated manufacturers on touchless activation, eroding the capability moat that once separated premium and commodity tiers in commercial washroom fixtures.
Growth Catalysts
- Post-pandemic building code mandates:Germany's updated hygiene infrastructure standards now require touchless fixtures in all new public facility construction, forcing procurement officers to specify automatic dispensing systems.
- Healthcare cross-contamination protocols:Hospital infection control committees are standardizing infrared-activated units across patient rooms and surgical suites to eliminate reservoir contact points.
- Stainless steel reservoir demand:EPA chemical compatibility requirements for registered sanitizers are driving material upgrades in North American healthcare facilities.
Market Restraints
- Lithium battery supply concentration:Cell production for dispenser power modules clusters in East Asian contract manufacturers, exposing brands to input volatility and logistics bottlenecks.
- Phthalate substitution costs:ECHA REACH restrictions on plasticizer compounds in sensor housings force reformulation of ABS and polycarbonate resins, raising unit material expenses.
- Manual pump legacy stock:Existing installed base of squeeze-bottle and push-pump dispensers in budget hospitality chains creates replacement inertia and extended replacement cycles.
Strategic Opportunities
- Hybrid power architectures:Battery-AC dual-mode systems with manual backup activation represent an unclaimed configuration tier between pure automatic and legacy manual units.
- Facility management contractor channels:Direct specification relationships with multi-site property service firms bypass fragmented distributor networks and capture recurring consumable attach rates.
- IP-rated outdoor installations:Parks, transit stations, and stadium concourses in Japan and California present specification gaps where moisture-resistant stainless steel units command placement premiums.
Industry Challenges
- Firmware integration complexity:Calibrating sensor-pump algorithms for variable viscosity foam and liquid formulations requires embedded systems expertise scarce in traditional plumbing fixture engineering teams.
- Multi-jurisdiction certification timelines:Securing simultaneous FDA device sanitation clearance, EPA chemical compatibility validation, and ECHA REACH material compliance extends product launch windows by 14-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Soap Dispenser Market |
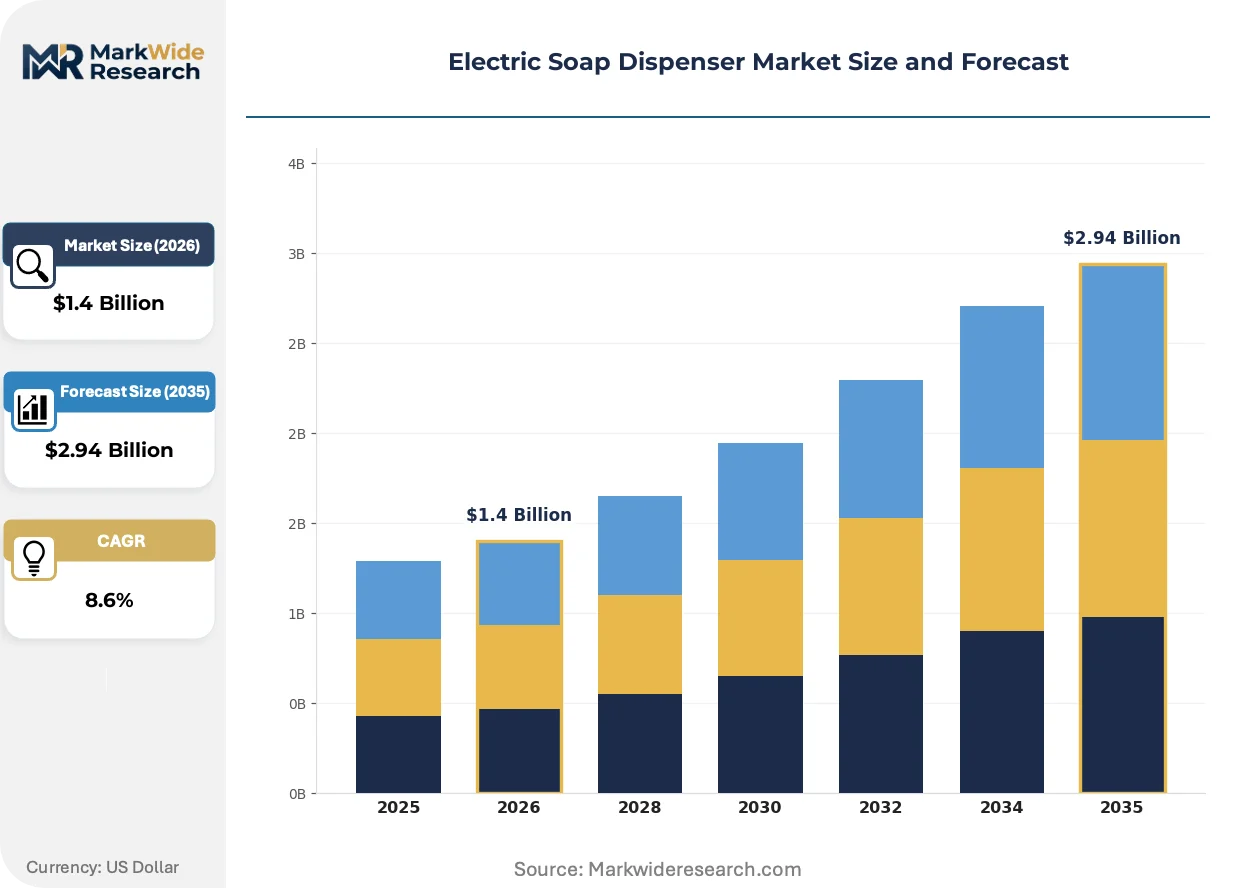
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Wall-mounted, Portable, Countertop End User: Residential, Commercial, Healthcare, Educational Material: Plastic, Stainless Steel, Glass, Aluminum Technology: Infrared, Touchless, Button-operated, Hybrid |
| Companies Covered | TOTO LTD., simplehuman, American Specialties, Inc., Bobrick Washroom Equipment, Inc., GOJO Industries, Umbra, ORCHIDS INTERNATIONAL, Kimberly-Clark, Shenzhen SVAVO Intelligent Technology Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Soap Dispenser Market Shifts & Advancements
Component commodification is fragmenting competitive advantage across three vectors: sensor module standardization, firmware open-sourcing, and contract manufacturing scale economics that favor new entrants over incumbents.
Peristaltic pump mechanisms are decomposing the traditional solenoid valve architecture that dominated early automatic dispenser generations. Healthcare procurement officers in the United States and Germany are specifying tube-based dosing systems for their superior chemical compatibility with high-alcohol sanitizers and reduced clogging incidence. This shift is compressing margins for valve-specialist component suppliers while enabling Asian contract manufacturers to capture pump assembly value previously held by European precision engineering houses.
REACH Annex XVII restrictions on nickel release rates from metallic finishes are compelling stainless steel reservoir suppliers to migrate toward 316L grade or polymer-lined alternatives. European market access now hinges on laboratory certification documentation that adds 8-12 weeks to production ramps. German healthcare facility architects are responding by writing explicit material grade specifications into public infrastructure bids, effectively filtering non-compliant suppliers before competitive tender stages.
Building service contractors are consolidating vendor relationships around single-source automatic hygiene system providers who bundle dispenser hardware, consumable refills, and maintenance telemetry into unified service agreements. This disintermediates traditional plumbing distributors and captures multi-year specification lock-in. The pattern is most visible in California and Japan where integrated facility management platforms like CBRE and JLL control washroom upgrade budgets across corporate campus portfolios.
Electric Soap Dispenser Market Segmentation
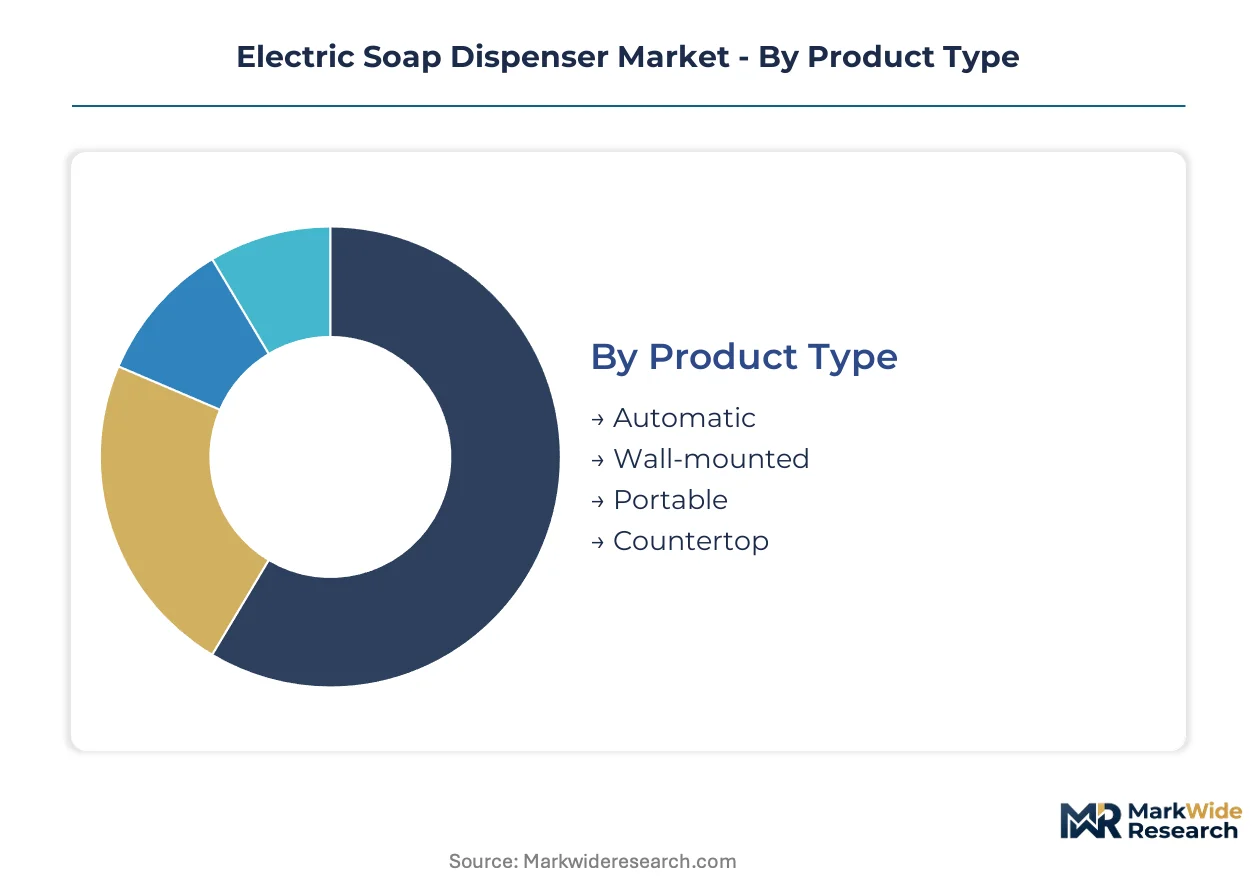
Segmentation in electric soap dispensers reveals where substitution pressure from manual alternatives and competing hygiene technologies reshapes procurement priorities. Specification decisions by architects, infection control officers, and facility managers hinge on which configuration-material-technology combinations deliver measurable cross-contamination reduction at acceptable lifecycle cost.
Product Type:
Wall-mounted and automatic configurations face the strongest substitution threat from hybrid systems that combine touchless activation with manual backup, as facilities seek redundancy against power failures and battery depletion.
- Automatic:Infrared-activated units with peristaltic pump mechanisms dominate healthcare procurement in the United States and Germany due to standardized sensor costs and elimination of reservoir contact points. Hospital infection control committees specify these for patient rooms and surgical suites where EPA chemical compatibility requirements drive material upgrades.
- Wall-mounted:Fixed installations in commercial washrooms leverage existing plumbing infrastructure and reduce countertop clutter. TOTO LTD. dominates premium specifications in Japan through ceramics and electronics supply chain integration, while facility management contractors across California consolidate vendor relationships around bundled service agreements.
- Portable:Battery-powered mobile units serve temporary event infrastructure and construction site hygiene stations where permanent installation is impractical.
- Countertop:Design-forward units command shelf space at specialty retailers through direct-to-consumer channels, with plastic construction enabling price-accessible residential volume.
Automatic retains volume leadership; hybrid holds the steepest expansion curve as procurement officers prioritize operational redundancy.
End User:
Cost tier stratification separates specification authority between capital-project architects and recurring-service procurement officers across customer categories.
- Healthcare:Infection control protocols mandate infrared-activated stainless steel units with 316L grade reservoirs to satisfy ECHA REACH nickel release restrictions. German facility architects write explicit material specifications into public infrastructure bids, filtering non-compliant suppliers before tender stages.
- Commercial:Corporate campuses and hospitality chains balance upfront hardware cost against consumable attach rates, with CBRE and JLL controlling washroom upgrade budgets across multi-site portfolios in California and Japan.
- Residential:Price-sensitive countertop plastic designs dominate volume through mass retail channels, though design premiums persist in specialty segments.
- Educational:K-12 and university procurement prioritizes durability and vandal resistance over sensor sophistication, extending replacement cycles for manual pump legacy stock.
Healthcare commands margin concentration; commercial delivers the steepest volume acceleration through facility management contractor consolidation.
Material:
Supply concentration in East Asian contract manufacturers shapes margin distribution between commodity plastic housings and certified metallic finishes.
- Stainless Steel:316L grade reservoirs with polymer linings satisfy ECHA REACH Annex XVII nickel release restrictions for European market access. Laboratory certification documentation adds 8-12 weeks to production ramps, compelling suppliers to migrate from standard grades.
- Plastic:ABS and polycarbonate resins face reformulation costs from phthalate substitution under REACH restrictions, raising unit material expenses while maintaining residential price accessibility.
- Glass:Premium aesthetic applications in hospitality and residential segments where visible soap level monitoring enhances user experience.
- Aluminum:Lightweight alternative for portable and outdoor IP-rated installations in parks and transit stations where moisture resistance commands placement premiums.
Plastic retains shipment volume leadership; stainless steel holds the steepest margin expansion trajectory as healthcare procurement tightens material grade specifications.
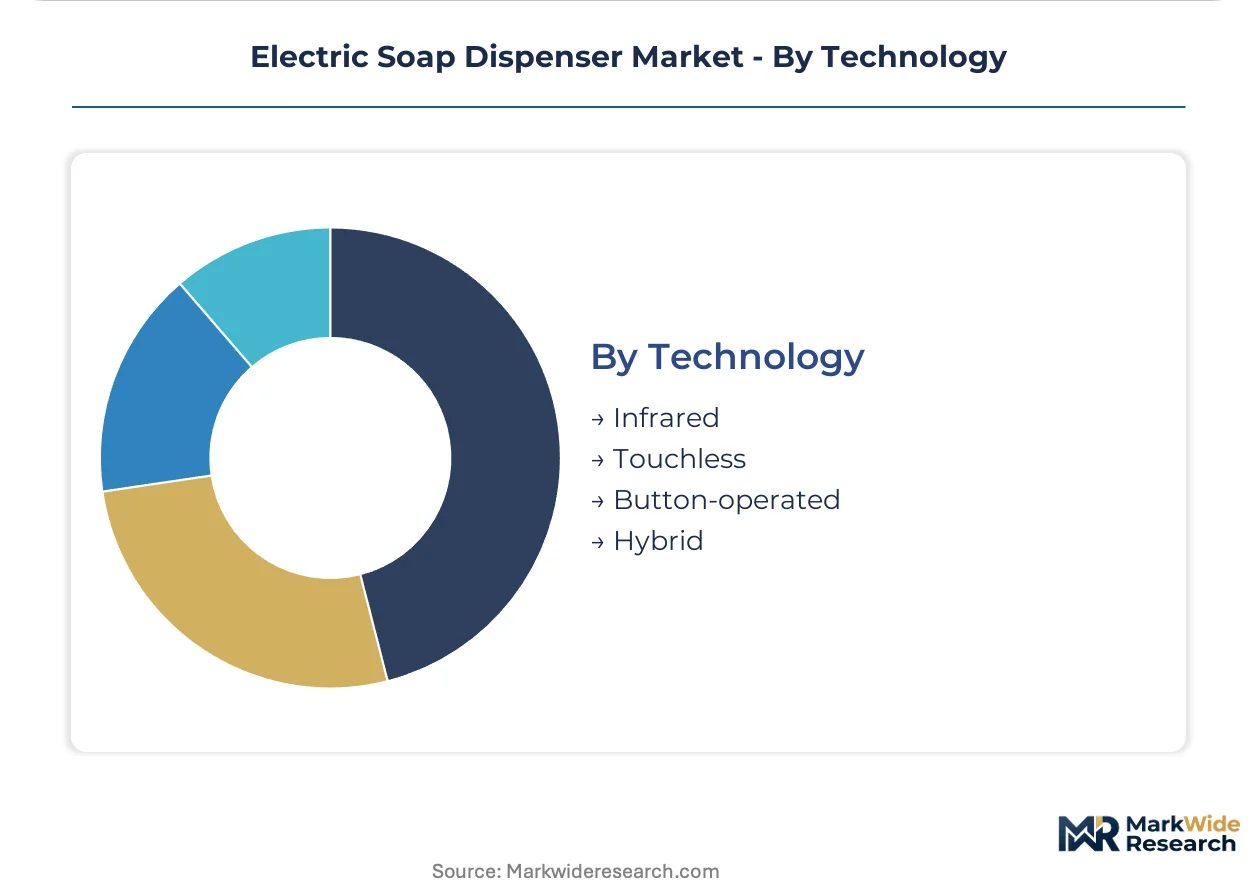
Technology:
Customer type differentiation separates specification authority between embedded systems engineering teams and traditional plumbing fixture procurement.
- Infrared:Proximity sensor modules below cost thresholds enable basic assembly houses to match integrated manufacturers on touchless activation, eroding capability moats between premium and commodity tiers.
- Hybrid:Battery-AC dual-mode systems with manual backup activation represent an unclaimed configuration tier between pure automatic and legacy manual units, gaining share fastest as facilities seek redundancy.
- Touchless:Ultrasonic and capacitive alternatives compete for specification in specialized environments where infrared interference from ambient lighting or reflective surfaces degrades performance.
- Button-operated:Electromechanical actuation persists in budget hospitality chains and educational institutions where capital constraints override hygiene protocol stringency.
Infrared retains specification dominance; hybrid climbs the fastest as building codes mandate touchless fixtures while operational risk management demands backup activation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan demonstrate the lowest price elasticity, accepting premium stainless steel specifications under stringent regulatory frameworks, while procurement officers in India and Southeast Asia prioritize unit cost minimization over material certification documentation.
United States
Healthcare facility architects specify infrared-activated dispensers for patient rooms and surgical suites to satisfy FDA device sanitation standards. EPA chemical compatibility requirements for registered sanitizers drive material upgrades toward 316L grade stainless steel reservoirs. California building codes mandate touchless fixtures in public infrastructure bids, with facility management contractors consolidating vendor relationships across corporate campus portfolios.
Germany
Updated hygiene infrastructure standards require touchless fixtures in all new public facility construction, eliminating procurement discretion. ECHA REACH Annex XVII restrictions on nickel release rates from metallic finishes compel suppliers to migrate toward certified 316L grade or polymer-lined alternatives. Bavarian healthcare facility architects write explicit material specifications into public tenders, filtering non-compliant suppliers before competitive stages.
Japan
Post-pandemic building codes accelerate washroom infrastructure upgrades in commercial and transit environments. METI standards shape domestic certification requirements for sensor-integrated fixtures in high-traffic applications. The Kanto region around Tokyo concentrates premium wall-mounted installations, with ceramics and electronics supply chain integration enabling rapid specification response.
China
Manufacturing scale economics favor high-volume automatic dispenser production for export to facility management contractors across Asia and the Middle East. GB standards govern domestic product safety while export-oriented producers navigate multi-jurisdiction certification timelines. Shenzhen-based assemblers leverage collapsed infrared sensor module costs to match integrated manufacturers on touchless activation.
India
Budget hospitality chains and educational institutions extend replacement cycles for manual pump legacy stock due to capital constraints. BIS certification requirements for electronic fixtures create entry barriers for unorganized sector suppliers. Maharashtra and Gujarat industrial corridors host contract manufacturing operations serving price-sensitive residential countertop segments.
Electric Soap Dispenser Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated manufacturers competing on embedded systems expertise while scale-driven assemblers capture volume through manufacturing economics. The vendor base spans three tiers: premium specification holders with certified material documentation, mid-market hybrid system providers, and commodity infrared module integrators. Dominant competitive moves include backward integration into sensor module sourcing and direct specification relationships with multi-site facility management contractors.
Among Japan-based integrated manufacturers, TOTO LTD. anchors the premium wall-mounted installation segment through ceramics and electronics supply chain control. simplehuman occupies a position within the design-forward direct-to-consumer tier, commanding shelf space at specialty retailers through countertop unit aesthetics. Shenzhen SVAVO Intelligent Technology Co., Ltd exemplifies the scale-driven contract manufacturing archetype, shipping high-volume automatic dispensers to facility management contractors across Asia and the Middle East.
| Leading Market Players |
|---|
| TOTO LTD. |
| simplehuman |
| American Specialties, Inc. |
| Bobrick Washroom Equipment, Inc. |
| GOJO Industries |
| Umbra |
| ORCHIDS INTERNATIONAL |
| Kimberly-Clark |
| Shenzhen SVAVO Intelligent Technology Co., Ltd |
| Others |
Supply & Pricing Matrix
Eight-to-twelve-week laboratory certification delays for 316L grade stainless steel documentation compress inventory turns and shift pricing power toward suppliers with pre-certified material stockpiles in Germany and Japan. Procurement officers in healthcare facilities face extended lead-time bands that force premium absorption for compliant reservoir grades, while plastic housing assemblers in Shenzhen exploit collapsed infrared sensor costs to undercut on unit pricing.
Pricing Analysis
Consumable refill contracts and maintenance telemetry subscriptions drive lifetime value beyond hardware margins. Three-tier pricing structure across premium stainless steel, mid-market hybrid systems, and economy plastic units separates specification tiers by ECHA REACH certification status. Cost compression in commodity infrared modules intensifies as Shenzhen assemblers match integrated manufacturers on touchless activation. Budget hospitality chains in India exhibit highest price sensitivity, while German healthcare facility architects accept premium absorption for documented 316L grade compliance.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for sensor modules and peristaltic pump components sourced from contract manufacturers in China and South Korea. Lithium cell production clusters in East Asian power module suppliers, drawing from nickel and cobalt feedstocks with concentrated extraction profiles. Single-source vulnerability in infrared sensor module sourcing threatens production continuity for brands without dual-qualified component vendors. Distribution runs through facility management contractor direct specifications that disintermediate traditional plumbing distributors in California and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded systems expertise for sensor-pump algorithm calibration remains scarce among traditional plumbing fixture engineering teams, creating a persistent capability gap that separates specification winners from commodity assemblers.
For Market Incumbents: Fortify backward integration into peristaltic pump mechanisms to capture value previously held by European precision engineering houses. Deepen certification investment in ECHA REACH Annex XVII documentation to maintain German healthcare specification access against Asian contract manufacturers eroding capability moats through collapsed sensor costs. For New Entrants and Emerging Players: Anchor in hybrid power architectures combining battery-AC dual-mode systems with manual backup activation, an unclaimed configuration tier between pure automatic and legacy manual units. Target IP-rated outdoor installations in Japanese transit stations and California parks where moisture-resistant stainless steel units command placement premiums and specification relationships remain unconsolidated. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified building products conglomerates with under-monetized washroom fixture divisions lacking embedded systems capabilities. Long-term viability hinges on firmware integration expertise and direct facility management contractor relationships. Watch for consolidation signals when multi-site property service firms bundle dispenser hardware into unified hygiene service agreements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Module Sourcing | Captures value from commoditized infrared components and secures supply continuity against East Asian logistics bottlenecks. |
| ECHA REACH Certification Investment | Unlocks German healthcare procurement where architects filter non-compliant suppliers before tender stages. |
| Direct Facility Management Contractor Relationships | Bypasses fragmented distributor networks and locks in multi-year consumable attach rates with CBRE and JLL. |
| Hybrid Power Architecture Development | Addresses operational redundancy demand from building codes mandating touchless fixtures while mitigating power failure risk. |
| IP-Rated Outdoor Product Line Expansion | Captures specification gaps in Japanese transit infrastructure and California public parks with moisture-resistant stainless steel designs. |
Research Methodology
Desk research of customs trade databases, EPA chemical compatibility filings, and ECHA REACH registration records preceded structured interviews with hospital infection control officers, facility management procurement directors, and sensor module contract manufacturing executives. Primary fieldwork with German healthcare architects and California building service contractors combined with secondary validation against GB standards documentation and METI certification requirements. Bottom-up shipment estimates triangulated against top-down hygiene infrastructure spending projections.
Variance decomposition across product type, material grade, technology configuration, and end-use sector shaped the analytical framework over the projection horizon. Modeled dimensions included automatic versus hybrid activation systems, 316L grade versus standard stainless steel versus plastic housings, and healthcare versus commercial versus residential demand clusters. CAGRs derived from segment-level growth rate reconciliation with macro hygiene infrastructure investment patterns, incorporating peristaltic pump adoption curves and REACH regulatory compliance timelines as industry-specific forecast inputs.
Material uncertainties — lithium battery supply disruptions, nickel release rate standard revisions, and building code mandate acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions about sensor cost trajectories and certification timeline stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Handheld Fans Market
Household Items
Electric Shoe Dryer Market
Household Items
Global Electric Scissors Market
Household Items
Underwear Disinfection Dryers Market
Household Items
Smart Bathroom Market
Household Items
Kick Bucket Market
Household Items
Air Care Market
Household Items
US Flashlights Market
Household Items
Air Humidifier Market
Household Items
Tiki Torch Market
Household Items
Ironing Boards Market
Household Items
Massage Pillow Market
Household Items
Folded Tissues Market
Household Items
Global Refrigerator Water Filters Market
Household Items
Beach Towel Market
Household Items
Insulated Lunch Box Market