
 Residential Vacuum Cleaners Market | 2026-2036
Residential Vacuum Cleaners Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Vacuum Cleaners Market Analytics
Chinese contract manufacturers is restructuring capacity toward cordless and robotic assembly lines to serve brand owners worldwide. Dyson sustains premium positioning through proprietary digital motor technology and direct-to-consumer channel control. Miele anchors the high-end canister segment with German engineering credentials and extended product lifecycles. SharkNinja competes aggressively in North American retail through rapid product iteration and price-accessible feature sets.
Residential vacuum cleaners are electrically powered suction devices designed for floor and surface debris removal, typically operating at 100-240 volts with airflow rates of 20-100 cubic feet per minute depending on format. Their primary commercial purpose centers on maintaining indoor air quality and surface hygiene in domestic environments while minimizing manual labor. The cordless power source segment is capturing the fastest growth as lithium-ion battery energy density improvements enable runtime parity with corded units. Robotic product types are concentrating margin pools through software subscription attach rates and replacement component ecosystems. HEPA filtration features are maturing into baseline expectations rather than premium differentiators across most price tiers.
The EU Ecodesign Regulation and REACH framework constrain motor efficiency thresholds and material compositions for units sold in Europe, while the FDA maintains indirect influence through indoor air quality guidance that shapes HEPA marketing claims in the United States. China's GB standards and NMPA-adjacent quality certifications create compliance layering for brands accessing domestic retail channels. Stakeholders must weigh battery chemistry transitions against recycling infrastructure readiness as cordless volumes scale.
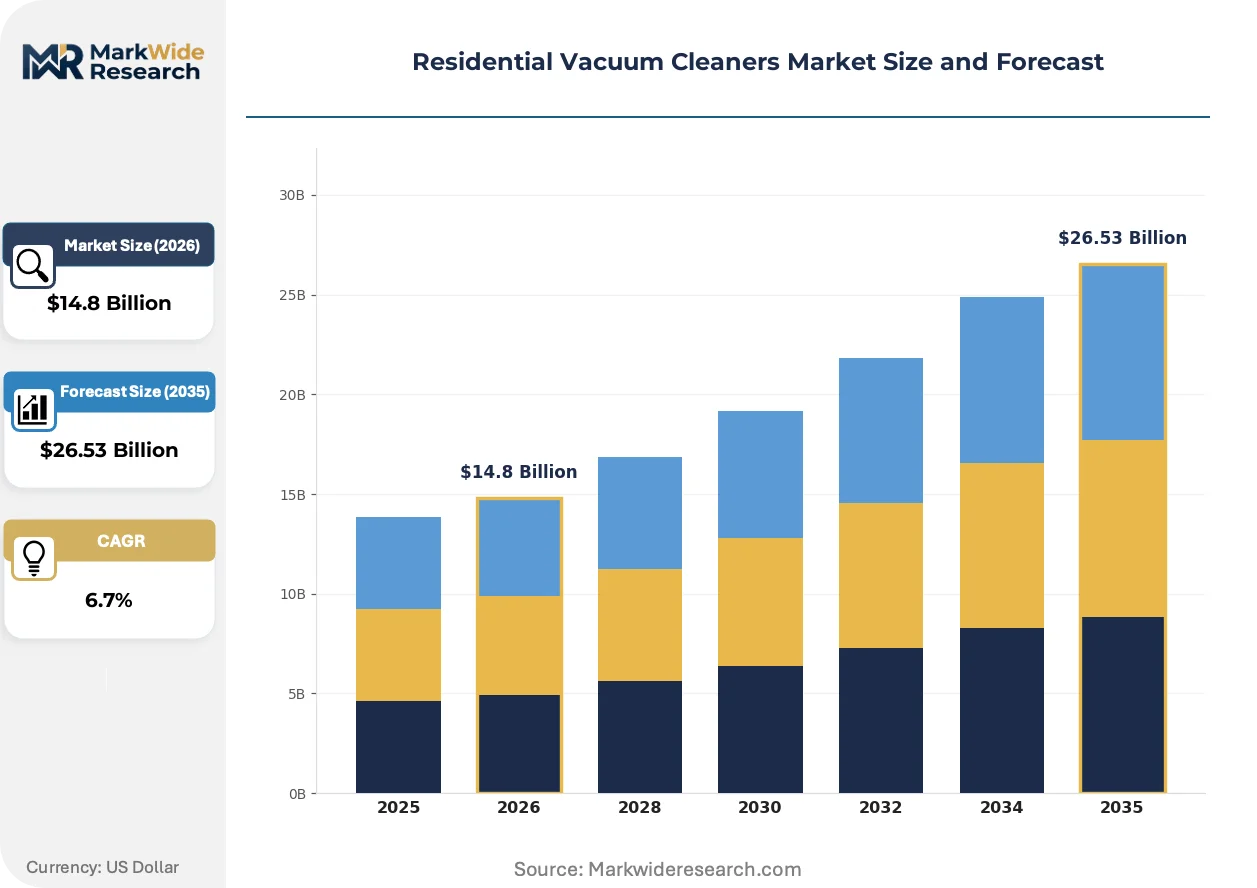
Market Dynamics
The EU Ecodesign Regulation is compressing motor efficiency tolerances while lithium-ion battery density advances are collapsing runtime gaps between cordless and corded formats, forcing incumbent manufacturers to restructure assembly priorities.
Growth Catalysts
- Lithium-ion energy density:Cell chemistry improvements now deliver 60-minute runtimes in stick formats, matching legacy corded suction performance and unlocking apartment-dwelling demand in dense urban centers.
- EU Ecodesign motor mandates:Tiered efficiency thresholds taking effect in 2025 are phasing out universal brushed motors, creating replacement cycles for compliant brushless designs across European retail channels.
- Robotic navigation convergence:Simultaneous localization and mapping algorithms developed for autonomous vehicles are migrating to residential robotics, enabling room-specific cleaning protocols without user intervention.
Market Restraints
- Neodymium magnet supply concentration:High-efficiency brushless motors require rare-earth elements where processing capacity clusters in China, exposing motor costs to export quota volatility.
- Cordless battery replacement economics:Lithium-ion pack degradation after 3-4 years creates lifecycle cost parity issues versus corded units with 15-year motor lifespans.
- REACH substance restrictions:The European Chemicals Agency is tightening limits on PVC and certain flame retardants in power cords and housings, complicating material sourcing for legacy suppliers.
Strategic Opportunities
- India urban middle-class expansion:Metro household formation in Mumbai and Bangalore is outpacing floor-care penetration, creating first-time buyer pools for robotic entry-level units.
- Software subscription attach:Robotic manufacturers are layering mapping storage, pet-recognition AI, and automated scheduling behind recurring revenue models with 40-60% gross margins.
- EU Green Deal repairability mandates:Pending right-to-repair requirements for electrical appliances will advantage brands with modular battery architectures and component availability.
Industry Challenges
- Brushless motor controller firmware:Field-programmable gate array programming expertise sits concentrated in automotive and industrial automation sectors, creating recruitment bottlenecks for appliance engineering teams.
- Multi-certification parallelism:Simultaneous UL, CE, and GB standard testing for global product launches extends development timelines by 8-12 months and fragments validation resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Residential Vacuum Cleaners Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Upright, Canister, Robotic, Handheld Power Source: Corded, Cordless, Battery Operated, Hybrid Feature: Bagless, HEPA Filtration, Smart Technology, Quiet Mode End User: Households, Cleaning Services, Property Managers, Rental Properties |
| Companies Covered | iRobot, Miele, Dyson, LG Electronics, Electrolux, SharkNinja, Hoover, Samsung, Bissell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Vacuum Cleaners Market Evolving Landscape
Power delivery architectures and autonomous navigation systems are converging to redefine residential cleaning from scheduled chore to ambient background service, compressing user interaction to monthly maintenance intervals.
Smart battery management systems with cell-level monitoring are decentralizing power optimization from centralized motor controllers to distributed pack electronics. Urban apartment dwellers with irregular cleaning schedules are adopting these formats fastest. The shift is decentralizing warranty and service relationships from retail intermediaries to direct manufacturer channels.
The EU Ecodesign Regulation's 2025 efficiency tiers are eliminating marginally compliant motor designs from European distribution. Manufacturers with vertically integrated motor production are absorbing compliance costs through design reuse across multiple SKU tiers. Canister formats with high-wattage demands face the steepest redesign requirements.
Direct-to-consumer channel migration is fragmenting traditional retail dependency for premium cordless launches. SharkNinja and Dyson are building proprietary fulfillment infrastructure that bypasses big-box slotting fees. North American suburban households show highest conversion rates for online-only configuration tools with augmented reality fit visualization.
Residential Vacuum Cleaners Market Segmentation
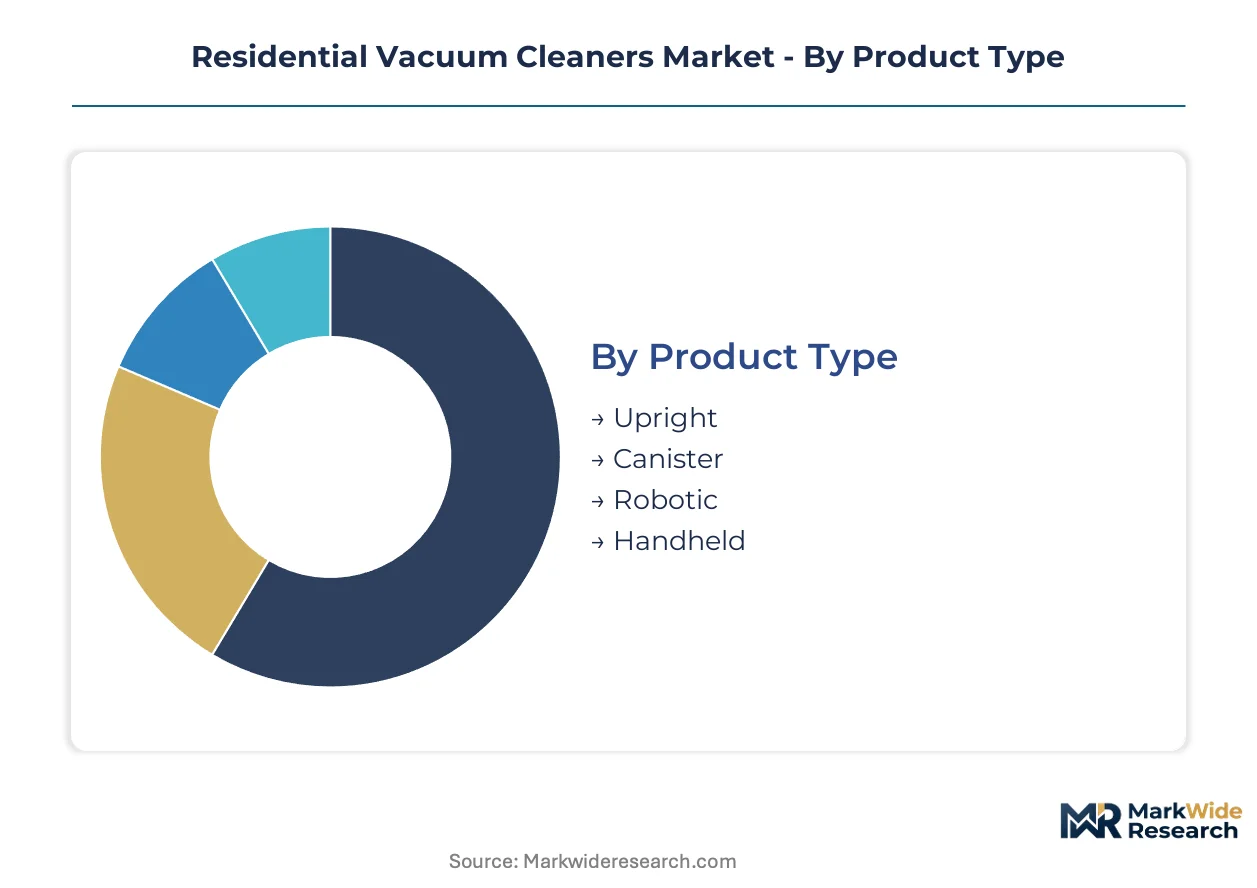
Vacuum cleaner segmentation determines regulatory compliance pathways and manufacturing line configurations. Product format and power architecture choices lock in certification requirements and margin structures for multi-year production cycles.
Product Type:
UL certification in North America and CE marking in Europe apply uniformly across formats, though robotic units trigger additional FCC and radio equipment directives for navigation sensors and Wi-Fi connectivity.
- Upright:Motor-and-brushroll housings mounted vertically above cleaning heads deliver 80-100 CFM airflow with 12-15 amp draw. North American suburban households with wall-to-wall carpeting concentrate replacement demand here, constrained by storage footprint requirements in smaller dwellings.
- Robotic:Autonomous disc or D-shaped chassis integrate simultaneous localization and mapping with 45-60 minute autonomous runtime. Chinese and Indian metro apartment dwellers adopt these units fastest as first-time floor-care purchases, driven by software subscription attach rates and minimal storage needs.
- Canister:Separate suction motor and dust collection units connected by flexible hoses; German engineering credentials anchor premium positioning through extended product lifecycles.
- Handheld:Compact lithium-ion powered units for spot cleaning and vehicle interiors; rapid product iteration cycles compress development timelines.
Upright configurations sit at the top of the volume ranking, with robotic formats climbing the fastest.
Power Source:
Cost tier stratification separates premium cordless from economy corded positioning, with battery chemistry choices determining three-year total cost of ownership calculations.
- Cordless:Lithium-ion battery packs with 18650 or 21700 cell formats now achieve 60-minute runtime parity with corded suction performance. Urban apartment dwellers in dense centers adopt these formats fastest, enabled by energy density improvements collapsing previous performance gaps.
- Corded:Universal 100-240V AC motors deliver sustained suction without runtime constraints; 15-year motor lifespans create lifecycle cost advantages over battery-dependent alternatives.
- Battery Operated:Removable pack architectures enable field replacement; modular designs align with pending EU right-to-repair mandates.
- Hybrid:Dual-mode architectures switch between battery and AC operation; complexity premiums limit volume penetration.
Corded units maintain volume leadership, though cordless formats are gaining share fastest in replacement cycles.
Feature:
Application context determines feature bundling, with pet-owning households and allergy-sensitive users driving premium tier differentiation.
- HEPA Filtration:99.97% particle capture at 0.3 microns has migrated from premium differentiator to baseline expectation across mid-tier and above. FDA indoor air quality guidance shapes marketing claims in the United States, while EU Ecodesign efficiency mandates constrain motor power available to drive filtration airflow.
- Smart Technology:Wi-Fi connectivity, app-based scheduling, and mapping storage layer recurring revenue models with 40-60% gross margins. Robotic manufacturers concentrate software subscription attach here.
- Bagless:Cyclonic separation chambers eliminate recurring bag purchases; dust emptying hygiene concerns limit adoption in allergy-sensitive segments.
- Quiet Mode:Motor controller firmware reduces RPM and suction for nighttime operation; acoustic engineering adds BOM cost without functional performance gains.
HEPA filtration sits at the top of the volume ranking, with smart technology climbing the fastest.
End User:
Customer type determines procurement channel and service relationship structure, fragmenting warranty and support models across direct-to-consumer and institutional contracting pathways.
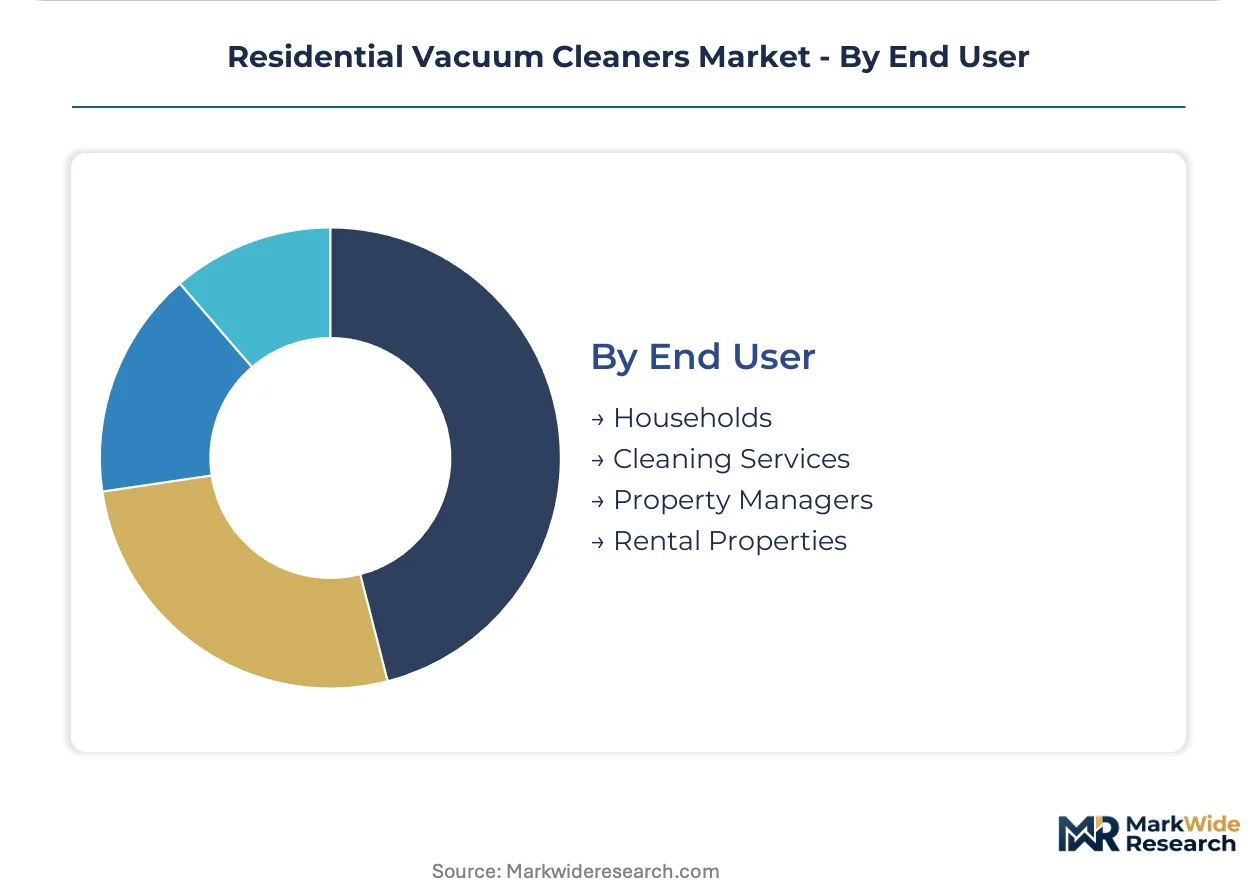
- Households:Individual consumers purchasing through retail or direct channels; augmented reality fit visualization tools convert highest in North American suburban markets.
- Cleaning Services:Commercial operators prioritize runtime durability and rapid battery swap capability; fleet procurement concentrates volume in cordless stick formats.
- Property Managers:Multi-unit residential operators standardize on single formats across portfolios; repairability and component availability drive selection criteria.
- Rental Properties:Landlord-provisioned units emphasize theft resistance and simplified operation; economy tier canister formats dominate.
Households sit at the top of the volume ranking, with cleaning services climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are relocating final assembly to jurisdictions with lighter efficiency certification burdens while maintaining component sourcing from established industrial clusters. The EU Ecodesign Regulation's 2025 motor mandates have widened the compliance-cost gap between European retail channels and export-oriented production bases. Contract manufacturers in coastal China now dominate cordless and robotic vacuum assembly for brand owners worldwide.
United States
Suburban households with wall-to-wall carpeting sustain replacement demand for upright formats. The FDA's indoor air quality guidance shapes HEPA filtration marketing claims without mandating specific capture thresholds. Greater Chicago and Dallas-Fort Worth concentrate distribution infrastructure for North American retail channels.
Germany
Engineering-intensive canister formats retain premium positioning through extended product lifecycle credentials. The EU Ecodesign Regulation's tiered efficiency thresholds are eliminating marginally compliant motor designs from domestic distribution. Stuttgart and Munich anchor high-end manufacturing clusters serving European and export markets.
China
Metro apartment formation in Shanghai and Shenzhen is outpacing floor-care penetration, creating first-time buyer pools for robotic entry-level units. GB standards and NMPA-adjacent quality certifications create compliance layering for brands accessing domestic retail channels. The Pearl River Delta concentrates contract manufacturing capacity for cordless and robotic assembly lines.
India
Household formation in Mumbai and Bangalore is outpacing floor-care penetration, creating first-time buyer pools for robotic entry-level units. BIS certification requirements and DGFT import regulations structure market access for foreign brands. The Delhi-NCR corridor concentrates e-commerce fulfillment infrastructure for direct-to-consumer distribution.
Japan
Compact dwelling footprints accelerate demand for stick and robotic formats with minimal storage requirements. METI energy efficiency labeling programs constrain motor power availability for premium-tier products. The Kanto region around Tokyo concentrates retail channel headquarters and aftermarket service networks.
Residential Vacuum Cleaners Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue software-enabled service models and direct-to-consumer channel control. The vendor base organizes around three strategic archetypes: vertically integrated motor manufacturers, brand marketers with outsourced assembly, and robotic specialists with recurring revenue platforms. Dominant competitive moves include backward integration into battery pack assembly and geographic expansion through e-commerce platform partnerships.
Among Germany-based engineering specialists, Miele GmbH anchors the high-end canister segment through extended product lifecycle positioning. Dyson Ltd. occupies the premium cordless tier through proprietary motor technology and direct-to-consumer channel control. SharkNinja Operating LLC exemplifies the rapid-iteration, price-accessible archetype competing aggressively in North American retail.
| Leading Market Players |
|---|
| iRobot |
| Miele |
| Dyson |
| LG Electronics |
| Electrolux |
| SharkNinja |
| Hoover |
| Samsung |
| Bissell |
| Others |
Value Network & Pricing Analysis
Captive motor production in Germany and China anchors pricing power for tier-one manufacturers while compressing margin capture for brand marketers dependent on outsourced assembly. The EU Ecodesign Regulation's efficiency mandates are forcing compliance-cost absorption through design reuse across multiple SKU tiers, concentrating margin pressure on canister formats with high-wattage demands.
Pricing Analysis
Retailer markup layers in North American big-box channels absorb 35-45 points of manufacturer landed cost, driving Dyson and SharkNinja toward proprietary direct-to-consumer fulfillment infrastructure. Three-tier pricing structure across premium, standard, and economy levels separates brushless motor architectures with software subscriptions from brushed-motor transactional units and entry-level corded alternatives. Cost compression in the economy tier is intensifying because Chinese contract manufacturers are restructuring capacity toward cordless and robotic lines, constraining legacy corded supply. Urban apartment dwellers show lowest price sensitivity for robotic formats with recurring software attach, while rental property landlords prioritize theft-resistant economy canisters.
Supply Chain Analysis
Workforce availability for FPGA programming and brushless motor controller firmware sits concentrated in Stuttgart automotive clusters and Shenzhen industrial automation hubs, creating recruitment bottlenecks for appliance engineering teams. Component sourcing draws from China for lithium-ion cell assembly, Japan for precision motor magnets, and Germany for high-efficiency controller silicon. Neodymium magnet processing capacity clustering in China exposes motor costs to export quota volatility. Distribution runs through direct-to-consumer channels for premium cordless launches and traditional retail intermediaries for economy tier volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through software subscription attach rates in robotic formats, where recurring revenue models with 40-60% gross margins offset hardware commoditization pressures in corded segments.
For Market Incumbents: Anchor defensive positioning through backward integration into battery pack assembly and modular architectures aligned with pending EU right-to-repair mandates. Incumbents must absorb compliance costs from the EU Ecodesign Regulation's tiered efficiency thresholds by reusing brushless motor designs across multiple SKU tiers. Channel control through proprietary fulfillment infrastructure defends margin position against retail slotting fee compression. For New Entrants and Emerging Players: Enter via robotic entry-level units targeting first-time buyer pools in Indian and Chinese metro apartment markets, where household formation outpaces floor-care penetration. White-space concentration sits in software-enabled service models with mapping storage and pet-recognition AI behind subscription paywalls. Direct-to-consumer platform partnerships enable bypass of established retail gatekeepers. For Investors and Strategic Acquirers: Roll-up economics work for robotic specialists with recurring revenue platforms because software subscription attach rates create predictable cash flow visibility absent in transactional hardware models. Acquisition targets should demonstrate firmware development capabilities and direct channel control. The signal to watch is lithium-ion battery energy density improvements enabling runtime parity with corded units, which would accelerate cordless replacement cycles and concentrate margin pools in battery-dependent formats.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Migration | Proprietary fulfillment infrastructure bypasses big-box slotting fees and captures first-party customer data for robotic subscription attach. |
| Modular Battery Architecture Development | Field-replaceable pack designs align with EU Green Deal repairability mandates and extend product lifecycle revenue. |
| Software Subscription Platform Launch | Mapping storage and pet-recognition AI behind recurring paywalls concentrate margin pools in robotic formats. |
| Brushless Motor Controller Firmware Investment | FPGA programming expertise recruited from automotive clusters enables compliance with EU Ecodesign efficiency tiers. |
| Geographic E-Commerce Partnership Expansion | Platform relationships in the Delhi-NCR corridor access Indian urban middle-class first-time buyer pools. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. The research team conducted interviews with product development executives at cordless and robotic manufacturers, procurement leads at Chinese contract assembly operations, regulatory affairs specialists navigating EU Ecodesign and REACH compliance, and category buyers at North American retail chains. Secondary sources include customs and trade data for component flow analysis, SEC filings for public company segment reporting, EU regulatory databases for efficiency standard evolution, and e-commerce platform transaction data for channel shift quantification. Bottom-up unit economics and top-down market sizing were triangulated against contract manufacturer capacity disclosures.
Rate-of-change decomposition separated volume growth from value growth across the analysis window, with CAGRs derived from regression against lithium-ion energy density improvement curves and urban household formation rates. Segmentation dimensions modeled include product format, power architecture, feature bundle, and end-user type, with additional granularity on software subscription penetration in robotic units. Forecast inputs incorporated EU Ecodesign compliance phase-in schedules and BIS certification timelines for Indian market access.
The model holds under continued lithium-ion energy density improvement and stable rare-earth magnet export quotas; deviation in neodymium supply disruption or REACH substance restriction expansion would shift cordless format economics. Forecasts reflect assumptions on urbanization rates and regulatory enforcement intensity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Electric Fan Market
Appliances
Domestic Food Preparation Appliances Market
Appliances
Smart Washing Machine Market
Appliances
Commercial Microwave Ovens Market
Appliances
Electric Yogurt Maker Market
Appliances
Saudi Arabia Electric Water Heater Market
Appliances
Asia Pacific Compact Dishwasher Market
Appliances
Toaster Ovens Market
Appliances
Europe Tumble Dryers Market
Appliances
North America Washing Machine Market
Appliances
United States Commercial Laundry Appliances Market
Appliances
Global Home Ice Maker Market
Appliances
Mexico Washing Machine Market
Appliances
French Door Refrigerator Market
Appliances
Gas Ranges Market
Appliances
Electric Hand Dryer Market