
 Industrial Floor Mats Market | 2026-2036
Industrial Floor Mats Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Floor Mats Market Outlook
Recycled rubber is expanding its share in industrial floor mat construction as virgin petroleum-based compounds face cost volatility. 3M Company leverages its polymer science portfolio to develop high-traction surfaces for chemical-exposed environments. Bergo Flooring AB anchors its position through modular interlocking systems that reduce installation labor. Wearwell LLC differentiates via specialized anti-fatigue compounds targeting standing-worker ergonomics.
Industrial floor mats are engineered surface coverings, typically 0.5 to 1.5 inches thick, manufactured from rubber, vinyl, nylon, or foam substrates to provide slip resistance, fatigue reduction, and contamination control in commercial and industrial environments. Their primary purpose is protecting personnel from musculoskeletal strain and preventing workplace accidents caused by wet or uneven flooring. Anti-fatigue mats command the strongest margin pool due to specialized ergonomic certification requirements and replacement cycles tied to worker compensation claims. Safety mats represent the fastest-growing application segment as manufacturing facilities automate material handling and require sensor-integrated floor surfaces. Custom mats remain a mature, fragmented category where local fabricators compete on turnaround speed rather than material innovation.
OSHA workplace safety standards and the EPA's volatile organic compound regulations directly shape mat composition requirements and manufacturing location decisions in the United States. REACH chemical restrictions in Europe limit certain plasticizers and flame retardants, pushing manufacturers toward bio-based polyurethane formulations. Stakeholders must monitor evolving ergonomic certification protocols and regional chemical compliance thresholds to align product development with procurement specifications across divergent regulatory environments.
Market Dynamics
OSHA slip-resistance mandates and EPA volatile organic compound restrictions are compressing formulation flexibility while simultaneously elevating compliance costs across domestic manufacturing. This regulatory tightening is concentrating procurement authority among large facility operators capable of absorbing certification overhead.
Growth Catalysts
- Food Safety Modernization Act enforcement:USDA-inspected facilities now require drainage-integrated matting systems, expanding specification depth for hygienic flooring in meat and poultry processing plants.
- Automotive manufacturing automation:Sensor-integrated safety mats are accelerating replacement cycles as German OEMs retool assembly lines for collaborative robotics deployment.
- Ergonomic litigation trends:Rising worker compensation claims in warehousing and distribution are forcing employers toward anti-fatigue matting with documented biomechanical certification.
Market Restraints
- Petrochemical input volatility:Natural rubber and synthetic polymer prices fluctuate with crude oil indices, compressing margin stability for compound-dependent manufacturers.
- REACH chemical restrictions:ECHA limitations on phthalate plasticizers and halogenated flame retardants force costly reformulation of legacy vinyl formulations for European export.
- Recycled crumb rubber contamination:Inconsistent quality in post-consumer tire feedstock creates performance variability that deters specification in pharmaceutical cleanrooms.
Strategic Opportunities
- India manufacturing expansion:BIS certification requirements and PLI scheme incentives for domestic production are opening specification windows for localized supply chains serving automotive and pharmaceutical clusters.
- Smart facility integration:Convergence of pressure-sensing polymers with industrial IoT platforms enables predictive maintenance contracts and usage-based replacement scheduling.
- Bio-based polyurethane formulations:EU Green Deal procurement preferences and CSRD reporting requirements are creating first-mover advantage for suppliers with verified renewable content.
Industry Challenges
- Polymer compounding expertise scarcity:Formulation chemists capable of balancing slip resistance, fatigue reduction, and chemical compliance command premium compensation and extended recruitment timelines.
- Multi-jurisdiction certification stacking:Simultaneous OSHA, EPA, and state-level ergonomic mandates create testing bottlenecks that delay product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Floor Mats Market |
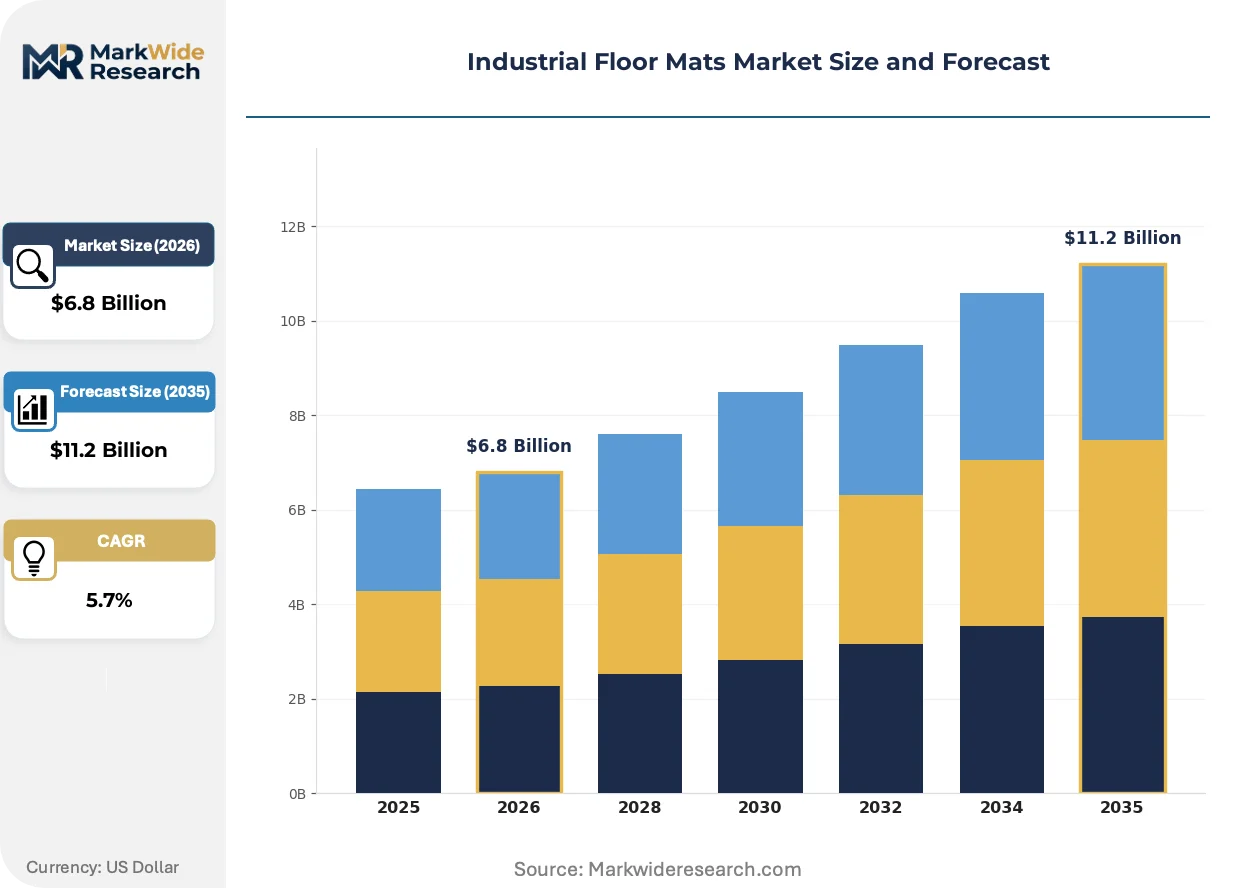
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
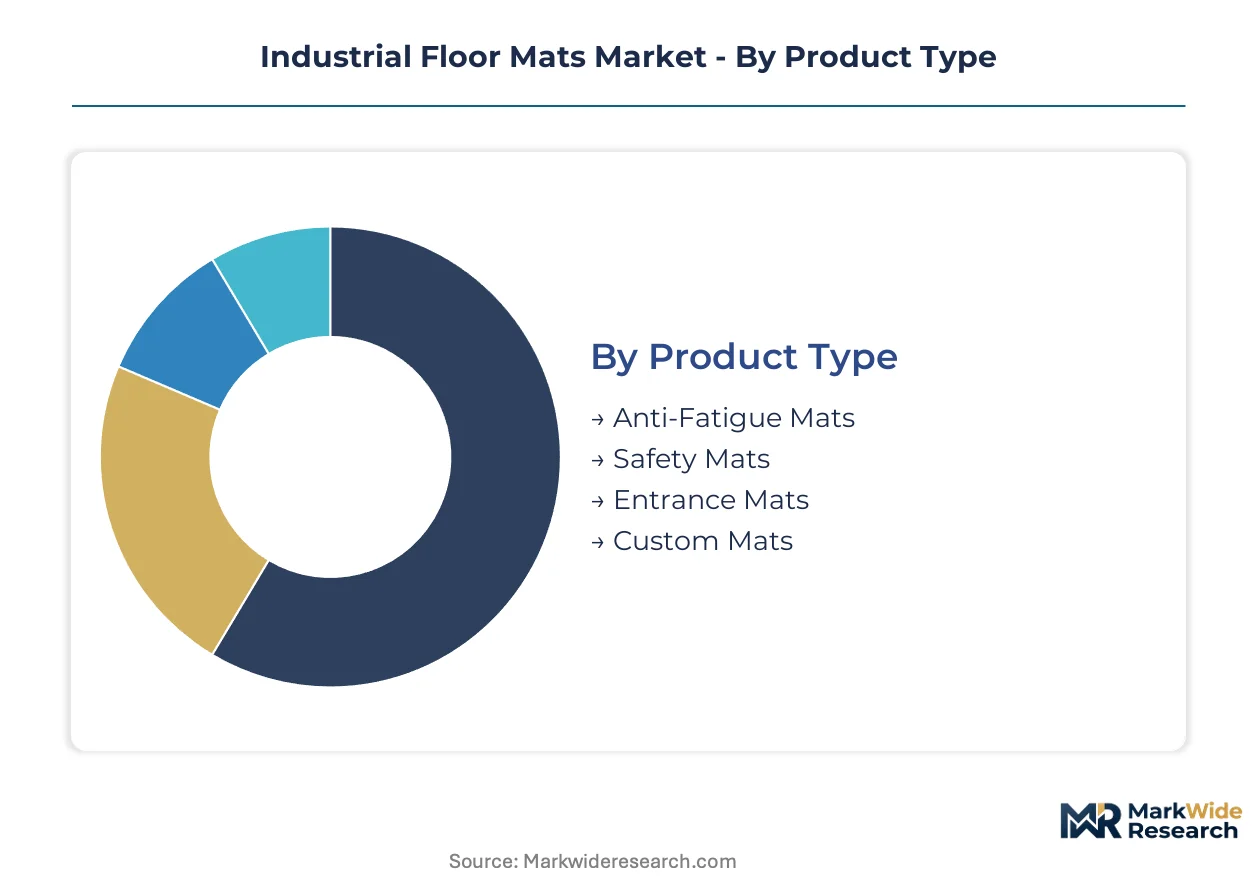
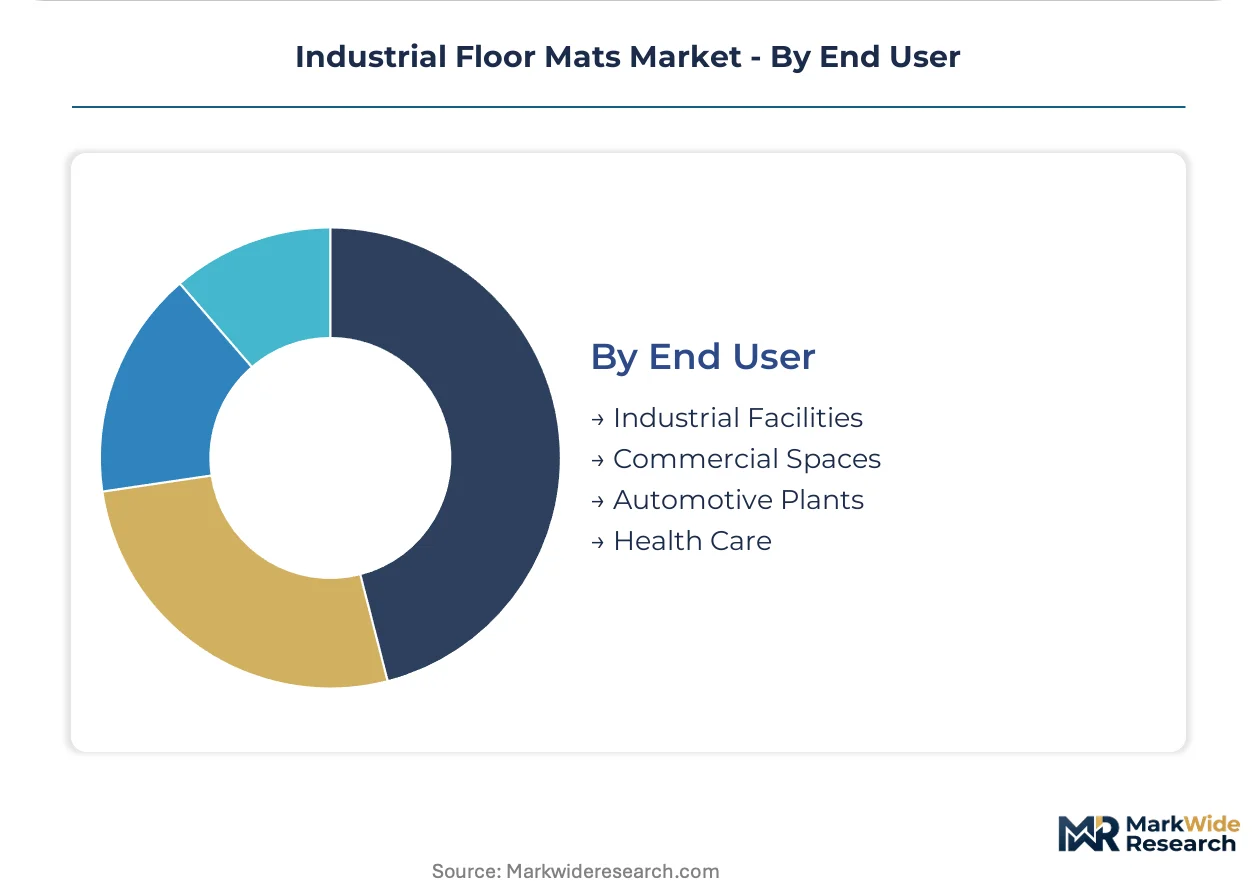
| Segmentation | Product Type: Anti-Fatigue Mats, Safety Mats, Entrance Mats, Custom Mats Application: Manufacturing, Warehousing, Retail, Food Processing Material: Rubber, Vinyl, Nylon, Foam End User: Industrial Facilities, Commercial Spaces, Automotive Plants, Health Care |
| Companies Covered | Wearwell LLC, UniFirst Corporation, 3M Company, Apache Mills, Eagle Mat and Floor Products, Cintas Corporation, Notrax, Bergo Flooring AB, M+A Matting, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Floor Mats Market Strategic Shifts
Material science advances and connected infrastructure requirements are restructuring how industrial flooring is specified, procured, and maintained across manufacturing verticals.
Recycled rubber composite formulations are consolidating specification share in heavy-traffic environments. Automotive stamping plants and metal fabrication facilities are adopting these compounds at accelerated rates to meet sustainability procurement scorecards. The technology is consolidating supplier tiers by rewarding compounders with captive tire shredding and controlled contamination protocols.
EPA volatile organic compound emissions standards for consumer and commercial products are reshaping adhesive and coating selections in mat manufacturing. Industrial consequences include accelerated phase-out of solvent-based bonding systems and migration toward hot-melt and reactive polyurethane alternatives. Chemical processing and electronics assembly facilities in Texas and California are most affected, driving demand for low-emission installation methods.
Integrated service contracts bundling matting supply with scheduled maintenance and replacement are displacing transactional purchase models. Third-party facility management providers and multi-site logistics operators are consolidating vendor relationships to reduce administrative burden. This pattern is most visible in North American distribution center networks where uniform flooring standards support brand consistency and safety audit uniformity.
Industrial Floor Mats Market Segmentation
Industrial floor mat procurement varies sharply by operational environment, with replacement cycles and specification depth diverging across facility types. Understanding these segment boundaries clarifies where margin pools concentrate and which technical requirements command premium positioning.
Product Type:
Upgrade cycles accelerate where ergonomic litigation or automation integration reshapes facility requirements.
- Anti-Fatigue Mats:These 0.5-1.5 inch thick elastomeric surfaces reduce musculoskeletal strain through controlled compression and rebound. Demand concentrates in warehousing and distribution centers across the United States, where rising worker compensation claims force employers toward biomechanically certified products with documented replacement protocols.
- Safety Mats:Sensor-integrated or high-traction surfaces designed for hazard detection and slip prevention in automated environments. German automotive OEMs are driving specification expansion as collaborative robotics deployment requires pressure-sensitive flooring that interfaces with material handling systems.
- Entrance Mats:Scraping and drying surfaces positioned at facility thresholds to control moisture and particulate migration. Commercial real estate operators in high-traffic urban centers specify these for liability reduction.
- Custom Mats:Fabricated-to-order surfaces addressing irregular dimensions or specialized chemical exposure. Local fabricators compete on turnaround speed rather than material innovation in this fragmented tier.
Volume placements concentrate in Anti-Fatigue Mats; the faster expansion belongs to Safety Mats.
Application:
Cost tiers separate specification depth, with regulated environments absorbing premium pricing for certified compliance.
- Manufacturing:Heavy-duty rubber and vinyl compounds endure chemical exposure, welding sparks, and continuous forklift traffic. Automotive stamping plants in Germany's manufacturing corridor specify recycled rubber composites to meet sustainability procurement scorecards.
- Warehousing:Anti-fatigue and drainage-integrated matting dominates this high-labor-intensity environment. OSHA ergonomic mandates in the United States are compressing procurement authority toward large operators capable of absorbing certification overhead.
- Retail:Entrance and decorative matting with brand customization and moderate durability requirements. National chains prioritize uniform flooring standards across multi-site networks.
- Food Processing:USDA-inspected facilities mandate drainage-integrated, antimicrobial matting systems with documented cleanability. Meat and poultry plants absorb premium pricing for hygienic flooring that satisfies Food Safety Modernization Act enforcement.
Revenue concentration sits with Manufacturing; the steepest expansion trajectory appears in Food Processing.
Material:
Supply concentration among compounders with captive feedstock or polymer science capabilities shapes competitive access.
- Rubber:Natural and synthetic elastomers deliver superior abrasion resistance and chemical tolerance. Petrochemical input volatility compresses margin stability for manufacturers dependent on crude oil-indexed synthetic compounds.
- Vinyl:Polyvinyl chloride formulations offer cost efficiency and design flexibility. REACH chemical restrictions on phthalate plasticizers force costly reformulation for European export compliance.
- Nylon:High-tenacity synthetic fibers provide moisture-wicking and rapid drying in entrance applications. Carpet-style construction suits commercial environments with moderate mechanical stress.
- Foam:Polyurethane and EVA substrates deliver lightweight anti-fatigue performance at lower price points. Inconsistent density control limits specification in pharmaceutical cleanrooms.
Procurement volume clusters around Rubber; bio-based polyurethane alternatives are gaining share fastest.
End User:
Customer type determines whether procurement flows through facility management contracts or direct capital expenditure.
- Industrial Facilities:Multi-site manufacturing and heavy industry operators with standardized safety protocols. Integrated service contracts bundling supply with scheduled maintenance are displacing transactional purchase models.
- Commercial Spaces:Office buildings, hospitality, and retail with aesthetic and moderate durability requirements. Third-party facility management providers consolidate vendor relationships to reduce administrative burden.
- Automotive Plants:OEM and tier supplier facilities with robotics integration and sustainability mandates. German producers drive sensor-integrated safety mat specification as assembly lines retool for collaborative automation.
- Health Care:Hospitals and clinics requiring antimicrobial, fluid-resistant, and slip-prevention surfaces. Ergonomic certification for standing surgical and nursing staff creates specialized demand.
Contract value concentrates in Industrial Facilities; Automotive Plants show the quickest specification evolution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration sits with automotive OEMs in Germany, food processing clusters in the United States, and emerging manufacturing hubs in India. Regulatory divergence across OSHA, REACH, and BIS frameworks fragments procurement specifications. Facility operators prioritize localized supply chains to compress lead times and satisfy domestic content requirements.
United States
Warehousing and distribution networks drive anti-fatigue mat procurement as worker compensation litigation escalates. OSHA ergonomic mandates and EPA volatile organic compound restrictions compress formulation flexibility for domestic manufacturers. The Midwest automotive corridor and Texas chemical processing belt absorb premium pricing for certified compliance matting.
Germany
Automotive OEMs retooling for collaborative robotics accelerate sensor-integrated safety mat specification. REACH chemical restrictions on phthalate plasticizers force reformulation of legacy vinyl exports. The Baden-Württemberg and Bavaria manufacturing clusters concentrate demand for recycled rubber composites meeting sustainability procurement scorecards.
China
Electronics assembly and heavy machinery sectors expand drainage-integrated and chemical-resistant matting deployment. MIIT industrial safety standards and provincial environmental regulations tighten manufacturing location decisions. The Yangtze River Delta and Pearl River Delta absorb volume placements as facility automation intensifies.
India
Pharmaceutical and automotive clusters drive specification for hygienic flooring with antimicrobial certification. BIS quality mandates and PLI scheme incentives for domestic production open procurement windows for localized compounders. Maharashtra and Gujarat manufacturing belts concentrate demand as export-oriented facilities expand capacity.
Japan
Precision manufacturing and semiconductor cleanrooms require contamination-controlled matting with documented performance protocols. METI industrial standards and JIS certification requirements elevate specification depth. The Kanto and Kansai industrial corridors prioritize ergonomic solutions for standing-worker environments in electronics assembly.
Industrial Floor Mats Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with premium-tier suppliers capturing margin through certification depth while volume fabricators compete on turnaround speed. The vendor base organizes into three tiers: polymer science specialists with captive compounding, modular system providers with installation labor advantages, and regional fabricators serving custom dimensions. Consolidation pressure concentrates among mid-scale compounders seeking backward integration into recycled rubber feedstock. Geographic expansion and technology licensing represent the dominant competitive vectors as suppliers chase multi-jurisdiction certification stacking.
Within the polymer science tier, 3M Company and Bergo Flooring AB exemplify divergent specialization strategies. 3M leverages material science capabilities across industrial adhesive and surface technology portfolios. Bergo Flooring AB anchors modular interlocking system architecture that reduces field installation labor. Wearwell LLC occupies a position in the ergonomic certification segment, representing the anti-fatigue specialist archetype where biomechanical documentation commands premium positioning. These three players illustrate how technical differentiation vectors—compound innovation, system modularity, and ergonomic validation—structure competitive access across procurement segments.
| Leading Market Players |
|---|
| Wearwell LLC |
| UniFirst Corporation |
| 3M Company |
| Apache Mills |
| Eagle Mat and Floor Products |
| Cintas Corporation |
| Notrax |
| Bergo Flooring AB |
| M+A Matting |
| Others |
Value Chain & Pricing Dynamics
Crude oil-indexed synthetic rubber prices cascade through compounder margins into three distinct procurement tiers, with petrochemical volatility compressing standard-grade economics while certified anti-fatigue and sensor-integrated safety mats retain pricing power through ergonomic litigation risk and automation integration requirements.
Pricing Analysis
Volume placements cluster in economy-grade rubber entrance mats where Asian compounders compete on feedstock arbitrage; premium-mid-economy pricing differentiation separates biomechanically certified anti-fatigue products with OSHA documentation from commodity drainage matting. Cost compression in standard vinyl formulations is intensifying because REACH-forced reformulation elevates compounder R&D overhead. Warehousing procurement teams show highest price sensitivity as facility management contracts consolidate vendor relationships, while German automotive OEMs absorb premium sensor-integrated safety mat pricing without material pushback.
Supply Chain Analysis
Dual-sourcing mandates from multi-site facility operators require qualification of at least two compounders per mat category, with supply anchored in Thailand and Malaysia for natural rubber feedstock, China for synthetic polymer compounding, and the United States for finished anti-fatigue assembly serving domestic warehousing networks. Raw material flows draw from petrochemical crackers, post-consumer tire crumb processors, and bio-based polyurethane precursor plants. Tariff exposure on Chinese vinyl compounds creates qualification bottlenecks for European export. Distribution runs through integrated service contractors bundling supply with scheduled maintenance rather than transactional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around compounders with captive recycled rubber feedstock and multi-jurisdiction certification capabilities, with REACH chemical restrictions and OSHA ergonomic mandates forcing sub-scale fabricators toward exit or acquisition.
For Market Incumbents: Anticipate margin compression in commodity entrance matting as Southeast Asian compounders expand capacity; defend position through backward integration into controlled-contamination tire shredding operations and accelerated bio-based polyurethane certification for EU Green Deal procurement windows. Prioritize polymer science hiring to address formulation chemist scarcity that delays product launches. For New Entrants and Emerging Players: Begin with localized supply chain construction in India's Maharashtra pharmaceutical belt, where BIS certification requirements and PLI scheme incentives create specification windows for domestic compounders lacking established vendor relationships. Target food processing drainage-integrated matting as the most penetrable segment given USDA enforcement expansion and incumbent capacity constraints. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale compounders with OSHA ergonomic certification and established automotive OEM relationships in Germany's Baden-Württemberg corridor, where sensor-integrated safety mat demand accelerates fastest. Long-term viability hinges on bio-based formulation pipelines and captive recycled feedstock. Watch for inflection when ECHA expands phthalate restriction lists beyond current REACH annexes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Rubber Feedstock | Captive tire shredding with contamination protocols secures sustainability scorecard compliance for German automotive procurement. |
| Bio-Based Polyurethane Certification Investment | EU Green Deal procurement preferences and CSRD reporting requirements reward first-movers with verified renewable content. |
| Sensor-Integrated Safety Mat Platform Development | Pressure-sensing polymer convergence with industrial IoT enables predictive maintenance contracts and usage-based replacement scheduling. |
| Multi-Jurisdiction Certification Stacking | Simultaneous OSHA, EPA, and state ergonomic qualification compresses launch timelines and concentrates procurement authority among large facility operators. |
| Integrated Service Contract Expansion | Bundling matting supply with scheduled maintenance displaces transactional purchase models in North American distribution center networks. |
Study Parameters
Independent corroboration across facility maintenance directors, OEM procurement leads at German automotive plants, compounder R&D directors, and third-party facility management providers underwrites the qualitative findings. Primary interviews explored specification depth, replacement cycle timing, and certification burden absorption. Secondary validation drew from OSHA enforcement databases, ECHA REACH restriction updates, USDA facility inspection records, and customs trade data for rubber and vinyl compound flows. Bottom-up segment sizing triangulated against top-down facility count estimates across manufacturing verticals.
Comparable-period anchoring to pre-pandemic baseline volumes established trajectory calibration across the projection horizon. The analytical framework modeled demand by product type, application environment, material substrate, and end-user procurement channel, with additional dimensioning for regulatory jurisdiction clustering. CAGRs derived from segment-level replacement cycle analysis, automation penetration curves, and ergonomic litigation trend extrapolation. Forecast inputs incorporated petrochemical price elasticity, BIS certification timeline assumptions, and collaborative robotics deployment schedules at German OEM facilities.
Underlying measurement precision varies by segment; anti-fatigue mat demand in United States warehousing carries tighter precision than custom fabrication turnover given standardized OSHA reporting. Forecasts reflect assumptions about REACH enforcement intensity, PLI scheme disbursement pacing, and crude oil price band stability. Deviation in ECHA chemical restriction expansion timing or German automotive automation retooling pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Air Purifier Market
Household Items
United States Barbeque Grill Market
Household Items
Alarm Clocks Market
Household Items
Snow Blower Market
Household Items
Electric Clothes Drying Hanger Market
Household Items
High-Efficiency Laundry Liquid Detergent Market
Household Items
Insulated Drinkware Market
Household Items
Knife Market
Household Items
Domestic Sauna Heaters Market
Household Items
Disposable Napkins Market
Household Items
Towel Warmers Market
Household Items
Steam Cleaners Market
Household Items
Leaf Blower Market
Household Items
Candle Air Fresheners Market
Household Items
Hands-Free Faucet Market
Household Items
Dryer Sheets Market