
 Cookware Market | 2026-2036
Cookware Market Size, Share, and Industry Trends Forecast 2026-2036
Cookware Market Intelligence
The integration of multi-ply bonding technology in cookware manufacturing is reshaping product performance and heat distribution standards. This process involves layering metals like stainless steel and aluminum to optimize heating. Groupe SEB SA leverages its All-Clad brand to lead in this premium segment with patented constructions. Lodge Manufacturing sustains its position through specialization in seasoned cast iron, while Le Creuset Group differentiates with its iconic enameled cast iron designs.
Cookware comprises vessels such as pots and pans designed for food preparation on various heat sources like stovetops and ovens. Products are engineered from materials like stainless steel or cast iron, often featuring specific ceramic or PTFE coatings for non-stick functionality. The stainless steel and aluminum material segments command the largest market share due to their versatility. Residential cooking remains the primary application, with commercial kitchens requiring products with enhanced durability and specific heat retention properties.
Product safety is governed by regulations concerning food-contact materials, such as those from the US FDA and the European Union's REACH framework. These rules restrict substances like PFOA, lead, and cadmium in coatings and base materials, influencing manufacturing processes globally. Stakeholders must monitor evolving material science innovations and consumer preferences for sustainable and health-conscious products to maintain market relevance.
Market Dynamics
The central force is the collision between consumer demand for healthier, non-toxic materials and the complex regulatory landscape for food-contact substances. This dynamic shapes material R&D and global supply chain compliance.
Growth Catalysts
- Urbanization in Emerging Economies:Rising disposable incomes in urban centers across India and China fuel investment in modern kitchens and higher-quality cookware.
- Health-Conscious Consumerism:Demand for PFOA-free coatings and inert materials like ceramic grows as consumers prioritize health and food safety in their product choices.
- Home Cooking Renaissance:A sustained increase in at-home culinary activities, driven by social media trends, expands the market for specialized and premium cookware.
Market Restraints
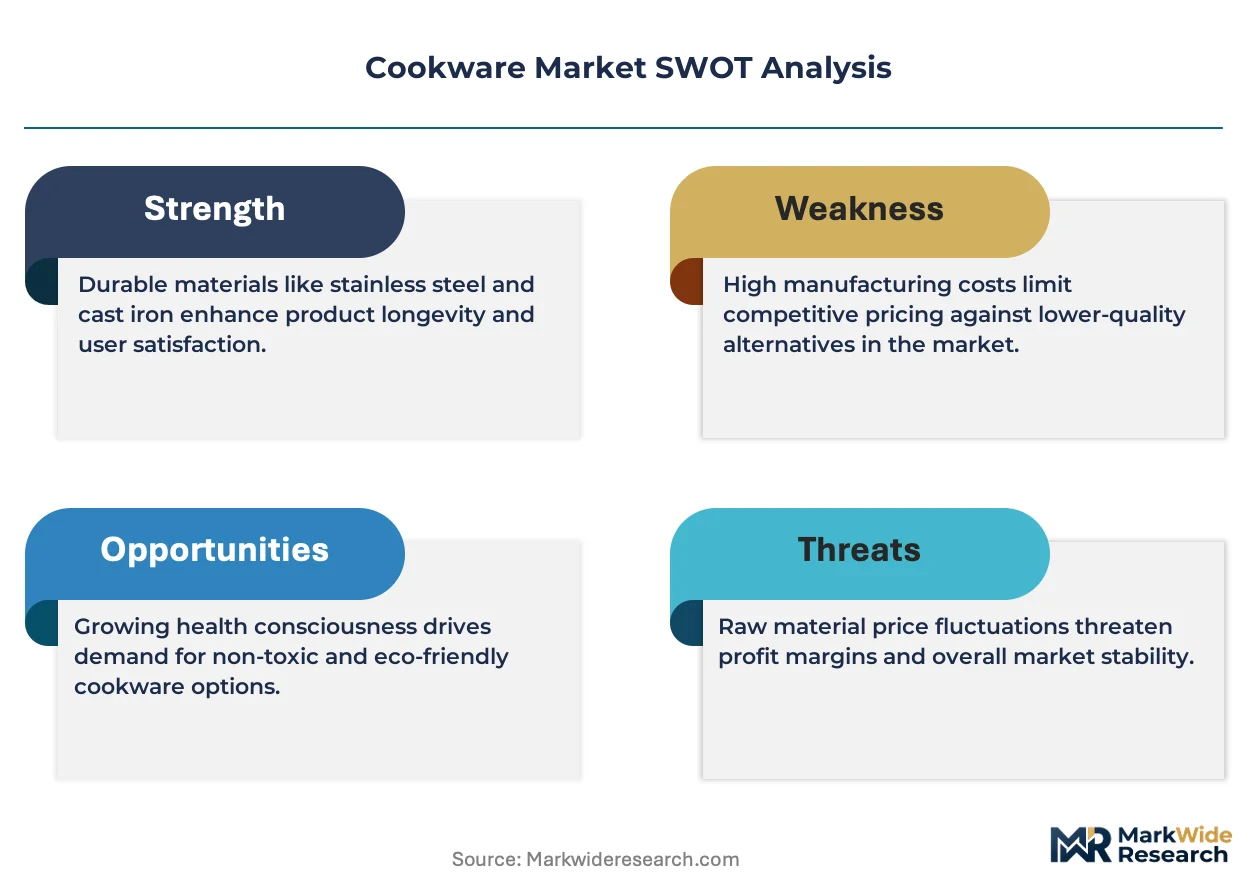
- Raw Material Price Volatility:Fluctuations in global prices of stainless steel and aluminum create pricing instability and compress manufacturer profit margins.
- Stringent Regulatory Hurdles:Compliance with evolving food-contact regulations, like the EU's REACH framework, imposes significant testing costs and delays product launches.
- Competition from Kitchen Appliances:Multi-functional appliances like air fryers and electric cookers present a substitution threat, reducing the need for certain traditional pans.
Strategic Opportunities
- Induction-Compatible Cookware:The global shift to energy-efficient induction cooktops creates a market for cookware with magnetic bases for optimal performance.
- Direct-to-Consumer Channels:E-commerce platforms enable D2C sales, allowing brands to control the customer experience and capture higher margins.
- Modular and Space-Saving Designs:Innovative, modular cookware with detachable handles targets consumers in smaller urban dwellings with limited kitchen space.
Industry Challenges
- Supply Chain Disruptions:Managing global supply chains is challenged by geopolitical instability and trade policy shifts affecting material sourcing and delivery.
- Counterfeit Goods Proliferation:Counterfeit products, especially online, erode brand value and pose safety risks, requiring constant investment in brand protection.
- Protecting Design and Technology IP:Defending patented technologies, like unique multi-ply bonding methods, from infringement across different legal jurisdictions is a continuous challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cookware Market |
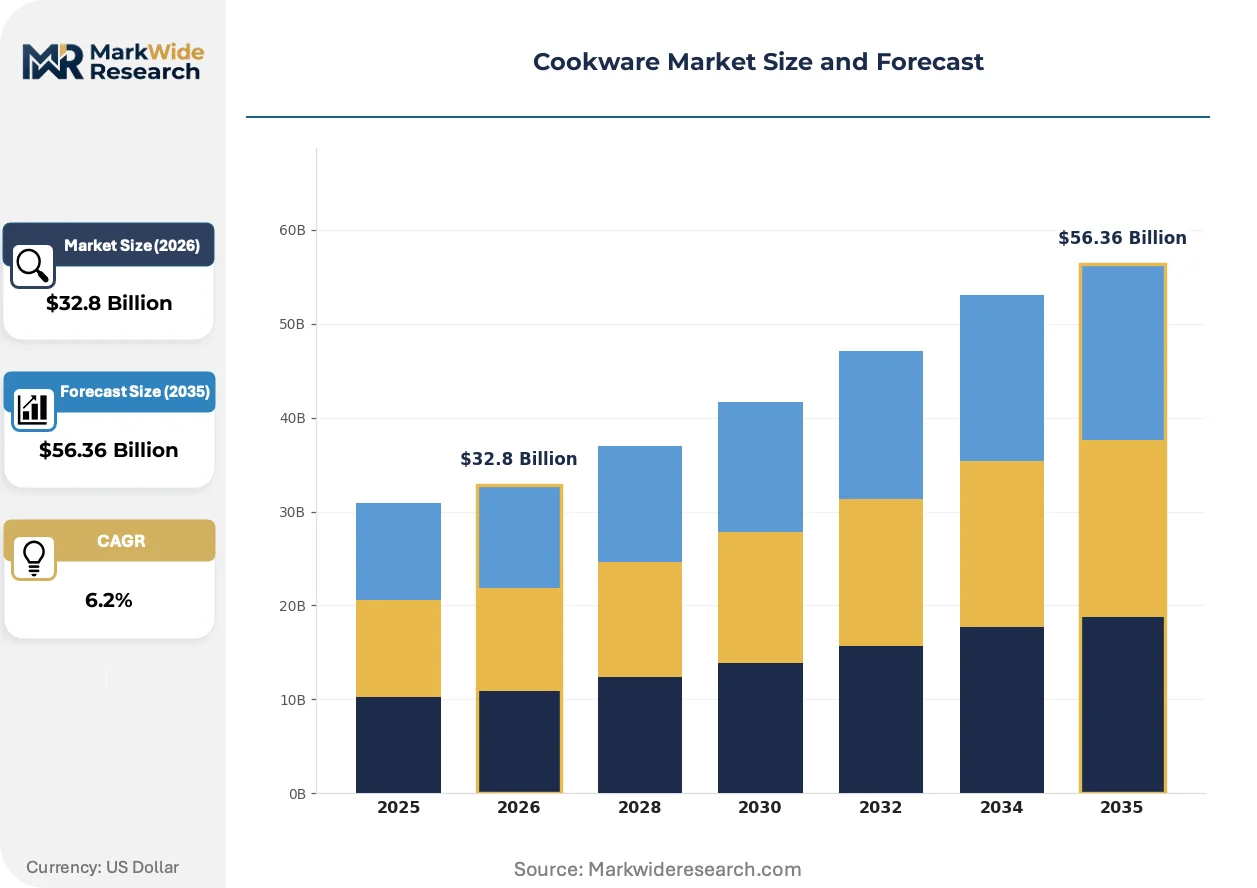
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $56.36 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frying Pans, Saucepans, Stockpots, Dutch Ovens, Griddles Material: Stainless Steel, Cast Iron, Aluminum, Copper, Ceramic Application: Residential Cooking, Commercial Kitchens, Catering Services, Culinary Schools, Outdoor Cooking Distribution Channel: Online Retailers, Specialty Stores, Supermarkets, Department Stores, Direct Sales |
| Companies Covered | Tramontina SA, Le Creuset Group, Groupe SEB SA, Lodge Manufacturing, Zwilling J.A. Henckels, Meyer Corporation, TTK Prestige Ltd, All-Clad, Newell Brands, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cookware Market Strategic Shifts & Innovations
Material science advancements are converging with sustainability mandates to redefine product value. This shift steers innovation toward measurable improvements in health, safety, and environmental impact across the product lifecycle.
Smart cookware incorporates embedded sensors and Bluetooth connectivity to monitor cooking processes. Tech-forward home cooks are the primary adopters, especially in the premium market segment. This technology is hybridizing the physical pot with digital guided cooking platforms, creating an interactive kitchen ecosystem.
The European Union’s push toward a circular economy emphasizes product longevity and material traceability. This forces manufacturers to document recycled material sources and design for easier disassembly. The metal cookware segment is directly impacted, as it must provide greater transparency on lifecycle impacts.
Consumer purchasing is shifting from large cookware sets to curating a collection of individual, high-performance pieces. This trend disrupts the traditional retail model built on bundled promotions and benefits specialist D2C brands. The pattern is most visible among urban consumers in North America and Europe.
Cookware Market Segmentation
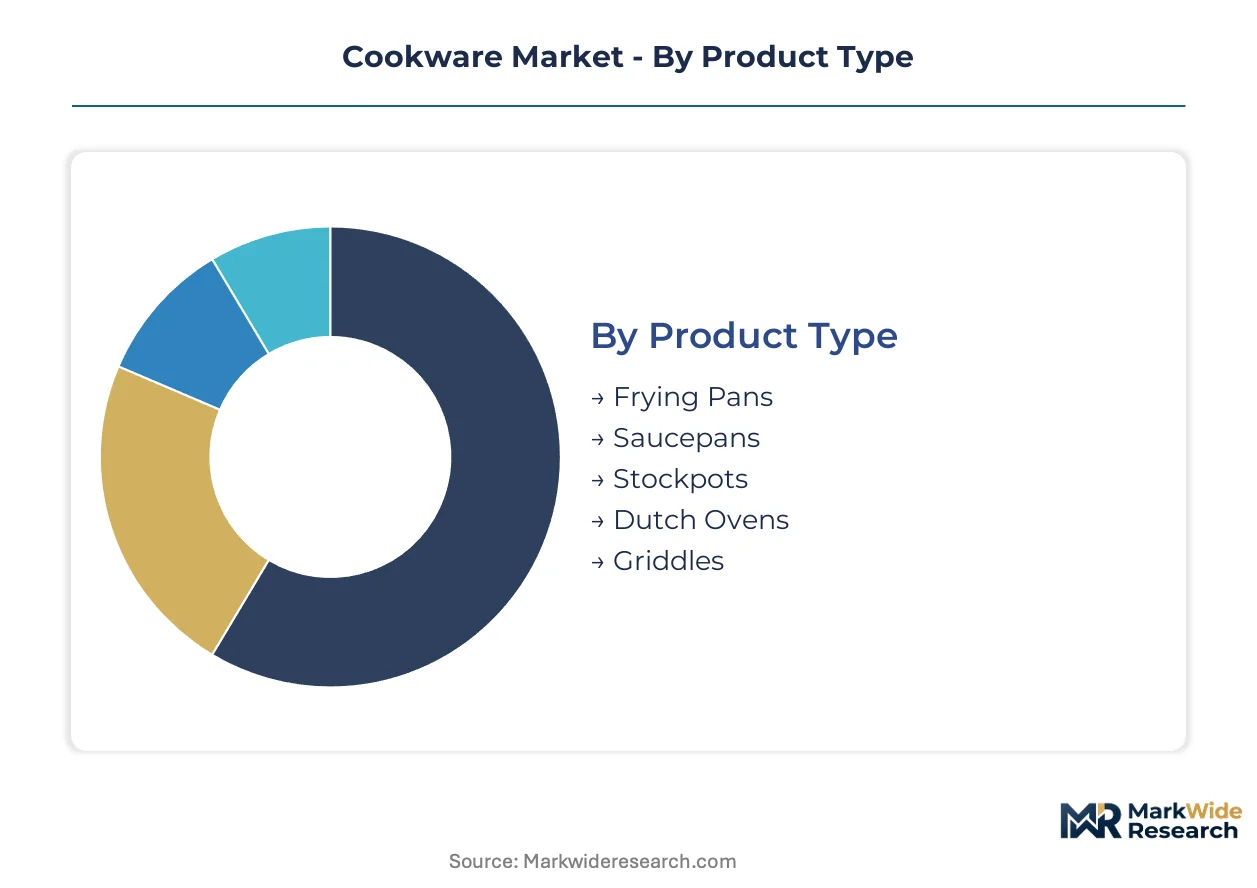
The cookware market segmentation provides a comprehensive view of diverse product offerings and consumer needs. It highlights the distinct demands across various product types, materials, applications, and distribution channels. This granular analysis assists manufacturers in developing targeted product lines and optimizing market penetration strategies.
Product Type:
The spectrum of product types defines specific culinary functions and user preferences within the cookware market.
- Frying Pans:These flat-bottomed, shallow vessels are essential for searing, sautéing, and browning. Demand for non-stick frying pans is high in urban centers of China, driven by the popularity of quick, stir-fried meals.
- Saucepans:These versatile, deep pots with a single handle are ideal for liquid-based cooking and reheating.
- Stockpots:Large, deep pots with high sides are designed for boiling, simmering stocks, and preparing large batches of food. Commercial kitchens in India increasingly require durable stockpots for high-volume meal preparation.
- Dutch Ovens:Heavy, thick-walled cooking pots, often made of cast iron, are valued for slow cooking and braising.
- Griddles:Flat, often rectangular cooking surfaces are used for pancakes, sandwiches, and other flat foods.
Frying Pans hold significant installed capacity. Dutch Ovens are rotating up the share rankings.
Material:
Material composition directly impacts heat conductivity, durability, and health considerations for consumers.
- Stainless Steel:An alloy of iron, chromium, and nickel, offering corrosion resistance and durability, often with an aluminum core for heat distribution. Residential consumers in Germany favor stainless steel for its longevity and aesthetic appeal.
- Cast Iron:A heavy, durable material known for superior heat retention and even cooking, requiring seasoning for non-stick properties. Outdoor cooking enthusiasts in the United States prefer cast iron for its robustness and versatility over open flames.
- Aluminum:Lightweight and an excellent heat conductor, aluminum cookware often features non-stick coatings.
- Copper:Highly conductive and responsive to temperature changes, copper cookware is prized by professional chefs.
- Ceramic:These inert, non-toxic coatings provide a naturally non-stick surface over metal substrates.
Stainless Steel maintains a dominant position. Ceramic is experiencing the steepest expansion trajectory.
Application:
Customer type segmentation reveals distinct demands for performance, durability, and aesthetic design.
- Residential Cooking:Involves cookware for daily home meal preparation, emphasizing ease of use, non-stick properties, and aesthetic appeal. The sustained increase in home culinary activities in Canada drives demand for diverse residential cookware.
- Commercial Kitchens:Requires robust, heavy-duty cookware designed for high-volume, continuous use and adherence to strict hygiene standards. Restaurants in France prioritize durable, professional-grade cookware for consistent culinary output.
- Catering Services:These operations demand portable, stackable, and high-capacity cookware for off-site food preparation.
- Culinary Schools:Educational institutions require a range of standard and specialized cookware for student training.
- Outdoor Cooking:This segment includes durable, often portable cookware suitable for camping, grilling, and open-fire use.
Residential Cooking represents the largest volume segment. Outdoor Cooking is gaining share fastest among niche applications.
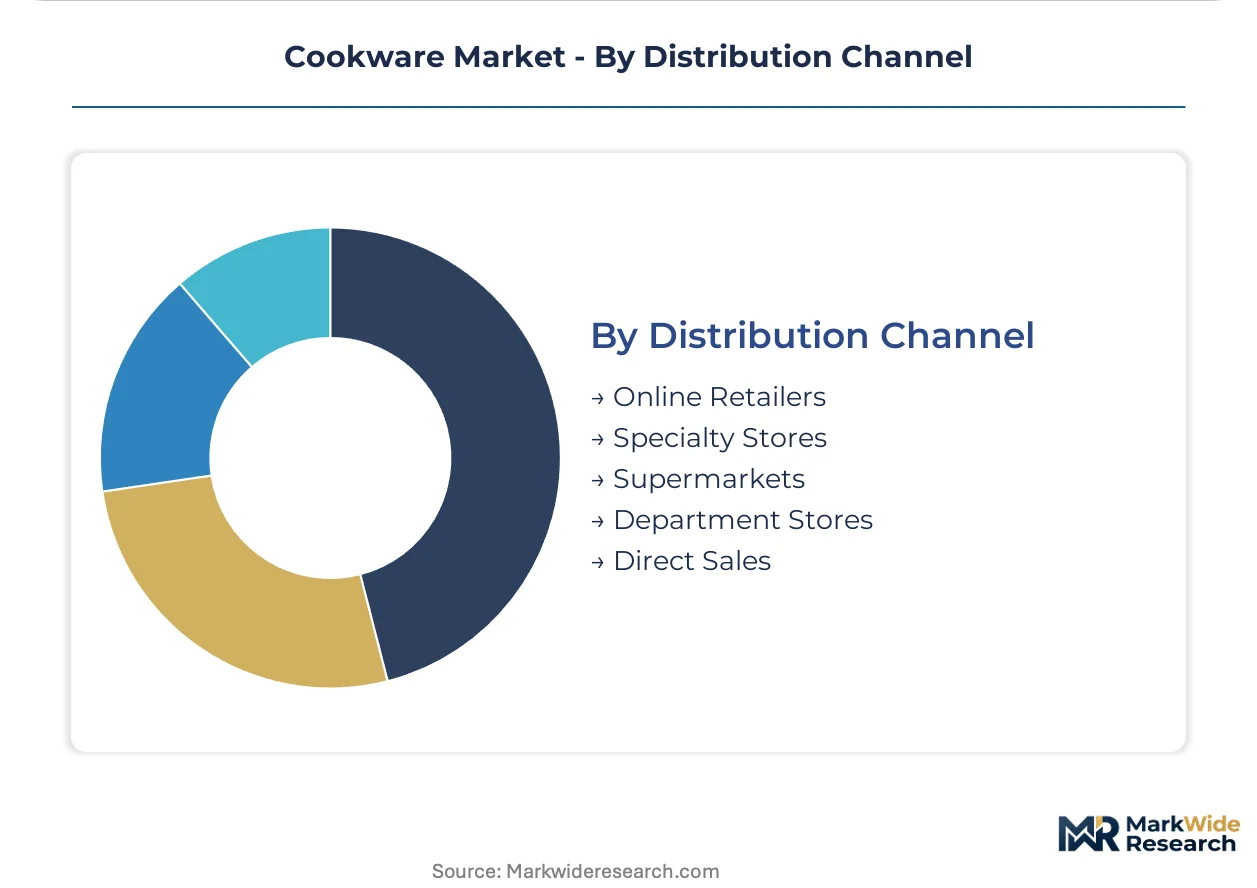
Distribution Channel:
The pathway to market for cookware reflects evolving consumer purchasing habits and brand reach strategies.
- Online Retailers:E-commerce platforms facilitate direct-to-consumer sales, offering extensive product catalogs and competitive pricing. Urban consumers in the United Kingdom increasingly purchase cookware through online channels for convenience and wider selection.
- Specialty Stores:These outlets offer curated selections of premium and professional-grade cookware with expert advice.
- Supermarkets:These large retail formats provide a convenient physical point of sale for mass-market cookware, often bundled with other household goods. Shoppers in Germany frequently acquire essential cookware items during their regular grocery trips.
- Department Stores:Traditional retail chains provide a broad range of mid-to-high-end cookware, often with brand displays.
- Direct Sales:This channel involves selling directly from manufacturer to consumer, bypassing intermediaries.
Online Retailers dominate new customer acquisition. Direct Sales is expanding most quickly for niche brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration heavily influences regional market dynamics, particularly in areas with burgeoning middle-class populations. Urban consumers in China and India drive demand for modern kitchen setups. Meanwhile, established markets like Germany and the United States show distinct preferences for material durability and specialized cooking methods.
China
Urbanization and rising disposable incomes in China significantly boost demand for non-stick frying pans, particularly for quick stir-fried meals. The country's GB standards ensure product safety and quality for food-contact materials. In metropolitan areas like Shanghai, a growing number of households are upgrading their cookware collections.
India
Increased disposable incomes across India fuel investment in modern kitchens and higher-quality cookware. The FSSAI regulates food-contact materials, ensuring consumer safety in cookware products. Commercial kitchens in Mumbai actively seek durable stockpots for high-volume meal preparation.
Germany
Residential consumers in Germany prioritize stainless steel for its longevity and aesthetic appeal, often making purchases during regular grocery trips. Compliance with the EU's REACH framework impacts material sourcing and manufacturing processes across Europe. Retail hubs in Frankfurt show strong sales of premium, durable cookware.
United States
Outdoor cooking enthusiasts in the United States drive demand for robust cast iron products, valued for their versatility over open flames. The US FDA sets strict regulations for food-contact materials in cookware, influencing product development. In states like Texas, camping and grilling culture supports a specialized cast iron market.
Canada
A sustained increase in home culinary activities across Canada boosts demand for diverse residential cookware, from specialized pieces to full sets. Health Canada guidelines ensure that cookware materials meet safety standards for consumer use. Major urban centers like Toronto exhibit strong consumer interest in advanced, multi-functional kitchen tools.
Cookware Market Key Industry Players
Channel-controlling players compete with product-specialist players across a tiered market structure. The market exhibits fragmentation among niche brands, while consolidation is evident at the premium, established end. Strategic archetypes include heritage brands focused on craftsmanship, material innovators developing new non-toxic coatings, and agile direct-to-consumer specialists. Dominant competitive moves involve portfolio diversification to capture varied consumer preferences and geographic expansion into rapidly urbanizing areas.
Specialists in premium materials and heritage designs include Groupe SEB SA, a French company leveraging multi-ply bonding technology to optimize heat distribution for high-performance cooking. Le Creuset Group, also based in France, differentiates with its iconic enameled cast iron designs, appealing to consumers who prioritize both aesthetic appeal and superior heat retention. Lodge Manufacturing, a US-based entity, sustains its position through specialization in seasoned cast iron, a material particularly popular among outdoor cooking enthusiasts for its inherent robustness and versatile application over various heat sources.
| Leading Market Players |
|---|
| Tramontina SA |
| Le Creuset Group |
| Groupe SEB SA |
| Lodge Manufacturing |
| Zwilling J.A. Henckels |
| Meyer Corporation |
| TTK Prestige Ltd |
| All-Clad |
| Newell Brands |
| Others |
Cost & Logistics Intelligence
Upstream raw material concentrations in steel and aluminum production directly influence downstream margin pools for cookware manufacturers. This dynamic shapes product pricing and supply chain resilience.
Pricing Analysis
Cost-plus contract patterns with indexation to global metal prices define pricing for many base cookware products. Price differentiation stems from material quality, brand premium for heritage designs like Le Creuset, and compliance with PFOA-free certifications. Pricing pressure stems from raw material price volatility and competition from multi-functional appliances. Residential consumers exhibit higher price sensitivity for basic items, while commercial kitchens prioritize durability and performance.
Supply Chain Analysis
Global supply of primary aluminum and stainless steel feeds from concentrated production hubs in China and India. The industry depends on these raw material inputs, alongside specialized non-stick coatings. Geopolitical instability affecting material sourcing presents a structural supply chain risk. Distribution runs through online retailers and supermarkets for mass-market products, with specialty stores and D2C channels serving premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cookware market offers a service-attach opportunity, particularly as smart cookware platforms with digital guided cooking are expanding faster than traditional hardware sales. This integration enhances user experience and creates recurring engagement points.
For Market Incumbents: Pre-empt market share erosion by diversifying product portfolios into smart cookware and induction-compatible designs. Invest heavily in R&D for advanced PFOA-free coatings to counter health-conscious consumer shifts. Strengthen channel control through expanded direct-to-consumer operations to mitigate competition from online counterfeit goods and multi-functional appliances. Defend multi-ply bonding IP through active legal enforcement.
For New Entrants and Emerging Players: Establish a beachhead in niche segments like modular, space-saving designs for urban consumers or specialized outdoor cooking equipment. Target health-conscious buyers with innovative ceramic-coated products. Leverage direct-to-consumer channels to emphasize sustainability credentials and build brand loyalty. Focus on specific material innovations or unique design aesthetics.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with established mid-market brands specializing in cast iron or enameled cookware with strong heritage. The market offers stable, long-term viability with potential for innovation-driven growth. Acquisition targets include agile direct-to-consumer specialists or material innovators in sustainable coatings. Watch for widespread adoption of smart home ecosystems as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Material R&D Investment | Drives innovation in PFOA-free and ceramic coatings, meeting health-conscious consumer demand. |
| Direct-to-Consumer Channel Expansion | Enhances brand control and captures higher margins by bypassing traditional retail intermediaries. |
| Smart Cookware Platform Development | Integrates digital guided cooking, creating interactive kitchen ecosystems for tech-forward users. |
| Circular Economy Design Principles | Supports product longevity and material traceability, aligning with EU sustainability mandates. |
| Multi-Ply Bonding IP Protection | Defends proprietary technology from infringement, maintaining competitive advantage in premium segments. |
Research Approach
The analysis maps residential and commercial cooking sub-sectors, each validated through primary interviews with product development engineers, procurement managers, and retail category buyers. Secondary validation draws from US FDA regulatory documents, EU REACH framework guidelines, industry association reports, and financial filings of major manufacturers. This approach triangulates bottom-up data with top-down market insights.
Assumptions regarding stable geopolitical conditions and consistent regulatory environments were held fixed across the analysis window. The analytical framework modeled segmentation dimensions including product type, material, application, distribution channel, and regional consumer preferences. Compound annual growth rates were derived from historical trends and projected market shifts. Key forecast inputs included urbanization rates in emerging economies and consumer health consciousness.
Stress conditions across raw material price volatility and regulatory shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding market stability and technological adoption. Cross-checking against external economic forecasts is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Asia-Pacific Hand Dryer Market
Household Items
India Non-Stick Cookware Market
Household Items
South Korea Cookware Market
Household Items
Insulated Water Bottles Market
Household Items
Household Sewing Machines Market
Household Items
Sanitary Metal Ware Market
Household Items
North America Car Air Freshener Market
Household Items
Memory Foam Market
Household Items
Toilet Paper Market
Household Items
India Cookware Market
Household Items
Europe Digital Showers Market
Household Items
Residential Air Purifiers Market
Household Items
Plastic Bathtub Market
Household Items
Fan Market
Household Items
Command Hooks Market
Household Items
Crash Mat Market