
 Indoor Humidifier Market | 2026-2036
Indoor Humidifier Market Size, Share, and Industry Trends Forecast 2026-2036
Indoor Humidifier Market Analytics
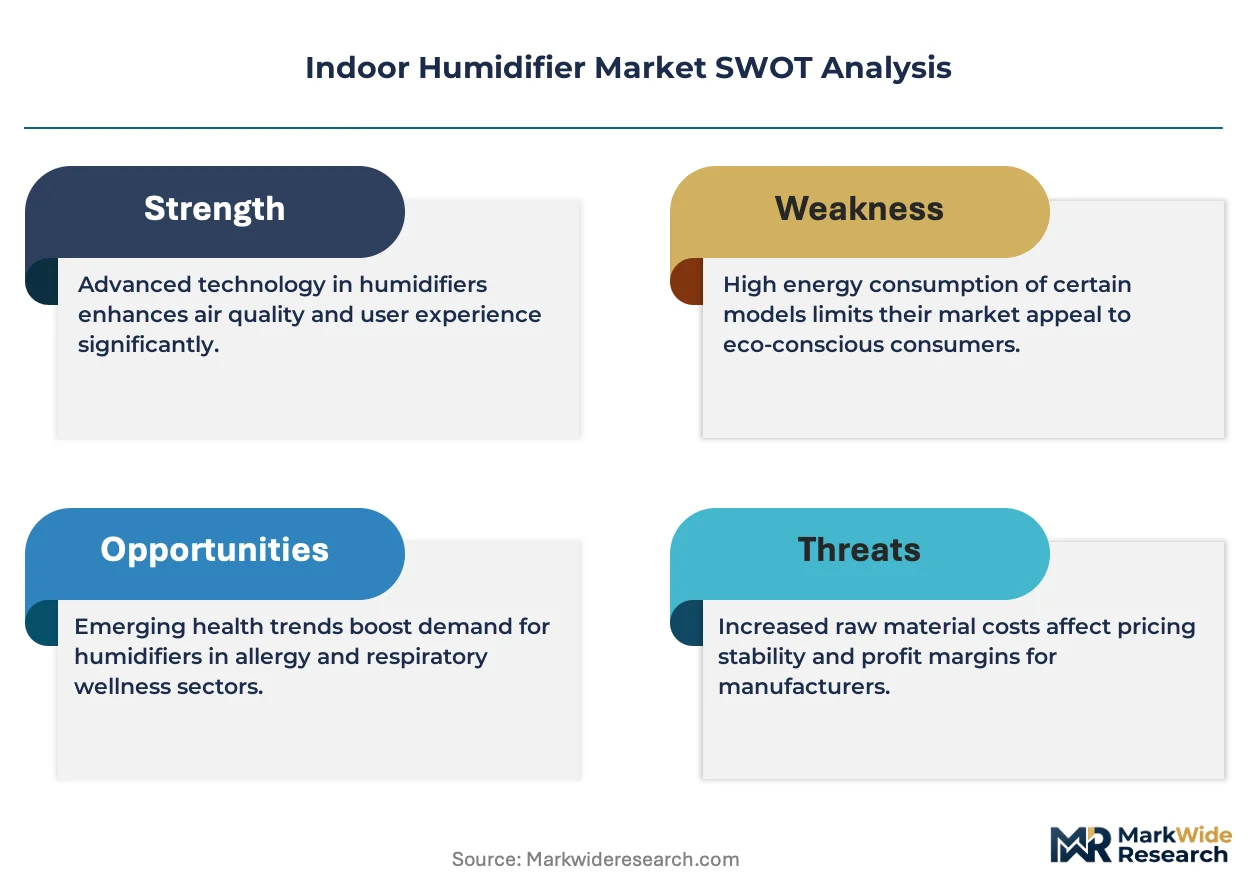
The premium HEPA-compatible specification tier is collapsing into mid-range price bands as ultrasonic and evaporative technologies mature. Honeywell International Inc. leverages its building-automation heritage to dominate commercial installations. Condair Group AG anchors industrial-grade steam vapor systems through captive supply of precision humidity controls. Dyson Ltd. differentiates via air-multiplier engineering that integrates humidification with purification.
An indoor humidifier is an electromechanical device that adds water vapor to ambient air to maintain relative humidity between 30% and 60%, employing ultrasonic piezoelectric transducers, evaporative wick filters, or steam-generation heating elements to prevent respiratory irritation and protect moisture-sensitive materials. Ultrasonic units lead residential volume due to silent operation and low energy draw, while steam vapor systems command industrial margin pools where precise humidity control protects pharmaceutical and electronics manufacturing. The healthcare end-user segment represents the fastest-growing application as hospitals deploy infection-control protocols requiring validated humidity ranges.
The EPA sets minimum efficiency standards for humidifier energy consumption, while the FDA regulates devices marketed with therapeutic claims; OSHA workplace air-quality guidelines further shape commercial demand. REACH compliance in Europe restricts antimicrobial additive chemistries, compelling manufacturers to reformulate reservoir treatments. Stakeholders must monitor evolving biocide regulations and smart-home interoperability standards to secure channel access and avoid compliance-driven product redesigns.
Market Dynamics
The residential smart-home integration wave is compressing product lifecycles and forcing manufacturers to prioritize interoperability certifications over standalone performance metrics.
Growth Catalysts
- EPA Energy-Efficiency Standards:The agency's tightening minimum efficiency requirements for humidifier energy consumption are pulling obsolete models from retail channels and accelerating replacement cycles among cost-conscious households.
- Antimicrobial Material Innovations:Advances in reservoir surface treatments and wick filter chemistries are expanding the addressable market to immunocompromised consumers and clinical settings previously served by industrial-grade systems.
- Healthcare Infection-Control Protocols:Hospital accreditation bodies are mandating validated humidity ranges in patient rooms and surgical suites, creating specification pull for precision-capable units.
Market Restraints
- REACH Biocide Restrictions:ECHA's evolving restrictions on antimicrobial additive chemistries in Europe are compelling costly reformulation of reservoir treatments and threatening shelf-life claims.
- Ultrasonic Transducer Supply Concentration:Precision piezoelectric component manufacturing clusters in East Asia create vulnerability to logistics disruptions and tariff exposure for brands without captive supply.
- Evaporative Wick Degradation:The inherent mineral accumulation and microbial fouling of wick-based systems limits their viable service interval in hard-water regions, compressing customer lifetime value.
Strategic Opportunities
- India Residential Penetration:Severe dry-season conditions and rising air-conditioning adoption in urban centers create latent demand currently served by improvised solutions.
- Smart-Home Interoperability Mandates:Matter protocol certification requirements from major retail channels are creating a compliance barrier that favors early-adopter manufacturers with dedicated connectivity engineering teams.
- Pharmaceutical Cleanroom Expansion:Biologics manufacturing growth is driving specification demand for steam vapor systems with validated control loops and audit-trail documentation.
Industry Challenges
- Firmware Security Certification:Connected humidifiers face escalating cybersecurity validation requirements from retailers and liability insurers, extending product development timelines.
- Cross-Border Harmonization Delays:Divergent smart-home interoperability standards between North American and European certification bodies are fragmenting R&D roadmaps and inflating variant engineering costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indoor Humidifier Market |
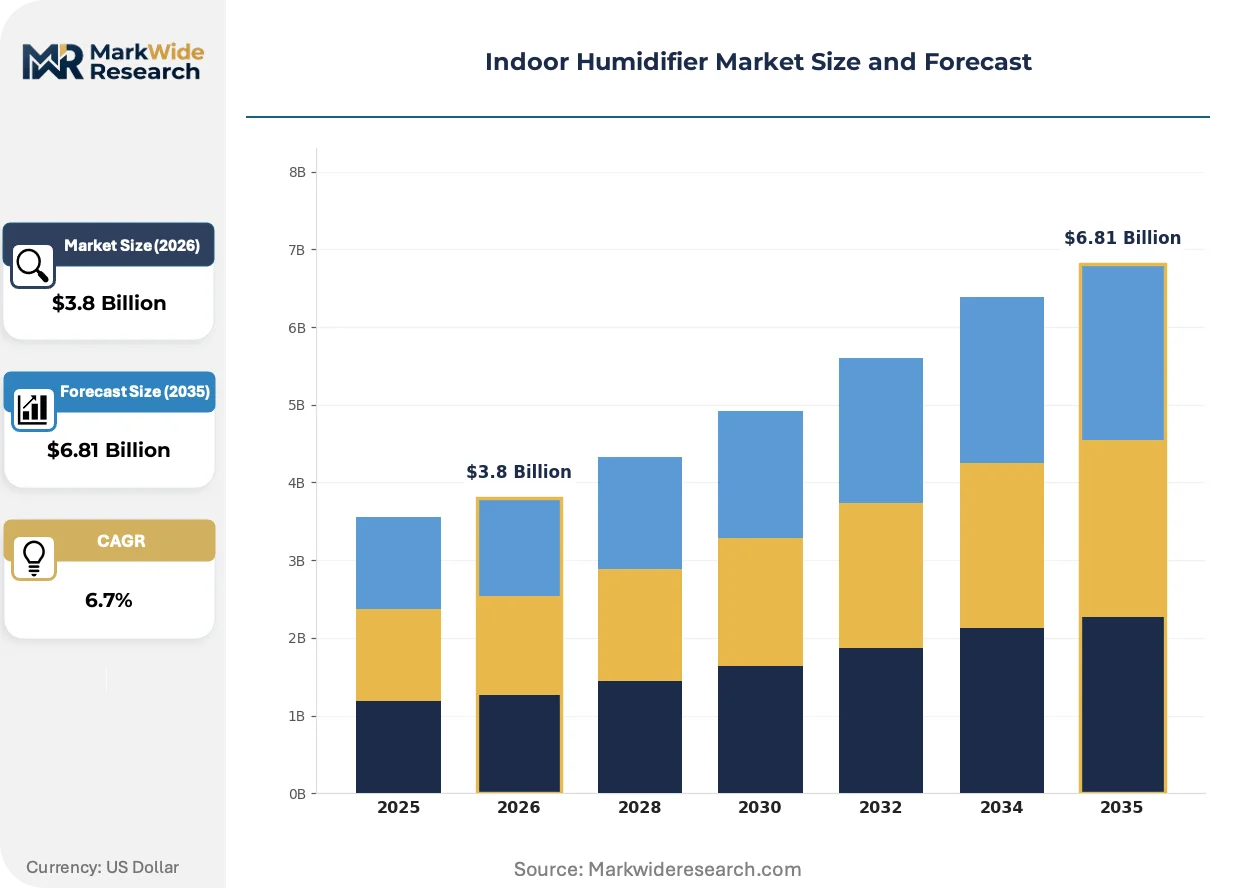
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Evaporative, Steam Vapor, Ultrasonic, Impeller End User: Residential, Commercial, Industrial, Healthcare Capacity: Small, Medium, Large, Extra Large Distribution Channel: Online, Offline, Retail, Direct Sales |
| Companies Covered | Honeywell International Inc., Condair Group AG, DriSteem, Pure Humidifier, Coway Co., Ltd, Dyson Ltd., Crane USA, Boneco AG, CAREL INDUSTRIES S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indoor Humidifier Market Evolving Landscape
Product architecture is splitting between premium integrated air-care platforms and stripped-down connected basics, with the middle tier losing shelf space and margin.
Ultrasonic piezoelectric transducer technology is bifurcating the residential market. High-frequency vibration systems enable silent, low-energy moisture dispersion ideal for bedroom deployment. Mass-market brands are racing to integrate these transducers with basic connectivity at entry price points. The technology is bifurcating the category into whisper-quiet connected units and legacy evaporative systems relegated to utility spaces.
REACH compliance deadlines in Europe are accelerating material substitution across the supply chain. ECHA's restrictions on legacy antimicrobial chemistries are forcing reservoir and wick manufacturers to validate alternative surface treatments. German and French testing laboratories report certification backlogs extending product launch timelines by four to six months for reformulated designs.
Hospital procurement departments are unbundling humidification from bundled HVAC maintenance contracts. Infection-control officers now specify standalone validated units with independent monitoring documentation. This pattern is most visible in United States academic medical centers and is spreading to German university hospital networks seeking direct vendor accountability for humidity compliance.
Indoor Humidifier Market Segmentation
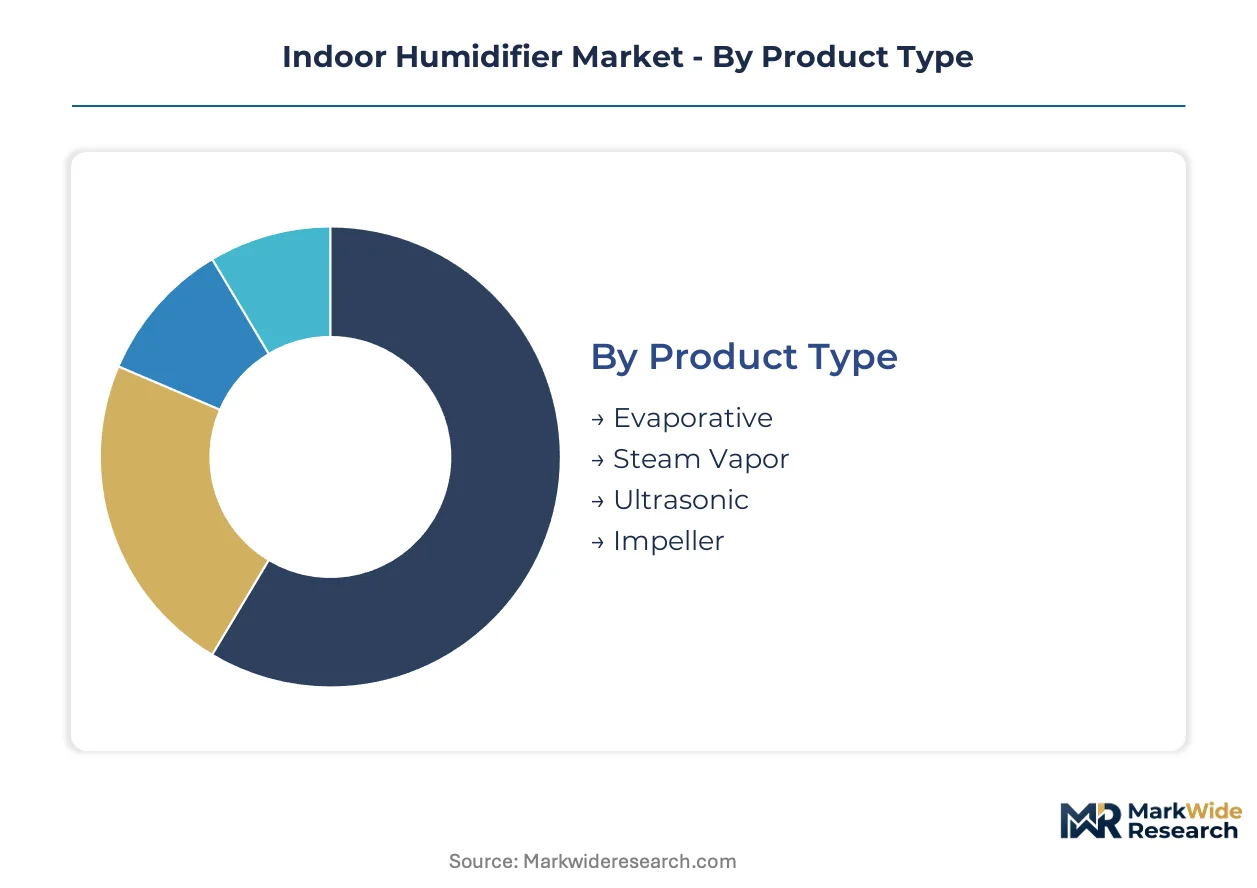
Product architecture in the Indoor Humidifier Market fragments across four dimensions, each presenting distinct margin profiles and regulatory exposure. Substitution threats from integrated HVAC systems and alternative moisture-control technologies reshape competitive intensity within each category.
Product Type:
Steam vapor systems face the most acute substitution pressure from building-integrated humidification, while ultrasonic units confront evaporative alternatives in residential bedrooms.
- Ultrasonic:High-frequency piezoelectric transducers generate micro-fine mist without heating elements, enabling silent operation below 30 decibels. Demand concentrates in United States suburban households prioritizing sleep compatibility, though hard-water mineral dust accumulation drives filter replacement revenue.
- Steam Vapor:Electric heating elements boil water to produce sterile vapor, achieving hospital-grade humidity precision with validated control loops. German pharmaceutical cleanrooms and United States academic medical centers specify these units for infection-control compliance, despite higher energy draw.
- Evaporative:Wick-filter systems pass air through moistened media, offering self-regulating output that tapers as ambient humidity rises.
- Impeller:Rotating disks fling water against diffuser screens, producing coarse droplets suited for utility spaces and budget-conscious buyers.
Ultrasonic retains volume leadership; steam vapor holds the steepest expansion curve.
End User:
Cost-tier stratification separates specification-heavy institutional buyers from price-sensitive residential consumers, with commercial offices occupying a contested middle ground.
- Healthcare:Hospitals and surgical suites require FDA-registered devices with continuous monitoring documentation and audit-trail capabilities. United States infection-control officers increasingly specify standalone validated units, unbundling humidification from HVAC maintenance contracts.
- Residential:Smart-home integration and Matter protocol compatibility now dominate purchase criteria among connected-device adopters in China and Germany.
- Industrial:Electronics and pharmaceutical manufacturing demand precision humidity control with redundant sensor arrays.
- Commercial:Office buildings and hospitality venues balance first-cost constraints against tenant comfort complaints.
Residential dominates unit shipments; healthcare climbs the fastest.
Capacity:
Volume concentration in medium-capacity units reflects apartment-dwelling patterns in urban China and Germany, while extra-large systems serve industrial process requirements.
- Medium:Coverage areas of 400-1000 square feet align with typical apartment footprints in Shanghai and Mumbai high-rises, where dry-season air conditioning compounds moisture extraction.
- Large:Whole-home and small commercial deployments in United States suburban single-family residences.
- Small:Desktop and travel-sized units for personal workspaces and hotel room portability.
- Extra Large:Centralized building systems and cleanroom installations requiring redundant capacity.
Medium capacity commands the largest installed base; large capacity gains share fastest.
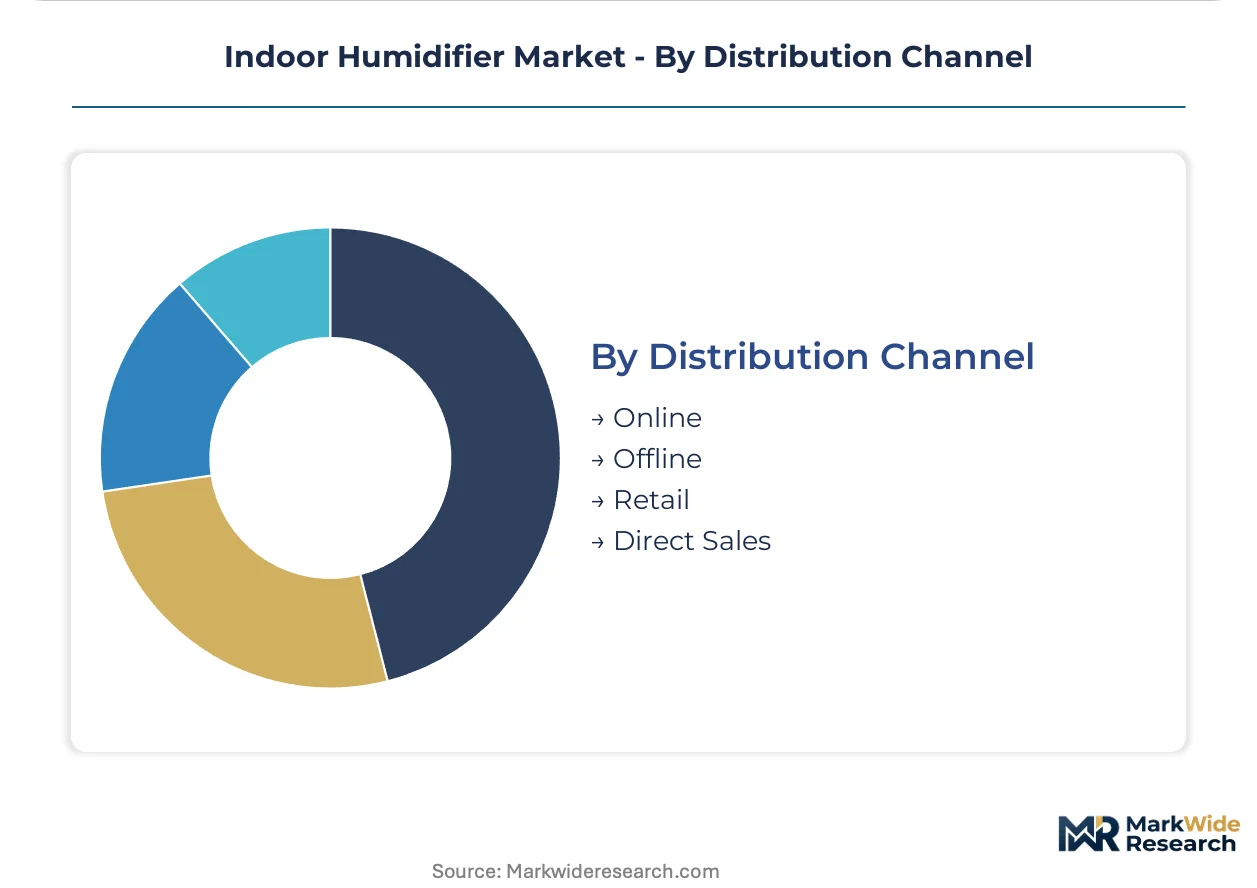
Distribution Channel:
Smart-home interoperability mandates from major retail channels are compressing margins for brands lacking dedicated connectivity engineering teams.
- Online:E-commerce platforms enable direct-to-consumer brands to bypass traditional retail markups while leveraging review aggregation and comparison tools. Amazon and Tmall dominate traffic in the United States and China respectively.
- Retail:Big-box stores and specialty home-goods chains provide tactile evaluation opportunities for first-time buyers.
- Direct Sales:Industrial and healthcare procurement departments source validated systems through manufacturer representatives.
- Offline:Remaining traditional channels including catalog and telephone sales.
Online leads transaction volume; direct sales expands most quickly in institutional segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component manufacturing clusters for piezoelectric transducers and precision humidity sensors concentrate in East Asian industrial zones, while specification-driven demand emanates from healthcare and pharmaceutical corridors in the United States and Germany.
United States
Suburban household penetration drives residential volume, with sleep-compatible ultrasonic units dominating bedroom deployments. The EPA enforces tightening minimum efficiency standards for humidifier energy consumption, accelerating replacement cycles. Academic medical centers in Boston and New York unbundle humidification from HVAC contracts, specifying standalone validated units with audit-trail documentation.
China
Urban air-conditioning adoption compounds dry-season moisture extraction in Shanghai and Beijing high-rises, creating concentrated demand for medium-capacity units. The Ministry of Ecology and Environment advances dual carbon goals that shape energy-efficiency requirements for domestic manufacturers. Shenzhen and Dongguan electronics clusters supply precision piezoelectric components to global brands.
Germany
Pharmaceutical cleanroom expansion in Bavaria and Baden-Württemberg drives specification demand for steam vapor systems with validated control loops. ECHA REACH compliance deadlines restrict legacy antimicrobial chemistries, forcing reservoir material reformulation. Testing laboratories in Berlin and Hamburg report certification backlogs extending product launch timelines.
India
Severe dry-season conditions in Delhi and Mumbai create latent demand currently served by improvised solutions. The Bureau of Indian Standards develops harmonized efficiency labeling for domestic appliances. Maharashtra and Gujarat manufacturing corridors attract assembly investment targeting price-sensitive residential segments.
Japan
Premium residential preferences favor integrated air-care platforms combining humidification with purification functions. METI energy-conservation standards influence product design requirements for connected home appliances. Nagoya industrial machinery clusters supply precision sensor arrays for healthcare-grade humidity control systems.
Indoor Humidifier Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with precision-engineering specialists commanding institutional margins and mass-market fabricators competing on connected-device accessibility. The vendor base spans building-automation conglomerates, industrial humidity-control specialists, and consumer-appliance innovators. Three archetypes dominate: heritage HVAC integrators leveraging commercial infrastructure relationships; captive-component manufacturers controlling transducer supply; and design-led brands differentiating through integrated air-care platforms. Competitive intensity manifests in smart-home interoperability certification races and antimicrobial material patent filings.
Within the heritage building-automation tier, Honeywell International Inc. and Condair Group AG exemplify divergent strategic positions. Honeywell leverages its commercial installation legacy to anchor specification-driven healthcare and office segments, while Condair's captive supply of precision humidity controls secures industrial-grade steam vapor contracts. Dyson Ltd. occupies a distinct design-engineering position, representing the integrated-platform archetype that merges humidification with air purification through proprietary fluid dynamics.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Condair Group AG |
| DriSteem |
| Pure Humidifier |
| Coway Co., Ltd |
| Dyson Ltd. |
| Crane USA |
| Boneco AG |
| CAREL INDUSTRIES S.p.A. |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between German pharmaceutical cleanroom operators and steam vapor system manufacturers lock in both piezoelectric component supply access and five-year price visibility, insulating procurement teams from spot-market volatility in East Asian transducer markets.
Pricing Analysis
EPA energy-efficiency standards dictate the pricing tier structure across the United States residential channel, separating ENERGY STAR-certified ultrasonic units from legacy evaporative models facing retail delisting. Three-tier pricing structure across premium connected, standard certified, and economy non-certified levels reflects smart-home interoperability investment and antimicrobial surface treatment costs. Cost compression in the mid-tier is intensifying because Matter protocol certification requirements concentrate engineering spend among early-adopter brands. Residential consumers in India and China exhibit highest price sensitivity, while United States hospital procurement departments prioritize validated audit-trail capabilities over unit economics.
Supply Chain Analysis
Strategic stockpiling of piezoelectric transducers by Japanese and German precision-component specialists buffers against just-in-time vulnerabilities exposed by East Asian logistics disruptions. Manufacturing concentration in China, South Korea, and Vietnam feeds global ultrasonic unit assembly, while German and Swiss suppliers anchor steam vapor precision controls. The supply chain rests on ceramic oscillator substrates, antimicrobial polymer resins, and humidity sensor arrays. Single-source vulnerability concentrates in high-frequency transducer fabrication clusters. Distribution runs through Amazon and Tmall direct-to-consumer platforms in volume markets, with direct sales penetrating healthcare and industrial procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The indoor humidifier market is experiencing high-growth disruption as EPA efficiency mandates and Matter protocol certification requirements simultaneously obsolete legacy inventory and erect compliance barriers for connectivity-lagged competitors.
For Market Incumbents: Compound defensive positioning by securing captive supply agreements with Dongguan and Shenzhen piezoelectric manufacturers before tariff exposure hardens, and accelerate antimicrobial material patent filings ahead of ECHA REACH compliance deadlines. Smart-home interoperability certification races threaten margin pools for brands lacking dedicated connectivity engineering teams.
For New Entrants and Emerging Players: Anchor in India's latent residential demand currently served by improvised solutions, targeting price-sensitive apartment dwellers in Delhi and Mumbai with stripped-down connected basics omitting premium air-purification integration. Direct-to-consumer launches via Flipkart and Amazon India bypass established retail markups.
For Investors and Strategic Acquirers: Captive-component manufacturers with in-house transducer production and validated healthcare-grade control systems represent the highest-conviction acquisition archetype for exposure to pharmaceutical cleanroom expansion. Watch FDA registration timelines for standalone hospital humidification units as the inflection signal separating specification winners from commodity players.
| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Amazon and Best Buy interoperability mandates filter out connectivity-lagged competitors from premium shelf space. |
| Antimaterial Patent Filing | ECHA REACH compliance deadlines force reservoir reformulation, rewarding early movers with validated alternative chemistries. |
| Healthcare Direct Sales Expansion | United States academic medical centers unbundle humidification from HVAC contracts, creating standalone validated unit demand. |
| India E-commerce Launch | Bureau of Indian Standards efficiency labeling harmonization opens price-sensitive residential penetration opportunity. |
| Steam Vapor Capacity Addition | German pharmaceutical cleanroom expansion in Bavaria drives specification demand for precision humidity control systems. |
Research Methodology
Cross-validation between primary interviews with product managers at connected-device manufacturers and secondary validation through EPA ENERGY STAR certification databases anchors the qualitative findings. Conversations with infection-control officers at United States academic medical centers, procurement directors at German pharmaceutical cleanroom operators, and category buyers at Amazon and Tmall informed demand-side segmentation. Customs records from China and Vietnam, SEC 10-K filings from building-automation conglomerates, and ECHA biocide registration databases provided supply-side triangulation. Bottom-up unit shipment modeling and top-down value aggregation reconciled through iterative stakeholder feedback.
Sensitivity analysis around EPA efficiency standard implementation timelines and Matter protocol adoption curves stress-tested volume projections across the analysis window. Segmentation dimensions modeled include product type (ultrasonic, steam vapor, evaporative, impeller), end user (healthcare, residential, industrial, commercial), capacity tier, and distribution channel. CAGRs derive from regression against historical replacement cycle data and regulatory-driven obsolescence patterns. Smart-home interoperability certification rates and antimicrobial material substitution timelines served as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under base assumptions of steady EPA enforcement and REACH compliance deadlines; material deviation would warrant model refresh. Revision becomes warranted when ECHA expands biocide restriction lists or when major retail channels advance interoperability mandates beyond current Matter protocol requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Insulated Water Bottles Market
Household Items
Snow Blower Market
Household Items
Air Freshener Market
Household Items
Sleeping Pods Market
Household Items
Europe Handheld Vacuum Cleaners Market
Household Items
Fine Mist Sprayer Market
Household Items
Hydration Containers Market
Household Items
Coffin and Cremation Urn Market
Household Items
Lunch Box Market
Household Items
India Digital Showers Market
Household Items
Hydralight Lanterns Market
Household Items
Candle Air Fresheners Market
Household Items
Non-Stick Cookware Market
Household Items
Electric Brooms Market
Household Items
US Air Purifier Market
Household Items
UK Digital Showers Market