
 India Air Purifier Market | 2026-2036
India Air Purifier Market Size, Share, and Industry Trends Forecast 2026-2036
India Air Purifier Market Outlook
Skilled HVAC technician availability is collapsing across tier-two Indian cities, forcing manufacturers to build captive service networks. Daikin Industries Ltd anchors its position through backward integration into compressor and filter manufacturing. Koninklijke Philips NV competes on diagnostic sensor precision and connected-home compatibility. Voltas dominates the value-tier segment through deep distribution into smaller municipal markets.
An air purifier is an electromechanical device that draws ambient air through a multi-stage filtration matrix—typically comprising a pre-filter, HEPA media rated at 99.97% efficiency for 0.3-micron particles, and activated carbon—to reduce airborne particulate matter, volatile organic compounds, and biological contaminants. Portable units lead volume shipments due to apartment-friendly form factors and plug-and-play deployment, while in-duct systems command premium pricing in commercial new-build projects. HEPA technology sustains the largest installed base, though UV-C augmentation is displacing legacy ionizer configurations in healthcare and hospitality specifications.
BIS certification requirements and the CEA's energy-efficiency labeling framework shape product compliance costs and market access timelines for imported and domestic assemblies alike. The PLI scheme for white goods and consumer electronics is redirecting capital toward local component sourcing and assembly automation. Stakeholders must monitor how state-level clean-air action plans translate into institutional procurement mandates for schools, transit hubs, and government facilities.
Market Dynamics
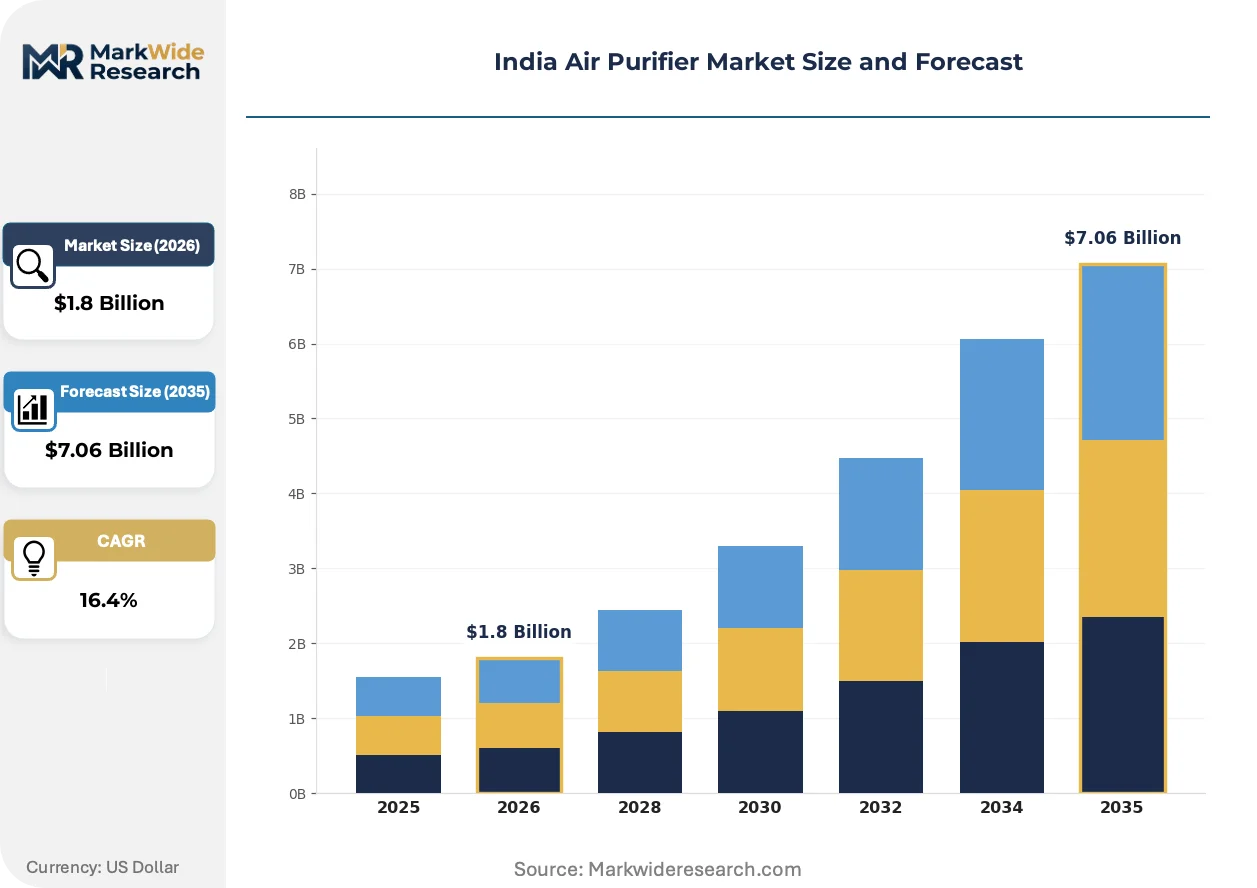
Skilled HVAC technician scarcity across tier-two Indian cities is forcing manufacturers toward captive service networks and backward integration into component production. The BIS certification mandate and CEA energy-efficiency labeling are tightening compliance timelines while the PLI scheme redirects capital toward local assembly automation.
Growth Catalysts
- Winter particulate spikes:Seasonal AQI deterioration in Delhi-NCR and Mumbai triggers concentrated replacement cycles among middle-class households, creating predictable demand windows for portable units.
- CEA energy-efficiency labeling:Mandatory star-rating disclosure accelerates obsolescence of unlabeled legacy inventory and tilts procurement toward certified models in institutional channels.
- PLI scheme for white goods:Production-linked incentives are pulling component sourcing and final assembly into domestic facilities, compressing landed costs for India-manufactured HEPA systems.
Market Restraints
- HEPA media import dependency:Domestic glass microfiber supply remains underdeveloped, exposing assemblers to freight volatility and currency fluctuation on Japanese and German membrane imports.
- Technician density gaps:Certified HVAC service capacity concentrates in six metropolitan clusters, leaving tier-two cities with 72-hour-plus response times that degrade warranty fulfillment rates.
- Activated carbon substitution risk:Low-cost ionizer configurations without substantive filtration media continue capturing price-sensitive segments despite documented ozone emission concerns.
Strategic Opportunities
- State clean-air procurement mandates:Delhi, Maharashtra and Karnataka action plans are institutionalizing purifier specifications for schools, transit infrastructure and government facilities.
- UV-C augmentation convergence:Healthcare and hospitality specifications are merging HEPA mechanical capture with ultraviolet germicidal irradiation, opening premium positioning above standard filtration.
- Apartment-friendly form factors:Compact tower and wall-mounted designs are penetrating Mumbai and Bengaluru high-rise stock where floor-space constraints previously blocked category entry.
Industry Challenges
- BIS certification timeline compression:Electronic goods safety testing queues at BIS-recognized laboratories currently extend 14-18 weeks, delaying product launches past seasonal demand peaks.
- Filter replacement logistics:Consumables replenishment networks remain fragmented outside top-10 cities, causing user attrition when HEPA media saturates and no retail channel stocks compatible replacements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Air Purifier Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Wall-mounted, Ceiling-mounted, In-duct Technology: HEPA, Activated Carbon, UV, Ionizer End User: Residential, Commercial, Industrial, Automotive Distribution Channel: Online, Offline, Direct Sales, Retail |
| Companies Covered | Dyson Ltd, Coway, Daikin Industries Ltd, Blueair, Sharp, Honeywell International Inc, Panasonic Corporation, Voltas, Koninklijke Philips NV, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Air Purifier Market Strategic Shifts
Filtration architecture is splitting between premium multi-stage systems with diagnostic sensors and stripped-down value-tier units, while regulatory pressure and procurement formalization reshape competitive positioning across residential and institutional channels.
HEPA-UV hybrid technology is bifurcating the specification landscape in healthcare and hospitality verticals. Standard HEPA mechanical capture now serves cost-constrained residential buyers. Premium contracts for hospital HVAC retrofits and hotel chain rollouts mandate ultraviolet germicidal augmentation. This split is compressing margin pools for single-technology vendors unable to certify combined systems.
BIS certification requirements and CEA energy-efficiency labeling are hardening product entry standards for both imported and domestic assemblies. Compliance costs have risen substantially for manufacturers relying on third-party testing. Smaller municipal markets now filter procurement through star-rating thresholds that exclude unlabeled inventory from institutional tenders.
After-sales service unbundling is disrupting traditional bundled warranty models in tier-one cities. Buyers increasingly purchase hardware through e-commerce channels while sourcing filter replacements and maintenance through manufacturer-direct subscription programs. This pattern is most visible in Delhi-NCR and Mumbai apartment complexes where service aggregator apps now intermediate technician dispatch.
India Air Purifier Market Segmentation
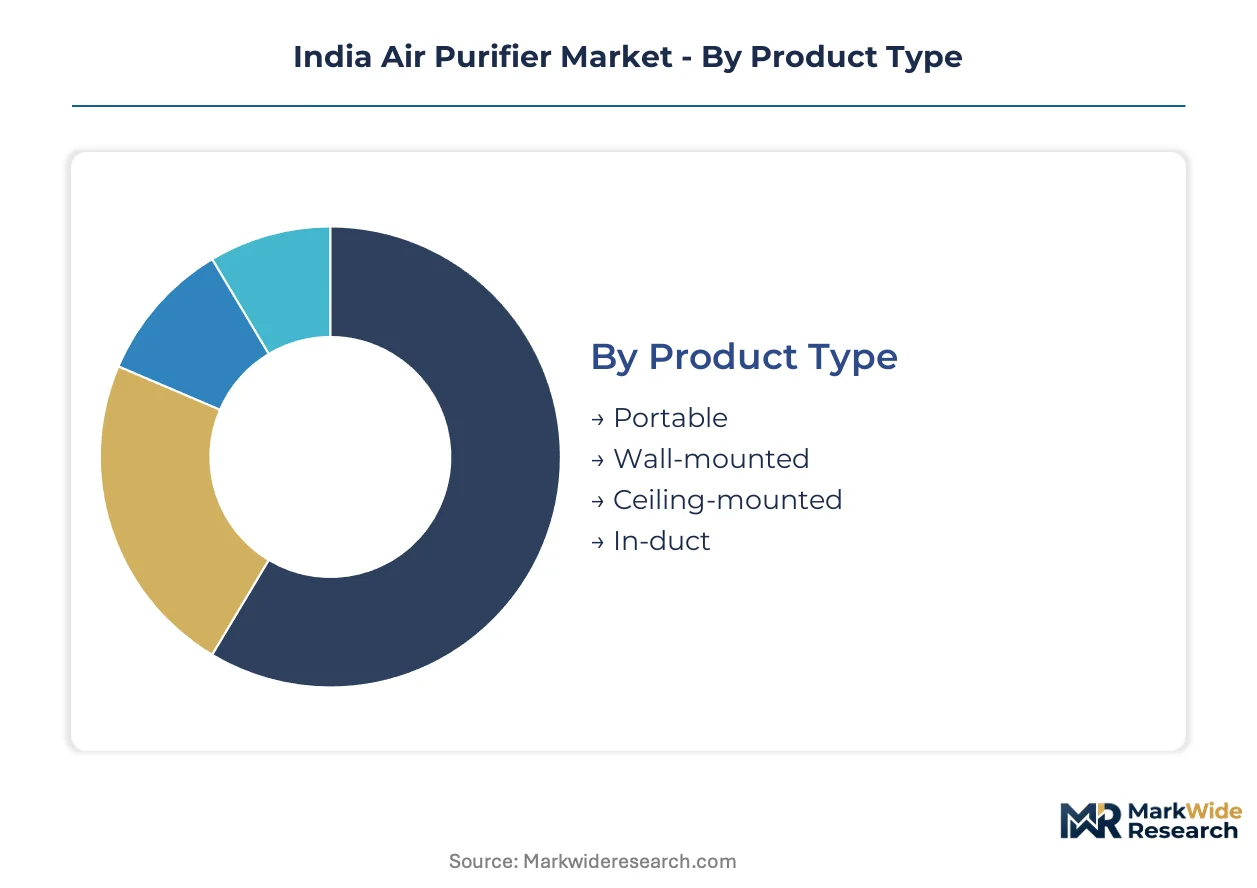
Segmentation in the India air purifier market reveals how substitution threats, regulatory compliance costs, and service infrastructure gaps concentrate value across distinct product configurations and channel pathways. Manufacturers must align portfolio depth with the geographic and institutional demand patterns that dominate each segment.
Product Type:
Substitution pressure from low-cost ionizer units without genuine filtration media weighs heaviest on portable and wall-mounted categories, while in-duct systems face minimal direct replacement risk due to their integration into building infrastructure.
- Portable:Freestanding electromechanical units with plug-and-play deployment dominate apartment installations across Delhi-NCR and Mumbai. Seasonal AQI spikes in northern Indian states drive replacement cycles among middle-class households lacking permanent HVAC infrastructure.
- In-duct:Integrated filtration systems installed within central air handling units command premium positioning in commercial new-build projects. Healthcare and hospitality specifications in Bengaluru and Hyderabad mandate these configurations for comprehensive building-wide air quality management.
- Wall-mounted:Compact units affixed to vertical surfaces address floor-space constraints in Mumbai high-rise stock. Demand concentrates among urban renters seeking semi-permanent installation without structural modification.
- Ceiling-mounted:Suspended units distribute filtered air downward in open-plan commercial interiors. Corporate office retrofits in Gurugram and Noida represent the primary adoption corridor.
Portable units retain volume leadership; in-duct systems hold the steepest expansion curve.
Technology:
Cost tier stratification separates certified multi-stage systems from stripped-down alternatives, with compliance timelines under BIS and CEA frameworks widening the gap between premium and value-tier offerings.
- HEPA:Glass microfiber media rated at 99.97% efficiency for 0.3-micron particles constitutes the dominant installed base. Import dependency on Japanese and German membrane suppliers exposes assemblers to currency fluctuation and freight volatility.
- UV:Ultraviolet germicidal irradiation augmentation is displacing legacy configurations in healthcare specifications. Hospital HVAC retrofits in Delhi and Maharashtra now routinely mandate HEPA-UV hybrid certification.
- Activated Carbon:Porous media adsorbs volatile organic compounds and gaseous contaminants. Replacement logistics outside top-10 Indian cities remain fragmented, causing user attrition when saturated media cannot be sourced.
- Ionizer:Electrostatic precipitation devices without substantive filtration capture price-sensitive segments despite documented ozone emission concerns under BIS electronic goods safety standards.
HEPA technology anchors the largest installed base; UV augmentation is gaining share fastest.
End User:
Application-driven procurement patterns split between discretionary residential purchases triggered by seasonal AQI deterioration and institutional mandates formalized through state clean-air action plans.
- Residential:Individual household purchases concentrate in Delhi-NCR, Mumbai, and Bengaluru metropolitan clusters. Winter particulate spikes create predictable demand windows for portable units among middle-class consumers.
- Commercial:Corporate offices, retail chains, and hospitality properties drive specification-grade procurement. Mumbai and Bengaluru high-rise commercial stock generates sustained demand for integrated building systems.
- Industrial:Manufacturing facilities and warehouse operations deploy heavy-duty configurations for process air quality control. Regulatory enforcement under state pollution control boards varies across Maharashtra, Gujarat, and Tamil Nadu industrial corridors.
- Automotive:Cabin air filtration systems address particulate intrusion in vehicle interiors. Aftermarket retrofit demand tracks vehicle ownership expansion in tier-two Indian cities.
Residential adoption maintains volume dominance; commercial specifications are expanding most quickly.
Distribution Channel:
Customer type fragmentation between e-commerce natives and service-dependent buyers is unbundling traditional bundled warranty models, with channel selection correlating directly to technical support requirements.
- Online:E-commerce platforms capture hardware transactions among digitally fluent consumers in tier-one cities. Manufacturer-direct filter subscription programs now intermediate replenishment and technician dispatch.
- Offline:Brick-and-mortar electronics retailers provide tactile evaluation and immediate fulfillment. Tier-two municipal markets remain dependent on this channel due to delivery infrastructure gaps.
- Direct Sales:Manufacturer-controlled channels serve institutional procurement with customized specification and service bundling. State clean-air mandates for schools and transit hubs route through this pathway.
- Retail:General merchandise and home appliance stores stock value-tier inventory for price-sensitive segments. Voltas leverages this channel for deep distribution into smaller municipal markets.
Online channels are climbing the fastest; offline retail retains the deepest geographic penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Indian states diverge sharply between northern metros responding to winter particulate emergencies and southern cities prioritizing year-round allergen control. This geographic split shapes product specifications, distribution requirements, and service infrastructure investments.
Delhi-NCR
Winter AQI deterioration above 400 triggers concentrated replacement cycles among middle-class households. The Commission for Air Quality Management enforces Graded Response Action Plan mandates for institutional procurement. Gurugram and Noida corporate campuses drive ceiling-mounted unit specifications for open-plan office retrofits.
Maharashtra
Mumbai high-rise stock generates apartment-friendly form factor demand among space-constrained renters. The state pollution control board enforces clean-air action plan specifications for transit infrastructure. Pune manufacturing corridors create industrial-grade procurement for process air quality management.
Karnataka
Bengaluru's technology workforce sustains year-round portable unit adoption driven by allergen sensitivity rather than seasonal spikes. State energy department procurement guidelines reference CEA star-rating thresholds. Whitefield and Electronic City commercial clusters mandate in-duct systems for new-build projects.
Tamil Nadu
Chennai coastal humidity drives corrosion-resistant specification requirements distinct from northern dust-focused designs. State industrial policy incentives align with PLI scheme domestic assembly requirements. Sriperumbudur automotive belt generates cabin air filtration aftermarket demand.
Telangana
Hyderabad pharmaceutical manufacturing corridors deploy HEPA-UV hybrid configurations for cleanroom compliance. State municipal administration directives specify purifier deployment for government school infrastructure. HITEC City commercial developments integrate building-wide air handling specifications.
India Air Purifier Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with Japanese and Korean conglomerates controlling premium filtration technology while domestic assemblers capture volume through distribution depth. The competitive terrain splits between certification-heavy institutional channels and price-sensitive retail segments. Two strategic archetypes dominate: vertically integrated component manufacturers and brand licensors leveraging third-party assembly. Capacity expansion into domestic manufacturing and captive service network construction represent the dominant competitive moves.
Among Japanese diversified industrials, Daikin Industries Ltd exemplifies backward integration into compressor and filter manufacturing. Koninklijke Philips NV anchors the diagnostic sensor tier with connected-home positioning. Voltas occupies the value-tier vector through deep distribution into smaller municipal markets beyond the top-ten urban clusters.
| Leading Market Players |
|---|
| Dyson Ltd |
| Coway |
| Daikin Industries Ltd |
| Blueair |
| Sharp |
| Honeywell International Inc |
| Panasonic Corporation |
| Voltas |
| Koninklijke Philips NV |
| Others |
Value Chain & Pricing Dynamics
BIS certification timelines and CEA energy-efficiency labeling gate both supply qualification and price differentiation simultaneously, compressing margin pools for assemblers unable to absorb 14-18 week laboratory queues while tier-one buyers demand star-rated inventory.
Pricing Analysis
Long-term offtake contracts dominate institutional procurement for schools and transit infrastructure under state clean-air mandates, while spot purchasing governs seasonal residential spikes in Delhi-NCR. Price differentiation hinges on CEA star-rating certification and after-sales service bundling, with subscription-based filter replenishment commanding premium positioning. Cost compression in the value tier intensifies as ionizer substitutes capture price-sensitive segments despite BIS safety concerns. Commercial buyers show lowest price sensitivity due to specification mandates, while tier-two municipal markets remain highly price-elastic.
Supply Chain Analysis
Inventory lead times for HEPA glass microfiber media extend 8-12 weeks due to concentrated sourcing from Japan and Germany, exposing domestic assemblers to freight volatility and currency fluctuation. Raw material dependencies center on imported membrane substrates, activated carbon from Southeast Asia, and UV-C lamp assemblies from South Korea. Single-source vulnerability on Japanese microfiber suppliers represents the primary structural risk. Distribution runs through manufacturer-direct channels for institutional buyers and fragmented retail networks for residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified HVAC technician scarcity constrains warranty fulfillment and service network expansion, creating competitive advantage for players with captive technical capacity or aggregator-platform partnerships.
For Market Incumbents: Shield margin pools by accelerating backward integration into compressor and filter manufacturing to offset HEPA media import dependency. Invest in captive service network construction across tier-two cities where 72-hour response times currently degrade customer retention. Prioritize BIS-recognized laboratory partnerships to compress certification timelines ahead of seasonal demand windows. For New Entrants and Emerging Players: Lead with apartment-friendly form factors targeting Mumbai and Bengaluru high-rise renters underserved by bulky portable units. Exploit fragmented filter replacement logistics outside top-10 cities through subscription-based consumables programs. Pursue direct sales channels for state clean-air procurement mandates in Delhi, Maharashtra and Karnataka schools and transit infrastructure. For Investors and Strategic Acquirers: Secondary-cycle assets sit with domestic assemblers lacking vertical integration but holding deep tier-two distribution relationships. Five-to-ten year viability hinges on PLI scheme utilization and local component sourcing transition. Monitor BIS certification queue compression as inflection indicator for product launch velocity and market share capture potential.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Filter Manufacturing | Reduces HEPA media import exposure and compresses landed costs under PLI incentives. |
| Captive Service Network Construction | Addresses tier-two technician scarcity and improves warranty fulfillment rates. |
| CEA Star-Rating Certification Investment | Enables institutional procurement access under state clean-air mandates. |
| Filter Subscription Program Launch | Captures recurring revenue and reduces user attrition from replacement logistics gaps. |
| UV-C Augmentation Certification | Opens premium healthcare and hospitality specifications above standard HEPA systems. |
Study Parameters
A standing panel of HVAC service technicians, BIS certification laboratory directors, state pollution control board officials, and institutional procurement managers provided ongoing calibration across primary interview cycles. Secondary validation drew from CEA energy-efficiency registry data, BIS electronic goods safety filings, state clean-air action plan documents, and customs import records for HEPA media and activated carbon. Bottom-up unit shipment estimates triangulated against top-down value projections derived from distributor and retailer channel checks.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling incorporated product type, technology tier, end-user application, and distribution channel dimensions. CAGRs were derived from fitted growth curves applied to baseline consumption estimates, with sensitivity testing around PLI scheme participation rates and BIS certification timeline assumptions.
The analysis sits within stated boundaries; outcomes outside sustained AQI deterioration patterns or PLI scheme continuity would require recalibration. Forecasts reflect documented assumptions regarding technician availability, import tariff stability, and state procurement mandate implementation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Air Humidifier Market
Household Items
Drinkware Market
Household Items
Alarm Clocks Market
Household Items
Europe Handheld Fans Market
Household Items
Moving Supplies Market
Household Items
Collapsible Water Bottle Market
Household Items
Air Purifier Market
Household Items
Cat Hair Remover Market
Household Items
Smart Faucets Market
Household Items
US Handheld Vacuum Cleaners Market
Household Items
Electric Mop Market
Household Items
Dry and Wet Wipes Market
Household Items
Dry Vacuum Cleaner Market
Household Items
Global Electronic Bidet Seats Market
Household Items
United States Smart Shower Market
Household Items
Stainless Steel Toilet Paper Dispenser Market