
 Emergency Blankets Market | 2026-2036
Emergency Blankets Market Size, Share, and Industry Trends Forecast 2026-2036
Emergency Blankets Market Intelligence
Paramedic training capacity is collapsing across rural health districts, forcing emergency medical services to stock more self-warming blankets that require minimal operator skill. SOL specializes in ultralight reflective designs that leverage proprietary metalized film layering. Adventure Medical Kits dominates the retail backpacking channel through direct-to-consumer distribution. Titan Survival anchors the military-surplus segment with heavy-duty Mylar construction rated for extreme altitudes.
An emergency blanket is a compact thermal barrier typically manufactured from vacuum-deposited aluminum on polyethylene terephthalate film, designed to reduce convective and radiant heat loss in trauma, exposure, or mass-casualty scenarios. The reflective segment leads value generation due to aerospace-grade metallization tolerances demanded by alpine rescue protocols, while the disposable category sustains volume through institutional bulk purchasing by ambulance corps and humanitarian logistics fleets. Mylar-based products occupy the premium tier in hospital procurement, whereas cotton-blend alternatives compete on tactile comfort for extended patient transport.
FDA Class I medical device exemptions govern over-the-counter emergency blanket sales in the United States, while the EU MDR imposes biocompatibility testing for products marketed to hospitals across member states. ISO 13485 certification increasingly filters supplier eligibility for European public health tenders. Stakeholders must monitor evolving thermal-resistance benchmarks from standards bodies and calibrate material investments before regulatory thresholds harden.
Market Dynamics
Rural paramedic training collapse is forcing emergency medical services toward self-warming blanket technologies that eliminate operator-skill dependencies. This structural shift toward low-touch thermal intervention is reshaping procurement specifications across ambulance corps and disaster response agencies.
Growth Catalysts
- EU Medical Device Regulation:The MDR's tightened biocompatibility testing mandates for hospital-grade emergency supplies are filtering out marginal suppliers and consolidating demand around ISO 13485-certified manufacturers.
- Alpine rescue protocols:Aerospace-grade metallization tolerances specified by mountain search-and-rescue agencies in Switzerland and Austria are elevating performance benchmarks for reflective blanket procurement.
- Federal disaster preparedness:Germany's civilian shelter operation budgets are directing sustained institutional purchasing toward reflective blanket stockpiles, creating predictable volume anchors for suppliers.
Market Restraints
- Petrochemical input volatility:Vacuum-deposited aluminum and polyethylene terephthalate film costs fluctuate with energy markets, compressing margins on Mylar-based premium products.
- Supply concentration in East Asian metallization:Vacuum deposition capacity clusters in China and South Korea, exposing European and North American assemblers to logistics disruption and tariff exposure.
- Cotton-blend tactile limitations:Extended patient transport scenarios require comfort properties that metallized films cannot replicate, capping reflective blanket penetration in inter-facility transfers.
Strategic Opportunities
- Backcountry rescue expansion:United States outdoor recreation agencies are scaling thermal blanket procurement for wilderness programs, opening institutional channels beyond traditional medical buyers.
- Dual-use military-civilian convergence:Heavy-duty Mylar constructions rated for extreme altitudes are migrating from defense surplus into commercial alpine tourism and expedition logistics.
- Direct-to-consumer channel maturation:Adventure-oriented retailers are building captive demand through educational content on hypothermia prevention, reducing reliance on institutional procurement cycles.
Industry Challenges
- ISO 13485 certification timelines:European public health tender eligibility now requires quality management system validation that extends supplier onboarding by 12-18 months.
- Metallization skill scarcity:Vacuum deposition technicians with medical-device-grade tolerances are concentrated in aerospace supply chains, creating recruitment friction for blanket manufacturers scaling capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emergency Blankets Market |
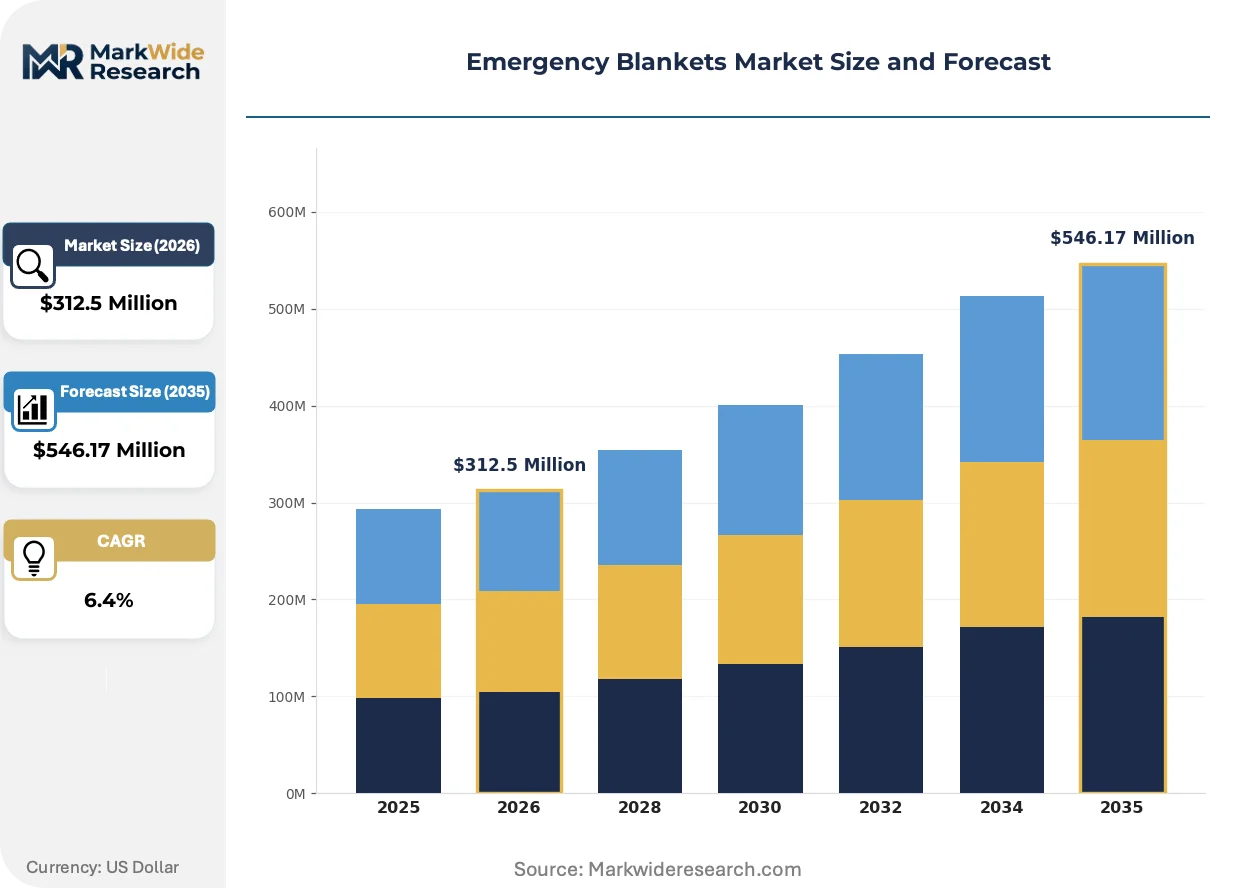
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Thermal, Reflective Material: Mylar, Polyethylene, Cotton, Foil End User: Emergency Services, Outdoor Enthusiasts, Hospitals, Disaster Relief Organizations Distribution Channel: Online Retail, Supermarkets, Direct Sales, Specialty Stores |
| Companies Covered | Titan Survival, Boen Medical, SOL (Survive Outdoors Longer), YEYETAC, Emergency Zone, Adventure Medical Kits, KEMP USA, Grabber, Swiss Safe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emergency Blankets Market Strategic Shifts & Innovations
Material science advances and regulatory harmonization pressures are compressing product lifecycles while elevating performance verification requirements. Manufacturers must now balance thermal efficiency claims against biocompatibility documentation and sustainability disclosures.
Multi-layer metalized film architectures with embedded phase-change materials are displacing single-layer reflective designs in professional rescue applications. Alpine search teams in Switzerland and Austria are adopting these constructions for extended hypothermia management. The technology is displacing conventional Mylar dominance in premium procurement tiers by enabling longer effective intervention windows without external heat sources.
The EU Medical Device Regulation's biocompatibility testing requirements for hospital-marketed emergency supplies are forcing reformulation of adhesive edges and surface coatings. Manufacturers serving European member states must now document cytotoxicity and sensitization profiles previously exempt under legacy directives. This regulatory compression is accelerating consolidation among suppliers with in-house toxicology testing capabilities.
Institutional buyers are unbundling blanket procurement from bundled trauma kit contracts, creating direct sourcing relationships with metallized film converters. Ambulance corps in Germany and Austria are negotiating volume commitments directly with material suppliers, bypassing traditional medical distributors. This disintermediation is most visible in federal and state-level disaster preparedness budgets, where procurement officers prioritize traceability and lot-control documentation over brand recognition.
Emergency Blankets Market Segmentation
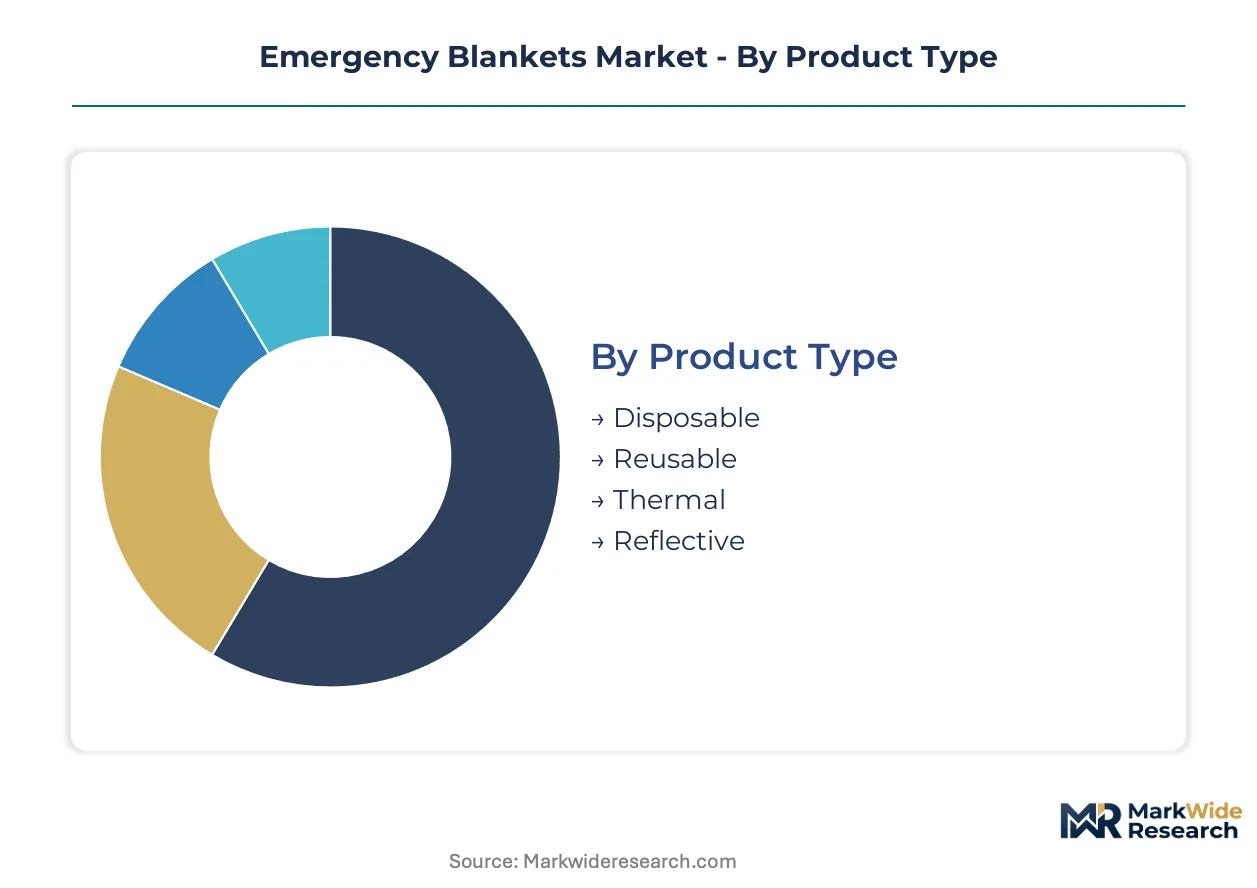
Emergency blanket procurement specifications diver sharply across institutional buyers, with FDA Class I exemptions governing US over-the-counter sales while EU MDR biocompatibility mandates filter hospital-grade suppliers. Material selection and distribution channel choices directly determine regulatory compliance pathways and margin structures for manufacturers.
Product Type:
FDA Class I medical device exemptions and EU MDR testing thresholds create divergent compliance burdens across product categories, with hospital procurement favoring validated constructions and retail channels accepting simpler designs.
- Reflective:Vacuum-deposited aluminum on polyethylene terephthalate film achieves aerospace-grade metallization tolerances demanded by alpine rescue protocols in Switzerland and Austria. Mountain search teams specify these constructions for extended hypothermia management, driving premium procurement tiers.
- Disposable:Single-use designs sustain volume through institutional bulk purchasing by ambulance corps and humanitarian logistics fleets. Germany's federal disaster preparedness budgets prioritize reflective blanket stockpiles for civilian shelter operations, anchoring predictable demand.
- Reusable:Durable constructions target extended patient transport scenarios where tactile comfort properties exceed metallized film limitations.
- Thermal:Self-warming technologies eliminate operator-skill dependencies, addressing rural paramedic training collapse across health districts.
Established volume favors Disposable; emerging adoption favors Reflective.
Material:
Cost tier stratification separates premium metallized films from commodity alternatives, with vacuum deposition capacity concentration in East Asia shaping supply security calculations for European and North American assemblers.
- Mylar:Polyethylene terephthalate film with vacuum-deposited aluminum occupies the premium tier in hospital procurement. Petrochemical input volatility compresses margins as energy markets fluctuate.
- Foil:Heavy-duty constructions rated for extreme altitudes migrate from defense surplus into commercial alpine tourism and expedition logistics, enabling dual-use military-civilian convergence.
- Polyethylene:Lower-cost substrates compete on institutional volume contracts where thermal resistance benchmarks are less stringent.
- Cotton:Blend alternatives compete on tactile comfort for extended patient transport, capping reflective blanket penetration in inter-facility transfers.
Mylar commands margin concentration; Foil is climbing the fastest.
End User:
Customer type determines performance verification requirements, with professional rescue applications demanding ISO 13485 certification and consumer segments prioritizing portability and education.
- Emergency Services:Ambulance corps and disaster response agencies specify self-warming technologies that reduce operator-skill dependencies. ISO 13485 certification timelines extend supplier onboarding by 12-18 months for European public health tenders.
- Hospitals:EU MDR biocompatibility testing mandates for hospital-grade emergency supplies filter out marginal suppliers, consolidating demand around certified manufacturers with in-house toxicology capabilities.
- Outdoor Enthusiasts:Adventure-oriented retailers build captive demand through educational content on hypothermia prevention, reducing reliance on institutional procurement cycles.
- Disaster Relief Organizations:Humanitarian logistics fleets drive disposable category volume through bulk purchasing programs.
Emergency Services anchor procurement scale; Outdoor Enthusiasts show steepest expansion trajectory.
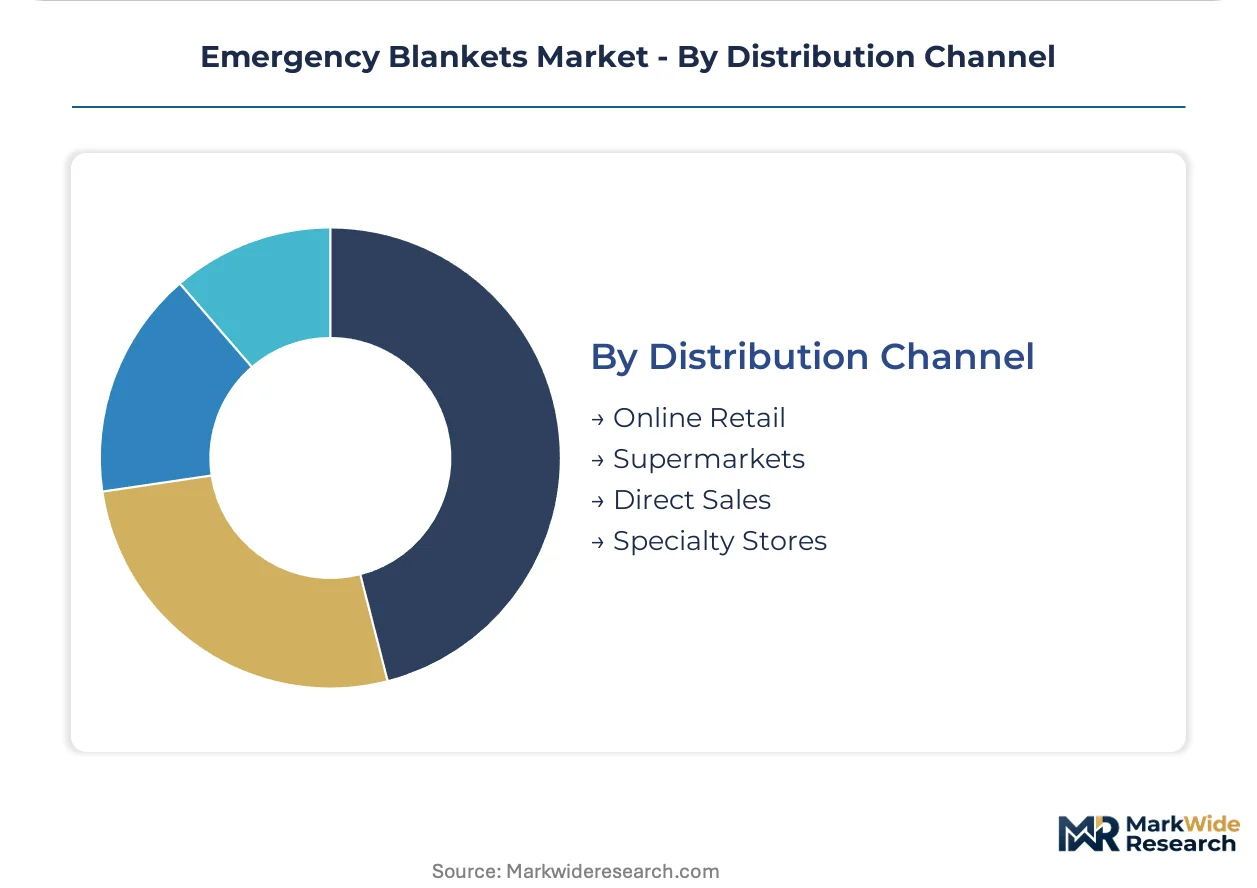
Distribution Channel:
Supply concentration patterns favor direct relationships with metallized film converters over traditional medical distributors, particularly in federal and state-level disaster preparedness budgets.
- Direct Sales:Institutional buyers unbundle blanket procurement from bundled trauma kit contracts, negotiating volume commitments directly with material suppliers. German and Austrian ambulance corps prioritize traceability and lot-control documentation.
- Online Retail:Adventure Medical Kits dominates the retail backpacking channel through direct-to-consumer distribution, leveraging educational content to build captive demand.
- Specialty Stores:Outdoor recreation agencies in the United States expand procurement through wilderness program channels beyond traditional medical buyers.
- Supermarkets:Mass retail access for over-the-counter emergency blanket sales governed by FDA Class I exemptions.
Direct Sales capture institutional value; Online Retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Class I exemptions govern over-the-counter emergency blanket sales in the United States, while EU MDR biocompatibility mandates reshape procurement across member states. Vacuum deposition capacity clusters in East Asia, exposing European and North American assemblers to logistics disruption.
United States
Outdoor recreation agencies expand thermal blanket procurement for backcountry rescue programs across federal wilderness areas. FDA Class I medical device exemptions streamline over-the-counter distribution channels. Colorado and Utah anchor demand concentration, where mountain search teams specify aerospace-grade metallization tolerances for alpine operations.
Germany
Federal disaster preparedness budgets prioritize reflective blanket stockpiles for civilian shelter operations, creating predictable institutional volume. EU MDR biocompatibility testing mandates filter hospital-grade suppliers, consolidating demand around ISO 13485-certified manufacturers. Bavaria and North Rhine-Westphalia concentrate procurement coordination for federal stockpile programs.
Switzerland
Mountain search-and-rescue agencies specify aerospace-grade metallization tolerances that elevate performance benchmarks for reflective blanket procurement. Swissmedic hospital-grade device standards exceed baseline EU requirements. Alpine cantons including Valais and Graubünden drive specification tightening for extended hypothermia management protocols.
China
Vacuum deposition capacity for metallized films concentrates in coastal manufacturing clusters, supplying global assemblers with polyethylene terephthalate substrates. NMPA medical device registration requirements apply to hospital-grade exports. Jiangsu and Zhejiang provinces host the dominant share of metallization technicians with medical-device-grade tolerances.
Austria
Alpine rescue protocols from Tyrol and Salzburg regions influence reflective blanket specifications across Central European procurement networks. EU MDR implementation timelines extend supplier onboarding for public health tenders. Vienna anchors institutional purchasing coordination for federal disaster response stockpiles.
Emergency Blankets Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with vacuum deposition capabilities and ISO 13485 certification creating separation between contract manufacturers and brand owners. The market structures around material control, regulatory documentation, and channel access rather than scale economies alone. Three archetypes dominate: metallized film converters with captive aerospace expertise, medical device assemblers with toxicology testing infrastructure, and outdoor brands with direct-to-consumer distribution. Competitive moves concentrate on backward integration into vacuum deposition capacity and strategic partnerships with alpine rescue agencies for specification influence.
Within the outdoor-specialist tier, SOL and Adventure Medical Kits exemplify divergent channel strategies, while Titan Survival occupies a position bridging military-surplus heritage and commercial alpine applications. SOL represents the ultralight design archetype leveraging proprietary metalized film layering. Adventure Medical Kits anchors direct-to-consumer educational marketing approaches. Titan Survival sits within the heavy-duty construction segment originally developed for defense applications. These three companies illustrate how brand positioning around use-case specificity—backpacking, institutional procurement, extreme altitude—shapes competitive differentiation more than manufacturing scale.
| Leading Market Players |
|---|
| Titan Survival |
| Boen Medical |
| SOL (Survive Outdoors Longer) |
| YEYETAC |
| Emergency Zone |
| Adventure Medical Kits |
| KEMP USA |
| Grabber |
| Swiss Safe |
| Others |
Cost & Logistics Intelligence
ISO 13485 certification gates supplier eligibility for European public health tenders while simultaneously stratifying price tiers, as hospitals pay premiums for validated quality management systems that smaller converters cannot document. This regulatory threshold compresses margins for uncertified assemblers while concentrating pricing power among vacuum deposition specialists with in-house metallization capabilities.
Pricing Analysis
Long-term offtake contracts dominate institutional procurement from German federal disaster stockpiles and Austrian alpine rescue agencies, insulating certified manufacturers from spot-market volatility in petrochemical inputs. Price differentiation rests on aerospace-grade metallization tolerances versus standard reflective grades, with ISO 13485-certified suppliers commanding sustained premiums. Cost compression intensifies in the disposable tier as polyethylene substrate costs fluctuate with energy markets. Ambulance corps exhibit highest price sensitivity, while mountain search teams prioritize performance benchmarks over unit economics.
Supply Chain Analysis
Vacuum deposition technician scarcity in Jiangsu and Zhejiang provinces creates a chokepoint that constrains global metallized film output for medical-device-grade applications. Raw material dependencies center on polyethylene terephthalate resin, aluminum feedstock, and phase-change material substrates. Single-source vulnerability concentrates in East Asian metallization capacity, exposing European and North American assemblers to logistics disruption. Distribution runs through direct relationships with film converters, bypassing traditional medical distributors in federal procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities expand faster than hardware sales as alpine rescue agencies demand extended hypothermia management training bundled with phase-change blanket deployments. Recurring revenue from certification maintenance and lot-traceability documentation outpaces unit shipment growth in institutional channels.
For Market Incumbents: Consolidate backward integration into vacuum deposition capacity before metallization technician scarcity worsens across aerospace supply chains. Defend position by locking multi-year offtake agreements with German federal stockpile programs before ISO 13485 onboarding timelines extend further. Prioritize in-house toxicology testing infrastructure to capture EU MDR biocompatibility documentation premiums. For New Entrants and Emerging Players: Anchor in the United States outdoor recreation agency channel, where wilderness program procurement operates outside hospital-grade certification requirements. Target backcountry rescue expansion with ultralight designs that compete on educational content rather than metallization tolerances. Pursue direct-to-consumer distribution partnerships with adventure retailers building captive demand through hypothermia prevention curricula. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across phase-change material integration as multi-layer architectures displace single-layer Mylar dominance. Long-term viability favors converters with captive aerospace metallization expertise and existing ISO 13485 footprints. Watch for inflection signals in Swissmedic specification tightening that would accelerate premium-tier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vacuum Deposition | Captive metallization capacity insulates margins from East Asian supply concentration and technician scarcity. |
| ISO 13485 Certification Investment | Quality management validation unlocks European hospital tenders and federal disaster preparedness contracts in Germany. |
| Phase-Change Material Partnership | Multi-layer architectures with embedded thermal regulation capture alpine rescue premium tiers from conventional Mylar. |
| Direct-to-Consumer Educational Launch | Adventure retailer content partnerships build brand equity and reduce reliance on institutional procurement cycles. |
| Dual-Use Military-Civilian Repositioning | Defense-surplus heavy-duty constructions migrate into commercial expedition logistics, opening volume beyond medical channels. |
Research Approach
The analysis maps reflective, disposable, reusable, and thermal blanket sub-sectors, each validated through procurement officers at German ambulance corps, alpine rescue coordinators in Switzerland, and metallized film converters in China. Primary interviews with hospital purchasing committees, outdoor recreation agency directors, and vacuum deposition technicians combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, and customs trade records for polyethylene terephthalate film imports. Bottom-up shipment estimates from material suppliers triangulated against top-down federal budget allocations for disaster preparedness stockpiles.
Consistency checks validated volume and value outputs against external benchmarks including hospital procurement database trends, GPO contract awards, and alpine rescue equipment expenditure reports across the analysis window. The analytical framework modeled product type, material substrate, end-user segment, and distribution channel dimensions. CAGRs derived from curve-fitting historical institutional purchasing patterns against projected federal shelter operation budget trajectories and backcountry rescue program expansion timelines.
Material uncertainties — petrochemical input volatility, EU MDR enforcement variance across member states, and metallization capacity expansion delays — sit outside the modeled envelope. Forecasts reflect assumptions about sustained German federal stockpiling commitments and stable aerospace-grade tolerance specifications from Swiss alpine agencies. Practitioners should keep alternative scenarios live as REACH chemical restriction proposals and dual-carbon policy implementation timelines in China evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emergency and Disaster Management
North America Emergency Shower and Eye Wash Station Market
Emergency and Disaster Management
EHS Market
Emergency and Disaster Management
Global Emergency Medical Service (EMS) Products Market
Emergency and Disaster Management
Emergency and Disaster Response Market
Emergency and Disaster Management
Survival Tools Market
Emergency and Disaster Management
Outdoor Emergency Safety Shower Market
Emergency and Disaster Management
North America Homeland Security and Emergency Management Market
Emergency and Disaster Management
Earthquake Early Warning System Market
Emergency and Disaster Management
Asia-Pacific Process Safety Services Market
Emergency and Disaster Management
Emergency Shower and Eyewash Station Market
Emergency and Disaster Management
Emergency Escape Breathing Device Market
Emergency and Disaster Management
Crisis Emergency and Incident Management Platform Market
Emergency and Disaster Management
Disaster Restoration Services Market
Emergency and Disaster Management
Free Fall Lifeboats Market
Emergency and Disaster Management
Intelligent Evacuation System Market
Emergency and Disaster Management
Cyber Crisis Management Market