
 Black Sapote Market | 2026-2036
Black Sapote Market Size, Share, and Industry Trends Forecast 2026-2036
Black Sapote Market Analysis
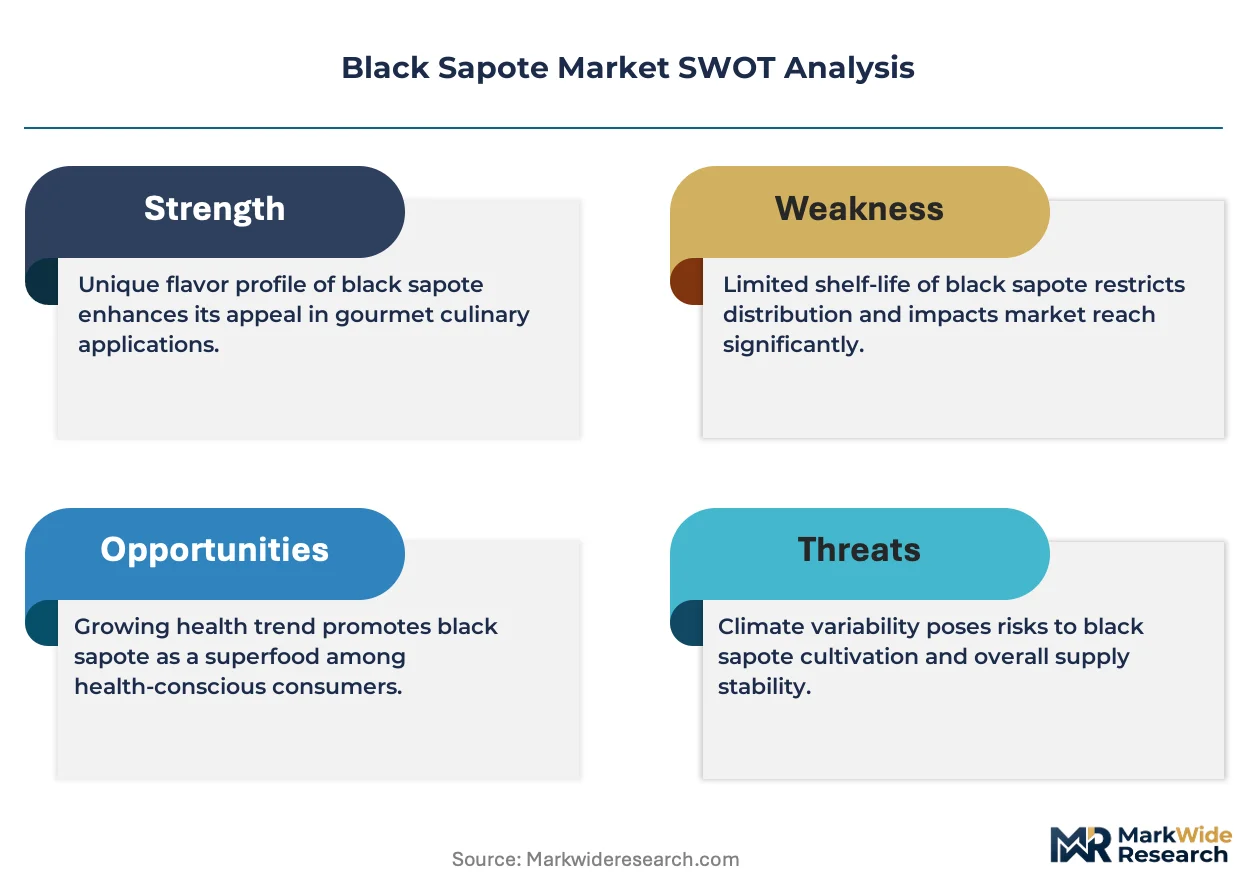
Organic certification under USDA NOP standards is rotating supplier eligibility across the Black Sapote Market, favoring operations with documented soil management and cold-chain integrity. Pacific Produce Trading Pty Ltd. leverages its Queensland orchards to sustain year-round export capacity into Asian premium channels. Tropical Foods, LLC anchors North American distribution through controlled ripening facilities in Florida. Paradise Fruits Solutions GmbH competes on IQF processing technology for European industrial buyers.
Black sapote (Diospyros nigra) is a tropical evergreen species producing berry-type fruit with 20-30% dry matter pulp content, dark brown custard-like interior, and climacteric respiratory behavior requiring ethylene-managed postharvest handling; its commercial utility centers on fresh dessert applications, dairy analog bases, and natural colorant substitutes in confectionery. Fresh whole fruit occupies the dominant value position in retail and foodservice channels, while puree and frozen pulp segments carry expanding margin pools as smoothie chains and plant-based dessert manufacturers scale procurement. Powder and extract forms remain nascent but attract functional food R&D investment due to polyphenol retention in spray-dried formats.
FDA produce safety rules under FSMA, USDA AMS organic integrity requirements, and Mexico's SENASICA phytosanitary export protocols collectively determine market access eligibility and lot-by-lot documentation burdens for cross-border shipments. SENASICA's HLB disease monitoring in Veracruz growing zones directly impacts planting permissions and export certificate issuance velocity. Stakeholders must monitor evolving equivalence agreements between Mexican federal agricultural authorities and destination country regulators to preempt supply disruptions.
Market Dynamics
USDA organic certification traceability requirements are rotating supplier eligibility across the Black Sapote Market, favoring operations with documented soil management and cold-chain integrity while disqualifying legacy handlers lacking lot-level documentation systems.
Growth Catalysts
- USDA NOP Organic Integrity Requirements:Tightened traceability obligations for tropical fruit imports into the United States are filtering out non-compliant handlers and concentrating volume among certified operations with full chain-of-custody documentation.
- Gourmet Ice Cream Manufacturing:Premium dessert producers in Mexico are expanding procurement of fresh black sapote pulp for custard-base applications, creating pull-through demand for controlled-ripening infrastructure.
- Veracruz Cultivation Concentration:Demand gravity is concentrating in Mexico's Veracruz state growing zones and adjacent processing corridors, enabling cluster efficiencies in harvesting and postharvest handling.
Market Restraints
- Perishability and Cold-Chain Cost Structure:Black sapote's climacteric respiratory behavior demands ethylene-managed postharvest handling, imposing capital-intensive controlled-atmosphere infrastructure on exporters.
- Phytosanitary Certificate Velocity:SENASICA's HLB disease monitoring protocols in Veracruz growing zones directly constrain export certificate issuance timelines, creating lot-release bottlenecks.
- Substitution Threat from Frozen Mango:IQF mango pulp competes for smoothie-chain and plant-based dessert formulations, offering comparable color profiles with established supply reliability.
Strategic Opportunities
- Underpenetrated European Industrial Channel:IQF black sapote pulp remains nascent in European bakery and confectionery applications, presenting first-mover positioning for processors with spray-dried format capabilities.
- Functional Food R&D Convergence:Polyphenol retention in spray-dried black sapote powder is attracting investment from nutraceutical formulators seeking natural colorant substitutes with antioxidant positioning.
- Direct-to-Processor Distribution Innovation:Bypassing traditional wholesale produce channels through contracted supply agreements with plant-based dessert manufacturers is compressing margin capture for integrated growers.
Industry Challenges
- FSMA Produce Safety Rule Compliance Timeline:FDA's preventive controls and agricultural water testing requirements impose documentation burdens that smaller Mexican growers struggle to operationalize without third-party audit support.
- Controlled Ripening Technical Skill Gap:Ethylene management expertise for climacteric fruit remains scarce in emerging cultivation zones, limiting expansion beyond established Veracruz operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Black Sapote Market |
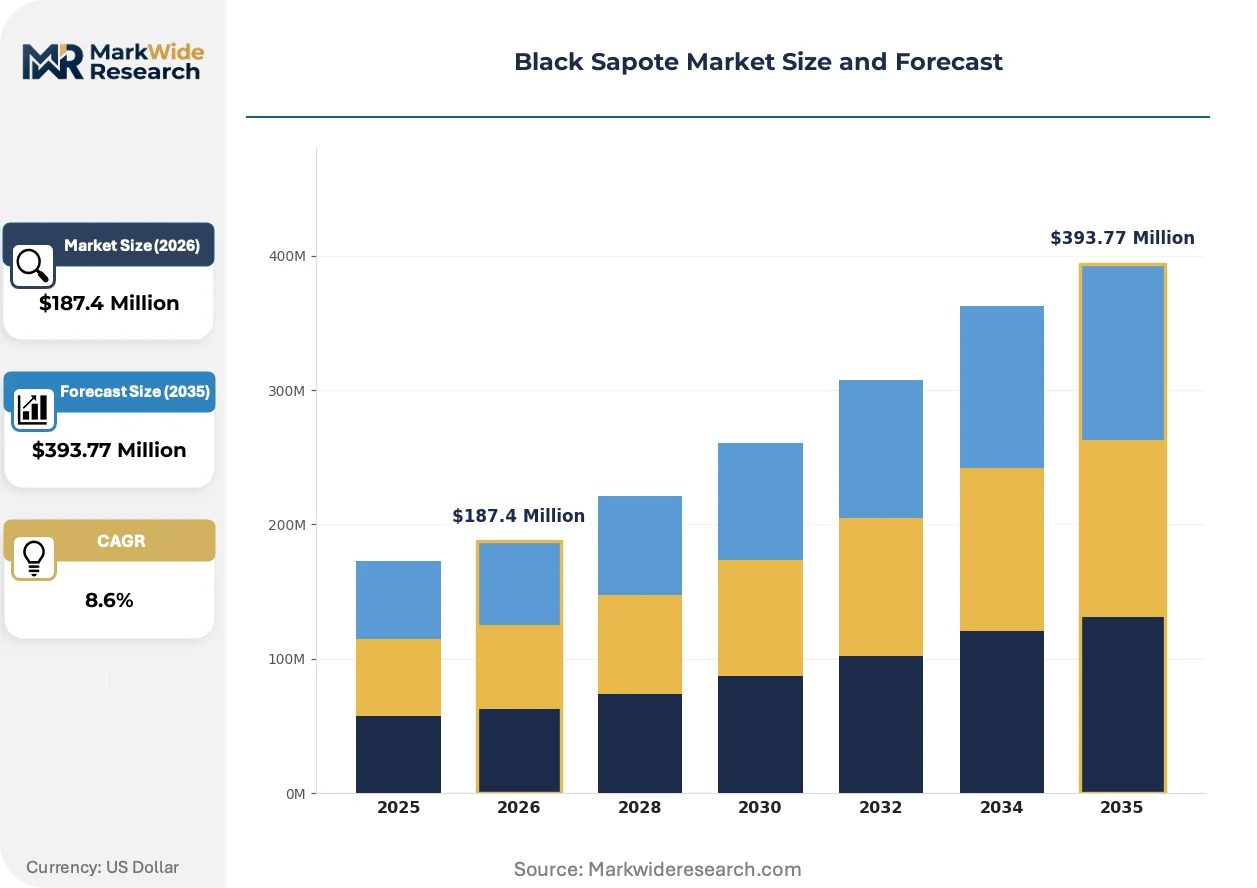
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh, Dried, Frozen, Puree Distribution Channel: Online, Supermarkets, Specialty Stores, Farmers' Markets End User: Retail Consumers, Restaurants, Food Manufacturers, Juice Producers Form: Whole Fruit, Slices, Powder, Extract |
| Companies Covered | Pacific Produce Trading Pty Ltd., Tropical Foods, LLC, Exotic Fruits USA, Jining Green Land International Trading Co., Ltd., Ningxia Yisa Food Development Co., Ltd., Pitahaya Foods, Paradise Fruits Solutions GmbH, KGH Exports, Moonlit Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Black Sapote Market Emerging Trajectories
Postharvest technology adoption and regulatory documentation requirements are fragmenting competitive position in the Black Sapote Market, separating capitalized operators from legacy handlers.
Controlled-atmosphere storage with ethylene scrubbing and real-time respiration monitoring is fragmenting supplier tiers in the fresh whole fruit segment. Gourmet retailers and high-end foodservice operators are prioritizing suppliers with verified cold-chain telemetry. This technology is compressing margin pools among handlers lacking capital to upgrade postharvest infrastructure.
USDA's Strengthening Organic Enforcement final rule is tightening supplier verification and import certificate requirements for tropical fruit entering the United States. The regulation is disqualifying uncertified handlers from organic-labeled supply chains. Fresh pulp exporters to North American premium channels are most affected, with compliant operators capturing displaced volume.
Smoothie chains and plant-based dessert manufacturers are consolidating procurement around frozen pulp contracts with specified brix and viscosity parameters. This specification-driven purchasing is displacing spot-market buying of whole fruit for in-house processing. The shift is most visible in Florida's controlled-ripening corridor, where processors are installing puree lines to capture downstream margin.
Black Sapote Market Segmentation
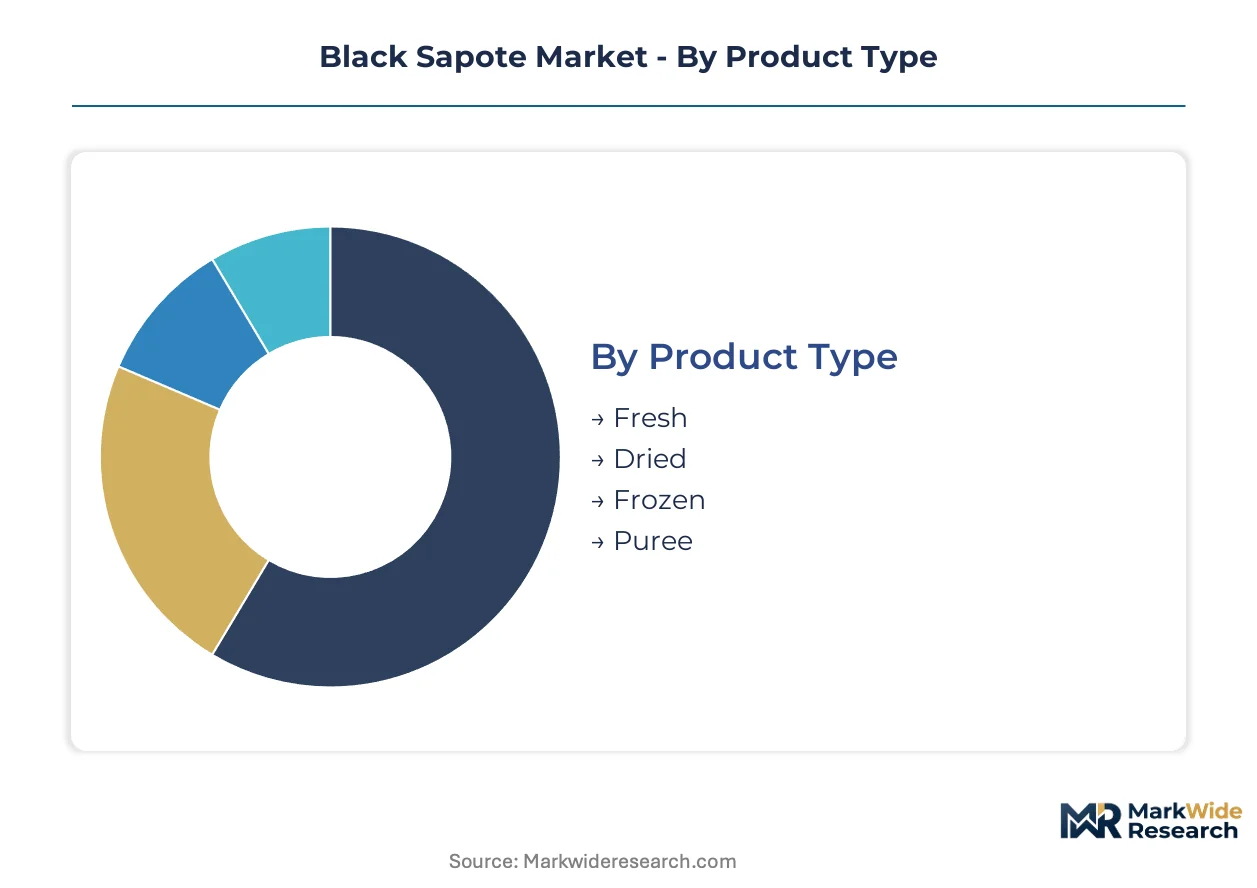
Black sapote segmentation reveals divergent margin structures between perishable fresh channels and value-added processed formats. Each category reflects distinct cold-chain investments, certification burdens, and customer procurement behaviors that reshape supplier positioning.
Product Type:
Fresh black sapote dominates domestic Mexican consumption and nearby export corridors, while frozen and dried formats capture transoceanic demand with extended shelf stability.
- Fresh:Whole fruit with climacteric ripening requirements commands premium pricing in gourmet retail and immediate-consumption foodservice. Veracruz state cultivation zones supply the bulk of certified organic volume into US premium channels under tightened USDA traceability protocols.
- Frozen:IQF pulp segments attract industrial procurement from smoothie chains and plant-based dessert manufacturers seeking specified brix and viscosity parameters. Queensland orchards sustain year-round export capacity into Asian markets through Pacific Produce Trading's controlled-ripening infrastructure.
- Dried:Dehydrated slices and chunks serve snack-food applications with reduced cold-chain dependency.
- Puree:Aseptic and frozen puree formats target dairy analog bases and confectionery colorant substitution.
Fresh commands the established base. The steepest expansion runs through Frozen.
Distribution Channel:
Channel selection determines certification exposure, with direct-to-processor contracts bypassing traditional wholesale markups while imposing lot-level documentation burdens.
- Supermarkets:Chain retail requires full USDA organic chain-of-custody documentation and real-time cold-chain telemetry for climacteric fruit quality verification. Florida's controlled-ripening corridor anchors North American supermarket replenishment through Tropical Foods' distribution network.
- Specialty Stores:Gourmet retailers prioritize verified postharvest handling with ethylene scrubbing and respiration monitoring, filtering supplier tiers toward capitalized operators.
- Online:Direct-to-consumer platforms expose perishability risks through last-mile delivery uncertainty.
- Farmers' Markets:Local vending escapes federal import certification requirements but constrains volume scale.
Supermarkets absorb the volume concentration. Specialty stores capture the margin expansion.
End User:
End-user procurement patterns split between specification-driven industrial contracts and spot-market fresh purchasing with diverging documentation intensity.
- Food Manufacturers:Plant-based dessert and confectionery formulators consolidate procurement around frozen pulp contracts with defined polyphenol retention and color stability metrics. Paradise Fruits Solutions' IQF processing technology targets this industrial segment across European bakery applications.
- Restaurants:High-end foodservice operators demand fresh whole fruit with verified ripening-stage management for custard-base dessert applications.
- Retail Consumers:Household purchasing concentrates on fresh whole fruit for immediate consumption or home processing.
- Juice Producers:Beverage manufacturers extract pulp for natural colorant and flavoring applications.
Food Manufacturers anchor the procurement consolidation. Restaurants sustain the freshness premium.
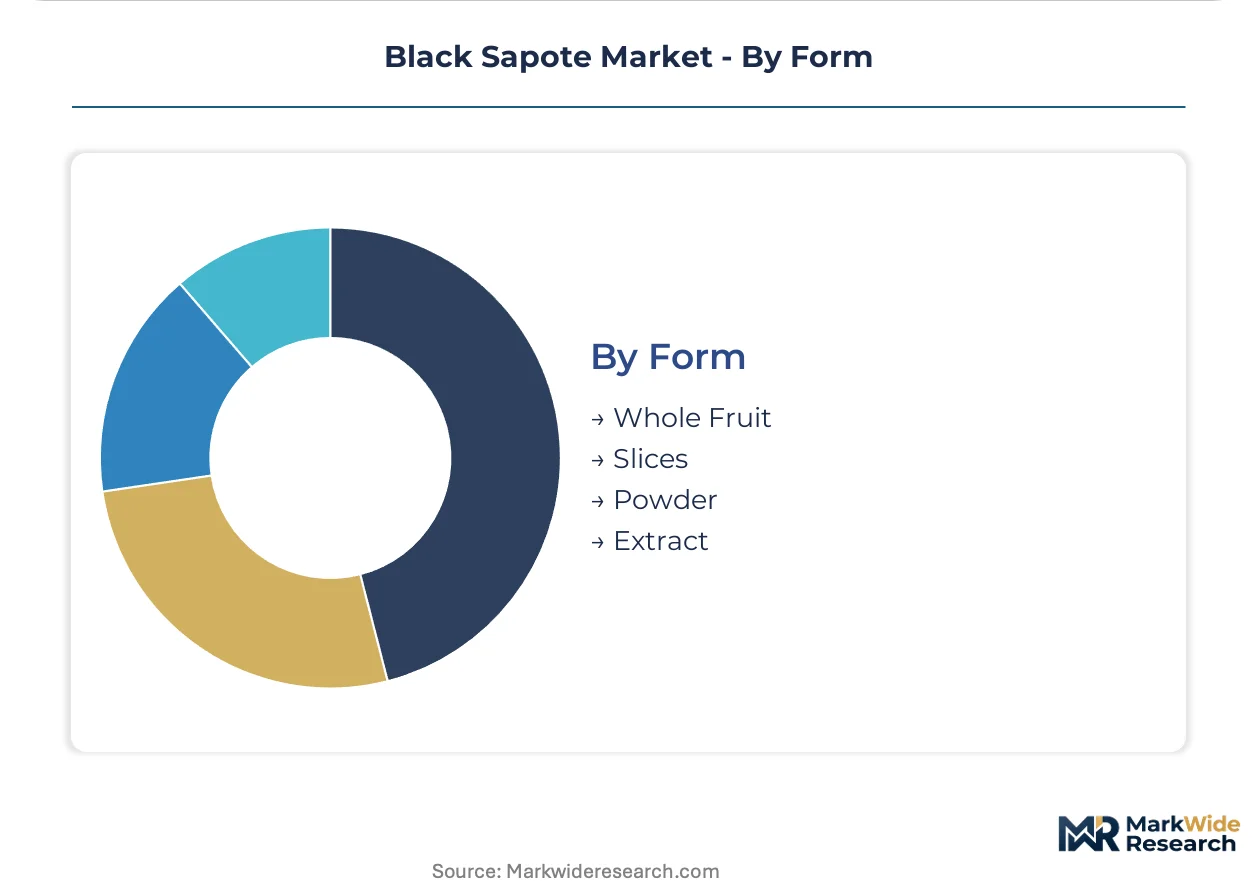
Form:
Form selection reflects downstream processing economics, with whole fruit requiring customer-side ripening expertise versus ready-to-use processed alternatives.
- Whole Fruit:Unprocessed units retain maximum pulp integrity but impose ethylene-managed postharvest handling costs on receivers. SENASICA's HLB disease monitoring in Veracruz directly constrains export certificate issuance timelines for whole fruit shipments.
- Powder:Spray-dried formats attract functional food R&D investment for polyphenol retention in nutraceutical applications with extended ambient stability.
- Slices:Fresh-cut segments serve immediate foodservice preparation with reduced labor burden.
- Extract:Concentrated colorant and antioxidant fractions target pharmaceutical and cosmetic formulators.
Whole Fruit holds the volume foundation. Powder claims the innovation trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Veracruz anchors Mexico's export infrastructure for climacteric tropical fruit, connecting Veracruz state cultivation zones to US Gulf Coast and Atlantic seaboard distribution hubs through dedicated reefer container service.
Mexico
SENASICA's HLB disease monitoring protocols in Veracruz growing zones constrain export certificate issuance timelines for fresh whole fruit shipments. USDA organic certification traceability requirements filter supplier eligibility toward operations with documented soil management systems. The Veracruz-Coatepec corridor concentrates controlled-ripening infrastructure serving North American premium channels.
United States
Florida's controlled-ripening facilities anchor North American distribution through ethylene-managed postharvest handling systems. FDA's FSMA produce safety rules impose agricultural water testing and preventive controls documentation burdens on Mexican import suppliers. Miami-Dade County logistics clusters coordinate cross-border cold-chain integrity for retail and foodservice replenishment.
Australia
Queensland orchards sustain year-round export capacity into Asian premium channels through Pacific Produce Trading's integrated supply infrastructure. The country's national agricultural regulator enforces biosecurity protocols for exotic fruit exports that exceed baseline international phytosanitary standards. Bundaberg-Gympie growing regions supply counter-seasonal volume to Northern Hemisphere markets.
Germany
IQF processing technology for European industrial buyers concentrates in Paradise Fruits Solutions' operations serving bakery and confectionery applications. EU Green Deal sustainability reporting requirements pressure supply chain transparency for tropical fruit ingredient sourcing. Hamburg-Bremen port complexes handle bulk frozen pulp imports for redistribution across continental manufacturing clusters.
China
Jining and Ningxia-based trading companies source processed black sapote formats for domestic functional food R&D investment in polyphenol retention applications. The country's national food safety regulator enforces GB standards for imported tropical fruit products with escalating documentation intensity. Shandong Province processing corridors attract spray-dried format manufacturing for nutraceutical formulators.
Black Sapote Market Vendor Landscape
Listed leaders compete with private specialists across certification and cold-chain infrastructure dimensions, fragmenting competitive position between capitalized operators and legacy handlers lacking lot-level documentation systems. Three archetypes dominate: integrated growers with controlled-ripening assets, IQF processors serving industrial formulation contracts, and trading specialists arbitraging seasonal supply gaps. Geographic expansion and backward integration into captive orchard supply represent the dominant competitive moves.
Among Asia-Pacific-based trading specialists, Jining Green Land International Trading Co., Ltd. and Ningxia Yisa Food Development Co., Ltd. occupy positions within the processed format export tier, while Pacific Produce Trading Pty Ltd. exemplifies the integrated grower-processor archetype with Queensland orchard assets and year-round export capacity. These entities represent the spectrum from pure trading to vertically controlled supply.
| Leading Market Players |
|---|
| Pacific Produce Trading Pty Ltd. |
| Tropical Foods, LLC |
| Exotic Fruits USA |
| Jining Green Land International Trading Co., Ltd. |
| Ningxia Yisa Food Development Co., Ltd. |
| Pitahaya Foods |
| Paradise Fruits Solutions GmbH |
| KGH Exports |
| Moonlit Ltd. |
| Others |
Supply Flow & Price Mechanics
IQF mango pulp substitution for smoothie-chain formulations is compressing black sapote pricing power in frozen pulp tiers while simultaneously redirecting procurement gravity toward Veracruz state cultivation zones with certified organic infrastructure. This displacement dynamic rewards handlers with documented cold-chain integrity and disqualifies legacy suppliers lacking lot-level traceability systems.
Pricing Analysis
Certification level under USDA NOP standards creates the primary spread between premium organic and conventional handling tiers in black sapote procurement. Contract-based long-term offtake agreements dominate industrial volume, with price differentiation resting on organic chain-of-custody documentation and real-time cold-chain telemetry verification. Cost compression in conventional fresh whole fruit segments is intensifying because SENASICA's HLB disease monitoring delays export certificate issuance and extends inventory carrying costs. Food manufacturers with specification-driven frozen pulp contracts exhibit the lowest price sensitivity, while spot-market buyers of fresh fruit for in-house processing face acute margin pressure.
Supply Chain Analysis
The Port of Veracruz chokepoint underwrites North American replenishment timelines for climacteric tropical fruit entering through Gulf Coast distribution hubs. Geographic supply concentration centers on Mexico, Australia, and China, with raw material dependencies spanning ethylene-managed postharvest infrastructure, controlled-atmosphere storage systems, and phytosanitary-certified propagation stock. Single-source vulnerability in Veracruz growing zones feeds from SENASICA's concentrated export certificate authority. Distribution runs through integrated grower-processor networks with captive ripening facilities rather than traditional wholesale produce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Black sapote procurement is approaching a platform-economics inflection as smoothie chains and plant-based dessert manufacturers consolidate around frozen pulp contracts with embedded quality specifications, creating interoperability standards that favor integrated suppliers over fragmented handlers.
For Market Incumbents: Secure backward integration into captive orchard supply in Queensland or Veracruz to defend margin capture against trading specialists arbitraging seasonal gaps. Invest in spray-dried format capabilities to capture functional food R&D demand from nutraceutical formulators seeking polyphenol retention. Priority lever: controlled-atmosphere infrastructure with real-time respiration monitoring to maintain gourmet retailer and high-end foodservice relationships. For New Entrants and Emerging Players: Lead with IQF processing technology targeting European industrial bakery and confectionery applications where black sapote pulp remains underpenetrated relative to established tropical alternatives. The most penetrable segment is direct-to-processor distribution bypassing wholesale markups through contracted supply agreements with plant-based dessert manufacturers. Go-to-market angle: specified brix and viscosity parameters with verified organic chain-of-custody documentation. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated grower-processor archetypes with controlled-ripening assets and certification infrastructure over pure trading specialists. Long-term viability across a 5-10 year window rests on regulatory compliance capabilities rather than commodity arbitrage. Acquisition target archetype: mid-scale operators in Veracruz or Queensland with documented soil management systems and cold-chain telemetry. Signal to watch: equivalence agreement velocity between Mexican federal agricultural authorities and destination country regulators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Orchard Supply | Queensland and Veracruz orchard assets secure year-round export capacity against seasonal trading volatility. |
| IQF Processing Technology Deployment | Paradise Fruits Solutions' European installation demonstrates industrial buyer pull-through for specified pulp parameters. |
| USDA Organic Certification Investment | Strengthening Organic Enforcement final rule disqualifies uncertified handlers from premium North American channels. |
| Direct-to-Processor Distribution Contracts | Smoothie chain consolidation around frozen pulp specifications compresses traditional wholesale margin capture. |
| Spray-Dried Format Capability Expansion | Polyphenol retention in dehydrated formats attracts functional food R&D investment from nutraceutical formulators. |
Methodological Framework
Initial hypotheses were tested against primary input from orchard operations managers, controlled-ripening facility engineers, frozen pulp procurement directors at plant-based dessert manufacturers, and regulatory compliance officers at tropical fruit importers, and refined through secondary validation against FDA FSMA produce safety rule documentation, USDA AMS organic integrity requirements, SENASICA phytosanitary export protocols, and customs trade data for tropical fruit categories. Bottom-up volume estimates from cultivation zone interviews were triangulated against top-down market sizing from import certification records.
Variance decomposition across product type, distribution channel, end user, and form dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate modeling calibrated to procurement pattern shifts in frozen pulp contracts. Industry-specific forecast inputs included SENASICA export certificate issuance velocity and equivalence agreement negotiation status between Mexican federal agricultural authorities and destination country regulators.
Forecasts assume regulatory continuity in USDA NOP organic certification requirements and FDA FSMA produce safety enforcement; material policy shifts would require re-modeling around altered documentation burdens or import eligibility criteria. Specific risk factors encompass HLB disease monitoring protocol intensification in Veracruz, substitution acceleration from IQF mango pulp, and cold-chain infrastructure investment shortfalls in emerging cultivation zones. Practitioners should keep alternative scenarios live as equivalence agreement negotiations and organic integrity rule implementation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Cage Free Eggs Market
Agriculture and Agri Products
Spain Alfalfa Hay Market
Agriculture and Agri Products
Japan Floriculture Market
Agriculture and Agri Products
Philippines Feed Industry Market
Agriculture and Agri Products
Honeysuckle Market
Agriculture and Agri Products
France Animal Protein Market
Agriculture and Agri Products
Livestock and Meat Market
Agriculture and Agri Products
Organic Starter-Grower Chicken Feed Market
Agriculture and Agri Products
US Greenhouse Horticulture Market
Agriculture and Agri Products
Organic Soybean Market
Agriculture and Agri Products
United Kingdom Animal Protein Market
Agriculture and Agri Products
Colombia Floriculture Market
Agriculture and Agri Products
Fermented Soybean Meal Protein for Animal Feed Market
Agriculture and Agri Products
Africa Orange Market
Agriculture and Agri Products
Kenya Floriculture Market
Agriculture and Agri Products
France Compound Feed Market