
 Chaga Mushroom Market | 2026-2036
Chaga Mushroom Market Size, Share, and Industry Trends Forecast 2026-2036
Chaga Mushroom Market Outlook
Siberian wild harvest operations is decoupling from Canadian cultivated supply as climate volatility disrupts boreal forest foraging corridors. Baikal Herbs Ltd. leverages its Lake Baikal sourcing network to secure raw material traceability. Fungi Perfecti LLC sustains mycelium cultivation R&D programs that reduce pressure on wild stocks. Four Sigmatic dominates ready-to-drink formulation, occupying premium shelf positions in North American natural retail channels.
Chaga mushroom denotes Inonotus obliquus, a parasitic fungus growing primarily on birch trees in cold climates, containing bioactive compounds including betulinic acid, polysaccharides, and melanin with documented antioxidant properties. The organism requires sustained subarctic temperatures for optimal metabolite accumulation, making geographic sourcing a critical quality determinant. Powder formats anchor volume shipments through bulk ingredient trade, while extract segments command margin concentration due to standardized polysaccharide content and beverage-ready solubility. Capsule applications compete on convenience positioning within nutraceutical portfolios, though tea formats retain cultural stickiness in East Asian consumer bases.
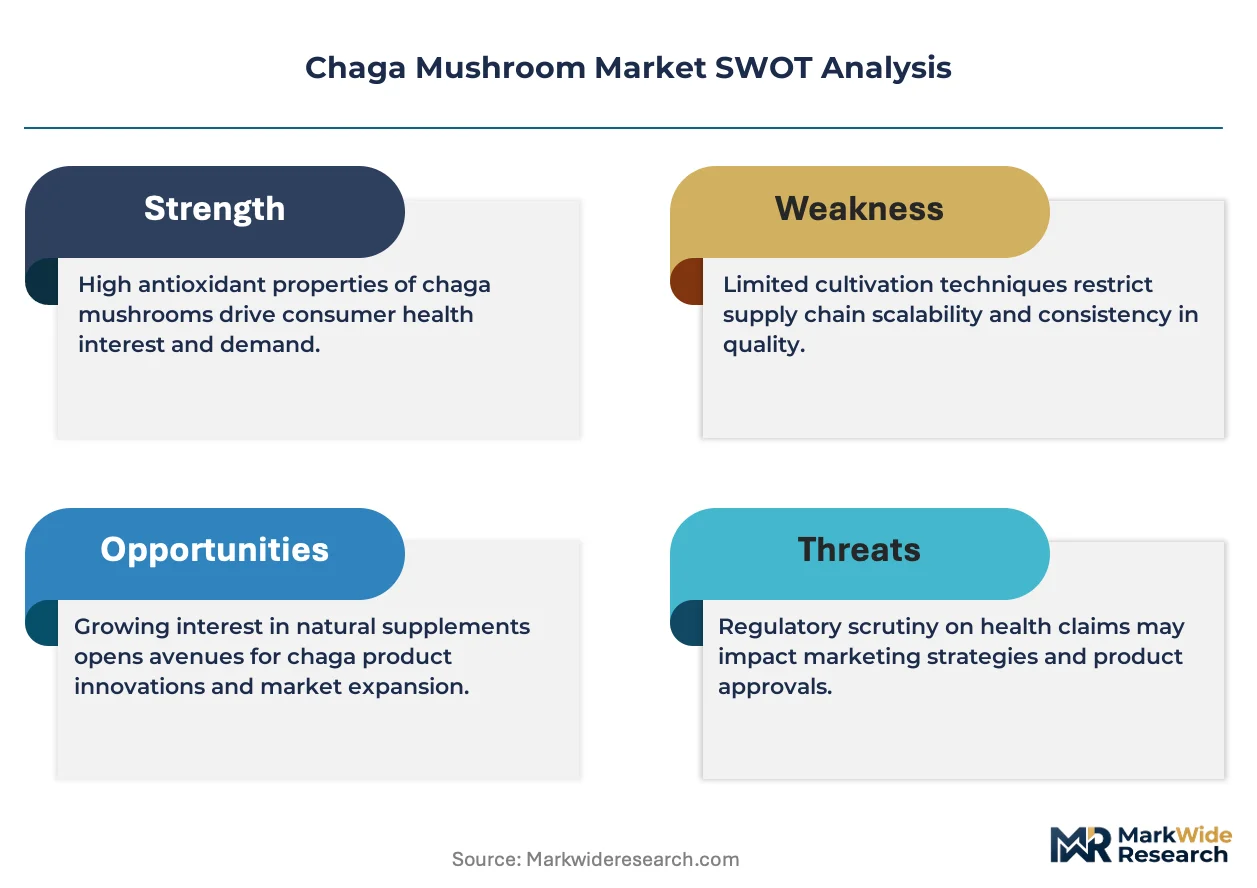
FDA New Dietary Ingredient notifications govern chaga extract entry into US supplement formulations, while Health Canada's Natural and Non-prescription Health Products Directorate imposes distinct quality specifications on Canadian-labeled products. EFSA novel food assessments create additional compliance layers for European market access, particularly for concentrated extracts exceeding traditional use thresholds. Stakeholders must monitor evolving adaptogen classification debates across jurisdictions, as regulatory reclassification would reshape labeling requirements and channel eligibility.
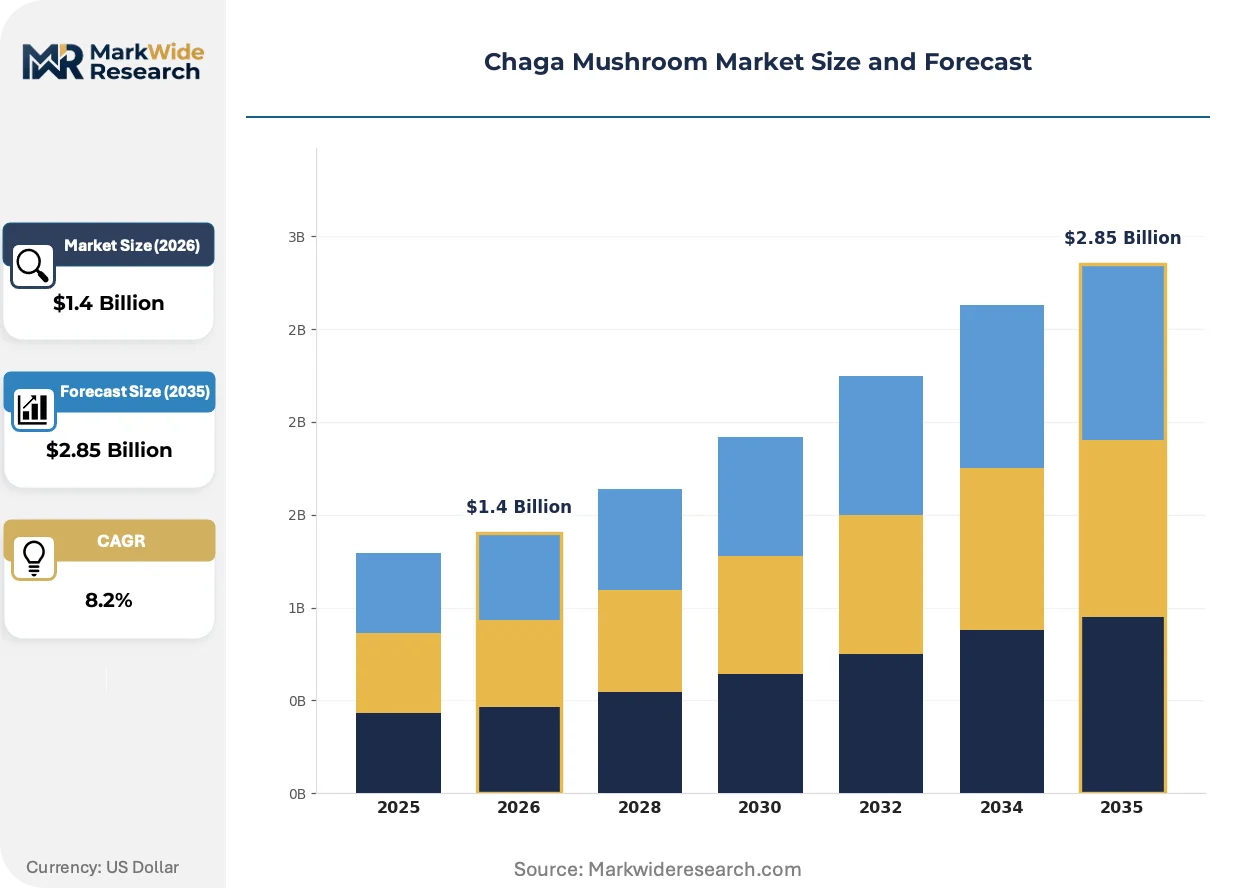
Market Dynamics
Wild harvest depletion across Siberian boreal zones is forcing supply chain reconfiguration toward cultivated mycelium alternatives, with climate volatility accelerating the transition timeline for extract manufacturers dependent on birch forest corridors.
Growth Catalysts
- Functional beverage integration:North American beverage manufacturers are incorporating chaga into adaptogenic drink portfolios as consumer interest in mushroom-based wellness expands beyond supplement aisles into mainstream retail.
- South Korean traditional medicine demand:Integration of chaga extracts into hanbang formulations drives premium pricing acceptance, with domestic distributors prioritizing certified wild-harvested origin claims.
- FDA NDI pathway maturation:Clarified notification procedures for Inonotus obliquus extracts reduce regulatory uncertainty for US supplement entrants, accelerating formulation development cycles.
Market Restraints
- Birch forest access volatility:Permafrost degradation and wildfire frequency in Russian Far East harvest zones create raw material supply discontinuities, compressing predictable sourcing windows.
- EFSA novel food assessment thresholds:Concentrated extracts exceeding traditional use concentrations trigger extended safety evaluation timelines, delaying European market entry for standardized polysaccharide products.
- Cordyceps and reishi substitution:Competing adaptogenic fungi with established supply chains and lower cultivation costs capture shelf space in price-sensitive nutraceutical segments.
Strategic Opportunities
- Subarctic cultivation zone expansion:Finnish and Alaskan birch plantation partnerships offer controlled-environment chaga production with traceable metabolite profiles, reducing wild harvest dependency.
- Direct-to-consumer subscription channels:E-commerce platforms enable extract brands to bypass conventional retail margin structures while capturing recurring revenue through personalized dosing protocols.
- Health Canada NHP registration harmonization:Alignment between Canadian and US quality specifications creates streamlined dual-market access for compliant manufacturers.
Industry Challenges
- Mycologist cultivation expertise scarcity:Specialized knowledge in subarctic fungal propagation remains concentrated in academic and traditional foraging networks, constraining scaled domestication efforts.
- Betulinic acid standardization complexity:Variable compound concentration across harvest batches complicates extract consistency, requiring investment in chromatographic verification infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chaga Mushroom Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.85 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Extract, Capsules, Tea End User: Retail Consumers, Health Shops, E-commerce, Food Services Distribution Channel: Retail Stores, Online Platforms, Pharmacies, Specialty Stores Application: Dietary Supplements, Beverages, Cosmetics, Nutraceuticals |
| Companies Covered | Baikal Herbs Ltd., Fungi Perfecti LLC, Annanda Chaga Mushrooms, Sayan Health, Inc., Four Sigmatic, Om Mushroom Superfood, Aloha Medicinals, FreshCap Mushrooms Ltd., Host Defense Mushrooms, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chaga Mushroom Market Strategic Shifts
Bioprocessing advances and regulatory clarification are compressing development cycles for chaga-derived ingredients, while demand patterns shift from traditional tea consumption toward precision-dosed functional applications.
Submerged fermentation technology for mycelium biomass production is decentralizing raw material sourcing away from geographically constrained wild harvest zones. North American ingredient suppliers are adopting bioreactor systems at accelerating rates, enabling year-round metabolite extraction independent of seasonal foraging windows. This shift compresses supply lead times from months to weeks while reducing quality variance inherent in wild-collected specimens.
Health Canada's Natural and Non-prescription Health Products Directorate has tightened polysaccharide content disclosure requirements for chaga-labeled products, mandating third-party verification for therapeutic claims. The policy revision elevates compliance costs for smaller extract importers while advantaging vertically integrated manufacturers with captive analytical capabilities. Canadian supplement brands are responding by consolidating supplier relationships toward audited cultivation operations.
Buyer concentration among functional beverage formulators is reshaping procurement terms for extract suppliers, with large-scale manufacturers demanding exclusive supply agreements and custom standardization protocols. This pattern displaces spot-market purchasing that previously dominated bulk ingredient trade. The shift is most visible in Pacific Northwest beverage clusters, where contract structures now incorporate minimum volume commitments and co-development clauses for novel delivery formats.
Chaga Mushroom Market Segmentation
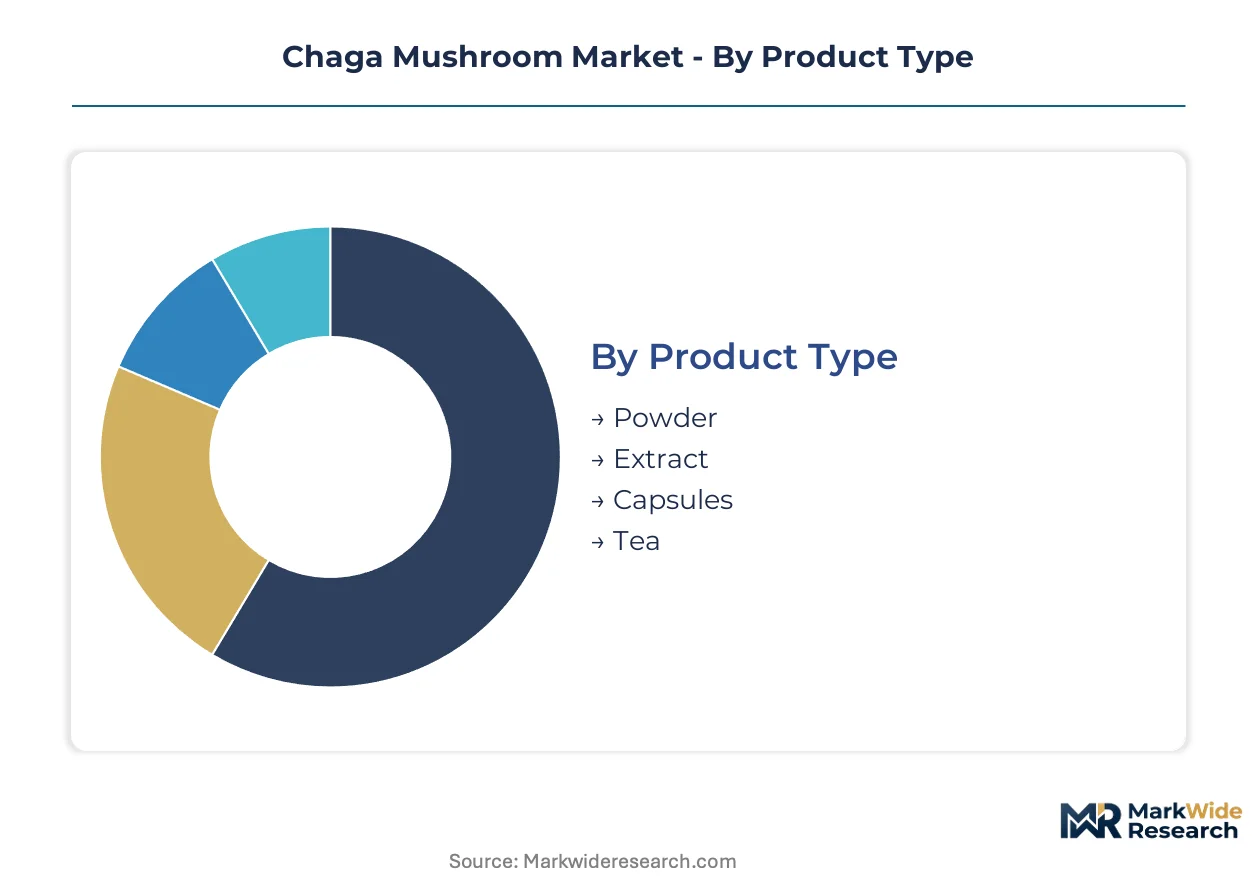
Chaga mushroom procurement patterns diverge sharply across buyer categories, with functional beverage manufacturers demanding standardized extracts while traditional medicine practitioners prioritize wild-harvested provenance. Understanding these segment-specific requirements illuminates where formulation investment and supply chain control deliver competitive advantage.
Product Type:
Buyers select formats based on solubility requirements, dosing precision needs, and shelf stability demands in their target applications.
- Extract:Standardized polysaccharide concentrates enable beverage-ready solubility and consistent bioactive dosing. Functional drink manufacturers in South Korea and the United States specify betulinic acid thresholds that wild harvest alone cannot reliably meet, driving demand toward chromatographically verified batches.
- Powder:Bulk ground biomass anchors ingredient trade volumes through cost-efficient handling and extended shelf stability. North American supplement blenders favor powder for encapsulation flexibility, though variable metabolite density complicates therapeutic claim substantiation.
- Capsules:Pre-dosed convenience formats compete on compliance adherence within nutraceutical portfolios, with Health Canada NHP registration requirements favoring suppliers with captive analytical verification.
- Tea:Traditional cut-and-sift formats retain cultural stickiness in East Asian consumer bases, particularly among hanbang practitioners who value whole-fungus visual authentication over standardized potency.
Volume sits with Powder; growth tilts toward Extract.
End User:
Procurement authority concentrates differently across channels, with direct-to-consumer platforms capturing recurring revenue while food service buyers prioritize menu differentiation.
- E-commerce:Subscription-based extract brands bypass conventional retail margin structures through personalized dosing protocols and origin storytelling. Finnish and Alaskan suppliers leverage traceable subarctic cultivation credentials to justify premium positioning in recurring shipment models.
- Retail Consumers:Supermarket and natural channel shoppers respond to adaptogenic wellness positioning, with shelf placement in Pacific Northwest clusters indicating mainstream acceptance trajectory.
- Health Shops:Staff-assisted purchasing environments favor education-intensive formats like whole mushroom pieces and traditional preparation guidance over pre-standardized extracts.
- Food Services:Specialty coffee roasters and functional beverage cafes incorporate chaga into limited-time offerings, with procurement driven by Instagram-ready visual differentiation rather than therapeutic dosing consistency.
Transaction frequency peaks with E-commerce; average order value concentrates with Health Shops.
Distribution Channel:
Channel selection determines compliance burden exposure, with pharmacy placement requiring therapeutic claim substantiation that retail channels escape.
- Online Platforms:Direct brand websites and marketplace aggregators enable global reach without territorial distribution agreements, though FDA NDI notification requirements still govern US-bound supplement shipments.
- Retail Stores:Mass-market and natural channel placement demands slotting fee structures and promotional calendar alignment that disadvantage smaller extract importers without volume guarantees.
- Pharmacies:Behind-the-counter positioning in South Korean and Canadian markets requires MFDS or Health Canada registration, creating barrier-to-entry advantages for vertically integrated manufacturers with captive quality infrastructure.
- Specialty Stores:Traditional medicine apothecaries and mushroom-focused boutiques prioritize wild-harvested origin claims and forager relationships over standardized potency metrics.
Reach concentrates with Online Platforms; margin protection concentrates with Specialty Stores.
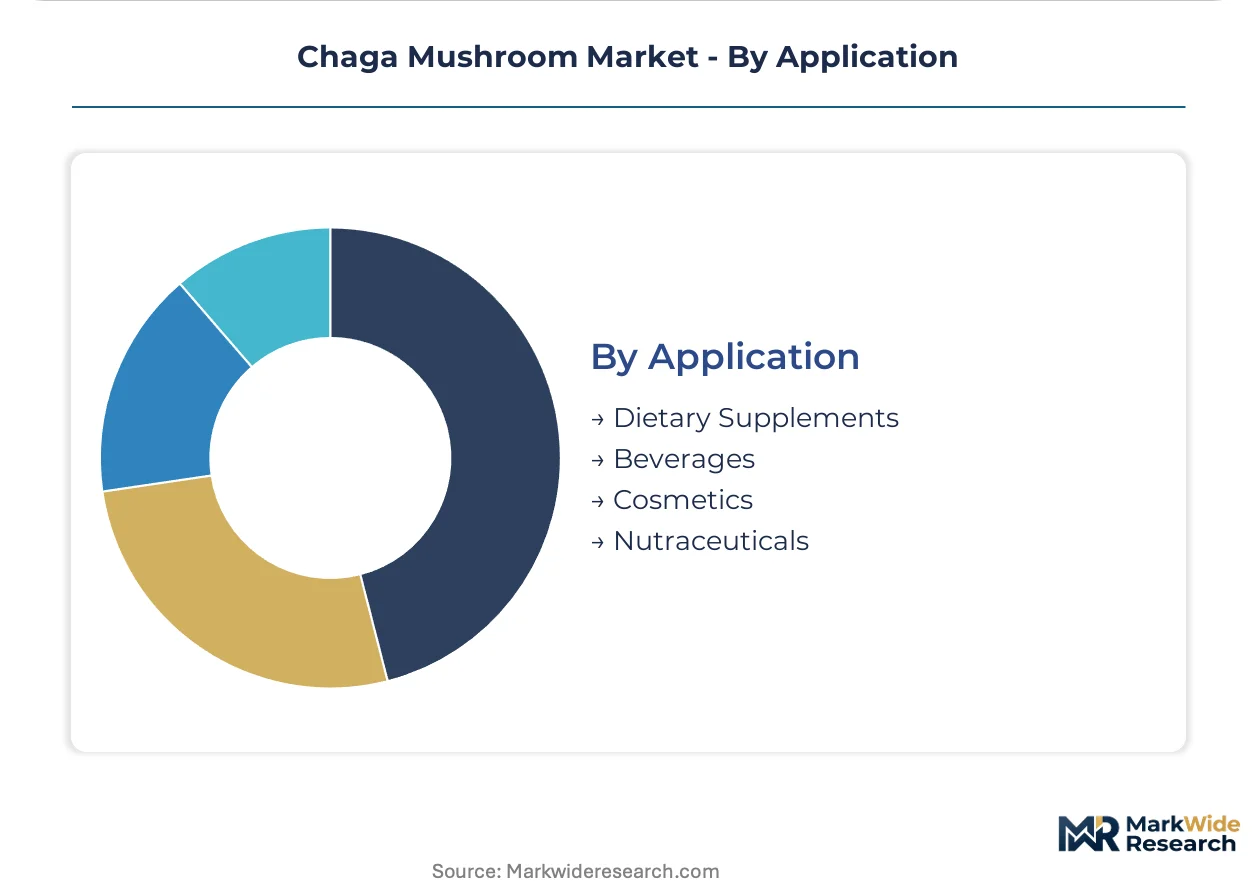
Application:
Formulation requirements vary dramatically across end-use categories, with beverage integration demanding solubility profiles that cosmetic applications disregard.
- Beverages:Ready-to-drink and powdered drink mix applications require cold-water solubility and neutral flavor masking, driving extract standardization investments among North American contract manufacturers.
- Dietary Supplements:Capsule and tablet formulations compete on polysaccharide content disclosure compliance, with Health Canada's tightened verification requirements elevating analytical infrastructure costs.
- Nutraceuticals:Functional food fortification applications in protein bars and snack formats prioritize cost-efficient powder incorporation over bioavailability optimization.
- Cosmetics:Topical antioxidant claims leverage melanin content for UV-protective positioning, with Korean skincare formulators specifying extract grades distinct from ingestible specifications.
Revenue concentration favors Dietary Supplements; formulation innovation concentrates in Beverages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Siberian birch forests anchor raw material flows for extract manufacturers, though climate volatility is redrawing harvest corridors toward cultivated alternatives in Finland, Alaska, and Canadian subarctic zones.
United States
Functional beverage manufacturers in the Pacific Northwest and Colorado drive extract procurement for adaptogenic drink portfolios. FDA New Dietary Ingredient notifications govern supplement entry pathways, with clarified procedures accelerating formulation timelines. Seattle and Portland clusters concentrate contract manufacturing capacity for ready-to-drink chaga integration.
South Korea
Traditional medicine practitioners and hanbang formulators sustain premium pricing for certified wild-harvested extracts. MFDS registration requirements create barrier-to-entry advantages for vertically integrated suppliers with captive quality infrastructure. Seoul-based distributors prioritize birch forest origin authentication over standardized potency metrics.
Canada
Health Canada's Natural and Non-prescription Health Products Directorate imposes tightened polysaccharide disclosure requirements, elevating analytical verification costs for extract importers. British Columbia and Ontario host cultivation R&D operations reducing wild harvest dependency. Vancouver-area suppliers leverage Health Canada registration for dual-market US-Canada access.
Finland
Subarctic birch plantation partnerships offer controlled-environment chaga production with traceable metabolite profiles. EFSA novel food assessment thresholds delay concentrated extract market entry, though traditional use formats circulate freely. Finnish suppliers capitalize on EU-origin credentials for premium positioning in German and French natural product channels.
Russia
Lake Baikal sourcing networks maintain raw material traceability for export-oriented extract processors. Permafrost degradation and wildfire frequency in the Russian Far East compress predictable foraging windows, forcing supply chain reconfiguration. Irkutsk-based operations leverage proximity to harvest zones for first-mover access to limited wild stocks.
Chaga Mushroom Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue cultivated mycelium alternatives and direct-to-consumer subscription channels. The vendor base stratifies across wild harvest specialists, bioreactor cultivators, and finished goods formulators. Three archetypes dominate: vertically integrated extract manufacturers with captive sourcing, pure-play cultivation technology providers, and brand-forward functional beverage marketers. Competitive intensity concentrates on supply exclusivity agreements and co-development partnerships for novel delivery formats.
Within the wild harvest sourcing tier, Baikal Herbs Ltd. and Sayan Health, Inc. occupy positions anchored to Siberian birch forest networks. Fungi Perfecti LLC exemplifies the cultivation technology archetype, with mycelium R&D programs reducing pressure on geographically constrained wild stocks. Four Sigmatic sits within the brand-forward formulation tier, commanding premium shelf positions in North American natural retail channels through ready-to-drink portfolio concentration.
| Leading Market Players |
|---|
| Baikal Herbs Ltd. |
| Fungi Perfecti LLC |
| Annanda Chaga Mushrooms |
| Sayan Health, Inc. |
| Four Sigmatic |
| Om Mushroom Superfood |
| Aloha Medicinals |
| FreshCap Mushrooms Ltd. |
| Host Defense Mushrooms |
| Others |
Value Chain & Pricing Dynamics
Functional beverage manufacturers' insistence on chromatographically verified betulinic acid thresholds is compressing supply options toward cultivated mycelium alternatives, elevating pricing power for bioreactor operators while squeezing wild harvest margins.
Pricing Analysis
Third-party polysaccharide certification bundled with origin traceability commands substantial premiums over unverified spot-market powder. Three-tier pricing structure across premium, standard, and economy levels separates wild-harvested Siberian extracts with full documentation from Finnish cultivated grades and generic blended powders. Pricing pressure stems from Health Canada's tightened verification requirements elevating compliance costs for smaller importers. Health Shops exhibit lowest price sensitivity due to staff-assisted education justifying premium positioning, while Nutraceutical blenders in bulk powder procurement show highest elasticity.
Supply Chain Analysis
Return flows of expired or non-conforming extract batches from European distributors create reverse logistics complexity for Russian and Finnish processors lacking refurbishment infrastructure. Raw material sourcing concentrates in Russia, Finland, and Alaska, with birch forest access volatility in the Russian Far East forcing supply reconfiguration. Mycelium biomass production draws from glucose substrates, temperature-controlled bioreactors, and specialized inoculum strains. Single-source vulnerability around Lake Baikal wild harvest networks exposes processors to permafrost degradation and wildfire disruption. Distribution runs through direct-to-consumer subscription platforms and exclusive supply agreements with Pacific Northwest beverage manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive advantage in this market is becoming a vertical-integration race, with upstream control over traceable cultivation zones and downstream captive access to functional beverage formulators determining margin capture.
For Market Incumbents: Lock in exclusive birch plantation partnerships in Finnish and Alaskan subarctic zones before cultivation capacity scarcity intensifies. Secure chromatographic verification infrastructure in-house to meet Health Canada and FDA notification requirements without third-party dependency. Defend against mycelium-based substitutes by emphasizing wild-harvested origin authentication in South Korean hanbang channels. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable route, bypassing slotting fee structures that disadvantage smaller extract importers in conventional retail. Target South Korean e-commerce aggregators with personalized dosing protocols and birch forest origin storytelling. Pursue white-space in cosmetics-grade melanin extracts for Korean skincare formulators seeking UV-protective positioning distinct from ingestible specifications. For Investors and Strategic Acquirers: The window for entry favors vertically integrated cultivators with captive bioreactor capacity and Health Canada NHP registration already secured. Long-term viability hinges on subarctic cultivation zone control as climate volatility compresses wild harvest windows. Monitor EFSA novel food assessment timelines for concentrated extracts as the inflection signal for European market access acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Subarctic Cultivation Partnership | Finnish birch plantation alliances reduce wild harvest dependency with traceable metabolite profiles. |
| Chromatographic Verification Infrastructure | In-house polysaccharide standardization meets FDA NDI and Health Canada tightened disclosure mandates. |
| Direct-to-Consumer Subscription Launch | E-commerce platforms bypass retail margin structures while capturing recurring revenue through personalized dosing. |
| Exclusive Beverage Supply Agreement | Pacific Northwest contract manufacturing clusters demand co-development clauses for novel delivery formats. |
| Cosmetics-Grade Extract Diversification | Korean skincare formulators specify melanin-rich grades distinct from ingestible therapeutic specifications. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with cultivation R&D directors, functional beverage formulators, Health Canada compliance officers, and Siberian foraging cooperative managers. FDA New Dietary Ingredient notification databases, EFSA novel food assessment registers, and Korean MFDS registration records provided regulatory pathway validation. Bottom-up extract production estimates triangulated against top-down functional beverage procurement surveys across the analysis window.
Granularity-level modeling disaggregated volume and value across product type, application, and distribution channel dimensions, with additional segmentation by cultivation source origin. CAGRs derived from logistic growth curve fitting anchored to historical trade flow trajectories and projected beverage integration rates. Forecast inputs incorporated birch forest access volatility indices, bioreactor adoption curves in North American cultivation operations, and regulatory assessment timeline distributions for concentrated extract categories.
The model holds under stable regulatory classification of chaga as dietary supplement; deviation in adaptogen reclassification debates or EFSA novel food threshold adjustments would shift channel eligibility and labeling requirements. Practitioners should monitor permafrost degradation rates in Russian Far East harvest zones and Health Canada polysaccharide verification mandate enforcement intensity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Global Quail Eggs Market
Agriculture and Agri Products
Tanzania Cashew Market
Agriculture and Agri Products
Asia-Pacific Artificial Humus Market
Agriculture and Agri Products
Black Sapote Market
Agriculture and Agri Products
Africa Animal Protein Market
Agriculture and Agri Products
Lucerne Market
Agriculture and Agri Products
Saudi Arabia Agriculture Market
Agriculture and Agri Products
Brazil Rice Market
Agriculture and Agri Products
Colombia Agriculture Market
Agriculture and Agri Products
Organic Soybean Market
Agriculture and Agri Products
Angola Agriculture Market
Agriculture and Agri Products
Asia-Pacific Compound Feed Market
Agriculture and Agri Products
Brazil Compound Feed Market
Agriculture and Agri Products
Spain Compound Feed Market
Agriculture and Agri Products
Canada Backyard Poultry Feed Market
Agriculture and Agri Products
North America Palm Oil Market