
 North America Poultry Feed Market | 2026-2036
North America Poultry Feed Market Size, Share, and Industry Trends Forecast 2026-2036
North America Poultry Feed Market Analytics
Commercial integrators is recalibrating the North America poultry feed market by shifting toward precision-formulated diets that optimize feed conversion ratios at scale. Cargill Inc. leverages its grain origination network across the U.S. Midwest to secure cost-advantaged corn and soybean supplies for captive feed production. Archer Daniels Midland Company anchors its position through oilseed processing assets that generate high-protein meal streams directed to broiler operations. Alltech Inc. differentiates via yeast-based additive technologies that improve gut health metrics in antibiotic-free production systems.
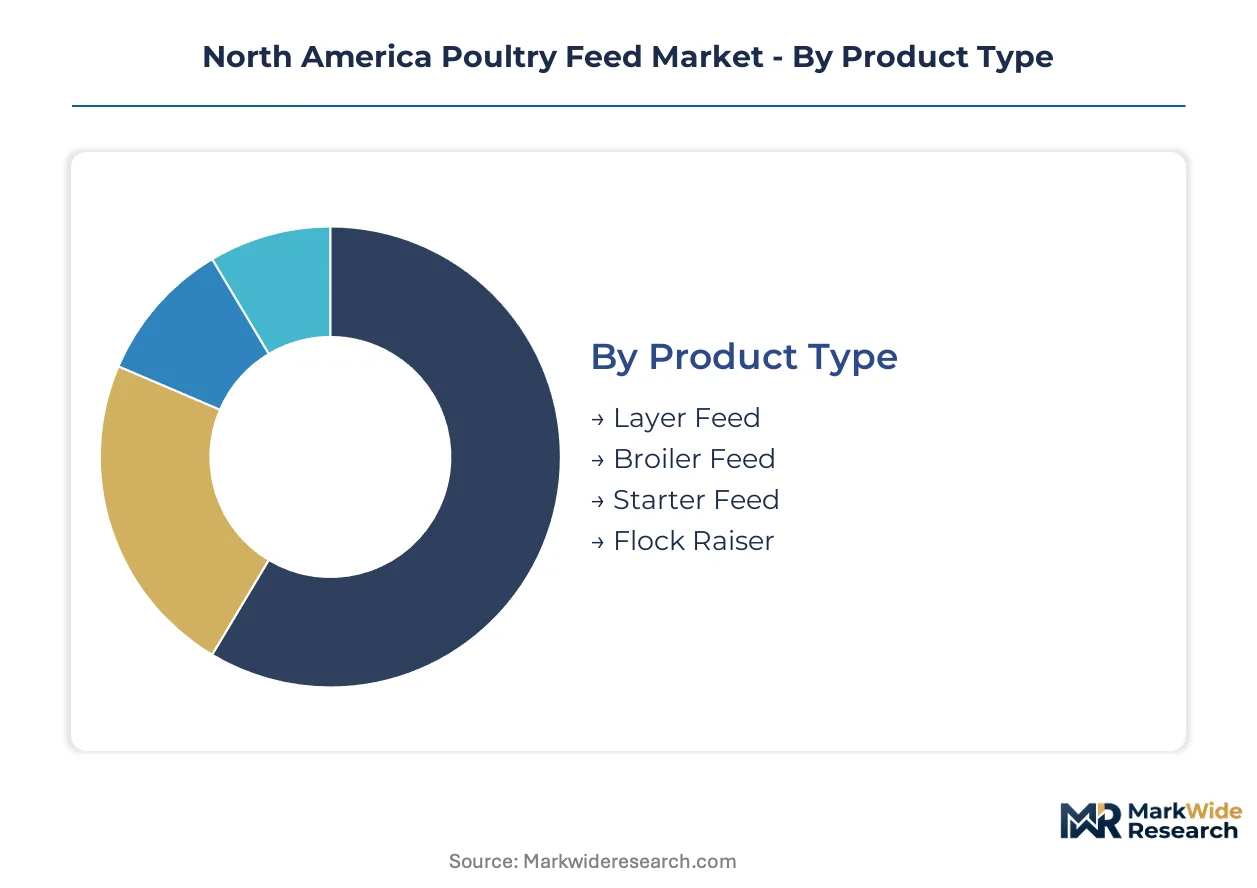
Poultry feed comprises scientifically formulated mixtures of grains, protein meals, vitamins, and minerals designed to deliver precise metabolizable energy levels and amino acid profiles for specific bird growth stages. Manufacturers grind, mix, pelletize, and cool ingredients to achieve uniform nutrient distribution and reduce feed wastage in automated delivery systems. Broiler feed occupies the largest volume share as integrators pursue accelerated grow-out cycles to maximize barn turnover economics. Layer feed commands margin premiums due to extended production cycles requiring sustained calcium and phosphorus management. Starter feed represents the fastest-growing product category as early nutrition protocols gain adoption among commercial breeders targeting improved flock uniformity.
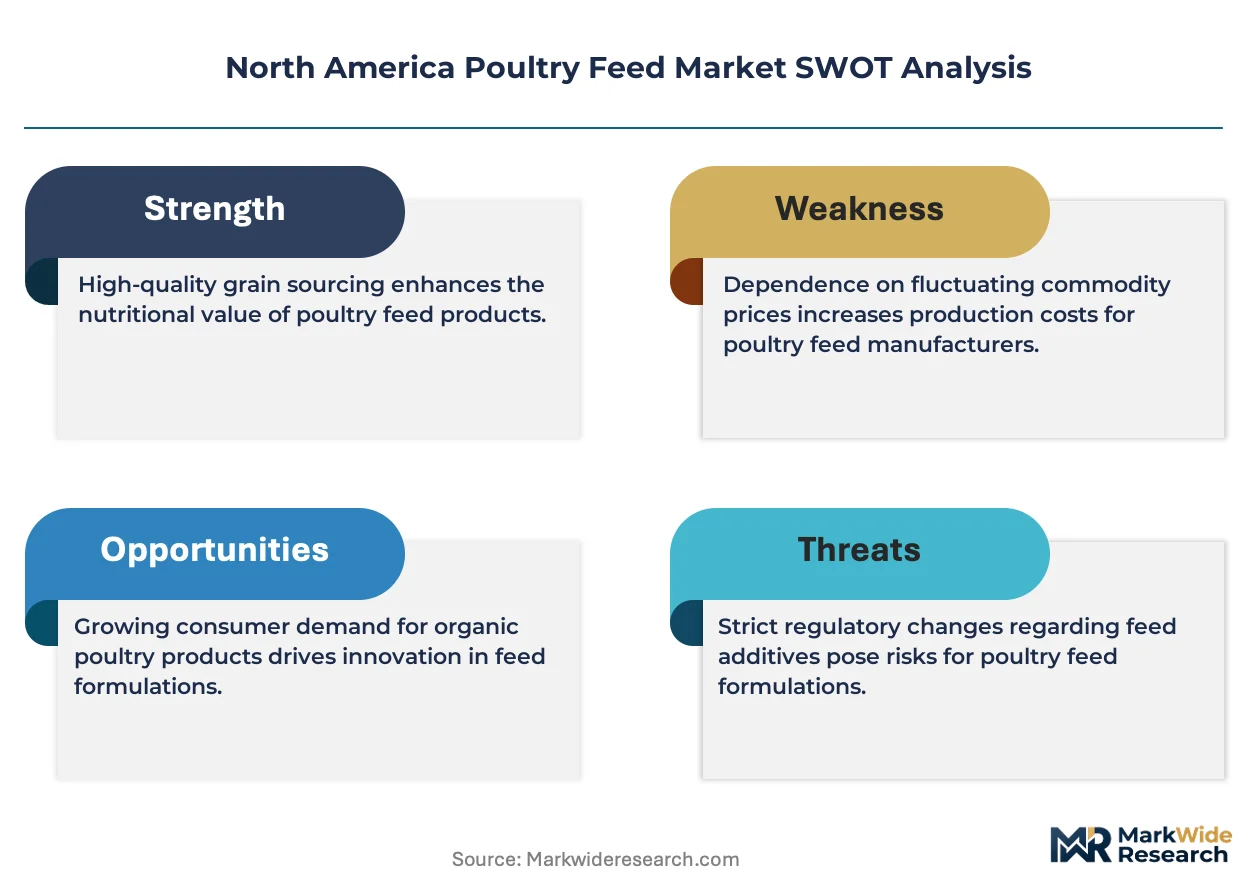
The U.S. Food and Drug Administration's Veterinary Feed Directive restricts medically important antibiotics in feed, redirecting formulation investment toward alternatives like organic acids and phytogenics. The EPA enforces Clean Air Act permits and water discharge standards that elevate compliance costs for feed mill operations across multiple states. State agriculture departments in Georgia, Arkansas, and North Carolina administer additional nutrient management certifications that affect facility siting and expansion timelines. Stakeholders must monitor evolving state-level environmental enforcement intensity and antibiotic-free certification standards as these forces reshape formulation economics and facility investment decisions.
Market Dynamics
Consolidation among commercial integrators is compressing the North America poultry feed market's supplier base as captive feed production displaces third-party sourcing across the U.S. Southeast. Vertically integrated operations in Georgia and Arkansas now control formulation specifications that ripple through regional ingredient procurement.
Growth Catalysts
- Precision nutrition protocols:Commercial breeders are deploying early-stage feed formulations that improve flock uniformity metrics. Layer operations in North Carolina are expanding calcium-optimized diets to extend production cycles.
- EPA Clean Water Act enforcement:Tighter discharge standards are accelerating capital investment in closed-loop feed mill systems. Arkansas and Alabama facilities are retrofitting wastewater treatment to meet nutrient management certifications.
- Antibiotic-free certification demand:Retail and foodservice buyers are mandating verification protocols that redirect formulation spend toward functional additives. Gut health optimization is becoming a procurement criterion for broiler integrators.
Market Restraints
- Corn and soybean price volatility:Feed cost structures remain exposed to Midwest grain futures swings. Drought cycles in the Corn Belt transmit directly to formulation economics.
- Midwest grain origination concentration:Cost-advantaged supply sits with a narrow corridor of elevator and processor networks. Disruption risk concentrates in Illinois and Iowa logistics nodes.
- FDA Veterinary Feed Directive compliance friction:Medically important antibiotic restrictions create formulation reformulation costs and veterinary oversight requirements that slow product cycle iterations.
Strategic Opportunities
- Mexico import market expansion:Cross-border protein demand is opening formulation specification opportunities for U.S.-based feed exporters. Monterrey and Guadalajara distribution channels are deepening.
- Organic acid and phytogenic additive convergence:Synthetic antibiotic replacements are combining with enzyme technologies to create premium feed tiers. Commercial integrators are testing stacked additive protocols.
- State-level renewable energy incentives:Solar and biogas installations at feed mill sites are qualifying for Georgia and Arkansas tax credits that reduce operational energy costs.
Industry Challenges
- Feed mill automation technician scarcity:Pelletizing and extrusion system maintenance requires specialized mechanical-electrical skill sets that regional labor markets undersupply.
- Multi-state nutrient management certification timelines:Georgia, Arkansas, and North Carolina each administer distinct permitting processes that delay facility expansions by quarters.
- Legacy formulation software integration:Precision diet modeling platforms require data migration from decades-old batch control systems that resist API connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Poultry Feed Market |
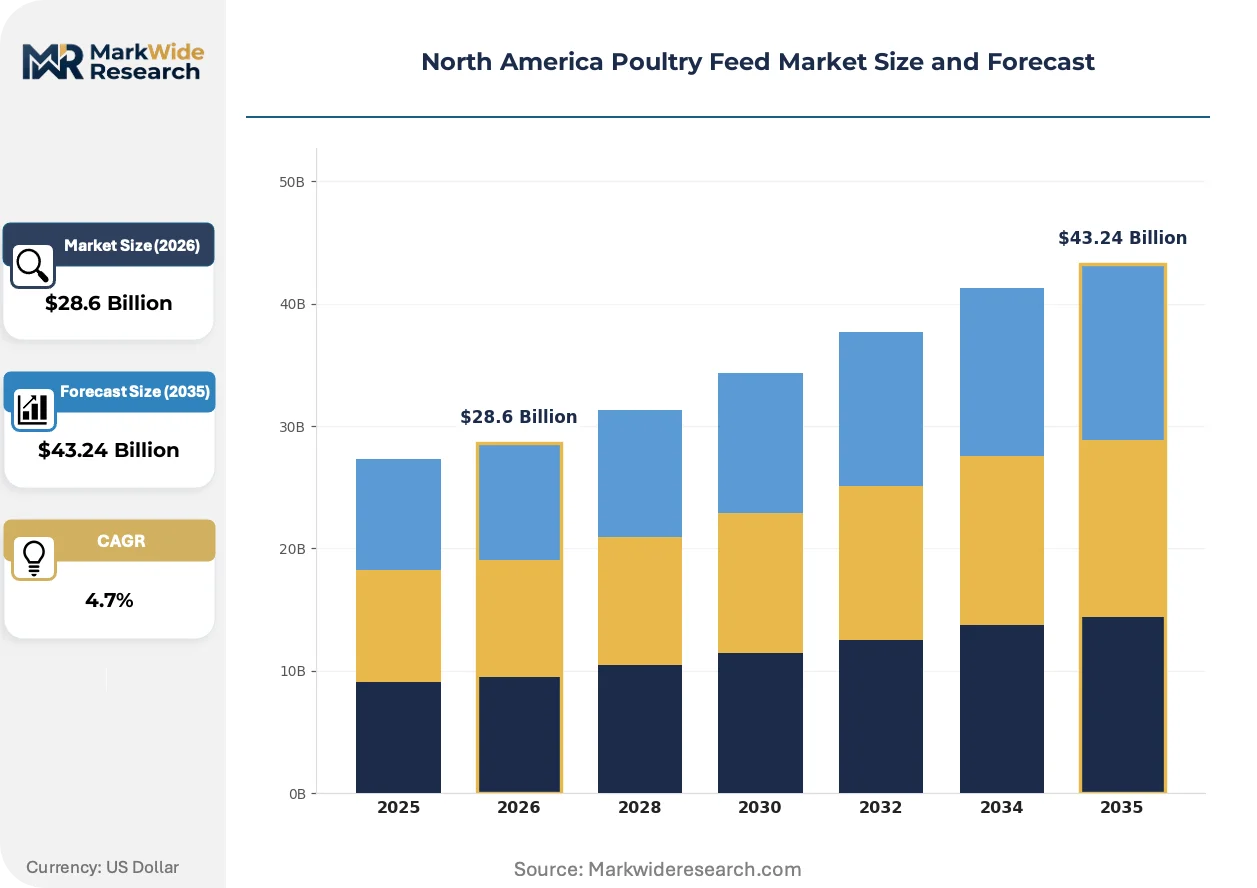
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.24 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Layer Feed, Broiler Feed, Starter Feed, Flock Raiser Ingredient Type: Grains, Proteins, Vitamins, Minerals Distribution Channel: Retail, Wholesaler, Direct Sales, Online End User: Poultry Farms, Commercial Breeders, Backyard Poultry Owners, Integrators |
| Companies Covered | Cargill Inc., Archer Daniels Midland Company, Alltech Inc., Nutreco NV, Land O'Lakes Inc., Novus International Inc., Koninklijke DSM NV, Evonik Industries AG, Kent Nutrition Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Poultry Feed Market Evolving Landscape
Automation and alternative protein sourcing are restructuring how North American poultry feed is formulated, manufactured, and delivered. These shifts are compressing legacy operational models while opening new competitive axes.
Near-infrared spectroscopy coupled with automated batching systems is automating real-time ingredient quality assessment and formulation adjustment. Large commercial integrators in Georgia and Alabama are deploying these systems across multiple mill sites simultaneously. The technology is automating away manual sampling and laboratory turnaround delays that previously constrained production scheduling.
The FDA's Veterinary Feed Directive continues tightening medically important antibiotic restrictions in feed formulations. Broiler operations are responding by accelerating phytogenic and organic acid additive adoption. North Carolina and Arkansas integrators are absorbing higher input costs to maintain antibiotic-free certification access to retail channels.
Direct procurement relationships between commercial integrators and grain originators are displacing traditional feed distributor intermediaries. Large operators in the U.S. Southeast are negotiating long-term corn and soybean meal contracts that bypass regional feed suppliers. This concentration is most visible in Georgia, where three integrators now control the majority of independent grow-out feed flow.
North America Poultry Feed Market Segmentation
Segmentation in the North America poultry feed market reflects divergent buyer economics across production scales and regulatory exposure. Commercial integrators prioritize feed conversion efficiency metrics while backyard operators respond to retail certification signals. Understanding these tiered demand patterns clarifies where formulation investment and distribution infrastructure should concentrate.
Product Type:
Buyer economics separate most sharply by bird growth stage and production cycle length.
- Broiler Feed:High-energy formulations with precise amino acid balancing support accelerated grow-out cycles targeting barn turnover maximization. Georgia and Arkansas integrators dominate procurement volumes as they consolidate regional grow-out operations under unified formulation specifications.
- Layer Feed:Sustained calcium and phosphorus management protocols extend production cycles across 80-plus week hen lifespans. North Carolina operations command margin premiums for extended-cycle diets that maintain shell quality metrics through late lay phases.
- Starter Feed:Early nutrition protocols targeting improved flock uniformity are gaining adoption among commercial breeders.
- Flock Raiser:Intermediate growth-stage formulations bridge starter and finisher phases for smaller-scale operations.
Volume sits with broiler feed; growth tilts toward starter feed as early-stage nutrition protocols expand.
Ingredient Type:
Cost structures concentrate where Midwest grain origination intersects with oilseed processing infrastructure.
- Grains:Corn delivers metabolizable energy density at scale, with formulation economics tethered to Illinois and Iowa futures pricing. Drought cycles in the Corn Belt transmit directly to regional feed mill cost structures.
- Proteins:Soybean meal supplies essential amino acid profiles, with crushing capacity concentrated near Midwest oilseed processing assets. Cargill and ADM origination networks secure cost-advantaged meal streams for captive production.
- Vitamins:Micro-nutrient premixes require precise blending accuracy to avoid deficiency or toxicity thresholds.
- Minerals:Calcium and phosphorus sources anchor layer feed specifications for shell strength maintenance.
Procurement gravity centers on grains; proteins command the steepest price volatility exposure.
Distribution Channel:
Channel selection tracks operation scale and formulation customization requirements.
- Direct Sales:Large commercial integrators negotiate long-term supply contracts that bypass intermediary margins and enable specification customization. Georgia-based operators increasingly control feed flow through captive mill networks.
- Wholesaler:Regional distributors aggregate smaller-volume orders across independent grow-out farms in Alabama and Mississippi.
- Retail:Pre-formulated bagged products serve backyard poultry owners through farm supply stores.
- Online:E-commerce channels are emerging for specialty additive and supplement procurement.
Volume concentrates in direct sales; online channels are expanding most quickly for niche additive categories.
End User:
User type determines regulatory exposure intensity and certification requirements.
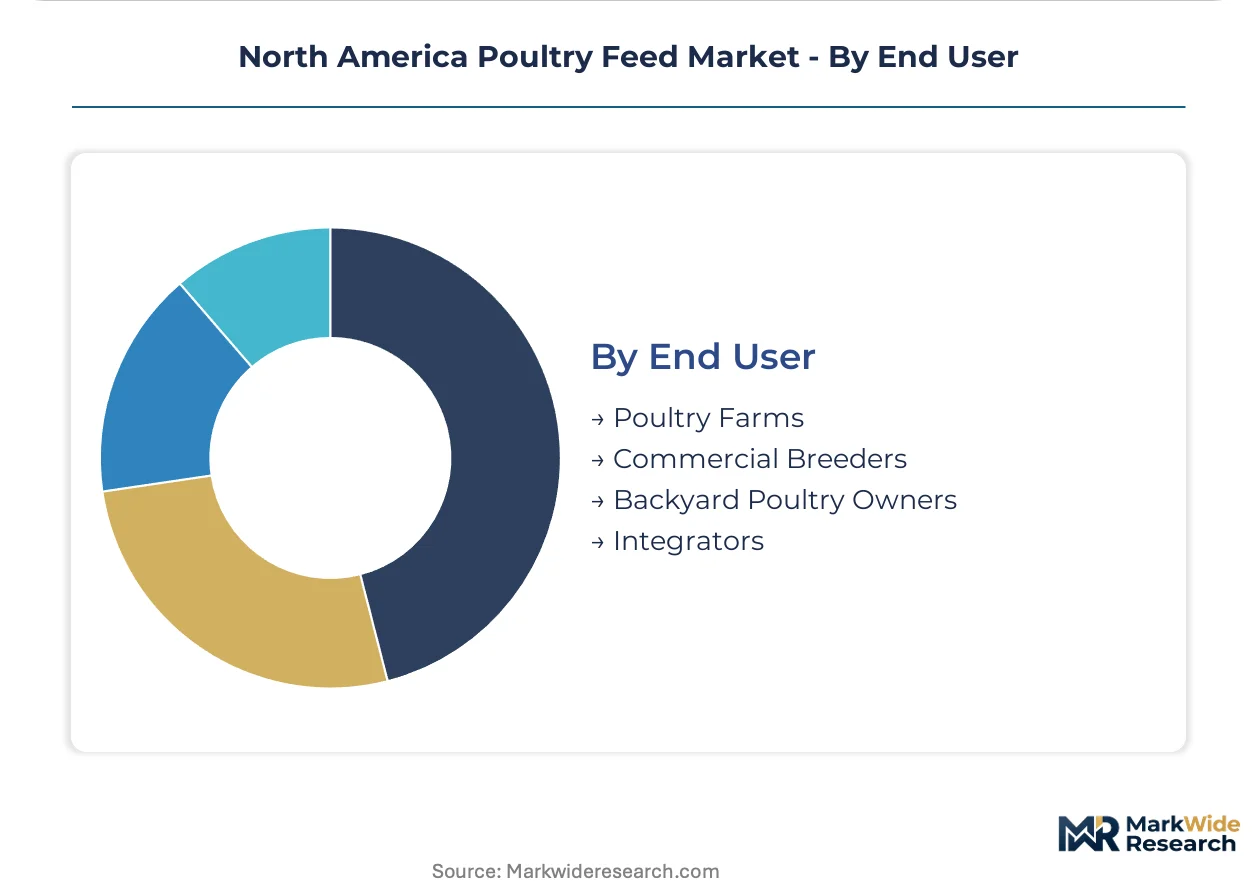
- Integrators:Vertically controlled operations in the U.S. Southeast specify formulations across captive supply chains, driving standardization at scale. Three Georgia-based integrators now direct the majority of regional feed procurement decisions.
- Commercial Breeders:Early-stage nutrition investment targets flock uniformity metrics and genetic potential realization.
- Poultry Farms:Independent grow-out operations respond to integrator feed specifications under contract arrangements.
- Backyard Poultry Owners:Small-scale demand responds to retail certification signals including antibiotic-free labeling.
Procurement authority sits with integrators; backyard ownership is gaining share fastest as retail channel access expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The U.S. Southeast's poultry production corridor operates as a de facto special economic zone, where Georgia, Arkansas, and Alabama cluster vertically integrated operations that drive regional feed demand concentration.
United States
Georgia and Arkansas host the densest concentrations of commercial integrators, where three operators now direct the majority of regional feed procurement decisions. EPA Clean Water Act enforcement tightens discharge standards for feed mills across these states. The Georgia-Arkansas corridor sees accelerated capital deployment in closed-loop wastewater systems to meet nutrient management certifications.
Canada
Ontario and Quebec maintain specialized layer operations that source precision-formulated calcium-optimized diets for extended production cycles. Health Canada and the PMRA administer feed additive approvals that lag FDA timelines, creating formulation specification gaps. The St. Lawrence Valley corridor concentrates Prairie grain origination with Eastern Canadian processing infrastructure.
Mexico
Monterrey and Guadalajara distribution channels deepen as cross-border protein demand opens formulation specification opportunities for U.S.-based exporters. The country's national agricultural regulator oversees import protocols for feed ingredients and finished formulations. The Bajío Region attracts investment in automated feed mill infrastructure to serve expanding commercial poultry operations.
North America Poultry Feed Market Competitive Landscape
Top-tier vendors anchor grain origination and oilseed processing, while mid-tier specialists concentrate on functional additives and regional distribution. The supplier base compresses as captive feed production displaces third-party sourcing across the U.S. Southeast. Three strategic archetypes dominate: grain-integrated processors, additive technology specialists, and regional nutrition service providers. Consolidation and backward integration into ingredient supply represent the dominant competitive moves reshaping procurement relationships.
Among grain-integrated processors, Cargill Inc. and Archer Daniels Midland Company occupy positions that exemplify cost-advantaged supply chain control. Within the functional additive tier, Alltech Inc. represents the archetype of yeast-based technology providers targeting antibiotic-free certification requirements. These three entities anchor distinct competitive vectors—origination infrastructure, processing scale, and nutritional innovation—that structure rivalry across formulation specification negotiations.
| Leading Market Players |
|---|
| Cargill Inc. |
| Archer Daniels Midland Company |
| Alltech Inc. |
| Nutreco NV |
| Land O'Lakes Inc. |
| Novus International Inc. |
| Koninklijke DSM NV |
| Evonik Industries AG |
| Kent Nutrition Group |
| Others |
Value Network & Pricing Analysis
Captive feed mill networks across Georgia, Arkansas, and Alabama anchor supply positioning and pricing power for commercial integrators consolidating regional grow-out operations. These vertically controlled production systems bypass intermediary margins while enabling specification customization that commands premium positioning in antibiotic-free certification tiers.
Pricing Analysis
Short lead-time premiums for just-in-time ingredient delivery separate contract-based integrator procurement from spot-market spot purchases at independent mills. Three-tier pricing structure across precision-formulated premium, standard commodity, and economy bulk tiers tracks certification level and volume scale. Cost compression in standard-tier formulations is intensifying because drought-driven corn futures volatility transmits directly to Midwest origination economics. Backyard poultry owners through retail channels exhibit highest price sensitivity, while Georgia-based integrators with captive supply demonstrate lowest sensitivity due to backward integration into grain origination.
Supply Chain Analysis
Specialized automation technician scarcity across Illinois, Iowa, and Arkansas feed mill corridors constrains pelletizing system maintenance capacity and elevates operational downtime risk. Geographic supply concentration centers on the U.S. Midwest for corn origination, the Southeast for oilseed processing assets, and the Georgia-Arkansas corridor for finished feed manufacturing. Raw material dependencies rest on Illinois and Iowa corn futures, Mississippi River barge logistics, and domestic soybean meal crushing capacity. Single-source vulnerability concentrates in Midwest elevator networks during drought cycles. Distribution runs through direct sales contracts for integrators, regional wholesalers for independent growers, and farm supply retail for backyard operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over Midwest grain origination and captive feed mill networks determines competitive survival. Players are pursuing upstream control over corn and soybean meal supply as the decisive lever.
For Market Incumbents: To counter displacement by integrators building captive mill capacity, third-party feed manufacturers should secure long-term offtake agreements with Arkansas and Alabama grain elevators and invest in FDA-compliant phytogenic premix certification to maintain specification relevance in antibiotic-free supply chains.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in layer feed calcium optimization creates white-space opportunity for specialized nutrition service providers targeting North Carolina extended-cycle operations. Mexico import channels through Monterrey distribution represent the most penetrable geography. A go-to-market angle anchored in organic acid additive stacking protocols can bypass incumbent grain-integrated processor dominance.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by grain-integrated processors seeking regional feed mill assets. Long-term viability across the analysis window favors operators with EPA Clean Water Act compliance infrastructure already deployed. Acquisition target archetype: mid-tier regional nutrition specialists with Georgia or Arkansas facility permits and active phytogenic formulation pipelines. The signal to watch is EPA enforcement intensity escalation accelerating stranded asset risk at non-compliant mills.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain Origination | Captive corn and soybean supply from Illinois and Iowa elevators secures cost-advantaged formulation inputs against futures volatility. |
| Closed-Loop Wastewater System Deployment | EPA Clean Water Act compliance infrastructure in Arkansas and Georgia facilities prevents nutrient management certification delays. |
| Phytogenic Additive Certification Investment | FDA-compliant organic acid and yeast-based gut health protocols maintain antibiotic-free retail channel access for integrators. |
| Near-Infrared Spectroscopy Automation | Real-time ingredient quality assessment across Georgia and Alabama mill sites compresses laboratory turnaround and batch adjustment cycles. |
| Mexico Distribution Channel Expansion | Cross-border formulation specification opportunities through Monterrey and Guadalajara deepen market access beyond U.S. Southeast concentration. |
Research Methodology
Multi-period observation of feed conversion ratio trends, EPA enforcement actions, and integrator consolidation patterns anchored the trend analysis, supplemented by interviews with commercial integrator procurement directors, feed mill operations managers, grain elevator origination specialists, and state agriculture department regulatory officials. Secondary validation drew from USDA crop production reports, EPA Clean Water Act permit databases, FDA Veterinary Feed Directive guidance documents, and state-level nutrient management certification records. Bottom-up volume modeling across product type, ingredient category, and distribution channel segments triangulated against top-down market sizing from trade association data.
Input-output matrix analysis mapped corn and soybean meal price transmission to formulation economics across the projection horizon. Segmentation dimensions modeled included bird growth stage, ingredient type, distribution channel, and end-user scale tier. CAGRs were derived from regression analysis of historical volume trajectories adjusted for regulatory inflection points. Industry-specific forecast inputs incorporated EPA enforcement intensity indices and integrator captive capacity expansion announcements.
Inputs from USDA crop reports and EPA permit databases were available through the study window; gaps in real-time integrator inventory positioning data introduce uncertainty bands around quarterly volume assumptions. Forecasts reflect documented assumptions regarding drought cycle frequency and antibiotic-free certification adoption curves. Material deviation in EPA enforcement intensity or Midwest grain futures volatility warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Non GMO Soybean Market
Agriculture and Agri Products
Europe Alfalfa Hay Market
Agriculture and Agri Products
Philippines Feed Industry Market
Agriculture and Agri Products
Kenya Floriculture Market
Agriculture and Agri Products
Indonesia Animal Feed Market
Agriculture and Agri Products
South America Poultry Feed Market
Agriculture and Agri Products
South Africa Compound Feed Market
Agriculture and Agri Products
Vietnam Floriculture Market
Agriculture and Agri Products
China Animal Protein Market
Agriculture and Agri Products
Mushroom Cultivation Market
Agriculture and Agri Products
China Compound Feed Market
Agriculture and Agri Products
Clover Leaf Oil Market
Agriculture and Agri Products
Chaga Mushroom Market
Agriculture and Agri Products
Sugar Beet Market
Agriculture and Agri Products
Tarragon Market
Agriculture and Agri Products
American Ginseng Market