
 Uruguay Agricultural Products Market | 2026-2036
Uruguay Agricultural Products Market Size, Share, and Industry Trends Forecast 2026-2036
Uruguay Agricultural Products Market Insights
Specialized agronomy talent is redrawing competitive boundaries across Uruguay's farm belt. Cargill Incorporated leverages its grain origination network to secure soy and wheat flows from the Litoral region. Copagran anchors domestic oilseed crushing capacity, sustaining supply to local feed manufacturers and biodiesel producers. Marfrig Global Foods S.A. dominates cattle procurement, extending its reach from pasture to processed beef exports through controlled cold-chain infrastructure.
Uruguay agricultural products encompass cultivated outputs including cereals, oilseeds, fruits, and vegetables, typically harvested at moisture contents below 14 percent for stable storage and graded by protein, oil, or sugar content depending on species. These outputs serve food processing, animal nutrition, biofuel feedstock, and cross-border trade functions. Cereals and oilseeds occupy the largest value share, with soybeans and wheat generating the dominant margin pools through export parity pricing. The food processing end-use channel shows the fastest structural expansion, driven by rising regional demand for packaged proteins and vegetable oils.
Uruguay's Ministry of Livestock, Agriculture and Fisheries (MGAP) enforces phytosanitary certification and traceability protocols that shape export market access, particularly for beef and grain shipments to the European Union and China. The country's national standards body, UNIT, aligns quality benchmarks with Mercosur technical regulations and international CODEX references. Stakeholders must monitor how evolving EU deforestation-free supply chain rules and domestic water-use permitting affect planting decisions and capital allocation across the western agricultural zones.
Market Dynamics
EU deforestation-free supply chain rules are forcing Uruguayan exporters to restructure traceability systems across cattle and soy operations, compressing compliance timelines and redirecting capital toward digital infrastructure.
Growth Catalysts
- Precision agriculture hardware:Variable-rate seeding and soil mapping systems are lifting per-hectare yields across the Pampas belt, allowing producers to capture premium grades for export parity pricing.
- China's feed demand:Livestock feed operations in East Asian markets sustain offtake volumes for Uruguayan soy and coarse grains through long-term supply contracts.
- MGAP traceability mandates:Uruguay's Ministry of Livestock, Agriculture and Fisheries certification protocols are opening preferential access to EU beef import quotas.
Market Restraints
- Fertilizer import dependency:Domestic production capacity for nitrogen and phosphate inputs is negligible, exposing margins to Black Sea supply disruptions and currency volatility.
- Port infrastructure concentration:Montevideo's port complex handles the dominant share of grain and beef exports, creating single-point vulnerability for high-value trade flows.
- Water-use permitting delays:Western agricultural zones face extended approval timelines for irrigation expansion under revised basin management frameworks.
Strategic Opportunities
- Biodiesel feedstock expansion:Copagran's crushing capacity and local biofuel mandates create captive demand for high-oil soybean varieties.
- Digital agronomy services:Remote sensing and predictive analytics convergence is opening subscription revenue streams from mid-scale producers previously underserved by technical assistance.
- Direct-to-processor channels:Beef producers are bypassing traditional auction systems through vertical contracts with Marfrig's cold-chain infrastructure.
Industry Challenges
- Agronomy talent scarcity:Specialized crop and livestock advisors are concentrated in legacy cooperatives, constraining technology transfer to independent farms.
- Legacy system integration:Traceability software deployment requires manual data entry bridging with paper-based field records, slowing compliance verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Uruguay Agricultural Products Market |
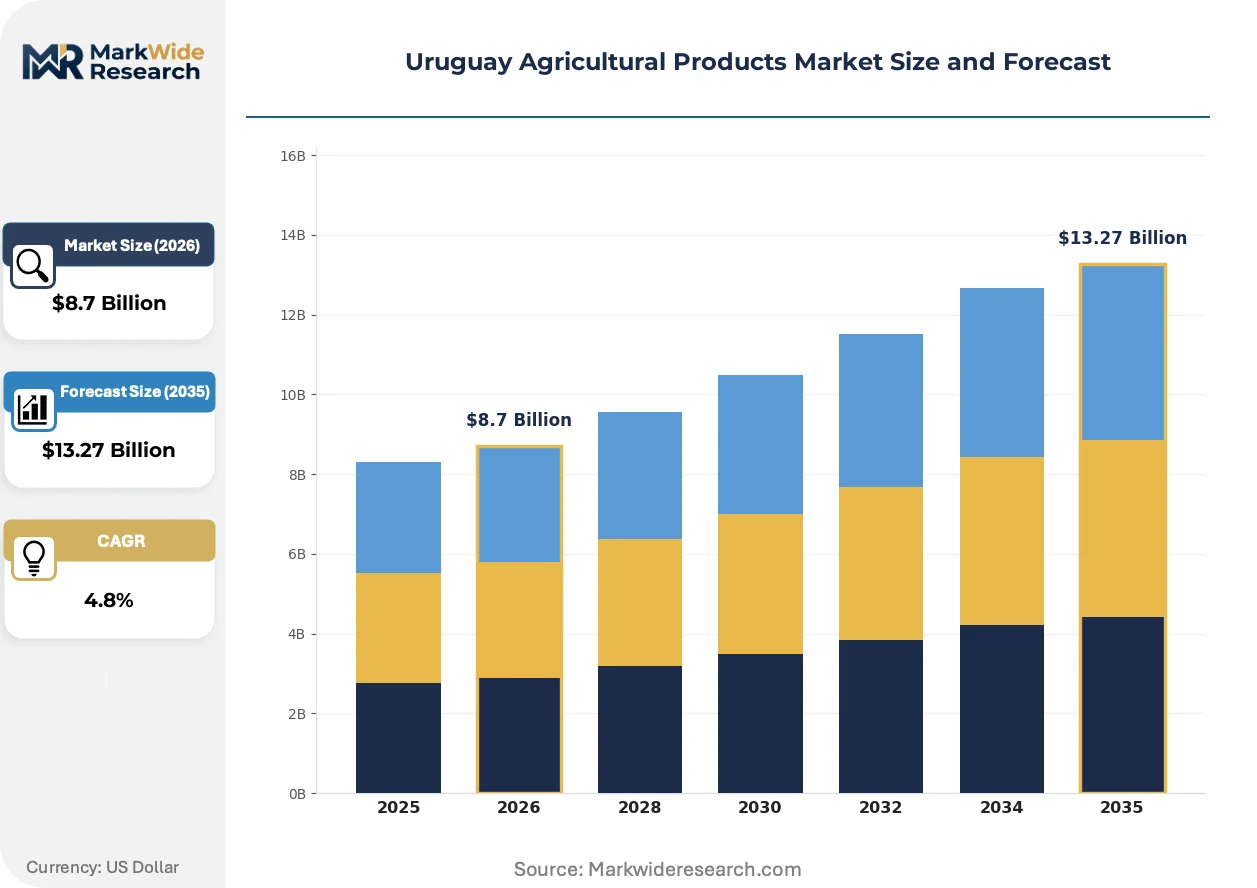
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cereals, Fruits, Vegetables, Oilseeds End Use: Food Processing, Animal Feed, Biofuels, Export Packaging Type: Bags, Bales, Boxes, Bulk Distribution Channel: Wholesale, Retail, E-commerce, Direct Sales |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, COFCO International Limited, Louis Dreyfus Company B.V., Marfrig Global Foods S.A., Bunge Limited, Saman, Copagran, Barraca Erro, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Uruguay Agricultural Products Market Trends and Innovations
Digital infrastructure and regulatory stringency are reshaping how Uruguayan agricultural products move from field to foreign buyer, with technology adoption curves diverging sharply across producer scale tiers.
Variable-rate application technology is bifurcating the precision agriculture landscape. Soil mapping and automated spreading systems enable large-scale operations to optimize input placement across heterogeneous zones. Mid-tier producers lag adoption due to capital constraints and technical support gaps. The technology is compressing yield variance within elite farms while widening productivity spreads across the sector.
EU Deforestation Regulation implementation timelines are tightening due diligence requirements for beef and soy exporters. MGAP is aligning national traceability protocols with satellite-based geolocation verification standards. Cattle ranching operations in northern departments face the steepest compliance costs as they retrofit herd management systems.
Buyers in premium protein channels are demanding unbundled certification credentials rather than bundled quality assurances. Food processors and retail chains now source animal welfare, carbon footprint, and origin documentation separately through digital platforms. This pattern is most visible in EU and UK import procurement where supermarket chains dictate specification tiers.
Uruguay Agricultural Products Market Segmentation
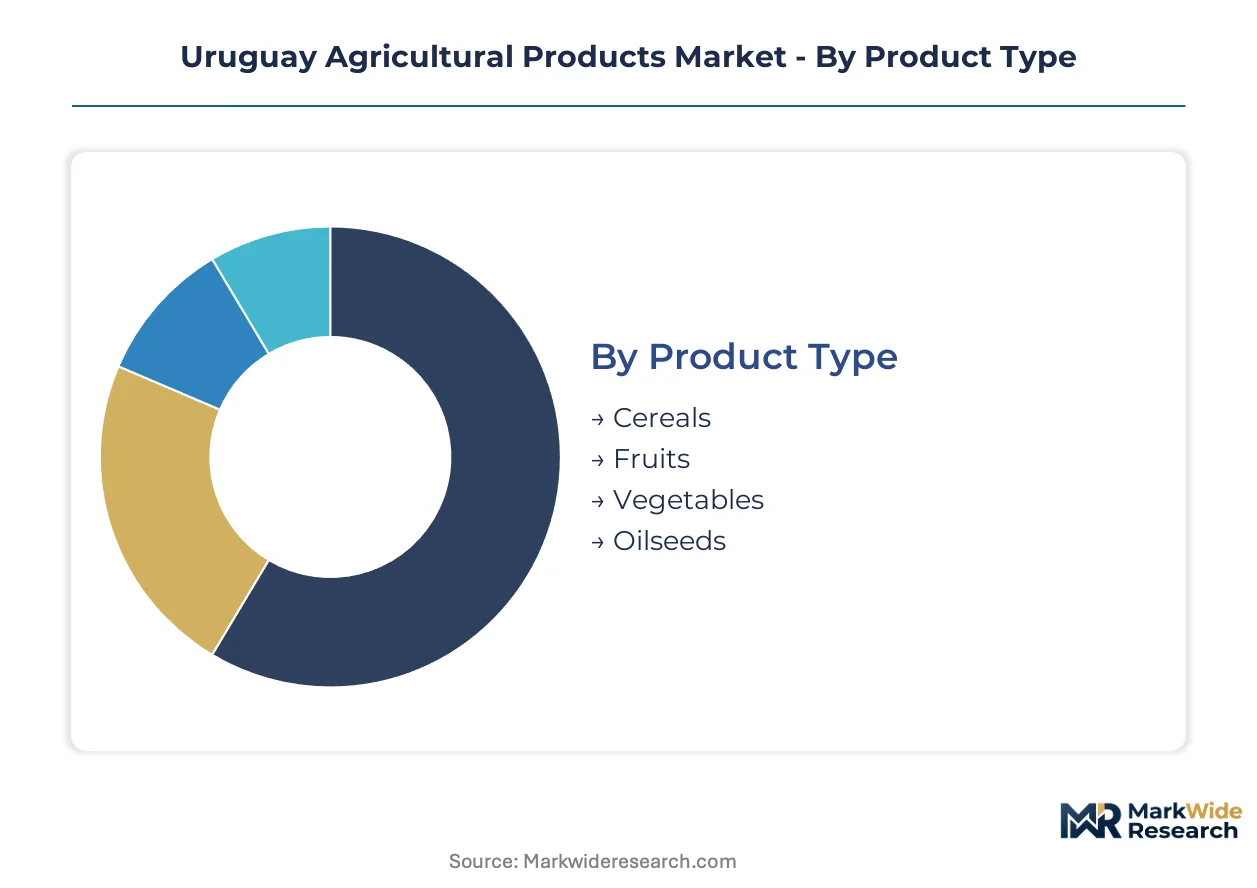
Segmentation reveals how Uruguayan agricultural value pools concentrate across export-grade commodities versus domestic food security crops. Product type and end-use splits expose where traceability investments yield premium access and where price-taking dynamics dominate.
Product Type:
Oilseeds and cereals flow overwhelmingly toward export channels through Montevideo's port complex, while fruits and vegetables serve domestic processors and urban retail.
- Oilseeds:Soybeans dominate planted area with protein and oil specifications graded for crushing efficiency. Export demand from China's feed compounders and EU biodiesel producers shapes varietal selection toward high-oil cultivars.
- Cereals:Wheat and coarse grains supply domestic feed manufacturers and regional flour mills, with milling quality segregated at harvest for price differentiation. MGAP phytosanitary certification unlocks preferential EU wheat import quotas.
- Fruits:Citrus and stone fruits concentrate in northern irrigation districts, supplying Montevideo processors and Mercosur fresh markets.
- Vegetables:Leafy greens and root vegetables circulate through wholesale terminals in Canelones and Montevideo metropolitan markets.
Oilseeds command the established base. The steepest expansion runs through cereals as precision agriculture lifts per-hectare yields across the Pampas belt.
End Use:
Margin structures diverge sharply between captive domestic channels and export-parity pricing, with regulatory compliance costs concentrated in premium protein and biofuel segments.
- Export:Beef and soybean shipments generate the highest unit values through EU and China quota access, requiring MGAP traceability documentation and satellite-verified origin data. EU Deforestation Regulation compliance timelines compress working capital cycles for cattle ranchers.
- Food Processing:Packaged proteins and vegetable oils for regional retail chains represent the most rapidly scaling demand channel, driven by urbanization in Argentina and Brazil.
- Animal Feed:Domestic livestock operations and regional exporters consume soy meal and coarse grains through long-term supply contracts with crushing facilities.
- Biofuels:Local blending mandates create captive offtake for high-oil soybean varieties, with Copagran's crushing infrastructure anchoring feedstock conversion.
Export channels command the established base. Food processing climbs fastest as regional supermarket chains consolidate procurement.
Packaging Type:
Cost structures and handling requirements segment packaging selection, with bulk dominating high-volume grain flows and unitized formats serving quality-differentiated products.
- Bulk:Grain and oilseed exports move through Montevideo's port silos in uncontainerized bulk, minimizing handling costs for standardized grades. Port infrastructure concentration creates single-point vulnerability for these flows.
- Bags:Polypropylene sacks serve domestic feed distributors and small-scale processors requiring inventory flexibility.
- Bales:Hay and forage products compress into standardized bales for livestock operations across the Pampas belt.
- Boxes:Fresh produce and premium cuts utilize corrugated containers for cold-chain integrity in retail distribution.
Bulk formats anchor volume throughput. Boxed packaging gains fastest as supermarket chains impose handling specifications.
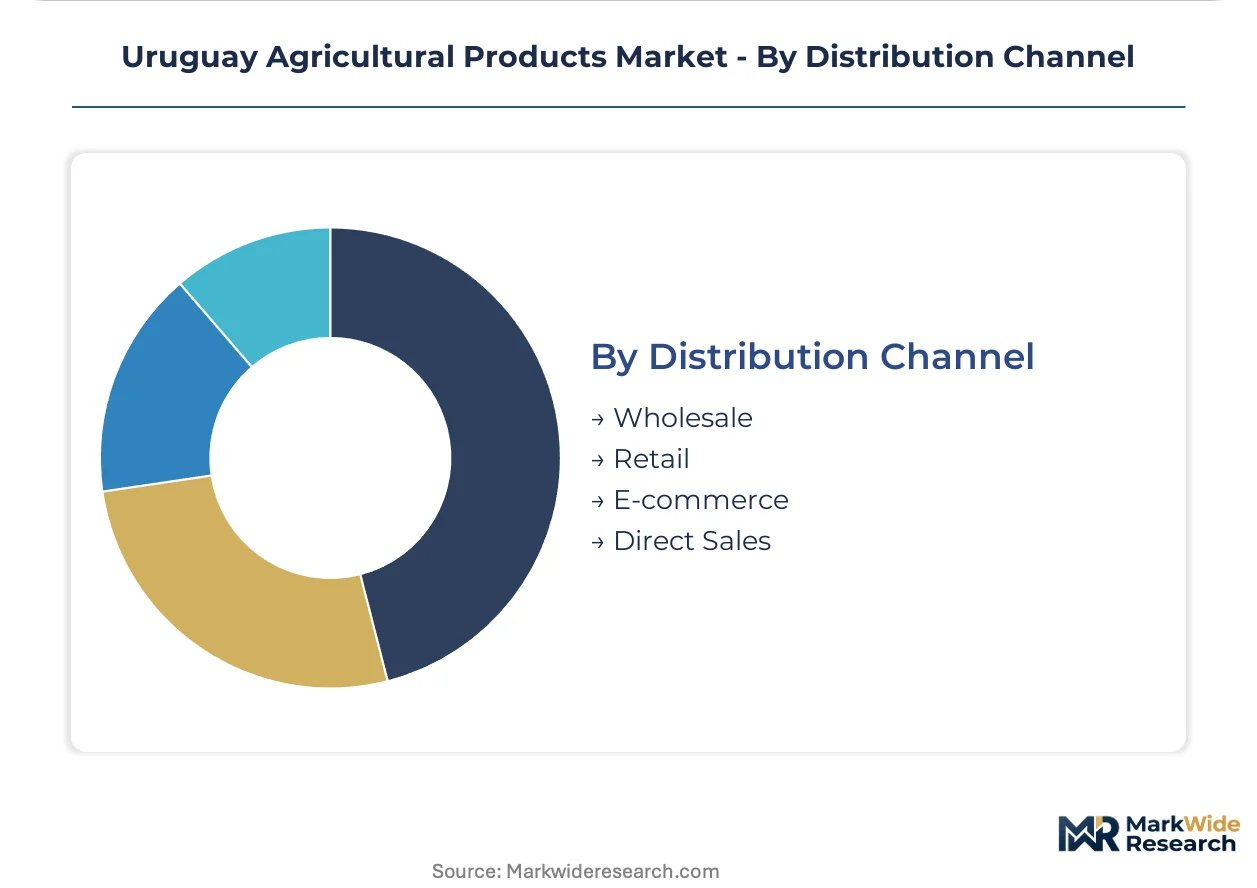
Distribution Channel:
Channel selection reflects buyer scale and information requirements, with direct sales expanding among large producers and digital platforms penetrating mid-tier procurement.
- Wholesale:Traditional grain elevators and livestock auction systems aggregate supply from dispersed producers, concentrating price discovery in Montevideo and regional terminals.
- Direct Sales:Large-scale beef producers bypass auction systems through vertical contracts with Marfrig's cold-chain infrastructure, capturing margin otherwise absorbed by intermediaries.
- Retail:Supermarket chains and independent grocers source packaged proteins and fresh produce through contracted distributors.
- E-commerce:Digital platforms emerge for agricultural inputs and specialty food products, though physical inspection requirements constrain adoption for bulk commodities.
Wholesale channels retain the volume base. Direct sales expand most quickly as traceability systems enable contract bypass of traditional aggregators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MGAP certification protocols anchor Uruguay's export competitiveness, with departmental production zones responding differently to EU traceability mandates and Asian feed demand cycles.
Florida Department
Citrus and dairy operations concentrate in Florida's irrigated districts, supplying Montevideo processors with cold-chain dependent outputs. MGAP's revised water-use permitting under the Santa Lucía River basin management framework extends approval timelines for expansion projects. Producers near Sarandí Grande retrofit irrigation systems to meet stricter volumetric allocation rules.
Salto Department
Beef cattle ranching dominates northern grasslands, with pasture-to-plate traceability systems capturing EU quota premiums. The EU Deforestation Regulation compliance deadlines force rapid digital infrastructure investment across dispersed herd management operations. Ranching cooperatives around Salto city deploy satellite-linked ear tagging to satisfy geolocation verification requirements.
Colonia Department
Grain origination networks converge at Nueva Palmira's river port terminal, creating alternative export capacity outside Montevideo's concentration risk. Cargill's Litoral region sourcing operations anchor soy and wheat flows through this western corridor. Crushing facilities along the Río Uruguay process high-oil soybean varieties for biodiesel feedstock conversion.
Canelones Department
Vegetable production and peri-urban agriculture serve Montevideo's metropolitan wholesale terminals through short distribution channels. The country's national standards body UNIT aligns fresh produce quality benchmarks with Mercosur technical regulations and CODEX references. Greenhouse clusters near Progreso adopt precision climate control to extend growing seasons for leafy greens.
Río Negro Department
Mid-scale crop and livestock mixed farming characterizes this central belt, with precision agriculture adoption lagging larger Pampas operations. Variable-rate technology penetration remains constrained by technical assistance gaps and capital access limitations. Producer cooperatives around Young aggregate equipment-sharing arrangements to overcome individual scale constraints.
Uruguay Agricultural Products Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Uruguay's agricultural value chain. The market structure consolidates around three tiers: multinational grain traders with origination networks, domestic crushing and processing operators with captive infrastructure, and regional livestock integrators with cold-chain control. Strategic moves concentrate on backward integration into primary production and digital traceability system deployment to capture EU compliance premiums.
Among multinational trading houses, Cargill Incorporated and Bunge Limited exemplify the grain origination archetype with Litoral region network density. Marfrig Global Foods S.A. occupies a position within the protein integration tier, while Copagran represents domestic crushing capacity concentration. These three anchors illustrate how competitive positioning separates flow-control players from processing-margin capturers across soy, beef, and biodiesel value chains.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| COFCO International Limited |
| Louis Dreyfus Company B.V. |
| Marfrig Global Foods S.A. |
| Bunge Limited |
| Saman |
| Copagran |
| Barraca Erro |
| Others |
Pricing and Supply Chain Analysis
Soybean oil's displacement of mineral diesel in Uruguay's biodiesel blending mandate is simultaneously shifting crushing capacity toward the western Litoral corridor and compressing feedstock pricing spreads between domestic crushers and export-oriented grain traders. This substitution dynamic concentrates margin capture among operators with integrated origination-to-refining assets while exposing price-taking producers to heightened basis risk at Montevideo's port terminals.
Pricing Analysis
Export-parity spreads between Montevideo and Nueva Palmira port terminals diverge by certification tier, with EU Deforestation Regulation-compliant cattle and soybeans commanding measurable premiums over standard-grade alternatives. Pricing stratifies across premium traceability-verified, standard MGAP-certified, and economy domestic-sale tiers, with differentiation driven by geolocation documentation depth and phytosanitary protocol stringency. Cost compression in the economy tier intensifies as fertilizer import dependency exposes margins to Black Sea supply volatility. Small-scale producers exhibit highest price sensitivity, while integrated operators with crushing or cold-chain assets demonstrate inelastic procurement behavior.
Supply Chain Analysis
Inventory strategy preferences split between just-in-time grain elevator flows for export-grade soybeans and strategic stockpiling of nitrogen fertilizers ahead of Southern Hemisphere planting windows. Geographic supply concentration centers on Argentina, Brazil, and Paraguay for phosphate and urea inputs, with domestic blending capacity negligible. Raw material dependencies encompass Black Sea-origin nitrogen, Moroccan phosphate rock, and Brazilian potash shipments through Paranaguá. Single-point vulnerability concentrates at Montevideo's port silo complex for high-value beef and grain exports. Distribution runs through controlled cold-chain infrastructure for protein flows and bulk terminal aggregation for oilseed and cereal movements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Uruguay's agricultural products market represents an early-cycle expansion story where precision agriculture penetration remains below 25 percent of cultivated area, creating runway for yield-capture investments as satellite-guided input placement diffuses from large-scale Pampas operations toward mid-tier producers.
For Market Incumbents: Consolidate origination networks in the Litoral region through equipment-sharing alliances with mid-scale cooperatives, neutralizing emerging digital agronomy platforms that threaten to disintermediate technical advisory relationships. Prioritize backward integration into irrigation-permitted land banks in Florida and Salto departments ahead of water-use permitting tightening under revised Santa Lucía River basin frameworks.
For New Entrants and Emerging Players: Anchor in Río Negro Department's underserved precision agriculture segment, where equipment-sharing gaps and technical assistance scarcity create penetrable white space for subscription-based remote sensing services. Target mid-scale mixed farming operations with predictive analytics bundles that bypass legacy cooperative advisory channels. Deploy direct-to-processor contracting platforms that replicate Marfrig's vertical integration model for cattle producers outside established cold-chain catchments.
For Investors and Strategic Acquirers: The market sits at a technology-adoption inflection phase that favors infrastructure-heavy operators with traceability system deployment capabilities. Long-term viability over the coming decade rests on regulatory compliance infrastructure rather than commodity cycle timing. Prioritize acquisition targets with deployed satellite-linked herd management or soil mapping assets. Watch for inflection when EU deforestation-free verification costs exceed 8 percent of export unit values, triggering consolidation among non-compliant cattle ranchers.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Agriculture Platform Deployment | Variable-rate technology adoption lifts per-hectare yields across Pampas belt operations. |
| Traceability System Integration | MGAP-aligned satellite verification unlocks EU beef import quota premiums for compliant exporters. |
| Backward Integration into Irrigation Assets | Water-use permitting delays in western zones reward early land-bank positioning under Santa Lucía framework. |
| Biodiesel Feedstock Capacity Expansion | Copagran's crushing infrastructure anchors captive offtake for high-oil soybean varieties under local mandates. |
| Direct-to-Processor Channel Development | Vertical contracts with cold-chain operators bypass traditional auction margin absorption for beef producers. |
Research Methodology
The analysis maps oilseed crushing, cattle processing, precision agriculture services, and export logistics sub-sectors, each validated through grain origination managers, livestock procurement directors, farm equipment distributors, and port terminal operators. Primary intelligence combined structured interviews with cooperative agronomists and biodiesel plant engineers against secondary validation from MGAP certification databases, Mercosur trade flow statistics, and UNIT quality standard filings. Bottom-up acreage and yield estimates triangulated against top-down export value reconstructions from customs documentation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with modeled segmentation spanning product type, end-use channel, packaging format, and departmental production zone. CAGRs derived from trend extrapolation of planted area expansion, yield improvement curves, and export demand elasticity to Chinese feed compounder procurement cycles. Forecast inputs incorporated EU Deforestation Regulation compliance cost trajectories and Santa Lucía River basin water allocation scenarios.
Decision-makers should treat outputs as directional under assumptions of sustained Chinese soy demand and stable MGAP-EU regulatory alignment; material deviation would warrant model refresh. Revision becomes warranted when fertilizer import cost volatility crosses thresholds that trigger acreage abandonment in marginal western zones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Canada Bamboos Market
Agriculture and Agri Products
Alfalfa Market
Agriculture and Agri Products
Brazil Cashew Market
Agriculture and Agri Products
Saudi Arabia Agriculture Market
Agriculture and Agri Products
Netherlands Commercial Greenhouse Market
Agriculture and Agri Products
Sudan Alfalfa Market
Agriculture and Agri Products
Saudi Arabia Alfalfa Market
Agriculture and Agri Products
Rapeseed Oil Market
Agriculture and Agri Products
Forage Feed Market
Agriculture and Agri Products
Sweet Potato Flour Market
Agriculture and Agri Products
Organic Starter-Grower Chicken Feed Market
Agriculture and Agri Products
Netherlands Cashew Market
Agriculture and Agri Products
Tissue Cultured Date Palm Market
Agriculture and Agri Products
Livestock and Meat Market
Agriculture and Agri Products
Forage Market
Agriculture and Agri Products
Organic Quinoa Market