
 Alfalfa Hay Market | 2026-2036
Alfalfa Hay Market Size, Share, and Industry Trends Forecast 2026-2036
Alfalfa Hay Market Intelligence
Aftermarket nutrition consulting is tilting margin pools away from raw bale sales toward value-added feeding programs. Anderson Hay and Grain Inc leverages its Pacific Northwest processing footprint to dominate export-grade supply chains. Standlee Hay Company anchors premium positioning through compressed pellet and cube formats that reduce shipping costs. Al Dahra ACX Global Inc controls Middle Eastern distribution channels, sustaining volume through long-term dairy farm contracts.
Alfalfa hay consists of dried perennial legume forage containing 15-22% crude protein and 25-30% fiber, harvested at early bloom to maximize digestible nutrient density for ruminant livestock. The crop requires well-drained soils with pH above 6.5 and sustained irrigation during summer stress periods to achieve protein targets. Dairy Farmers represent the dominant end-user segment where margin pools concentrate around certified weed-free and low-moisture bales meeting export specifications. Pellets and cubes are accelerating fastest as mechanized feeding systems displace traditional bale handling on large operations. Grass Hay competes on price-sensitive beef backgrounding operations where lower protein requirements permit cheaper forage substitution.
USDA Agricultural Marketing Service sets official grade standards for leafiness, color, and foreign matter that determine export eligibility and price premiums. EPA water-use regulations in California and Idaho constrain acreage expansion, forcing producers toward drip-irrigation efficiency investments. FSSAI import protocols in India and Chinese customs quarantine rules shape market access timing for containerized shipments. Stakeholders must monitor drought-frequency trends and water-right adjudications that threaten productive capacity in the Central Valley and Snake River Plain.
Market Dynamics
Water-right adjudications in the western United States are forcing irrigated acreage consolidation, concentrating production among capitalized operators capable of drip-irrigation infrastructure upgrades. This structural compression reshapes competitive positioning around water security rather than land availability alone.
Growth Catalysts
- Dairy feed ration optimization:Livestock operators in California and Idaho are substituting higher-protein forage for grain concentrates to improve milk yield efficiency and reduce feed-cost volatility.
- USDA grading standardization:Official leafiness and color certifications enable price-premium capture for export-grade bales, accelerating cross-border trade formalization.
- Pellet mechanization:Compressed cube formats reduce shipping cube by 60% versus traditional bales, unlocking containerized export economics to Middle Eastern dairy operations.
Market Restraints
- Input water cost volatility:Colorado River Compact allocations and Snake River Plain aquifer depletion are elevating per-acre irrigation expenses beyond smallholder break-even thresholds.
- Supply geography concentration:Premium-grade output depends on Central Valley and southern Idaho microclimates, creating single-region weather exposure for export-contract fulfillment.
- Grass hay substitution:Beef backgrounding operations in the Great Plains are accepting lower-protein forage when alfalfa premiums exceed ration-budget tolerances.
Strategic Opportunities
- Indian dairy formalization:FSSAI import protocol streamlining is opening containerized shipment windows to cooperative dairy processors in Gujarat and Punjab.
- Precision irrigation convergence:Soil-moisture sensor networks combined with variable-rate drip systems are enabling protein-targeted harvest timing for contract premiums.
- Veterinary nutrition service unbundling:Independent consultants are displacing traditional dealer relationships, creating direct channel access for certified-premium producers.
Industry Challenges
- Certification timeline compression:Weed-free and low-moisture testing protocols add 14-21 days to shipment preparation, constraining just-in-time contract execution.
- Equipment capex intensity:Pelletizing and compression machinery requires seven-figure capital deployment, favoring incumbent processors over grower-owned cooperatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alfalfa Hay Market |
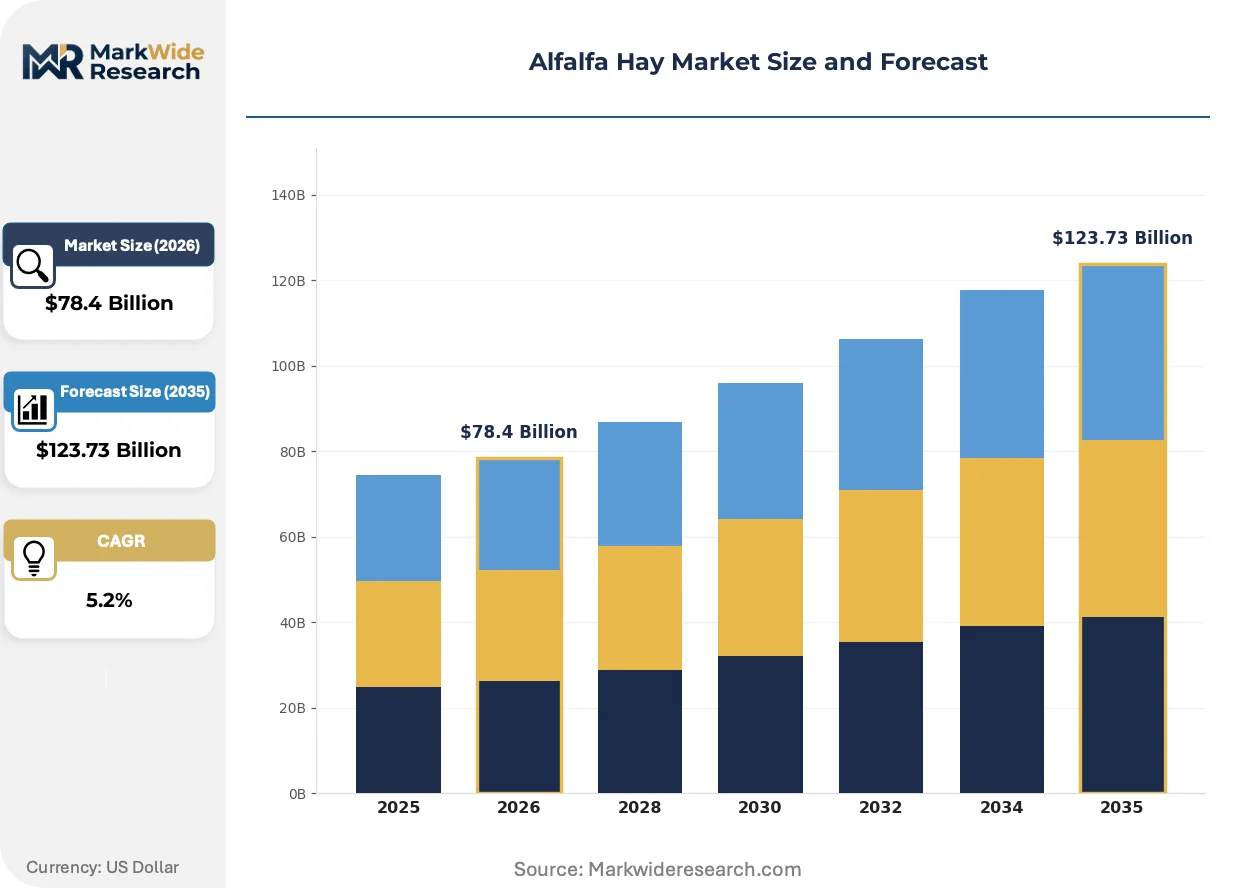
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $123.73 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grass Hay, Legume Hay, Hay Cubes, Pellets End User: Dairy Farmers, Beef Producers, Horse Owners, Pet Owners Packaging Type: Bales, Bags, Loose, Bulk Distribution Channel: Direct Sales, Online Retail, Agricultural Supply Stores, Wholesalers |
| Companies Covered | Anderson Hay and Grain Inc, Al Dahra ACX Global Inc, Alfalfa Monegros SL, Bailey Farms International, Border Valley, Standlee Hay Company, Cubeit Hay Company, Green Prairie International, Haykingdom Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alfalfa Hay Market Strategic Shifts & Innovations
Mechanization of feeding systems and digitization of forage-quality tracking are compressing traditional bale-handling workflows while elevating nutritional precision in large dairy operations.
Spectral analysis technology deployed at receiving stations is digitizing real-time crude-protein and fiber-content verification. Large integrated dairies in the San Joaquin Valley are adopting these systems at feed-mixing facilities to replace laboratory send-out delays. This capability is digitizing payment settlement cycles from 30-day invoice terms to load-by-load quality-adjusted pricing.
EPA water-use efficiency mandates under the Clean Water Act are accelerating drip-irrigation retrofits across California's Central Valley. Producers face 20% consumptive-use reduction targets by 2028, forcing capital deployment into pressure-compensating emitter systems. The regulation most affects premium-grade growers dependent on flood-irrigation legacy infrastructure.
Consolidated procurement by 500-plus-cow dairies is displacing spot-market bale purchases with annual volume contracts tied to certified quality tiers. Large operators in the Midwest are integrating nutrition consultants into buying committees, shifting supplier selection criteria from price-per-ton to milk-yield-per-dollar-of-feed. This pattern concentrates most visibly in Wisconsin and New York states where cooperative processing infrastructure supports scale.
Alfalfa Hay Market Segmentation
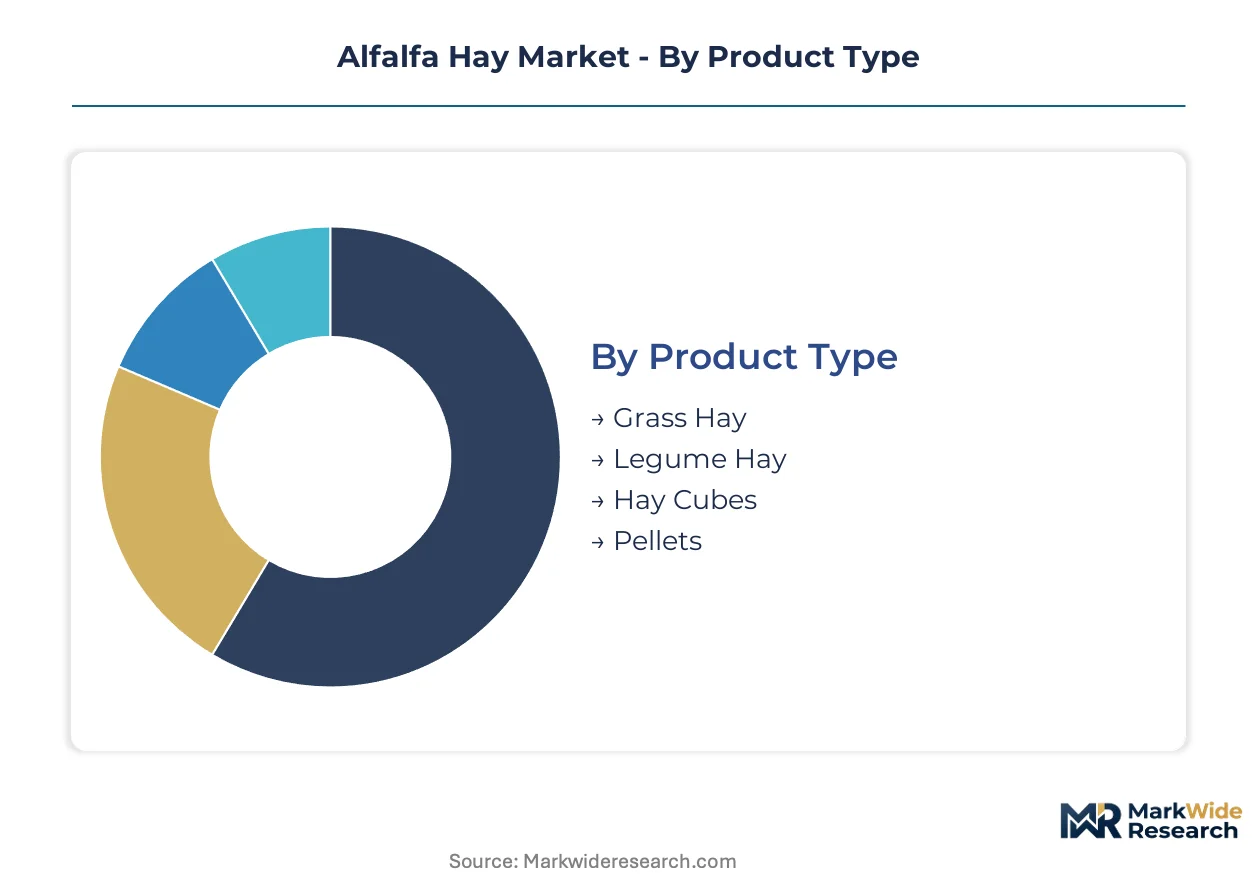
Alfalfa hay segmentation reflects divergent handling economics across livestock operation scales, packaging formats, and procurement channels. Product form decisions cascade through storage requirements, feeding labor, and transport cost structures that separate commodity hay from value-added nutrition solutions.
Product Type:
The use-case spectrum spans grazing-quality roughage through precision-formulated feed additives, with physical form determining mechanization compatibility and nutrient preservation.
- Grass Hay:Lower crude protein (8-12%) and higher fiber content suit beef backgrounding operations where cost-per-pound of gain outweighs milk-yield optimization. Demand concentrates in Great Plains feedlots substituting grass hay when alfalfa premiums exceed ration-budget thresholds.
- Legume Hay:Alfalfa and clover varieties deliver 15-22% crude protein with superior digestible energy density for high-producing dairy rations. California and Idaho dairies anchor volume demand, with certified weed-free grades commanding export premiums to Middle Eastern markets.
- Hay Cubes:Compressed format reduces shipping volume by 60% versus traditional bales, enabling containerized export to automated feeding systems. Al Dahra ACX Global Inc leverages long-term dairy contracts across UAE and Saudi Arabia to sustain throughput.
- Pellets:Fine-ground and extruded format maximizes nutrient uniformity for precision TMR mixing in 500-plus-cow operations. Standlee Hay Company anchors premium positioning through compressed pellet supply chains serving mechanized Midwest dairies.
Established volume favors Legume Hay; emerging adoption favors Pellets.
End User:
Customer scale and production intensity separate spot-market purchasers from contract-anchored volume buyers with embedded nutrition consulting relationships.
- Dairy Farmers:High-producing herds (30+ liters daily) require consistent protein density to maintain milk yield efficiency. California Central Valley and southern Idaho operations dominate procurement, with certified low-moisture bales tied to annual volume contracts replacing spot-market purchases.
- Beef Producers:Backgrounding and finishing operations prioritize cost-per-pound of gain over protein density, accepting grass-legume blends when price spreads compress. Great Plains feedlots exhibit seasonal substitution patterns responsive to alfalfa premium volatility.
- Horse Owners:Equine operations demand dust-free, leaf-retentive grades with controlled NSC levels for metabolic-sensitive animals. Premium pricing tolerance supports small-bale and bagged formats despite higher per-pound handling costs.
- Pet Owners:Small-mammal and rabbit keepers drive demand for boutique-packaged, laboratory-tested hay with guaranteed analysis labels. Online retail channels capture this fragmented, specification-sensitive segment.
Contract concentration favors Dairy Farmers; margin expansion favors Horse Owners.
Packaging Type:
Handling labor and storage infrastructure requirements separate manual-feeding operations from automated systems with capital-intensive material-handling equipment.
- Bales:Traditional three-tie and large-square formats dominate on-farm storage with tarp-covered outdoor stacks. USDA leafiness and color grading determines export eligibility for premium-grade California and Idaho production.
- Bags:Retail-format packaging serves horse owners and pet keepers requiring weather-protected, vermin-resistant storage in limited-space facilities. Compression technology enables 50-pound bags with bale-equivalent density.
- Loose:Chopped and unpressed hay supports TMR mixing in large dairies with dedicated mixer wagons, eliminating manual bale-breaking labor. Moisture management challenges constrain geographic distribution radius.
- Bulk:Pneumatic or conveyor-delivered loose hay serves integrated feed mills and large calf-raising operations with silo storage infrastructure. Volume discounts reflect elimination of packaging material and compression capital costs.
Mechanization tailwinds favor Bulk; retail channel access favors Bags.
Distribution Channel:
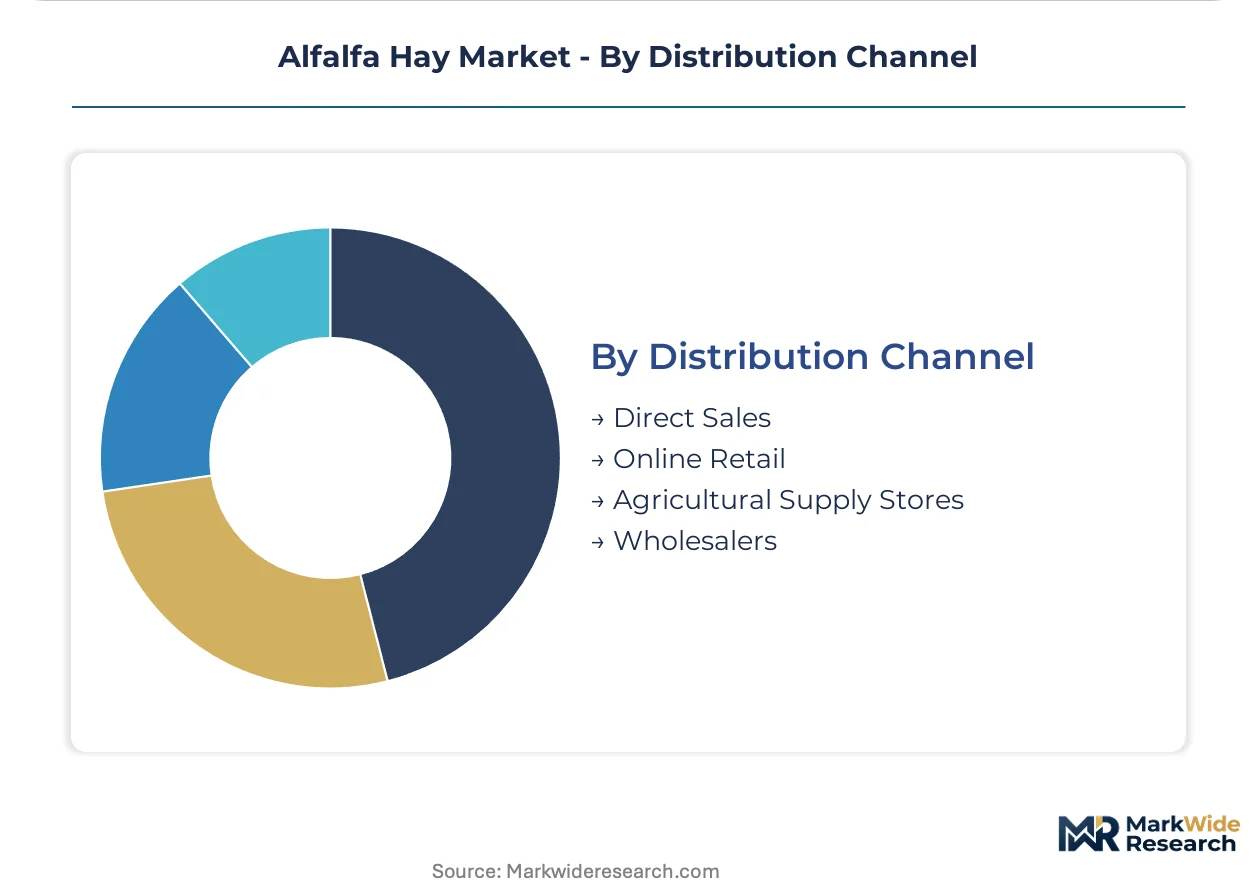
Procurement authority consolidation among large operators is displacing traditional dealer relationships with direct manufacturer connections and nutrition-consultant-mediated selection.
- Direct Sales:Annual volume contracts between growers and 500-plus-cow dairies eliminate intermediary margins while enabling quality-tier pricing. Anderson Hay and Grain Inc leverages Pacific Northwest processing footprint to dominate export-grade direct supply chains.
- Online Retail:E-commerce platforms capture horse owner and pet keeper segments with guaranteed analysis transparency and subscription delivery models. Bagged and compressed formats optimize parcel-shipping economics.
- Agricultural Supply Stores:Regional dealer networks maintain local inventory for mid-scale beef producers and hobby farms with irregular purchase timing. Credit terms and delivery services sustain channel relevance despite price premiums.
- Wholesalers:Container consolidation and export documentation services bridge domestic growers to FSSAI-regulated Indian and Chinese customs quarantine requirements. Long certification timelines (14-21 days) favor established wholesaler relationships over spot transactions.
Scale concentration favors Direct Sales; specification transparency favors Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: Middle Eastern dairies import compressed cubes for mechanized feeding, while American operations favor bulk loose formats for TMR integration, and European buyers prioritize certified organic grades for niche equine markets.
United States
California Central Valley dairies drive premium-grade demand through annual volume contracts tied to milk-yield efficiency targets. EPA water-use regulations under the Clean Water Act mandate 20% consumptive-use reductions by 2028, forcing drip-irrigation capital deployment. Southern Idaho's Snake River Plain sustains year-round production through aquifer-fed center-pivot systems serving export certification facilities.
China
Dairy herd expansion in Hebei and Inner Mongolia provinces generates containerized import demand for low-moisture certified bales. SAMR quarantine protocols and GB standards for foreign matter content extend customs clearance timelines, favoring established wholesaler relationships over spot transactions. Tianjin Port consolidation hubs coordinate redistribution to northeastern processing cooperatives.
Saudi Arabia
Heat-stressed indigenous dairy operations rely on imported cubes and pellets for automated feeding systems in Riyadh and Eastern Province clusters. SFDA import documentation requirements align with long-term supply contracts that Al Dahra ACX Global Inc maintains across UAE and Saudi distribution channels. Jeddah Islamic Port handles bulk container throughput for central kingdom feed mills.
India
Cooperative dairy processors in Gujarat and Punjab states are formalizing procurement through FSSAI-import-protocol streamlining for containerized alfalfa shipments. NDDB-supported milk unions in Anand and Ludhiana districts trial precision-ration formulations to boost buffalo milk yields above 8 liters daily. Mumbai Nava Sheva Port serves as primary customs entry point for Middle Eastern re-exports.
Spain
Arid-zone dairy operations in Aragon and Castilla-La Mancha substitute imported legume hay for degraded native pasture. EFSA feed hygiene regulations and drought-frequency adaptation programs concentrate demand around Zaragoza logistics corridors. Barcelona Port mediates transshipment to North African markets through established Maghreb trade lanes.
Alfalfa Hay Market Key Industry Players
Capability concentration sits with processing specialists commanding pelletizing infrastructure; scale advantage sits with integrated growers controlling irrigated acreage and export certification workflows. The market structures around three archetypes: Pacific Northwest processors with containerized export dominance, compressed-format specialists serving automated dairy systems, and Middle Eastern distributors anchoring long-term contract volumes. Competitive moves center on backward integration into captive hay production and geographic expansion through port-proximate consolidation facilities.
Among Pacific Northwest operators, Anderson Hay and Grain Inc exemplifies the export-processor archetype through its irrigated-acreage and container-loading infrastructure. Standlee Hay Company occupies the compressed-format premium tier, representing mechanized-feeding-system compatibility. Al Dahra ACX Global Inc anchors Middle Eastern distribution control, sitting within the long-term-contract logistics archetype that sustains volume through dairy-farm relationships.
| Leading Market Players |
|---|
| Anderson Hay and Grain Inc |
| Al Dahra ACX Global Inc |
| Alfalfa Monegros SL |
| Bailey Farms International |
| Border Valley |
| Standlee Hay Company |
| Cubeit Hay Company |
| Green Prairie International |
| Haykingdom Inc |
| Others |
Cost & Logistics Intelligence
California's Central Valley irrigation districts anchor premium-grade capacity, and their drip-retrofit cost trajectories determine which growers capture protein-premium pricing power versus exiting to lower-value crop rotations. Water-right scarcity concentrates bargaining leverage among capitalized operators with metered aquifer access, compressing margins for flood-irrigation legacy producers.
Pricing Analysis
Long-term offtake contracts dominate volume flows, with annual agreements between 500-plus-cow dairies and certified growers replacing spot-market purchases. Pricing stratifies across premium, standard, and economy tiers based on USDA leafiness grades and weed-free certification status. Cost compression in standard-grade bales is intensifying because Snake River Plain water adjudications are elevating per-acre irrigation expenses. Beef backgrounding operations in the Great Plains exhibit highest price sensitivity, while export-grade buyers in Saudi Arabia and China tolerate premiums for low-moisture certified product.
Supply Chain Analysis
USDA phytosanitary export controls and SAMR quarantine protocols in China constrain containerized shipment velocity, extending certification-to-delivery timelines. Geographic supply concentration centers on the United States, Spain, and Australia, with California and Idaho drawing from Snake River Plain aquifer systems and Central Valley surface-water allocations. Raw material dependencies include drip-irrigation equipment, fertilizer inputs, and baling twine. Single-region weather exposure in the Central Valley creates fulfillment risk for export contracts. Distribution runs through Pacific Northwest port consolidation facilities serving Middle Eastern and Asian dairy operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Alfalfa hay sits in early-cycle expansion as mechanized feeding systems displace traditional bale handling across 500-plus-cow operations, accelerating pellet and cube format penetration beyond historical growth trajectories.
For Market Incumbents: Pre-empt grass hay substitution in beef backgrounding by backward integration into precision-irrigation acreage in southern Idaho, securing protein-targeted harvest timing for contract premiums. Defend against compressed-format specialists by investing in pelletizing infrastructure or exclusive supply agreements with Standlee Hay Company-tier processors. Channel control through veterinary nutrition consultant relationships offers margin protection against dealer displacement. For New Entrants and Emerging Players: Gujarat and Punjab dairy cooperatives present underpenetrated procurement formalization, with FSSAI import protocol streamlining enabling direct containerized shipments bypassing established wholesaler markups. Target horse owner segments through dust-free, NSC-controlled bagged formats sold via subscription e-commerce, capturing premium pricing tolerance absent in commodity bale markets. Go-to-market leverage rests on guaranteed analysis transparency and parcel-shipping optimization. For Investors and Strategic Acquirers: Long-term, this sits as a water-security infrastructure play because EPA-mandated consumptive-use reductions force capital deployment into drip-irrigation retrofits that concentrate production among capitalized operators. Acquisition targets should emphasize irrigated-acreage control with metered aquifer access and export certification workflows. The signal to watch is drought-frequency trends in the Central Valley and Snake River Plain adjudication rulings that accelerate acreage consolidation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Hay Production | Anderson Hay-style acreage control secures protein consistency for export-grade certification. |
| Pelletizing Infrastructure Deployment | Compression capital enables 60% shipping cube reduction for Middle Eastern mechanized dairies. |
| Long-term Supply Agreement with Dairy Cooperatives | Al Dahra ACX Global Inc's UAE and Saudi contracts demonstrate volume stability through relationship lock-in. |
| Precision Irrigation Technology Integration | Soil-moisture sensor networks enable protein-targeted harvest timing for premium-tier pricing. |
| Direct E-commerce Channel Development | Online retail captures horse owner and pet keeper segments with specification transparency. |
Research Approach
A standing panel of dairy nutrition consultants, hay grower cooperative managers, export logistics coordinators, and USDA Agricultural Marketing Service certification officers provided ongoing calibration across the study period. Primary interviews with large-herd dairy operators in California and Idaho, Middle Eastern feed mill procurement heads, and Indian cooperative dairy processors combined with secondary validation from USDA crop production reports, FSSAI import protocol documentation, EPA water-use filings, and customs containerized shipment records. Bottom-up acreage and yield estimates triangulated against top-down consumption modeling across end-use segments.
Scenario-bracketing around drought-frequency projections and water-right adjudication timelines shaped volume and value outputs across the projection horizon. Segmentation dimensions modeled include product form (bales, cubes, pellets, loose), end-use intensity (dairy, beef, equine, pet), packaging type, and distribution channel structure. CAGRs derived from historical consumption elasticity to dairy herd expansion and protein-premium capture rates, with irrigation cost inflation and EPA regulatory compliance spend as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by drip-irrigation equipment suppliers or compressed-format specialists would shift outcomes beyond modeled ranges. Material shifts in Colorado River Compact allocations, SAMR quarantine enforcement intensity, or FSSAI import protocol streamlining timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Swine Feed Premix Market
Agriculture and Agri Products
Clover Leaf Oil Market
Agriculture and Agri Products
North America Bonsai Market
Agriculture and Agri Products
Global Guayusa Market
Agriculture and Agri Products
North America Aloe Vera Market
Agriculture and Agri Products
Germany Animal Protein Market
Agriculture and Agri Products
India Palm Oil Market
Agriculture and Agri Products
Cashew Market
Agriculture and Agri Products
Black Sapote Market
Agriculture and Agri Products
Rice Straw Market
Agriculture and Agri Products
Oman Agriculture Market
Agriculture and Agri Products
High Fiber Feed Market
Agriculture and Agri Products
Seaweed Algae Market
Agriculture and Agri Products
Poultry Fat Market
Agriculture and Agri Products
United Kingdom Animal Protein Market
Agriculture and Agri Products
Specialty Egg Market