
 Germany Compound Feed Market | 2026-2036
Germany Compound Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Compound Feed Market Foresight
German compound feed milling capacity is restructuring around fewer, larger production sites in the northwestern grain belt. Deutsche Tiernahrung Cremer GmbH & Co. KG leverages its Baltic Sea port access to sustain competitive grain procurement. Agravis Raiffeisen AG anchors farmer-owned cooperative supply through vertically integrated crushing and blending assets. Rothkötter Mischfutterwerk specializes in precision-formulated swine diets for Lower Saxony's contract-finishing operations.
Germany compound feed denotes nutritionally complete rations manufactured by grinding, mixing, and pelleting cereal grains with protein meals, vitamins, minerals, and functional additives to meet species-specific metabolizable energy and amino acid requirements for commercial livestock production. Pellet form dominates industrial-scale poultry and pig operations due to reduced feed wastage and improved feed conversion ratios compared with mash alternatives. Cereal grains and protein meals constitute the bulk ingredient base, though additive-infused premium blends capture disproportionate margin pools as antibiotic-free and gut-health formulations expand. Direct sales and cooperative channels control the majority of volume flows, locking in grower-commitment contracts that insulate compounders from spot commodity volatility.
The EU Green Deal's Farm to Fork strategy, enforced through EFSA feed safety standards and national KBA-aligned transport regulations, mandates deforestation-free soy sourcing and tightened mycotoxin thresholds that reshape formulation costs and supplier qualification. Germany's Federal Ministry of Food and Agriculture (BMEL) implements the national Fertilizer Ordinance and animal welfare labeling rules that cascade into feed ration specifications for reduced crude protein and phased-in group housing. Stakeholders must monitor Brussels' ongoing revision of the EU Protein Strategy and Berlin's biogas feedstock competition for domestic grain flows.
Market Dynamics
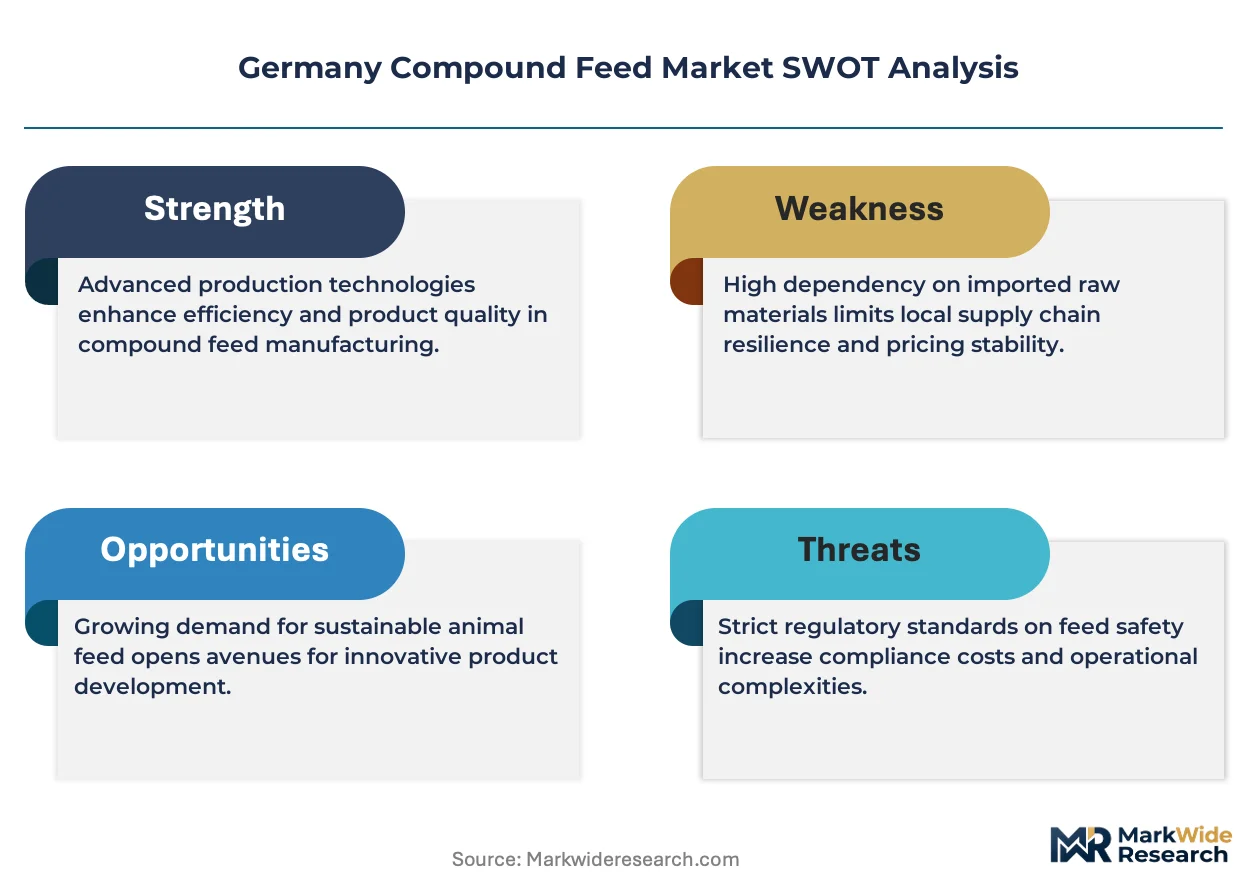
EU Green Deal enforcement through EFSA feed safety standards is compressing formulation flexibility while elevating compliance costs across German compound feed operations.
Growth Catalysts
- Lower Saxony livestock density:Concentrated pig and poultry finishing operations in Germany's northwestern corridor sustain volume throughput for regional millers.
- Deforestation-free soy mandates:EU Green Deal sourcing rules accelerate supplier qualification investments that lock in premium contract channels.
- Pelleting technology diffusion:Industrial-scale pig and poultry operations adopt pellet systems that reduce feed wastage and improve conversion efficiency.
Market Restraints
- Grain procurement volatility:Baltic Sea port dependency exposes compounders to Black Sea supply disruptions and currency fluctuations.
- Crude protein reduction mandates:BMEL Fertilizer Ordinance enforcement tightens nitrogen excretion limits that constrain high-performance diet formulation.
- Biogas feedstock competition:Domestic grain diversion to anaerobic digestion facilities reduces local cereal availability for feed milling.
Strategic Opportunities
- Antibiotic-free formulation premium:Gut-health additive blends capture margin pools as livestock producers phase out growth-promoting antibiotics.
- Cooperative direct sales expansion:Farmer-owned supply channels deepen grower-commitment contracts that insulate compounders from spot commodity swings.
- Group housing transition services:BMEL animal welfare labeling rules create advisory revenue streams for ration reformulation around phased housing changes.
Industry Challenges
- Mycotoxin testing capacity:Tightened EFSA thresholds strain laboratory throughput and extend batch release timelines.
- Precision nutrition skill gaps:Formulation chemistry expertise shortages slow adoption of metabolizable energy optimization software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Compound Feed Market |
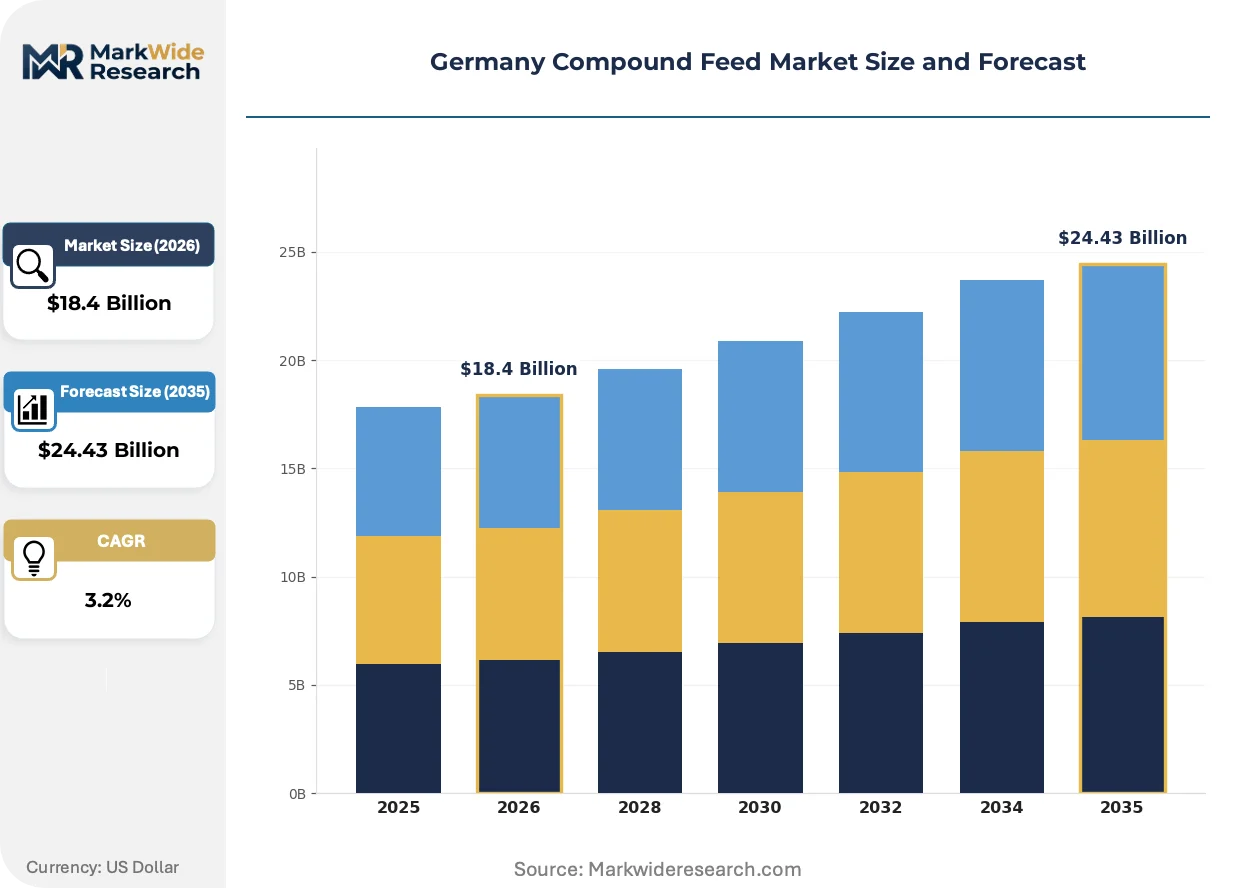
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $24.43 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Animal Type: Poultry, Swine, Ruminants, Aquatic Species, Pets Form: Pellets, Mash, Crumble, Powder, Extruded Ingredient Composition: Cereal Grains, Protein Meals, Vitamins & Minerals, Additives, Fats & Oils Distribution Channel: Direct Sales, Distributors, Online Platforms, Cooperatives, Retail Feed Stores |
| Companies Covered | Archer Daniels Midland Company, BayWa AG, ForFarmers N.V., HaGe Kiel, Deutsche Tiernahrung Cremer GmbH & Co. KG, Agravis Raiffeisen AG, Nutreco N.V., Rothkötter Mischfutterwerk, Cargill Incorporated, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Compound Feed Market Shifts & Advancements
Digital feed formulation platforms and alternative protein sourcing are restructuring how German compounders balance cost, compliance, and performance specifications.
Near-infrared spectroscopy is automating real-time ingredient quality assessment at mill intake points. Large cooperative compounders deploy these systems to verify protein and moisture content without offline laboratory delays. This technology is automating batch consistency enforcement that previously required manual sampling protocols.
EU Protein Strategy revision is redirecting research funding toward domestic legume cultivation and insect meal authorization pathways. German compounders face reformulation complexity as imported soy dependency comes under political pressure. Pig feed segments are responding fastest, testing fava bean and rapeseed meal substitutions in grower-finisher diets.
Contract-finishing consolidation is compressing procurement decision cycles from annual to quarterly terms. Lower Saxony pig operations now demand price-adjustment clauses tied to slaughter weight indices rather than fixed forward contracts. This shift is most visible among integrated pork processors operating company-owned finishing barns.
Germany Compound Feed Market Segmentation
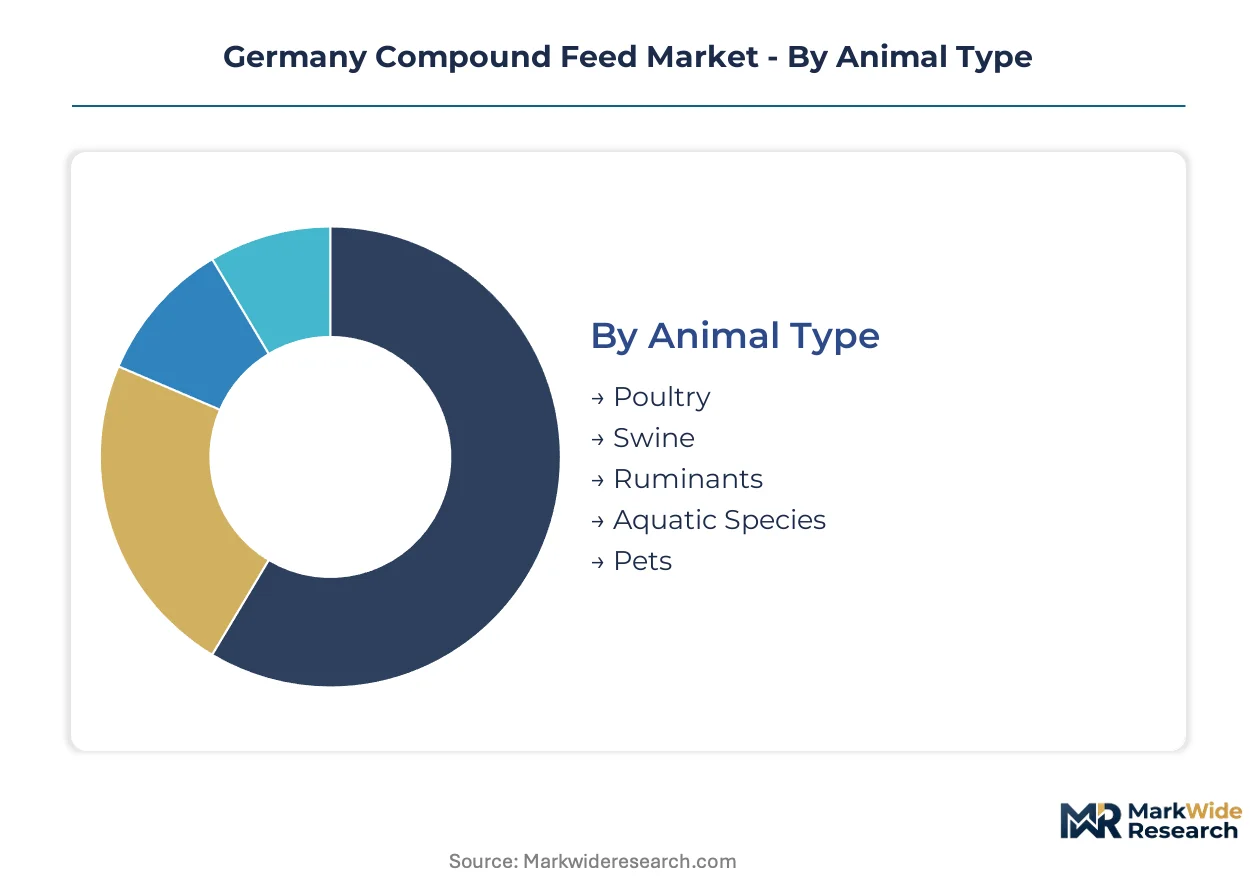
Feed form and species-specific formulation drive distinct manufacturing investments and margin structures across German compound feed operations. Procurement patterns and regulatory compliance requirements fragment differently across each segmentation axis.
Animal Type:
Species-specific metabolizable energy and amino acid specifications determine grinding, pelleting, and additive blending configurations.
- Swine:Precision-formulated grower-finisher diets dominate volume throughput in Lower Saxony's contract-finishing corridor. Herd stabilization sustains demand for high-energy rations with phased crude protein reduction under BMEL Fertilizer Ordinance enforcement.
- Poultry:Broiler and layer operations require uniform pellet geometry for automated feeding systems. EFSA mycotoxin thresholds strain batch release timelines for this segment's high-throughput mills.
- Ruminants:Dairy and beef cattle rations emphasize fiber digestibility and bypass protein protection. Regional grass silage variability demands customized mineral supplementation across Bavarian and Baden-Württemberg grazing districts.
- Aquatic Species:Extruded floating feeds for trout and carp operations require specialized thermal processing. Domestic production remains limited compared with livestock feed scale.
- Pets:Premium kibble and extruded formulations serve companion animal retail channels. Additive-infused gut-health blends capture disproportionate margin pools in this segment.
Mature deployment sits with Swine. Newer deployment is concentrated in Pets.
Form:
Physical feed structure determines wastage rates, storage stability, and mechanized handling compatibility across farm types.
- Pellets:Compressed cylindrical forms reduce dust losses and improve feed conversion ratios in automated pig and poultry systems. Pelleting technology diffusion accelerates among industrial-scale Lower Saxony operations.
- Mash:Ground and mixed but unprocessed meals serve ruminant self-feeders and smaller livestock holdings. Higher wastage rates and segregation during transport constrain adoption in large finishing units.
- Crumble:Broken pellet fragments bridge mash and pellet textures for young animal starter diets. Nursery pig and broiler chick operations specify crumble for palatability during early growth phases.
- Powder:Fine-ground meals support milk replacer and premix applications. Vitamin and mineral micro-premixes require powder consistency for homogeneous distribution.
- Extruded:High-pressure thermal processing gelatinizes starches for aquatic feeds and pet food. Energy-intensive production limits extrusion to higher-margin specialty applications.
Volume concentration favors Pellets. Margin expansion is strongest in Extruded.
Ingredient Composition:
Raw material sourcing strategies and formulation chemistry differentiate cost positions and regulatory compliance burdens.
- Cereal Grains:Wheat, barley, and maize provide metabolizable energy foundations. Baltic Sea port access shapes competitive procurement for northwestern millers facing biogas feedstock competition.
- Protein Meals:Soybean and rapeseed meals supply essential amino acid profiles. EU Green Deal deforestation-free sourcing mandates accelerate supplier qualification investments.
- Vitamins & Minerals:Micro-nutrient premixes ensure species-specific nutritional adequacy. Laboratory verification capacity strains under tightened EFSA batch testing requirements.
- Additives:Enzymes, probiotics, and acidifiers enable antibiotic-free performance claims. Gut-health formulation premiums expand as growth-promoting antibiotic phase-out progresses.
- Fats & Oils:Energy-dense lipid sources improve palatability and dust control. Rendered animal fats and vegetable oils compete on price and oxidation stability specifications.
Cost pressure concentrates in Cereal Grains. Value capture is expanding most quickly in Additives.
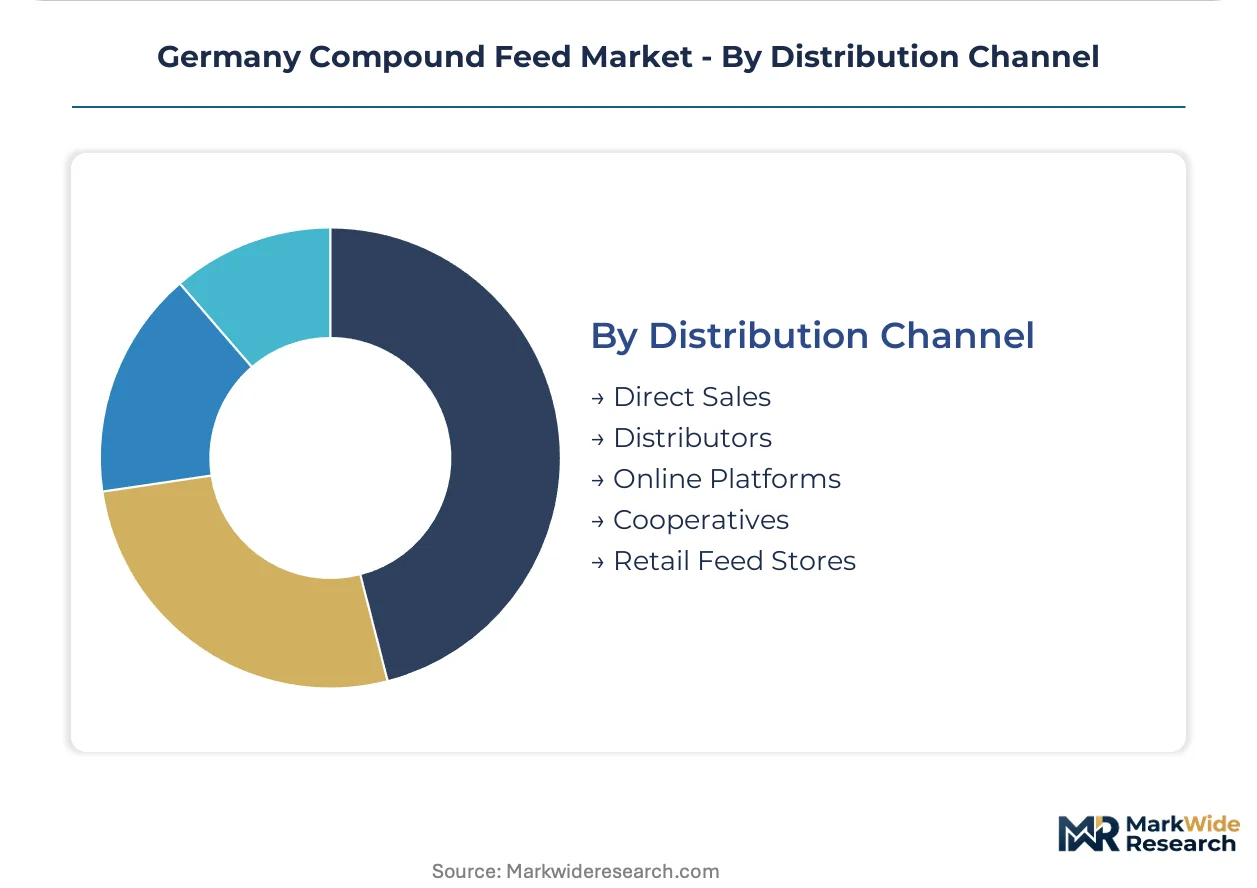
Distribution Channel:
Channel structure determines grower commitment depth and exposure to commodity price volatility.
- Direct Sales:Miller-to-producer contracts lock in volume commitments and insulate compounders from spot market swings. Integrated pork processors operating company-owned finishing barns favor direct procurement.
- Cooperatives:Farmer-owned supply channels anchor regional market share through crushing and blending asset control. Agravis Raiffeisen AG structures dominate northwestern grain belt distribution.
- Distributors:Independent wholesalers serve fragmented smaller holdings outside dense livestock corridors. Inventory carrying costs and credit terms constrain distributor margins.
- Retail Feed Stores:Bagged product sales support hobby farmers and equine operations. Higher per-unit margins offset lower volume throughput.
- Online Platforms:Digital ordering and delivery scheduling penetrate pet food and specialty additive segments. Traceability documentation requirements complicate bulk feed e-commerce adoption.
Volume leadership rests with Direct Sales. Digital penetration is climbing the fastest in Online Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baltic Sea port infrastructure anchors northwestern Germany's competitive grain procurement, while the northwestern grain belt concentrates milling capacity around fewer, larger production sites.
Lower Saxony
Contract-finishing pig operations sustain volume throughput for regional millers. BMEL Fertilizer Ordinance enforcement tightens nitrogen excretion limits that constrain high-performance diet formulation. The dense livestock corridor between Oldenburg and Osnabrück houses precision-formulated swine diet specialists serving integrated pork processors.
North Rhine-Westphalia
Dairy and beef cattle rations emphasize fiber digestibility across grazing districts. KBA-aligned transport regulations cascade into feed logistics specifications for cross-border ingredient flows. The Münsterland region maintains customized mineral supplementation services for grass silage variability.
Bavaria
Regional grass silage variability demands customized mineral supplementation across dairy operations. The national Fertilizer Ordinance reduces crude protein specifications for rations. The Allgäu alpine dairy cluster sustains demand for bypass protein protection formulations.
Baden-Württemberg
Specialized extruded feeds for trout and carp operations require thermal processing capabilities. EFSA feed safety standards mandate tightened mycotoxin thresholds that strain batch release timelines. The Lake Constance aquaculture zone anchors limited but technically sophisticated feed production.
Hamburg
Baltic Sea port access sustains competitive grain procurement for compounders facing Black Sea supply disruptions. Biogas feedstock competition diverts domestic grain flows from feed milling. The harbor district facilitates deforestation-free soy import channels under EU Green Deal sourcing rules.
Germany Compound Feed Market Competitive Landscape
Global majors compete with regional champions across sourcing networks and farmer-owned cooperative channels. The vendor base clusters around three strategic tiers: multinational agribusiness conglomerates with integrated trading arms, farmer-owned cooperatives controlling crushing and blending assets, and specialized regional compounders focused on species-specific formulations. Dominant competitive moves include cooperative direct sales expansion and precision nutrition technology licensing.
Within the cooperative tier, Agravis Raiffeisen AG and Deutsche Tiernahrung Cremer GmbH & Co. KG exemplify farmer-owned supply structures that anchor regional market share. Rothkötter Mischfutterwerk occupies a position among specialized regional compounders focused on precision-formulated swine diets. These three entities represent distinct archetypes: cooperative crushing and blending control, port-advantaged grain procurement, and contract-finishing operational specialization.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| BayWa AG |
| ForFarmers N.V. |
| HaGe Kiel |
| Deutsche Tiernahrung Cremer GmbH & Co. KG |
| Agravis Raiffeisen AG |
| Nutreco N.V. |
| Rothkötter Mischfutterwerk |
| Cargill Incorporated |
| Others |
Supply & Pricing Matrix
Chicago Board of Trade wheat futures volatility cascades through Baltic Sea port procurement into three-tier pricing structure across premium, standard, and economy levels for German compound feed buyers. The northwestern grain belt's milling concentration amplifies this transmission, as port-advantaged compounders pass through currency-adjusted grain costs while inland operators absorb logistics premiums.
Pricing Analysis
Service-bundling separates ration formulation advisory from unbundled commodity supply, with precision nutrition packages commanding premiums over standard mash deliveries. Price differentiation hinges on EFSA compliance certification tier and volume commitment scale, with integrated pork processors locking in quarterly adjustment clauses tied to slaughter weight indices. Cost compression in standard-tier poultry feed is intensifying because of mycotoxin testing capacity bottlenecks. Smallholder ruminant operations show highest price sensitivity; contract-finishing pig units demonstrate lowest sensitivity due to feed conversion ratio guarantees.
Supply Chain Analysis
Regional distribution centers in Hamburg, Bremen, and Rostock form a hub-and-spoke pattern radiating into Lower Saxony's livestock corridor. Supply draws from Ukraine, Brazil, and Argentina for protein meals, with domestic wheat and barley from Schleswig-Holstein. Single-source vulnerability concentrates in deforestation-free soy qualification channels. Distribution runs through farmer-owned cooperative crushing assets and direct miller-to-producer contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German compound feed operates as a vertical-integration race, with upstream grain procurement control and downstream grower-commitment contracts as the decisive levers separating margin leaders from price-takers.
For Market Incumbents: Lock in Baltic Sea port access through long-term terminal agreements that insulate against Black Sea disruption, while deepening cooperative crushing asset control to defend against multinational trading house encroachment. BMEL Fertilizer Ordinance crude protein mandates threaten formulation margins; respond with precision nutrition software licensing to capture advisory revenue streams. For New Entrants and Emerging Players: Begin with antibiotic-free additive formulation services for mid-scale Lower Saxony contract-finishers, the most penetrable segment given incumbent blind spots in gut-health premix customization. Digital feed formulation platforms offer a direct go-to-market angle that bypasses cooperative channel gatekeeping. For Investors and Strategic Acquirers: Distressed-cycle entries favor port-advantaged regional compounders in Hamburg and Rostok with underutilized pelleting capacity and existing EFSA supplier qualification. Long-term viability over a multi-year window rests on deforestation-free soy sourcing infrastructure that survives EU Green Deal enforcement tightening. Watch Brussels' EU Protein Strategy revision as the inflection signal for domestic legume substitution economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Port Terminal Assets | Hamburg harbor grain handling control secures deforestation-free soy import channels under EU Green Deal rules. |
| Precision Nutrition Software Licensing | Rothkötter Mischfutterwerk's metabolizable energy optimization tools capture advisory revenue from BMEL compliance mandates. |
| Cooperative Crushing Asset Expansion | Agravis Raiffeisen AG structures deepen farmer-owned supply channel control across northwestern grain belt. |
| Antibiotic-Free Premix Manufacturing Scale-Up | Gut-health additive blends address EFSA growth-promoter phase-out requirements in Lower Saxony pig operations. |
| Near-Infrared Spectroscopy Deployment | Real-time protein verification automates batch consistency enforcement without offline laboratory delays. |
Research Methodology
Multi-period observation of Baltic Sea grain import volumes, BMEL regulatory enforcement timelines, and cooperative channel market share shifts anchored the trend analysis, supplemented by interviews with compound feed mill managers, EFSA regulatory affairs specialists, Lower Saxony contract-finishing operators, and agricultural cooperative procurement directors. Secondary validation drew from EU customs trade databases, BMEL Fertilizer Ordinance implementation reports, EFSA feed safety guidance documents, and Brussels EU Protein Strategy revision drafts. Bottom-up volume modeling triangulated against top-down sector expenditure estimates.
Segment-weighting applied animal type, feed form, and ingredient composition dimensions across the projection horizon, with species-specific metabolizable energy specifications and additive penetration rates as industry-specific forecast inputs. CAGRs derived from regression against livestock herd stabilization trends and pelleting technology diffusion curves throughout the forecast period.
Underlying measurement precision varies by segment; swine and poultry feed volume estimates carry tighter precision than aquatic species and pet food given data availability. Forecasts reflect documented assumptions around EU Green Deal enforcement timing and Black Sea supply normalization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Saudi Arabia Eggs Market
Agriculture and Agri Products
Organic Starter-Grower Chicken Feed Market
Agriculture and Agri Products
Rutin Market
Agriculture and Agri Products
Agrimony Market
Agriculture and Agri Products
American Ginseng Market
Agriculture and Agri Products
Africa Poultry Feed Market
Agriculture and Agri Products
Argentina Agriculture Market
Agriculture and Agri Products
UAE Agriculture Market
Agriculture and Agri Products
Global Vermicompost Market
Agriculture and Agri Products
Limestone for Agriculture Market
Agriculture and Agri Products
Malaysia Floriculture Market
Agriculture and Agri Products
Global Quail Eggs Market
Agriculture and Agri Products
Organic Soybean Market
Agriculture and Agri Products
Animal Feed and Feed Additives Market
Agriculture and Agri Products
Non GMO Soybean Market
Agriculture and Agri Products
Sweet Potato Flour Market