
 Angola Agriculture Market | 2026-2036
Angola Agriculture Market Size, Share, and Industry Trends Forecast 2026-2036
Angola Agriculture Market Insights
Certified seed-grade quality is rotating the Angola Agriculture Market toward higher-yield cultivation systems. Syngenta Group leverages its hybrid maize and vegetable seed portfolio to anchor technical advisory networks across smallholder cooperatives. Grupo Carrinho Holding sustains diversified agro-industrial operations spanning grain milling and poultry feed, while Biocom specializes in sugarcane-to-ethanol integration with captive power generation.
Angola Agriculture encompasses crop cultivation, livestock husbandry, fisheries management, and agrochemical application across tropical and subtropical agro-ecological zones, with primary outputs serving domestic food security, industrial feedstock supply, and export commodity trade. The sector operates through rain-fed and irrigated production systems where soil acidity correction and no-till adoption remain priority technical parameters. Crops and livestock occupy the dominant value share, while fisheries and aquaculture represent the fastest-expanding product category driven by Atlantic coastline access and dam reservoir stocking programs. Distribution channels bifurcate between informal retail networks serving urban consumers and wholesale-export pathways channeling coffee, soybeans, and timber to Portugal, China, and regional SADC buyers.
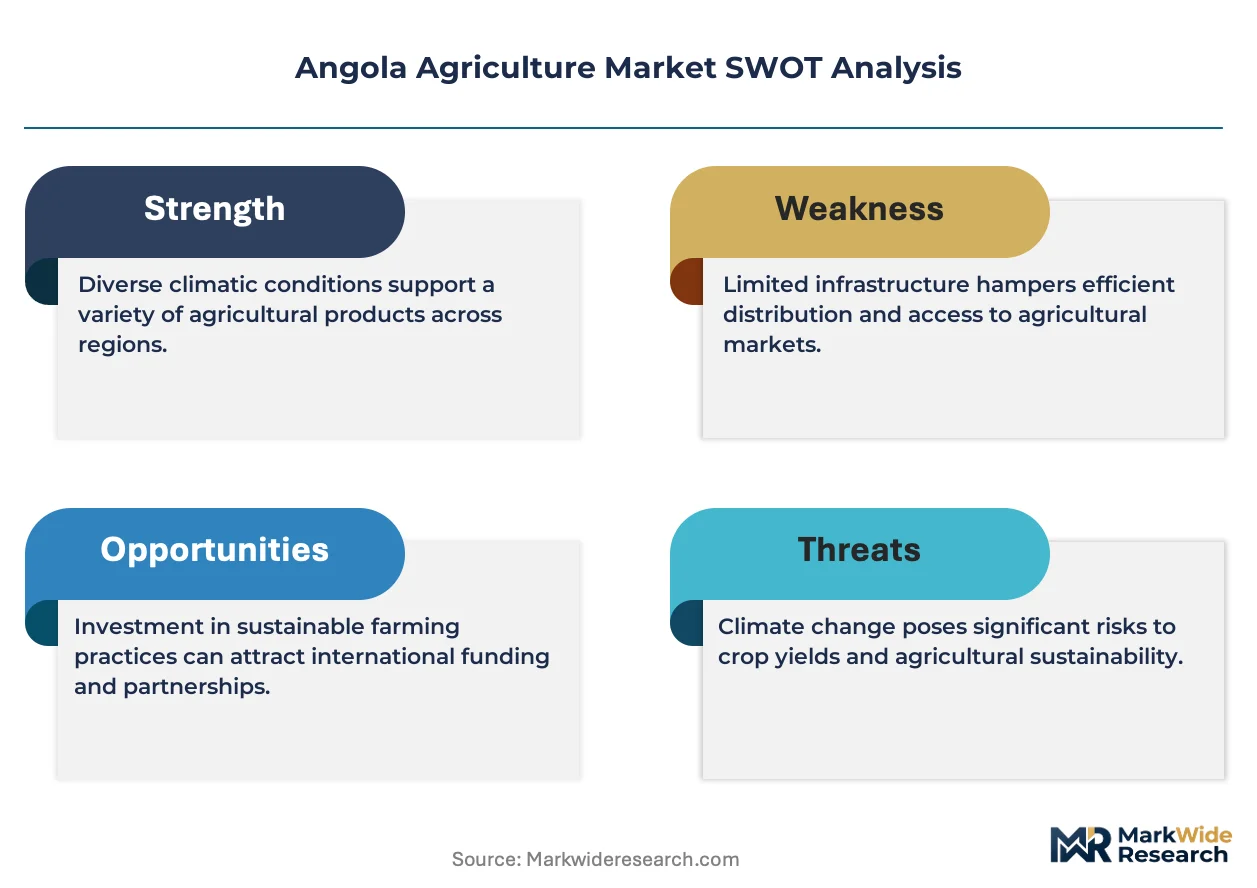
Angola's Ministry of Agriculture and Forestry administers commercial farming concessions and phytosanitary certification under national food security directives, while the country's national standards body enforces agricultural input quality benchmarks for seeds, fertilizers, and veterinary products. The Banco Nacional de Angola coordinates rural credit facilities and foreign exchange allocation for agricultural machinery imports, constraining capital access for non-integrated operators. Stakeholders must monitor irrigation infrastructure completion timelines and SADC regional trade protocol negotiations to anticipate competitive positioning shifts.
Market Dynamics
Irrigation infrastructure deployment through the Ministry of Agriculture and Forestry is concentrating productive capacity along mechanized farming corridors, redirecting capital from rain-fed smallholdings toward commercial perimeters with guaranteed water access.
Growth Catalysts
- Plano de Desenvolvimento da Agricultura Comercial:This national commercial agriculture development plan channels concession rights and fiscal incentives toward large-scale grain and oilseed operations in the Huambo Province corridor.
- Cassava industrial processing:Domestic food manufacturers are scaling local procurement of cassava roots to replace imported wheat starch in bakery and beverage applications.
- No-till cultivation systems:Soil acidity correction programs combined with minimum-tillage machinery are expanding arable productivity in the Cuanza Sul irrigation perimeters.
Market Restraints
- Foreign exchange rationing:Banco Nacional de Angola's allocation controls on agricultural machinery imports constrain equipment replacement cycles for non-integrated operators.
- Seed quality fragmentation:Informal seed networks dominate maize and bean distribution, undermining yield consistency across smallholder cooperatives.
- Fertilizer supply concentration:Import dependence on nitrogen and phosphate products exposes producers to port congestion and international price volatility.
Strategic Opportunities
- Dam reservoir aquaculture:The Capanda and Cambambe hydroelectric complexes offer untapped surface area for tilapia cage farming to supply Luanda's protein deficit.
- SADC trade protocol alignment:Harmonized sanitary standards with regional neighbors would unlock formal export channels for Huambo soybeans and Malanje timber.
- Agrivoltaic pilot zones:Solar panel arrays elevated above irrigated vegetable plots can generate captive power while reducing evaporative water loss in coastal perimeters.
Industry Challenges
- Phytosanitary certification timelines:The national standards body's laboratory backlog delays export clearance for coffee and timber shipments to European buyers.
- Mechanic-technician scarcity:Irrigation system maintenance and precision planter calibration require skills absent from rural vocational pipelines.
- Cooperative governance fragmentation:Smallholder associations struggle with financial transparency and collective input procurement, undermining their negotiating position with millers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Angola Agriculture Market |
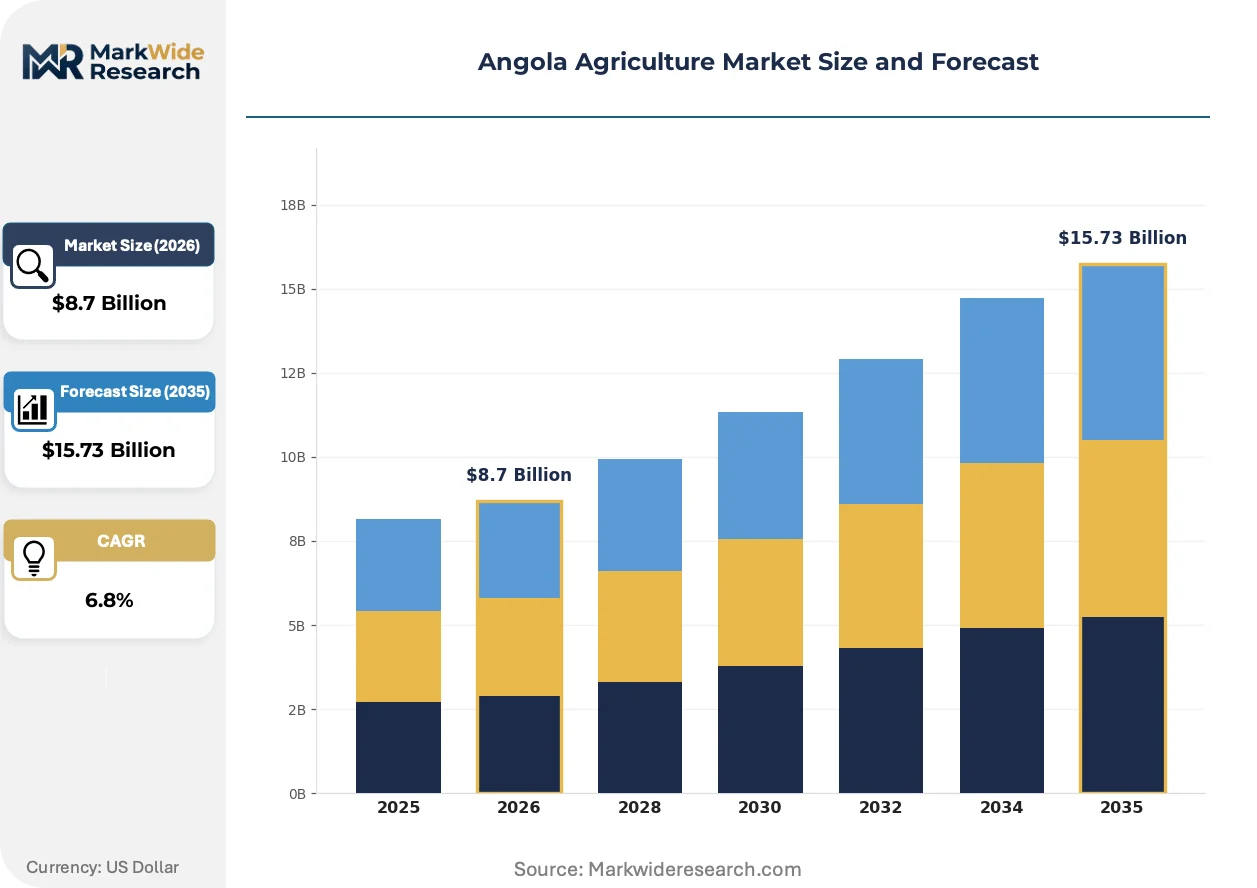
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crops, Livestock, Fisheries, Agrochemicals Distribution Channel: Retail, Wholesale, Online, Export End Use Industry: Agriculture, Food Processing, Export Trade, Animal Husbandry Packaging Type: Bulk, Consumer, Biodegradable, Reusable |
| Companies Covered | Pioneer Hi-Bred International, Grupo Carrinho Holding, Syngenta Group, Al Dahra, Companhia de Bioenergia de Angola - Biocom, Cargill, SinoHydro Group, Gesterra E.P., Bayer CropScience, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Angola Agriculture Market Trends and Innovations
Certified seed distribution networks and digital soil mapping are compressing the gap between subsistence and commercial farming systems, while regulatory pressure on phytosanitary compliance accelerates formalization of export supply chains.
Hybrid maize and vegetable seed portfolios are bifurcating the Angola Agriculture Market between technology-adopting cooperatives with extension service access and isolated smallholders reliant on retained grain. Syngenta Group's technical advisory networks in Huambo and Benguela provinces are concentrating yield gains among organized producer groups. This technology diffusion pattern is compressing the productivity spread between commercial perimeters and rain-fed outlying districts.
The Ministry of Agriculture and Forestry's concession framework for commercial farming zones is tightening land tenure security for capital-intensive operators while formalizing eviction risk for informal occupants. Industrial-scale soybean and maize ventures in the Planalto Central now operate under 25-year renewable leases with mandatory infrastructure commitments. This regulatory shift is displacing speculative land banking and channeling investment toward immediate cultivation rather than asset holding.
Urban wholesale buyers in Luanda and Lubango are consolidating procurement through miller-processor direct contracts, bypassing the fragmented assembly markets that historically aggregated smallholder surplus. Large grain handlers now offer advance payment and input credit against future delivery, capturing loyalty from organized cooperatives. This purchasing concentration is most visible in the maize value chain, where domestic feed mills and food processors are vertically integrating backward into primary production through contract farming arrangements.
Angola Agriculture Market Segmentation
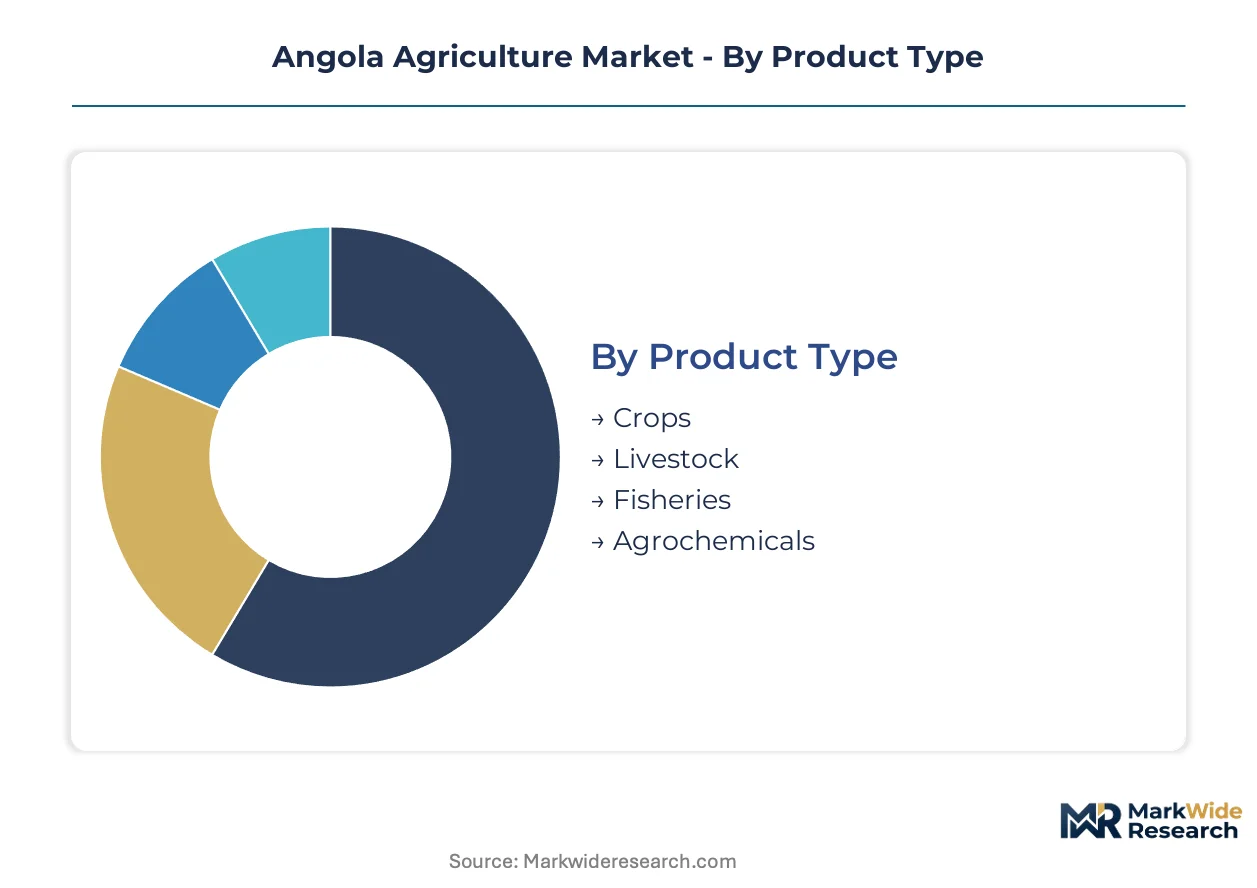
Segmentation in the Angola Agriculture Market reveals how capital flows concentrate across production systems and distribution pathways. Understanding these divisions exposes where mechanization investments and infrastructure gaps create divergent margin structures for operators.
Product Type:
Margin pools concentrate in segments with captive processing infrastructure and concession-backed land tenure security.
- Crops:Rain-fed and irrigated cultivation of maize, cassava, soybeans, and coffee dominates cultivated hectares. Demand concentrates in the Huambo Province grain belt where Plano de Desenvolvimento da Agricultura Comercial concessions channel fiscal incentives toward mechanized operations, though soil acidity correction costs erode returns in outlying districts.
- Livestock:Cattle, poultry, and small ruminant production serves domestic protein demand and industrial feed supply. Procurement is shifting toward integrated feed mill operations in the Planalto Central, where backward integration into grain production secures input cost stability against volatile international soy meal prices.
- Fisheries:Atlantic capture fisheries and reservoir aquaculture supply Luanda's protein deficit. Dam stocking programs at Capanda and Cambambe complexes are expanding tilapia cage farming surface area.
- Agrochemicals:Fertilizer, seed, and crop protection inputs face import dependence constraints. Port congestion and foreign exchange rationing from Banco Nacional de Angola create supply intermittency for non-integrated operators.
The dominant share belongs to Crops, while Fisheries is closing the gap fastest through aquaculture reservoir expansion.
Distribution Channel:
Channel selection determines working capital intensity and price realization for producers.
- Retail:Informal urban market networks and supermarket chains in Luanda, Huambo, and Lubango serve end consumers. Assembly market fragmentation persists in peri-urban zones.
- Wholesale:Miller-processor direct contracts now dominate grain procurement, offering advance payment and input credit against future delivery. Large handlers capture cooperative loyalty through vertical control over logistics.
- Online:Emerging digital platforms connect input suppliers with smallholder cooperatives. Extension service digitization is compressing information asymmetries in remote districts.
- Export:Coffee, soybeans, and timber shipments to Portugal, China, and SADC buyers require phytosanitary certification. Laboratory backlog at the national standards body delays clearance timelines for European-bound consignments.
Wholesale channels command the highest throughput volumes, though Export pathways deliver superior unit economics for certified operators.
End Use Industry:
Downstream industry concentration shapes input specifications and contract terms for primary producers.
- Agriculture:Primary production for subsistence and local market sale. Smallholder cooperatives in rain-fed districts struggle with collective input procurement and financial transparency.
- Food Processing:Cassava industrial processors are scaling local root procurement to replace imported wheat starch. Bakery and beverage manufacturers anchor demand in Luanda's manufacturing perimeter.
- Export Trade:Formal commodity shipments require SADC protocol alignment and harmonized sanitary standards. Huambo soybeans and Malanje timber face competitive positioning shifts from regional trade negotiations.
- Animal Husbandry:Poultry feed mills and integrated livestock operations drive concentrated demand for maize and soy meal. Grupo Carrinho Holding operations span grain milling through captive feed supply.
Agriculture absorbs the greatest production volume, yet Food Processing is expanding procurement fastest through import substitution mandates.
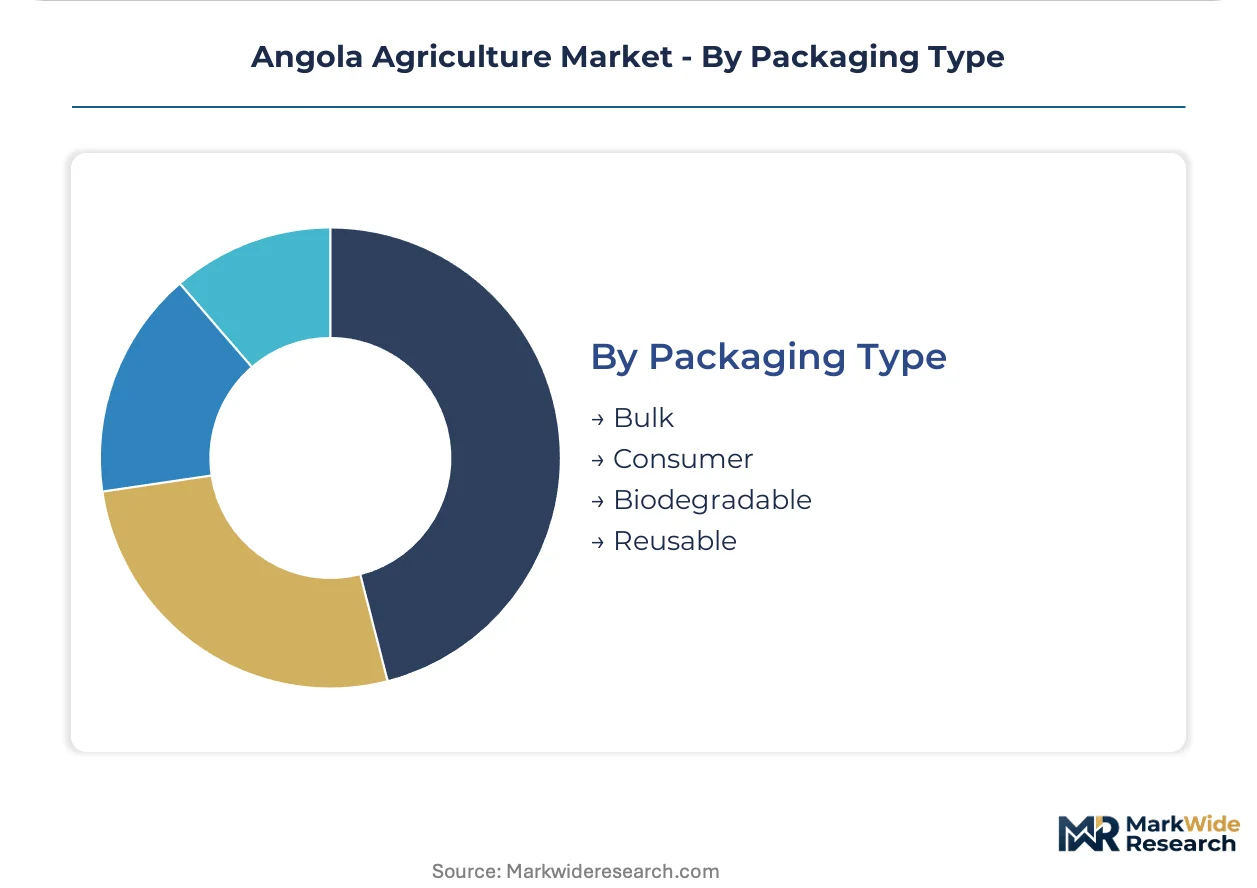
Packaging Type:
Packaging specifications differentiate commodity flows between bulk industrial supply and consumer-facing retail.
- Bulk:Unpackaged grain, oilseeds, and raw cassava roots move through miller-processor supply chains. Silo storage and container loading infrastructure concentrates at coastal export terminals.
- Consumer:Pre-packaged rice, flour, and processed foods serve supermarket and informal retail channels. Urbanization in Luanda is compressing traditional bulk purchasing patterns.
- Biodegradable:Emerging regulatory pressure on plastic waste is piloting cassava-starch based alternatives. Compliance costs remain prohibitive for small-scale processors.
- Reusable:Returnable crate systems for fresh produce distribution face logistics coordination challenges across fragmented cooperative networks.
Bulk packaging handles the dominant commodity flow, while Consumer formats are gaining share fastest through urban retail formalization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Angola's agricultural trade balance tilts toward import dependence for processed foods and machinery, while export revenues concentrate in unprocessed commodities facing phytosanitary bottlenecks. Regional production clusters exploit distinct agro-ecological advantages across sub-national zones. Provincial infrastructure investments and concession frameworks are redrawing competitive boundaries.
Huambo Province
Grain belt operations anchor national maize and soybean output through mechanized farming corridors. The Plano de Desenvolvimento da Agricultura Comercial channels fiscal incentives toward 25-year renewable concessions with mandatory infrastructure commitments. Huambo city serves as the primary collection point for miller-processor direct contracts.
Cuanza Sul
Irrigation perimeters along the Cuanza River support vegetable and cereal production through state-funded water infrastructure. No-till cultivation systems and soil acidity correction programs expand arable productivity. Sumbe and Gabela function as logistics nodes connecting coastal processing facilities to interior supply zones.
Benguela Province
Atlantic coastline access and desert-edge microclimates favor horticultural exports and fishing fleet operations. Cold chain investments from Lobito port support perishable cargo movements to SADC markets. The province hosts technical advisory networks for hybrid seed distribution.
Malanje
Timber concessions and cassava cultivation dominate land use in this northern zone. Capanda hydroelectric reservoir surface area supports expanding tilapia cage farming programs. Malanje city processes raw agricultural commodities for onward shipment to Luanda manufacturing perimeters.
Luanda Perimeter
Urban demand concentration drives food processing scale and import substitution mandates. Cassava industrial processors replace wheat starch in bakery and beverage applications. The capital's wholesale buyers consolidate procurement through advance payment and input credit schemes.
Angola Agriculture Market Competitive Landscape
Listed leaders compete with private specialists across concession-backed land tenure and captive processing infrastructure. Market structure fragments between integrated agro-industrial conglomerates with backward control over grain supply and input distributors serving fragmented smallholder networks. Three archetypes dominate: seed-chemical technology providers, diversified holding companies spanning milling through retail, and state-affiliated plantation operators with renewable lease security. Competitive moves center on vertical control over primary production and contract farming arrangements capturing cooperative loyalty.
Within the technology-provider tier, Syngenta Group and Bayer CropScience represent global seed-chemical majors leveraging hybrid portfolios and extension networks. Grupo Carrinho Holding exemplifies diversified domestic operators with integrated grain milling and feed production capabilities. Companhia de Bioenergia de Angola — Biocom occupies a position among concession-based agro-energy ventures with captive power generation from sugarcane processing. Pioneer Hi-Bred International and Cargill anchor multinational agricultural input and trading presence.
| Leading Market Players |
|---|
| Pioneer Hi-Bred International |
| Grupo Carrinho Holding |
| Syngenta Group |
| Al Dahra |
| Companhia de Bioenergia de Angola - Biocom |
| Cargill |
| SinoHydro Group |
| Gesterra E.P. |
| Bayer CropScience |
| Others |
Pricing and Supply Chain Analysis
Cassava-to-starch substitution in Luanda's bakery sector simultaneously redraws procurement geography toward Cuanza Sul smallholders and compresses pricing premiums previously commanded by imported wheat derivatives. This input pivot forces domestic millers to renegotiate contract terms with organized cooperatives while informal traders absorb margin erosion in fragmented peri-urban assembly markets.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing for grain and oilseed flows, with price differentiation driven by certified seed-grade quality and volume scale commitments. Pricing pressure stems from Banco Nacional de Angola's foreign exchange rationing on machinery imports, which constrains yield-enhancing technology adoption among non-integrated operators. Smallholder cooperatives exhibit highest price sensitivity due to working capital constraints and fragmented input procurement, while concession-backed commercial ventures with captive processing infrastructure maintain pricing power through backward integration into primary production.
Supply Chain Analysis
Inventory lead times for nitrogen and phosphate fertilizers stretch unpredictably due to port congestion at Luanda and Lobito, forcing producers to carry buffer stocks through planting seasons. Supply concentrates in Brazil, Morocco, and South Africa for fertilizer inputs, while hybrid seed genetics draw from Swiss and Dutch breeding programs. Single-source vulnerability pervades the agrochemical import channel, where Banco Nacional de Angola's allocation controls create supply intermittency. Distribution runs through miller-processor direct contracts that bypass traditional assembly markets, consolidating throughput through advance payment and input credit schemes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Angola Agriculture Market expansion represents a high-growth disruption propelled by the Ministry of Agriculture and Forestry's irrigation infrastructure deployment and concession framework formalization, which redirects capital from rain-fed smallholdings toward mechanized commercial perimeters with guaranteed water access.
For Market Incumbents: Consolidate land tenure security through accelerated infrastructure commitments under Plano de Desenvolvimento da Agricultura Comercial concessions before regulatory tightening displaces speculative holdings. Deepen backward integration into certified seed distribution networks to capture cooperative loyalty against Syngenta Group's technical advisory expansion. Prioritize mechanic-technician training pipelines to resolve irrigation system maintenance bottlenecks that threaten yield realization in Cuanza Sul perimeters. For New Entrants and Emerging Players: Differentiate on dam reservoir aquaculture specialization at Capanda and Cambambe complexes, where tilapia cage farming surface area remains underutilized against Luanda's protein deficit. Target the agrivoltaic pilot zone white space in coastal irrigation perimeters, combining captive solar generation with evaporative water loss reduction. Pursue digital platform connectivity with smallholder cooperatives to compress information asymmetries in remote districts through extension service digitization. For Investors and Strategic Acquirers: Secondary-cycle assets sit with diversified domestic holding companies possessing integrated grain milling and feed production capabilities but lacking concession-backed land tenure expansion. Five-to-ten year viability hinges on SADC trade protocol alignment unlocking formal export channels for Huambo soybeans and Malanje timber. Monitor phytosanitary certification timeline compression at the national standards body as the inflection signal for export pathway scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Concession Lease Renewal | 25-year renewable leases with mandatory infrastructure commitments channel investment toward immediate cultivation rather than asset holding. |
| Backward Integration into Seed Production | Captive supply of certified hybrid maize genetics reduces dependence on Syngenta Group's technical advisory networks. |
| Dam Reservoir Aquaculture Expansion | Tilapia cage farming at Capanda and Cambambe complexes addresses Luanda's protein deficit through underutilized hydroelectric surface area. |
| Digital Input Procurement Platform | Extension service digitization compresses information asymmetries between remote smallholder cooperatives and urban wholesale buyers. |
| SADC Sanitary Standard Harmonization | Regional trade protocol alignment unlocks formal export channels for Huambo soybeans facing competitive positioning shifts. |
Research Methodology
The analysis maps crop cultivation, livestock husbandry, fisheries management, and agrochemical application sub-sectors, each validated through cooperative managers, concession operators, miller-processor procurement leads, and Ministry of Agriculture and Forestry planning officers. Primary interviews with irrigation infrastructure contractors and veterinary supply distributors combined with secondary validation from customs trade records, Banco Nacional de Angola rural credit disbursement data, and SADC regional trade protocol documentation. Bottom-up hectare-yield modeling and top-down GDP-agriculture value-add triangulation anchored volume estimates.
Consistency checks against external benchmarks validated projections across the analysis window. Segmentation dimensions modeled include product type, distribution channel, end-use industry, and packaging format alongside agro-ecological zone differentiation. CAGRs derived from historical production data, concession deployment timelines, and import substitution elasticity coefficients. Forecast inputs incorporated Plano de Desenvolvimento da Agricultura Comercial fiscal incentive allocation patterns and foreign exchange rationing severity assumptions.
The analysis sits within stated boundaries; outcomes outside continued irrigation infrastructure completion and stable concession enforcement would require recalibration. Forecasts reflect documented assumptions regarding seed quality fragmentation persistence and fertilizer import channel reliability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Agriculture in Egypt Market
Agriculture and Agri Products
UAE Agriculture Market
Agriculture and Agri Products
Organic Soybean Market
Agriculture and Agri Products
Lucerne Market
Agriculture and Agri Products
Animal Feed Market
Agriculture and Agri Products
Netherlands Floriculture Market
Agriculture and Agri Products
Africa Animal Protein Market
Agriculture and Agri Products
India Palm Oil Market
Agriculture and Agri Products
Europe Eggs Market
Agriculture and Agri Products
Animal Feed and Pet Food Market
Agriculture and Agri Products
Canada Bamboos Market
Agriculture and Agri Products
Asia-Pacific Alfalfa Market
Agriculture and Agri Products
South America Poultry Feed Market
Agriculture and Agri Products
Rutin Market
Agriculture and Agri Products
Germany Animal Protein Market
Agriculture and Agri Products
Swine Feed Premix Market