
 Netherlands Floriculture Market | 2026-2036
Netherlands Floriculture Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Floriculture Market Foresight
Dutch greenhouse operators is expanding heated glasshouse acreage for year-round rose and phalaenopsis production. Royal FloraHolland anchors the sector through its Aalsmeer auction clock, which still handles substantial daily throughput. Dümmen Orange specializes in breeding and propagating young plants, leveraging extensive tissue culture labs. Beekenkamp sustains market position through integrated pot-plant propagation and finished-plant distribution across Western Europe.
Floriculture encompasses the commercial cultivation, breeding, and post-harvest handling of ornamental plants and cut flowers under controlled-environment agriculture, typically requiring maintained temperatures of 18–24°C and 60–80% relative humidity to optimize photosynthetic efficiency and vase life. The primary purpose is supplying live botanical products for decorative, ceremonial, and gifting applications through retail and institutional channels. Cut flowers generate the dominant revenue pool within product type segments, while online distribution channels exhibit the fastest structural expansion as direct-to-consumer logistics mature. Bedding plants retain mature, seasonally cyclical demand patterns tied to spring planting calendars across European garden centers.
The Dutch Ministry of Agriculture, Nature and Food Quality enforces EU Plant Health Regulation compliance for all export-bound propagation material, while the EU Green Deal Farm to Fork framework mandates pesticide reduction targets that reshape input protocols across Westland and Limburg growing regions. The Netherlands Food and Consumer Product Safety Authority conducts residue testing that determines market access eligibility for third-country shipments. Stakeholders must monitor evolving EU deforestation-free supply chain due diligence rules and their potential extension to ornamental plant sourcing footprints.
Market Dynamics
The Netherlands Floriculture Market is undergoing structural compression as the EU Green Deal Farm to Fork strategy forces wholesale input protocol redesign across Westland and Limburg growing regions, while heated glasshouse acreage expansion strains energy cost absorption capacity.
Growth Catalysts
- EU Green Deal pesticide reduction mandates:The Farm to Fork framework's residue targets accelerate biological pest management adoption, creating compliance-driven demand for integrated crop protection services across Dutch propagation facilities.
- Year-round heated glasshouse production:Controlled-environment agriculture investments in the Randstad corridor enable consistent rose and phalaenopsis supply to European retail chains regardless of seasonal import availability.
- Online direct-to-consumer channel maturation:Logistics infrastructure improvements allow Aalsmeer auction bypass for premium cut flower shipments to individual buyers, expanding addressable customer bases beyond traditional wholesale.
Market Restraints
- Natural gas price volatility:Heated greenhouse operations in Westland depend on natural gas for climate control, exposing margin structures to energy input cost swings that compressed profitability during recent supply shocks.
- Propagation material supply concentration:Tissue culture lab capacity for young plant production clusters around Limburg and select Belgian suppliers, creating bottleneck risk for breeding program scale-up timelines.
- EU Plant Health Regulation compliance friction:Export-bound propagation material faces extended certification timelines at Netherlands Food and Consumer Product Safety Authority inspection facilities, delaying shipment windows to third-country markets.
Strategic Opportunities
- Deforestation-free supply chain due diligence extension:Proposed EU regulatory expansion to ornamental plant sourcing footprints creates first-mover advantage for Dutch operators with established traceability systems in peat and substrate procurement.
- Phalaenopsis varietal IP licensing:Breeding houses can monetize tissue culture exclusivity through royalty-bearing propagation agreements with offshore greenhouse operators in Poland and Spain seeking premium genetics.
- Institutional and corporate gifting segment:Subscription-based floral delivery to office complexes and hospitality chains represents underpenetrated demand relative to retail concentration in current channel mix.
Industry Challenges
- Skilled greenhouse climate technician scarcity:Precision agriculture roles combining horticultural science with data analytics face recruitment gaps as educational pipeline output lags sector digitization pace.
- Legacy auction clock system integration:Royal FloraHolland's infrastructure requires interface upgrades to connect with emerging direct-ship logistics platforms without disrupting established buyer bidding workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Floriculture Market |
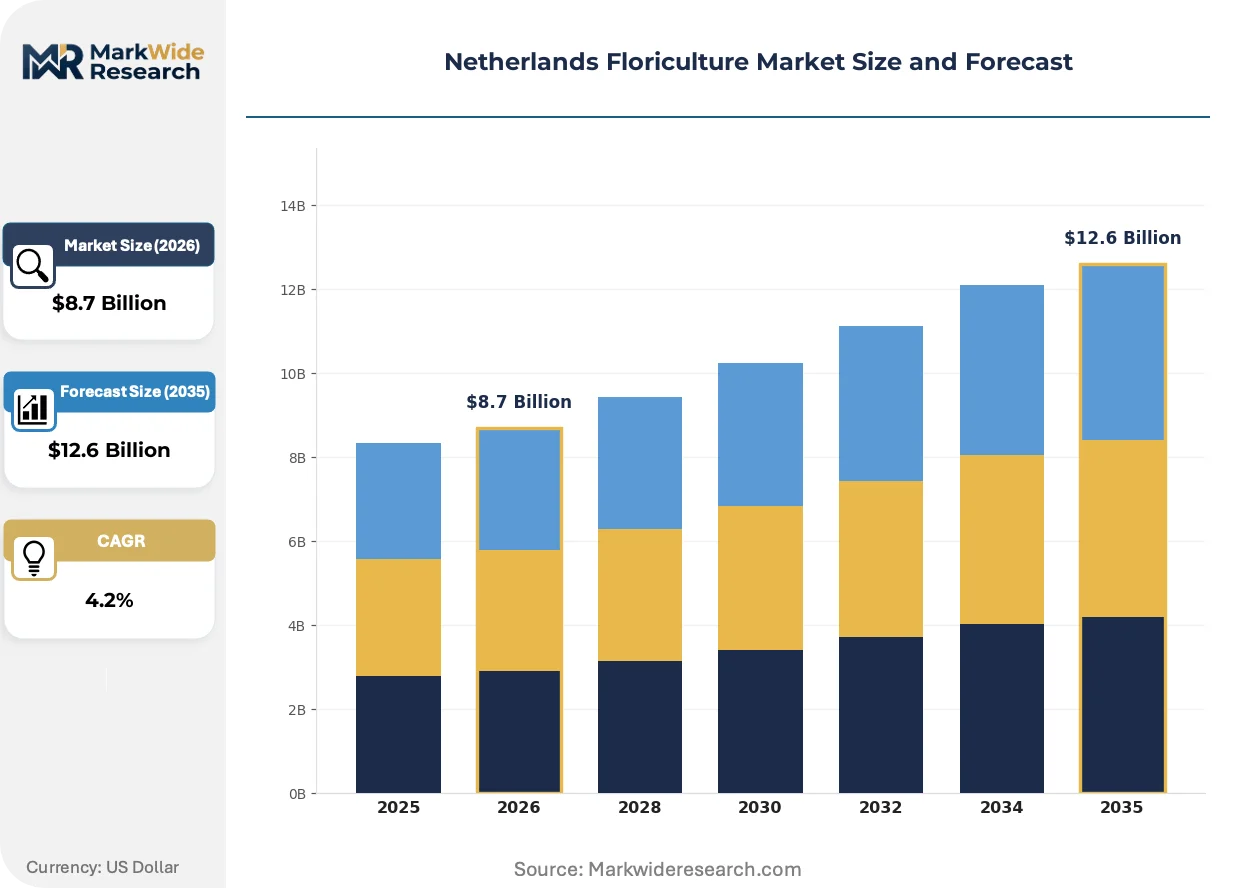
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.6 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cut Flowers, Pot Plants, Bedding Plants, Bulbs Distribution Channel: Wholesale, Retail, Online, Export End User: Florists, Garden Centers, Wholesale Markets, Direct Consumers Seasonality: Spring, Summer, Autumn, Winter |
| Companies Covered | Beekenkamp, Syngenta Flowers, Royal FloraHolland, One Flora Group, Dümmen Orange, Dutch Flower Group, Queens Group, Floricultura Netherlands, Heemskerk Flowers, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Floriculture Market Shifts & Advancements
Digital sensing and biological input technologies are compressing traditional cultivation cycles while regulatory pressure on chemical residues forces protocol reinvention across Dutch growing regions.
LED supplemental lighting is expanding into year-round rose production facilities as spectral tuning technology enables photosynthetic optimization at lower energy intensity than high-pressure sodium alternatives. Westland greenhouse operators adopting full LED retrofit programs report accelerated stem elongation and reduced time-to-harvest for premium cut varieties. This technology diffusion is compressing the competitive gap between Dutch winter production and Kenyan or Ethiopian sun-grown imports.
The EU Green Deal Farm to Fork strategy's pesticide reduction targets are mandating biological control agent substitution across all export-bound propagation material. Netherlands Food and Consumer Product Safety Authority residue testing protocols now reject shipments exceeding tightened maximum residue limits, forcing integrated pest management investment. Cut flower segments supplying German and French retail chains face the steepest compliance cost escalation as buyer specifications align with regulatory ceilings.
Direct-to-consumer subscription models are displacing traditional auction-to-florist distribution for premium gifting occasions. Urban households in Amsterdam and Rotterdam increasingly bypass retail intermediaries for weekly bouquet deliveries sourced through breeder-direct platforms. This channel fragmentation concentrates margin capture with logistics-integrated cultivators while compressing wholesale auction throughput volumes at Aalsmeer.
Netherlands Floriculture Market Segmentation

Segmentation reveals how capital deployment, regulatory exposure, and channel control distribute across Dutch floriculture. Each dimension carries distinct margin profiles and compliance burdens that reshape competitive positioning.
Product Type:
Capital intensity varies sharply across propagation methods, with heated glasshouse requirements and tissue culture infrastructure driving upfront investment thresholds.
- Cut Flowers:Rose and phalaenopsis cultivation dominates heated acreage in Westland and Aalsmeer, where year-round climate control demands substantial natural gas infrastructure. Dutch growers supply premium long-stem varieties to German and French retail chains, though energy cost volatility compresses margins during supply shocks.
- Pot Plants:Phalaenopsis and foliage species require controlled-environment agriculture with maintained temperatures of 18–24°C and 60–80% relative humidity. Beekenkamp and Dümmen Orange concentrate propagation material supply in Limburg tissue culture labs, creating bottleneck risk for breeding program scale-up.
- Bedding Plants:Seasonal cyclical demand ties to spring planting calendars across European garden centers. Lower capital barriers attract smaller operators, though EU Green Deal pesticide residue rules reshape input protocols.
- Bulbs:Tulip and lily bulb exports face Netherlands Food and Consumer Product Safety Authority certification timelines that delay shipment windows to third-country markets. Cold storage infrastructure requirements moderate entry costs relative to heated production.
Cut flowers absorb the bulk of installed capacity; online channel expansion for pot plants is expanding most quickly.
Distribution Channel:
Channel selection determines margin capture location, with direct-to-consumer models displacing traditional auction intermediation.
- Wholesale:Royal FloraHolland's Aalsmeer auction clock still handles substantial daily throughput, though legacy infrastructure requires interface upgrades to connect with emerging direct-ship logistics platforms.
- Retail:European garden center chains and supermarket floral departments concentrate volume absorption. German and French buyer specifications align with tightened EU maximum residue limits, forcing integrated pest management investment.
- Online:Direct-to-consumer subscription models bypass auction-to-florist distribution for premium gifting occasions. Amsterdam and Rotterdam households increasingly source weekly bouquet deliveries through breeder-direct platforms.
- Export:Third-country propagation material shipments face extended Netherlands Food and Consumer Product Safety Authority inspection timelines. EU Plant Health Regulation compliance friction delays market access eligibility for non-EU destinations.
Wholesale retains volume concentration; online distribution is gaining share fastest through logistics-integrated cultivator platforms.
End User:
Customer type dictates specification stringency, with institutional buyers enforcing tighter residue and traceability standards than consumer channels.
- Florists:Traditional auction-dependent buyers face margin compression as direct-ship logistics mature. Premium variety sourcing concentrates through Royal FloraHolland bidding workflows.
- Garden Centers:Bedding plant and seasonal pot plant demand clusters here, with spring volume spikes requiring flexible propagation scheduling.
- Wholesale Markets:Aalsmeer and Naaldwijk cluster activity anchors sector liquidity, though throughput volumes face compression from channel fragmentation.
- Direct Consumers:Subscription-based floral delivery to urban households represents underpenetrated demand relative to retail concentration in current channel mix.
Florists and garden centers absorb traditional volume; direct consumer channels show the steepest expansion trajectory.
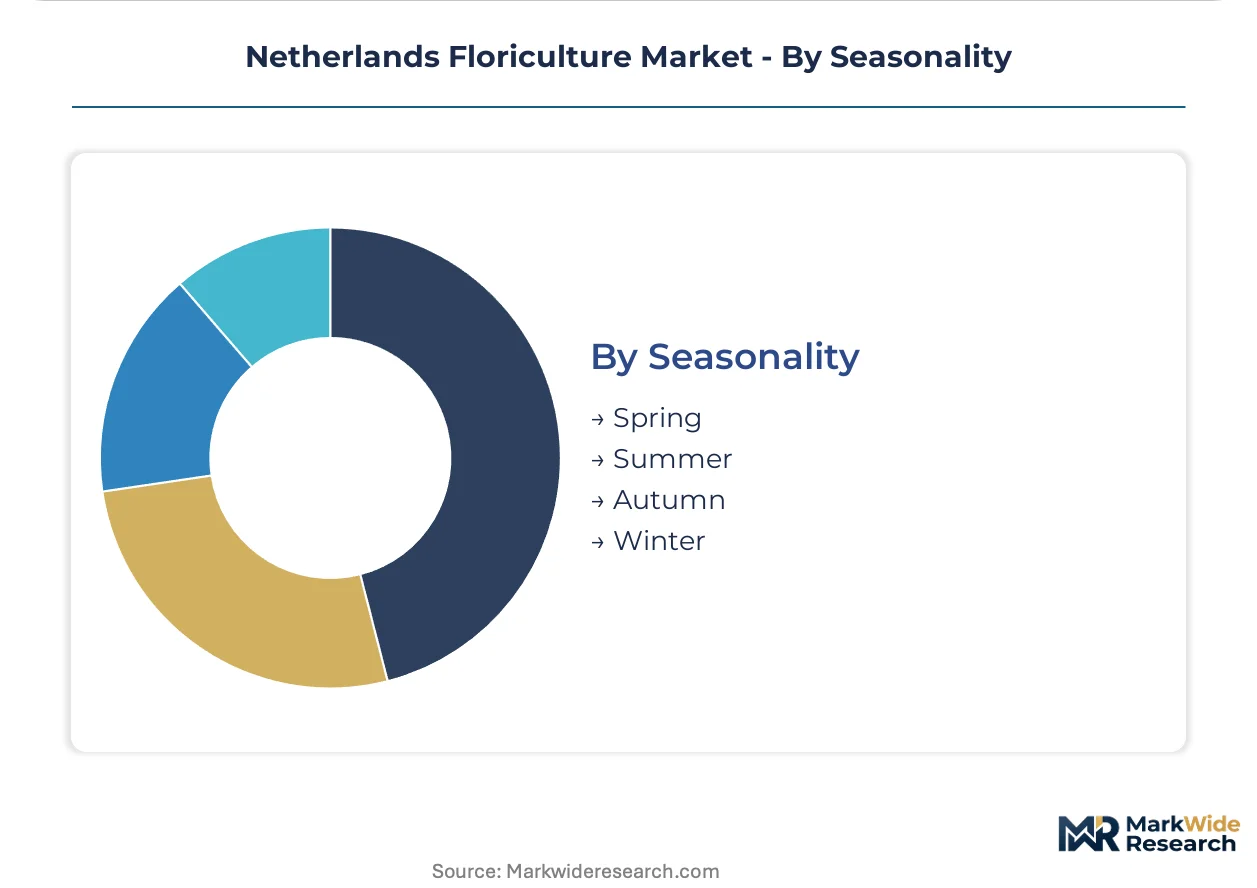
Seasonality:
Production calendar alignment determines capacity utilization and energy cost absorption across heated and unheated facilities.
- Spring:Bedding plant volume peaks align with garden center restocking cycles. Limburg and Westland operators scale temporary labor for propagation surges.
- Summer:Cut flower demand concentrates in wedding and event gifting, with Dutch production competing against Kenyan and Ethiopian sun-grown imports.
- Autumn:Phalaenopsis and pot plant shipments accelerate ahead of holiday retail preparation. EU Green Deal compliance costs escalate as buyer specifications tighten.
- Winter:Heated glasshouse rose production achieves maximum premium pricing, though natural gas input costs strain margin structures.
Spring and summer absorb peak labor deployment; autumn pot plant shipments are climbing the fastest on a year-over-year basis.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peat extraction fields in the northern Netherlands supply the substrate base that anchors Dutch floriculture propagation. Limburg tissue culture labs and Westland heated glasshouses cluster around these raw material nodes. The Randstad corridor concentrates auction logistics and breeder headquarters.
Randstad Corridor
Aalsmeer, Naaldwijk, and Westland greenhouse clusters absorb the majority of Dutch heated acreage investment. The Netherlands Food and Consumer Product Safety Authority enforces EU Plant Health Regulation compliance for all export-bound propagation material from this zone. Royal FloraHolland's Aalsmeer auction clock handles substantial daily throughput while legacy infrastructure requires interface upgrades for direct-ship logistics.
Limburg
Young plant propagation and tissue culture lab capacity concentrates in southern Netherlands border zones near Belgian suppliers. EU Green Deal Farm to Fork pesticide reduction mandates reshape input protocols across breeding facilities here. Dümmen Orange and Beekenkamp operations exemplify the integrated pot-plant propagation and distribution model serving Western European garden centers.
Brabant
Phalaenopsis breeding programs and foliage species cultivation occupy controlled-environment facilities in this southern province. The Dutch Ministry of Agriculture, Nature and Food Quality monitors residue testing protocols that determine German and French retail chain eligibility. Eindhoven Region logistics hubs connect breeder-direct platforms to Amsterdam and Rotterdam consumer markets.
Northern Netherlands
Peat and substrate procurement for national propagation networks originates from extraction zones in Groningen and Friesland. Proposed EU deforestation-free supply chain due diligence rules threaten to extend traceability requirements to ornamental plant sourcing footprints. Cold storage infrastructure for tulip and lily bulb exports moderates entry costs relative to heated production.
Netherlands Floriculture Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue breeder-direct subscription channels and offshore licensing arrangements. The market structures around auction-dependent wholesale incumbents, integrated propagation-to-retail hybrids, and specialized breeding houses. Three archetypes dominate: auction-anchored logistics platforms, tissue-culture-based genetics licensors, and direct-to-consumer logistics integrators. Competitive moves concentrate on LED retrofit capacity expansion and phalaenopsis varietal IP licensing partnerships.
Within the auction-anchored tier, Royal FloraHolland represents the legacy infrastructure model requiring digital interface upgrades. Among integrated propagation specialists, Beekenkamp and Dümmen Orange exemplify the Limburg-based tissue culture-to-finished-plant value chain control. These three entities occupy positions spanning logistics, breeding, and distribution archetypes without exclusive segment lock-in.
| Leading Market Players |
|---|
| Beekenkamp |
| Syngenta Flowers |
| Royal FloraHolland |
| One Flora Group |
| Dümmen Orange |
| Dutch Flower Group |
| Queens Group |
| Floricultura Netherlands |
| Heemskerk Flowers |
| Others |
Supply & Pricing Matrix
Natural gas futures benchmarks cascade through Dutch floriculture pricing tiers, with Westland heated glasshouse operators absorbing input volatility into premium rose and phalaenopsis quotations while unheated bulb storage facilities in the northern Netherlands operate on flatter cost structures. The Randstad corridor's auction-to-retail logistics stack layers margin extraction at each handoff, compressing farmgate capture for growers lacking direct-ship infrastructure.
Pricing Analysis
Service unbundling separates phytosanitary certification costs from base product quotations, with EU Plant Health Regulation compliance fees now itemized for export-bound propagation material. Three-tier pricing structure across premium, standard, and economy levels stratifies by vase-life certification and varietal exclusivity, with tissue-culture-licensed phalaenopsis genetics commanding royalty premiums. Cost compression in standard-tier cut flowers is intensifying because Kenyan and Ethiopian sun-grown imports undercut Dutch winter production on landed cost. German retail chains exhibit the sharpest price sensitivity, while Dutch direct-to-consumer subscription buyers prioritize reliability over per-stem economics.
Supply Chain Analysis
Dual-sourcing mandates from German and French retail chains force propagation material buyers to qualify tissue culture labs across Limburg, Belgium, and select Spanish facilities. Geographic concentration centers on the Netherlands for finished cut flowers, Kenya and Ethiopia for sun-grown rose imports, and Poland for phalaenopsis greenhouse expansion. Raw material dependencies include Groningen-sourced peat substrate, Belgian propagation genetics, and natural gas for climate control infrastructure. Single-source vulnerability concentrates in Limburg young plant supply, where breeding program scale-up faces bottleneck risk. Distribution runs through Royal FloraHolland's Aalsmeer auction clock for wholesale volume, with breeder-direct platforms capturing subscription channel growth.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
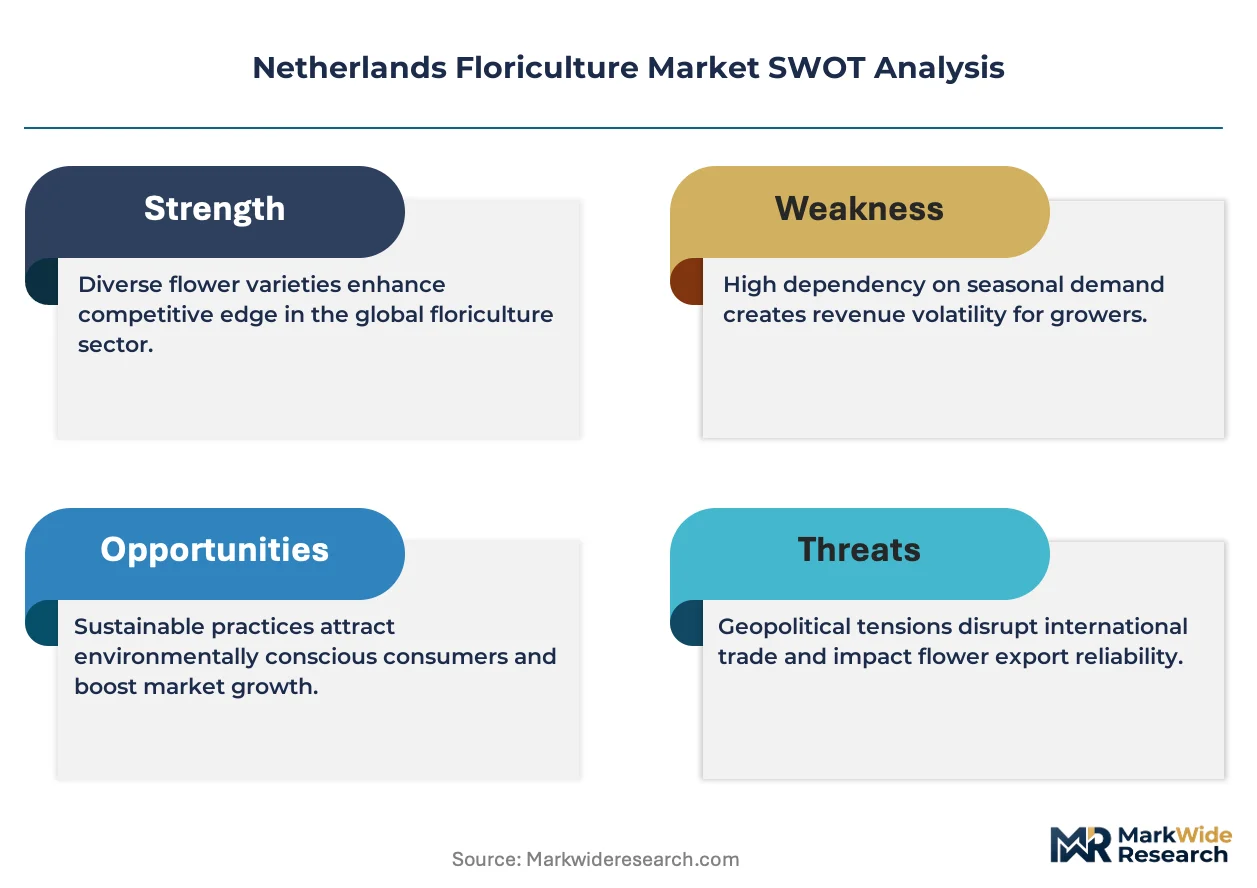
The Netherlands Floriculture Market functions as a cost-of-compliance arena where EU Green Deal Farm to Fork pesticide residue mandates erect barrier-to-entry moats favoring incumbent operators with established integrated pest management infrastructure.
For Market Incumbents:Acquire distressed heated glasshouse acreage in Westland to consolidate Randstad corridor production capacity against Polish and Spanish greenhouse expansion. Priority defensive moves include retrofitting legacy facilities with LED supplemental lighting to compress energy cost exposure, and securing exclusive tissue culture propagation agreements with Limburg breeding houses to lock genetics access before regulatory compliance costs escalate further.
For New Entrants and Emerging Players:Launch via breeder-direct subscription platforms targeting Amsterdam and Rotterdam urban households, bypassing Royal FloraHolland auction infrastructure entirely. White-space concentration sits in corporate and institutional floral gifting, where subscription delivery to hospitality chains and office complexes remains underpenetrated relative to retail channel saturation. Poland and Spain offer the most penetrable geography for offshore phalaenopsis licensing partnerships with Dutch genetics houses.
For Investors and Strategic Acquirers:Distressed-cycle entries favor tissue-culture-based breeding specialists in Limburg with established EU Plant Health Regulation compliance infrastructure, as energy cost shocks force marginal heated-glasshouse operators toward asset sales. Long-term viability over a multi-year horizon hinges on deforestation-free supply chain traceability readiness for impending EU due diligence expansion. The signal to watch is Netherlands Food and Consumer Product Safety Authority inspection backlog duration, which indicates regulatory friction intensity affecting export-bound shipment windows.
| Strategic Initiative | Industry Significance |
|---|---|
| LED Retrofit Capacity Expansion | Full-spectrum lighting adoption at Westland facilities compresses time-to-harvest for premium cut rose varieties. |
| Phalaenopsis Varietal IP Licensing | Royalty-bearing propagation agreements with Polish and Spanish greenhouse operators monetize tissue culture exclusivity. |
| Direct-to-Consumer Platform Launch | Breeder-direct subscription models bypass Aalsmeer auction intermediation to capture urban household demand. |
| Deforestation-Free Traceability Investment | Peat and substrate procurement documentation prepares Dutch operators for EU due diligence rule extension. |
| Integrated Pest Management Infrastructure | Biological control agent substitution aligns with EU Green Deal Farm to Fork residue reduction mandates. |
Research Methodology
Document review covered EU regulatory filings, Netherlands Food and Consumer Product Safety Authority inspection protocols, and Royal FloraHolland auction throughput disclosures, complemented by interviews with Westland greenhouse operators, Limburg tissue culture lab directors, German retail chain procurement managers, and Dutch floriculture logistics specialists. Secondary validation drew from EU Plant Health Regulation implementation reports, energy price benchmark series, and horticultural trade association datasets. Bottom-up grower-level capacity assessments and top-down auction volume reconciliation provided triangulation integrity.
Segment-level value and volume trajectories across the analysis window reflect product type, distribution channel, and end-user stratification combined with heated versus unheated production system classification. CAGRs were derived from installed acreage expansion schedules, channel shift velocity assumptions, and regulatory compliance cost absorption modeling. Key forecast inputs include natural gas price scenario bands and LED retrofit adoption curves for climate-controlled facilities.
Energy price volatility, regulatory inspection backlog duration, and offshore greenhouse competitor expansion pace are the dominant revision risks to the outlook. Deviation in natural gas benchmark trajectories would shift margin structure assumptions materially across heated glasshouse segments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agriculture and Agri Products
Agriculture in Egypt Market
Agriculture and Agri Products
Europe Poultry Feed Market
Agriculture and Agri Products
Flower and Ornamental Plants Market
Agriculture and Agri Products
Post-Harvest Treatment Market
Agriculture and Agri Products
Sweet Potato Flour Market
Agriculture and Agri Products
Uncaria Tomentosa Market
Agriculture and Agri Products
Mushroom Cultivation Market
Agriculture and Agri Products
Beet Pulp Market
Agriculture and Agri Products
Germany Animal Protein Market
Agriculture and Agri Products
Manufactured Garden Soil Market
Agriculture and Agri Products
Potting Soil Market
Agriculture and Agri Products
France Compound Feed Market
Agriculture and Agri Products
Chaga Mushroom Market
Agriculture and Agri Products
Prunus Africana Market
Agriculture and Agri Products
Brazil Rice Market
Agriculture and Agri Products
France Animal Protein Market