
 Argentina Pouch Packaging Market | 2026-2036
Argentina Pouch Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Pouch Packaging Market Insights
Brazilian flexible packaging capacity is narrowing the supply gap for Argentine converters facing resin and film shortages. Amcor Group GmbH leverages its regional laminating footprint to serve Buenos Aires-based food exporters with high-barrier retort structures. Gualapack SpA anchors the domestic spouted pouch segment through specialized forming equipment and local ink supply partnerships. Mondi Group competes on kraft paper-based flexible formats that align with retailer sustainability procurement rules.
Argentina pouch packaging denotes flexible, sealed containers manufactured from laminated plastic, aluminum foil, paper, or biodegradable films, typically ranging from 50 milliliters to five liters in fill volume, formed through horizontal or vertical form-fill-seal processes with heat-sealed or zippered closures. These structures protect oxygen-sensitive and moisture-critical contents across ambient, chilled, and retort sterilization distribution chains. Stand-up pouches dominate shelf presence in Argentine supermarkets due to their carton-free pallet efficiency and gravity-fed dispensing. Retort pouches represent the fastest-growing product type as meat processors and ready-meal brands replace metal cans to reduce shipping weight. Plastic laminates still command the material mix, though biodegradable film adoption is accelerating among organic food labels seeking differentiation.
ANMAT governs food contact migration limits under Mercosur GMC Resolution 32/07, while Argentina's Secretariat of Industry and Productive Development administers import substitution incentives that favor domestic film extrusion over finished pouch imports. BIS-equivalent conformity assessments for flexible packaging machinery create compliance thresholds that filter out uncertified Asian equipment suppliers. Stakeholders must monitor whether proposed updates to Mercosur technical regulations will mandate recyclable or mono-material structures, a shift that would force reformulation across the current multi-layer supply base.
Market Dynamics
Argentine food processors are accelerating their shift from rigid metal cans and glass jars to flexible retort pouches, driven by freight cost pressures on export routes through the Port of Buenos Aires and ANMAT's migration-limit enforcement favoring high-barrier multi-layer films.
Growth Catalysts
- Retort sterilization technology:Meat processors and ready-meal brands adopt retort-compatible pouch structures to cut shipping weight by 70% versus metal cans on long-haul export routes to Brazil and Chile.
- ANMAT regulatory alignment:The national food contact materials regulator enforces Mercosur GMC Resolution 32/07 migration limits that disqualify monolayer films, mandating multi-layer barrier constructions that Argentine converters now supply domestically.
- Greater Buenos Aires production clustering:Half of Argentina's packaged food output concentrates within 50 kilometers of the capital's port and industrial belt, creating localized demand density for just-in-time pouch delivery.
Market Restraints
- Resin import dependency:Argentine converters rely on Brazilian petrochemical suppliers for polyethylene and polypropylene feedstock, exposing margins to cross-border logistics disruptions and currency volatility.
- Multi-layer recyclability barrier:Current high-barrier laminates combine polyethylene, polyamide, and aluminum foil in non-separable layers that municipal recycling streams cannot process, creating end-of-life liability for brand owners.
- Capital equipment certification:BIS-equivalent conformity assessments for form-fill-seal machinery filter out uncertified Asian equipment suppliers, limiting secondary machinery supply and inflating replacement part costs.
Strategic Opportunities
- Biodegradable film differentiation:Organic food labels in Córdoba and Mendoza provinces seek compostable pouch alternatives to conventional plastics, creating premium positioning for converters with PLA or cellulose-based barrier certifications.
- Spouted pouch format expansion:Dairy and sauce segments remain underpenetrated by convenient dispensing formats, offering white space for equipment investments in specialized forming and zipper-sealing capabilities.
- Import substitution incentives:Argentina's Secretariat of Industry and Productive Development administers tariff and tax benefits favoring domestic film extrusion over finished pouch imports, rewarding backward integration by local converters.
Industry Challenges
- Multi-layer reformulation complexity:Proposed Mercosur updates may mandate recyclable or mono-material structures, forcing technical teams to replicate oxygen and moisture barrier performance without aluminum foil or incompatible polymer combinations.
- Specialized laminating technician scarcity:Local workforce development lags behind demand for operators skilled in adhesive-less bonding and coextrusion die configuration, extending commissioning timelines for new production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Pouch Packaging Market |
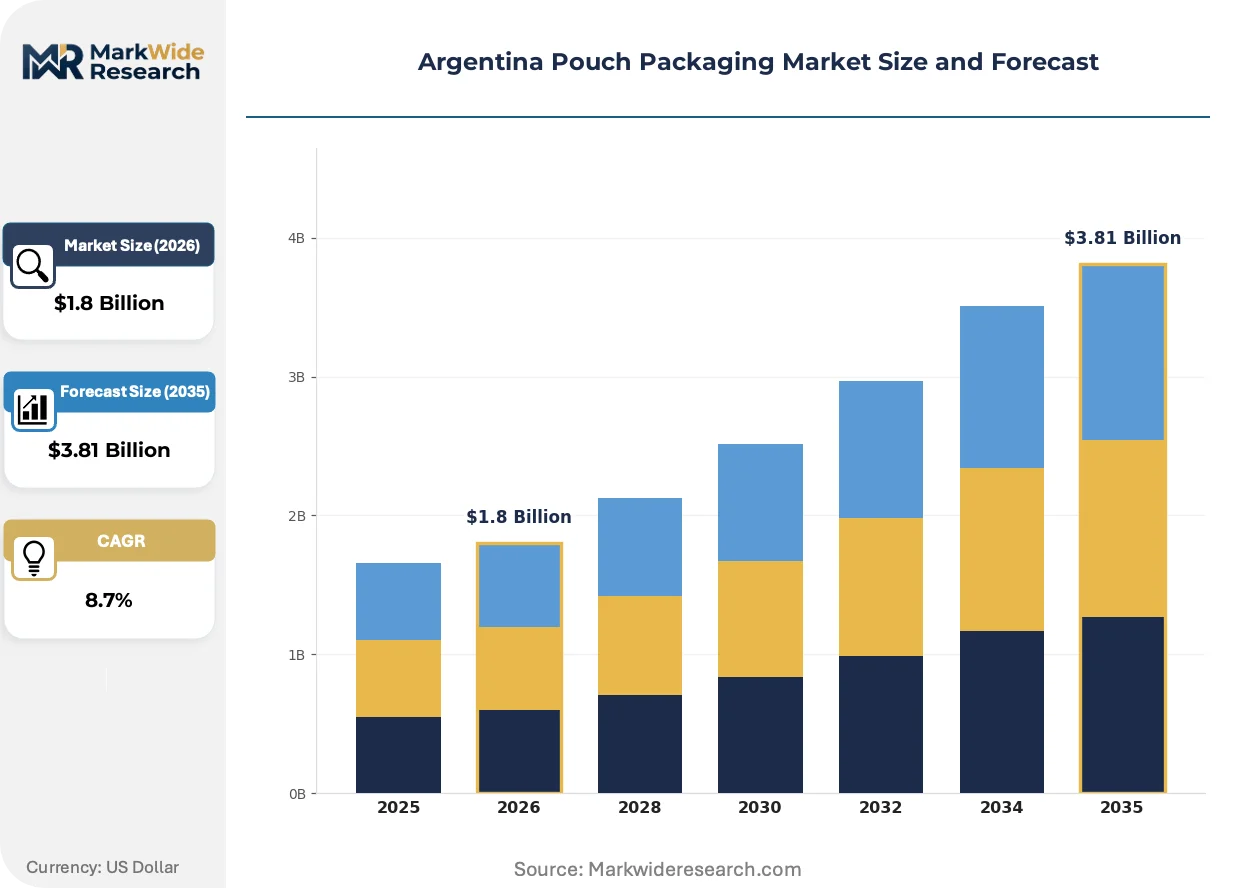
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-up Pouches, Flat Pouches, Vacuum Pouches, Retort Pouches Material: Plastic, Paper, Aluminum Foil, Biodegradable Film End User: Food & Beverage, Personal Care, Healthcare, Household Products Closure Type: Zipper, Heat Seal, Spout, Tear Notch |
| Companies Covered | Grupo HZ, Amcor Group GmbH, Sealed Air Corporation, Sonoco Products Company, Bischof + Klein SE & Co KG, Gualapack SpA, Coresa Argentina, ProAmpac LLC, Mondi Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Pouch Packaging Market Trends and Innovations
Digital printing and smart packaging integration are compressing minimum order quantities and enabling batch-level traceability, while regulatory pressure on recyclability forces material scientists to reinvent barrier performance without legacy multi-layer constructions.
Water-based flexographic ink systems with nanoscale pigment dispersion are rendering obsolete solvent-based rotogravure printing for short-run pouch decoration. Argentine organic brands and craft food startups adopt these systems to eliminate volatile organic compound emissions and reduce make-ready waste from 500 meters to under 50 meters per job. This transition compresses economic order quantities from 100,000 units toward 10,000 units, enabling regional brands to compete with multinational scale economies.
ANMAT's anticipated alignment with EU Single-Use Plastics Directive principles threatens to designate non-recyclable multi-layer pouches as priority reduction targets. The industrial consequence is accelerated investment in mono-material polyethylene and polypropylene barrier films that maintain 12-month shelf stability. Ready-meal and pet food segments face the steepest compliance timelines, with reformulation deadlines likely to precede technical readiness by 18-24 months.
Supermarket private-label buyers now specify pouch suppliers by combined carbon intensity and shelf-impact metrics rather than unit cost alone. Discounters and mid-market chains in Buenos Aires and Rosario award multi-year contracts to converters offering kraft-paper exterior layers with transparent windows, displacing conventional all-plastic stand-up pouches in breakfast cereal and dried fruit categories. This specification shift is most visible in retailer sustainability scorecard programs targeting 30% packaging weight reduction by 2030.
Argentina Pouch Packaging Market Segmentation
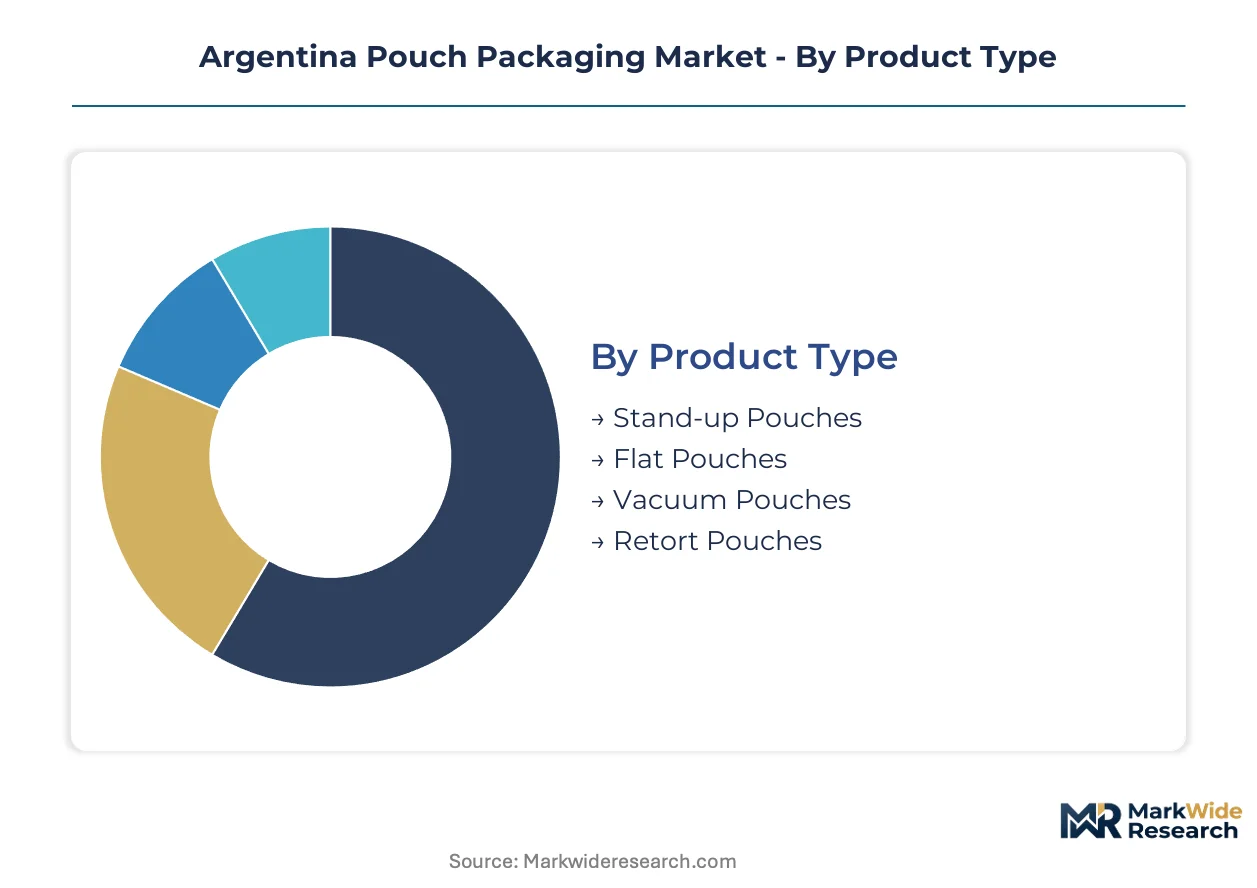
Argentina's pouch packaging market fragments across four structural dimensions that determine converter investment priorities and brand owner procurement strategies. Each segmentation axis carries distinct regulatory, technical, and margin implications for suppliers serving Greater Buenos Aires and provincial production clusters.
Product Type:
Converters across Córdoba and Buenos Aires provinces configure forming equipment around four distinct structural formats, each demanding specialized barrier engineering and sterilization compatibility.
- Stand-up Pouches:These gusseted bottom structures incorporate multi-layer laminates of polyethylene, polyamide, and aluminum foil to achieve 12-month oxygen barrier performance. Argentine breakfast cereal and dried fruit brands in Buenos Aires specify kraft-paper exterior layers with transparent windows to meet retailer sustainability scorecards.
- Retort Pouches:Heat-resistant laminates withstand 121°C sterilization cycles while cutting shipping weight 70% versus metal cans. Meat processors and ready-meal exporters through the Port of Buenos Aires drive capacity expansion for this format.
- Flat Pouches:Two-dimensional sealed envelopes without gusseted bases serve cost-sensitive commodity segments in Mendoza province's wine and juice concentrate sectors.
- Vacuum Pouches:High-barrier coextruded films with oxygen transmission rates below 1 cc/m²/day protect refrigerated meat cuts for domestic distribution and Chilean export routes.
Established volume favors stand-up configurations; emerging adoption favors retort-compatible structures.
Material:
Raw material selection in Argentine converting facilities hinges on ANMAT migration limits and Mercosur recyclability proposals that threaten legacy multi-layer constructions.
- Plastic:Polyethylene and polypropylene laminates dominate current production, though converters face reformulation pressure as ANMAT aligns with EU Single-Use Plastics Directive principles.
- Biodegradable Film:PLA and cellulose-based barriers command premium positioning among organic food labels in Córdoba seeking compostable end-of-life credentials.
- Aluminum Foil:Ultra-thin metallized layers deliver moisture and light barrier performance in retort applications, though non-separable construction blocks municipal recycling streams.
- Paper:Kraft exterior layers with polymer interior coatings satisfy Buenos Aires supermarket private-label specifications for 30% packaging weight reduction targets.
Conventional plastics retain production share leadership; biodegradable alternatives gain share fastest among premium organic segments.
End User:
Demand concentration patterns across Argentine manufacturing sectors determine regional converter location and technical service investment.
- Food & Beverage:Meat processors, dairy cooperatives, and ready-meal brands in Greater Buenos Aires generate half of national pouch consumption, with sauce and condiment sub-segments driving spouted format adoption.
- Personal Care:Shampoo and conditioner pouches remain underpenetrated versus rigid bottles, though Argentine mid-market brands test flexible formats for travel-size positioning.
- Healthcare:Sterile medical device pouches require ISO 11607 compliance, with domestic production concentrated among Buenos Aires-area contract manufacturers serving public hospital procurement.
- Household Products:Laundry detergent and surface cleaner refills in stand-up pouches displace rigid containers in Rosario and Córdoba retail channels.
Food applications anchor installed capacity; healthcare and personal care segments offer untapped expansion corridors for barrier film specialists.
Closure Type:
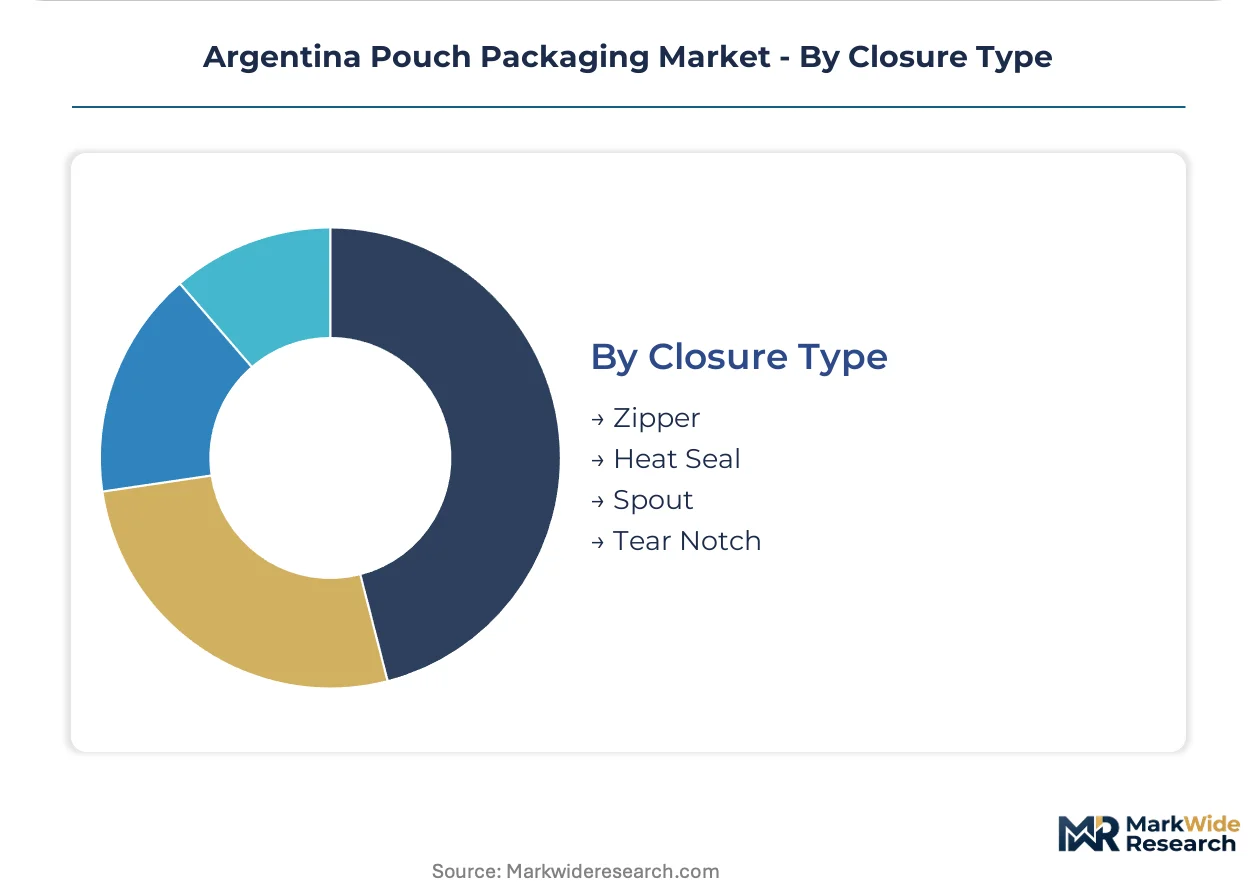
Dispensing convenience specifications separate commodity pouch production from value-added converting operations in Argentina's industrial belt.
- Heat Seal:Permanent fusion bonds remain the default for single-use commodity pouches, offering lowest unit cost for price-sensitive bulk food segments.
- Zipper:Reclosable interlocking profiles command 15-20% price premiums in snack and dried fruit categories, with equipment investments concentrated among Buenos Aires converters serving multinational brand owners.
- Spout:Injection-molded dispensing fitments require specialized forming equipment and local ink supply partnerships, with Gualapack SpA anchoring domestic technical capability for dairy and sauce applications.
- Tear Notch:Laser-scored opening features balance child-resistance with adult accessibility in pharmaceutical and household chemical segments.
Heat seal configurations dominate volume throughput; spout and zipper investments concentrate among exporters targeting Brazilian and Chilean retail specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Film extrusion capacity concentrates in Greater Buenos Aires, where half of Argentina's packaged food production clusters within 50 kilometers of the port and industrial belt. Provincial demand pockets in Córdoba and Mendoza operate on secondary supply chains from Brazilian resin corridors. ANMAT's migration-limit enforcement under Mercosur GMC Resolution 32/07 shapes technical specifications across all sub-regional markets.
Greater Buenos Aires
Meat processors and ready-meal exporters drive retort pouch adoption to cut shipping weight by 70% versus metal cans on Brazilian and Chilean export routes. ANMAT's enforcement of food contact migration limits mandates multi-layer barrier constructions that domestic converters now supply locally. The industrial belt surrounding the Port of Buenos Aires hosts the densest concentration of form-fill-seal machinery and laminating technical expertise in the country.
Córdoba Province
Organic food labels in this central agricultural region seek compostable pouch alternatives to conventional plastics, creating premium positioning for converters with PLA or cellulose-based barrier certifications. Argentina's Secretariat of Industry and Productive Development administers import substitution incentives that favor domestic film extrusion over finished pouch imports. Dairy cooperatives and sauce manufacturers here remain underpenetrated by spouted dispensing formats.
Mendoza Province
Wine and juice concentrate sectors in this western region favor flat pouch configurations for cost-sensitive bulk packaging applications. Brazilian petrochemical suppliers provide polyethylene and polypropylene feedstock across the Andean border, exposing margins to cross-border logistics disruptions. Local converters serve domestic distribution with limited retort capability compared to Buenos Aires-based competitors.
Rosario Industrial Corridor
Household product refill applications in stand-up pouches displace rigid containers in this Santa Fe province retail channel. Supermarket private-label buyers specify combined carbon intensity and shelf-impact metrics rather than unit cost alone. Discounters here award multi-year contracts to converters offering kraft-paper exterior layers with transparent windows.
Patagonian Export Zones
Seafood processors in Chubut and Santa Cruz provinces require high-barrier vacuum pouch structures for refrigerated distribution to Chilean markets. ANMAT alignment with EU Single-Use Plastics Directive principles threatens to designate non-recyclable multi-layer pouches as priority reduction targets. Technical service investment from Buenos Aires-based converters remains limited due to distance and lower demand density.
Argentina Pouch Packaging Market Competitive Landscape
Multinational laminate suppliers and domestic forming specialists split the market into complementary capability tiers. The structure consolidates around three strategic archetypes: global film and laminating conglomerates with regional extrusion footprints, specialized spouted pouch equipment owners with local ink partnerships, and mid-scale converters exploiting import substitution incentives through backward integration. Dominant competitive moves include capacity expansion in high-barrier retort structures and strategic partnerships between equipment suppliers and resin distributors to secure feedstock allocation.
Among global laminate suppliers, Amcor Group GmbH and Mondi Group exemplify the multinational tier with regional laminating footprints serving Buenos Aires-based food exporters. Gualapack SpA anchors the domestic spouted pouch segment through specialized forming equipment presence. These three represent distinct strategic positions: global scale with local adaptation, format-specific technical depth, and equipment-integrated service capability respectively.
| Leading Market Players |
|---|
| Grupo HZ |
| Amcor Group GmbH |
| Sealed Air Corporation |
| Sonoco Products Company |
| Bischof + Klein SE & Co KG |
| Gualapack SpA |
| Coresa Argentina |
| ProAmpac LLC |
| Mondi Group |
| Others |
Pricing and Supply Chain Analysis
Brazilian petrochemical feedstock concentration upstream funnels margin pools toward converters in Greater Buenos Aires with backward-integrated film extrusion capabilities and ANMAT-certified multi-layer laminating expertise.
Pricing Analysis
Mercosur GMC Resolution 32/07 migration limits dictate the pricing tier structure across Argentine pouch packaging. Three-tier pricing stratifies across premium retort-compatible multi-layer structures, standard stand-up pouches with conventional barrier films, and economy flat pouch formats for bulk commodities. Price differentiation hinges on ANMAT certification grade and volume scale, with certified retort structures commanding substantial premiums over uncertified alternatives. Pricing pressure stems from resin import dependency on Brazilian polyethylene and polypropylene suppliers, exposing margins to cross-border logistics disruptions. Brand owners in the organic food segment exhibit lowest price sensitivity, prioritizing compostable film credentials over unit cost.
Supply Chain Analysis
Tariff exposure between Argentina and Brazil dominates supply chain risk architecture for Argentine converters. Raw material sourcing draws from Brazilian petrochemical corridors for polyethylene and polypropylene feedstock, with secondary aluminum foil supply anchored in domestic metallurgy and imported Asian metallized films. Single-source vulnerability concentrates in cross-border resin pipelines traversing the Mercosur customs union. Distribution runs through Buenos Aires port infrastructure and provincial industrial clusters in Córdoba and Rosario, with just-in-time delivery networks serving meat processors and ready-meal exporters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Argentina's pouch packaging sector sits at a high-growth inflection as ANMAT's anticipated alignment with EU Single-Use Plastics Directive principles threatens to disqualify legacy multi-layer structures and force rapid mono-material reformulation.
For Market Incumbents: Pre-empt regulatory obsolescence by accelerating investment in mono-material polyethylene and polypropylene barrier films capable of replicating 12-month oxygen barrier performance without aluminum foil. Secure backward integration into domestic film extrusion to exploit Secretariat of Industry import substitution incentives. Anchor technical service teams in Greater Buenos Aires to defend against Brazilian flexible packaging capacity encroachment. For New Entrants and Emerging Players: Pursue biodegradable film specialization targeting organic food labels in Córdoba and Mendoza provinces seeking compostable pouch alternatives. Spouted pouch format penetration in dairy and sauce segments offers the most accessible white space, requiring specialized forming equipment partnerships rather than commodity converting scale. Lead with ANMAT certification credentials and local ink supply partnerships to bypass incumbent equipment-lock advantages. For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-scale Argentine converters holding ANMAT-certified laminating capacity and established relationships with Buenos Aires-based meat processors and ready-meal exporters. Long-term viability hinges on technical readiness for mono-material transition before regulatory deadlines precede capability. Watch for proposed Mercosur technical regulation updates mandating recyclable structures as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Barrier Film R&D | ANMAT's anticipated EU alignment threatens multi-layer obsolescence, forcing technical reinvention of oxygen and moisture protection. |
| Backward Integration into Film Extrusion | Secretariat of Industry incentives reward domestic resin conversion over finished pouch imports, capturing margin pools upstream. |
| Spouted Pouch Equipment Investment | Gualapack's domestic technical dominance leaves white space for specialized forming and zipper-sealing capabilities in dairy applications. |
| Biodegradable Film Certification | Organic labels in Córdoba seek PLA and cellulose-based barriers for compostable end-of-life differentiation and premium positioning. |
| Retort Pouch Capacity Expansion | Meat processors and ready-meal exporters through Port of Buenos Aires drive 70% shipping weight reduction versus metal cans. |
Research Methodology
A standing panel of plant managers at Argentine converting facilities, procurement leads at Buenos Aires-based food exporters, ANMAT regulatory affairs specialists, and laminating equipment technicians provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation from ANMAT food contact material filings, Secretariat of Industry incentive program documentation, Mercosur GMC Resolution 32/07 technical standards, and Brazilian petrochemical trade flow data. Bottom-up capacity assessments at individual converting facilities triangulated against top-down demand estimates from packaged food production statistics.
Scenario-bracketing anchored the analytical framework across the projection horizon, modeling demand trajectories under varying assumptions for ANMAT regulatory alignment timing and mono-material technical readiness. Segmentation dimensions included product type, material composition, end-use industry, and closure configuration, with additional granularity around sterilization compatibility and sustainability certification tiers. CAGRs derived from fitted growth curves applied to base-year estimates, cross-referenced against resin price elasticity assumptions and export route freight cost structures.
Sensitivities concentrate around ANMAT regulatory update timing, Brazilian resin supply disruptions, and mono-material barrier performance achievement. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Child Resistant Pouches Market
Pouch
Global Medical and Pharmaceutical Pouch Market
Pouch
Asia-Pacific Pouch Packaging Market
Pouch
Aluminum Foil Zipper Pouch Market
Pouch
Inflatable Pouches Market
Pouch
Vietnam Pouch Packaging Market
Pouch
North America Stand-Up Pouch Packaging Market
Pouch
Morocco Pouch Packaging Market
Pouch
United States Retort Pouches Market
Pouch
Flexible Plastic Pouches Market
Pouch
Thailand Pouch Packaging Market
Pouch
Child Resistant Single Dose Pouches Market
Pouch
Stand Up Paper Pouches Market
Pouch
Cold Seal Lamination Pouch Market
Pouch
Global Pouches Packaging Market
Pouch
Child Resistant Locking Pouches Market