
 Foil Pouch Packaging Market | 2026-2036
Foil Pouch Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Foil Pouch Packaging Market Foresight
Ready-to-eat meals and retort food applications are shifting toward higher-barrier foil pouch formats as processors seek extended shelf stability without cold chain dependency. Amcor plc leverages its global laminating infrastructure to supply multi-layer foil structures for pharmaceutical and food clients. ProAmpac Intermediate, Inc. specializes in spout and fitment integration for liquid and semi-solid formats. Mondi Group anchors European demand through its recycled-content aluminum hybrid films.
Foil pouch packaging consists of flexible laminated structures incorporating aluminum foil layers between polymer films, typically achieving oxygen transmission rates below 0.1 cc/m²/day and moisture vapor transmission rates under 0.1 g/m²/day, primarily engineered to protect oxygen-sensitive and moisture-degradable contents across food, pharmaceutical, and chemical supply chains. Stand-up pouches occupy the largest volume position due to retail shelf visibility and dispensing convenience, though spout pouches represent the fastest-growing configuration as beverage and liquid food brands convert from rigid containers. Aluminum foil laminates retain the highest margin pool among material categories because of technical complexity and pharmaceutical qualification requirements, while metallized film competes aggressively in cost-sensitive snack and confectionery segments.
FDA regulations governing indirect food contact materials and pharmaceutical packaging integrity directly shape foil pouch specification requirements in the United States, while REACH and the EU Packaging and Packaging Waste Regulation mandate recyclability assessments and substance restrictions across European supply chains. EMA guidelines for primary packaging materials further tighten barrier validation protocols for drug products distributed in foil-based formats. Stakeholders must monitor evolving extended producer responsibility frameworks and mono-material recyclability targets that could force structural redesigns of multi-layer foil laminates.
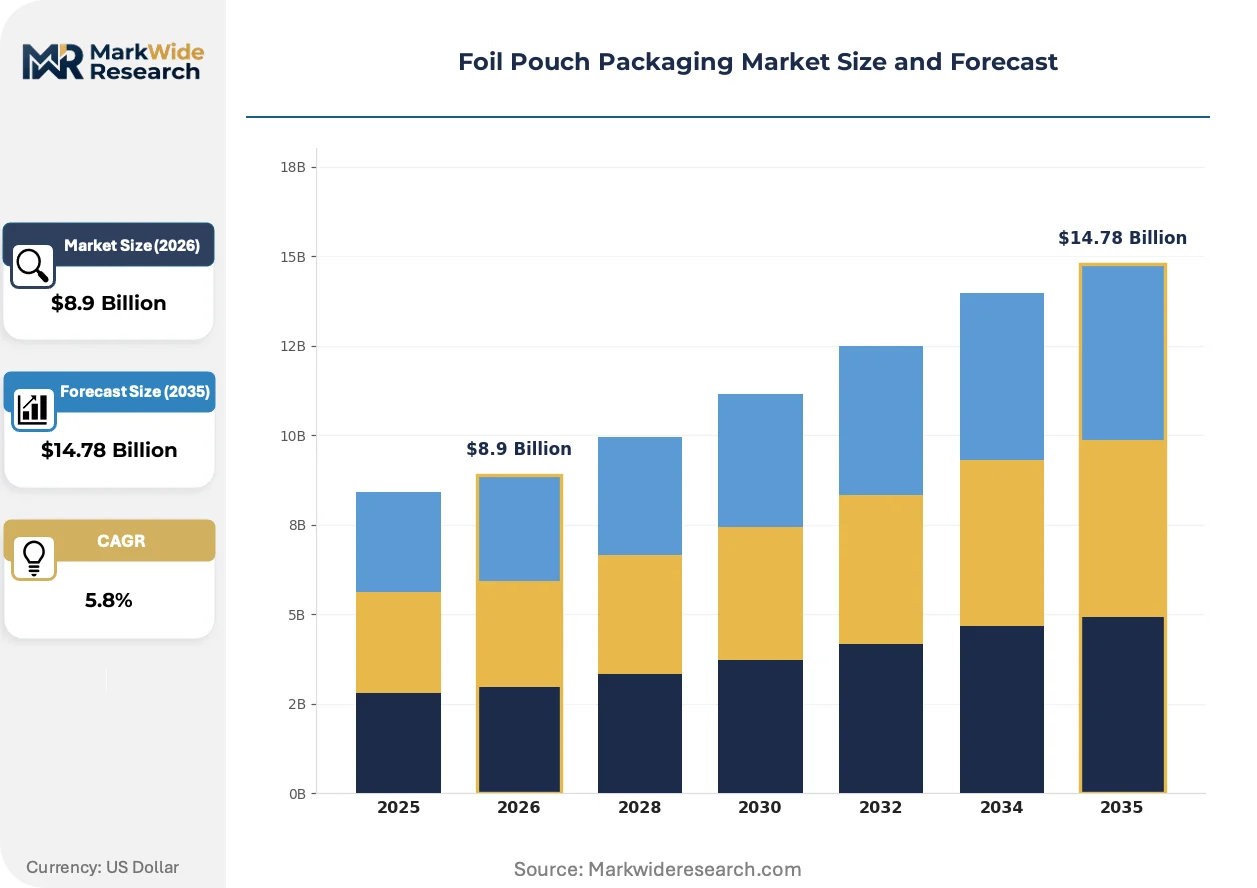
Market Dynamics
Multi-layer foil laminate structures face structural pressure from EU Packaging and Packaging Waste Regulation recyclability mandates, forcing processors to redesign barrier films without sacrificing oxygen and moisture protection.
Growth Catalysts
- Retort food processing expansion:Ready-to-eat meal manufacturers in Germany and the United States are specifying high-barrier foil pouches for ambient-stable protein formats, eliminating cold chain infrastructure requirements.
- EMA barrier validation protocols:Pharmaceutical packaging qualification standards for primary aluminum-based containers are tightening, creating specification premiums for validated laminate suppliers.
- Spout fitment integration:Liquid food and beverage brands are converting rigid bottle formats to flexible spout pouches, driving pouch machinery retrofit cycles and laminate throughput.
Market Restraints
- Aluminum ingot cost volatility:Primary aluminum pricing fluctuations transmit directly to laminate converters, compressing margin pools on fixed-price annual contracts.
- German converter concentration:High-specification pharmaceutical foil laminates concentrate among a limited supplier base near Frankfurt and Munich industrial clusters, creating single-source vulnerability.
- Metallized film substitution:Cost-sensitive snack processors in India and Brazil are downgrading from aluminum foil to vacuum-metallized PET for oxygen barriers below 1 cc/m²/day.
Strategic Opportunities
- Mono-material recyclable laminates:Polyethylene-based barrier films with aluminum oxide coatings are emerging as drop-in replacements for multi-layer structures under EU Green Deal circular economy targets.
- India pharmaceutical cold-chain bypass:Foil pouch formats for temperature-sensitive biologics address infrastructure gaps in Maharashtra and Gujarat distribution networks.
- E-commerce direct-to-consumer formats:Single-serve and sample-size foil pouches bypass traditional retail shelf constraints, opening specialty chemical and cosmetic ingredient channels.
Industry Challenges
- Multi-layer delamination expertise:Adhesive formulation chemists capable of bonding aluminum to bio-based sealant layers command wage premiums exceeding 40% above standard packaging engineers.
- Retort process validation timelines:FDA food contact notification cycles for new laminate structures extend 18-24 months, freezing product development pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foil Pouch Packaging Market |
| Market Size in 2026 | $8.9 Billion |
| Market Size in 2035 | $14.78 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-up Pouches, Spout Pouches, Flat Pouches, Gusseted Pouches, Vacuum Pouches Material: Aluminum Foil, Polyester, Nylon, Polyethylene, Metallized Film Application: Food & Beverages, Personal Care, Pharmaceuticals, Pet Care, Chemicals End User: Manufacturers, Brand Owners, Retailers, Distributors, Contract Packers |
| Companies Covered | Amcor plc, ProAmpac Intermediate, Inc., Sealed Air, Mondi Group, Sonoco Products Company, Constantia Flexibles Group GmbH, Winpak, Berry Global Group, Inc., Flair Flexible Packaging Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foil Pouch Packaging Market Shifts & Advancements
Barrier technology is fragmenting across competing material platforms as sustainability mandates collide with shelf-life performance requirements, creating parallel development tracks rather than convergent standards.
Aluminum oxide deposition on oriented polyamide films is modularizing barrier film supply chains by enabling regional converters to source base films locally and apply barrier coatings through plasma-enhanced chemical vapor deposition systems. Pharmaceutical contract packagers in Switzerland and the Netherlands are piloting these structures for moisture-sensitive solid dose formats. The technology is modularizing what was previously a concentrated aluminum foil rolling and laminating value chain into distributed coating operations.
REACH substance restriction expansions are forcing laminate producers to eliminate per- and polyfluoroalkyl substances from grease-resistant sealant layers by 2026. Food contact material suppliers must reformulate heat-seal coatings without compromising retort temperature resistance. German and French ready-meal processors are accelerating qualification timelines for PFAS-free alternatives ahead of enforcement windows.
Brand-owners are consolidating supplier panels from twelve-plus regional converters to three validated partners with integrated spout insertion and aseptic filling capabilities. This concentration compresses switching flexibility but secures capacity allocation during resin shortage periods. The pattern is most pronounced among North American organic infant nutrition brands seeking dual-source redundancy with single-point accountability.
Foil Pouch Packaging Market Segmentation
Foil pouch packaging segments diverge sharply across performance requirements and supply chain complexity. Material selection and pouch geometry determine barrier specifications, regulatory pathways, and equipment compatibility for end-users.
Product Type:
Customization intensity varies from standardized flat formats to engineered spout systems requiring fitment welding and cap integration.
- Stand-up Pouches:Self-supporting bottom-gusset structures with front-facing billboard panels dominate retail shelf placement for snacks, grains, and pet food. German and U.S. organic food brands specify high-barrier laminates with resealable zipper closures for ambient protein formats.
- Spout Pouches:Fitment-integrated formats with injection-molded dispensing closures are displacing rigid bottles for baby food, sauces, and beverages. Swiss and Dutch dairy processors drive qualification timelines for aseptic spout filling lines.
- Flat Pouches:Two-seal or three-seal pillow formats serve cost-sensitive powder and chemical applications with minimal material usage.
- Gusseted Pouches:Side-folded structures expand fill volume for coffee and dried fruit without stand-up requirements.
- Vacuum Pouches:Thermoformable barrier films for chamber-sealed meat and cheese formats prioritize oxygen exclusion over print aesthetics.
Leading the category by volume: Stand-up Pouches. Expanding most quickly: Spout Pouches.
Material:
Cost tiers separate pharmaceutical-grade laminates from commodity snack packaging, with metallized films capturing mid-range barrier requirements.
- Aluminum Foil:Cold-rolled aluminum layers between 6-12 microns deliver sub-0.1 cc/m²/day oxygen transmission for pharmaceutical blister packs and retort meals. EMA validation protocols and FDA food contact notifications create 18-24 month qualification barriers for new suppliers.
- Metallized Film:Vacuum-deposited aluminum on PET or OPP substrates achieves 0.5-2.0 cc/m²/day barriers at 40% lower laminate cost, dominating Indian and Brazilian snack markets where shelf life requirements permit moderate oxygen ingress.
- Polyester:Biaxially oriented PET provides dimensional stability and print clarity as outer web layers in multi-ply structures.
- Nylon:Oriented polyamide contributes puncture resistance and thermoformability for vacuum and retort applications.
- Polyethylene:Sealant layers and mono-material recyclable structures are reformulating to eliminate PFAS under REACH substance restrictions.
Highest margin pool: Aluminum Foil. Fastest volume growth: Metallized Film.
Application:
End-use concentration determines barrier specification stringency, with pharmaceutical and retort food segments demanding validated laminates.
- Food & Beverages:Retort-ready meals, ambient soups, and premium coffee drive high-barrier foil laminates with 12-24 month shelf life targets. German ready-meal processors specify PFAS-free sealants ahead of enforcement windows.
- Pharmaceuticals:Blister packs, sachets, and strip packaging for moisture-sensitive solid doses require EMA-compliant barrier validation and aluminum foil with pinhole-free specifications.
- Personal Care:Single-serve masks, serums, and cosmetic samples utilize metallized or aluminum oxide barrier films with premium print finishes.
- Pet Care:Wet food and treat formats mirror human food barrier requirements with lower regulatory qualification burdens.
- Chemicals:Agricultural actives and industrial powders prioritize chemical resistance and child-resistant closure compatibility over oxygen barrier.
Largest volume share: Food & Beverages. Steepest specification escalation: Pharmaceuticals.
End User:
Procurement authority and technical capability separate integrated manufacturers from outsourcing-dependent brand owners.
- Brand Owners:Nestlé, Unilever, and pharmaceutical multinationals dictate laminate specifications through approved vendor lists and audit protocols, concentrating volume among three validated partners with integrated spout insertion capabilities.
- Contract Packers:Toll manufacturers in Switzerland and the Netherlands invest in aseptic spout filling lines to serve organic infant nutrition brands seeking dual-source redundancy.
- Manufacturers:Vertically integrated food processors with captive pouch forming equipment source master rolls rather than finished pouches.
- Retailers:Private label programs for discount chains drive standardization toward metallized film formats with 6-month shelf life specifications.
- Distributors:Regional converters serving chemical and agricultural sectors stock generic vacuum pouch inventories with minimal customization.
Specification authority concentrates with Brand Owners. Fastest capacity investment: Contract Packers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Maharashtra and Gujarat concentrate pharmaceutical foil pouch manufacturing for temperature-sensitive biologics distribution. These zones attract converters through tax incentives and streamlined customs processing for aluminum foil imports.
Germany
Frankfurt and Munich industrial clusters host high-specification pharmaceutical laminate suppliers serving EMA-validated drug packaging. REACH substance restrictions are forcing PFAS elimination from sealant layers by 2026. Baden-Württemberg converters are accelerating qualification timelines for retort-ready meal formats ahead of enforcement windows.
United States
FDA food contact notification cycles spanning 18-24 months freeze new laminate development pipelines for ready-to-eat meal processors. Organic infant nutrition brands in California and New York Metro are consolidating supplier panels to three validated partners. Pacific Northwest specialty coffee roasters drive demand for high-barrier stand-up pouches with extended shelf life targets.
India
Maharashtra and Gujarat distribution networks bypass cold-chain infrastructure gaps through foil pouch formats for temperature-sensitive pharmaceuticals. BIS standards for food contact materials are tightening barrier performance specifications. Mumbai-Pune industrial corridor converters are retrofitting lines for spout pouch integration serving liquid food brands.
Switzerland
Swissmedic guidelines for primary packaging materials tighten barrier validation protocols for aluminum-based drug containers. Basel and Zurich pharmaceutical contract packagers pilot aluminum oxide-coated polyamide films for moisture-sensitive solid doses. The country's precision manufacturing heritage supports premium laminate qualification for export markets.
Netherlands
Dutch dairy processors drive aseptic spout filling line qualifications for beverage and liquid food conversion from rigid bottles. Rotterdam port logistics facilitate aluminum foil import flows for laminate converters serving northwest European markets. Eindhoven Region coating technology specialists are modularizing barrier film supply chains through plasma-enhanced chemical vapor deposition systems.
Foil Pouch Packaging Market Competitive Landscape
Top-tier vendors anchor pharmaceutical and retort food qualification tiers, while regional converters serve cost-sensitive snack and commodity chemical segments. The market structures around three strategic archetypes: integrated multinationals with global laminating infrastructure, specialized fitment-integrators for liquid formats, and regional metallized film suppliers competing on laminate cost. Dominant competitive moves include capacity consolidation through approved vendor list concentration and backward integration into aluminum oxide coating technology.
Within the integrated multinational tier, Amcor plc and Mondi Group exemplify archetypes spanning pharmaceutical validation and recycled-content film development. ProAmpac Intermediate, Inc. occupies a position among fitment-integration specialists. These three entities represent the supplier consolidation pattern where brand owners compress twelve-plus regional relationships to three validated partners with integrated spout insertion capabilities.
| Leading Market Players |
|---|
| Amcor plc |
| ProAmpac Intermediate, Inc. |
| Sealed Air |
| Mondi Group |
| Sonoco Products Company |
| Constantia Flexibles Group GmbH |
| Winpak |
| Berry Global Group, Inc. |
| Flair Flexible Packaging Corporation |
| Others |
Supply & Pricing Matrix
Adhesive formulation chemists capable of bonding aluminum to bio-based sealant layers concentrate in Frankfurt and Munich industrial clusters, and this workforce scarcity widens pricing spreads between pharmaceutical-grade laminates and commodity snack formats. Labor-cost differentials between these German specialists and standard packaging engineers in India or Brazil translate directly into tiered laminate pricing.
Pricing Analysis
Lead-time premiums dominate contract negotiations, with EMA-validated pharmaceutical laminates commanding substantial markups for sub-12-week delivery windows while spot inventory of metallized snack films trades at discounts. Three-tier pricing structure across premium, standard, and economy levels separates EMA-validated pharmaceutical laminates, FDA food-contact-certified retort films, and unqualified metallized commodity formats. Price differentiation rests on certification tier and volume scale, with annual offtake commitments above master-roll thresholds unlocking standard-tier access. Cost compression in metallized snack films is intensifying because Indian and Brazilian processors downgrade from aluminum foil to vacuum-metallized PET. Contract packers in Switzerland and the Netherlands exhibit lowest price sensitivity due to qualification switching costs, while discount retailers sourcing private-label vacuum pouches show highest sensitivity.
Supply Chain Analysis
EMA and FDA qualification gating restricts validated laminate supply to converters with 18-24 month notification cycle completion, concentrating pharmaceutical-grade production in Germany, Switzerland, and the Netherlands. Raw material dependencies draw from primary aluminum ingot flows through Rotterdam port, oriented polyamide base films from regional European polymer producers, and PFAS-free sealant resins under REACH reformulation timelines. Supply chain risk centers on single-source vulnerability for high-specification pharmaceutical foil laminates near Frankfurt and Munich. Distribution runs through approved vendor list concentration, with brand owners compressing twelve-plus regional relationships to three validated partners with integrated spout insertion capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foil pouch packaging is transitioning from multi-layer aluminum laminates toward mono-material recyclable structures, with aluminum oxide deposition on oriented polyamide films displacing cold-rolled foil in moisture-sensitive solid dose applications.
For Market Incumbents: Hedge qualification concentration risk by diversifying EMA-validation capacity beyond Frankfurt and Munich clusters into Switzerland and the Netherlands. Secure backward integration into aluminum oxide coating technology through plasma-enhanced chemical vapor deposition partnerships in Eindhoven Region. Metallized film substitution in Indian and Brazilian snack markets threatens volume retention in commodity tiers. For New Entrants and Emerging Players: The mid-tier price-point gap between pharmaceutical-validated laminates and unqualified metallized films creates entry space for converters mastering PFAS-free sealant formulation ahead of REACH enforcement. Target Maharashtra and Gujarat pharmaceutical distribution networks bypassing cold-chain infrastructure gaps. Pursue toll manufacturing relationships with Swiss and Dutch dairy processors seeking aseptic spout filling capacity. For Investors and Strategic Acquirers: Re-rating potential sits with specialized fitment-integrators given spout pouch conversion acceleration among beverage and liquid food brands. Long-term viability favors converters with dual capability across aluminum foil laminating and aluminum oxide coating platforms. Watch EMA barrier validation protocol tightening as inflection indicator for specification premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Sealant Reformulation | REACH substance restrictions by ECHA force 2026 elimination timeline for German and French processors. |
| Aluminum Oxide Coating Capacity | Plasma-enhanced chemical vapor deposition modularizes barrier supply chains for Swiss pharmaceutical packagers. |
| Aseptic Spout Filling Integration | Dutch dairy processors drive qualification timelines displacing rigid bottle formats. |
| Mono-Material Recyclable Laminate Development | EU Packaging and Packaging Waste Regulation recyclability mandates accelerate polyethylene-based barrier film adoption. |
| Approved Vendor List Consolidation | North American organic infant nutrition brands compress supplier relationships to three validated partners with dual-source redundancy. |
Research Methodology
Trade association filings, customs import records, and regulatory notification databases formed the secondary backbone, cross-referenced against primary interviews with adhesive formulation chemists, pharmaceutical contract packaging executives, and food contact material compliance officers. Bottom-up laminate volume estimates from converter capacity utilization rates were triangulated against top-down end-use demand segmentation across retort meals, blister packs, and beverage spout applications.
Historical trendline analysis of aluminum ingot pricing transmission, EMA validation cycle durations, and spout pouch machinery retrofit rates informed projection modeling across material, product type, and application dimensions throughout the forecast period. CAGRs were derived from segment-level growth rate convergence analysis. Industry-specific forecast inputs incorporated REACH substance restriction enforcement timelines and PFAS-free sealant qualification acceleration patterns.
Underlying measurement precision varies by segment; pharmaceutical and retort food laminates carry tighter precision than commodity metallized snack films due to validated supplier concentration. Forecasts reflect documented assumptions regarding regulatory enforcement timing and raw material cost transmission elasticity. A model refresh is warranted upon material change in EU Packaging and Packaging Waste Regulation recyclability mandate implementation or aluminum oxide coating technology yield breakthroughs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Center Seal Pouch Making Machine Market
Pouch
Stand-Up Pouches Market
Pouch
Italy Pouch Packaging Market
Pouch
Peelable Pouches Market
Pouch
Saudi Arabia Pouch Packaging Market
Pouch
Compostable Pouches Market
Pouch
Inflatable Pouches Market
Pouch
Rice Paper Stand Up Pouch Market
Pouch
Asia-Pacific Retort Pouch Market
Pouch
Recyclable PE Pouch Market
Pouch
Middle East and Africa Pouch Packaging Market
Pouch
Pouch Dispensing Fitment Market
Pouch
North America Stand-Up Pouch Packaging Market
Pouch
Kraft Block Bottom Pouch Market
Pouch
India Pouch Packaging Market
Pouch
United States Retort Pouches Market