
 Inverted Pouch Market | 2026-2036
Inverted Pouch Market Size, Share, and Industry Trends Forecast 2026-2036
Inverted Pouch Market Analysis
Subscription-based pouch design services is decoupling hardware sales from recurring revenue in flexible packaging. Glenroy Inc. leverages its Wisconsin manufacturing base to dominate North American custom laminate production for inverted formats. Amcor Plc anchors global supply through its integrated film-to-pouch operations across multiple continents. Berry Global competes on scale, sustaining one of the broadest plastic laminate portfolios in the converted flexible packaging sector.
An inverted pouch is a flexible container engineered with the spout or dispensing aperture positioned at the bottom, constructed from multi-layer laminates typically combining polyethylene, polyester, and adhesive tie layers through coextrusion or adhesive lamination processes, designed to enable gravity-assisted evacuation of viscous or semi-liquid contents. Plastic laminates occupy the dominant material position due to their moisture barrier performance and seal integrity under mechanical stress. Zip closure formats are gaining traction in personal care and household segments where resealability extends product usable life. Biodegradable materials represent the fastest-evolving material category, though performance gaps in oxygen transmission rates currently limit penetration beyond premium niche applications.
FDA maintains jurisdiction over food-contact substances under 21 CFR regulations, while EPA oversees resin manufacturing emissions that affect laminate cost structures; in Europe, EFSA and REACH collectively govern migration limits and substance authorization for pouches entering consumer markets. These frameworks compel converters to maintain dual certification portfolios, raising capital requirements for new market entrants. Stakeholders must monitor evolving state-level extended producer responsibility laws in the United States, as these could mandate recycled content thresholds that reshape laminate specifications and supplier qualification criteria.
Market Dynamics
Quick-service restaurant chains in the United States are mandating portion-controlled condiment formats, compressing converter order cycles and forcing laminate suppliers to accelerate qualification timelines for inverted pouch specifications.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Revisions to substrate compliance rules are compelling CPG brands to redesign laminate stacks, creating replacement demand for certified inverted pouch structures.
- Single-serve condiment pouches:North American food packaging buyers are expanding purchase volumes for inverted formats that enable gravity-assisted evacuation of viscous contents.
- Zip closure technology:Resealable aperture designs are penetrating personal care and household segments, extending product usable life and justifying premium positioning.
Market Restraints
- Resin cost volatility:Polyethylene and polyester feedstock price swings compress converter margins and complicate long-term contract pricing with quick-service restaurant chains.
- Biodegradable performance gaps:Oxygen transmission rate deficiencies in compostable laminates limit penetration beyond premium niche applications in food-contact packaging.
- Dual certification burden:FDA 21 CFR compliance for US markets and EFSA authorization for European entry raise capital requirements for new laminate converters.
Strategic Opportunities
- Extended producer responsibility laws:State-level mandates in the United States for recycled content thresholds will reshape supplier qualification criteria and favor early-moving converters.
- Household cleaning concentrates:Inverted pouches for refill systems represent underpenetrated application space as retailers reduce shelf space for rigid bottle formats.
- Subscription-based design services:Recurring revenue models decouple hardware sales from custom laminate engineering, locking in multi-year relationships with CPG brands.
Industry Challenges
- Multi-layer lamination expertise:Shortage of adhesive tie layer specialists and coextrusion engineers constrains production scaling for complex inverted pouch structures.
- Migration testing timelines:FDA and EFSA certification cycles for new laminate formulations extend 18-24 months, delaying revenue recognition on R&D investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inverted Pouch Market |
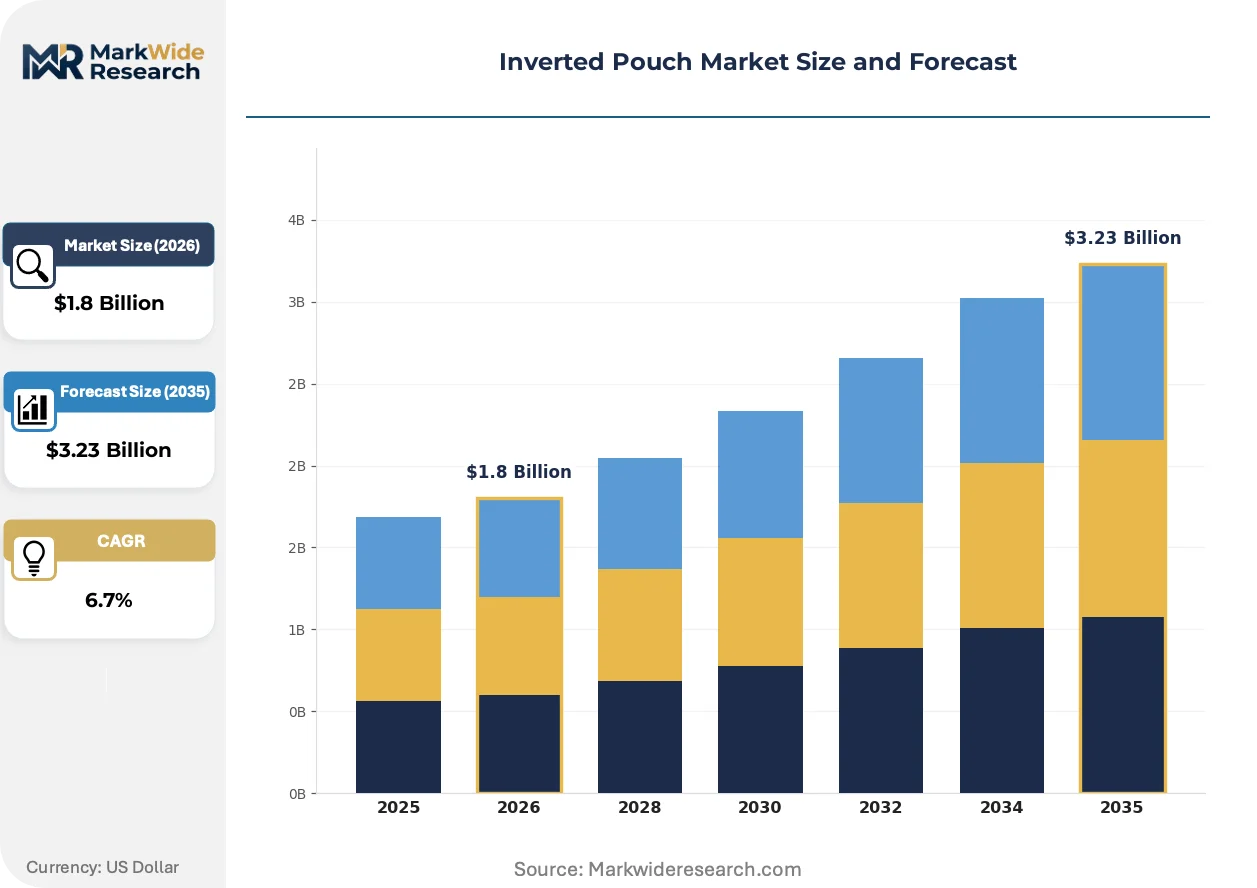
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Closure Type: Zip Closure, Heat Seal, Slide Seal, Press-to-Close Material Type: Plastic Laminates, Aluminum Foil, Paper, Biodegradable Materials Application Type: Food Packaging, Personal Care, Pharmaceuticals, Household Products Shape: Square, Rectangular, Oval, Custom Shapes |
| Companies Covered | Glenroy Inc., Amcor Plc, Berry Global, ProAmpac, Polymer Packaging Inc., Semco S.A.M, Mondi, Tetra Pak, Cheer Pack, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inverted Pouch Market Emerging Trajectories
Flexible packaging converters are reconfiguring production lines around gravity-assisted dispensing architectures, with material science and regulatory compliance emerging as the primary axes of technical differentiation.
Coextruded barrier films with enhanced moisture resistance are consolidating technical leadership in inverted pouch construction. Quick-service restaurant chains and CPG brands are specifying these laminates for condiment and sauce applications at accelerating rates. This consolidation is compressing market share for converters reliant on older adhesive lamination processes with inferior seal integrity under mechanical stress.
REACH substance authorization requirements in Europe are tightening migration limits for adhesive components in food-contact laminates. Converters must reformulate tie layers or face exclusion from EU consumer markets. Personal care brands with pan-European distribution are most affected, accelerating qualification of alternative adhesive chemistries ahead of 2025 enforcement milestones.
Buyer consolidation among US quick-service restaurant chains is compressing supplier negotiation cycles and unbundling pouch design from long-term equipment contracts. Smaller CPG brands are responding by pooling specification development through third-party packaging consultants. This pattern is most visible in the condiment segment, where portion-control mandates from major chains cascade down to mid-tier private label suppliers.
Inverted Pouch Market Segmentation
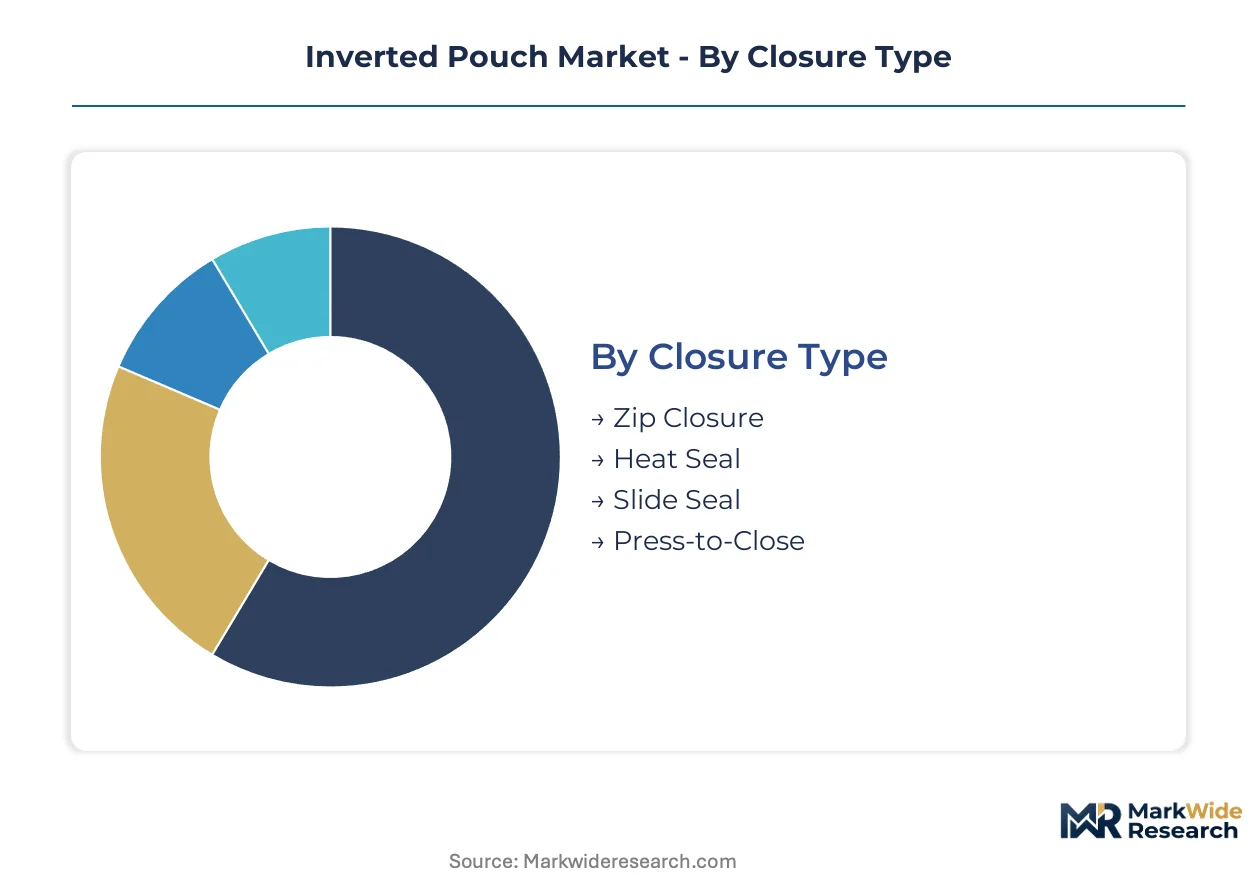
Inverted pouch converters engineer laminate specifications around closure mechanics, barrier performance, and dispensing geometry. Each segmentation dimension carries distinct tooling investments and regulatory qualification burdens that reshape supplier competitive position.
Closure Type:
Supply concentration for complex aperture mechanisms favors converters with captive zipper extrusion or licensed sealing technology partnerships.
- Zip Closure:Multi-track interlocking profiles manufactured from polyethylene blends enable repeated opening cycles without seal degradation. Personal care brands in the United States specify these formats for hair mask and lotion refills where resealability extends product usable life.
- Heat Seal:Fusion bonding of coextruded barrier layers creates tamper-evident seals with zero additional hardware cost. Quick-service restaurant chains mandate heat-sealed condiment pouches for portion-controlled sauce dispensing where single-use economics dominate.
- Slide Seal:Slider-actuated closure systems integrate molded polyethylene components with laminated film bodies. Household cleaning concentrate brands favor this format for refill pouch applications requiring controlled pouring.
- Press-to-Close:Snap-fit aperture designs reduce zipper royalty costs while maintaining finger-press resealability. Mid-tier CPG brands specify these for economy-tier personal care products.
Today's leader: Heat Seal. Tomorrow's challenger: Zip Closure.
Material Type:
Cost tier stratification separates commodity polyethylene laminates from certified barrier structures carrying EFSA migration compliance premiums.
- Plastic Laminates:Multi-layer coextrusions combining polyethylene, polyester, and adhesive tie layers deliver moisture barriers below 0.1 g/m²/day transmission rates. FDA 21 CFR certification cycles for new laminate formulations extend 18-24 months, locking in incumbent converter relationships.
- Biodegradable Materials:Polylactic acid and polyhydroxyalkanoate blends compost under industrial conditions but exhibit oxygen transmission rates 3-5x higher than conventional barriers. Premium organic food brands in California and New York accept performance trade-offs for sustainability positioning.
- Aluminum Foil:Metallized or unsupported foil layers provide near-zero oxygen and light transmission for pharmaceutical and retort food applications.
- Paper:Fiber-based substrates with polymer barrier coatings serve dry goods segments where moisture protection requirements moderate.
Plastic Laminates command current volume. Biodegradable Materials face the steepest expansion trajectory as EPR mandates harden.
Application Type:
Customer type concentration among quick-service restaurant procurement departments compresses converter margins while locking in multi-year specification agreements.
- Food Packaging:Gravity-assisted evacuation of ketchup, mayonnaise, and hot sauce drives specification for 3-5 mil polyethylene-polyester laminates with bottom-mounted spouts. Chains with headquarters in Illinois and Texas mandate inverted formats for drive-thru condiment distribution.
- Personal Care:Viscous shampoo, conditioner, and body wash formulations require wider aperture diameters and enhanced squeeze resistance. Resealable closures justify premium shelf pricing for salon-format professional products.
- Pharmaceuticals:Unit-dose liquid medication pouches demand child-resistant closure certification and validated seal integrity testing.
- Household Products:Concentrated cleaning solutions for spray-bottle refill systems reduce retail shelf space requirements versus rigid packaging.
Food Packaging owns present revenue. Household Products represent the fastest-climbing application as retailers delist rigid bottles.
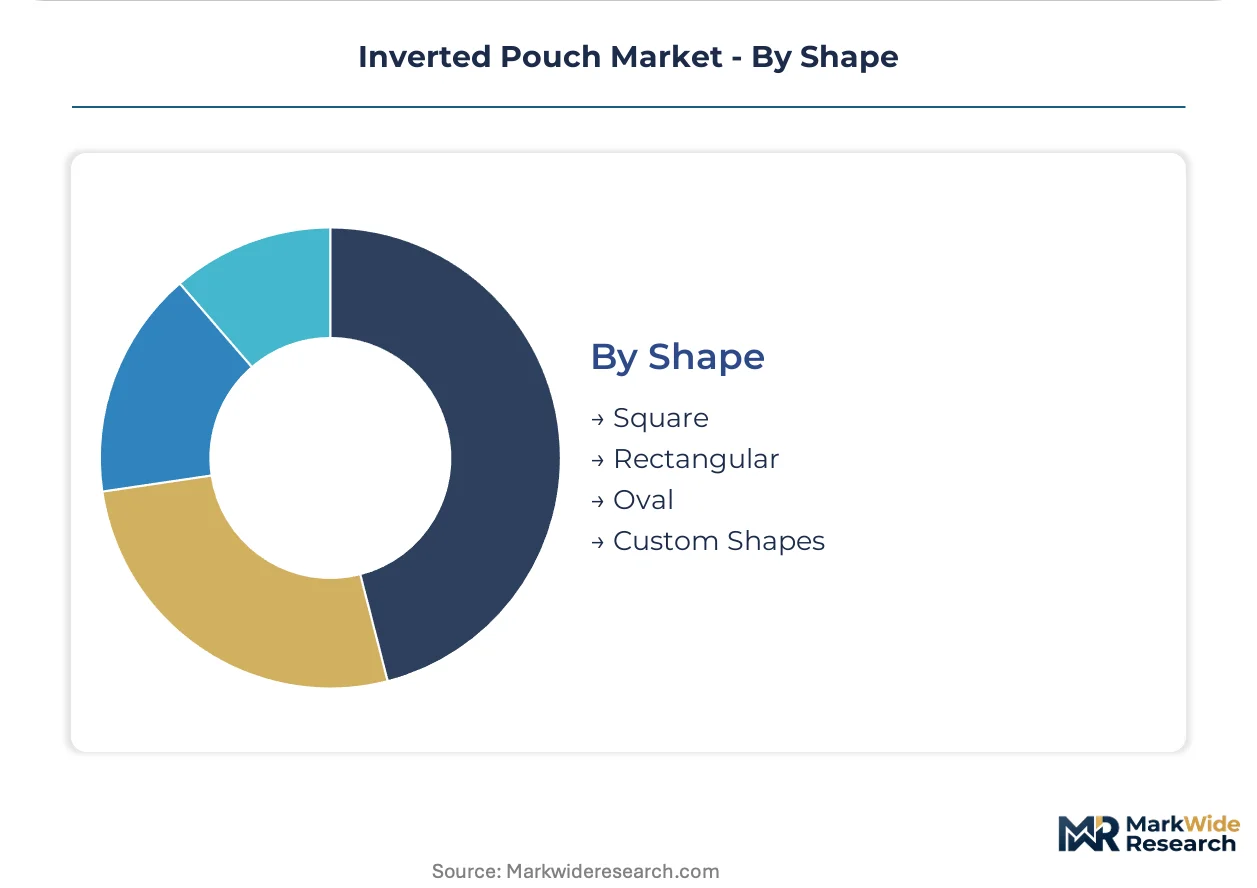
Shape:
Volume concentration in standardized rectangular formats enables high-speed form-fill-seal line efficiencies that custom geometries cannot match.
- Rectangular:Parallel-sided geometry maximizes pallet cube utilization and aligns with legacy form-fill-seal tooling across converter fleets. CPG brands with national distribution specify these for supply chain compatibility.
- Custom Shapes:Die-cut contours with branded silhouette profiles differentiate shelf presence in personal care segments. Tooling amortization across shorter production runs elevates unit economics for mid-tier brands.
- Square:Equal-edge dimensions optimize folding carton integration for retail multipacks.
- Oval:Rounded profiles reduce stress concentration points during squeeze dispensing of high-viscosity contents.
Rectangular dominates throughput. Custom Shapes gain share where brand differentiation commands price premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's converter base supplies precision-engineered laminates across the EU, while the United States concentrates demand from quick-service restaurant procurement departments. Regulatory divergence between EFSA migration limits and FDA 21 CFR compliance timelines forces multinational CPG brands to maintain dual certification portfolios.
United States
Quick-service restaurant chains headquartered in Illinois and Texas mandate portion-controlled condiment pouches for drive-thru distribution. FDA 21 CFR certification cycles for new laminate formulations extend 18-24 months, locking in incumbent converter relationships. Wisconsin-based manufacturing clusters dominate North American custom laminate production for inverted formats.
Germany
REACH substance authorization requirements tighten migration limits for adhesive components in food-contact laminates. EFSA authorization protocols govern laminate stack redesigns for CPG brands seeking pan-European distribution. Industrial concentration in North Rhine-Westphalia hosts coextrusion specialists serving pharmaceutical and retort food applications.
China
Domestic CPG brands accelerate adoption of gravity-assisted dispensing formats for sauce and condiment lines. SAMR food-contact material standards and GB compliance frameworks reshape substrate specifications for export-oriented converters. Yangtze River Delta manufacturing bases scale form-fill-seal capacity for regional quick-service restaurant supply chains.
India
FSSAI packaging regulations and state-level plastic waste management rules drive laminate reformulation for domestic food brands. BIS certification requirements for food-contact materials raise technical barriers for imported pouch structures. Maharashtra-based converters develop localized supply relationships with quick-service restaurant franchises expanding across metropolitan Mumbai and Pune corridors.
Brazil
ANVISA pharmaceutical packaging standards and CONAMA environmental regulations shape laminate specifications for personal care and household concentrate applications. São Paulo industrial clusters host adhesive lamination specialists serving Latin American CPG brand regional headquarters. Mid-tier converters face margin compression from buyer consolidation among multinational quick-service restaurant operators.
Inverted Pouch Market Vendor Landscape
Top-tier vendors anchor integrated film-to-pouch operations, while mid-tier specialists compete on custom laminate engineering and regional certification expertise. The vendor base stratifies across three tiers: multinational converters with captive resin supply, regional specialists with deep regulatory portfolios, and niche players focused on biodegradable material development. Dominant competitive moves include backward integration into coextrusion capacity and technology licensing partnerships for zip closure mechanisms.
Within the integrated multinational tier, Amcor Plc and Berry Global exemplify scale-driven positioning through broad laminate portfolios spanning multiple continents. Glenroy Inc. occupies a specialist position as a Wisconsin-based entity focused on North American custom laminate production. These three entities collectively represent the competitive archetypes of global supply anchoring, diversified scale operations, and regional technical specialization that define current market structure.
| Leading Market Players |
|---|
| Glenroy Inc. |
| Amcor Plc |
| Berry Global |
| ProAmpac |
| Polymer Packaging Inc. |
| Semco S.A.M |
| Mondi |
| Tetra Pak |
| Cheer Pack |
| Others |
Supply Flow & Price Mechanics
Coextrusion technology adoption across North American converter fleets is compressing cost structures for high-barrier laminates while simultaneously concentrating supply relationships around Wisconsin-based manufacturing clusters. This production-method transition simultaneously lowers unit economics for quick-service restaurant chains and locks out smaller converters lacking capital for multi-layer line upgrades.
Pricing Analysis
Capacity additions in the United States are reshaping price floors for standard polyethylene-polyester laminates as new coextrusion lines come online. Three-tier pricing structure across premium, standard, and economy levels separates FDA-certified barrier grades from uncertified commodity laminates and biodegradable alternatives. Pricing pressure stems from resin cost volatility in polyethylene and polyester feedstocks. Quick-service restaurant chains exhibit highest price sensitivity due to mandated portion-control economics, while pharmaceutical buyers accept premium positioning for validated seal integrity.
Supply Chain Analysis
Regional distribution centers in Wisconsin, Germany, and China's Yangtze River Delta anchor hub-and-spoke patterns for laminate supply to converter networks. Raw material flows draw from Saudi Arabian polyethylene producers, South Korean polyester resin specialists, and domestic adhesive compounders. Single-source vulnerability concentrates in FDA-certified tie layer formulations with 18-24 month qualification timelines. Distribution runs through converter-direct relationships with quick-service restaurant procurement departments and CPG brand supply chain managers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where quick-service restaurant chains are mandating premium coextruded barrier specifications that obsolete older adhesive lamination capacity.
For Market Incumbents: Acquire captive coextrusion lines in Wisconsin or equivalent regional manufacturing clusters to defend against margin compression from resin volatility. Secure dual FDA-EFSA certification portfolios ahead of EU Packaging and Packaging Waste Regulation enforcement milestones. Lock in multi-year specification agreements with consolidating quick-service restaurant procurement departments. For New Entrants and Emerging Players: State-level extended producer responsibility laws in the United States open a window for biodegradable laminate specialists to capture premium shelf positioning ahead of recycled content mandates. Target household cleaning concentrate applications where refill system adoption is displacing rigid bottle formats. Lead with subscription-based pouch design services to decouple hardware sales from recurring engineering revenue. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier converters with stranded adhesive lamination capacity and underdeveloped regulatory certification portfolios. Five-to-ten year viability hinges on backward integration into film extrusion and zip closure licensing partnerships. Watch for quick-service restaurant chain consolidation announcements as inflection indicators for specification-driven replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coextrusion Capacity | Cuts resin cost exposure and accelerates FDA certification timelines for laminate converters. |
| Dual Certification Portfolio Investment | Unlocks pan-European distribution for CPG brands facing REACH substance authorization requirements. |
| Zip Closure Technology Licensing | Captures recurring royalty streams from personal care brands seeking resealable aperture formats. |
| Subscription-Based Design Services Launch | Locks in multi-year relationships with mid-tier CPG brands pooling specification development. |
| Biodegradable Material R&D Partnership | Positions converters for state-level extended producer responsibility recycled content mandates. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to capture converter capacity utilization and buyer specification trends. Primary fieldwork included packaging engineers at quick-service restaurant chains, procurement managers at CPG brands, plant operators at Wisconsin-based manufacturing clusters, and regulatory affairs specialists navigating FDA 21 CFR and EFSA authorization protocols. Secondary validation drew from FDA food-contact substance filings, EU Packaging and Packaging Waste Regulation drafts, customs data on polyethylene and polyester resin imports, and SEC disclosures from integrated film-to-pouch operators. Bottom-up volume estimates triangulated against top-down spending analysis across food packaging, personal care, and household product applications.
Segment-weighting approaches distributed value across closure type, material certification tier, and application end-use throughout the forecast period. Modeled dimensions included heat-sealed versus zip closure formats, FDA-certified versus uncertified barrier grades, and quick-service restaurant versus CPG brand customer concentration. CAGRs derived from elasticity-adjusted demand curves incorporating resin price sensitivity and specification replacement cycles. Industry-specific inputs captured coextrusion line capacity additions and migration testing timeline bottlenecks.
Revisions become necessary when FDA or EFSA accelerate substance authorization timelines, when state-level extended producer responsibility mandates harden recycled content thresholds faster than modeled, or when quick-service restaurant chain consolidation abruptly shifts procurement concentration. Forecasts reflect documented assumptions around resin cost trajectories and certification cycle durations. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Peelable Pouches Market
Pouch
Open Mouth Sacks Market
Pouch
Child Resistant Single Dose Pouches Market
Pouch
Aluminum Foil Zipper Pouch Market
Pouch
Feminine Care Pouch Film Market
Pouch
Asia-Pacific Pouch Packaging Market
Pouch
Cold Seal Lamination Pouch Market
Pouch
Pre-Made Pouch Packaging Market
Pouch
Brazil Pouch Packaging Market
Pouch
Latin America Pouch Packaging Market
Pouch
Child Resistant Locking Pouches Market
Pouch
Sterilization Pouches Market
Pouch
Saudi Arabia Pouch Packaging Market
Pouch
Liquid Pouch Packing Machine Market
Pouch
Spouted Pouches Market
Pouch
Europe Pouch Packaging Market