
 Asia-Pacific Polylactic Acid (PLA) Market | 2026-2036
Asia-Pacific Polylactic Acid (PLA) Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Polylactic Acid (PLA) Market Outlook
Food-grade crystalline PLA specification upgrades is rotating procurement standards across the Asia-Pacific region. NatureWorks LLC leverages its fermentation technology leadership to sustain supply security for high-purity lactide streams. Zhejiang Hisun Biomaterials Co., Ltd. anchors regional production capacity with integrated corn-to-PLA operations in Taizhou. Toray Industries, Inc. differentiates through specialty film grades that compete in premium flexible packaging segments.
Polylactic acid is a thermoplastic aliphatic polyester synthesized from lactic acid monomers derived from fermented plant starch, typically exhibiting a glass transition temperature near 55-60°C and melting point around 150-160°C depending on crystallinity. Its primary industrial purpose centers on replacing petroleum-derived plastics in disposable and short-lifecycle applications where biodegradability delivers compliance value. Injection molding formulations currently dominate volume throughput across the Asia-Pacific conversion base, while 3D printing filament grades capture expanding margin pools in precision manufacturing and medical prototyping. Films and coatings applications are maturing fastest in fresh produce packaging where oxygen barrier requirements are less stringent.
China's SAMR enforces GB standards for biodegradable plastics labeling, while Japan's METI coordinates bioplastics deployment targets through its Resource Circulation Strategy for Plastics. India's BIS is developing certification protocols for compostable packaging materials under its Plastic Waste Management Rules amendments. Stakeholders must monitor how ASEAN harmonization of biodegradability testing standards reshapes cross-border product qualification requirements.
Market Dynamics
China's dual carbon goals are compressing compliance timelines for single-use polymer alternatives, forcing rapid material substitution across food packaging supply chains while fermentation capacity struggles to match procurement velocity.
Growth Catalysts
- Japan's METI bioplastics roadmap:Deployment targets under the Resource Circulation Strategy for Plastics are mandating PLA adoption in premium flexible packaging segments, accelerating demand from Toray Industries and comparable compounders.
- Quick-service restaurant chains:Food packaging specifications are rotating toward crystalline PLA grades as cold-chain beverage cup and cutlery substitution volumes multiply across the Asia-Pacific conversion base.
- Eastern China manufacturing belt:Zhejiang and Jiangsu provinces concentrate the densest cluster of PLA compounding facilities, creating network effects that reduce logistics costs for downstream converters.
Market Restraints
- Corn starch input volatility:Feedstock price swings for fermented plant starch expose integrated producers to margin compression when agricultural commodity markets tighten.
- High-purity lactide supply concentration:Fermentation technology leadership remains concentrated among a limited set of technology holders, creating bottlenecks for regional capacity expansion.
- GB standards compliance friction:China's SAMR labeling requirements for biodegradable plastics impose testing costs that disadvantage smaller compounders lacking in-house certification capabilities.
Strategic Opportunities
- India's BIS compostable certification:Developing protocols under Plastic Waste Management Rules amendments will open procurement channels for PLA film grades in fresh produce packaging as compliance infrastructure matures.
- 3D printing filament convergence:Precision manufacturing and medical prototyping applications are capturing expanding margin pools as material purity specifications diverge from commodity injection molding grades.
- ASEAN harmonization of biodegradability testing:Cross-border standard alignment will reduce product qualification duplication costs for converters serving multiple Southeast Asian markets.
Industry Challenges
- Fermentation process engineering talent scarcity:High-purity lactide production requires specialized biochemical engineering expertise that regional universities are not yet producing at sufficient scale.
- Composting infrastructure certification timelines:Industrial composting facility validation for PLA end-of-life claims delays market entry for packaging converters targeting premium sustainability positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Polylactic Acid (PLA) Market |
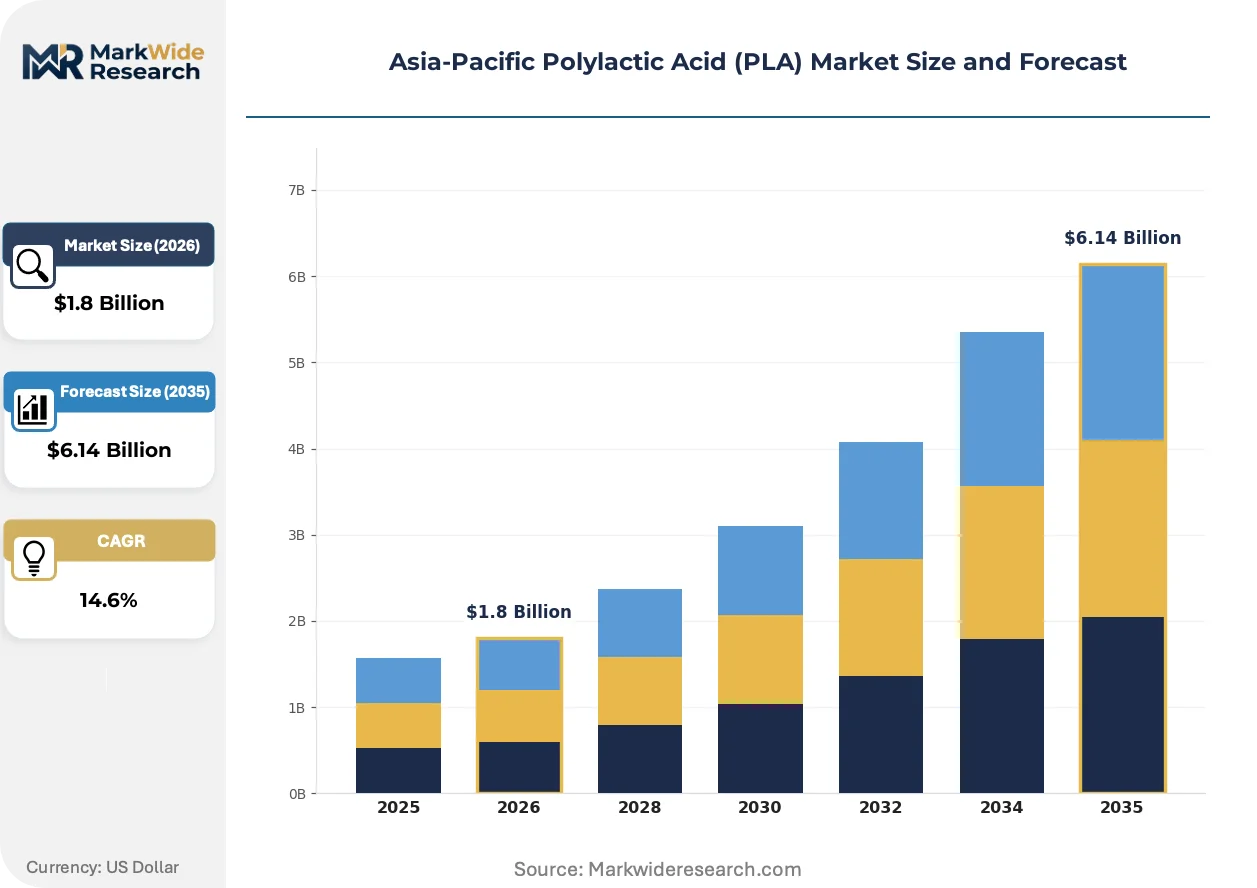
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection Molding, 3D Printing, Films, Coatings End Use Industry: Packing, Textiles, Agriculture, Automotive Form: Granules, Powder, Film, Sheet Technology: Fermentation, Polymerization, Biodegradation, Extrusion |
| Companies Covered | Mitsubishi Chemical Holdings Corporation, Futerro SA, NatureWorks LLC, Evonik Industries AG, COFCO Corporation, BASF SE, Toray Industries, Inc., Zhejiang Hisun Biomaterials Co., Ltd., TotalEnergies Corbion, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Polylactic Acid (PLA) Market Strategic Shifts
Material science advances and regulatory compression are converging to redefine performance specifications across biodegradable polymer applications, with crystallinity control and barrier engineering emerging as decisive technical battlegrounds.
High-crystallinity PLA grades are decomposing the traditional performance gap between biodegradable and fossil-based plastics in hot-fill packaging applications. Beverage bottlers in South Korea and Thailand are qualifying these materials for 85°C fill temperatures, enabling structural substitution in juice and ready-to-drink tea segments that previously excluded PLA on thermal stability grounds.
METI's coordinated bioplastics deployment targets are forcing Japanese packaging converters to accelerate qualification timelines for film-grade PLA. The Resource Circulation Strategy for Plastics mandates 25% bioplastic content in specified single-use categories by 2030, compelling brand owners to renegotiate multi-year supply agreements with compounders ahead of compliance deadlines.
Supermarket chains are consolidating procurement specifications around food-grade crystalline PLA standards that exceed legacy injection molding grades. Australia's major grocery retailers and Japan's convenience store operators are jointly specifying oxygen transmission rates and heat-seal initiation temperatures, compressing supplier diversity as compliance costs rise for non-specialized compounders.
Asia-Pacific Polylactic Acid (PLA) Market Segmentation
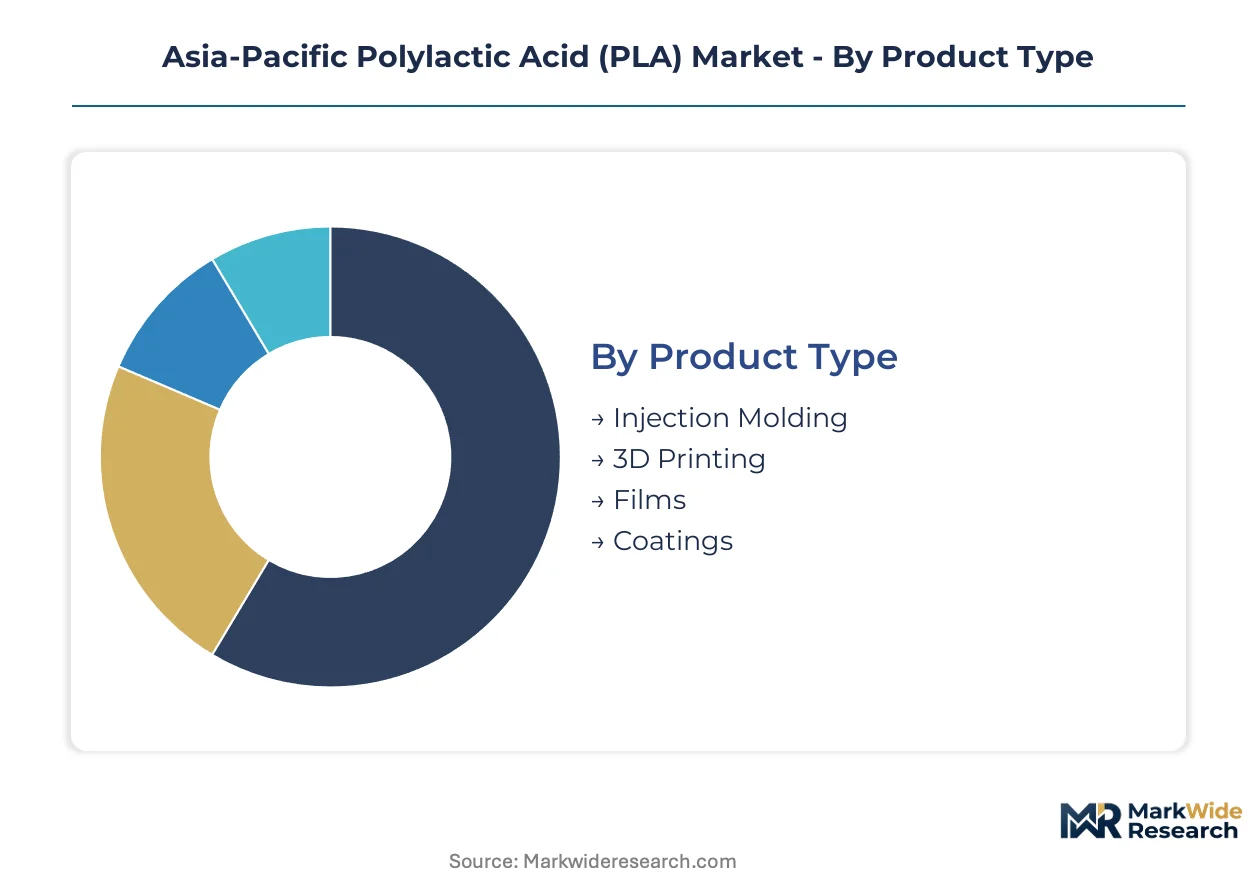
PLA segmentation in the Asia-Pacific region tracks how material specifications diverge across conversion technologies and end-use compliance requirements. Procurement patterns cluster around thermal performance thresholds and biodegradability certification standards that vary by application.
Product Type:
Margin pools concentrate in specialty grades where crystallinity control commands premium positioning over commodity injection formulations.
- Injection Molding:Commodity-grade formulations dominate volume throughput across Zhejiang and Jiangsu compounding facilities. Quick-service restaurant chains in China and Japan are specifying crystalline grades for cold-chain beverage cups as GB standards and METI roadmaps tighten compliance timelines.
- 3D Printing:Precision filament grades require higher lactide purity specifications that strain regional fermentation capacity. Medical prototyping labs in South Korea and precision manufacturing facilities in Japan are capturing expanding margin pools as material purity requirements diverge from commodity grades.
- Films:Fresh produce packaging in Australian supermarket chains and Japanese convenience stores is consolidating procurement around oxygen transmission specifications.
- Coatings:Barrier engineering applications for paperboard substitution are maturing fastest where composting infrastructure validation supports end-of-life claims.
Injection molding holds installed capacity. 3D printing is rotating up the share rankings.
End Use Industry:
Application concentration follows regulatory enforcement intensity across national packaging directives and agricultural subsidy programs.
- Packing:Food-grade specifications are rotating procurement standards across quick-service restaurant chains and supermarket operators. Australia's major grocery retailers and Japan's convenience store operators are jointly specifying heat-seal initiation temperatures that compress supplier diversity.
- Textiles:Fiber-grade PLA competes in disposable nonwoven applications where biodegradability delivers compliance value against synthetic alternatives. South Korean textile converters are qualifying high-tenacity grades for agricultural mulch films under MFDS-adjacent sustainability procurement guidelines.
- Agriculture:Mulch film demand concentrates in eastern China's greenhouse cultivation belt where provincial environmental bureaus enforce plastic pollution reduction targets.
- Automotive:Interior trim applications remain nascent as thermal stability requirements exceed unmodified PLA performance envelopes.
Packing commands current revenue concentration. Textiles are climbing the fastest as fiber-grade capacity expands.
Form:
Physical configuration determines logistics economics and converter equipment compatibility across the regional compounding network.
- Granules:Standard pellet form dominates injection molding feedstock supply chains with established handling infrastructure across Taizhou and Zhangjiagang processing hubs.
- Powder:Finely milled grades serve rotational molding and coating applications where melt uniformity requirements exceed pellet dissolution kinetics.
- Film:Pre-cast sheet stock accelerates thermoforming throughput for fresh produce trays in Australian and Japanese retail supply chains.
- Sheet:Calendered formats support deep-draw packaging applications where thickness tolerance specifications are tightening under supermarket chain procurement consolidation.
Granules hold installed capacity. Film is rotating up the share rankings.
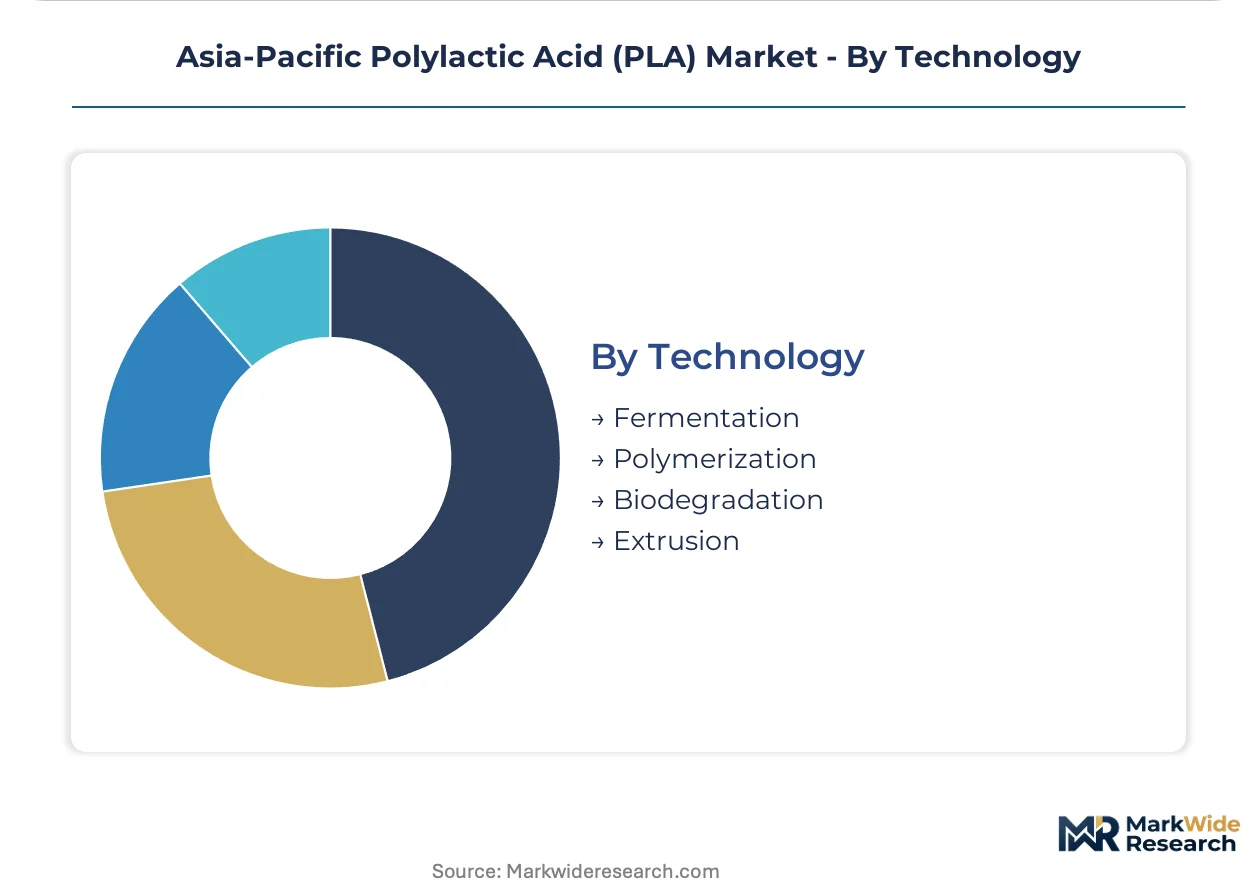
Technology:
Process control capabilities separate integrated producers from compounders dependent on merchant lactide supply.
- Fermentation:High-purity lactide production requires specialized biochemical engineering expertise that regional universities are not yet producing at sufficient scale. NatureWorks LLC and Zhejiang Hisun Biomaterials Co., Ltd. anchor technology leadership through integrated corn-to-PLA operations.
- Polymerization:Ring-opening lactide polymerization capacity concentrates among technology holders with captive fermentation supply or long-term offtake agreements.
- Biodegradation:Composting infrastructure certification timelines delay market entry for packaging converters targeting premium sustainability positioning in Japan and Australia.
- Extrusion:Compounding and conversion equipment installation is concentrating in eastern China's manufacturing belt where network effects reduce logistics costs for downstream processors.
Fermentation holds installed capacity. Polymerization is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated fermentation capacity concentrates in eastern China's manufacturing belt, where corn-to-PLA operations anchor regional supply security. Zhejiang and Jiangsu provinces host the densest clustering of compounding and conversion facilities, creating network effects that reduce logistics costs for downstream processors across the Asia-Pacific conversion base.
China
Quick-service restaurant chains and supermarket operators are rotating procurement toward crystalline PLA grades for cold-chain beverage cups and cutlery substitution. SAMR enforces GB standards for biodegradable plastics labeling that impose testing costs on smaller compounders. Taizhou in Zhejiang province anchors integrated corn-to-PLA operations where Zhejiang Hisun Biomaterials Co., Ltd. sustains captive lactide supply.
Japan
Toray Industries and comparable compounders face accelerated demand from premium flexible packaging segments as brand owners renegotiate supply agreements. METI coordinates bioplastics deployment targets under the Resource Circulation Strategy for Plastics mandating 25% bioplastic content in specified single-use categories by 2030. Convenience store operators in the Kanto region are jointly specifying oxygen transmission rates and heat-seal initiation temperatures with Australian grocery retailers.
India
BIS is developing compostable certification protocols under Plastic Waste Management Rules amendments that will open procurement channels for PLA film grades. Fresh produce packaging applications are maturing fastest where compliance infrastructure supports end-of-life claims. Agricultural mulch film demand concentrates in greenhouse cultivation belts where state environmental bureaus enforce plastic pollution reduction targets.
South Korea
Beverage bottlers are qualifying high-crystallinity PLA grades for 85°C fill temperatures, enabling structural substitution in juice and ready-to-drink tea segments. MFDS-adjacent sustainability procurement guidelines are driving textile converters to qualify high-tenacity grades for agricultural applications. Medical prototyping labs in Seoul are capturing expanding margin pools in precision manufacturing filament grades.
Australia
Major grocery retailers are consolidating procurement specifications around food-grade crystalline PLA standards that exceed legacy injection molding grades. Industrial composting facility validation timelines delay market entry for packaging converters targeting premium sustainability positioning. Fresh produce tray thermoforming operations are accelerating throughput as pre-cast sheet stock supply matures.
Asia-Pacific Polylactic Acid (PLA) Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where integrated fermentation specialists compete with merchant lactide-dependent compounders. The vendor base separates into three strategic archetypes: integrated corn-to-PLA operators with captive lactide supply, specialty film-grade compounders serving premium flexible packaging, and regional conversion specialists focused on injection molding formulations. Dominant competitive moves include capacity expansion in eastern China's manufacturing belt and strategic partnerships securing long-term lactide offtake agreements.
Within the integrated operator tier, NatureWorks LLC and Zhejiang Hisun Biomaterials Co., Ltd. exemplify archetypes combining fermentation technology with regional supply chain positioning. Toray Industries, Inc. occupies a position among specialty compounders differentiating through film-grade specifications. Mitsubishi Chemical Holdings Corporation represents diversified chemical conglomerates with bioplastics portfolio exposure. These players anchor competitive dynamics without exclusive market control, as merchant lactide availability and compounding capacity constraints create entry points for specialized converters.
| Leading Market Players |
|---|
| Mitsubishi Chemical Holdings Corporation |
| Futerro SA |
| NatureWorks LLC |
| Evonik Industries AG |
| COFCO Corporation |
| BASF SE |
| Toray Industries, Inc. |
| Zhejiang Hisun Biomaterials Co., Ltd. |
| TotalEnergies Corbion |
| Others |
Value Chain & Pricing Dynamics
Long-term lactide offtake contracts lock in supply access and price visibility for compounders serving Japan's METI-mandated bioplastics procurement timelines, while China's SAMR labeling requirements compress margins for non-integrated processors lacking captive fermentation capacity.
Pricing Analysis
China's SAMR GB standards dictate the pricing tier structure across the Asia-Pacific conversion base, separating certified biodegradable grades from uncertified commodity formulations. Pricing stratifies across food-grade crystalline, medical-grade high-purity, and standard injection molding tiers, with corn starch input volatility driving cost compression in commodity segments. Quick-service restaurant chains exhibit highest price sensitivity due to volume procurement mandates, while medical prototyping labs in Seoul and Tokyo tolerate premium positioning for filament-grade purity specifications.
Supply Chain Analysis
High-purity lactide inventory cycles extend 8-12 weeks for merchant-dependent compounders versus 3-4 weeks for integrated operators, creating working capital disparities that reshape competitive positioning. Feedstock supply concentrates in China, Thailand, and the United States corn belts, with fermentation capacity anchored in Zhejiang and Jiangsu provinces. Regional supply chains draw from fermented plant starch, specialized biochemical engineering talent pools, and industrial composting validation infrastructure. Single-source vulnerability runs through NatureWorks LLC's technology licensing network. Distribution feeds from Taizhou compounding hubs through Zhangjiagang conversion facilities to downstream packaging processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific PLA demand disruption is accelerating as China's dual carbon goals and Japan's METI bioplastics roadmap compress substitution timelines for fossil-based packaging, creating a high-growth inflection where fermentation capacity constraints separate winners from capacity-constrained followers.
For Market Incumbents: Secure captive lactide supply through backward integration into corn-to-PLA operations or exclusive offtake agreements with Zhejiang Hisun Biomaterials Co., Ltd. and comparable integrated operators, defending against merchant supply bottlenecks that threaten production continuity for METI-compliant film grades. Reinforce certification capabilities to absorb SAMR testing cost burdens that disadvantage smaller compounders lacking in-house GB standards compliance infrastructure. For New Entrants and Emerging Players: Anchor in India's BIS compostable certification development under Plastic Waste Management Rules amendments, where compliance infrastructure gaps create procurement channel openings for film-grade PLA in fresh produce packaging ahead of incumbent qualification. Target agricultural mulch film segments in eastern China's greenhouse cultivation belt, where provincial environmental bureau enforcement of plastic pollution reduction targets outpaces domestic supply response. For Investors and Strategic Acquirers: Specialty film-grade compounders with Toray Industries-type premium positioning command scarcity premiums as brand owners renegotiate supply agreements ahead of Japan's 2030 bioplastic content mandates. Long-term viability hinges on fermentation technology access rather than compounding scale alone. Monitor ASEAN harmonization of biodegradability testing standards as the signal for cross-border product qualification cost reduction and regional consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation | Captive lactide supply insulates Zhejiang Hisun Biomaterials Co., Ltd. from merchant bottlenecks. |
| GB Standards Certification Investment | SAMR compliance infrastructure separates viable compounders from margin-compressed non-specialists. |
| High-Crystallinity Grade Development | South Korean beverage bottlers qualify 85°C fill materials for juice and ready-to-drink tea substitution. |
| Long-term Lactide Offtake Agreement | Secures supply priority for Toray Industries as METI deployment targets accelerate procurement velocity. |
| Industrial Composting Partnership | Validates end-of-life claims for Australian supermarket chains consolidating procurement specifications. |
Study Parameters
Initial hypotheses were tested against primary input from fermentation technology directors, packaging procurement managers at quick-service restaurant chains, bioplastics regulatory affairs leads, and industrial composting facility operators, and refined through secondary validation against SAMR GB standards documentation, METI Resource Circulation Strategy implementation reports, customs trade data for lactic acid derivatives, and SEC filings of diversified chemical conglomerates with PLA portfolio exposure. Bottom-up capacity installation tracking across Zhejiang and Jiangsu provinces was triangulated against top-down demand modeling from food packaging substitution mandates.
Variance decomposition across the projection horizon isolates volume drivers by injection molding versus film-grade specifications, end-use concentration in food packaging versus agricultural mulch films, and technology segmentation between integrated fermentation operators and merchant lactide-dependent compounders. CAGRs were derived from segment-level growth rate reconciliation against regional regulatory enforcement intensity. Forecast inputs include corn starch price volatility indices, industrial composting facility certification timelines, and ASEAN standard harmonization progress indicators.
Decision-makers should treat outputs as directional under sustained dual carbon policy enforcement and METI roadmap implementation; material deviation in fermentation capacity expansion or composting infrastructure deployment would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioplastics
Global Synthetic and Bio Based Polypropylene Market
Bioplastics
Global Bio-Based PET Market
Bioplastics
Biodegradable Microbeads Market
Bioplastics
Southeast Asia Bio-PET Market
Bioplastics
Global Green and Bio-Based Plastic Additives Market
Bioplastics
Bio-Based Succinic Acid Derivatives for Plasticizers Market
Bioplastics
Global Bio-Plasticizers Market
Bioplastics
Cellulose Bioplastic Market
Bioplastics
Starch-Based Bioplastics Market
Bioplastics
Middle East and Africa Polylactic Acid (PLA) Market
Bioplastics
Cellulose Plastics Market
Bioplastics
Biodegradable Disposable Tableware Market
Bioplastics
Bio-Polyamide, Specialty Polyamide and Precursors Market
Bioplastics
Global Bio-Polylactic Acid (PLA) Market
Bioplastics
Biodegradable Superabsorbent Materials Market
Bioplastics
Biodegradable Plastics Market